
 Oil Mist Collector Market | 2026-2036
Oil Mist Collector Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Mist Collector Market Analytics
The EU Green Deal industrial emissions framework is repositioning oil mist filtration from optional equipment to mandatory capital expenditure across European metalworking plants. Donaldson Company leverages its vertically integrated filter media production to sustain pricing power in high-efficiency collector systems. Nederman Holding AB anchors its competitive stance through channel control in automated welding and machining environments. Absolent Group AB specializes in compact, energy-recovery collector designs that differentiate its portfolio in space-constrained factory floors.
An oil mist collector is a mechanical air filtration device that captures sub-micron oil droplets and coolant aerosols generated during metal cutting, grinding, and forming operations, typically achieving separation efficiencies above 99% for particles larger than 0.3 microns. The device protects worker respiratory health, preserves machine tool accuracy, and recovers valuable cutting fluids for reuse in continuous manufacturing cycles. Electrostatic precipitation technology leads the market in total installed value due to its low pressure-drop operation and minimal filter replacement requirements, though filtration-based systems retain dominant unit volume in cost-sensitive metalworking shops. High-efficiency collectors represent the fastest-expanding product tier as aerospace and medical device manufacturers tighten particulate tolerance thresholds. Centralized systems command the largest margin pools by integrating ductwork engineering, remote monitoring, and predictive maintenance contracts into multi-year service agreements.
EPA National Emission Standards for Hazardous Air Pollutants shape demand in United States metal fabrication by mandating capture efficiency benchmarks for metalworking fluids containing chlorinated paraffins and other designated toxic compounds. OSHA Permissible Exposure Limits for mineral oil mist further tighten workplace air quality obligations, pushing smaller job shops toward compliant collector retrofits. In Europe, REACH restrictions on hazardous substance releases and CE marking requirements for industrial ventilation equipment create parallel compliance-driven replacement cycles. Stakeholders must monitor how evolving PFAS regulations in both jurisdictions reshape coolant formulations and, consequently, collector material compatibility specifications.
Market Dynamics
EU Green Deal industrial emissions guidelines are compressing upgrade cycles across European metalworking facilities, converting oil mist filtration from discretionary maintenance spend into mandatory capital allocation tied to permit renewals and factory certification timelines.
Growth Catalysts
- REACH hazardous substance restrictions:European coolant formulation rules are forcing metalworking plants to install high-efficiency capture systems that handle reformulated metalworking fluids without cross-contamination risks.
- Automotive precision machining clusters:Tier-1 suppliers in China, Germany, and the United States are expanding synchronized production lines that require centralized oil mist collection with remote monitoring capabilities.
- Electrostatic precipitation:This low pressure-drop technology is penetrating aerospace component manufacturing where minimal filter replacement downtime protects just-in-time delivery schedules.
Market Restraints
- Specialized filter media supply:Glass fiber and nanofiber substrate production concentrates among a limited set of European and Japanese material suppliers, creating input bottlenecks during demand surges.
- PFAS regulatory uncertainty:Evolving restrictions on per- and polyfluoroalkyl substances in both EPA and ECHA jurisdictions are delaying coolant specification finalization and collector material compatibility testing.
- Wet scrubber substitution:Water-based mist suppression systems retain cost advantages in heavy roughing operations where ultra-fine particle capture is not required.
Strategic Opportunities
- Medical device manufacturing:ISO 13485-certified cleanroom machining environments in Switzerland and Ireland represent underpenetrated demand for compact, energy-recovery collector designs with validated particulate retention documentation.
- OSHA Permissible Exposure Limit enforcement:Enhanced workplace inspection protocols in the United States are accelerating retrofit demand among small and mid-sized job shops previously operating below compliance radar.
- IoT-enabled predictive maintenance:Convergence of pressure-drop sensors with cloud analytics platforms allows collector OEMs to unbundle monitoring services from equipment sales, capturing recurring revenue streams.
Industry Challenges
- Industrial ventilation technician shortage:Qualified ductwork design and balancing specialists are scarce in German and Polish manufacturing regions, extending installation timelines for centralized collector systems.
- Legacy machine tool integration:Retrofitting enclosed machining centers with extraction interfaces requires custom adapter fabrication that delays project commissioning and strains project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Mist Collector Market |
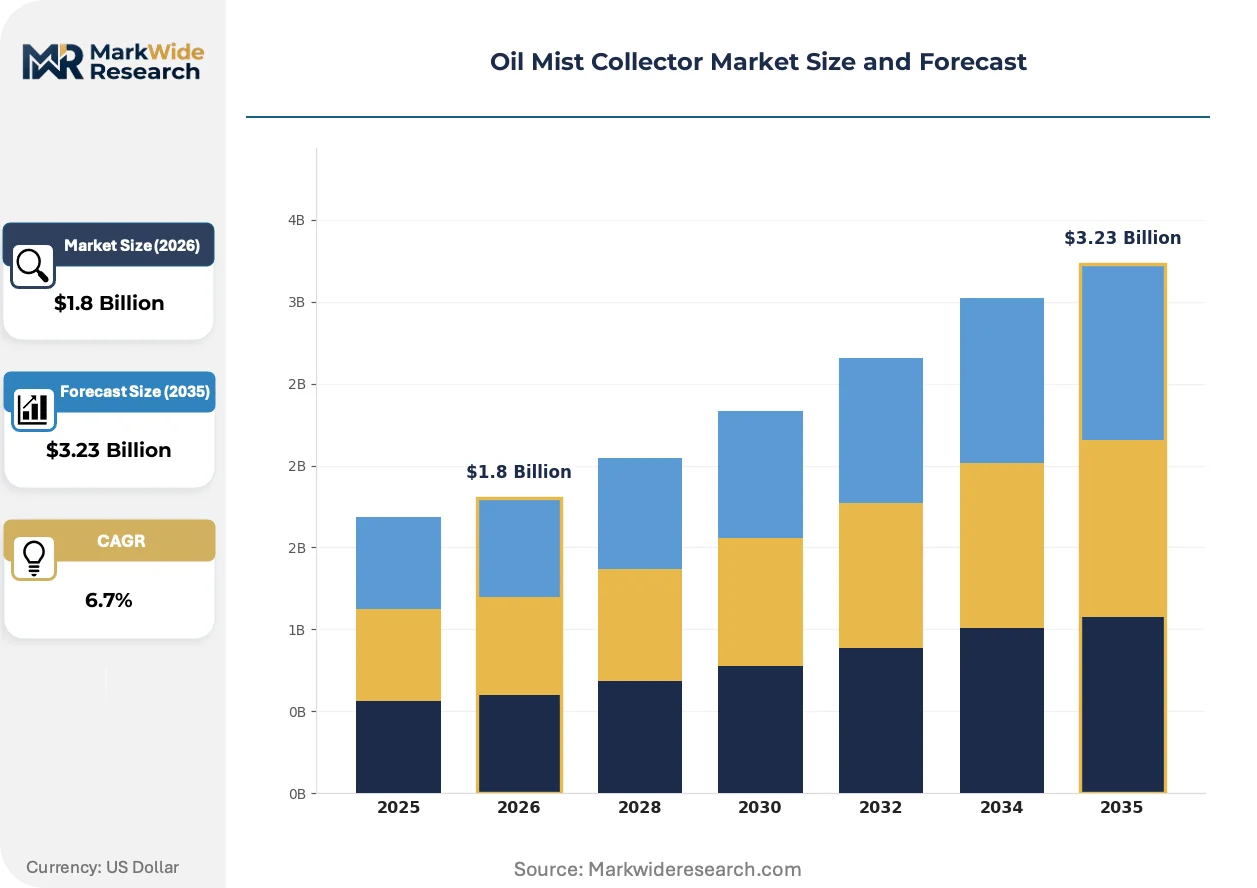
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Oil Mist Collectors, High-Efficiency Collectors, Portable Collectors, Centralized Systems Technology: Cyclonic Separation, Electrostatic Precipitation, Filtration, Absorption End User: Manufacturing, Automotive, Aerospace, Metalworking Installation: On-site Installation, Factory Setup, Mobile Installation, Integrated Systems |
| Companies Covered | Donaldson Company, Nederman Holding AB, Absolent Group AB, Camfil AB, RoboVent, Filtermist Holdings Limited, AIRMAX International, Rentschler REVEN, Losma S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Mist Collector Market Evolving Landscape
Active filtration architectures are absorbing functionality previously handled by separate downstream components, compressing system footprints while elevating separation efficiency thresholds demanded by precision manufacturing verticals.
Coalescing filter media with embedded drainage layers is absorbing sub-micron oil droplets at higher face velocities than conventional depth-loading designs. Medical device manufacturers in Switzerland and Ireland are specifying these configurations to protect Class 7 cleanroom environments. The technology is absorbing market share from electrostatic precipitators in applications where coolant recovery purity outweighs energy consumption minimization.
EPA National Emission Standards for Hazardous Air Pollutants are tightening capture efficiency benchmarks for metalworking fluids containing chlorinated paraffins. Metal fabrication facilities in Ohio and Michigan are responding with multi-stage collector upgrades that combine mechanical filtration with activated carbon polishing. The regulatory pressure is compressing replacement cycles for systems installed before the 2013 NESHAP amendments.
Compressed procurement timelines are displacing traditional capital budgeting cycles for oil mist collection equipment. Tier-1 automotive suppliers in Bavaria and Baden-Württemberg are consolidating vendor relationships under framework agreements that bundle collector procurement with predictive maintenance subscriptions. This concentration is most visible among powertrain machining operations where unplanned downtime costs exceed equipment capital outlays by an order of magnitude.
Oil Mist Collector Market Segmentation
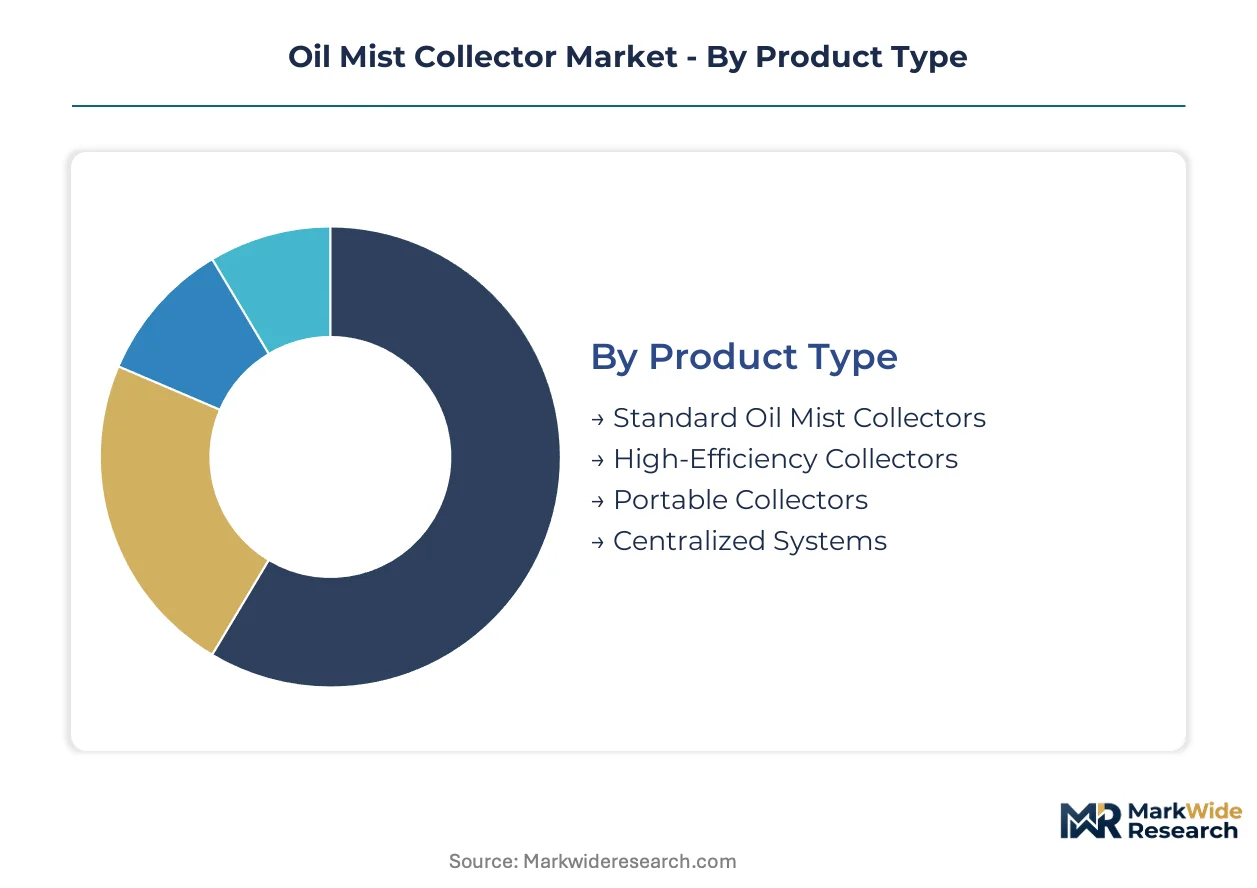
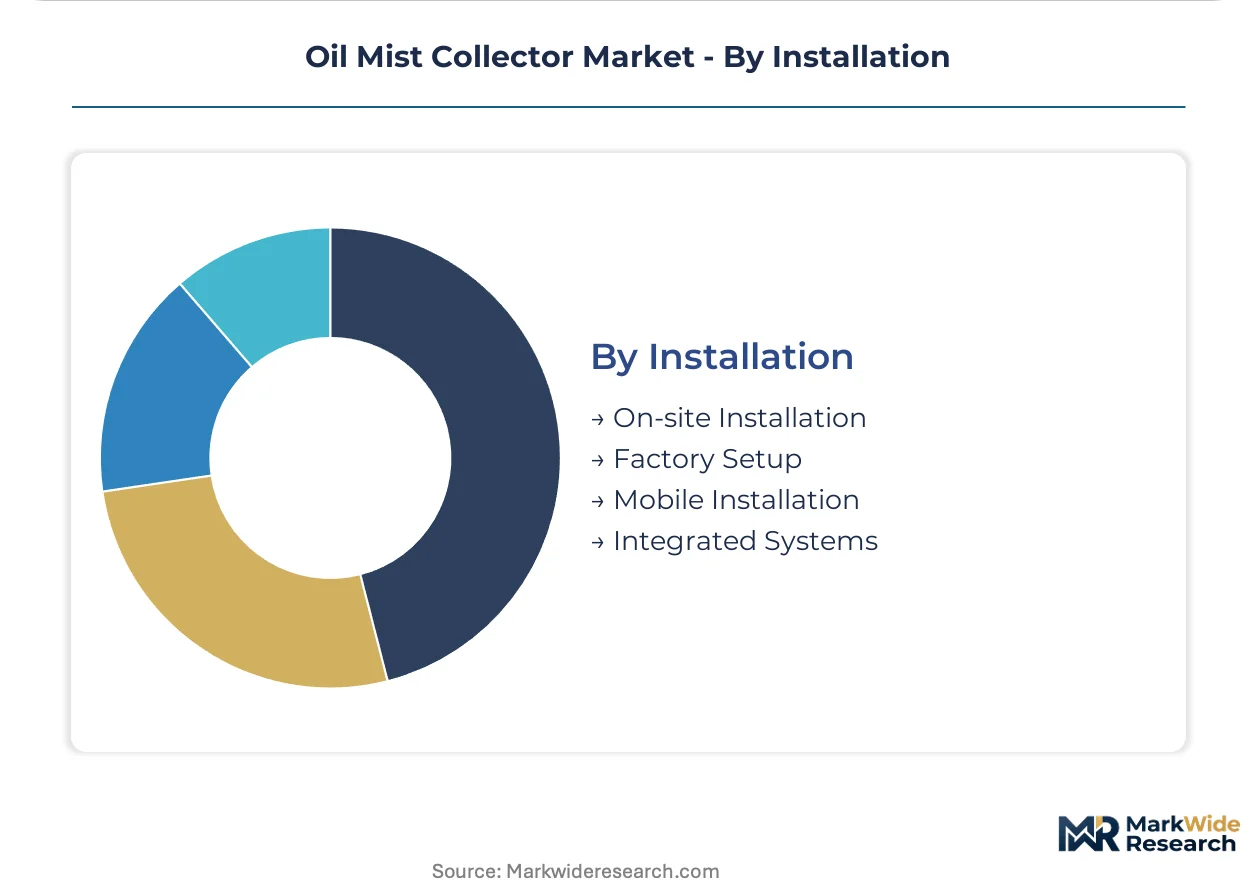
Segmentation in oil mist collection equipment reflects divergent capital allocation strategies across metalworking facilities. Product architecture, capture technology, and installation complexity each create distinct margin pools and competitive dynamics.
Product Type:
Equipment scale and efficiency specification define capital deployment patterns across metalworking verticals.
- Standard Oil Mist Collectors:Mechanical filtration units with fixed-media cartridges serve cost-sensitive job shops in Poland and Czech Republic metalworking clusters. Tier-2 automotive suppliers in Ohio and Michigan favor these systems for rough machining where coolant recovery purity is secondary to capital outlay control.
- High-Efficiency Collectors:Multi-stage configurations combining coalescing media with HEPA-grade final filters achieve sub-micron capture for aerospace component manufacturing in Toulouse and Hamburg. Medical device machining in Swiss cleanrooms demands validated documentation of particulate retention performance that only these systems provide.
- Portable Collectors:Self-contained units with castor mounting serve mobile maintenance operations and short-run fabrication.
- Centralized Systems:Ducted networks with remote monitoring capabilities dominate large-scale powertrain machining in Bavaria.
Centralized systems lead on scale; high-efficiency collectors lead on momentum.
Technology:
Capture mechanism selection trades operating cost against separation precision and maintenance burden.
- Electrostatic Precipitation:Ionization-based separation operates at minimal pressure drop with negligible filter replacement, penetrating aerospace manufacturing in Seattle and Toulouse where downtime avoidance justifies premium capital outlay. The technology demands precise voltage calibration and specialized cleaning protocols that constrain adoption among smaller metalworking shops.
- Filtration:Depth-loading and surface-loading media configurations retain dominant unit volume across cost-sensitive applications in Chinese automotive supplier parks. Coalescing filter advances with embedded drainage layers are displacing electrostatic units in medical device machining where coolant recovery purity outweighs energy minimization.
- Cyclonic Separation:Centrifugal force separation handles heavy mist loads in rough grinding operations.
- Absorption:Chemical scrubbing captures soluble oil fractions in specialized metal forming applications.
Filtration dominates volume deployment; electrostatic precipitation commands value concentration.
End User:
Industry-specific contamination tolerance and regulatory exposure shape equipment specification requirements.
- Metalworking:Grinding, cutting, and forming operations generate the baseline demand volume across German, Chinese, and United States fabrication clusters. EPA NESHAP compliance deadlines in Ohio and Michigan are accelerating retrofit cycles for facilities handling chlorinated paraffin coolants.
- Automotive:Powertrain and transmission machining in Stuttgart, Shanghai, and Detroit requires synchronized collector procurement under framework agreements bundling equipment with predictive maintenance subscriptions.
- Aerospace:Titanium and nickel alloy machining in Seattle and Toulouse demands validated capture efficiency for sub-micron metallic particles.
- Manufacturing:General industrial applications span food processing equipment and appliance fabrication with moderate specification requirements.
Metalworking anchors installed base; automotive drives contract value expansion.
Installation:
Deployment architecture determines project margin structure and customer relationship duration.
- Factory Setup:Greenfield integration with machine tool OEMs in Chinese automotive supplier parks captures multi-year service attachment. Ductwork engineering and balancing expertise scarcity in German manufacturing regions extends commissioning timelines and elevates project margins for qualified installers.
- Integrated Systems:Enclosed machining center retrofits require custom adapter fabrication that strains project economics but locks in proprietary interface relationships. Bavarian Tier-1 suppliers favor this architecture for just-in-time powertrain operations where unplanned downtime costs dominate capital considerations.
- On-site Installation:Standalone unit placement serves existing facility retrofits with minimal structural modification.
- Mobile Installation:Temporary deployment supports contract manufacturing and seasonal production peaks.
Factory setup commands margin concentration; integrated systems gain share in precision verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial oil mist filtration for precision metalworking during the post-war machine tool boom. Japanese manufacturers refined electrostatic precipitation for automotive mass production in the 1970s. Chinese supplier parks now drive volume expansion as domestic automotive precision machining clusters mature.
United States
EPA National Emission Standards for Hazardous Air Pollutants mandate capture efficiency benchmarks for metalworking fluids containing chlorinated paraffins. OSHA Permissible Exposure Limits for mineral oil mist tighten workplace air quality obligations across Ohio and Michigan fabrication clusters. Tier-1 automotive suppliers in Detroit are retrofitting centralized collection systems under compressed procurement timelines.
Germany
EU Green Deal industrial emissions guidelines compress upgrade cycles across Bavarian and Baden-Württemberg metalworking facilities. REACH hazardous substance restrictions force plants to install high-efficiency capture systems for reformulated coolants. Stuttgart powertrain machining operations bundle collector procurement with predictive maintenance subscriptions under framework agreements.
China
Domestic automotive precision machining clusters in Shanghai and Yangtze River Delta regions expand synchronized production lines requiring centralized oil mist collection. MIIT industrial emissions guidelines tighten particulate discharge standards for metalworking facilities. Tier-1 suppliers in automotive supplier parks specify remote monitoring capabilities to protect just-in-time delivery schedules.
Japan
METI energy efficiency standards elevate demand for low pressure-drop electrostatic precipitation systems in Nagoya and Osaka machining clusters. JIS industrial ventilation specifications mandate validated capture documentation for aerospace component manufacturing. Titanium and nickel alloy machining operations in Chubu region prioritize minimal filter replacement downtime.
Switzerland
Swissmedic-aligned cleanroom standards for medical device manufacturing drive specification of compact, energy-recovery collector designs in Zurich and Basel clusters. ISO 13485-certified machining environments demand validated particulate retention documentation. Precision component fabricators specify coalescing filter media with embedded drainage layers for Class 7 cleanroom protection.
Oil Mist Collector Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the oil mist collector supply base. Vertically integrated filter media manufacturers sustain pricing power through captive supply of glass fiber and nanofiber substrates. The vendor base separates into three archetypes: integrated filtration conglomerates with multi-industry portfolios, specialized industrial ventilation pure-plays, and regional fabrication shops serving cost-sensitive job shops. Dominant competitive moves include backward integration into filter media production and geographic expansion through distributor network acquisition.
Among Sweden-based industrial ventilation specialists, Absolent Group AB and Nederman Holding AB exemplify the pure-play archetype with concentrated exposure to metalworking and welding environments. Donaldson Company anchors the integrated conglomerate tier with multi-industrial filtration portfolios spanning engine and industrial segments. These three entities represent distinct strategic positions: specialized European engineering focus, Nordic channel control in automated environments, and North American scale with upstream media integration.
| Leading Market Players |
|---|
| Donaldson Company |
| Nederman Holding AB |
| Absolent Group AB |
| Camfil AB |
| RoboVent |
| Filtermist Holdings Limited |
| AIRMAX International |
| Rentschler REVEN |
| Losma S.p.A. |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between EPA NESHAP-compliant high-efficiency systems and standard mechanical units manifests in divergent margin structures and supply chain footprints across the oil mist collector market. Premium-tier collectors draw from captive nanofiber substrate production in Germany and Japan, while commodity-grade equipment sources generic filter media through distributed Asian supply networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement, with differentiation anchored in capture efficiency certification and predictive maintenance bundling. Premium systems command substantial markups for validated HEPA-grade documentation serving aerospace and medical device manufacturers. Cost compression in standard-tier mechanical units intensifies because Chinese automotive supplier parks consolidate procurement under framework agreements. Tier-2 job shops in Ohio and Michigan exhibit highest price sensitivity, while Stuttgart powertrain operations prioritize uptime value over capital outlay.
Supply Chain Analysis
Refurbishment flows for electrostatic precipitation cells and filter cartridge remanufacturing create secondary material circuits that reduce raw material exposure for collector OEMs. Glass fiber and nanofiber substrate production concentrates in Germany, Japan, and the United States, with specialized media drawing from borosilicate and synthetic polymer feedstocks. Single-source vulnerability in high-efficiency filter media strains supply security during demand surges from EU Green Deal compliance deadlines. Distribution runs through authorized industrial ventilation distributors and direct OEM relationships with Tier-1 automotive suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in oil mist collection equipment rests on the shift toward predictive maintenance subscriptions and energy-recovery designs that capture recurring revenue beyond initial hardware deployment.
For Market Incumbents: Deepen backward integration into nanofiber filter media production to defend pricing power against emerging Asian substrate suppliers. Expand certified service technician networks in German and Polish manufacturing regions where ductwork design expertise scarcity extends commissioning timelines. Prioritize IoT sensor integration to unbundle monitoring services from equipment sales. For New Entrants and Emerging Players: Enter via compact energy-recovery collector designs targeting ISO 13485-certified medical device machining in Switzerland and Ireland, where incumbent presence remains underdeveloped. Pursue direct relationships with precision component fabricators in Zurich and Basel clusters rather than competing for automotive powertrain contracts. Position around validated cleanroom documentation as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where filter media supply concentration meets fragmented regional installation capabilities across European metalworking corridors. Five-to-ten-year viability favors asset-light designers with proprietary coalescing media technology over capital-heavy producers dependent on commodity substrates. Monitor PFAS regulatory finalization timelines as the critical inflection signal for coolant formulation shifts and consequent collector material compatibility requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Media | Captive nanofiber substrate production insulates Donaldson and Japanese suppliers from input cost volatility. |
| Predictive Maintenance Subscription Launch | Bavarian Tier-1 suppliers bundle remote monitoring with collector procurement to minimize unplanned downtime. |
| Medical Device Certification Investment | Swissmedic-aligned documentation opens Class 7 cleanroom machining environments in Basel and Zurich clusters. |
| Electrostatic Precipitation Technology Licensing | Low pressure-drop designs penetrate aerospace manufacturing in Seattle and Toulouse where downtime avoidance commands premium pricing. |
| Regional Installation Capability Acquisition | Ductwork engineering expertise scarcity in German manufacturing regions extends project margins for qualified installers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads with secondary validation. EPA NESHAP regulatory filings, OSHA enforcement databases, EU ETS industrial emissions records, and customs trade data for filtration equipment supported bottom-up and top-down triangulation across the analysis window.
Segment-weighting approaches modeled product architecture, capture technology, installation complexity, and end-use vertical simultaneously. CAGRs were derived from installed base expansion rates and replacement cycle compression tied to regulatory deadlines. Forecast inputs incorporated MIIT emissions guideline enforcement timelines in China and REACH hazardous substance restriction implementation phases across European metalworking clusters.
Inputs from regulatory filings and trade databases were available through the study window; gaps in small job shop retrofit timing introduce uncertainty bands around near-term volume projections. Practitioners should monitor EPA PFAS rulemaking progress and ECHA restriction proposals for early signals of coolant formulation shifts that would reshape collector material compatibility specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Global Direct Current (DC) Motor Market
Industrial Motors
Global Low Voltage Motors Market
Industrial Motors
Vertical Gear Motor Market
Industrial Motors
Air Heater Tubes Market
Industrial Motors
Power Scraper Market
Industrial Motors
Permanent Magnet Synchronous Motors Market
Industrial Motors
Global Refrigeration Oil Market
Industrial Motors
Nuclear Polar Crane Market
Industrial Motors
Servo Motors and Drives Market
Industrial Motors
AC Servo Motors and Drives Market
Industrial Motors
Fractional Horsepower Motor Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
AC Motor Market
Industrial Motors
Safety Drives and Motors Market
Industrial Motors
Europe Hazardous Location Motors Market
Industrial Motors
Synchronous Electric Motor Market