
 High Frequency Transformer Market | 2026-2036
High Frequency Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
High Frequency Transformer Market Foresight
Magnetics engineering talent scarcity is reorganizing competitive dynamics across the high frequency transformer supply base. Murata Manufacturing Co. Ltd. leverages its in-house ferrite material science to dominate planar transformer architectures for telecommunications infrastructure. TDK Corporation anchors Japanese production networks through captive sintering operations that sustain cost discipline at scale. Delta Electronics Inc. competes aggressively in power supply applications by extending vertically into automated winding equipment.
A high frequency transformer is an electromagnetic device engineered to transfer energy between circuits through inductive coupling at switching frequencies typically exceeding 20 kHz, utilizing ferrite or powdered iron cores to minimize eddy current losses. Its primary purpose is enabling compact, efficient power conversion in switch-mode supplies and resonant converter topologies where line-frequency magnetics would impose prohibitive size and weight penalties. Planar transformers now capture the dominant share of value in data center power architectures due to their low profile and excellent thermal coupling to PCB substrates. Core transformers retain structural importance in industrial inverter applications where high-voltage isolation requirements and custom winding specifications create durable margin pools. Switching mode technology leads volume deployment across consumer electronics adapters, while resonant converter designs are gaining ground in automotive onboard chargers where efficiency targets approach physical limits.
The US FCC and EPA efficiency mandates are tightening no-load power consumption limits for external power supplies, directly shaping transformer core material selection and winding optimization priorities. China's GB standards and MIIT directives on dual carbon compliance are accelerating ferrite grade substitution toward lower-loss compositions in domestic manufacturing. Japan's METI Top Runner program sustains incremental pressure on standby power metrics that cascade into transformer design specifications. Stakeholders must monitor evolving regional efficiency tier thresholds and pre-position qualification capacity before product certification windows narrow.
Market Dynamics
Data center power density requirements are compressing transformer form factors while simultaneously demanding higher isolation ratings, forcing magnetics suppliers to reconcile thermal performance with dielectric spacing constraints that legacy winding architectures cannot satisfy.
Growth Catalysts
- EV charging infrastructure buildout:China's NMPA efficiency benchmarks and dual carbon goals mandate high-frequency magnetics in DC fast chargers, pulling ferrite core orders from domestic suppliers.
- Industrial automation servo drives:Germany's Ruhr industrial corridor specifications for welding equipment and robotics are standardizing planar transformer footprints to reduce control cabinet volume.
- Telecommunications 5G deployment:Base station power supply density requirements favor multilayer PCB-integrated magnetics over conventional bobbin-wound designs for thermal management.
Market Restraints
- Copper and ferrite raw material volatility:Mn-Zn ferrite powder pricing swings and copper magnet wire cost pressure compress margin predictability for mid-tier winding houses.
- Japanese sintering capacity concentration:Captive ferrite core production by integrated electronics conglomerates limits independent transformer manufacturers' supplier diversification options.
- Planar transformer height limitations:Low-profile PCB-integrated designs sacrifice winding window area, constraining power handling in applications above 5 kW without paralleling.
Strategic Opportunities
- India industrial electrification:BIS efficiency labeling expansion and CEA power quality mandates create qualification windows for high-frequency magnetics in motor drives and UPS systems.
- Solid-state transformer convergence:Silicon carbide power electronics integration with high-frequency magnetics enables medium-voltage DC distribution architectures for renewable interconnection.
- Automotive onboard charger expansion:Resonant converter topologies approaching physical efficiency limits are driving custom planar transformer specifications for 800V battery platforms.
Industry Challenges
- Magnetics engineering talent scarcity:Specialized knowledge in high-frequency loss modeling and thermal-electromagnetic co-simulation concentrates among senior practitioners at tier-one suppliers.
- Multi-jurisdiction certification timelines:UL insulation system recognition, VDE partial discharge testing, and IEC 61558 safety approvals require sequential rather than parallel qualification paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Frequency Transformer Market |
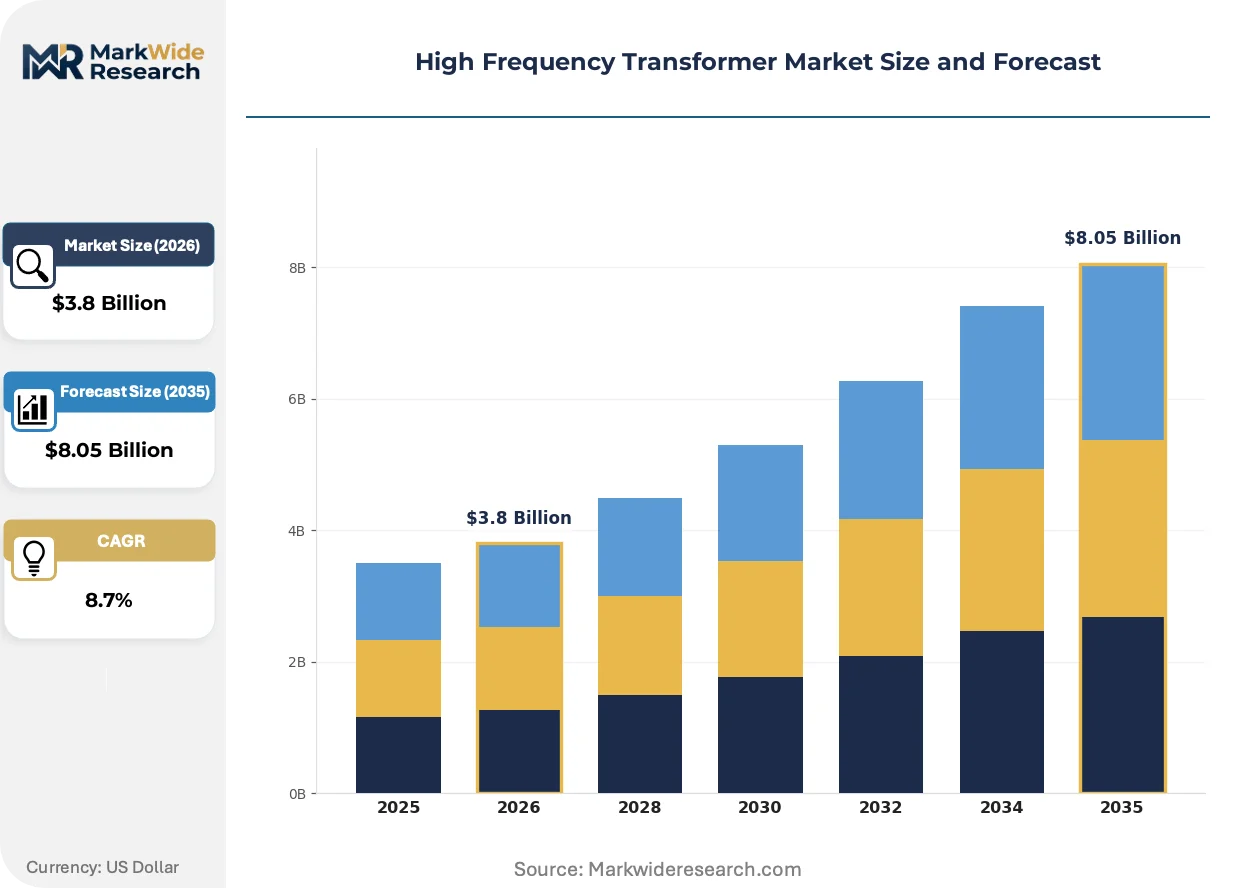
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Planar Transformers, Core Transformers, Split-Winding Transformers, Integrated Transformers Application: Telecommunications, Audio Equipment, Power Supplies, Inverters End User: Consumer Electronics, Industrial Equipment, Automotive, Aerospace Technology: Switching Mode, Resonant Converters, Magnetic Amplifiers, Flyback Converters |
| Companies Covered | Murata Manufacturing Co. Ltd., TDK Corporation, Delta Electronics Inc., Vishay Intertechnology, Inc., Würth Elektronik GmbH & Co. KG, Taiyo Yuden Co. Ltd., Coilcraft Inc., ABC Taiwan Electronics Corp., Bel Fuse Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Frequency Transformer Market Shifts & Advancements
Transformer architectures are bifurcating between ultra-flat PCB-integrated designs for density-constrained applications and custom-wound toroidal configurations where isolation robustness dominates procurement criteria.
Amorphous metal and nanocrystalline ribbon cores are fragmenting the traditional ferrite monopoly in high-frequency power conversion. These materials deliver sub-100 W/kg core losses at 100 kHz switching frequencies that ferrite grades struggle to match. Data center power supply manufacturers are qualifying nanocrystalline common-mode chokes and output inductors for 80 PLUS Titanium efficiency targets. The technology is fragmenting established supplier relationships as specialty alloy producers bypass conventional ferrite distributors to engage directly with magnetics designers.
REACH substance restrictions and RoHS recast directives are eliminating specific epoxy potting compounds and solder alloys from transformer manufacturing workflows. European power supply OEMs are reformulating insulation systems and requalifying thermal class ratings to maintain CE marking compliance. The regulatory pressure is accelerating material substitution timelines, with German industrial automation suppliers demanding full material declaration documentation from magnetic component vendors before contract renewal.
Power supply buyers are consolidating vendor panels and demanding application engineering support bundled with component supply. Tier-one data center operators now require transformer suppliers to provide thermal modeling and EMI pre-compliance testing as standard service inclusions. This service integration is displacing pure component distributors in the specification phase. The shift is most pronounced in North American hyperscale facility buildouts where procurement teams prioritize single-source accountability for magnetics performance.
High Frequency Transformer Market Segmentation
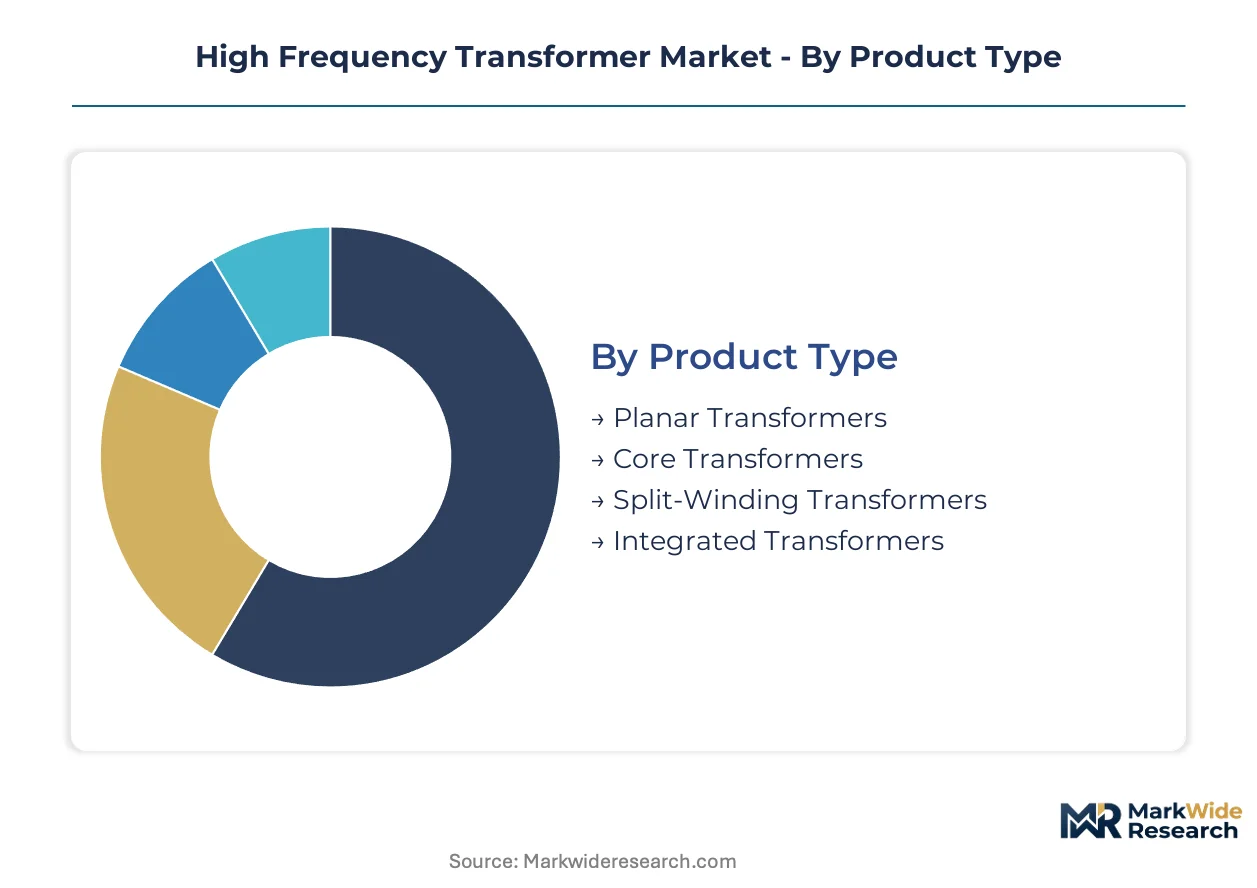
High frequency transformer procurement decisions hinge on thermal-electromagnetic trade-offs that vary sharply across application environments. Regulatory efficiency tiers and isolation safety standards fragment supplier qualification paths, making segment-specific technical roadmaps essential for market positioning.
Product Type:
Regulatory differentiation in efficiency benchmarking and safety isolation standards splits procurement criteria across transformer architectures. US FCC no-load power limits and China's GB standards favor distinct core geometries and winding methodologies.
- Planar Transformers:These multilayer PCB-integrated designs utilize flat copper windings etched or stamped onto substrate layers, achieving sub-10mm profile heights with direct thermal coupling to circuit boards. Data center power supply manufacturers in Germany's Ruhr industrial corridor specify these for 80 PLUS Titanium efficiency targets where volumetric density governs rack economics. Dielectric spacing constraints in high-voltage isolation zones force iterative thermal-electromagnetic co-simulation during qualification.
- Core Transformers:Conventional bobbin-wound ferrite assemblies with discrete core halves and interleaved winding windows dominate industrial inverter applications requiring custom voltage ratios. China's NMPA efficiency mandates for EV charging infrastructure pull orders toward Mn-Zn ferrite grades with lower core loss coefficients. Custom winding specifications create durable margin pools where automated winding equipment cannot achieve required fill factors.
- Split-Winding Transformers:Segmented primary and secondary configurations enable precise leakage inductance control for resonant converter topologies.
- Integrated Transformers:Magnetics-plus-passives consolidation reduces component count in space-constrained automotive onboard charger modules.
Planar transformers handle the majority of throughput in telecommunications and data center verticals; resonant converter-optimized split-winding designs are gaining share fastest in automotive electrification.
Application:
Cost tier stratification separates premium qualification-intensive deployments from high-volume consumer electronics procurement. Safety agency recognition requirements and thermal class ratings fragment pricing architecture across end-use categories.
- Telecommunications:Base station power supplies demand multilayer PCB-integrated magnetics with integrated shielding layers for EMI suppression in dense RF environments. 5G deployment in Japan under METI Top Runner efficiency pressure favors planar architectures with documented thermal modeling. Partial discharge testing to VDE standards extends qualification timelines for European network equipment suppliers.
- Power Supplies:External adapter and internal PSU applications span consumer electronics through industrial instrumentation with divergent isolation and efficiency specifications. US EPA efficiency mandates cascade into core material selection priorities for external power supply OEMs. Copper magnet wire gauge optimization and ferrite grade substitution dominate cost engineering workflows.
- Audio Equipment:Low-noise signal isolation requirements in professional and consumer audio favor toroidal geometries with minimal stray flux.
- Inverters:Motor drive and renewable energy conversion applications specify high-voltage isolation systems with extended thermal class ratings.
Power supplies absorb the largest share of transformer volume across all product categories; telecommunications infrastructure represents the steepest expansion trajectory as 5G densification accelerates.
End User:
Customer type fragmentation separates specification-driven industrial procurement from price-sensitive consumer electronics sourcing. Engineering support bundling and application co-development requirements concentrate among data center and automotive verticals.
- Automotive:Onboard charger and DC-DC converter applications specify planar transformers with 800V isolation ratings for battery electric platforms. Resonant converter topologies approaching physical efficiency limits drive custom magnetic designs with nanocrystalline core materials. REACH substance restrictions eliminate legacy epoxy potting compounds from manufacturing workflows.
- Industrial Equipment:Servo drives, welding equipment, and robotics specify high-frequency magnetics for compact control cabinet integration. Germany's industrial automation corridor standardizes planar footprints to reduce enclosure volume while maintaining VDE partial discharge compliance. Material declaration documentation requirements from Siemens and Bosch suppliers accelerate supply chain transparency mandates.
- Consumer Electronics:High-volume adapter and charger applications prioritize automated winding compatibility and ferrite core cost discipline.
- Aerospace:Radiation-hardened and extended temperature range specifications govern satellite and avionics power conversion subsystems.
Industrial equipment commands premium pricing through custom engineering engagement; automotive electrification is climbing the fastest on volume as 800V platforms proliferate.
Technology:
Volume concentration in mature switching mode designs contrasts with emerging resonant converter deployment in efficiency-critical segments. Topology selection cascades into transformer leakage inductance, core loss, and winding loss optimization priorities.
- Switching Mode:Hard-switched PWM topologies dominate consumer electronics adapters and industrial power supplies with switching frequencies typically 20-100 kHz. Ferrite core grades with optimized Mn-Zn compositions balance saturation flux density against core loss coefficients. China's MIIT directives on dual carbon compliance accelerate substitution toward lower-loss ferrite compositions in domestic manufacturing.
- Resonant Converters:Soft-switched LLC and LCC topologies enable zero-voltage switching transitions that push efficiency toward physical limits in automotive and data center applications. Custom planar transformer specifications with precise leakage inductance control govern resonant tank design. Silicon carbide power electronics integration enables medium-voltage DC distribution architectures with high-frequency magnetics at the core.
- Magnetic Amplifiers:Saturable reactor-based post-regulation persists in legacy telecommunications rectifier designs requiring multiple isolated outputs.
- Flyback Converters:Single-switch isolated topologies retain cost advantage in low-power adapter applications below 150W.
Switching mode technology processes the highest unit volumes across consumer and industrial segments; resonant converter deployment is expanding most quickly in automotive onboard chargers and hyperscale data center power architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA efficiency mandates and dual carbon targets are restructuring procurement patterns across the high frequency transformer supply base, with regulatory pressure cascading from EV charging infrastructure into industrial power conversion applications.
China
DC fast charger deployment under NMPA benchmarks is pulling ferrite core orders toward domestic Mn-Zn suppliers with lower-loss compositions. MIIT directives on dual carbon compliance accelerate substitution timelines in switch-mode power supply manufacturing. Yangtze River Delta magnetics clusters are absorbing capacity expansion from winding houses serving EV onboard charger programs.
Germany
Siemens and Bosch suppliers in the Ruhr industrial corridor specify planar transformer footprints to compress servo drive control cabinet volumes. VDE partial discharge testing requirements extend qualification timelines for welding equipment magnetics. Baden-Württemberg automation OEMs are standardizing PCB-integrated designs across robotics power architectures.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth are consolidating vendor panels for planar transformer supply with bundled thermal modeling services. FCC no-load power limits for external power supplies shape core material selection priorities. EPA efficiency mandates cascade into ferrite grade optimization for adapter manufacturers.
Japan
METI Top Runner program pressure on standby power metrics sustains incremental design specification tightening for telecommunications infrastructure. Kanto region base station power supply manufacturers favor multilayer PCB-integrated magnetics with documented thermal modeling. Captive sintering operations by integrated conglomerates limit independent transformer manufacturers' supplier diversification.
India
BIS efficiency labeling expansion and CEA power quality mandates create qualification windows for high-frequency magnetics in motor drives and UPS systems. Maharashtra industrial electrification programs are standardizing planar transformer specifications for textile and pharmaceutical automation. Tamil Nadu electronics manufacturing clusters are absorbing winding capacity for export-oriented power supply production.
High Frequency Transformer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the high frequency transformer market. Japanese and Taiwanese integrated electronics conglomerates with captive ferrite material science anchor premium-tier supply for telecommunications and data center applications. Mid-tier winding houses compete on automated manufacturing scale for consumer electronics adapter volumes. Strategic moves concentrate on backward integration into ferrite powder processing and geographic expansion into India's industrial electrification corridor.
Within the integrated materials tier, Murata Manufacturing Co. Ltd. and TDK Corporation exemplify archetypes combining captive sintering with planar transformer design capabilities. Delta Electronics Inc. occupies a position representing aggressive manufacturing scale and automated winding equipment control. These three anchors demonstrate how competitive positioning splits between material science depth and production automation intensity.
| Leading Market Players |
|---|
| Murata Manufacturing Co. Ltd. |
| TDK Corporation |
| Delta Electronics Inc. |
| Vishay Intertechnology, Inc. |
| Würth Elektronik GmbH & Co. KG |
| Taiyo Yuden Co. Ltd. |
| Coilcraft Inc. |
| ABC Taiwan Electronics Corp. |
| Bel Fuse Inc. |
| Others |
Supply & Pricing Matrix
Captive sintering operations at Japanese integrated conglomerates create scale economies that set ferrite core price floors independent of spot raw material movements. China's Yangtze River Delta winding houses absorb capacity expansion pressure from EV onboard charger programs, compressing margin pools for mid-tier suppliers without backward integration into powder processing.
Pricing Analysis
Japanese planar transformer quotations command 40-60% premiums over Taiwanese and Chinese equivalents due to METI Top Runner compliance documentation and captive material science. Three-tier pricing structure across premium, standard, and economy levels separates telecommunications infrastructure with bundled thermal modeling from consumer adapter volumes with pure component supply. Cost compression in consumer electronics tiers intensifies because automated winding equipment standardization eliminates customization premiums. Data center operators exhibit lowest price sensitivity, prioritizing single-source accountability and EMI pre-compliance testing over unit cost.
Supply Chain Analysis
China, Japan, and Taiwan anchor high-frequency transformer manufacturing through distinct capability layers: Chinese winding houses scale automated production, Japanese conglomerates control ferrite sintering, Taiwanese suppliers bridge PCB integration. Mn-Zn ferrite powder, copper magnet wire, and nanocrystalline ribbon cores constitute critical input dependencies. Single-source vulnerability concentrates in Japanese ferrite core supply, where independent transformer manufacturers lack supplier diversification options. Distribution runs through direct OEM engagement for data center and automotive verticals, with component distributors displaced in specification phases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state transformer convergence with silicon carbide power electronics represents a technological inflection that will restructure competitive boundaries across medium-voltage DC distribution architectures.
For Market Incumbents: Fortify captive ferrite material science capabilities against nanocrystalline ribbon core substitution threatening traditional Mn-Zn dominance. Expand qualification capacity for UL insulation system recognition and VDE partial discharge testing before certification windows narrow under evolving regional efficiency tiers. Backward integration into automated winding equipment preserves cost discipline at scale against mid-tier winding house competition. For New Entrants and Emerging Players: Anchor in India's industrial electrification corridor where BIS efficiency labeling expansion and CEA power quality mandates create qualification windows without entrenched supplier relationships. Target motor drive and UPS system applications in Maharashtra and Tamil Nadu clusters where planar transformer specifications remain under-standardized. Lead with application engineering support bundled with component supply, mirroring tier-one data center procurement expectations. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among magnetics designers with direct OEM relationships in automotive onboard charger and data center power supply verticals. Long-term viability hinges on qualification-intensive segments where safety agency recognition creates durable switching costs. Acquisition targets should demonstrate nanocrystalline core qualification progress or silicon carbide integration partnerships. The signal to watch is 800V platform proliferation rates among battery electric vehicle manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite Powder Processing | Captive Mn-Zn ferrite supply secures margin control against Japanese sintering concentration. |
| Automotive 800V Platform Qualification | Custom planar transformer specifications for resonant converters unlock premium pricing pools. |
| India Manufacturing Footprint Expansion | BIS and CEA mandates in Maharashtra create first-mover advantage in motor drive magnetics. |
| Nanocrystalline Core Material Partnership | Sub-100 W/kg core loss performance addresses 80 PLUS Titanium efficiency targets. |
| Bundled Application Engineering Services | Thermal modeling and EMI pre-compliance testing displace pure component distributors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industry association disclosures across magnetics engineering. Primary interviews engaged transformer design engineers at tier-one suppliers, procurement leads at data center operators, ferrite material scientists at integrated conglomerates, and plant managers at automated winding facilities. Secondary validation drew from NMPA efficiency benchmark publications, METI Top Runner program documentation, VDE testing standards, and SEC filings of publicly traded magnetics manufacturers. Bottom-up unit economics triangulate against top-down market size estimates from trade flow analysis.
Segmentation dimensions modeled include product architecture, application vertical, end-user category, and converter topology across the projection horizon. Planar, core, split-winding, and integrated transformer configurations segment by thermal-electromagnetic performance trade-offs. Power supply, telecommunications, industrial equipment, and automotive electrification applications stratify by qualification intensity and safety agency requirements. CAGRs derive from installation base growth, replacement cycle dynamics, and efficiency regulation enforcement timelines. Silicon carbide power electronics penetration rates and 800V automotive platform adoption constitute industry-specific forecast inputs.
Material uncertainties — raw material price volatility, regulatory timeline acceleration, and substitute core material qualification delays — sit outside the modeled envelope. Forecasts reflect assumptions about NMPA and MIIT enforcement consistency, METI program continuity, and REACH substance restriction implementation scope. Recalibration cycles align with material shifts in dual carbon policy intensity, data center power density requirements, and automotive voltage platform transitions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Liquid Filled Transformer Market
Transformers
Green Power Transformers Market
Transformers
Oil Filled Transformer Market
Transformers
Three Phase Transformer Market
Transformers
Gas Insulated Transformer Market
Transformers
Europe Distribution Transformer Market
Transformers
Cast Resin Transformers Market
Transformers
Rail Traction Transformers Market
Transformers
China Transformer Market
Transformers
Smart Transformer Market
Transformers
Industrial Control Transformers Market
Transformers
Box Transformer Substation Market
Transformers
Europe Smart Transformers Market
Transformers
Global Large Power Transformers Market
Transformers
Renewable Energy Transformer Market
Transformers
Traction Transformer Market