
 United States Distribution Transformer Market | 2026-2036
United States Distribution Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
United States Distribution Transformer Market Analytics
Multi-source procurement among electric utilities is restructuring supply relationships across the United States distribution transformer sector. Hammond Power Solutions anchors North American coil manufacturing with in-house core steel processing. Eaton competes through integrated power management portfolios spanning medium-voltage switchgear to distribution transformers. ERMCO specializes in pole-mounted designs for rural electric cooperatives across the Midwest and Southeast.
A distribution transformer is a static electromagnetic device that steps down medium-voltage electricity, typically 4-35 kV, to utilization voltages of 120-480 V through oil-immersed or dry-type insulation systems rated by NEMA and IEEE thermal performance standards. Its primary purpose is delivering reliable low-voltage power to end users while managing load fluctuations and fault currents across radial distribution networks. Oil-immersed units dominate utility-scale deployments where thermal capacity and cost efficiency outweigh fire safety constraints. Dry-type transformers command premium positioning in commercial buildings and data centers where indoor installation prohibits liquid dielectrics. Pad-mounted installations lead new construction segments while pole-mounted units sustain replacement cycles across aging overhead infrastructure.
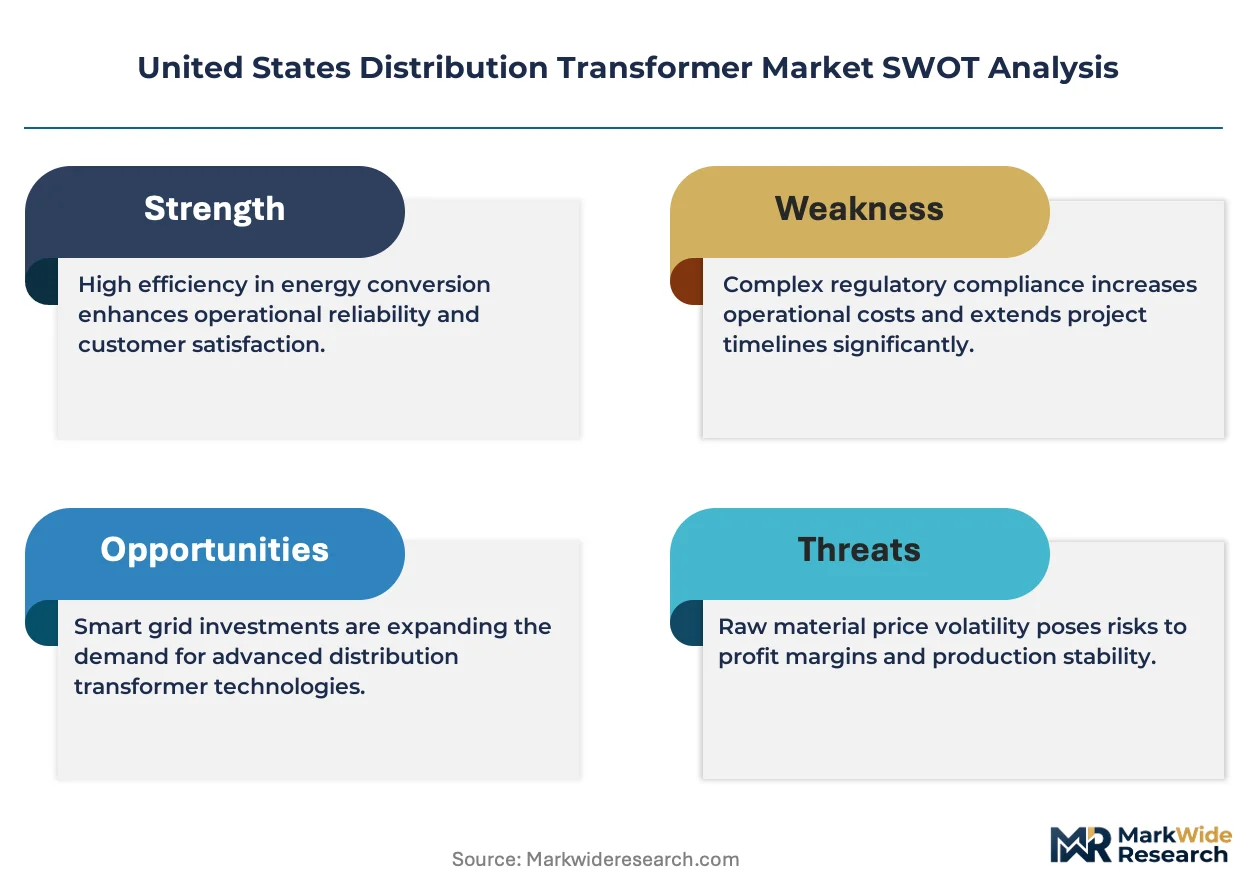
The Department of Energy mandates minimum efficiency standards under 10 CFR 431, compelling manufacturers to adopt amorphous metal cores and optimized winding geometries. NEMA TP-1 and IEEE C57.12.00 define testing protocols that shape product certification and market access for domestic and imported equipment. State public utility commissions in California, New York, and Texas incorporate these federal benchmarks into integrated resource planning requirements. Stakeholders must monitor proposed DOE rulemakings on distribution transformer efficiency tiers alongside copper and grain-oriented electrical steel price volatility to align capacity investments with procurement cycles.
Market Dynamics
Multi-source procurement among electric utilities is restructuring supply relationships across the United States distribution transformer sector. Hammond Power Solutions anchors North American coil manufacturing with in-house core steel processing. Eaton competes through integrated power management portfolios spanning medium-voltage switchgear to distribution transformers. ERMCO specializes in pole-mounted designs for rural electric cooperatives across the Midwest and Southeast.
Growth Catalysts
- Data center load expansion:Hyperscale facilities in Texas and Virginia are accelerating procurement of pad-mounted units with enhanced thermal capacity ratings.
- 10 CFR 431 efficiency mandates:The Department of Energy's tightening core loss requirements are compelling utilities to modernize aging transformer fleets ahead of compliance deadlines.
- Grid hardening programs:Southeast utilities are replacing overhead infrastructure damaged by severe weather events with resilient underground pad-mounted systems.
Market Restraints
- Grain-oriented electrical steel concentration:Domestic supply constraints on specialized core steel from limited North American melt shops create input bottlenecks.
- Amorphous metal core cost premium:DOE-compliant efficiency tiers require material substitutions that increase unit manufacturing costs substantially.
- Copper price volatility:Winding conductor costs fluctuate with commodity markets, compressing margin predictability for long-delivery contracts.
Strategic Opportunities
- Smart grid integration:Embedded sensors and IoT-enabled monitoring systems are creating upgrade pathways for existing transformer installations.
- Rural cooperative electrification:Midwest and Southeast electric cooperatives present underserved demand for pole-mounted single-phase units.
- Inflation Reduction Act manufacturing credits:Domestic content incentives are enabling reshoring of core steel processing and coil winding operations.
Industry Challenges
- Skilled winding technician shortage:Precision coil manufacturing requires specialized labor that training pipelines have failed to replenish.
- NEMA TP-1 certification timelines:Extended laboratory testing protocols delay product launches and contract awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Distribution Transformer Market |
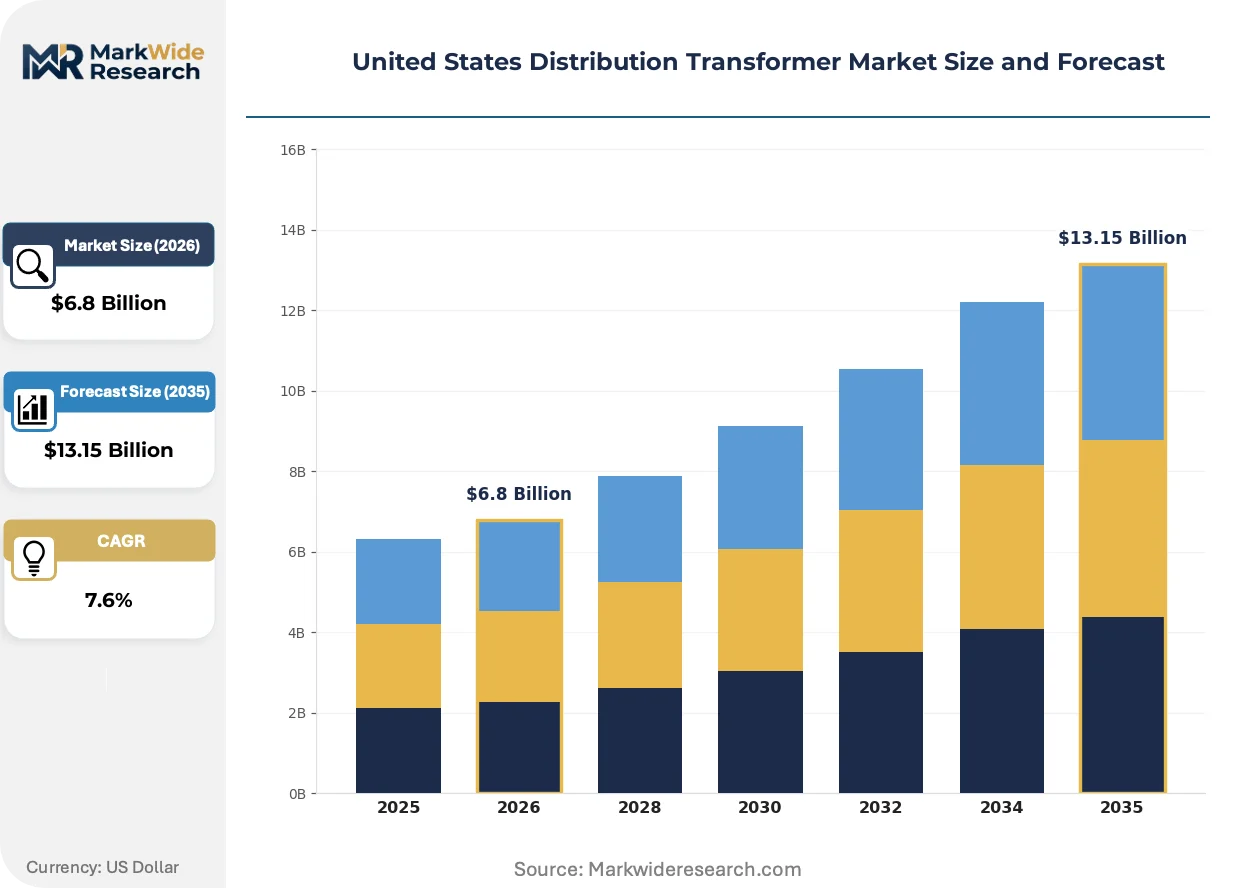
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-Immersed, Dry-Type, Hermetically Sealed, Non-Hermetic End User: Residential, Commercial, Industrial, Utilities Capacity: Up to 100 kVA, 100-500 kVA, 501-1000 kVA, Above 1000 kVA Installation: Pole-Mounted, Pad-Mounted, Underground, Others |
| Companies Covered | Hammond Power Solutions, Prolec-GE, Howard Industries, Eaton, Siemens Energy, ERMCO, Hitachi Energy, Carte International, Central Moloney, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Distribution Transformer Market Evolving Landscape
Amorphous metal core technology is electrifying efficiency benchmarks across utility procurement specifications. Manufacturers are reconfiguring production lines to accommodate material handling requirements that differ substantially from conventional grain-oriented silicon steel.
Veeco's deposition systems are enabling thinner amorphous ribbon production that is electrifying loss reduction targets. Data center operators in Northern Virginia and Dallas-Fort Worth are specifying these units for 24/7 baseload applications where no-load losses compound across decades of operation. The technology is compressing total cost-of-ownership calculations that previously favored cheaper conventional cores.
DOE rulemaking under 10 CFR 431 is mandating tiered efficiency standards that reshape product portfolios. Manufacturers must maintain parallel production capabilities for Tier 1 legacy units and Tier 2 amorphous-core designs serving regulated utilities. California and New York public utility commissions are incorporating these federal benchmarks into integrated resource planning requirements ahead of national adoption timelines.
Utility procurement departments are consolidating supplier relationships around integrated power management portfolios. Single-source contracting for switchgear, transformers, and protection equipment is displacing fragmented purchasing across multiple vendors. This concentration is most visible among Southeast investor-owned utilities executing grid hardening programs with unified equipment specifications.
United States Distribution Transformer Market Segmentation
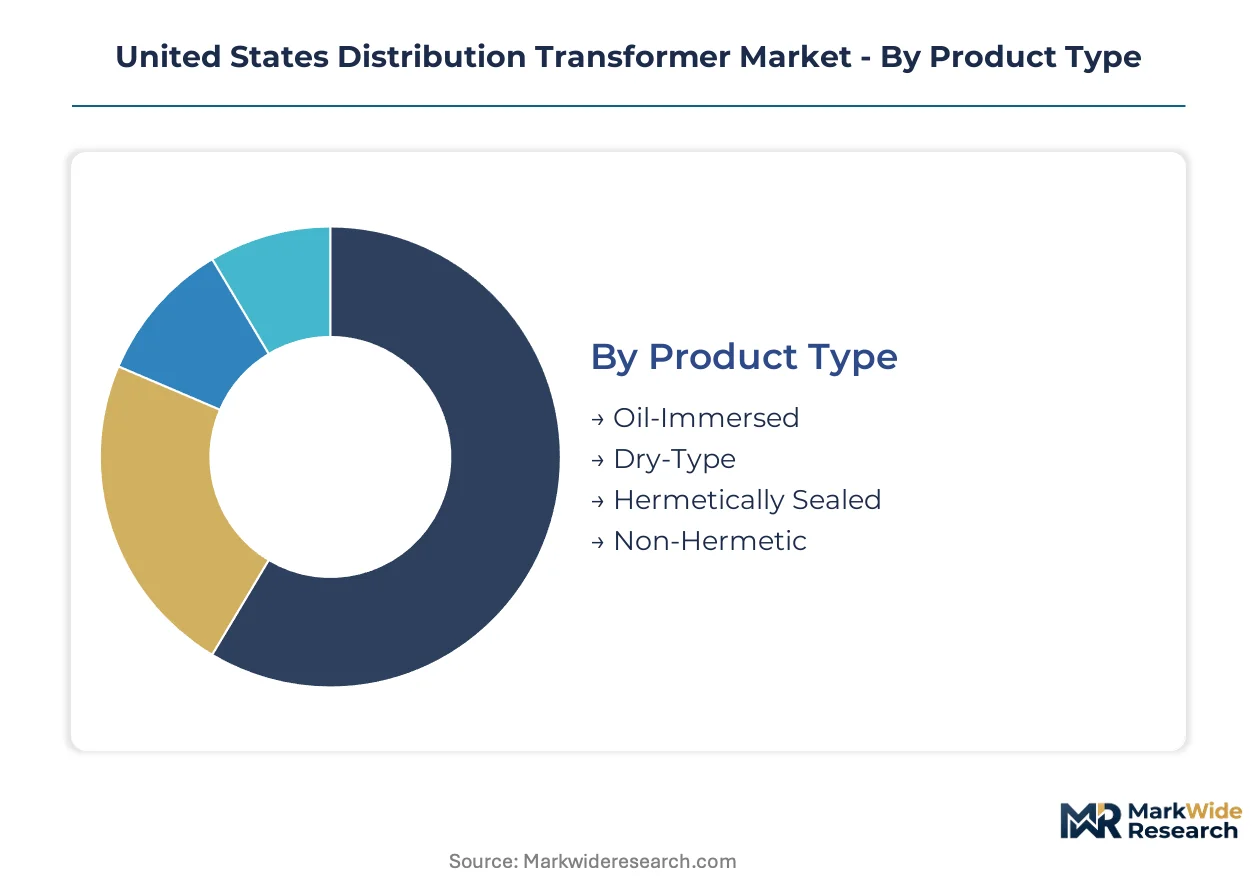
Distribution transformer procurement patterns diverge sharply across product architectures and deployment contexts. Utility engineers specify insulation systems and mounting configurations based on thermal constraints, fire safety codes, and grid topology requirements that vary by load density and climate exposure.
Product Type:
Oil-immersed designs dominate standalone outdoor installations where thermal capacity justifies liquid dielectric maintenance, while dry-type units embed into indoor commercial and data center environments where fire codes prohibit oil-filled equipment.
- Oil-Immersed:Mineral oil or synthetic ester fluid fills the tank to dissipate heat from core and windings, enabling higher power density per unit volume. Demand concentrates in Texas and Virginia utility substations serving hyperscale data centers where 24/7 thermal loading requires robust heat rejection. DOE efficiency mandates under 10 CFR 431 are accelerating fleet replacement ahead of compliance deadlines.
- Dry-Type:Epoxy resin or vacuum pressure impregnation insulates windings without liquid dielectrics, eliminating fire suppression requirements. Commercial buildings in California and New York specify these units for indoor electrical rooms where municipal codes restrict oil-filled apparatus. Premium pricing reflects copper winding costs and resin encapsulation complexity.
- Hermetically Sealed:Welded tank construction prevents atmospheric contamination of insulating fluid, extending service intervals in remote or unmanned locations. Rural electric cooperatives across the Midwest favor these designs for pole-mounted rural feeders.
- Non-Hermetic:Breather-equipped tanks allow pressure equalization with ambient atmosphere, simplifying manufacturing while requiring periodic maintenance. Aging infrastructure replacement programs in the Southeast utilize these cost-optimized units.
Volume placements concentrate in Oil-Immersed; the faster expansion belongs to Dry-Type.
End User:
Customer segments stratify by procurement scale, technical specification authority, and sensitivity to total cost-of-ownership versus first-cost minimization.
- Residential:Single-phase pole-mounted units serving individual dwellings or small clusters dominate replacement cycles. Investor-owned utilities in Florida and Georgia are accelerating underground conversion programs that displace overhead transformers with pad-mounted alternatives.
- Commercial:Three-phase pad-mounted and dry-type installations serve retail complexes, office buildings, and healthcare facilities. Load growth in Dallas-Fort Worth and Phoenix metro areas is expanding procurement of 500-1000 kVA units with enhanced short-circuit withstand.
- Industrial:Heavy manufacturing and petrochemical facilities specify custom-engineered units with specialized impedance characteristics. Gulf Coast refineries demand hermetically sealed designs resistant to corrosive atmospheres.
- Utilities:Bulk procurement by municipal and cooperative systems drives standardization around IEEE C57.12.00 configurations. FERC rate-case proceedings influence capital budgeting cycles for distribution infrastructure.
Procurement volume clusters in Utilities; Commercial applications are climbing the fastest.
Capacity:
Power rating selection follows load forecasting methodologies that balance peak demand headroom against no-load loss economics across decades of operation.
- Up to 100 kVA:Single-phase pole-mounted units serve rural residential feeders and agricultural irrigation systems. Electric cooperatives in Kansas and Nebraska maintain extensive inventories of these standardized designs.
- 100-500 kVA:Three-phase pad-mounted configurations dominate suburban commercial and light industrial applications. Virginia data center clusters are specifying upper-range units with amorphous metal cores to minimize no-load losses.
- 501-1000 kVA:Larger commercial campuses and small industrial facilities require these intermediate ratings. Texas grid hardening programs are procuring fault-current-limiting variants for improved resilience.
- Above 1000 kVA:Heavy industrial loads and utility substation step-down applications demand these high-capacity designs. Lead times extend substantially due to specialized core steel and winding conductor requirements.
Shipment volumes peak in 100-500 kVA; Above 1000 kVA shows the steepest expansion trajectory.
Installation:
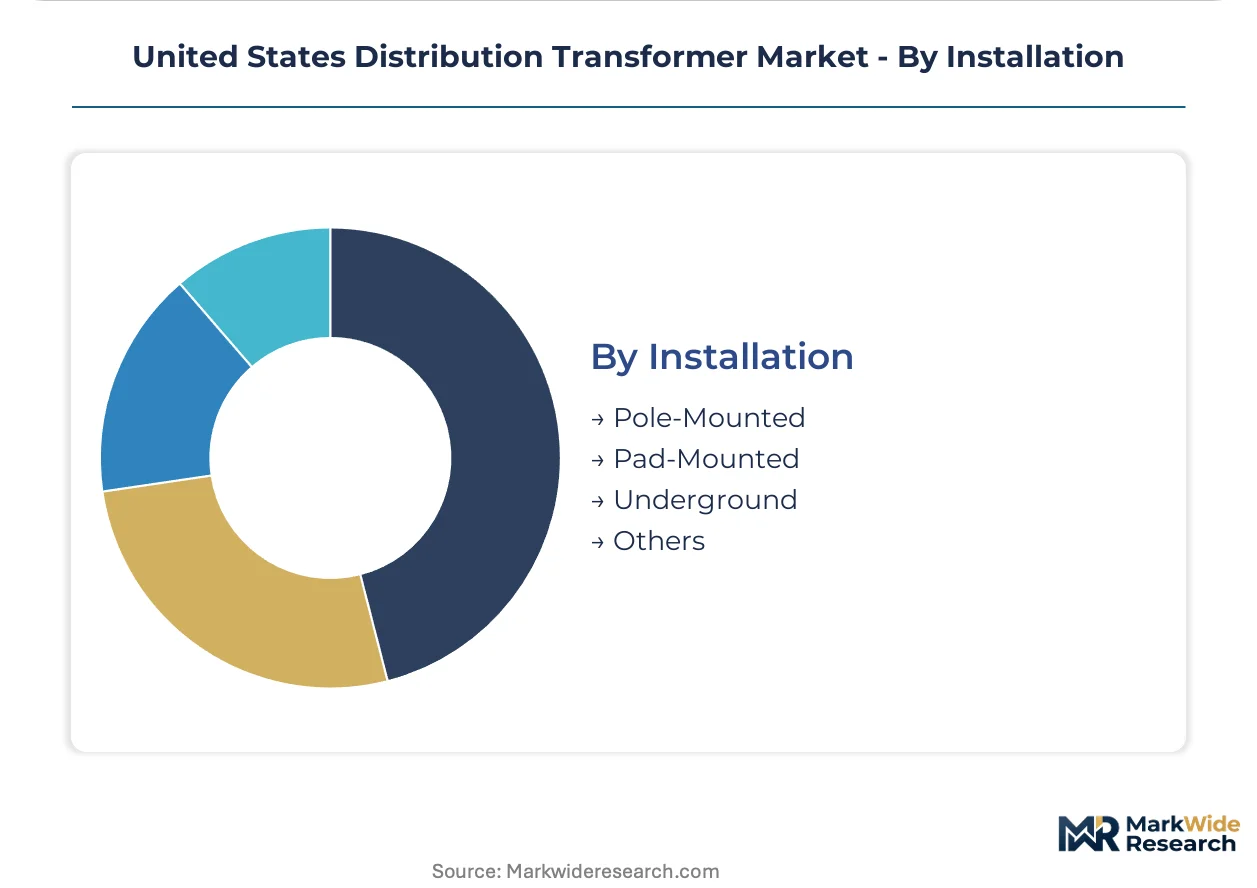
Mounting configuration determines accessibility for maintenance, vulnerability to environmental hazards, and land use requirements that shape utility capital planning.
- Pole-Mounted:Overhead line integration minimizes ground footprint and simplifies theft deterrence through elevation. Aging infrastructure across the Southeast sustains replacement demand despite undergrounding trends.
- Pad-Mounted:Compartmentalized enclosures enable underground cable termination and front-access maintenance. New construction in Texas and Virginia data center corridors is accelerating specification of tamper-resistant designs.
- Underground:Vault or direct-buried installations eliminate visual impact in urban cores and environmentally sensitive corridors. Manhattan and San Francisco density constraints favor these space-efficient configurations.
- Others:Submersible and specialty mounting arrangements serve flood-prone coastal zones and constrained industrial sites. Louisiana utilities specify these variants for hurricane resilience.
Pad-Mounted captures dominant volume share; Underground installations are gaining share fastest in coastal metros.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grain-oriented electrical steel production concentrates in the industrial Midwest, anchoring transformer manufacturing clusters across Ohio and Pennsylvania. This feedstock locality shapes regional procurement patterns and supplier logistics networks.
Southeast
Florida and Georgia utilities are accelerating underground conversion programs that displace aging overhead infrastructure. FERC rate-case proceedings influence capital budgeting cycles for distribution hardening investments. Atlanta and Miami metro areas are specifying pad-mounted units with enhanced fault-current withstand ratings.
Texas
Hyperscale data center construction in Dallas-Fort Worth and Austin is driving procurement of high-capacity pad-mounted transformers with amorphous metal cores. ERCOT interconnection queues are shaping utility planning horizons for substation expansions. The Permian Basin oilfield electrification sustains demand for ruggedized pole-mounted designs.
Virginia
Northern Virginia data center clusters are specifying 500-1000 kVA units with minimized no-load loss characteristics for 24/7 baseload operations. State corporation commission integrated resource planning incorporates DOE efficiency benchmarks ahead of federal deadlines. Loudoun County and Prince William County anchor the nation's densest data center transformer procurement corridor.
California
Commercial building electrification in Los Angeles and San Francisco is expanding dry-type transformer installations where municipal fire codes restrict oil-filled equipment. California Public Utilities Commission mandates are accelerating efficiency-compliant fleet replacements. Silicon Valley campus expansions are driving three-phase pad-mounted specifications with smart grid monitoring integration.
Midwest
Rural electric cooperatives across Kansas and Nebraska maintain extensive inventories of single-phase pole-mounted units for agricultural irrigation systems. MISO resource adequacy requirements are influencing transformer sizing standards for distributed generation interconnection. Chicago industrial corridor demand centers on custom-engineered units with specialized impedance characteristics.
United States Distribution Transformer Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers reconfigure production lines for amorphous metal core handling requirements. The vendor base stratifies across integrated power management conglomerates, specialized coil manufacturers, and regional fabricators serving electric cooperative procurement channels. Three archetypes define competitive positioning: vertically integrated steel-to-coil producers, diversified electrical equipment portfolios, and rural market specialists. M&A consolidation and domestic content-driven reshoring represent the dominant competitive moves reshaping supply relationships.
Among North American coil manufacturers, Hammond Power Solutions exemplifies the vertically integrated archetype with captive core steel processing capabilities. Eaton occupies a position within the diversified electrical equipment tier, spanning medium-voltage switchgear through distribution transformers in unified procurement portfolios. ERMCO represents the rural specialist segment, anchoring pole-mounted supply relationships with electric cooperatives across the Midwest and Southeast.
| Leading Market Players |
|---|
| Hammond Power Solutions |
| Prolec-GE |
| Howard Industries |
| Eaton |
| Siemens Energy |
| ERMCO |
| Hitachi Energy |
| Carte International |
| Central Moloney |
| Others |
Value Network & Pricing Analysis
Captive core steel processing anchors Hammond Power Solutions' supply position and pricing power against commodity-grade competitors. This backward integration into grain-oriented electrical steel production insulates coil manufacturing from spot market volatility while enabling premium positioning for amorphous metal core units compliant with DOE 10 CFR 431 mandates.
Pricing Analysis
Extended warranty and field service bundling separates premium-tier manufacturers from unbundled commodity suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—NEMA TP-1 and IEEE C57.12.00 compliance tiers command 15-25% premiums over unrated imports. Price erosion runs through economy-tier pole-mounted units as Asian fabricators capture rural cooperative procurement with stripped-down specifications. Electric cooperatives in Kansas and Nebraska exhibit highest price sensitivity, while Virginia data center operators prioritize total cost-of-ownership over first-cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with North American grain-oriented electrical steel melt shops concentrated in Ohio and Pennsylvania. Transformer manufacturing draws from specialized core steel, copper winding conductor, and epoxy resin encapsulation inputs. Tariff exposure on imported electrical steel from Japan and South Korea threatens margin stability for non-integrated fabricators. Distribution runs through direct utility procurement contracts and electric cooperative buying consortiums, with limited spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States distribution transformer sector is executing a technology-transition phase as amorphous metal cores displace conventional grain-oriented silicon steel under DOE efficiency mandates. This material substitution reconfigures competitive economics and supplier qualification requirements.
For Market Incumbents: Deploy captive core steel capacity as the priority lever. Hammond Power Solutions and Eaton should deepen backward integration into amorphous ribbon processing to defend margin position against import competition. Accelerate NEMA TP-1 certification pipelines to capture utility procurement windows ahead of 10 CFR 431 compliance deadlines. Consolidate supplier relationships with Southeast grid hardening programs through integrated power management portfolios spanning switchgear to transformers. For New Entrants and Emerging Players: Smart grid sensor integration offers a technology-first wedge into retrofit upgrade cycles. Target rural electric cooperative electrification gaps in Nebraska and Kansas with pole-mounted single-phase units featuring embedded IoT monitoring. Pursue white-label manufacturing partnerships with established coil winders to bypass NEMA certification timelines and access utility procurement channels without greenfield facility investment. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated electrical equipment conglomerates seeking coil manufacturing capacity. Long-term viability favors vertically integrated producers with captive steel processing and amorphous metal handling capabilities. Watch DOE rulemaking timelines on Tier 2 efficiency adoption as the inflection signal—accelerated federal mandates would strand conventional core manufacturing assets and trigger consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Amorphous Metal Core Capacity Buildout | DOE 10 CFR 431 compliance requires reconfiguring production lines for ribbon handling. |
| NEMA TP-1 Certification Investment | Laboratory testing protocols unlock utility procurement and FERC rate-case eligibility. |
| Smart Grid Sensor Integration | Embedded IoT monitoring creates upgrade pathways for existing transformer installations. |
| Rural Cooperative Channel Partnership | Midwest and Southeast electric cooperatives present underserved demand for pole-mounted units. |
| Domestic Content Reshoring | Inflation Reduction Act manufacturing credits enable captive core steel processing expansion. |
Research Methodology
Document review covered FERC rate-case filings, EIA electricity distribution data, and DOE 10 CFR 431 rulemaking dockets, complemented by interviews with utility planning officers, transformer procurement managers at investor-owned utilities, electric cooperative engineering directors, and core steel supply specialists. Secondary validation drew from SEC 10-K disclosures, NEMA shipment statistics, and IEEE standards documentation. Bottom-up unit shipment estimates triangulated against top-down utility capital expenditure projections.
Historical shipment patterns cross-referenced against utility procurement panel input across the analysis window. Segmentation modeling captured product type, end user, capacity tier, and installation configuration dimensions. CAGRs derived from regression analysis of utility infrastructure spending cycles, data center load growth trajectories, and efficiency mandate compliance deadlines. Forecast inputs incorporated ERCOT interconnection queue data and Virginia State Corporation Commission integrated resource planning filings.
Several conditions sit outside the modeled scope, including extreme weather event frequency beyond historical baselines and abrupt shifts in copper or electrical steel commodity pricing. Forecasts reflect assumptions on DOE rulemaking adoption timelines and Inflation Reduction Act credit continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Three Phase Transformer Market
Transformers
Green Transformer Market
Transformers
Transformer Monitoring Systems (TMS) Market
Transformers
Europe Telecom Transformers Market
Transformers
Transformer Bobbin Market
Transformers
Neon Transformer Market
Transformers
Europe Smart Transformers Market
Transformers
Electric Vehicle Charging Station Transformer Market
Transformers
India Transformer Market
Transformers
Phase-Shifting Transformer Market
Transformers
Distribution Transformer Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
Power Transformer Market
Transformers
Traction Transformer Market
Transformers
Saudi Arabia Transformer Market
Transformers
High Frequency Transformer Market