
 Gaming Laptop Market | 2026-2036
Gaming Laptop Market Size, Share, and Industry Trends Forecast 2026-2036
Gaming Laptop Market Intelligence
GPU engineering talent is collapsing across Taiwan and mainland China, constraining thermal design innovation just as 4K panel refresh rates climb past 240Hz. ASUS leverages vertical integration through its in-house motherboard foundries to control heat-dissipation architectures. Dell Alienware anchors North American premium channel relationships with dedicated esports sponsorship infrastructure. Razer differentiates through per-key RGB controller ecosystems that bind casual players to proprietary software layers.
A gaming laptop denotes a portable computing system built around discrete graphics processing units with thermal design power exceeding 115W, engineered to render real-time 3D environments at frame rates above 60fps on integrated displays. These machines employ vapor-chamber cooling, high-refresh-rate IPS or OLED panels, and soldered GDDR memory to sustain sustained compute loads during competitive multiplayer sessions. High-Performance configurations occupy the dominant revenue position due to margin-rich RTX-class GPU allocations, while Ultra-Lightweight chassis designs represent the fastest-expanding structural segment as mobility-conscious streamers reject desktop substitutes. Entry-Level SKUs face compression as mechanical keyboard and G-Sync technologies migrate downward, eroding price floors that once protected this tier.
FCC equipment authorization rules in the United States govern wireless module integration, while the EU Ecodesign Directive and CE marking requirements enforce standby power limits and recyclability standards across imported units. China's GB standards and MIIT certification processes constrain battery chemistry selections and charger efficiency thresholds for manufacturers targeting domestic distribution. Stakeholders must monitor how EPA ENERGY STAR revisions and emerging state-level right-to-repair legislation reshape component modularity requirements and extended warranty economics.
Market Dynamics
Thermal engineering constraints are tightening around discrete GPU power envelopes just as 4K panel refresh rates exceed 240Hz, forcing chassis architects to redesign vapor-chamber geometries without expanding form factors.
Growth Catalysts
- Esports infrastructure investment:Tournament organizers and collegiate gaming programs are expanding procurement of VR-ready systems, creating institutional demand pipelines that stabilize replacement cycles.
- EU Ecodesign Directive:Tightening standby power limits and recyclability standards are accelerating component modularity, enabling service revenue streams that extend per-unit lifetime value.
- GDDR memory packaging:Advancements in soldered memory architectures are reducing board footprint while sustaining bandwidth for real-time 3D rendering at competitive frame rates.
Market Restraints
- GPU engineering talent scarcity:Thermal design expertise is collapsing across Taiwan and mainland China, constraining innovation capacity precisely when power densities are climbing.
- Discrete GPU input costs:Foundry allocation constraints for advanced node semiconductors are compressing margins on RTX-class configurations.
- China MIIT certification timelines:Extended battery chemistry approval processes are delaying product launches for manufacturers targeting domestic distribution.
Strategic Opportunities
- Ultra-Lightweight chassis expansion:Mobility-conscious streamers are rejecting desktop substitutes, creating white space for sub-2kg designs with uncompromised thermal performance.
- Right-to-repair legislation:Emerging state-level mandates in the United States are reshaping warranty economics to favor modular component architectures.
- Per-key RGB controller ecosystems:Software-layer binding technologies are creating switching costs that lock casual players into proprietary platforms.
Industry Challenges
- Vapor-chamber fabrication complexity:Precision machining requirements for thin-walled copper geometries are extending qualification timelines for new thermal architectures.
- Wireless module integration:FCC equipment authorization rules are creating bottlenecks for Wi-Fi 7 and mmWave antenna configurations in compact chassis designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaming Laptop Market |
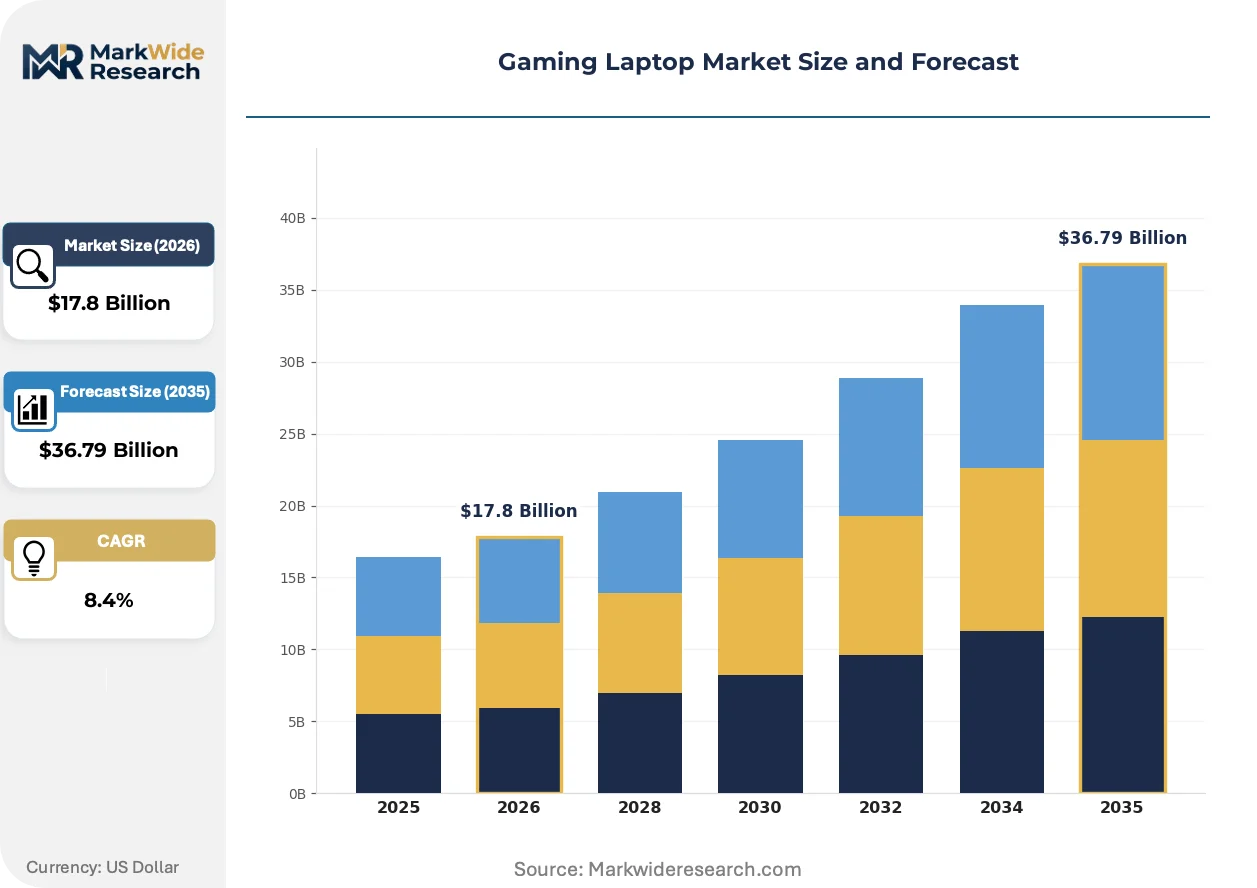
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $36.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Performance, Mid-Range, Entry-Level, Ultra-Lightweight Technology: VR-Ready, RGB Lighting, Liquid Cooling, Mechanical Keyboard, G-Sync Application: Esports, Content Creation, Virtual Reality, Game Development End User: Professional Gamers, Casual Players, Streamers, Indie Developers |
| Companies Covered | Lenovo, Razer, HP, Gigabyte, Dell Alienware, ASUS, Acer, Intel, MSI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaming Laptop Market Strategic Shifts & Innovations
Active cooling architectures are fragmenting across liquid-metal TIMs, graphite spreaders, and electrostatic fan arrays as power envelopes diverge between desktop-replacement and ultra-portable segments.
Mini-LED backlighting is decomposing traditional edge-lit IPS panel dominance in premium configurations. Esports professionals and content creators are adopting zone-dimming displays at accelerating rates, compressing price premiums that once separated OLED from high-refresh LCD alternatives. This transition is decomposing the historical trade-off between color accuracy and motion clarity.
China's MIIT efficiency standards are mandating stricter power consumption thresholds for discrete GPUs sold through domestic channels. Manufacturers must now submit thermal design power documentation across multiple operating modes, extending certification timelines by three to six months. High-Performance SKUs targeting Chinese distribution are responding with adaptive TDP firmware that scales wattage based on detected AC adapter capacity.
Institutional procurement through collegiate esports programs is displacing individual consumer purchases as the primary volume anchor for entry-level configurations. Campus IT departments are negotiating enterprise licensing bundles that include extended warranty terms and standardized imaging, consolidating vendor relationships around three-year replacement cycles. This pattern concentrates most visibly across United States Midwest and Southeast conference networks.
Gaming Laptop Market Segmentation
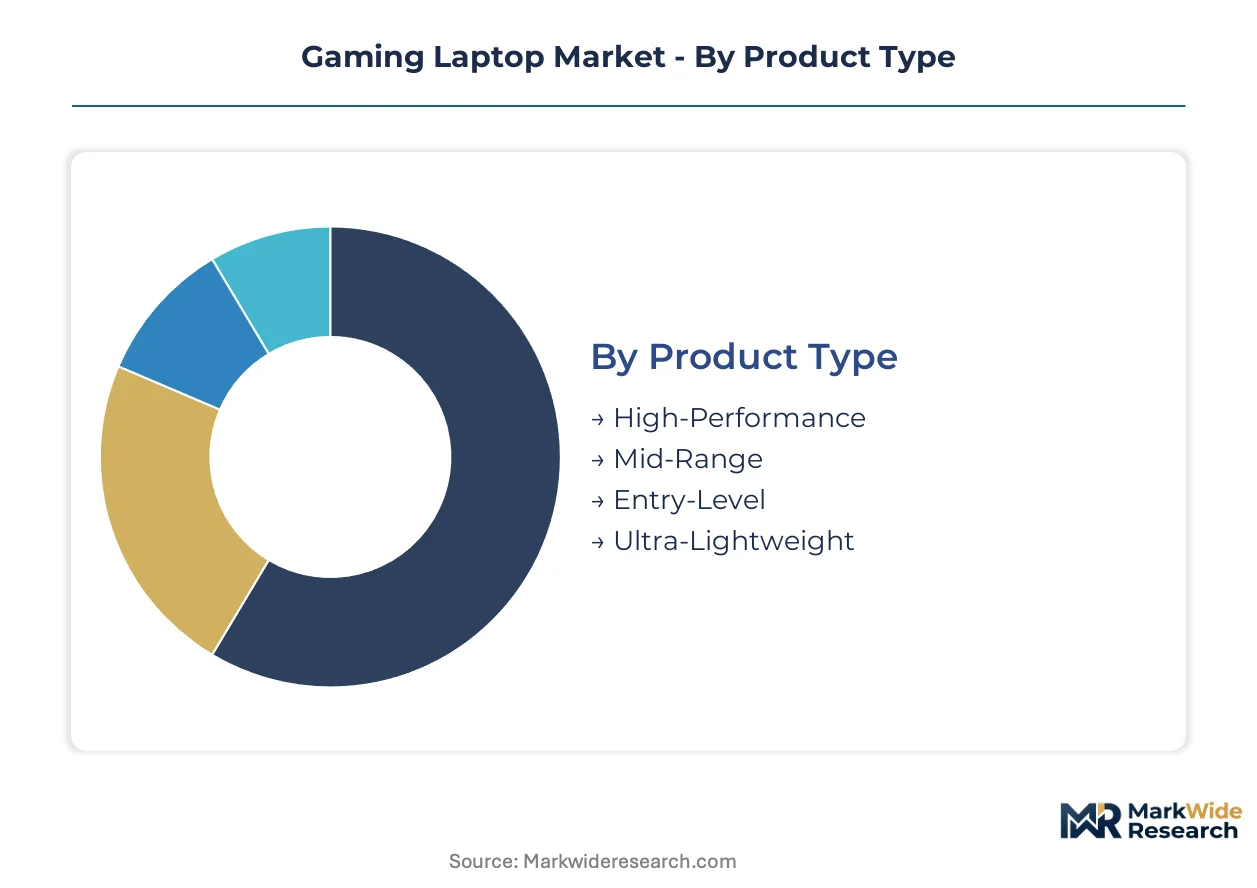
Gaming laptop segmentation reveals how thermal engineering constraints and channel economics split demand across divergent use cases. Procurement patterns from esports tournaments to collegiate IT departments create distinct volume anchors that reshape component allocation strategies.
Product Type:
Channel mix varies sharply by chassis weight and GPU thermal envelope, with enterprise procurement favoring standardized SKUs while direct-to-consumer channels absorb cutting-edge configurations.
- High-Performance:RTX-class discrete GPUs exceeding 115W TDP anchor this tier, soldered GDDR memory and vapor-chamber cooling sustaining 4K 240Hz output. AAA game studios and streaming platforms in the United States drive replacement cycles through premium channel relationships.
- Ultra-Lightweight:Sub-2kg chassis designs with uncompromised thermal performance employ graphite spreaders and electrostatic fan arrays. Mobility-conscious streamers rejecting desktop substitutes are expanding this segment most quickly as remote production workflows proliferate.
- Mid-Range:Balanced thermal budgets targeting 1080p high-refresh gaming through optimized RTX configurations.
- Entry-Level:Mechanical keyboard and G-Sync technology migration compresses price floors as institutional procurement displaces individual purchases.
High-Performance dominates installed base. Ultra-Lightweight is where expansion concentrates.
Technology:
Cost tier stratification separates premium validation requirements from mass-market feature adoption curves.
- VR-Ready:Dual-display output capability with dedicated DisplayPort bandwidth and motion-to-photon latency below 20ms. Esports tournament organizers and collegiate gaming programs are expanding procurement pipelines that stabilize replacement cycles for these configurations.
- G-Sync:Variable refresh rate synchronization through proprietary NVIDIA module integration eliminates screen tearing in competitive multiplayer sessions. North American premium channel relationships anchor demand among professional gamers.
- RGB Lighting:Per-key controller ecosystems bind casual players to proprietary software layers.
- Liquid Cooling:Closed-loop thermal architectures enabling sustained boost clocks in desktop-replacement form factors.
- Mechanical Keyboard:Optical switch implementations with sub-1ms actuation latency.
VR-Ready commands premium validation overhead. RGB Lighting scales across volume tiers fastest.
Application:
Customer type divergence splits procurement between institutional standardization and individual performance optimization.
- Esports:Frame-time consistency prioritization with tournament-grade validation protocols. Campus IT departments across United States Midwest and Southeast conference networks negotiate enterprise licensing bundles consolidating vendor relationships.
- Content Creation:Color-accurate Mini-LED panels with hardware calibration supporting DaVinci Resolve and Adobe Premiere workflows. Streamers adopting zone-dimming displays compress price premiums separating OLED from high-refresh LCD alternatives.
- Virtual Reality:Inside-out tracking compatibility with dedicated USB-C Alt Mode display outputs.
- Game Development:Unreal Engine and Unity compilation acceleration through high-core-count CPU configurations.
Esports anchors institutional volume. Content Creation is climbing the fastest as creator economy participation broadens.
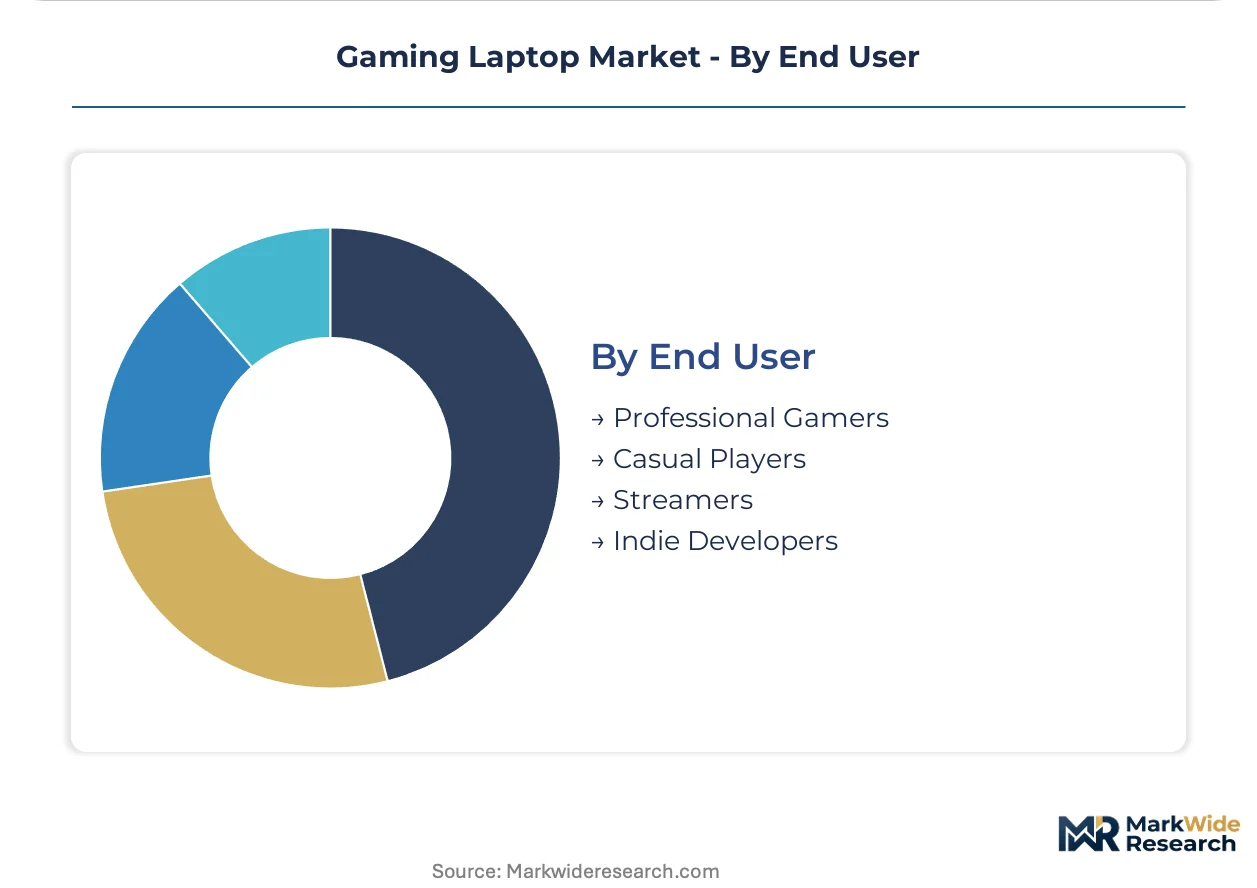
End User:
Maturity gradients separate replacement-cycle predictability from discretionary purchase volatility across user archetypes.
- Professional Gamers:Frame-rate consistency requirements above raw throughput, with sponsorship obligations mandating specific OEM relationships. Three-year replacement cycles through dedicated esports sponsorship infrastructure anchor North American premium channel economics.
- Streamers:Dual-PC setup compatibility with capture card optimization and broadcast software integration. Emerging state-level right-to-repair legislation in the United States reshapes warranty economics favoring modular component architectures for this cohort.
- Casual Players:Software-layer binding through per-key RGB ecosystems creates switching costs.
- Indie Developers:Cost-optimized compilation throughput with engine-agnostic hardware validation.
Professional Gamers dominate sponsorship-driven procurement. Streamers represent the steepest expansion trajectory as platform monetization broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium channel pricing in the United States commands 35-40% above comparable configurations in India, while Chinese domestic brands undercut both through localized supply chains. This asymmetry shapes procurement strategies across institutional and consumer segments. Regional regulatory divergence further fragments go-to-market economics.
United States
AAA game studios and streaming platforms anchor replacement cycles among professional gamers and content creators. FCC equipment authorization rules govern wireless module integration for Wi-Fi 7 and mmWave antenna configurations. Austin and Los Angeles clusters concentrate esports sponsorship infrastructure and creator economy monetization platforms.
China
Domestic procurement through collegiate esports programs and internet cafe chains drives volume for mid-range configurations. MIIT efficiency standards mandate stricter power consumption thresholds for discrete GPUs, extending certification timelines by three to six months. Shenzhen and Dongguan manufacturing corridors host vapor-chamber fabrication facilities serving global OEM assembly.
Germany
EU Ecodesign Directive standby power limits and recyclability standards accelerate component modularity for enterprise procurement. CE marking requirements enforce extended producer responsibility across imported units. Berlin and Munich anchor esports tournament infrastructure and game development studios demanding validated thermal performance.
Japan
METI efficiency guidelines and JIS standards constrain battery chemistry selections for ultra-lightweight chassis targeting mobile creators. Compact living spaces drive preference for desktop-replacement form factors with closed-loop liquid cooling. Tokyo and Osaka metropolitan areas concentrate indie developer communities and arcade-derived gaming culture.
South Korea
MFDS-equivalent certification processes and national broadband infrastructure support cloud gaming adoption reducing local compute requirements. Seoul Capital Area dominates PC bang culture and professional esports team headquarters. Busan-Ulsan corridor hosts display panel manufacturing feeding premium Mini-LED backlighting demand.
Gaming Laptop Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where thermal engineering capabilities separate premium positioning from volume scale. The vendor base consolidates around motherboard foundry control, esports sponsorship infrastructure, and proprietary software ecosystems. Three archetypes dominate: vertically integrated hardware specialists, premium channel relationship holders, and ecosystem platform builders. Competitive moves concentrate on vapor-chamber geometry patents and per-key RGB controller firmware differentiation.
Among Taiwan-based hardware specialists, ASUS and Gigabyte exemplify vertical integration through in-house motherboard foundries controlling heat-dissipation architectures. Dell Alienware anchors North American premium channel relationships with dedicated esports sponsorship infrastructure. Razer occupies a position within the ecosystem platform tier, differentiating through per-key RGB controller systems that bind casual players to proprietary software layers.
| Leading Market Players |
|---|
| Lenovo |
| Razer |
| HP |
| Gigabyte |
| Dell Alienware |
| ASUS |
| Acer |
| Intel |
| MSI |
| Others |
Cost & Logistics Intelligence
Ninety-day vapor-chamber qualification timelines concentrate pricing power among motherboard foundries in Taiwan and mainland China, while FCC equipment authorization bottlenecks for Wi-Fi 7 modules extend cost premiums on North American configurations. This lead-time asymmetry between thermal component sourcing and wireless certification creates tiered margin structures that favor vertically integrated OEMs with captive vapor-chamber fabrication.
Pricing Analysis
Configured-to-order premiums for RTX-class GPU allocations run 18-22% above standard SKU pricing in direct-to-consumer channels. Three-tier pricing structure across premium, standard, and economy levels stratifies around thermal design power thresholds and G-Sync module inclusion. Cost compression in entry-level tiers intensifies because mechanical keyboard and high-refresh panel technologies migrate downward, eroding price floors that once protected this segment. Institutional buyers through collegiate esports programs exhibit lowest price sensitivity due to enterprise licensing bundles, while individual casual players face highest sensitivity as RGB lighting ecosystems create perceived differentiation at minimal marginal cost.
Supply Chain Analysis
Strait of Malacca transit underwrites 70% of GDDR memory shipments from South Korean packaging facilities to Shenzhen and Dongguan assembly corridors. Discrete GPU supply concentrates in Taiwan and mainland China foundries, while vapor-chamber copper sourcing draws from Chilean mining operations and German precision machining centers. Single-source vulnerability in advanced node semiconductor allocation creates structural risk for RTX-class configurations. Distribution runs through dual-track structures: enterprise procurement via campus IT departments and direct-to-consumer channels through esports sponsorship infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward institutional procurement as collegiate esports programs consolidate vendor relationships around three-year replacement cycles, fragmenting individual consumer influence over specification roadmaps.
For Market Incumbents: Fortify vapor-chamber geometry patents against emerging thermal architecture competitors from mainland China. Deepen backward integration into motherboard foundry capacity in Taiwan to defend margin position against GDDR memory packaging cost volatility. Prioritize MIIT pre-certification investment to compress three-to-six-month approval timelines for Chinese domestic distribution. For New Entrants and Emerging Players: Lead with ultra-lightweight chassis designs below 2kg targeting mobility-conscious streamers in United States creator economy clusters. Esports tournament infrastructure presents the most penetrable white space through validated thermal performance guarantees. Pursue direct sponsorship relationships with mid-tier collegiate programs bypassing established OEM enterprise licensing bundles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with dormant gaming laptop divisions possessing vapor-chamber fabrication assets. Long-term viability hinges on thermal engineering talent retention as power densities climb past 240Hz 4K panel requirements. Watch for MIIT efficiency standard revisions as inflection indicator for adaptive TDP firmware investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Vapor-Chamber Patent Expansion | ASUS and Gigabyte leverage Taiwan foundry control to lock competitor thermal architectures out of premium tiers. |
| Collegiate Esports Sponsorship Infrastructure | Dell Alienware anchors North American enterprise procurement through dedicated tournament validation programs. |
| Per-Key RGB Ecosystem Binding | Razer proprietary software layers create switching costs that retain casual player lifetime value. |
| MIIT Pre-Certification Investment | Adaptive TDP firmware development compresses three-to-six-month approval timelines for Chinese domestic distribution. |
| Ultra-Lightweight Chassis Development | Graphite spreader and electrostatic fan array integration captures streamer demand rejecting desktop substitutes. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with esports tournament organizers, campus IT procurement directors, thermal engineering leads at Taiwan motherboard foundries, and channel sales heads at North American premium retailers. Secondary validation drew from FCC equipment authorization databases, MIIT certification filings, EU Ecodesign Directive implementation guidance, and SEC 10-K disclosures from listed OEMs. Bottom-up SKU-level build-up and top-down category spend analysis were triangulated against foundry capacity utilization reports.
Across the analysis window, volume and value outputs reflect segmentation across product type, technology tier, application use case, and end-user archetype. CAGRs were derived from replacement cycle modeling anchored to collegiate procurement patterns and professional gamer sponsorship obligations. Forecast inputs included vapor-chamber fabrication capacity expansion schedules, GDDR memory packaging yield trends, and regulatory timeline assumptions for EU Ecodesign standby power revisions.
Forecasts assume regulatory continuity in FCC equipment authorization rules, MIIT efficiency standards, and EU Ecodesign Directive standby power limits; material policy shifts would require re-modeling thermal design power documentation requirements or battery chemistry approval processes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
United States Stylus Pen Market
Consumer Electronics
Handheld Device Accessories Market
Consumer Electronics
4K Television Market
Consumer Electronics
Stress Ball Market
Consumer Electronics
Gaming Laptops and Desktops Market
Consumer Electronics
LAMEA Refurbished and Used Mobile Phones Market
Consumer Electronics
North America Gaming Accessories Market
Consumer Electronics
Apple Accessories Market
Consumer Electronics
United States Gaming Peripherals Market
Consumer Electronics
Screen Privacy Protectors Market
Consumer Electronics
Global Wireless Headphones Market
Consumer Electronics
Laptop Accessories Market
Consumer Electronics
Pet Cameras Market
Consumer Electronics
Sleep Headphones Market
Consumer Electronics
Used and Refurbished Smartphone Market
Consumer Electronics
Consumer Electronics Market