
 Portable Sandwich Maker Market | 2026-2036
Portable Sandwich Maker Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Sandwich Maker Market Analytics
Aluminum die-cast heating plates is consolidating as the dominant thermal core in mid-tier electric units, displacing older stamped-steel assemblies that suffered from uneven heat distribution. Breville Group Limited leverages its Sydney-based R&D center to sustain premium positioning through patented element geometries. Hamilton Beach Brands Inc anchors North American mass-market volume through deep retail partnerships with big-box chains. DeLonghi Appliances S.r.l. differentiates via European design credentials and multi-function feature sets that span sandwich pressing, grilling, and waffle plates.
A portable sandwich maker is a compact, thermostatically controlled appliance that applies simultaneous heat and pressure to bread and fillings, typically operating between 700 and 1,500 watts with non-stick coated aluminum or ceramic cooking surfaces to enable rapid food preparation and easy cleaning. Electric variants dominate commercial channels where food trucks require consistent output and fast recovery times, while manual and stovetop categories retain niche positions among outdoor enthusiasts and off-grid users. Stainless steel housings command margin premiums in European markets where durability signaling matters, whereas plastic-bodied units compete aggressively on entry-level price points in developing economies. Home cooks represent the largest volume pool, though cafes and mobile food vendors generate higher per-unit revenue through commercial-grade specifications and warranty terms.
FDA food-contact substance regulations govern non-stick coating approvals for US-bound products, while REACH compliance in Europe restricts perfluorinated compound formulations in cooking surfaces. The EU Ecodesign Directive and associated energy labeling rules are tightening standby power limits, forcing redesigns of control circuits and heating element duty cycles. China's GB standards for household electrical appliances set baseline safety and electromagnetic compatibility thresholds for manufacturing origin. Stakeholders must monitor how fragmented national efficiency regimes reshape component sourcing and whether ceramic coating technologies achieve cost parity with legacy PTFE formulations before the next product refresh cycle.
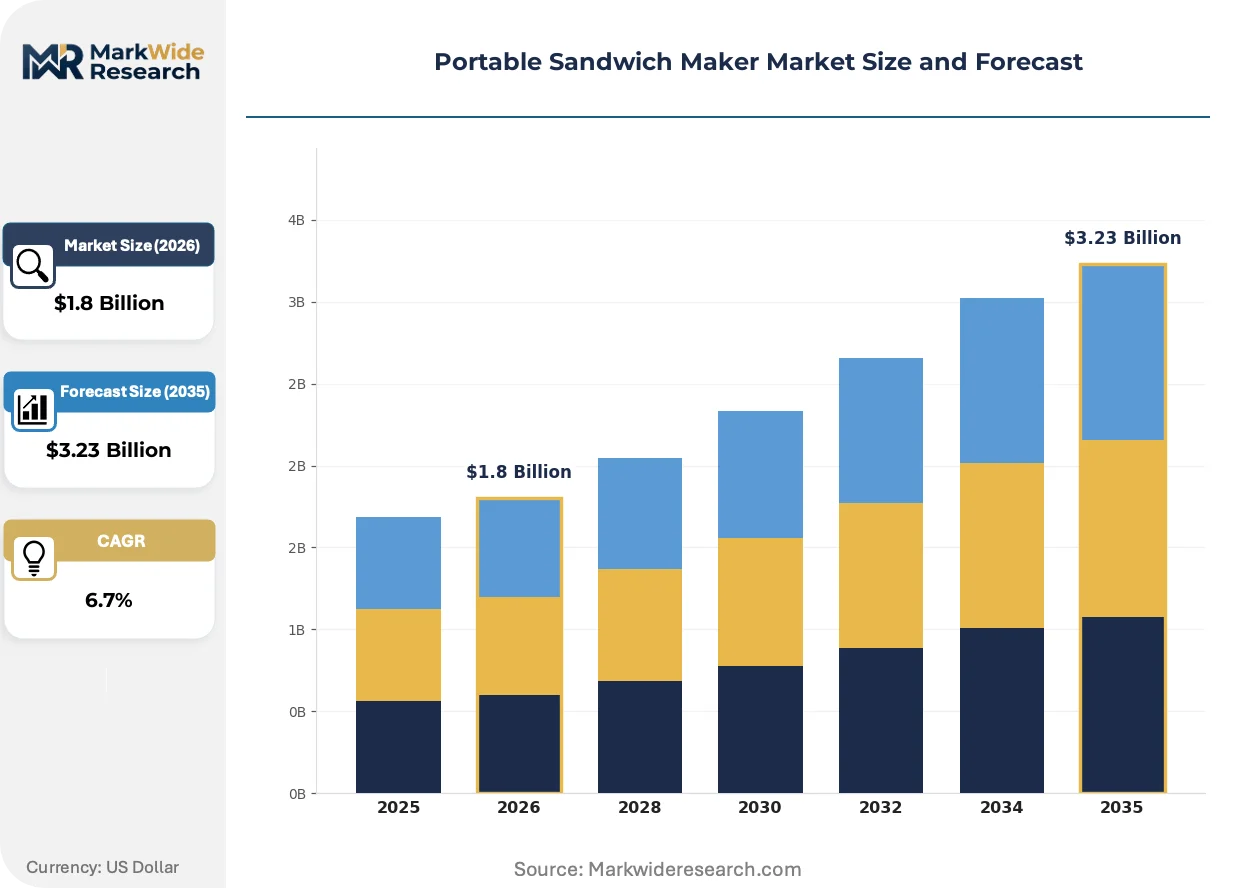
Market Dynamics
The portable sandwich maker market is consolidating around aluminum die-cast heating plates as food trucks and mobile catering operators demand faster thermal recovery and even heat distribution for high-volume service cycles.
Growth Catalysts
- EU Ecodesign Directive:Tightening standby power limits are accelerating redesigns of control circuits and heating element duty cycles, forcing manufacturers toward more efficient thermal cores.
- Street food culture in Germany:Commercial kitchen refurbishment cycles and replacement purchases are concentrating demand for compact electric models among mobile food vendors.
- Ceramic coating technologies:Advancements in non-stick surfaces are displacing legacy PTFE formulations as REACH compliance in Europe restricts perfluorinated compound usage.
Market Restraints
- Input cost volatility:Aluminum pricing fluctuations directly compress margins on die-cast heating plate production, squeezing mid-tier manufacturers.
- Supply concentration risk:Non-stick coating supply chains cluster in East Asian chemical processing hubs, creating exposure to trade friction and logistics disruption.
- Substitution threat:Multi-function countertop appliances with interchangeable plates threaten dedicated sandwich maker volume in residential kitchens.
Strategic Opportunities
- Food truck electrification in France:Municipal bans on diesel generators in Paris and Lyon are creating pull for battery-compatible low-wattage sandwich press models.
- Modular plate systems:Interchangeable grill, waffle, and sandwich configurations are opening premium price tiers among café operators seeking equipment flexibility.
- FDA food-contact substance pathways:Streamlined approval processes for ceramic coatings are enabling faster US market entry for European manufacturers.
Industry Challenges
- Electromagnetic compatibility certification:China's GB standards for household electrical appliances impose lengthy testing timelines that delay product launches.
- Thermal engineering talent scarcity:Specialized expertise in rapid-recovery heating element design concentrates among legacy appliance engineers nearing retirement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Sandwich Maker Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Manual, Microwave, Stovetop Material: Stainless Steel, Non-Stick Coating, Plastic, Cast Iron End User: Home Cooks, Restaurants, Food Trucks, Cafes Feature: Compact Design, Multi-Function, Fast Heating, Easy Clean |
| Companies Covered | Hamilton Beach Brands Inc, Black & Decker Corporation, Breville Group Limited, Cuisinart, Tefal, Philips, Russell Hobbs, Morphy Richards, DeLonghi Appliances S.r.l., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Sandwich Maker Market Evolving Landscape
Product development is pivoting toward modularity and energy efficiency as regulatory pressure and operator economics reshape equipment specifications across commercial and residential channels.
Aluminum die-cast heating plates deliver superior thermal mass and uniform surface temperatures compared to stamped-steel predecessors. Food trucks in high-turnover markets are adopting these units to minimize recovery lag between orders. The technology is integrating control electronics that modulate power draw based on load sensors, compressing energy consumption without sacrificing output speed.
REACH compliance in Europe is restricting perfluorinated compound formulations in cooking surfaces, forcing coating suppliers to accelerate ceramic and sol-gel alternatives. Manufacturers serving EU markets must reformulate non-stick layers and revalidate food-contact approvals. Residential product lines face the tightest reformulation timelines as consumer safety scrutiny intensifies.
Mobile catering operators are unbundling equipment procurement from traditional restaurant supply distributors, sourcing directly through manufacturer portals and industry-specific e-commerce platforms. This channel compression is fragmenting buyer power and enabling smaller brands to access commercial accounts previously locked behind distributor relationships. Germany and the Netherlands show the most advanced disintermediation among European food service equipment categories.
Portable Sandwich Maker Market Segmentation
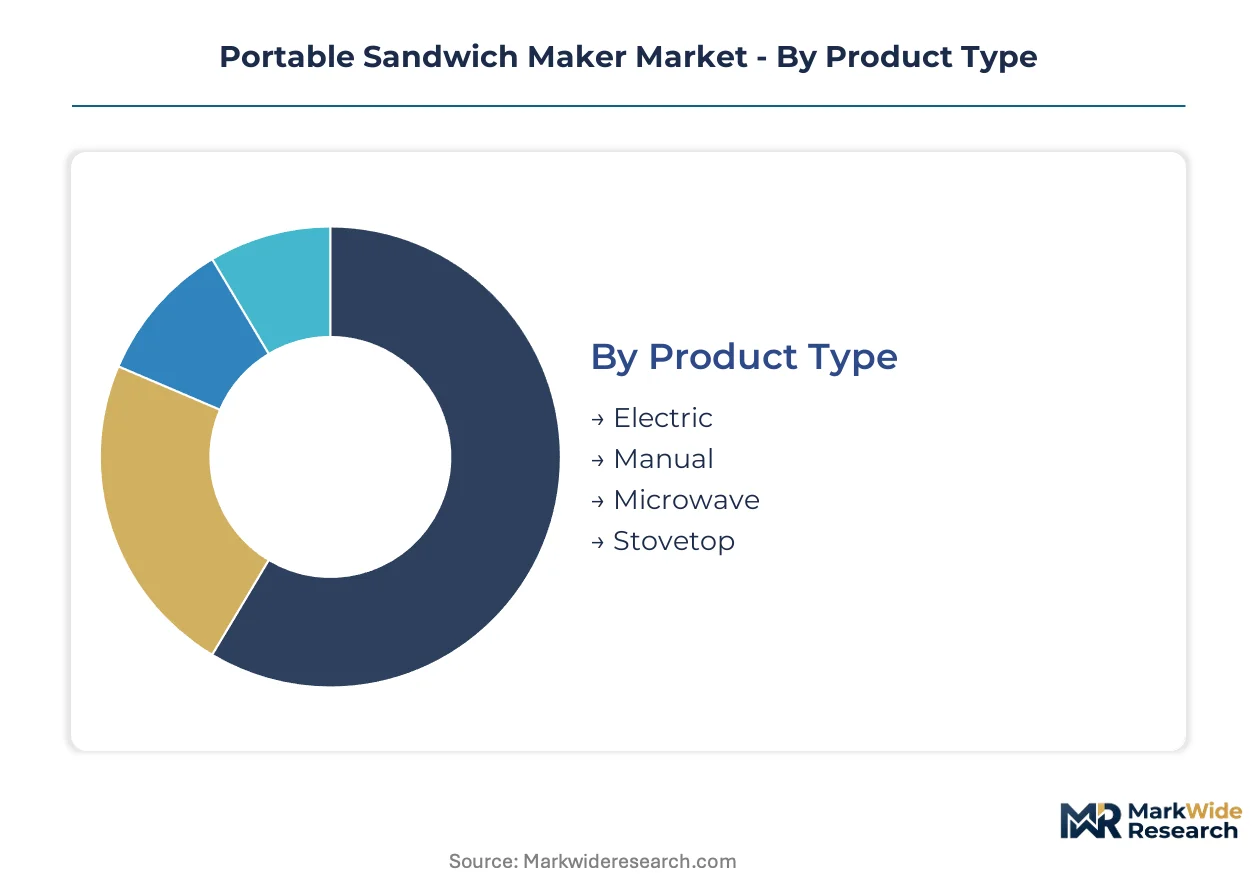
Portable sandwich maker purchasing patterns diverge sharply across power source, construction material, and operational intensity. Understanding these fault lines reveals where margin pools concentrate and which specifications command price premiums in commercial versus residential channels.
Product Type:
Power source and thermal control sophistication separate buyers by throughput requirements and infrastructure access.
- Electric:Thermostatically controlled units operating between 700 and 1,500 watts dominate food truck and café procurement in Germany where consistent output and rapid recovery times justify higher capital outlay. EU Ecodesign Directive standby power limits are forcing control circuit redesigns that favor premium manufacturers with dedicated thermal engineering capabilities.
- Manual:Hand-pressed or clamp-style units requiring external heat sources retain strong positioning among outdoor enthusiasts and off-grid users in rural France and Alpine regions where electrical infrastructure is unreliable or prohibited. These buyers prioritize portability and field durability over speed.
- Microwave:Single-use or collapsible designs target dormitory and office pantry environments with minimal storage space.
- Stovetop:Cast-aluminum or steel press plates appeal to home cooks seeking multi-purpose cookware without dedicated appliance investment.
Electric units lead volumes today; manual designs are gaining share fastest among specialty outdoor retailers.
Material:
Construction substrate signals durability expectations and determines thermal performance characteristics that buyers weight differently by use intensity.
- Stainless Steel:Brushed or polished housings command margin premiums across European markets where longevity signaling matters to commercial operators and design-conscious residential buyers. German café chains specify grade 304 enclosures for front-of-house visibility.
- Non-Stick Coating:PTFE and emerging ceramic formulations on aluminum or steel cooking surfaces enable rapid food release and reduced oil usage. REACH compliance in Europe is accelerating ceramic adoption as ECHA restrictions on perfluorinated compounds tighten formulation options for EU-bound production.
- Plastic:Polypropylene and ABS housings compete aggressively on entry-level price points in developing economies and student housing markets.
- Cast Iron:Pre-seasoned or enameled plates serve slow-food enthusiasts and traditional cooking method adherents seeking heat retention over speed.
Non-stick coated surfaces lead volumes today; stainless steel enclosures are climbing the fastest among premium commercial specifications.
End User:
Operational scale and equipment utilization rates create distinct procurement behaviors across residential and commercial buyer classes.
- Home Cooks:Casual residential users represent the largest volume pool but generate lower per-unit revenue through price-sensitive purchasing and minimal warranty utilization. Weekend meal preparation and occasional entertaining drive replacement cycles.
- Restaurants:Fixed-location food service operations demand commercial-grade specifications with extended warranty terms and rapid parts availability. Kitchen refurbishment cycles in Germany's independent restaurant sector concentrate replacement demand.
- Food Trucks:Mobile operators prioritize compact footprints, rapid thermal recovery, and compatibility with generator or battery power systems. Municipal diesel bans in Paris and Lyon are creating pull for low-wattage models.
- Cafes:Counter-service establishments seek equipment flexibility through modular plate systems that switch between sandwich pressing, grilling, and waffle configurations.
Home cooks lead volumes today; food trucks are expanding most quickly as street food culture formalizes across European capitals.
Feature:
Design priorities reflect space constraints, operational efficiency targets, and labor cost pressures that vary by end-use environment.
- Compact Design:Footprint-minimized units with vertical storage capability address space-constrained urban kitchens and mobile operations where every centimeter of counter space carries opportunity cost.
- Multi-Function:Interchangeable plate systems enabling sandwich pressing, grilling, and waffle preparation open premium price tiers among café operators seeking equipment flexibility. This feature set threatens dedicated single-purpose unit volume in residential settings.
- Fast Heating:Rapid-recovery aluminum die-cast plates minimize lag between orders in high-turnover commercial environments.
- Easy Clean:Removable dishwasher-safe plates and drip trays reduce labor input for commercial operators facing tight staffing.
Compact design leads volumes today; multi-function configurations are gaining share fastest among commercial buyers consolidating equipment footprints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's street food infrastructure anchors European demand for portable sandwich makers, with mobile catering operators driving replacement cycles and commercial kitchen refurbishment activity across the continent.
Germany
Mobile food vendors in Berlin and Hamburg concentrate procurement of compact electric units with rapid thermal recovery. The EU Ecodesign Directive mandates standby power limits below one watt, forcing control circuit redesigns among manufacturers serving this market. Bavaria's commercial kitchen equipment distributors report shortened replacement cycles as food truck electrification accelerates.
France
Municipal diesel generator bans in Paris and Lyon create demand for battery-compatible low-wattage sandwich press models among mobile operators. ANSM and CNIL oversight extends to food-contact surface compliance for commercial equipment. The Rhône-Alpes region hosts emerging assembly operations targeting French café chains seeking modular plate configurations.
United States
Food truck operators in Austin, Texas and Portland, Oregon prioritize commercial-grade specifications with extended warranty terms. FDA food-contact substance regulations govern non-stick coating approvals, creating compliance timelines that favor established suppliers. The Pacific Northwest shows concentration of outdoor enthusiast demand for manual stovetop variants.
China
Manufacturing origin for aluminum die-cast heating plate components clusters in Guangdong and Zhejiang provinces. GB standards for household electrical appliances impose electromagnetic compatibility certification timelines that delay product launches. Yangtze River Delta assembly plants serve both domestic price-sensitive residential buyers and export markets.
United Kingdom
London's café density supports premium positioning for stainless steel housings with front-of-house visibility. REACH compliance through ECHA restricts perfluorinated compound formulations in cooking surfaces, accelerating ceramic coating adoption. Midlands-based distributors consolidate procurement for independent restaurant refurbishment cycles.
Portable Sandwich Maker Market Competitive Landscape
Global majors compete with regional champions across thermal engineering capabilities and distribution reach, producing a tiered structure where premium positioning separates from mass-market volume plays. Appliance conglomerates with multi-category portfolios anchor the upper tier through design credentials and patent estates. Mid-tier specialists concentrate on food service channel relationships and rapid product refresh cycles. Competitive moves center on modular plate system development and direct-to-operator e-commerce channel compression.
Among Sydney-based premium appliance developers, Breville Group Limited occupies a position exemplifying design-led thermal engineering archetypes. Hamilton Beach Brands Inc represents North American mass-market volume strategies anchored in retail partnership depth. DeLonghi Appliances S.r.l. sits within the European design-centric tier, occupying a position that reflects multi-function feature set differentiation. These three entities collectively illustrate how geographic origin and corporate structure map to distinct competitive positioning vectors in this equipment category.
| Leading Market Players |
|---|
| Hamilton Beach Brands Inc |
| Black & Decker Corporation |
| Breville Group Limited |
| Cuisinart |
| Tefal |
| Philips |
| Russell Hobbs |
| Morphy Richards |
| DeLonghi Appliances S.r.l. |
| Others |
Value Network & Pricing Analysis
Performance-grade certification gaps between EU Ecodesign-compliant units and baseline imports bifurcate the portable sandwich maker landscape into premium thermal engineering and commodity assembly tiers, with pricing power accumulating among manufacturers who internalize aluminum die-cast plate production while margin compression punishes coating-dependent assemblers exposed to REACH reformulation costs.
Pricing Analysis
Aluminum ingot cost pass-through dominates pricing dynamics across die-cast heating plate tiers, with premium manufacturers absorbing volatility through captive foundry operations while mid-tier brands face margin erosion. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—EU Ecodesign compliance commands hardware redesign premiums, plastic-bodied economy units compete on landed cost in developing markets. Pricing pressure stems from ceramic coating qualification delays as REACH restrictions force PTFE phase-outs before cost parity. Food truck operators show lowest price sensitivity due to throughput recovery requirements; residential buyers in student housing segments drive aggressive commodity sourcing.
Supply Chain Analysis
Container freight rate normalization has compressed landed cost spreads between Guangdong assembly clusters and European distribution hubs, reshaping procurement calculus for German food service distributors. Manufacturing gravity centers on China for aluminum die-cast plates, non-stick coating formulation, and control circuit assembly; Italy retains niche stainless steel enclosure fabrication. Raw material dependencies span aluminum ingot, ceramic sol-gel precursors, and thermistor control components. Single-source vulnerability concentrates in East Asian chemical processing for REACH-compliant ceramic coatings. Distribution runs through commercial kitchen equipment distributors in Germany and France, with direct-to-operator portals gaining share among mobile catering accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The portable sandwich maker market functions as a regulatory compounder where EU Ecodesign standby power limits below one watt force hardware redesigns that concentrate margin pools among thermal engineering specialists.
For Market Incumbents: Anticipate ceramic coating supply rationing as REACH enforcement tightens by qualifying secondary sol-gel suppliers and accelerating in-house formulation development. Defensive consolidation should prioritize backward integration into aluminum die-cast plate production to escape commodity margin cycles, while channel control investments in direct-to-food-truck portals lock mobile operator relationships ahead of distributor disintermediation. For New Entrants and Emerging Players: Begin with battery-compatible low-wattage specifications targeting French municipal diesel bans in Paris and Lyon, where incumbent portfolios lack compliant models. Modular plate system white space among café operators seeking grill-waffle-swap flexibility offers the most penetrable entry point; go-to-market should route through industry-specific e-commerce platforms rather than traditional equipment distributors to bypass established gatekeeper relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where thermal engineering talent scarcity intersects with REACH-driven coating reformulation mandates, favoring acquisition of mid-tier specialists with qualified ceramic supply chains and EU regulatory dossiers. Long-term viability frames around equipment-as-a-service transitions in commercial channels. The signal to watch is food truck electrification subsidy announcements in European capitals, which would inflect battery-compatible model demand and reshape manufacturer order books.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Qualification | REACH-compliant formulations from ECHA-registered suppliers unlock EU market access ahead of PTFE phase-outs. |
| Modular Plate System Launch | Interchangeable grill-waffle configurations capture café operator consolidation demand in Germany and France. |
| Direct-to-Operator Portal | Manufacturer e-commerce bypasses distributor markups for mobile catering accounts in Netherlands and UK. |
| Die-Cast Plate Backward Integration | Captive aluminum foundry operations insulate margin from London Metal Exchange volatility. |
| Battery-Compatible Low-Wattage Line | Paris and Lyon diesel generator bans create first-mover positioning among municipal-compliant equipment. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary conversations with food truck operators, commercial kitchen equipment distributors, thermal engineering specialists, and coating formulation chemists with secondary validation against EU Ecodesign implementation guidance, ECHA REACH restriction timelines, FDA food-contact substance databases, and China GB standard certification records. Bottom-up demand modeling from end-user procurement patterns triangulated against top-down manufacturer shipment estimates across power source, material, and end-use segments.
Comparable historical reference periods anchored volume and value projections across the analysis window, with segmentation modeling spanning electric-manual-microwave-stovetop power categories, stainless steel-plastic-cast iron construction materials, and home cook-restaurant-food truck-café buyer archetypes. CAGRs derived from weighted average of replacement cycle analysis, refurbishment spend patterns, and regulatory-driven upgrade elasticity. Industry-specific forecast inputs incorporated aluminum price trajectory assumptions and ceramic coating cost-down curves.
Caveats apply where Ecodesign standby power limit enforcement delays or ceramic coating qualification failures could materially shift the outlook toward extended PTFE reliance or stranded inventory positions. Forecasts embed assumptions regarding food truck electrification policy continuity and REACH restriction implementation timelines. A model refresh is warranted upon material change in EU energy efficiency regulatory stringency or aluminum supply chain disruption events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Garlic Press Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market
Kitchen Appliances
Brazil Kitchen Appliances Market
Kitchen Appliances
Middle East Electric Vegetable Chopper Market
Kitchen Appliances
Mixers and Attachments Market
Kitchen Appliances
Commercial Countertop Ranges Market
Kitchen Appliances
Mexico Kitchen Appliances Products Market
Kitchen Appliances
United States Electric Vegetable Choppers Market
Kitchen Appliances
Smart Kitchen Faucet Market
Kitchen Appliances
Capsule Coffee Machines Market
Kitchen Appliances
Poland Household Electric Grills Market
Kitchen Appliances
Sweden Kitchen Appliances Market
Kitchen Appliances
Smart Kettle Market
Kitchen Appliances
Smart Kitchen System Market
Kitchen Appliances
Commercial Induction Cooktops Market
Kitchen Appliances
Pressure Cooker Market