
 Private Label Cosmetics Manufacturing Service Market | 2026-2036
Private Label Cosmetics Manufacturing Service Market Size, Share, and Industry Trends Forecast 2026-2036
Private Label Cosmetics Manufacturing Service Market Insights
The shift from in-house production to outsourced multi-source manufacturing is recalibrating how beauty brands build supply resilience. Intercos leverages its integrated R&D and manufacturing footprint across Europe and Asia to serve premium private label clients. Fareva Group anchors its competitiveness through pharmaceutical-grade GMP facilities that attract clean beauty entrants seeking compliant production pathways.
Private label cosmetics manufacturing service encompasses third-party formulation, production, and packaging of beauty products sold under a retailer's or brand's own trademark, typically involving emulsion chemistry, preservative systems, and stability testing to ensure shelf-ready performance. The skin care category dominates contract manufacturing volumes due to complex active ingredient handling and longer development cycles that lock in multi-year partnerships. Hair care competes on scale economics as shampoo and conditioner formats standardize around bulk liquid filling, while makeup specializes in pigment dispersion technology and compact pressing where smaller batch flexibility commands premium positioning.
FDA oversight under MoCRA mandates facility registration, serious adverse event reporting, and good manufacturing practice adherence for all cosmetics marketed in the United States, elevating compliance costs for smaller contract manufacturers. The EU Cosmetics Regulation enforces safety assessments through designated responsible persons and restricts specific substances via annexed prohibitions, shaping formulation choices across export-oriented production hubs. REACH compliance for chemical substances and emerging state-level fragrance disclosure laws in California and New York add layered regulatory complexity. Stakeholders must monitor evolving ingredient blacklist expansions and traceability mandates as the primary variables determining manufacturing partner selection and geographic sourcing strategy.
Market Dynamics
Direct-to-consumer beauty brands are abandoning captive manufacturing facilities in favor of outsourced multi-source production networks, compressing development timelines from 18 months to under 6 months while fragmenting supplier relationships across specialized formulators, packagers, and fulfillment operators.
Growth Catalysts
- MoCRA facility registration mandates:FDA's expanded oversight under the Modernization of Cosmetics Regulation Act forces smaller brands toward established contract manufacturers with pre-validated GMP infrastructure, accelerating outsourcing velocity.
- K-beauty export networks:South Korean private label clusters in Gyeonggi-do and Incheon supply formulation expertise to North American and Southeast Asian brands seeking proven emulsion technologies.
- Clean beauty certification pipelines:EWG Verified and COSMOS-standard formulation services attract brands targeting ingredient-conscious consumers through pre-approved raw material libraries.
Market Restraints
- Active ingredient cost volatility:Niacinamide, retinol derivatives, and peptide complexes face price swings tied to Chinese fine chemical production curbs and energy input fluctuations.
- Single-source packaging dependency:Airless pump and mono-material tube suppliers concentrate in Zhejiang province, creating vulnerability to regional logistics disruptions or trade policy shifts.
- Preservative system limitations:EU Annex V restrictions on parabens and formaldehyde releasers constrain formulation options, forcing expensive natural alternative validation.
Strategic Opportunities
- Indian domestic brand emergence:PLI scheme incentives for local manufacturing attract contract manufacturers to serve DTC brands in Mumbai, Bangalore, and Delhi-NCR with import-substituted production.
- Refillable and concentrated formats:Waterless shampoo bars and dissolvable sheet masks reduce shipping volumes, enabling manufacturers to capture value through formulation innovation rather than commodity filling.
- California fragrance disclosure laws:Senate Bill 312 mandates ingredient transparency for fragrance allergens, creating demand for compliant reformulation services among brands selling into the state's retail channels.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise in encapsulation technology and microbiome-compatible preservation commands premium compensation, constraining mid-tier manufacturer expansion.
- Stability testing backlog:Accelerated aging studies and preservative efficacy testing create 12-16 week queue times at third-party laboratories, delaying product launches.
- ERP integration with brand systems:Real-time inventory visibility and lot traceability requirements force contract manufacturers to replace legacy MRP platforms, absorbing 18-24 month implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Private Label Cosmetics Manufacturing Service Market |
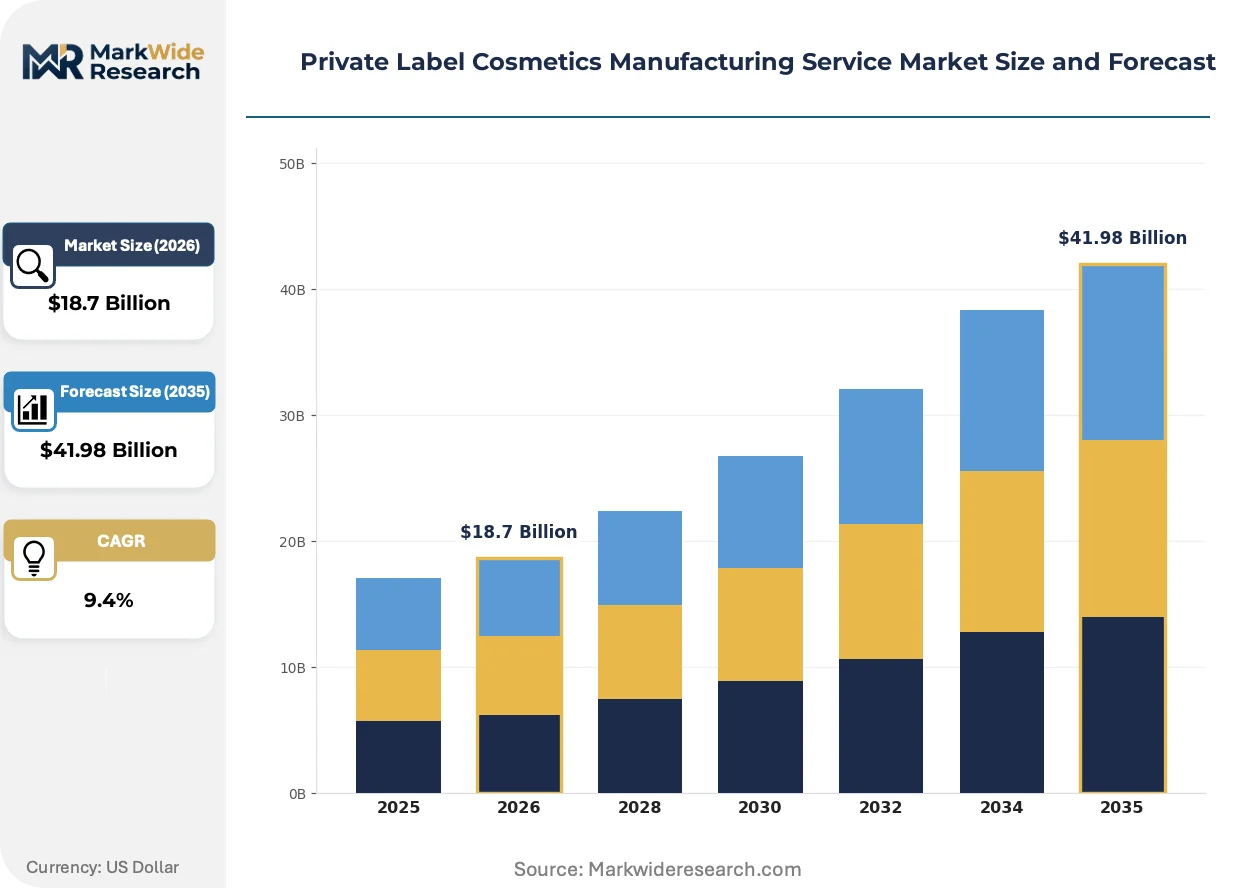
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Care, Makeup, Hair Care, Fragrance Packaging Type: Tubes, Jars, Bottles, Pumps Sales Channel: Online Retailers, Specialty Stores, Supermarkets, Distributors End User: Individuals, Salons, Retailers, Wholesalers |
| Companies Covered | Intercos, Fareva Group, Kolmar Laboratories, COSMECO, Cosmewax, HSA Cosmetics SpA, Skinlys, Bo International, Columbia Cosmetics Manufacturing Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Private Label Cosmetics Manufacturing Service Market Trends and Innovations
Biotechnology-derived actives and AI-assisted formulation platforms are compressing the traditional R&D-to-market pathway, while regulatory fragmentation across North America, Europe, and Asia-Pacific forces manufacturers to maintain parallel compliance infrastructures.
Encapsulation technology using lipid nanoparticles and cyclodextrin complexes is consolidating active ingredient stability and bioavailability into standardized delivery systems. Premium skin care brands adopt these platforms for retinol and vitamin C formats to minimize oxidation degradation. The technology is consolidating multiple formulation steps into single-supplier relationships, reducing brand-side technical staffing requirements.
REACH Annex XVII expansions and the EU Deforestation Regulation are tightening traceability mandates for palm-derived emollients and shea butter supply chains. Manufacturers must now document farm-level sourcing through mass-balance certification or segregated supply chains. Color cosmetics and body care categories face the steepest compliance cost increases due to complex botanical ingredient portfolios.
Subscription-box and social-commerce brands now specify 500-unit minimum order quantities with 4-week turnaround requirements, displacing traditional 10,000-unit production runs. Micro-batch manufacturing lines with rapid changeover capability command 40-60% price premiums over standard filling operations. This pattern concentrates most acutely among Gen Z-targeted brands launching through TikTok Shop and Instagram-native storefronts.
Private Label Cosmetics Manufacturing Service Market Segmentation
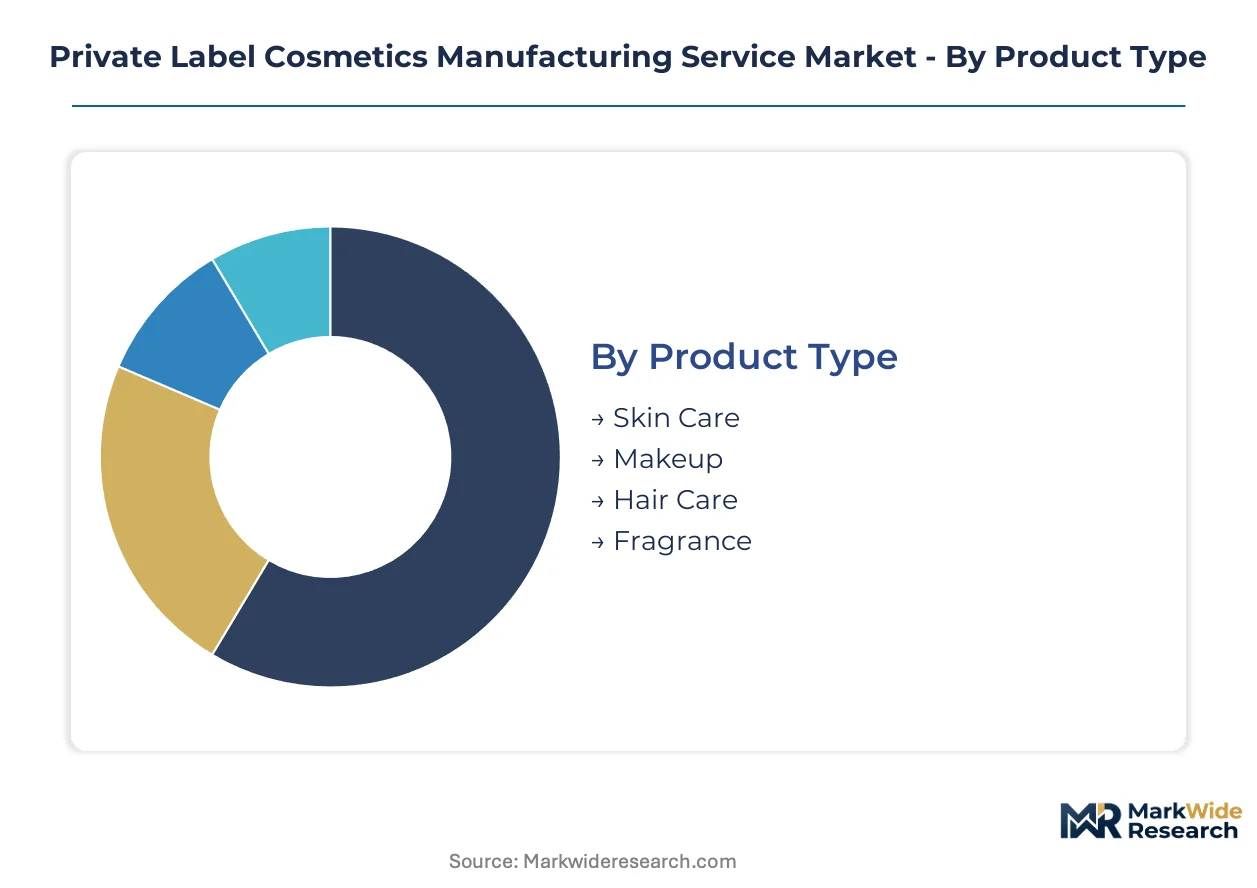
Segmentation in private label cosmetics manufacturing reveals how regulatory burden, formulation complexity, and packaging technology concentrate margin capture across distinct service tiers. Manufacturers align facility certifications and equipment configurations to specific segment demands, creating specialization barriers that reshape competitive dynamics.
Product Type:
Skin care and makeup segments carry the heaviest certification loads under FDA MoCRA facility registration and EU Cosmetics Regulation safety substantiation requirements, while hair care and fragrance face distinct preservative and allergen disclosure mandates.
- Skin Care:Emulsion chemistry and active ingredient encapsulation dominate formulation complexity, with retinol, vitamin C, and peptide handling requiring pharmaceutical-grade GMP infrastructure. Demand clusters in South Korean export networks and North American clean beauty entrants seeking COSMOS-standard compliance.
- Makeup:Pigment dispersion technology and compact pressing equipment create batch-size constraints that favor flexible manufacturing lines. Micro-batch 500-unit minimums from TikTok-native brands are displacing traditional 10,000-unit runs, commanding premium positioning in Gyeonggi-do and Incheon production clusters.
- Hair Care:Bulk liquid filling standardization around shampoo and conditioner formats enables scale economics, with Indian PLI scheme incentives attracting contract manufacturers to Mumbai and Bangalore for import-substituted production.
- Fragrance:California Senate Bill 312 allergen disclosure mandates and EU fragrance allergen labeling requirements impose layered reformulation costs, restricting supplier options for brands selling into regulated retail channels.
Leading the category by volume: Skin Care. Growing fastest: Makeup.
Packaging Type:
Cost tier stratification separates commodity filling equipment from precision dispensing systems, with airless pump technology commanding 40-60% price premiums over standard formats.
- Pumps:Airless pump systems with mono-material construction concentrate in Zhejiang province suppliers, creating single-source vulnerability for brands targeting EU Deforestation Regulation traceability and California fragrance disclosure compliance. Demand from premium skin care brands seeking oxidation protection for retinol formats drives fastest expansion.
- Tubes:Mono-material and recyclable tube formats face REACH Annex XVII compliance costs for palm-derived emollients, with mass-balance certification requirements steepest for body care applications.
- Jars:Wide-mouth containers for balms and masks utilize standard filling lines with rapid changeover capability, serving mid-tier manufacturers competing on 4-week turnaround specifications.
- Bottles:PET and glass bottle formats anchor commodity scale economics, with concentrated and waterless formulation trends reducing shipping volumes and shifting value capture toward formulation innovation.
Highest margin capture: Pumps. Steepest volume climb: Tubes.
Sales Channel:
Customer type differentiation separates direct-to-consumer velocity requirements from traditional retail procurement cycles, compressing development timelines from 18 months to under 6 months for digital-native brands.
- Online Retailers:Subscription-box and social-commerce platforms specify 500-unit micro-batch minimums with 4-week turnaround, forcing ERP integration investments for real-time inventory visibility and lot traceability. TikTok Shop and Instagram-native storefronts concentrate demand most acutely among Gen Z-targeted launches.
- Specialty Stores:Clean beauty certification pipelines through EWG Verified and COSMOS-standard pre-approved raw material libraries attract brands targeting ingredient-conscious consumers, with formulation services commanding premium positioning.
- Supermarkets:Mass-market volume requirements favor standardized filling operations with 10,000-unit production runs, competing on scale economics rather than flexibility.
- Distributors:Multi-territory logistics requirements demand parallel compliance infrastructures across FDA MoCRA, EU Cosmetics Regulation, and emerging state-level fragrance disclosure laws.
Dominant volume flow: Supermarkets. Fastest expansion trajectory: Online Retailers.
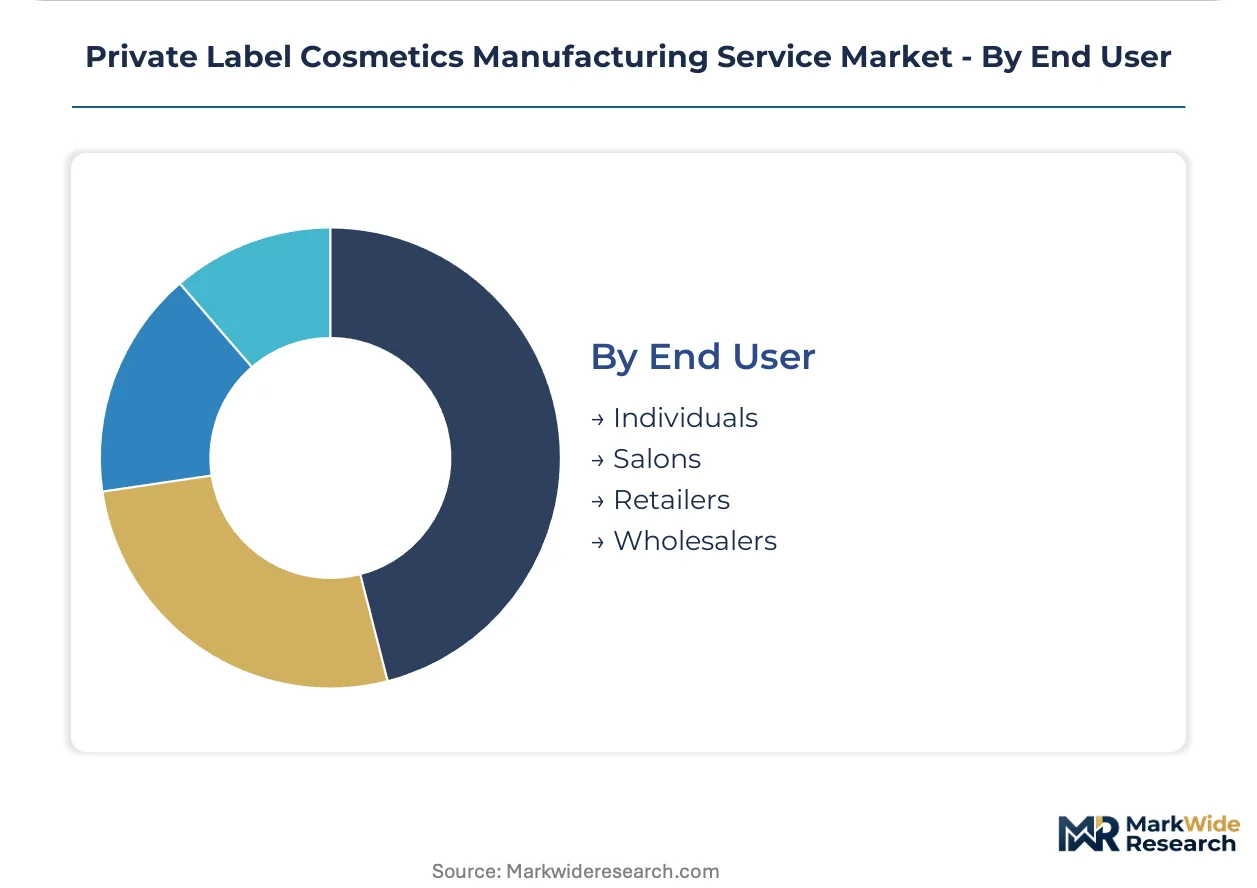
End User:
Application maturity separates established salon and wholesale relationships from emerging individual and retailer direct-sourcing patterns, reshaping manufacturer sales organization structures.
- Retailers:Private label program development for department stores and specialty chains requires multi-year partnerships with stability testing backlogs creating 12-16 week queue times at third-party laboratories.
- Individuals:Direct-to-consumer brand founders bypass traditional distribution layers, outsourcing formulation and production to specialized manufacturers with pre-validated GMP infrastructure under FDA MoCRA mandates.
- Salons:Professional-grade hair care and skin care procurement concentrates in established wholesale relationships with longer development cycles and locked-in multi-year supply agreements.
- Wholesalers:Volume aggregation across fragmented brand portfolios favors manufacturers with pharmaceutical-grade GMP facilities that attract clean beauty entrants seeking compliant production pathways.
Volume concentration: Retailers. Gaining share fastest: Individuals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in South Korea's K-beauty export networks and the United States' direct-to-consumer brand ecosystem, with regulatory fragmentation across FDA MoCRA and EU Cosmetics Regulation shaping manufacturing partner selection.
United States
Direct-to-consumer beauty brands in Los Angeles and New York accelerate outsourcing to contract manufacturers with pre-validated GMP infrastructure. FDA's Modernization of Cosmetics Regulation Act mandates facility registration and serious adverse event reporting, elevating compliance costs for smaller producers. California Senate Bill 312 fragrance disclosure requirements create additional reformulation demand for brands selling through the state's retail channels.
South Korea
K-beauty private label clusters in Gyeonggi-do and Incheon supply formulation expertise to North American and Southeast Asian brands seeking proven emulsion technologies. MFDS cosmetic safety standards enforce rigorous stability testing protocols that manufacturers leverage as competitive differentiation. Seoul Capital Area production hubs specialize in micro-batch 500-unit minimums for TikTok-native brand launches.
Germany
Clean beauty entrants target COSMOS-standard certification through contract manufacturers with pharmaceutical-grade facilities. ECHA REACH compliance for chemical substances and EU Cosmetics Regulation responsible person requirements shape formulation choices across export-oriented production. Bavaria-based manufacturers anchor competitiveness through integrated R&D and mass-balance certification for palm-derived emollients.
India
Domestic direct-to-consumer brands in Mumbai, Bangalore, and Delhi-NCR drive contract manufacturing demand through PLI scheme incentives for local production. CDSCO cosmetic import regulations and BIS quality standards push brands toward import-substituted manufacturing partnerships. Maharashtra and Karnataka production clusters compete on compressed 4-week turnaround specifications for social-commerce launches.
China
Zhejiang province suppliers concentrate airless pump and mono-material tube production, creating single-source vulnerability for brands dependent on precision dispensing systems. NMPA cosmetic registration requirements and SAMR market supervision enforce ingredient disclosure parallel to Western standards. Yangtze River Delta manufacturers face energy input fluctuations that transmit volatility to niacinamide and peptide complex pricing.
Private Label Cosmetics Manufacturing Service Market Competitive Landscape
Capacity expansion dominates the current landscape as established players validate GMP infrastructure under tightening FDA and EU regulatory mandates. The vendor base stratifies across pharmaceutical-grade facilities serving premium clean beauty entrants, flexible micro-batch specialists capturing TikTok-native brand demand, and scale-driven operators competing on shampoo and conditioner bulk liquid filling economics. Three archetypes anchor competitive positioning: integrated R&D-manufacturing hybrids, certification-focused compliance specialists, and rapid-turnaround micro-batch operators. M&A activity concentrates on acquiring pre-validated facility assets, while geographic expansion into Indian PLI scheme zones and South Korean export corridors represents the secondary competitive vector.
Within the integrated R&D tier, Intercos exemplifies the European-Asian footprint model that premium private label clients prioritize for multi-territory compliance coverage. Fareva Group occupies a position among pharmaceutical-grade GMP specialists that clean beauty entrants select for compliant production pathways. Kolmar Laboratories represents the South Korean export network archetype, anchoring formulation expertise supply to North American and Southeast Asian brand partners.
| Leading Market Players |
|---|
| Intercos |
| Fareva Group |
| Kolmar Laboratories |
| COSMECO |
| Cosmewax |
| HSA Cosmetics SpA |
| Skinlys |
| Bo International |
| Columbia Cosmetics Manufacturing Inc. |
| Others |
Pricing and Supply Chain Analysis
Niacinamide and peptide complex spot pricing on Chinese fine chemical exchanges cascades through contract manufacturing tiers, compressing margins for mid-tier producers while premium encapsulation specialists capture value through pharmaceutical-grade GMP certification premiums.
Pricing Analysis
Volume-midpoint manufacturers compete on bulk liquid filling economics for shampoo and conditioner formats, while encapsulation technology providers command premium positioning through retinol and vitamin C stability platforms. Price differentiation rests on COSMOS-standard certification and FDA MoCRA pre-validation status, with clean beauty entrants absorbing 40-60% premiums for compliant production pathways. Cost compression in standard filling operations intensifies due to Zhejiang province packaging concentration and energy input volatility. Social-commerce brands launching through TikTok-native channels exhibit highest price sensitivity, whereas premium skin care labels prioritize GMP infrastructure over unit economics.
Supply Chain Analysis
Cosmetic chemist availability in Gyeonggi-do and Incheon production clusters anchors South Korean export competitiveness, while formulation talent scarcity in European hubs elevates compensation premiums for encapsulation specialists. Supply concentration centers on China for airless pump mono-material components, India for PLI scheme incentivized bulk manufacturing, and South Korea for K-beauty emulsion expertise. Raw material dependencies encompass Chinese niacinamide derivatives, palm-derived emollients under EU Deforestation Regulation traceability mandates, and Zhejiang province mono-material tube inputs. Single-source packaging vulnerability in Zhejiang creates structural risk for brands targeting California Senate Bill 312 compliance. Distribution runs through direct-to-consumer brand networks, specialty retail procurement cycles, and supermarket volume aggregation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is accelerating into a vertical-integration race as manufacturers pursue captive supply of pharmaceutical-grade GMP infrastructure to defend margin capture against regulatory compliance cost escalation.
For Market Incumbents: Extend certification coverage across FDA MoCRA and EU Cosmetics Regulation parallel infrastructures to preempt smaller competitor displacement. Anchor capacity additions in Indian PLI scheme zones and South Korean export corridors where formulation expertise clusters. Deepen backward integration into encapsulation technology supply to offset active ingredient cost volatility from Chinese fine chemical markets. For New Entrants and Emerging Players: Begin with micro-batch manufacturing lines serving 500-unit minimum TikTok-native brand launches in Seoul Capital Area production hubs. Target fragrance reformulation services for California Senate Bill 312 compliance as the most penetrable white-space segment. Deploy rapid 4-week turnaround specifications as the primary go-to-market wedge against established competitors locked into 12-16 week stability testing queues. For Investors and Strategic Acquirers: Distressed-cycle entries favor pharmaceutical-grade GMP specialists in German Bavaria and South Korean Gyeonggi-do where regulatory compliance assets trade at compressed multiples. Long-term viability over the coming decade hinges on pre-validated facility ownership rather than contract manufacturing relationships. Monitor FDA facility registration enforcement intensity and EU Annex V preservative restriction expansions as inflection signals for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade GMP Certification | FDA MoCRA facility registration mandates elevate pre-validated infrastructure value for clean beauty entrants. |
| Encapsulation Technology Acquisition | Lipid nanoparticle delivery systems consolidate retinol stability expertise into single-supplier relationships. |
| Indian PLI Scheme Manufacturing Expansion | Import-substituted production in Maharashtra and Karnataka captures domestic DTC brand emergence demand. |
| EU Deforestation Regulation Traceability Investment | Mass-balance certification for palm-derived emollients secures color cosmetics supply chain access. |
| Micro-Batch Flexible Line Deployment | Rapid changeover capability commands premium positioning for 500-unit TikTok-native brand minimums. |
Research Methodology
Independent corroboration across contract manufacturing executives, cosmetic chemists specializing in encapsulation technology, regulatory affairs leads at clean beauty entrants, and specialty retail procurement managers underwrites the qualitative findings. Secondary validation draws from FDA facility registration databases, EU Cosmetics Regulation safety assessment filings, MFDS cosmetic stability testing protocols, and CDSCO import substitution tracking. Bottom-up demand modeling from brand-level outsourcing decisions triangulates against top-down market sizing from production capacity aggregation.
Comparable-period anchoring to historical outsourcing velocity trends and regulatory implementation timelines structures the projection framework across the analysis window. Segmentation dimensions encompass product type complexity tiers, packaging technology precision levels, sales channel velocity requirements, and end-user procurement maturity. CAGRs derive from weighted capacity expansion announcements, regulatory compliance cost trajectories, and active ingredient price elasticity assumptions. Forecast inputs incorporate cosmetic chemist talent availability indices and stability testing laboratory queue duration trends.
Underlying measurement precision varies by segment; skin care and makeup categories with established GMP certification pathways carry tighter precision than emerging fragrance reformulation services. Forecasts reflect assumptions around FDA enforcement intensity, EU Annex expansion schedules, and Chinese fine chemical production stability. Material deviation in preservative system regulatory restrictions or Zhejiang province logistics disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
UK Eyelash Serum Market
Cosmetics & Skincare
Eyeliner Market
Cosmetics & Skincare
Italy Lip Care Products Market
Cosmetics & Skincare
Mushroom Cosmetics Market
Cosmetics & Skincare
Color Cosmetics OEM and ODM Market
Cosmetics & Skincare
Deodorant Stick Market
Cosmetics & Skincare
China Skincare Market
Cosmetics & Skincare
GCC Bath Soap Market
Cosmetics & Skincare
Scalp Scrub Market
Cosmetics & Skincare
Natural Cosmetic Color Market
Cosmetics & Skincare
Matte Lipstick Market
Cosmetics & Skincare
Lip Products Pigment Market
Cosmetics & Skincare
Sweden Cosmetics Products Market
Cosmetics & Skincare
Epigenetic Cosmetic Products Market
Cosmetics & Skincare
Eye Shadow Market
Cosmetics & Skincare
Asia-Pacific Halal Cosmetics Market