
 Apple Accessories Market | 2026-2036
Apple Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Apple Accessories Market Analysis
Subscription-based warranty and device-protection services is rebalancing how accessory vendors monetize hardware relationships. Anker Innovations leverages its charging-technology leadership to anchor premium power-delivery portfolios. Belkin International sustains retail shelf presence through Best Buy and Apple Store partnerships. Spigen dominates third-party case design with rapid form-factor matching to new iPhone releases.
Apple accessories encompass physical peripherals engineered to complement, protect, or extend the functionality of Apple devices, typically incorporating Lightning, USB-C, or MagSafe connectors with precise dimensional tolerances measured in millimeters for seamless integration. These products serve consumer, commercial, and institutional buyers seeking device longevity, productivity enhancement, or audio-visual performance upgrades. Cases and screen protectors constitute the highest-volume product category, though noise-canceling headphones capture disproportionate margin pools due to semiconductor-intensive signal processing. Wireless technology segments outpace wired alternatives in growth velocity, while direct sales channels tighten manufacturer control over pricing and customer data compared to distributor-dependent models.
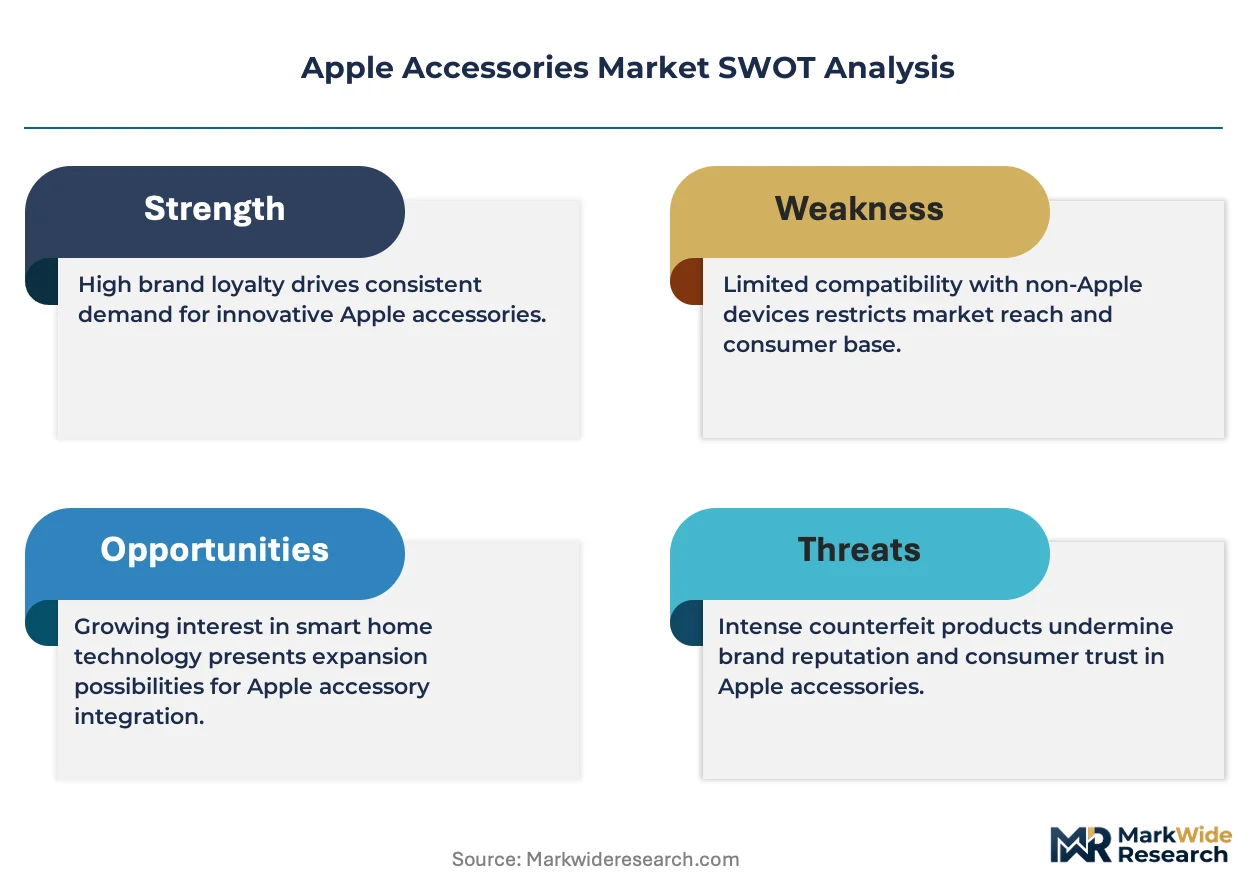
FCC electromagnetic-emission rules in the United States, CE marking requirements under EU harmonized standards, and China's GB certification for wireless radio-frequency equipment collectively dictate market-access thresholds for transmit-enabled accessories. RoHS substance restrictions and REACH chemical-registration obligations in Europe further constrain material-selection decisions for cables, adhesives, and surface coatings. Stakeholders must monitor evolving right-to-repair legislation across multiple jurisdictions, as regulatory pressure on device-repair accessibility threatens to commoditize historically proprietary connector ecosystems and reshape supplier competitive advantages.
Market Dynamics
Wireless charging standardization under IEC and Qi certification is compressing proprietary connector ecosystems and forcing accessory vendors to redesign power-delivery architectures around interoperable magnetic alignment systems.
Growth Catalysts
- Qi2 Magnetic Power Profile:The Wireless Power Consortium's updated standard mandates tighter coil alignment tolerances, enabling faster 15W charging across iPhone and Android devices simultaneously.
- Mobile Gaming Peripheral Demand:Competitive esports players in China and South Korea now prioritize low-latency controllers and cooling attachments, creating premium price tiers for thermal-management accessories.
- EU USB-C Harmonization Mandate:The European Commission's common-charging directive forces Lightning-to-USB-C adapter demand while opening design windows for unified cable portfolios.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium processing capacity clusters in China's Inner Mongolia region, exposing MagSafe-compatible manufacturers to export quota volatility.
- RoHS Substance Restrictions:ECHA's expanded REACH candidate list now restricts four additional phthalates in cable jacketing, forcing reformulation of existing PVC compounds.
- Semiconductor Fab Bottlenecks:Mature-node chip shortages for power-management ICs extend lead times for GaN chargers beyond 26 weeks.
Strategic Opportunities
- India PLI Scheme for Electronics:The government's production-linked incentive program offers 4-6% cashback on incremental mobile accessory output, attracting contract manufacturers to Noida and Chennai corridors.
- Automotive MagSafe Integration:Tier-1 suppliers are embedding Qi2 coils into center-console designs, creating certified-vehicle accessory programs with OEM branding rights.
- Repairability Score Mandates:France's repairability index legislation rewards modular cable designs with visible fasteners, privileging vendors with tool-free disassembly architectures.
Industry Challenges
- RF Emissions Certification Backlogs:FCC Part 15 testing queue times for 2.4GHz accessories now exceed 14 weeks, delaying product launches past seasonal demand windows.
- Legacy Lightning Inventory Stranding:Distributors face write-downs on MFi-certified cable stockpiles as USB-C transition accelerates across iPad and iPhone portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apple Accessories Market |
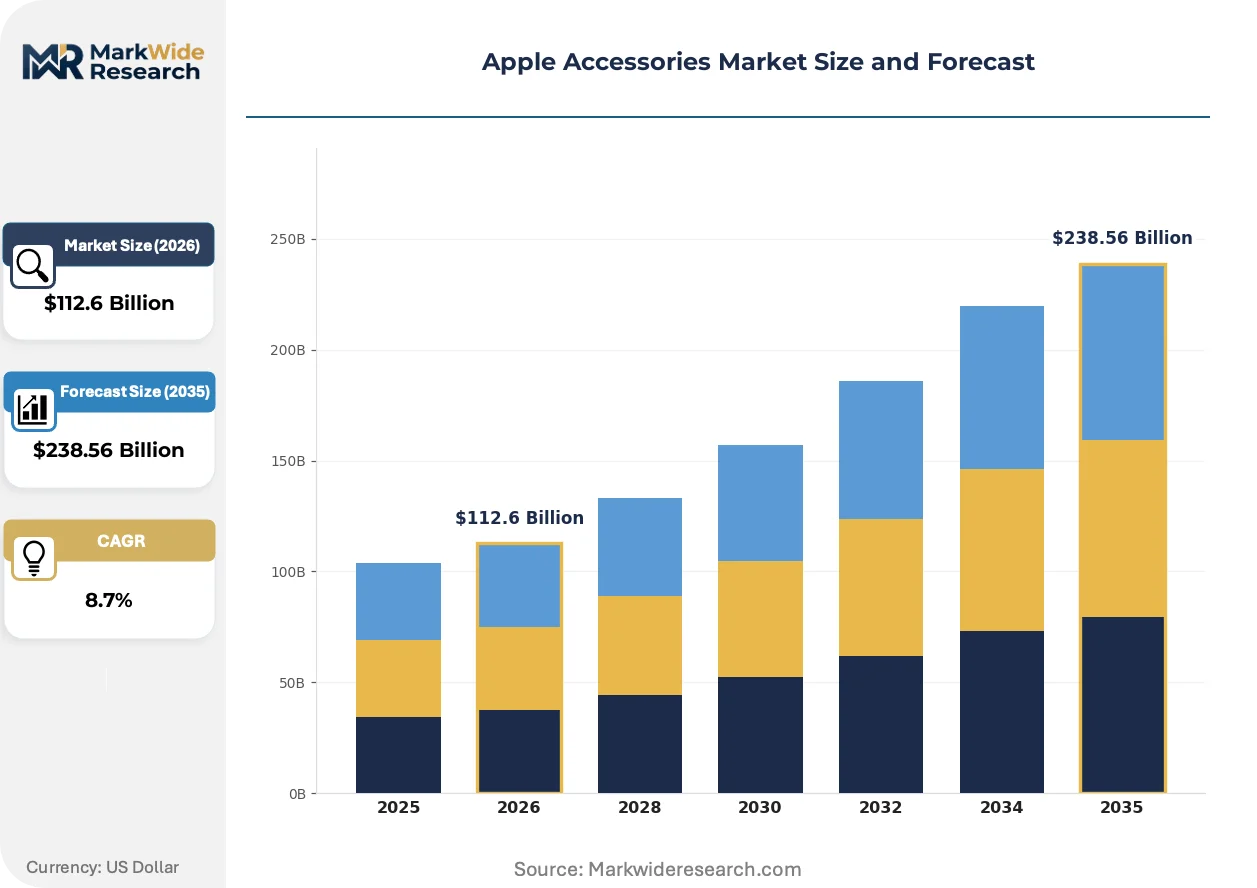
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $238.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cases, Chargers, Headphones, Screen Protectors End User: Consumers, Businesses, Educational Institutions, Retailers Technology: Wireless, Wired, Noise-Canceling, Smart Distribution Channel: Online, Retail Stores, Direct Sales, Distributors |
| Companies Covered | Spigen, Mophie, Belkin International, ESR, ZAGG Inc., Anker Innovations, OtterBox, Incipio Group, Logitech International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apple Accessories Market Emerging Trajectories
Gallium nitride power semiconductors and AI-driven noise cancellation are compressing form factors while elevating performance benchmarks across charging and audio categories.
GaN transistor technology is rewriting thermal design rules for wall chargers. Mobile professionals now demand 65W+ outputs from palm-sized adapters, collapsing the physical gap between laptop and phone power bricks. This compression is eliminating the discrete charger category for sub-100W devices.
EU right-to-repair frameworks are mandating seven-year spare-part availability for battery-dependent accessories. Manufacturers must now architect modular battery compartments with standardized cell formats, increasing BOM complexity but reducing e-waste liability. German and French enforcement agencies are prioritizing headphone and power-bank compliance audits.
Content creators now source accessories through TikTok Shop and YouTube affiliate links rather than retail shelves. This channel migration is concentrating marketing spend on influencer seeding programs, with Shenzhen-based vendors building dedicated creator-relations teams. The shift is most pronounced among Gen Z buyers in the United States and United Kingdom.
Apple Accessories Market Segmentation
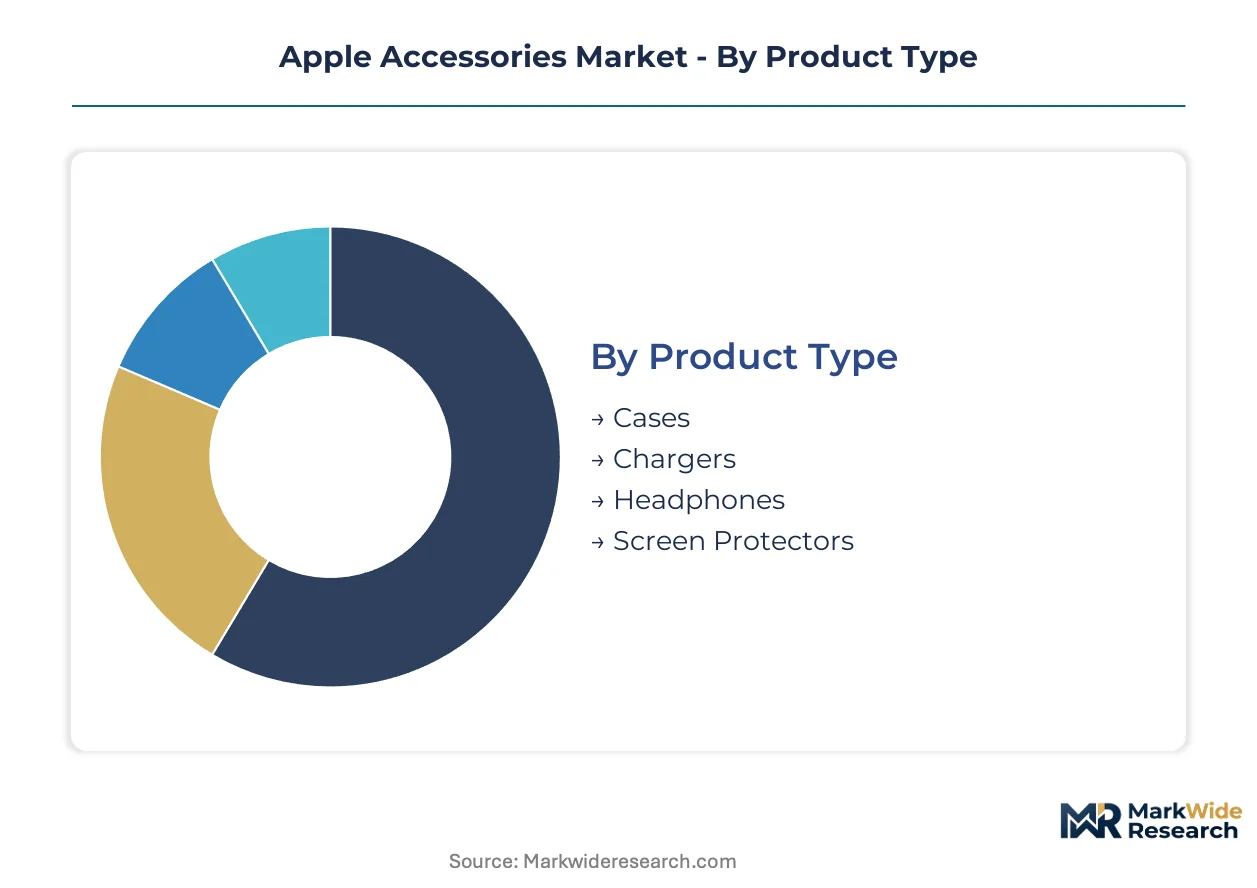
Accessory segmentation in Apple's ecosystem tracks how integration depth shapes procurement patterns. Standalone peripherals compete on speed-to-shelf with new device releases, while embedded systems lock into automotive and enterprise infrastructure.
Product Type:
Integration depth varies sharply: cases and screen protectors sit at the surface-interaction layer, while chargers and headphones embed semiconductor stacks that determine performance ceilings.
- Cases:Polycarbonate and liquid silicone shells with MagSafe magnet arrays embedded at precise 0.3mm tolerances. Shenzhen manufacturers dominate volume production for North American and European retail placement, though margin compression from commodity TPU alternatives limits premium capture.
- Chargers:GaN transistor architectures now enable 65W outputs from 30cc enclosures, collapsing thermal design constraints. Apple's USB-C transition across iPad and iPhone portfolios is redirecting R&D toward unified power-delivery controllers compatible with both legacy Lightning and new connector standards.
- Headphones:Active noise cancellation requires dedicated DSP silicon and multi-mic arrays.
- Screen Protectors:Tempered glass with oleophobic coatings; 9H hardness ratings standard.
Volume placements concentrate in Cases; the faster expansion belongs to Chargers.
End User:
Cost tiers separate procurement authority: consumers self-select at retail price points, while institutions negotiate multi-year fleet contracts with standardized SKUs.
- Consumers:Individual buyers purchasing through Amazon, Apple Store, or carrier channels. TikTok Shop and YouTube affiliate links now capture Gen Z discovery in the United States and United Kingdom, shifting marketing spend toward influencer seeding programs.
- Businesses:Enterprise IT departments sourcing dock stations, hubs, and privacy screens for hybrid work deployments. Procurement prioritizes warranty consolidation and single-vendor support agreements over feature differentiation.
- Educational Institutions:K-12 and university bulk purchasing with volume discounts.
- Retailers:Best Buy, Target, and carrier stores holding inventory risk for seasonal launches.
Businesses anchor procurement value; consumers drive absolute unit velocity.
Technology:
Application context determines connectivity choice: wireless architectures suit mobile and multi-device environments, while wired retains latency-critical use cases.
- Wireless:Qi2 Magnetic Power Profile coils with 15W output and tighter alignment tolerances. Demand clusters in China for automotive console integration and multi-device charging pads serving smartphone-plus-earbud households.
- Wired:USB-C and Lightning cables with MFi authentication chips. EU harmonization mandates are accelerating USB-C-only portfolio transitions, stranding legacy Lightning inventory at distributors.
- Noise-Canceling:Hybrid ANC with feedforward and feedback microphones.
- Smart:Find My network integration and firmware-updatable accessories.
Wired shipments still dominate unit volume; wireless configurations are climbing the fastest.
Distribution Channel:
Customer type and geography together determine channel efficiency: direct sales capture enterprise data and margin, while retail maintains impulse-purchase access.
- Online:Amazon, Apple.com, and direct-to-consumer storefronts. Shenzhen-based vendors now operate dedicated creator-relations teams to seed TikTok and YouTube review channels, bypassing traditional retail gatekeepers.
- Retail Stores:Apple Store, Best Buy, and carrier locations with merchandised displays. Shelf placement agreements with Belkin and Spigen lock out smaller competitors during iPhone launch windows.
- Direct Sales:Enterprise and education contracts with customized fulfillment.
- Distributors:Ingram Micro and regional wholesalers serving independent retailers.
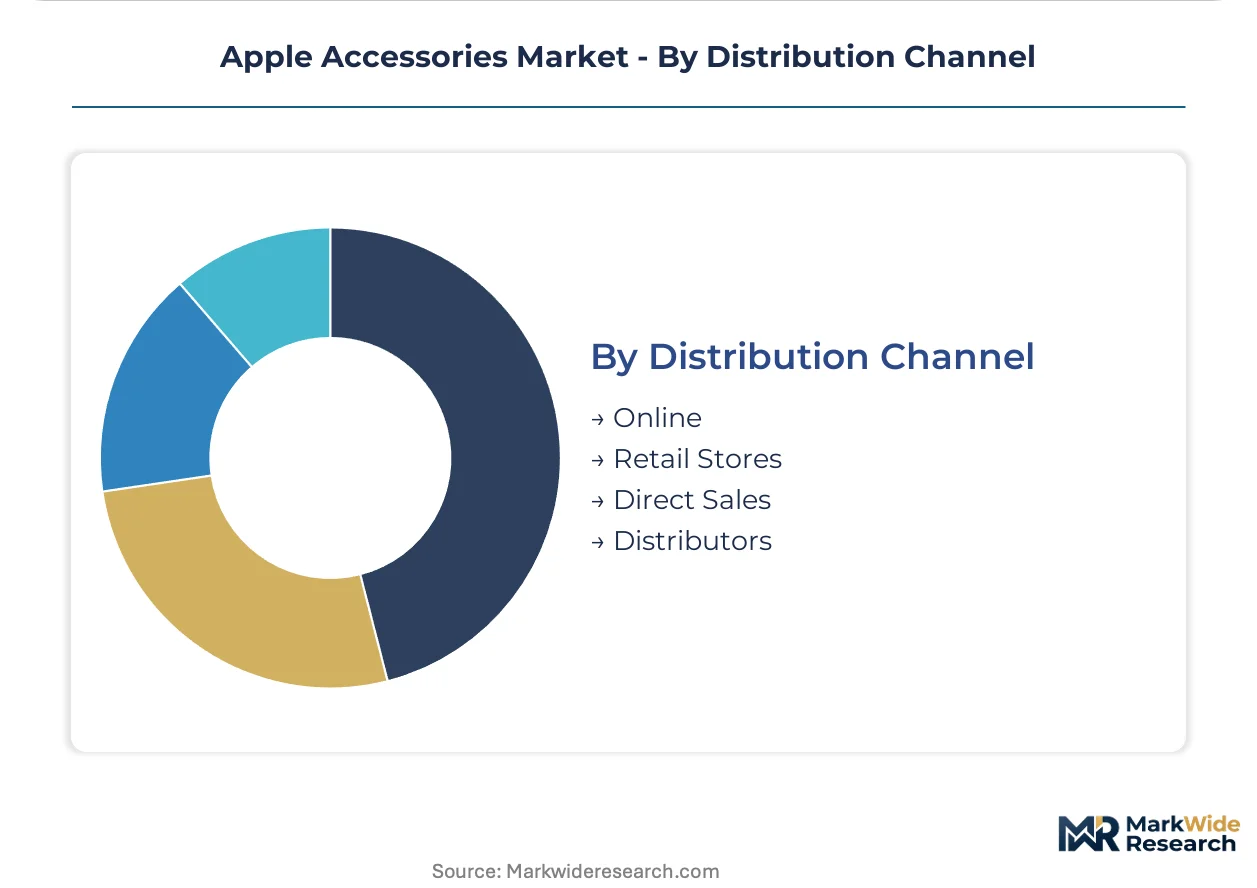
Online channels capture the steepest expansion trajectory; retail maintains launch-period volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Accessory manufacturing clusters in China while consumption concentrates in the United States and Western Europe. Shenzhen's electronics ecosystem feeds global supply chains through contract manufacturers serving branded vendors. Regulatory divergence between jurisdictions now shapes product architecture decisions.
United States
FCC electromagnetic-emission rules under Part 15 govern 2.4GHz accessory certification with queue times exceeding 14 weeks. The Biden administration's CHIPS Act indirectly supports domestic semiconductor packaging for power-management ICs. Austin and Silicon Valley host design centers for GaN charger engineering teams.
Germany
Industrial buyers in Bavaria and North Rhine-Westphalia prioritize warranty consolidation for enterprise dock station deployments. ECHA's expanded REACH candidate list restricts four additional phthalates in cable jacketing formulations. Berlin-based distributors manage stranded Lightning inventory from accelerated USB-C transitions.
China
Domestic mobile gamers in Guangdong and Jiangsu provinces drive premium peripheral demand for thermal-management accessories. MIIT's GB certification requirements for wireless radio-frequency equipment create market-access thresholds. Shenzhen manufacturers cluster around MagSafe-compatible neodymium magnet assembly lines.
India
The government's PLI scheme offers 4-6% cashback on incremental mobile accessory output, attracting contract manufacturers to Noida and Chennai corridors. BIS quality standards now apply to imported chargers and cables. Karnataka's electronics manufacturing zones host assembly operations for case and screen protector production.
Japan
METI efficiency regulations for external power supplies shape charger design specifications for domestic market entry. Tokyo and Osaka retail channels maintain premium positioning for noise-canceling headphone categories. Japanese semiconductor houses supply DSP silicon for active noise cancellation algorithms.
Apple Accessories Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the Apple accessories ecosystem. Shenzhen-based contract manufacturers own molding equipment and magnet insertion lines while brand holders concentrate on industrial design and channel relationships. Three archetypes dominate: integrated charging specialists, case-focused rapid form-factor matchers, and audio peripheral platform players. Competitive moves center on M&A for technology acquisition and strategic partnerships for automotive OEM certification programs.
Among charging-technology specialists, Anker Innovations occupies a position exemplifying power-delivery portfolio depth, while Belkin International represents retail shelf presence through carrier and electronics store partnerships. Spigen sits within the case-design tier, anchoring rapid form-factor matching capabilities to new device releases.
| Leading Market Players |
|---|
| Spigen |
| Mophie |
| Belkin International |
| ESR |
| ZAGG Inc. |
| Anker Innovations |
| OtterBox |
| Incipio Group |
| Logitech International |
| Others |
Supply Flow & Price Mechanics
EU USB-C harmonization mandates and Qi2 certification requirements are forcing accessory vendors to retool power-delivery architectures and magnetic alignment systems, compressing margins on legacy inventory while rewarding early standard adopters with pricing power in premium tiers.
Pricing Analysis
Margin tightening in economy-tier cases reflects Shenzhen manufacturers' race to match new iPhone form factors within 72-hour windows. Three-tier pricing structure across premium, standard, and economy levels separates GaN-enabled fast chargers from commodity 5W adapters and from MFi-certified cable bundles. Cost-down pressure on screen protectors accelerates because tempered glass production capacity outpaces brand-differentiated coating technologies. Enterprise procurement teams exhibit lowest price sensitivity due to warranty consolidation priorities, while Gen Z consumers through TikTok Shop channels drive hardest bargain hunting.
Supply Chain Analysis
Single-source vulnerability sits with Inner Mongolia neodymium processors supplying MagSafe magnet arrays to Shenzhen assembly clusters. Component sourcing draws from Taiwan for power-management ICs, South Korea for GaN semiconductors, and Japan for DSP silicon in noise-canceling headphones. Tariff exposure looms over finished goods shipments to North American retail channels. Distribution runs through Amazon fulfillment centers and Apple Store direct allocation for launch-window volume, with enterprise contracts bypassing wholesale tiers entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from semiconductor fab bottlenecks and regulatory certification backlogs will eliminate undercapitalized case vendors and Lightning-dependent cable specialists within two product cycles.
For Market Incumbents: Lock in automotive OEM certification programs for Qi2 console integration before Tier-1 suppliers finalize partner rosters. Deepen backward integration into neodymium magnet assembly to offset China's export quota volatility. Prioritize GaN charger R&D to defend against power-delivery commoditization. For New Entrants and Emerging Players: TikTok Shop creator-relations teams offer the most penetrable channel for Gen Z discovery in the United States and United Kingdom. Target India's PLI scheme corridors in Noida and Chennai for contract manufacturing cost advantages. Lead with modular, repairability-score-optimized designs to capture France's regulatory preference. For Investors and Strategic Acquirers: The window for entry favors charging-technology specialists with GaN IP and automotive qualification pipelines. Long-term viability hinges on standardization agility across USB-C and Qi2 transitions. Watch FCC Part 15 certification queue lengths as inflection indicator for launch-timing risk.| Strategic Initiative | Industry Significance |
|---|---|
| Qi2 Automotive Certification | Secures embedded placement in center-console designs with BMW and Mercedes Tier-1 programs. |
| GaN Semiconductor Backward Integration | Captures mature-node capacity before 26-week lead times strand competitor product launches. |
| Modular Repairability Architecture | Aligns product design with France's seven-year spare-part mandate and ECHA substance restrictions. |
| Creator-Relations Channel Buildout | Bypasses Best Buy and Apple Store shelf-placement gatekeepers through TikTok Shop affiliate networks. |
| India PLI Manufacturing Footprint | Locks in 4-6% cashback on incremental output while hedging against US tariff exposure. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs. Primary interviews with accessory category managers at Amazon, procurement leads at Best Buy, GaN charger engineering directors in Austin, and Shenzhen contract manufacturing executives combined with FCC Part 15 submission databases, Wireless Power Consortium certification registries, and EU harmonized standards documentation. Bottom-up unit shipment estimates triangulated against top-down consumer electronics spending patterns.
Product-type segmentation modeled charger, case, headphone, and screen protector categories separately across consumer, business, and institutional end users. Technology splits between wireless Qi2, wired USB-C/Lightning, and noise-canceling configurations captured substitution dynamics. CAGRs derived from fitted growth curves against historical release-cycle elasticities, with GaN adoption rates and right-to-repair legislative momentum as industry-specific forecast inputs throughout the projection horizon.
Caveats apply where FCC certification backlogs extend beyond seasonal demand windows or where China's rare earth export quotas disrupt MagSafe magnet supply. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
4K Television Market
Consumer Electronics
Global Wireless Headphones Market
Consumer Electronics
Closed Back Studio Headphone Market
Consumer Electronics
Middle East Radio Headset Market
Consumer Electronics
North America Wireless Anc Headphone Market
Consumer Electronics
Ultra-Portable Speakers Market
Consumer Electronics
Speakerphones Market
Consumer Electronics
Smartphone Console Market
Consumer Electronics
Middle East and Africa Smartphones Market
Consumer Electronics
Russia Gaming Gadgets Market
Consumer Electronics
Consumer Electronic Accessories Market
Consumer Electronics
Vertical Ergonomic Optical Mouse Market
Consumer Electronics
Electric Water Bottle Market
Consumer Electronics
North America Mobile Phone Accessories Market
Consumer Electronics
United States Gaming Peripherals Market
Consumer Electronics
Smart TV Sticks Market