
 Gaming Laptops and Desktops Market | 2026-2036
Gaming Laptops and Desktops Market Size, Share, and Industry Trends Forecast 2026-2036
Gaming Laptops and Desktops Market Insights
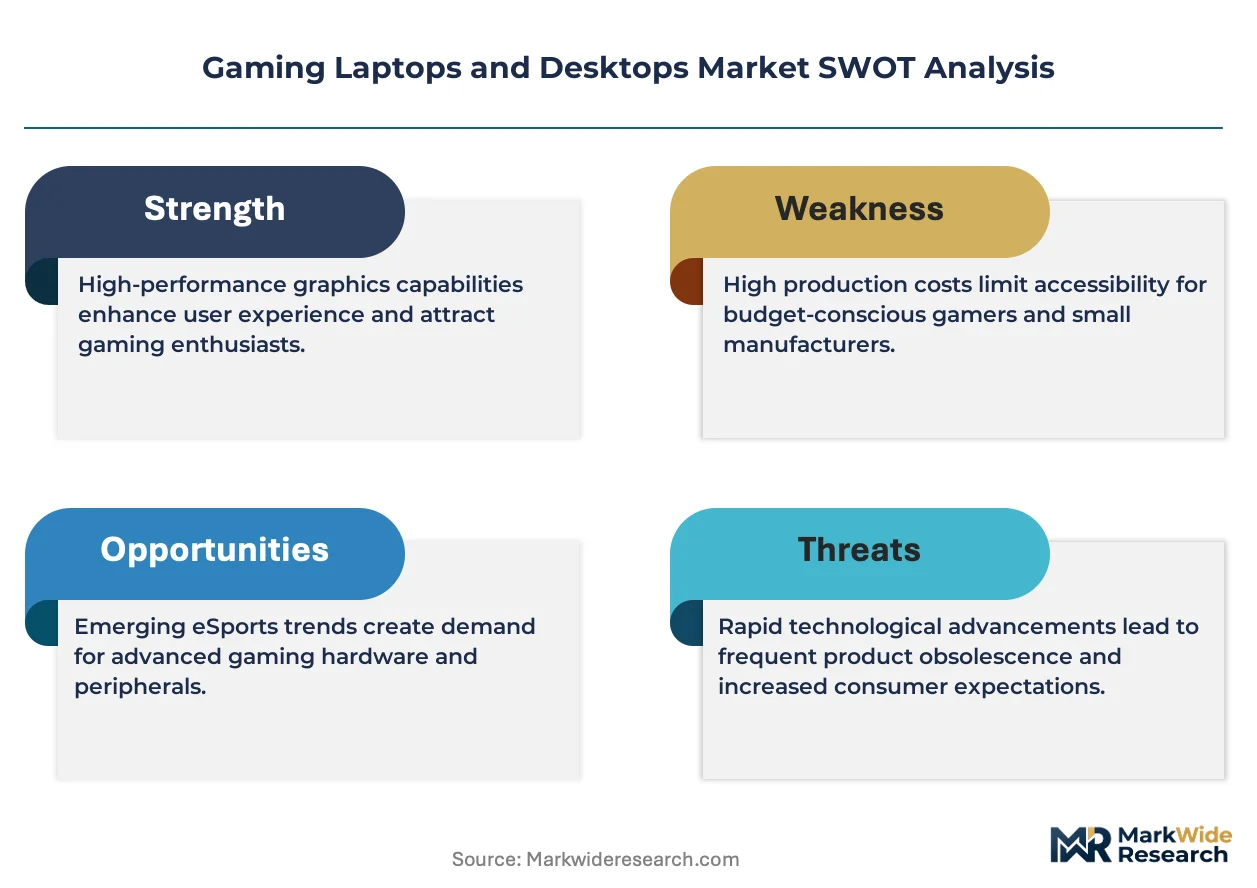
Taiwanese original design manufacturers are pivoting toward high-thermal-density chassis production for next-generation mobile GPUs. ASUS leverages vertical integration across motherboard and display panel supply to sustain margin control in premium gaming laptops. MSI anchors its position through deep specialization in esports-focused thermal engineering and tournament sponsorship channels.
Gaming laptops and desktops are high-performance computing systems engineered with discrete graphics processors, multi-core CPUs, and advanced vapor chamber or liquid cooling to sustain thermal design power loads above 150 watts during sustained workloads. Their primary commercial purpose is to render real-time 3D environments at high frame rates for interactive entertainment, competitive gaming, and live content production. The laptops segment leads volume shipments among product types due to portability demands from university students and mobile esports competitors, while the esports application category captures the fastest growth trajectory as tournament prize pools and league franchising expand. Graphics processing unit technology concentrates the largest margin pool, with discrete GPU configurations commanding substantial premiums over integrated alternatives.
The EU Ecodesign framework and REACH substance restrictions shape material choices and power supply efficiency requirements for systems sold across Europe. The FCC's equipment authorization process governs electromagnetic emissions for all devices entering the United States, while China's GB standards mandate specific safety and efficiency testing for domestic sales. Stakeholders must monitor how thermal design power ceilings and right-to-repair legislation evolve across multiple jurisdictions, as these will determine chassis engineering investments and regional product line differentiation.
Market Dynamics
The EU Ecodesign framework is compressing thermal design power ceilings across the entire gaming hardware supply chain, forcing chassis engineers to redesign vapor chamber geometries and power delivery subsystems for sustained 150-watt-plus workloads within stricter energy efficiency bands.
Growth Catalysts
- Esports league franchising:Tournament prize pools and professional team infrastructure are expanding the addressable base of competitive gamers requiring sub-20ms latency systems.
- REACH substance restrictions:European material compliance mandates are accelerating fluoropolymer-free thermal interface material adoption across motherboard and GPU assembly lines.
- Gaming café density in China:Domestic internet café licensing reforms and youth entertainment consumption patterns are concentrating volume demand in tier-two and tier-three cities.
Market Restraints
- Discrete GPU supply concentration:Foundry capacity for advanced node graphics processors concentrates with TSMC in Taiwan, creating single-point vulnerability for high-end mobile GPU allocation.
- Memory cost volatility:GDDR6X and HBM3 module pricing fluctuates with DRAM fab utilization rates, compressing margin predictability for systems above 16GB VRAM configurations.
- Right-to-repair legislative friction:Proposed EU and US state-level repairability mandates threaten proprietary thermal paste application and soldered RAM architectures that currently protect service revenue streams.
Strategic Opportunities
- Cloud gaming infrastructure gaps:Underpenetrated fiber-to-the-home markets in Indonesia and Vietnam create white space for hybrid local-render plus cloud-streaming laptop configurations.
- Dual-use workstation convergence:Real-time 3D engines and AI inference workloads are unifying gaming and content creation hardware specifications, expanding addressable market beyond entertainment.
- India PLI scheme for electronics:Production-linked incentive thresholds for IT hardware manufacturing are attracting motherboard and display panel assembly investments to Tamil Nadu and Karnataka.
Industry Challenges
- Thermal engineer scarcity:Vapor chamber and liquid metal application expertise concentrates among senior engineers at Taiwanese ODMs, constraining chassis design scaling for new market entrants.
- Certification timeline compression:FCC equipment authorization and China GB standards testing queues are extending from 12 to 18 weeks, delaying regional product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaming Laptops and Desktops Market |
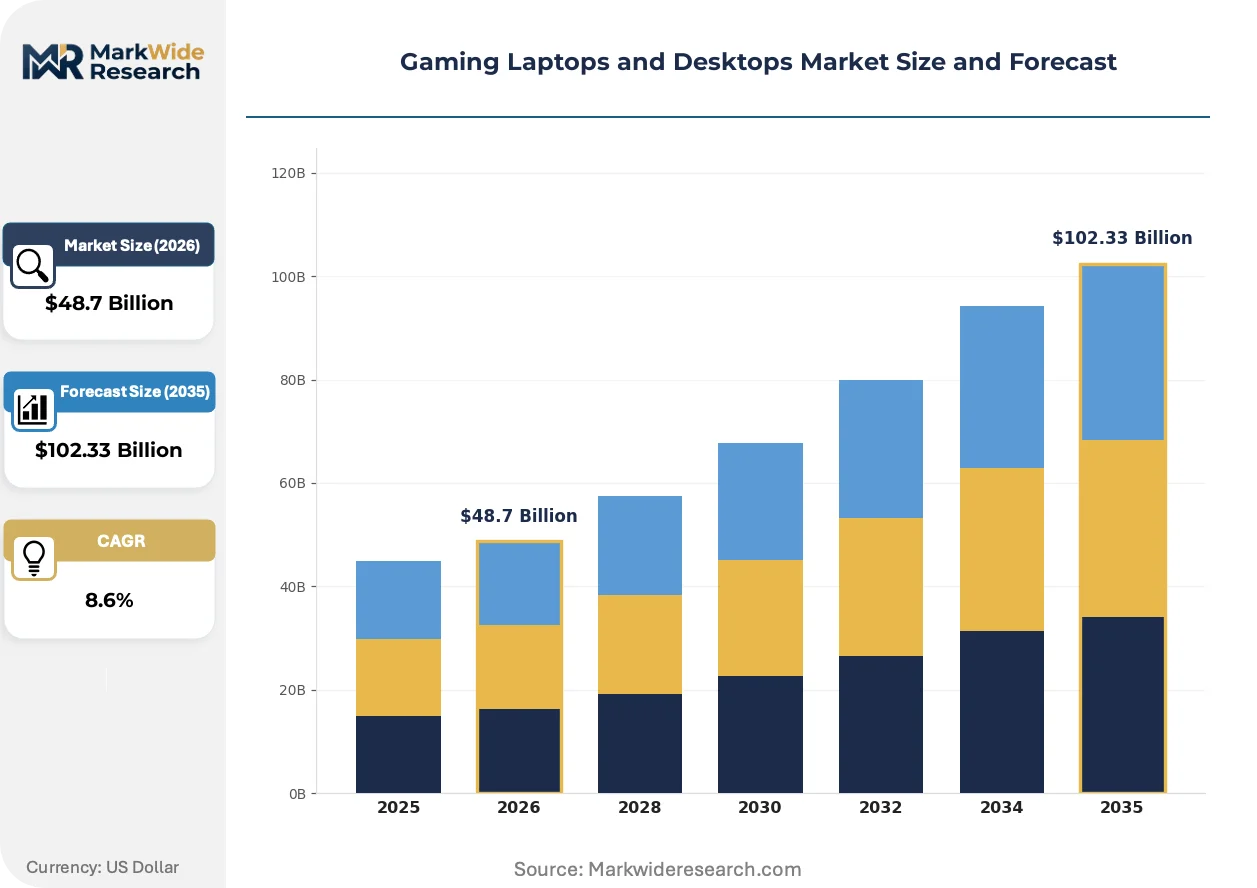
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $102.33 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laptops, Desktops, All-in-Ones, Gaming Consoles Application: Single Player, Multiplayer, Esports, Streaming Technology: Graphics Processing Unit, Central Processing Unit, Cooling Systems, Display Technology Customer Type: Casual Gamers, Professional Gamers, Streamers, Content Creators |
| Companies Covered | HP, MSI, ASUS, Gigabyte, Razer, Lenovo, Alienware, Dell, Acer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaming Laptops and Desktops Market Trends and Innovations
Three forces are compressing product development cycles: heterogeneous chiplet architectures merging CPU and GPU dies, regulatory pressure on standby power consumption, and procurement models shifting from retail to direct-to-education bulk contracts.
Chiplet-based mobile processors are unifying memory controller and graphics compute dies under unified thermal budgets. University IT departments and esports program directors are specifying these configurations for fleet standardization. This unification is compressing motherboard layer counts and enabling thinner chassis profiles without sacrificing sustained clock speeds.
The EU F-Gas Regulation is phasing down hydrofluorocarbon-based refrigerants used in liquid cooling loops for desktop systems. Manufacturers are retrofitting production lines for CO2 and hydrocarbon alternative charge systems. European gaming desktop assemblers are absorbing 15-20% cooling subsystem cost increases while redesigning for lower-global-warming-potential compliance.
Direct institutional procurement is displacing retail channel dependence for volume gaming laptop deployment. K-12 esports programs and university athletic departments are negotiating 500-unit-plus annual contracts with configured specifications. This pattern is most visible across Texas, California, and Ontario where scholastic esports receives dedicated athletic budget allocations.
Gaming Laptops and Desktops Market Segmentation
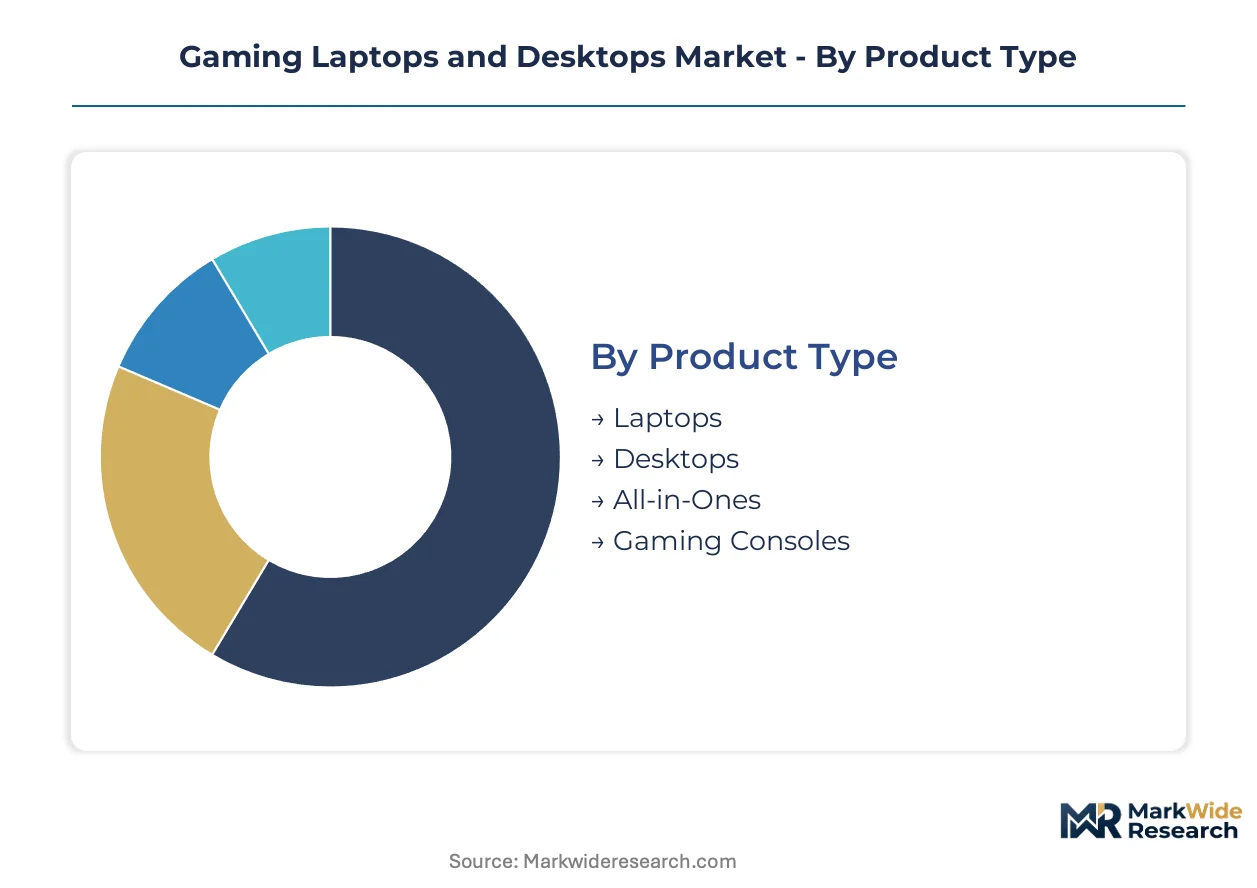
Gaming hardware segmentation reveals divergent engineering priorities across mobility requirements and thermal budgets. Component-level technology choices determine margin structures, while customer archetypes dictate distribution channel strategies and service attachment rates.
Product Type:
Standalone systems dominate commercial volumes, while embedded gaming modules within all-in-one workstations occupy specialized niches.
- Laptops:Portable chassis integrate discrete GPUs and vapor chamber cooling within sub-25mm z-heights. University students and mobile esports competitors in China drive procurement through direct-to-education contracts.
- Desktops:Tower and small-form-factor enclosures accommodate 300-watt-plus GPU configurations with liquid cooling loops. European gaming cafés and US scholastic esports programs prioritize these for upgradeability and thermal headroom.
- All-in-Ones:Display-integrated systems sacrifice GPU thermal budgets for spatial economy. Corporate training simulators and retail kiosk deployments represent the primary demand concentration.
- Gaming Consoles:Closed-architecture entertainment systems occupy adjacent market space with fixed hardware specifications. Living room entertainment centers and subscription-service bundling sustain this segment.
Laptops lead volumes today; esports-focused desktop configurations are gaining share fastest.
Application:
Cost tier separation runs from free-to-play casual engagement through six-figure professional tournament infrastructure.
- Single Player:Narrative-driven experiences prioritize GPU memory bandwidth for texture streaming. Steam platform users and console-adjacent PC builders in Germany and Japan concentrate demand here.
- Multiplayer:Competitive online modes require sub-20ms latency and stable frame pacing. Battle royale titles and team-based shooters drive hardware refresh cycles among 18-34 demographic clusters.
- Esports:Tournament-sanctioned titles mandate standardized 240Hz-plus displays and mechanical input devices. League franchising in Texas, California, and Ontario is expanding institutional procurement.
- Streaming:Simultaneous gameplay capture and broadcast encoding demands dedicated encoding hardware. Twitch and YouTube Gaming content creators in Brazil and Indonesia represent emerging demand pockets.
Multiplayer applications anchor current shipments; esports infrastructure is expanding most quickly.
Technology:
Margin concentration varies sharply across component layers, with discrete GPU supply commanding the largest value capture.
- Graphics Processing Unit:TSMC-fabricated discrete dies with GDDR6X or HBM3 memory stacks determine system performance ceilings. NVIDIA and AMD allocation queues constrain high-end mobile GPU availability.
- Central Processing Unit:Multi-core x86 and emerging ARM architectures balance single-thread gaming performance with background workload handling. Intel and AMD socket compatibility influences motherboard design longevity.
- Cooling Systems:Vapor chambers, liquid metal thermal interface materials, and pump-driven loops sustain thermal design power loads. EU Ecodesign efficiency bands are forcing redesign of 150-watt-plus sustained configurations.
- Display Technology:IPS and OLED panels with variable refresh rate synchronization reduce motion artifacts. AU Optronics and Samsung Display supply concentration affects regional product launch timing.
GPU technology captures the largest margin pool; cooling system innovation is climbing the fastest.
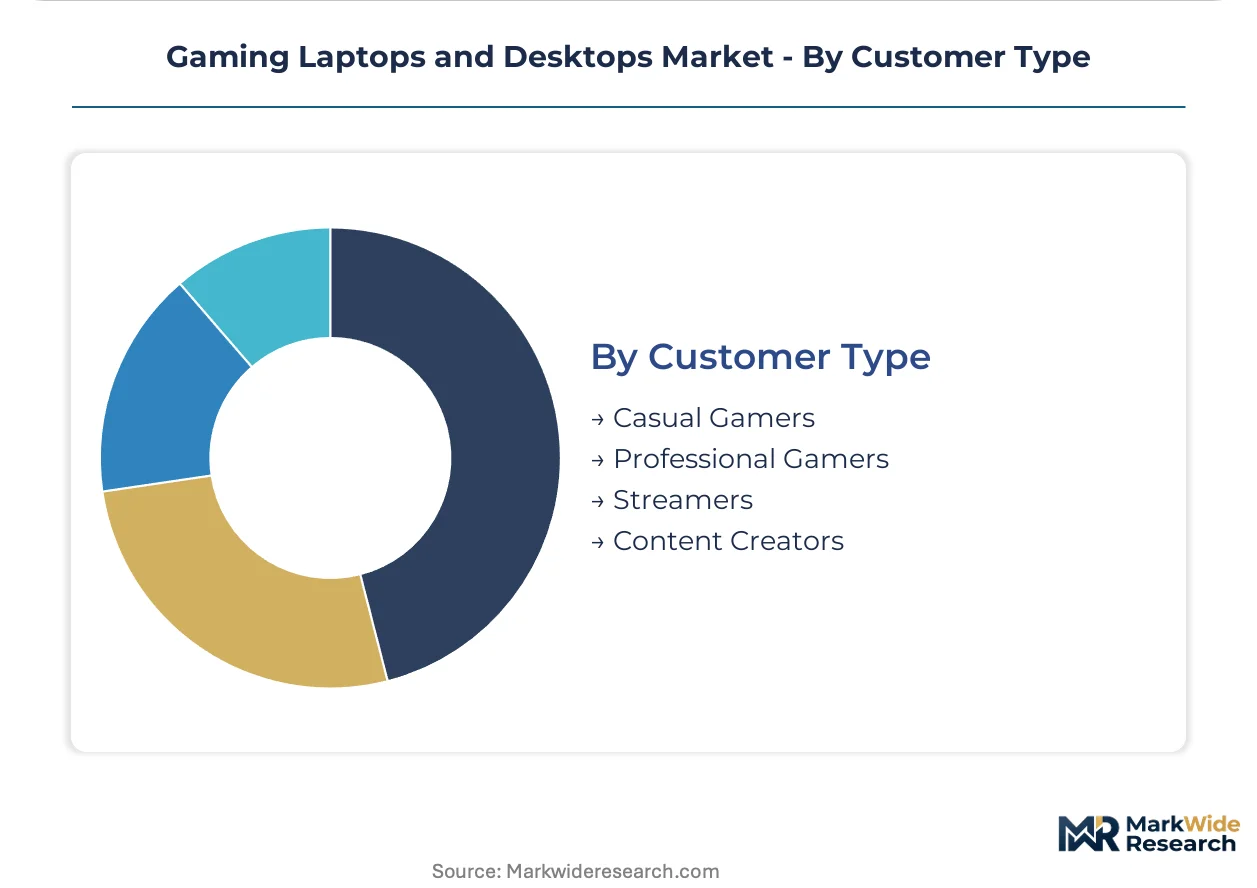
Customer Type:
Volume-maturity separation distinguishes mass-market retail from specialized professional channels with configured specifications.
- Casual Gamers:Price-sensitive purchasers prioritize 1080p resolution and 60Hz baseline performance. Amazon and Best Buy retail channels dominate this segment with promotional bundling.
- Professional Gamers:Sponsored competitors require tournament-grade latency consistency and standardized peripherals. Team house infrastructure and league equipment mandates drive fleet purchasing.
- Streamers:Dual-PC or single-system encoding configurations balance gameplay and broadcast quality. Elgato and AVerMedia capture card integration influences motherboard selection.
- Content Creators:Real-time 3D engine work and AI inference workloads unify gaming and workstation specifications. Blender and Unreal Engine certification programs guide hardware procurement.
Casual gamers sustain volume scale; content creator convergence is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are migrating final assembly toward jurisdictions with lighter Ecodesign compliance burdens, creating a regulatory-arbitrage dynamic that redistributes production capacity across the gaming hardware supply chain.
China
Gaming café licensing reforms and youth entertainment consumption patterns concentrate volume demand in tier-two and tier-three cities. MIIT's GB standards mandate specific safety and efficiency testing for domestic sales. Dongguan and Shenzhen industrial clusters host motherboard and display panel assembly operations serving both domestic brands and export markets.
United States
Scholastic esports programs in Texas and California negotiate 500-unit-plus annual contracts with configured specifications. FCC equipment authorization governs electromagnetic emissions for all devices entering the country. Austin and Seattle tech corridors anchor gaming hardware design centers and esports tournament infrastructure investments.
Germany
Steam platform users and console-adjacent PC builders drive demand for narrative-driven gaming experiences. REACH substance restrictions and EU Ecodesign framework compress thermal design power ceilings for systems sold across Europe. Bavaria's industrial base supports precision manufacturing for cooling subsystem components.
Taiwan
TSMC foundry capacity for advanced node graphics processors creates single-point vulnerability for high-end mobile GPU allocation. The island's trade authorities monitor export control developments affecting semiconductor supply security. Taipei and Taoyuan host original design manufacturers pivoting toward high-thermal-density chassis production.
India
Production-linked incentive thresholds for IT hardware manufacturing attract motherboard and display panel assembly investments. BIS certification requirements shape product localization strategies for multinational brands. Tamil Nadu and Karnataka industrial zones emerge as alternative assembly locations to China-dependent supply chains.
Gaming Laptops and Desktops Market Competitive Landscape
Taiwanese producers anchor one tier; American and Chinese specialists hold differentiated positions through channel access and cost structures. The vendor base organizes around three to four dominant players with captive GPU allocation agreements, while mid-tier assemblers compete on thermal engineering customization. Strategic archetypes include vertically integrated motherboard-to-display specialists, esports-focused thermal engineering boutiques, and scale-driven direct-to-education contract winners. Competitive moves center on tournament sponsorship channel capture and vapor chamber design licensing.
Within the premium-tier vector, ASUS and MSI occupy positions exemplifying divergent specialization strategies. ASUS leverages in-house production of motherboard and display panel supply to sustain margin control. MSI anchors its market presence through deep specialization in esports-focused thermal engineering. HP represents the scale-driven archetype with direct-to-education bulk contract capabilities spanning multiple continents.
| Leading Market Players |
|---|
| HP |
| MSI |
| ASUS |
| Gigabyte |
| Razer |
| Lenovo |
| Alienware |
| Dell |
| Acer |
| Others |
Pricing and Supply Chain Analysis
EU Ecodesign thermal efficiency mandates gate qualified supply access for gaming hardware manufacturers, compressing margin structures for chassis configurations above 150-watt sustained loads while elevating premium-tier pricing for compliant vapor chamber and liquid metal thermal interface systems. Buyers in scholastic esports programs and European gaming cafés face stepped cost thresholds as certified component availability concentrates among Taiwanese ODMs with proven Ecodesign compliance trajectories.
Pricing Analysis
Retailer markup layers dominate downstream pricing, with Amazon and Best Buy promotional bundling sustaining casual gamer volume while direct-to-education contracts command 8-12 point discounts for 500-unit fleet procurement. Three-tier pricing structure across premium, standard, and economy levels separates tournament-grade 240Hz configurations from 1080p baseline systems. Cost compression in mid-tier laptops intensifies because GDDR6X memory module volatility feeds through BOM calculations. University IT departments exhibit lowest price sensitivity due to athletic budget allocations, while tier-three Chinese gaming cafés operate at highest margin pressure.
Supply Chain Analysis
Regional distribution centers in Dongguan and Taoyuan anchor hub-and-spoke patterns feeding assembly operations across Shenzhen industrial clusters. Foundry capacity for advanced node GPUs concentrates in Taiwan, with South Korea and USA anchoring memory module and CPU supply respectively. Raw material dependencies span TSMC-fabricated dies, AU Optronics display panels, and fluoropolymer-free thermal interface materials. Single-source vulnerability at the GPU allocation tier threatens high-end mobile configuration availability. Distribution runs through ODM direct contracts for institutional buyers and retail channel partners for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gaming hardware functions as a regulatory compounder where EU F-Gas Regulation phase-downs and REACH substance restrictions accelerate compliant supplier consolidation, with Ecodesign thermal ceilings driving replacement demand across European installed bases.
For Market Incumbents: Anchor market position through captive vapor chamber design licensing and tournament sponsorship channel lock-in against emerging thermal engineering boutiques. TSMC allocation queue priority represents the critical defensive lever. Accelerate backward integration into display panel supply to offset AU Optronics and Samsung Display concentration risk. For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing opens a window for motherboard and chassis assembly investments in Tamil Nadu and Karnataka industrial zones. Indonesia and Vietnam fiber-to-the-home gaps create white space for hybrid cloud-streaming laptop configurations. Scholastic esports procurement in Texas and California offers the most penetrable institutional segment through direct-to-education sales archetypes. For Investors and Strategic Acquirers: Roll-up economics work for thermal engineering boutiques because vapor chamber and liquid metal application expertise concentrates among senior engineers at Taiwanese ODMs, constraining scaling for new entrants. Long-term viability centers on acquisition of esports-focused thermal engineering specialists with proven Ecodesign compliance track records. Monitor TSMC advanced node allocation announcements as inflection indicator for high-end mobile GPU availability compression.| Strategic Initiative | Industry Significance |
|---|---|
| Tournament Sponsorship Channel Capture | Esports league franchising in Texas and California locks in standardized fleet procurement. |
| Vapor Chamber Design Licensing | Taiwanese ODMs monetize thermal engineering IP as Ecodesign compliance gates competitor entry. |
| Direct-to-Education Contract Negotiation | University athletic departments in Ontario and California allocate dedicated esports equipment budgets. |
| Fluoropolymer-Free TIM Retrofit | REACH substance restrictions force thermal paste reformulation across motherboard assembly lines. |
| GPU Allocation Queue Securement | NVIDIA and AMD discrete die priority determines high-end mobile configuration launch timing. |
Research Methodology
Coverage spans China, United States, Germany, Taiwan, and India, with primary inputs from each regional cluster combining executive interviews with ODM thermal engineers, esports program directors at Texas and California universities, European gaming café procurement leads, and TSMC supply chain managers. Secondary validation draws from FCC equipment authorization filings, EU Ecodesign directive compliance databases, MIIT GB standards documentation, and SEC filings of publicly traded gaming hardware manufacturers. Bottom-up unit shipment modeling triangulates against top-down market value estimates.
Granularity-level framing segments the market by product type, application, technology component, and customer archetype, with additional modeling of thermal design power tier and regional regulatory compliance cluster. CAGRs derive from logistic diffusion curves fitted to historical adoption patterns and projected replacement cycles across the analysis window. Forecast inputs include esports tournament prize pool trajectories, EU F-Gas Regulation phase-down schedules, and India PLI scheme threshold achievement timelines.
Revisions become necessary when TSMC foundry allocation disruptions, REACH substance restriction enforcement escalations, or right-to-repair legislative passage materialize beyond baseline assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Middle East and Africa Refurbished and Used Mobile Phones Market
Consumer Electronics
Gaming Keyboard Market
Consumer Electronics
Middle East and Africa Mobile Phone Accessories Market
Consumer Electronics
Middle East and Africa Smartphones Market
Consumer Electronics
Stress Ball Market
Consumer Electronics
US Mobile Phone Accessories Market
Consumer Electronics
Global Earphones and Headphones Market
Consumer Electronics
Shoe Shining Machine Market
Consumer Electronics
Smart Television and Set-Top Box Market
Consumer Electronics
Smart Connected TV Market
Consumer Electronics
Smart Mirror Market
Consumer Electronics
Wireless Speakers Market
Consumer Electronics
IoT in Consumer Electronics Market
Consumer Electronics
Global White Noise Machines Market
Consumer Electronics
Portable Speaker Market
Consumer Electronics
North America Smartphone Accessories Market