
 Global Laptop Market | 2026-2036
Global Laptop Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laptop Market Outlook
Enterprise buyers is unwinding the consumer-heavy demand mix that defined the pandemic era. HP Inc. leverages its channel depth to sustain corporate refresh cycles across North America and Europe. Dell Technologies anchors its position through direct-to-business configurability and supply chain control. Lenovo Group dominates the commercial segment in Asia through scale manufacturing and localized SKUs.
A laptop is a portable personal computer integrating a clamshell chassis, liquid-crystal or OLED display panel, x86 or ARM-based processor, lithium-ion battery pack, and solid-state storage into a single mobile unit, designed for computing tasks outside fixed workstation environments. Gaming Laptop and Ultrabook categories now capture the strongest margin pools as enthusiast specifications and thin-and-light mobility command pricing premiums. The 2-in-1 Laptop segment competes for hybrid workforce budgets against tablets, while traditional Notebook units face pressure from Chrome OS alternatives in education procurement.
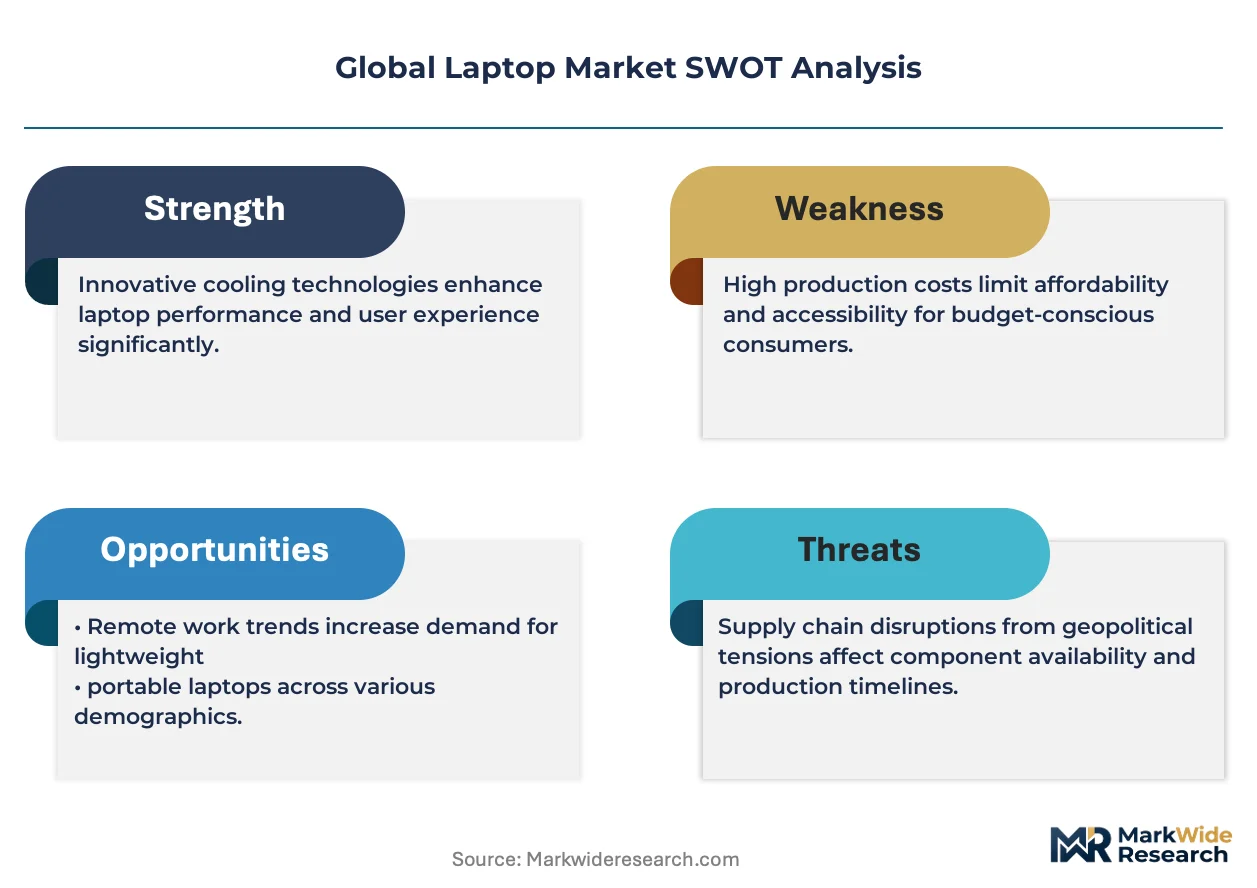
FCC certification governs wireless emissions for US-bound units, while the EU's REACH and RoHS frameworks restrict hazardous substances in chassis plastics and solder compositions. India's BIS compulsory registration scheme blocks uncertified imports and channels volume toward domestic assembly operations. Stakeholders must monitor how ARM architecture licensing and on-device AI inference requirements reshape component sourcing and thermal design roadmaps.
Market Dynamics
Enterprise fleet replacement cycles are compressing as on-device AI inference capabilities become procurement prerequisites, forcing thermal design and memory subsystem upgrades across manufacturer roadmaps.
Growth Catalysts
- EU Ecodesign Regulation:Repairability mandates under the Ecodesign for Sustainable Products Regulation are extending product lifecycles and creating aftermarket service revenue pools for certified repair networks.
- India PLI scheme:Production-linked incentives for local laptop assembly are redirecting supply chain investment toward Gujarat and Tamil Nadu manufacturing clusters.
- Neural processing units:Dedicated NPU silicon for on-device AI workloads is becoming a standard procurement specification in corporate RFPs.
Market Restraints
- Lithium-ion cell concentration:Cathode and cell manufacturing concentration in East Asian suppliers creates input cost volatility and geopolitical exposure.
- ARM licensing friction:Architecture licensing disputes between semiconductor designers and foundries are delaying product roadmap execution.
- Chrome OS substitution:Cloud-native computing alternatives are capturing education procurement budgets in North American and European institutional channels.
Strategic Opportunities
- Vietnam assembly expansion:Underpenetrated manufacturing capacity outside China offers tariff diversification for US-bound volume.
- Refurbishment certification:BIS registration pathways for factory-refurbished units create formal secondary market access in India.
- Copilot+ PC specification:Microsoft's AI PC certification program is creating a premium tier with dedicated marketing support and channel incentives.
Industry Challenges
- Thermal engineering talent scarcity:Vapor chamber and graphite sheet design expertise is concentrated among Asian ODM engineering teams.
- FCC pre-certification timelines:Wireless module approval delays are compressing product launch windows for seasonal retail cycles.
- Legacy port retention:Corporate buyer demands for USB-A and HDMI compatibility are constraining chassis thinness and battery volume.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laptop Market |
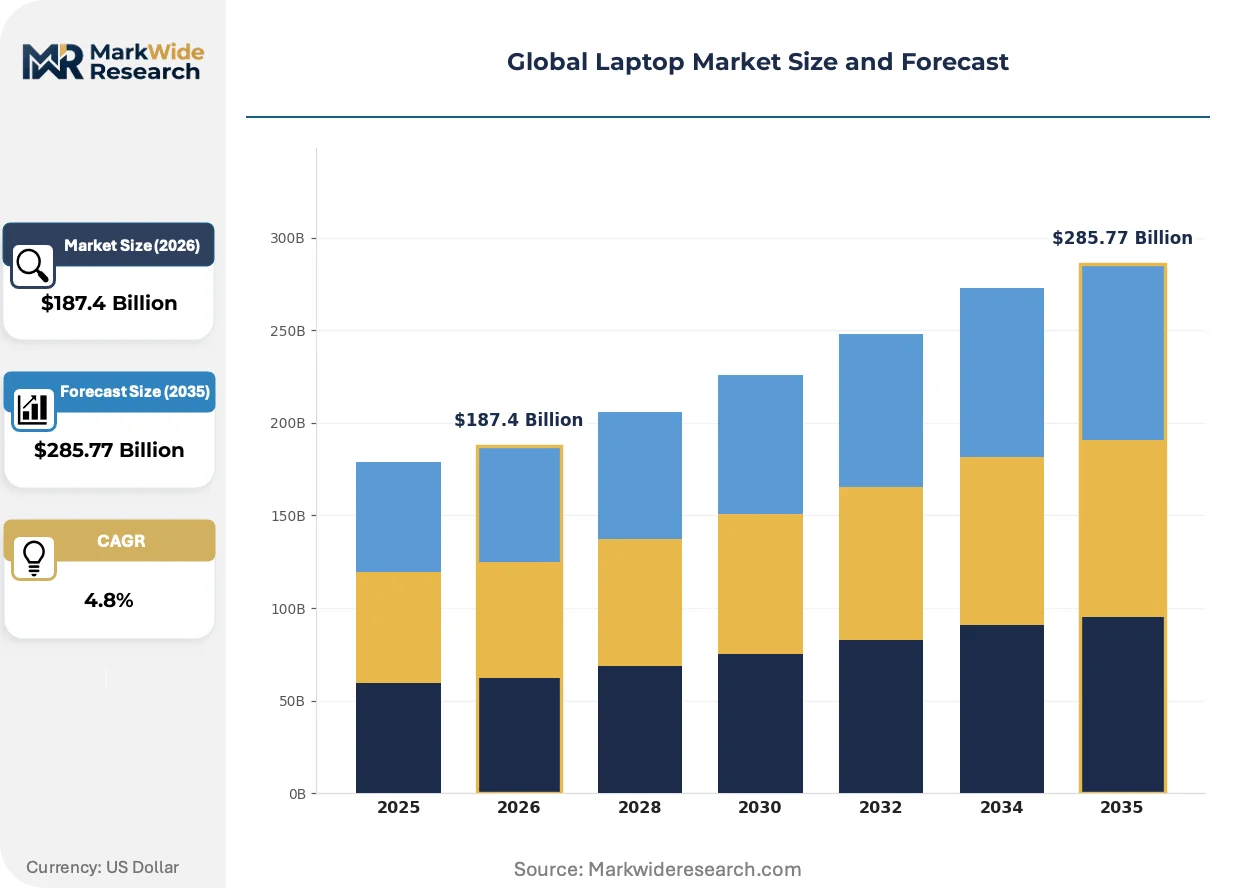
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gaming Laptop, Ultrabook, Notebook, 2-in-1 Laptop End User: Students, Professionals, Gamers, Businesses Operating System: Windows, macOS, Chrome OS, Linux Form Factor: Traditional, Convertible, Detachable, Rugged |
| Companies Covered | Lenovo Group, HP Inc., Dell Technologies, Apple Inc., ASUSTeK Computer, Acer Inc., Microsoft Corporation, Samsung Electronics, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laptop Market Strategic Shifts
Silicon architecture diversification and regulatory material restrictions are forcing concurrent redesigns of thermal systems, power delivery, and chassis construction across tier-one manufacturers.
Gallium nitride power ICs are replacing silicon MOSFETs in adapter and onboard voltage regulator designs. Enterprise procurement teams are specifying GaN adapters in fleet RFPs for weight and efficiency gains. The technology is miniaturizing wall-wart dimensions while enabling higher-wattage charging in thinner form factors.
REACH Substance of Very High Concern listings are expanding restricted substance catalogs for plastics and flame retardants. Manufacturers are reformulating chassis composites and solder alloys to maintain CE marking eligibility. Gaming laptop enclosures with higher plastic content face disproportionate material substitution costs and supply qualification delays.
Corporate buyers are unbundling device procurement from managed service contracts. Direct hardware purchasing with separate IT service agreements is displacing traditional bundled leasing arrangements. This pattern is most visible in North American enterprise accounts with mature device-as-a-service experience.
Global Laptop Market Segmentation
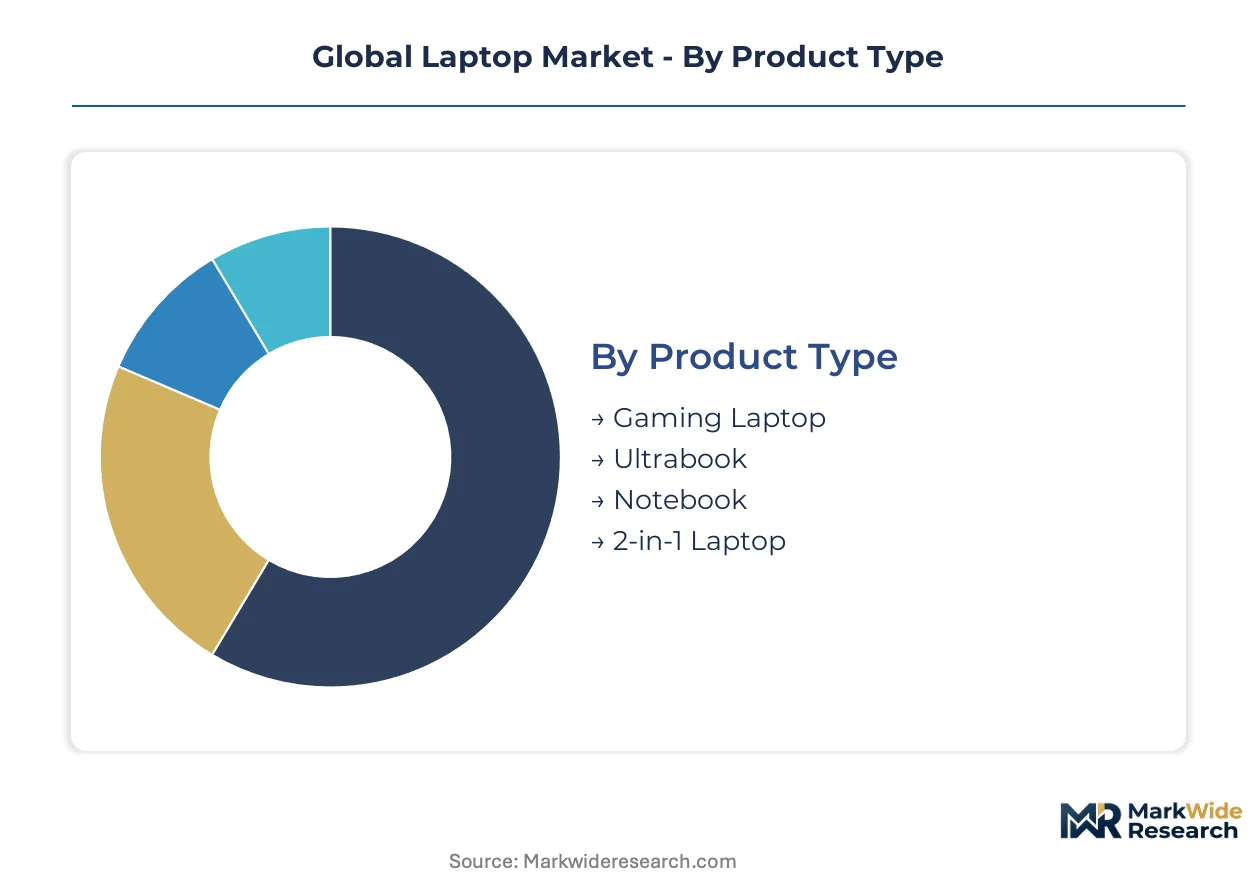
Segmentation in the laptop market reveals how margin pools concentrate around mobility-performance tradeoffs and procurement authority structures. Enterprise buyers, enthusiast consumers, and institutional channels each drive distinct specification requirements that reshape component sourcing and thermal engineering priorities across manufacturer portfolios.
Product Type:
Gaming Laptop and Ultrabook segments command the widest pricing spreads and strongest margin capture, while traditional form factors face compression from cloud-native alternatives.
- Gaming Laptop:Discrete GPU architectures with vapor chamber cooling and high-refresh OLED panels define thermal and power delivery specifications. Demand concentrates in China and the United States where esports infrastructure and enthusiast disposable income support $2,000+ average selling prices. NVIDIA's mobile RTX silicon allocation cycles create supply bottlenecks during university matriculation windows.
- Ultrabook:CNC-machined aluminum chassis, low-power OLED displays, and Intel Evo or Snapdragon X Elite certification programs establish thin-and-light performance baselines. Corporate fleet procurement in Germany and Japan prioritizes sub-1.2kg weights and 18-hour battery runtime for hybrid workforce deployment. GaN adapter miniaturization enables sub-45W charging in airport lounge and co-working scenarios.
- Notebook:Conventional clamshell designs with x86 processors and rotational hard drives or SATA SSDs serve cost-sensitive institutional channels. Volume concentrates in Indian education tenders and Southeast Asian SMB replacement cycles.
- 2-in-1 Laptop:Hinge or detachable keyboard mechanisms compete directly against iPad Pro and Surface tablets for mobile professional budgets. Stylus latency specifications and tablet-mode weight distribution determine competitive positioning against pure tablet alternatives.
Notebook holds installed capacity across emerging market education channels. Gaming Laptop is rotating up the share rankings as thermal engineering capabilities spread beyond specialized ODMs.
End User:
Procurement authority and replacement cycle length vary sharply across user categories, with enterprise IT departments imposing standardization that consumer segments resist.
- Students:K-12 and higher education procurement operates on 3-4 year district-wide refresh schedules with Chrome OS or Windows SE dominance. India's National Education Policy device distribution programs and US E-Rate funding cycles create concentrated volume spikes.
- Professionals:Creative workstation specifications with color-accurate displays and 32GB+ memory configurations serve media production and architecture workflows. Adobe Creative Cloud hardware certification requirements influence GPU and display panel selection.
- Gamers:Enthusiast segment tolerates 2.5kg+ chassis weights and 300W power adapters for frame rate performance. RGB lighting ecosystems and streaming-optimized webcam placement create brand switching costs.
- Businesses:Enterprise IT departments specify vPro management, TPM 2.0, and 3-year next-business-day warranty terms in centralized RFPs. Dell and HP channel programs capture direct procurement relationships through configuration lockdown and asset tagging services.
Businesses anchor replacement volume through managed refresh contracts. Gamers is expanding most quickly as cooling engineering capabilities democratize across price tiers.
Operating System:
Platform economics and developer ecosystem health determine attach rates for premium hardware configurations and service revenue streams.
- Windows:Dominant enterprise and gaming platform with Copilot+ PC certification creating new premium tier through NPU requirements. Microsoft's OEM licensing terms and Surface hardware reference designs influence manufacturer margin structures.
- macOS:Apple's vertical silicon integration with M-series processors enables unified memory architectures and extended battery runtime. Creative professional retention and enterprise MDM enrollment growth support premium pricing in United States and United Kingdom markets.
- Chrome OS:Cloud-native architecture with minimal local storage serves education and frontline worker segments. Google's per-device management licensing and automatic update policies reduce IT operational burden for scaled deployments.
- Linux:Developer workstation and privacy-conscious user preference drives demand for factory-supported distributions. Lenovo's Fedora and Ubuntu certification programs and Dell's Precision Linux offerings serve specialized professional workflows.
Windows maintains dominant installed base across commercial and consumer channels. Chrome OS is climbing the fastest in education procurement as Google Workspace integration deepens.
Form Factor:
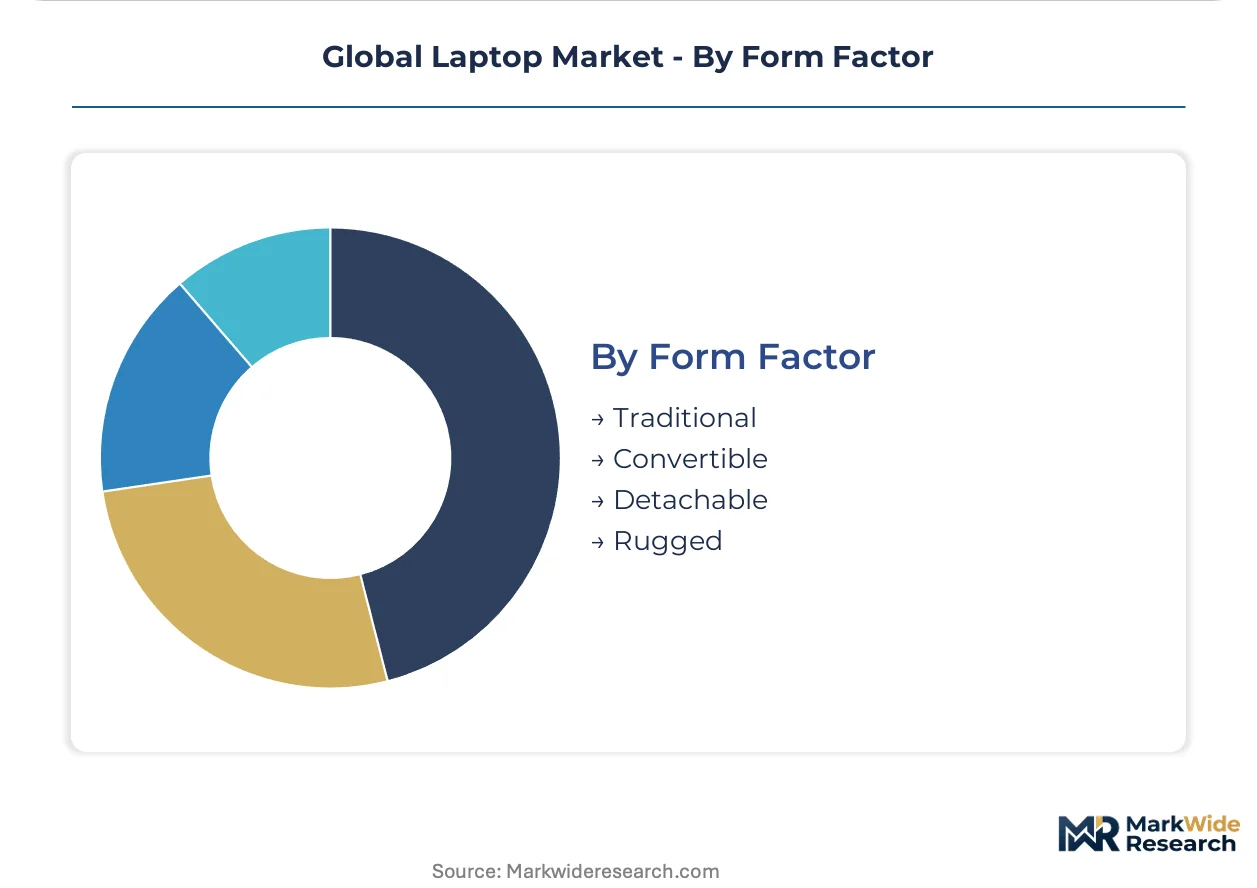
Mechanical engineering complexity and durability certification requirements segment manufacturing capabilities and regional competitive positioning.
- Traditional:Fixed-hinge clamshell designs with standardized component layouts enable lowest-cost manufacturing and fastest repair turnaround. Volume concentrates in Indian and Vietnamese assembly operations serving price-sensitive emerging markets.
- Convertible:360-degree hinge mechanisms with tent, stand, and tablet modes require reinforced cable routing and display panel protection. Lenovo's Yoga and HP's Spectre x360 establish mechanical durability benchmarks through 25,000+ cycle hinge testing.
- Detachable:Keyboard dock and tablet separation with pogo pin or wireless connectivity competes against pure tablets for mobile productivity. Microsoft's Surface Pro and Apple's iPad Magic Keyboard define magnetic attachment and trackpad precision standards.
- Rugged:MIL-STD-810H certification for drop, dust, and liquid ingress protection serves field service, military, and industrial applications. Panasonic's Toughbook and Dell's Latitude Rugged command 3-5x pricing premiums through specialized thermal management and sealed port designs.
Traditional form factor retains volume leadership in emerging market procurement. Convertible is gaining share fastest as hinge engineering costs decline and hybrid workforce use cases proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly capacity clusters in East Asian manufacturing hubs while procurement demand shifts toward India and Vietnam as tariff-diversification destinations reshape supply chain geography.
United States
Enterprise fleet refresh cycles and Copilot+ PC procurement specifications drive commercial volume. FCC wireless certification requirements govern all US-bound unit emissions. Austin and Round Rock in Texas anchor Dell's direct-to-business configuration operations.
China
Domestic consumption and ODM manufacturing for global brands sustain dual demand channels. MIIT equipment certification and dual carbon goals constrain factory energy intensity. Chongqing and Kunshan manufacturing clusters produce components for HP and Lenovo export programs.
India
National Education Policy device distribution and PLI scheme incentives redirect supply chain investment toward domestic assembly. BIS compulsory registration blocks uncertified imports and channels volume through Gujarat and Tamil Nadu manufacturing zones.
Germany
Corporate hybrid workforce deployment prioritizes sub-1.2kg Ultrabook specifications with extended battery runtime. EU Ecodesign repairability mandates and REACH substance restrictions govern chassis material selection. Berlin and Munich IT procurement departments standardize on vPro-enabled fleet configurations.
Vietnam
Tariff diversification for US-bound volume accelerates assembly expansion beyond Chinese manufacturing. General customs and investment regulations facilitate foreign OEM facility establishment. Bac Ninh and Hai Phong industrial zones attract laptop component suppliers establishing regional feeder operations.
Global Laptop Market Competitive Environment
Concentration sits with diversified electronics conglomerates that span enterprise, consumer, and education procurement channels. Three to five manufacturers capture dominant commercial share through direct sales organizations and channel depth. Strategic archetypes include vertically integrated silicon-to-system designers, scale ODM partners with global logistics networks, and direct-configuration specialists serving corporate IT departments. Competitive moves center on NPU-enabled product roadmap acceleration and Vietnam assembly expansion for tariff exposure reduction.
Among Asia-Pacific headquartered manufacturers, Lenovo Group and ASUSTek Computer exemplify scale-driven ODM-to-brand evolution, while HP Inc. anchors North American enterprise channel relationships. These three occupy distinct competitive positions: Lenovo represents manufacturing scale with localized SKU proliferation, ASUSTek exemplifies component-to-system vertical control, and HP Inc. sits within direct corporate procurement relationship depth.
| Leading Market Players |
|---|
| Lenovo Group |
| HP Inc. |
| Dell Technologies |
| Apple Inc. |
| ASUSTeK Computer |
| Acer Inc. |
| Microsoft Corporation |
| Samsung Electronics |
| Huawei Technologies |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with Taiwanese ODMs lock in both supply access and price visibility for tier-one manufacturers, insulating enterprise fleet procurement from spot-market volatility in memory and display panel inputs.
Pricing Analysis
Volume-discount tiering structures separate enterprise fleet contracts from retail channel pricing, with Copilot+ PC certification commanding premiums over standard configurations. Price differentiation hinges on NPU silicon inclusion and thermal engineering grade, while cost compression in education-focused Chromebook tiers intensifies due to Google Workspace bundling. Enterprise IT departments exhibit lowest price sensitivity, whereas Indian education procurement shows highest elasticity to unit cost.
Supply Chain Analysis
Inbound logistics costs through the Shanghai-to-Long Beach trade lane fluctuate with container availability and port congestion, compressing margin on US-bound Ultrabook shipments. Manufacturing concentrates in China, Vietnam, and India, with lithium-ion cells, OLED display panels, and x86/ARM processors anchoring component dependencies. Tariff exposure on Chinese-assembled units creates supply chain risk, while distribution runs through direct-to-business configuration centers and retail channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise buyer consolidation through centralized IT procurement departments has shifted negotiating leverage toward volume purchasers with standardized specification requirements.
For Market Incumbents: Fortify direct corporate relationships through configuration lockdown services and asset tagging capabilities. Invest in Vietnam assembly expansion to mitigate tariff exposure on US-bound volume. Deepen thermal engineering talent pipelines through partnerships with Asian ODM engineering teams to defend against cooling-technology commoditization. For New Entrants and Emerging Players: BIS fast-track certification for India domestic assembly creates formal market entry pathways. Target Gujarat and Tamil Nadu manufacturing zones for PLI scheme benefits. Pursue refurbishment certification to access secondary market revenue pools with lower capital intensity than greenfield production. For Investors and Strategic Acquirers: Specialized ODMs with vapor chamber and graphite sheet design expertise represent acquisition targets with scarce technical capabilities. Long-term viability rests on ARM architecture licensing resolution and on-device AI inference standardization. Monitor FCC pre-certification timeline compression as inflection indicator for product launch velocity advantages.| Strategic Initiative | Industry Significance |
|---|---|
| NPU-Enabled Product Roadmap Acceleration | Copilot+ PC certification requirements from Microsoft reshape procurement specifications and margin pools. |
| Vietnam Assembly Footprint Expansion | Bac Ninh and Hai Phong industrial zones attract tariff-diversification investment for US-bound volume. |
| Refurbishment Certification Investment | BIS registration pathways for factory-refurbished units unlock formal secondary market access in India. |
| GaN Power Adapter Integration | Enterprise fleet RFPs increasingly specify gallium nitride adapters for weight and efficiency gains. |
| EU Ecodesign Compliance Program | REACH and repairability mandates force chassis material reformulation and aftermarket service network buildout. |
Study Parameters
The analysis maps Gaming Laptop, Ultrabook, Notebook, and 2-in-1 segments, each validated through procurement directors at enterprise IT departments, ODM engineering leads, and channel distribution partners. Primary interviews with thermal design specialists and regulatory compliance officers combined with secondary validation through FCC equipment authorization databases, EU Ecodesign regulatory filings, and India BIS registration records. Bottom-up unit shipment estimates triangulate against top-down manufacturer revenue disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models product type, end user category, operating system, and form factor dimensions. CAGRs derive from segmented growth rate analysis incorporating enterprise fleet replacement cycle compression, education procurement timing, and consumer upgrade elasticity. Forecast inputs include ARM architecture licensing resolution timelines and NPU silicon allocation cycles.
Decision-makers should treat outputs as directional under base assumptions of sustained enterprise AI PC refresh demand and stable India PLI scheme incentives; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Smart Phones Market
Consumer Electronics
Vertical Ergonomic Optical Mouse Market
Consumer Electronics
Asia-Pacific Mobile Phone Accessories Market
Consumer Electronics
Smartphone Console Market
Consumer Electronics
Asia-Pacific Gaming Keyboard Market
Consumer Electronics
Europe Mobile Phone Accessories Market
Consumer Electronics
Global Home Audio System Market
Consumer Electronics
North America Wireless Anc Headphone Market
Consumer Electronics
PC Accessories Market
Consumer Electronics
Global Polaroid Market
Consumer Electronics
Mechanical Keyboard Market
Consumer Electronics
Europe Refurbished and Used Mobile Phones Market
Consumer Electronics
China Smartphone Market
Consumer Electronics
Mobile Cases and Covers Market
Consumer Electronics
Tattoo Stencil Printer Market
Consumer Electronics
North America Refurbished and Used Mobile Phones Market