
 United States Stylus Pen Market | 2026-2036
United States Stylus Pen Market Size, Share, and Industry Trends Forecast 2026-2036
United States Stylus Pen Market Intelligence
FCC Part 15 regulations for radio-frequency devices is realigning the cost-of-entry calculus for Bluetooth-enabled stylus entrants. Apple leverages its proprietary ecosystem integration to sustain premium positioning across professional workflows. Wacom Co., Ltd. anchors the graphics tablet and stylus segment through decades of pressure-sensitivity expertise. Samsung Electronics competes aggressively in the education sector with bundled S Pen offerings on Galaxy tablets.
A stylus pen is a handheld input device featuring a conductive or pressure-sensitive tip, typically employing electromagnetic resonance or capacitive coupling to register position, tilt, and force on a digitizing surface, engineered for precision annotation, drawing, and navigation on electronic displays. Active stylus variants, distinguished by internal circuitry and Bluetooth connectivity, command the highest margin pools due to their pressure-sensitivity and palm-rejection capabilities, while passive stylus products occupy the volume-driven education segment where cost minimization dominates procurement decisions. Capacitive technology leads unit shipments across consumer applications, though pressure-sensitivity integration is the fastest-growing technical dimension as digital art workflows expand beyond traditional creative professionals.
FCC certification requirements govern wireless transmission protocols, while California Proposition 65 compliance shapes material selection for plastic housings and coatings. OSHA ergonomic guidelines increasingly influence enterprise procurement specifications for prolonged digital annotation tasks. Stakeholders must monitor evolving FCC enforcement patterns around unlicensed spectrum congestion as stylus density per classroom and workplace rises.
Market Dynamics
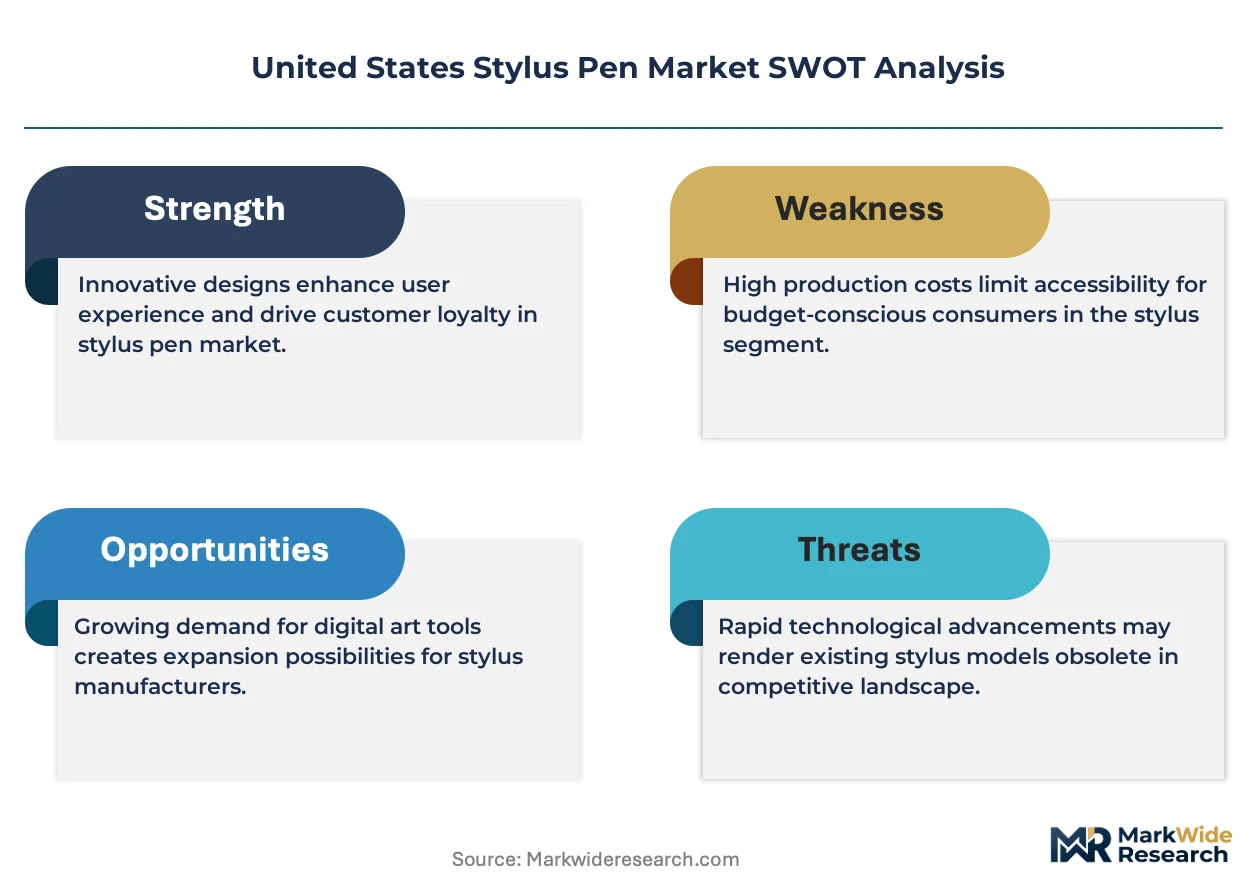
FCC Part 15 electromagnetic compatibility standards are compressing the competitive set for Bluetooth-enabled stylus entrants, while California's creative technology corridor concentrates demand pressure and tilts procurement specifications toward pressure-sensitivity performance tiers.
Growth Catalysts
- OSHA Ergonomic Guidelines:Enterprise procurement specifications for prolonged digital annotation tasks now mandate stylus design features that reduce repetitive strain injuries, expanding addressable volume in corporate training and healthcare documentation verticals.
- Digital Art Workflow Expansion:Professional illustrators and motion graphics studios across Los Angeles and San Francisco are replacing traditional input devices with pressure-sensitive active stylus systems for 3D sculpting and frame-by-frame animation pipelines.
- Education Sector Bundling:K-12 and higher education institutions are standardizing tablet-and-stylus configurations for STEM curricula, with California school districts leading procurement volume for passive stylus products in mathematics and engineering programs.
Market Restraints
- FCC Certification Timeline:Unlicensed spectrum congestion in the 2.4 GHz band is extending electromagnetic compatibility testing cycles for new Bluetooth stylus entrants, compressing product launch windows against seasonal education purchasing calendars.
- Capacitive Touchscreen Commoditization:Passive stylus alternatives lacking pressure sensitivity are capturing price-sensitive volume in consumer and primary education segments, constraining margin expansion for active stylus manufacturers.
- Semiconductor Supply Concentration:Custom ASICs for tilt detection and palm rejection algorithms depend on concentrated foundry capacity in East Asian manufacturing hubs, exposing cost volatility and allocation risk for US-based stylus vendors.
Strategic Opportunities
- Healthcare Documentation Workflows:Electronic health record annotation requirements in Medicare-reimbursed clinical settings are creating specification pull for antimicrobial stylus housings and HIPAA-compliant wireless transmission protocols.
- Texas and New York Creative Corridors:Austin's game development cluster and New York's advertising technology sector represent underpenetrated demand centers where pressure-sensitivity specifications lag California adoption curves by two to three procurement cycles.
- California Proposition 65 Material Innovation:Compliance-driven substitution of bisphenol-A and phthalate-based plastics is opening specification windows for bio-based polymer housings and ceramic composite tips in premium stylus tiers.
Industry Challenges
- Firmware Integration Complexity:Palm rejection algorithms require device-specific calibration across fragmented Android tablet hardware, multiplying engineering validation burden for stylus vendors targeting education sector volume.
- Pressure-Sensitivity Calibration Talent Scarcity:Electromagnetic resonance engineering expertise concentrates within legacy graphics tablet manufacturers, constraining hiring pipelines for emerging stylus entrants competing on tilt and force detection accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Stylus Pen Market |
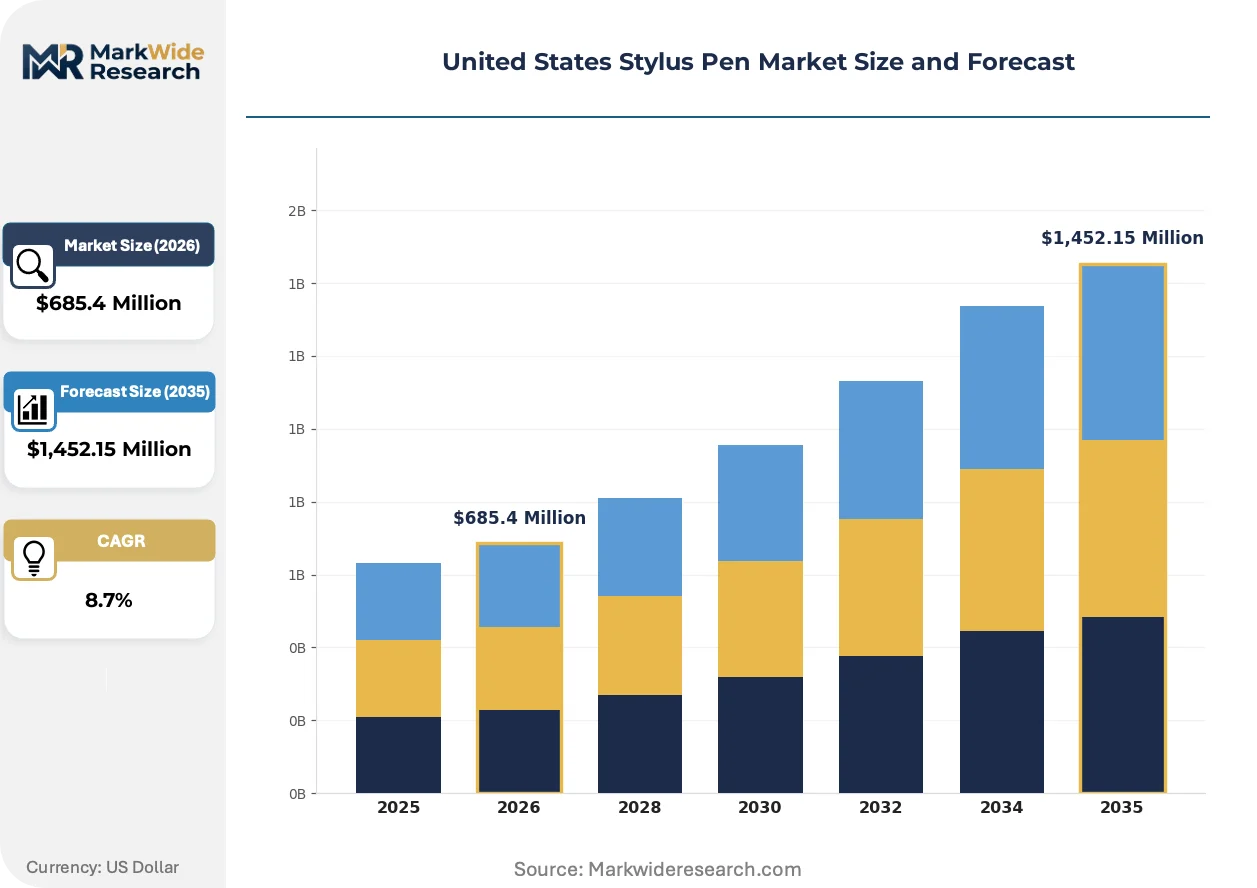
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Stylus, Passive Stylus, Digital Stylus, Graphics Stylus Technology: Capacitive, Resistive, Bluetooth, Pressure Sensitivity Application: Graphic Design, Education, Note-taking, Digital Art End User: Students, Professionals, Artists, Designers |
| Companies Covered | Wacom Co., Ltd., Lenovo Group Limited, Apple Inc., Logitech, HP Inc., Microsoft Corporation, Adonit, ASUSTeK Computer Inc., Samsung Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Stylus Pen Market Strategic Shifts & Innovations
Three vectors are actively restructuring competitive positioning: electromagnetic resonance architectures are compressing latency benchmarks, regulatory material mandates are reshaping housing chemistry, and procurement centralization in large education systems is concentrating vendor selection authority.
Ultra-low latency electromagnetic resonance stacks are rewriting performance expectations for professional digital art workflows. Wacom Co., Ltd.'s decades of pressure-sensitivity expertise has established sub-10 millisecond response benchmarks that professional illustrators now demand from all active stylus entrants. This latency compression is forcing second-tier vendors to license proprietary protocols or exit the premium segment entirely.
FCC Part 15 Subpart B unintentional radiator standards are tightening electromagnetic emission thresholds for classroom density scenarios where fifty-plus Bluetooth stylus devices operate simultaneously. Testing laboratories in California and Texas report extended certification cycles as manufacturers iterate shielding designs to pass radiated emission limits at 3-meter test distances. Education sector procurement committees are now requiring FCC grantee codes in pre-qualification documentation, filtering uncertified imports before competitive bidding.
Enterprise learning management system administrators are consolidating stylus procurement through volume licensing agreements that bundle hardware with software annotation platforms. This centralization is displacing individual teacher purchasing authority and favoring vendors with dedicated K-12 sales organizations and state-level contract vehicles. Texas Education Agency cooperative purchasing agreements illustrate this pattern, where multi-district contracts now cover over 1,200 campuses with standardized active stylus configurations.
United States Stylus Pen Market Segmentation
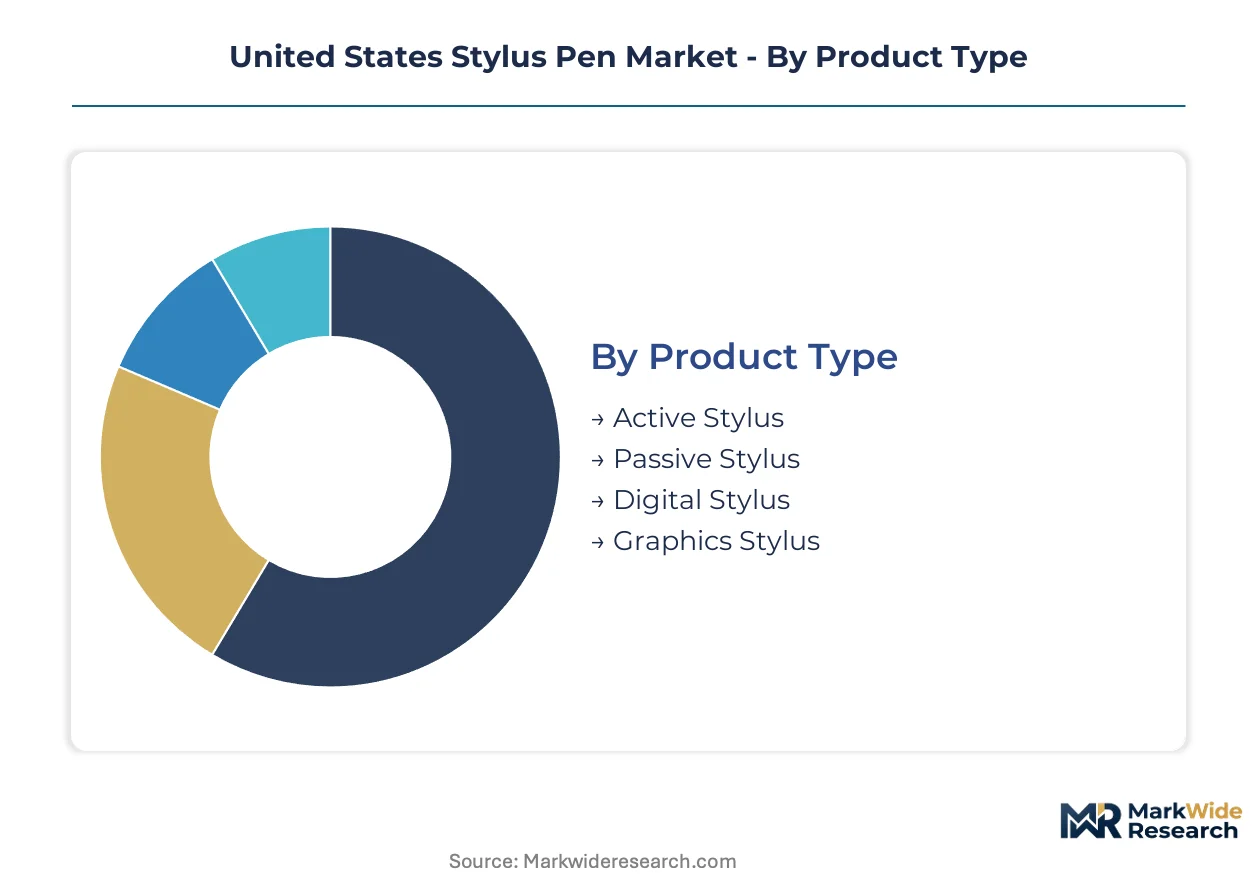
Stylus pen procurement cycles diverge sharply across user archetypes, with professional illustrators replacing active stylus systems every 18-24 months while education bulk purchases stretch replacement intervals to 4-5 years. Understanding these upgrade patterns is essential for aligning inventory planning with revenue recognition timing.
Product Type:
Replacement-cycle timing varies dramatically by product category, with pressure-sensitive active variants commanding premium trade-in values that accelerate refresh decisions among professional users.
- Active Stylus:Internal circuitry enables pressure sensitivity, tilt detection, and palm rejection through Bluetooth connectivity to host devices. Professional illustrators across Los Angeles and San Francisco animation studios drive specification pull for sub-10 millisecond latency and 8,192 pressure levels, though FCC Part 15 certification delays compress product launch windows against seasonal procurement calendars.
- Passive Stylus:Conductive rubber or foam tips operate without internal power, registering touch through capacitive coupling alone. California K-12 districts dominate volume procurement for mathematics and engineering curricula where cost minimization outweighs precision requirements, with bulk purchasing cycles synchronized to fiscal year funding releases.
- Digital Stylus:Hybrid architectures combine electromagnetic resonance positioning with capacitive touch compatibility for cross-platform workflows. Healthcare documentation verticals in Medicare-reimbursed clinical settings specify antimicrobial housings and HIPAA-compliant wireless protocols.
- Graphics Stylus:Specialized electromagnetic resonance stacks optimize for graphics tablet integration with dedicated digitizing surfaces. Motion graphics pipelines in Austin and New York advertising technology sectors represent underpenetrated demand relative to California adoption curves.
Passive Stylus sits at the top of the volume ranking, with Active Stylus climbing the fastest.
Technology:
Cost tier stratification separates premium electromagnetic resonance implementations from commodity capacitive alternatives, with mid-range Bluetooth variants capturing education sector bundling opportunities.
- Capacitive:Registers touch through electrical conductivity between stylus tip and touchscreen digitizer, dominating unit shipments across consumer applications where pressure sensitivity is non-essential. Texas Education Agency cooperative purchasing agreements standardize capacitive configurations for primary STEM curricula.
- Resistive:Mechanical pressure deforms conductive layers to register position, persisting in legacy industrial and healthcare environments where gloved operation is mandatory. Niche demand concentrates in clinical documentation workflows requiring sterilization tolerance.
- Bluetooth:Wireless protocol integration enables advanced features including customizable shortcut buttons, battery level monitoring, and firmware updates. FCC electromagnetic compatibility testing for 2.4 GHz band congestion in classroom density scenarios extends certification timelines for new entrants.
- Pressure Sensitivity:Force detection through electromagnetic resonance or strain gauge architectures commands the highest margin pools as digital art workflows expand beyond traditional creative professionals. Wacom Co., Ltd. proprietary protocols establish calibration benchmarks that constrain hiring pipelines for emerging vendors.
Capacitive technology maintains volume leadership, while Pressure Sensitivity expands most quickly as professional specifications migrate downstream.
Application:
Customer type differentiation separates enterprise learning management system procurement from individual creator purchasing, with institutional buyers consolidating authority through multi-campus volume agreements.
- Graphic Design:Frame-by-frame animation and 3D sculpting pipelines demand tilt detection accuracy and sub-10 millisecond latency. New York advertising technology sector procurement cycles lag Los Angeles and San Francisco by two to three refresh intervals.
- Education:K-12 and higher education institutions standardize tablet-and-stylus configurations, with California school districts leading procurement volume for passive products in mathematics programs. Centralized purchasing through state contract vehicles displaces individual teacher authority.
- Note-taking:Enterprise training and corporate documentation verticals mandate OSHA ergonomic guidelines compliance for prolonged annotation tasks. Healthcare electronic health record annotation creates specification pull for antimicrobial housings.
- Digital Art:Professional illustrators and motion graphics studios replace traditional input devices with pressure-sensitive active systems. Austin game development cluster demand represents geographic expansion beyond California creative technology corridor concentration.
Education commands the largest installed base, with Digital Art posting the steepest expansion trajectory as professional workflows proliferate.
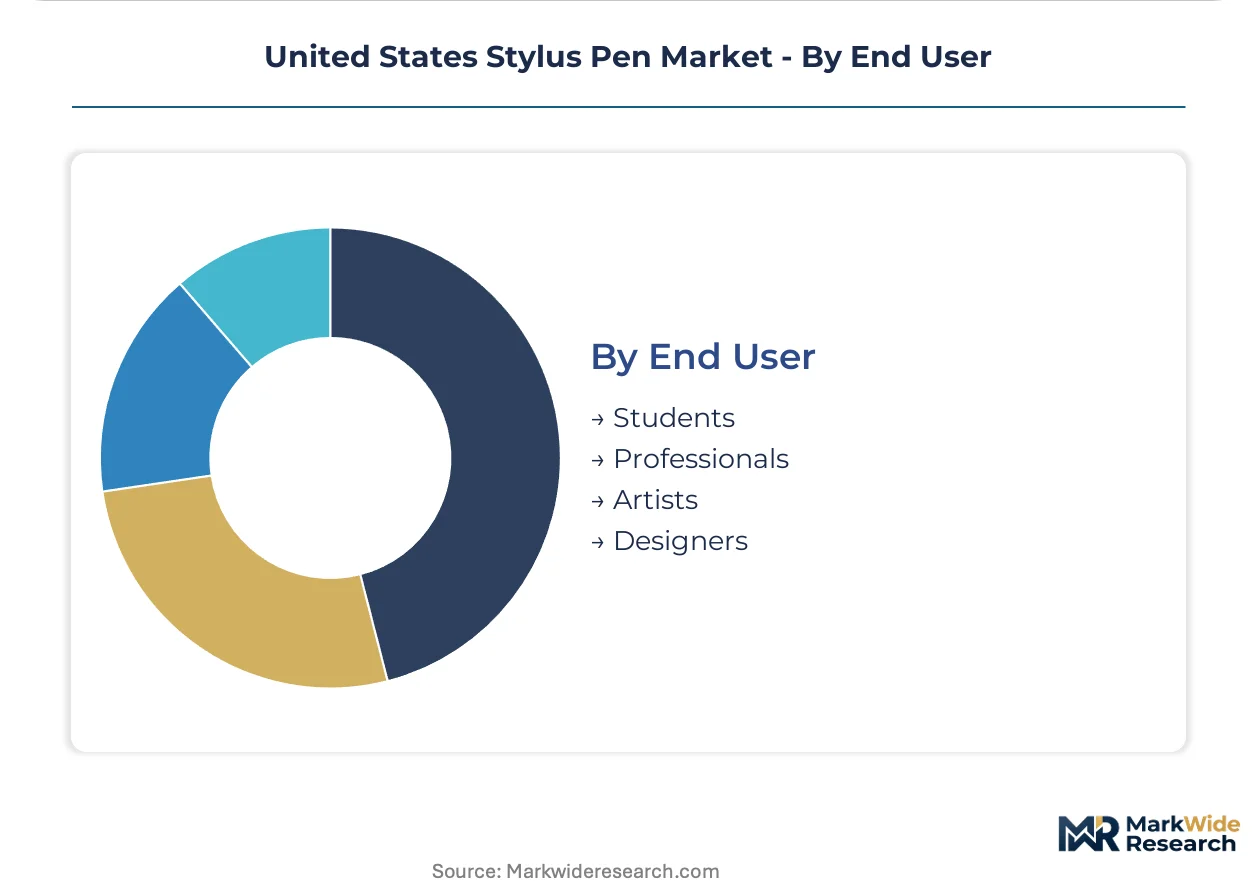
End User:
Margin structure inverts across user categories, with individual professionals accepting premium pricing for performance differentiation while institutional buyers extract volume discounts that compress vendor profitability.
- Students:Price-sensitive demand concentrates in bundled tablet-and-stylus configurations through education sector procurement. California Proposition 65 compliance shapes material selection for plastic housings in youth-facing products.
- Professionals:Corporate training and healthcare documentation workflows specify OSHA ergonomic features and HIPAA-compliant wireless protocols. Enterprise learning management system administrators consolidate purchasing authority.
- Artists:Professional illustrators demand electromagnetic resonance expertise for pressure-sensitivity calibration accuracy. Talent scarcity for tilt detection engineering constrains vendor hiring pipelines.
- Designers:Motion graphics and advertising technology professionals drive specification pull for latency compression and cross-platform compatibility. Texas and New York creative corridors lag California adoption curves.
Students represent the largest addressable population, with Professionals gaining share fastest as enterprise documentation workflows standardize stylus-based input.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electromagnetic resonance engineers and pressure-sensitivity calibration specialists concentrate along California's creative technology corridor, anchoring professional-grade stylus development clusters in Los Angeles and San Francisco.
California
Professional illustrators and motion graphics studios drive specification pull for sub-10 millisecond latency and 8,192 pressure levels across Los Angeles and San Francisco. FCC Part 15 electromagnetic compatibility standards govern Bluetooth-enabled active stylus certification timelines for classroom density scenarios. The creative technology corridor tilts procurement specifications toward premium pressure-sensitivity performance tiers.
Texas
Austin's game development cluster and Dallas-Fort Worth education technology procurement offices generate underpenetrated demand relative to California adoption curves. Texas Education Agency cooperative purchasing agreements consolidate multi-district contracts covering over 1,200 campuses with standardized active stylus configurations. Dallas-area testing laboratories report extended FCC certification cycles for shielding design iterations.
New York
Advertising technology professionals and corporate training administrators in Manhattan and Brooklyn lag California procurement cycles by two to three refresh intervals. OSHA ergonomic guidelines influence enterprise specifications for prolonged digital annotation tasks in financial services documentation workflows. The metropolitan area's healthcare systems specify antimicrobial stylus housings for electronic health record annotation.
Washington
Seattle-area technology hardware ecosystems and Redmond-based enterprise software procurement offices shape cross-platform compatibility requirements. FCC enforcement patterns around unlicensed spectrum congestion receive close attention from Pacific Northwest education technology vendors. The region's STEM-focused school districts pilot pressure-sensitive active stylus deployments in mathematics and engineering curricula.
Illinois
Chicago healthcare documentation systems and Midwest manufacturing training centers generate demand for HIPAA-compliant wireless transmission protocols. OSHA ergonomic specifications penetrate slower than coastal markets due to fragmented procurement authority across municipal and county health systems. The metropolitan area's community college networks represent emerging volume opportunities for bundled tablet-and-stylus configurations.
United States Stylus Pen Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions, with ecosystem-integrated technology platforms commanding premium positioning while component specialists capture education sector volume. The vendor set stratifies into three archetypes: proprietary ecosystem owners leveraging hardware-software integration, graphics tablet heritage manufacturers anchoring professional pressure-sensitivity standards, and third-party peripheral vendors competing on cross-platform compatibility. Competitive moves concentrate on M&A for electromagnetic resonance engineering talent and strategic partnerships with education procurement systems.
Within the ecosystem-integrated tier, Apple Inc. and Microsoft Corporation exemplify platform-centric positioning that binds stylus functionality to proprietary operating environments. Samsung Electronics occupies a position bridging consumer electronics scale with bundled S Pen offerings. Wacom Co., Ltd. anchors the professional graphics segment through decades of pressure-sensitivity expertise that establishes calibration benchmarks constraining competitor hiring pipelines. These three entities represent the dominant competitive anchors shaping specification standards across professional and education verticals.
| Leading Market Players |
|---|
| Wacom Co., Ltd. |
| Lenovo Group Limited |
| Apple Inc. |
| Logitech |
| HP Inc. |
| Microsoft Corporation |
| Adonit |
| ASUSTeK Computer Inc. |
| Samsung Electronics |
| Others |
Cost & Logistics Intelligence
California Proposition 65 compliance mandates for bisphenol-A and phthalate-free housings gate qualified supply access for premium-tier stylus vendors, compressing margins for uncertified imports while enabling compliant manufacturers to command sustained price premiums across education and healthcare procurement channels.
Pricing Analysis
The bundled-vs-unbundled service split separates education sector volume contracts from professional direct sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by pressure-sensitivity calibration accuracy and FCC certification status. Cost compression in passive stylus tiers intensifies because capacitive touchscreen commoditization erodes differentiation. Education procurement committees exhibit highest price sensitivity, while professional illustrators accept premium positioning for sub-10 millisecond latency performance.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for custom ASICs governing tilt detection and palm rejection algorithms. Electromagnetic resonance sensor arrays draw from Japanese precision component manufacturers, while plastic housing production rests on mainland China molding capacity. Tariff exposure on Chinese-manufactured passive stylus products threatens margin structures for education-focused vendors. Distribution runs through California-based testing laboratories for FCC Part 15 certification, then onward to state-level education cooperative purchasing agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States stylus pen market functions as a stable compounder, with digital art workflow standardization across professional animation studios delivering predictable replacement-cycle revenue visibility.
For Market Incumbents: Acquire electromagnetic resonance engineering talent pools to defend calibration expertise moats against emerging Bluetooth-enabled entrants. Deepen backward integration into custom ASIC design to reduce foundry allocation risk exposure. Prioritize FCC pre-certification investments to compress product launch windows against seasonal education purchasing calendars. For New Entrants and Emerging Players: Education technology distributors represent the most accessible channel pathway for unbundled passive stylus volume. Texas and New York creative corridors offer white-space demand with procurement specifications lagging California curves. Target healthcare documentation verticals with antimicrobial housing specifications as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for specialized electromagnetic resonance component suppliers because professional-grade calibration expertise concentrates within legacy graphics tablet heritage manufacturers. Five-to-ten year viability hinges on pressure-sensitivity specification migration from professional to prosumer tiers. Monitor FCC enforcement patterns around unlicensed spectrum congestion as the signal for classroom density saturation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Electromagnetic Resonance Specialist | Secures scarce calibration engineering talent pools anchoring professional-grade product tiers. |
| FCC Pre-Certification Investment | Compresses launch timelines against seasonal education procurement funding cycles. |
| Antimicrobial Housing Development | Unlocks Medicare-reimbursed clinical documentation specification requirements. |
| Education Cooperative Purchasing Partnership | Captures volume licensing authority displacing individual teacher decision-making. |
| Bio-Based Polymer Material Transition | Aligns with California Proposition 65 compliance mandates reshaping housing chemistry. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with stylus product managers, FCC testing laboratory directors, education procurement officers, and professional digital art directors with secondary validation against FCC grantee code databases, SEC 10-K filings of diversified electronics manufacturers, Texas Education Agency cooperative purchasing records, and California school district procurement disclosures. Bottom-up shipment estimates triangulated against top-down addressable device calculations.
Segment-weighting across product type, technology architecture, application vertical, and end-user category drove forecast construction over the projection horizon. Active stylus, passive stylus, digital stylus, and graphics stylus categories each carried distinct replacement-cycle assumptions. Capacitive, resistive, Bluetooth, and pressure-sensitivity technologies were modeled with divergent margin trajectories. CAGR derivation incorporated professional illustrator refresh intervals, education bulk purchase cycles, and healthcare documentation adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FCC regulatory shifts, foundry capacity allocation disruptions, and unlicensed spectrum congestion enforcement patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Consumer Electronics Electric Motor Market
Consumer Electronics
Consumer Electronic Accessories Market
Consumer Electronics
Vibrating Alarm Clock Market
Consumer Electronics
4K Television Market
Consumer Electronics
Education PC Market
Consumer Electronics
Ultraman Peripheral Market
Consumer Electronics
Tattoo Machine Market
Consumer Electronics
North America Refurbished and Used Mobile Phones Market
Consumer Electronics
Professional Headset Market
Consumer Electronics
Global Digital Watch Market
Consumer Electronics
Electric Water Bottle Market
Consumer Electronics
Wrist Dive Computer Market
Consumer Electronics
Vape Market
Consumer Electronics
Portable Speaker Market
Consumer Electronics
Asia-Pacific Professional Audio-Visual Systems Market
Consumer Electronics
Computing Mouse Market