
 Mobile Pet Care Market | 2026-2036
Mobile Pet Care Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Pet Care Market Analysis
The price-performance gap between premium white-glove mobile services and commodity van-based operators is hardening across urban and suburban markets. My Pet Mobile Vet leverages proprietary scheduling infrastructure to sustain premium positioning in dense metropolitan corridors. Blue Wheelers competes on volume through standardized grooming packages across Australian metro regions. HousePaws Mobile Veterinary Service anchors its model on specialist veterinary equipment within purpose-built mobile units.
Mobile pet care encompasses on-demand health, grooming, and behavioral services delivered via modified vehicles equipped with veterinary-grade anesthesia machines, hydraulic grooming tables, and climate-controlled holding compartments. These units function as distributed clinical and salon infrastructure, eliminating transit stress for animals while capturing revenue from time-constrained owners. Grooming and veterinary service types occupy the dominant revenue share due to recurring appointment cycles and insurance reimbursement eligibility. Telemedicine and GPS tracking technologies are expanding fastest, enabling real-time dispatch optimization and remote diagnostic triage that compresses labor idle time. Pet owners as a customer type generate the deepest margin pools, while corporate client contracts provide volume stability with lower per-visit yields.
The US FDA and state veterinary medical boards govern pharmaceutical dispensing and telemedicine prescription authority within mobile veterinary units, creating compliance costs that favor scaled operators with dedicated regulatory staff. OSHA workplace safety standards and DOT commercial vehicle regulations shape vehicle modification requirements and driver certification protocols across service fleets. Stakeholders must monitor evolving telehealth parity legislation and municipal permitting frameworks that could either accelerate or constrain route density in protected residential zones.
Market Dynamics
Telemedicine integration is compressing appointment cycles and expanding service radii for mobile veterinary fleets, while municipal zoning in dense metropolitan corridors constrains overnight vehicle storage and route density optimization.
Growth Catalysts
- Telehealth parity legislation:State-level mandates in the United States are expanding reimbursement eligibility for remote diagnostic triage, accelerating fleet deployment into suburban corridors with limited brick-and-mortar infrastructure.
- Urban pet density:High-rise residential concentration in metropolitan cores generates concentrated demand for stress-reducing at-home services, eliminating owner transit time and capturing premium pricing.
- GPS-enabled dispatch platforms:Real-time route optimization algorithms are compressing labor idle time between appointments, improving unit economics for scaled operators with multi-vehicle fleets.
Market Restraints
- DOT commercial vehicle regulations:Federal mandates governing modified vehicle weight classifications and driver certification protocols impose compliance costs that disproportionately burden single-unit operators.
- Veterinary pharmaceutical dispensing authority:State veterinary medical boards restrict controlled substance transport and prescription issuance from mobile units, limiting service scope compared to stationary clinics.
- Climate-controlled holding compartment costs:Specialized HVAC and anesthesia machine installations require capital outlays that extend payback periods for fleet expansion.
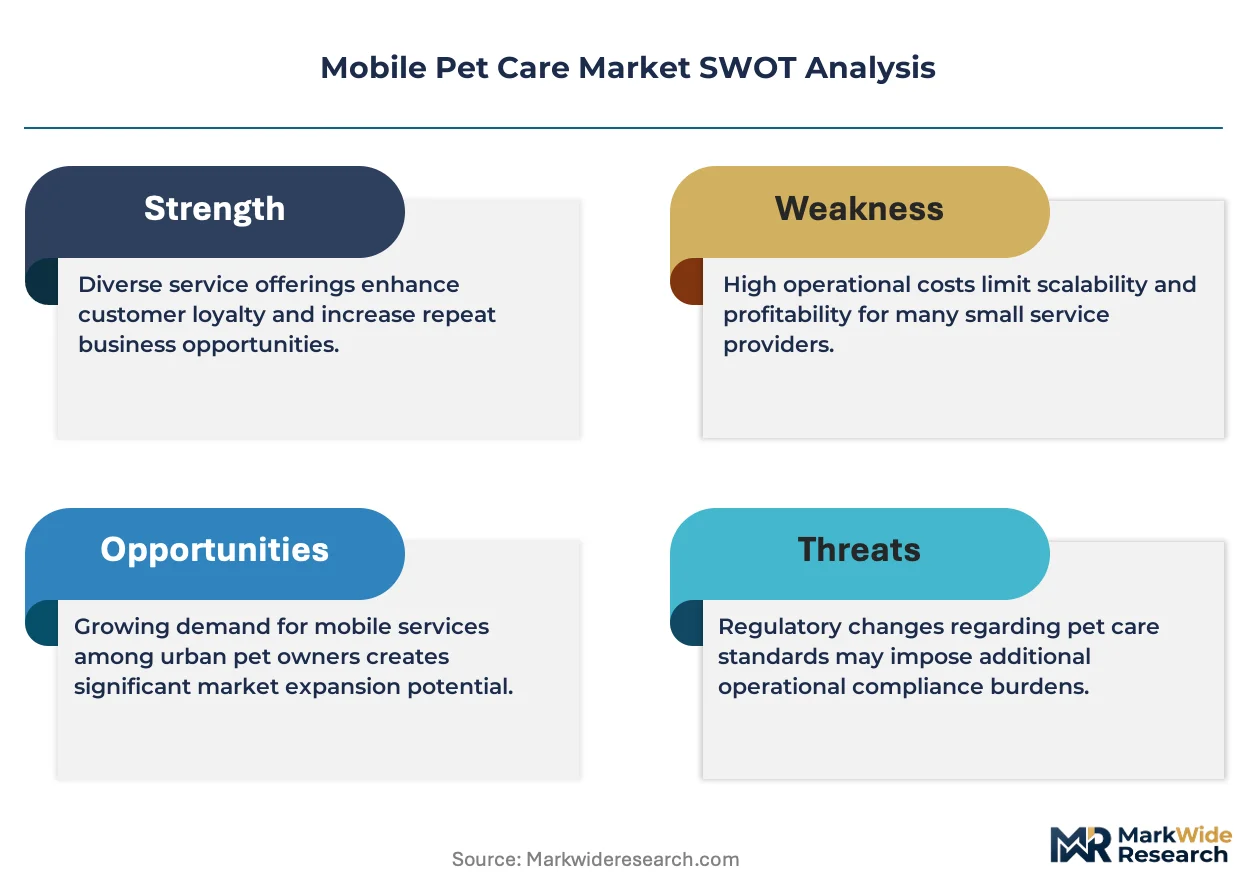
Strategic Opportunities
- Behavioral service integration:Mobile units equipped with training apparatus and certified behaviorists can capture recurring revenue from anxiety-prone breeds underserved by stationary facilities.
- Corporate client contracts:Employer-sponsored pet wellness programs offer volume stability with multi-year terms, insulating operators from consumer discretionary volatility.
- Municipal permitting framework liberalization:Zoning reforms in protected residential zones could unlock overnight vehicle storage and reduce deadhead mileage for route-dense operations.
Industry Challenges
- Licensed veterinary technician scarcity:Mobile service models require dual-competency staff capable of clinical procedures and commercial vehicle operation, constraining hiring pools.
- Equipment standardization delays:Absence of unified veterinary-grade anesthesia machine specifications for modified vehicles complicates multi-vendor fleet procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Pet Care Market |
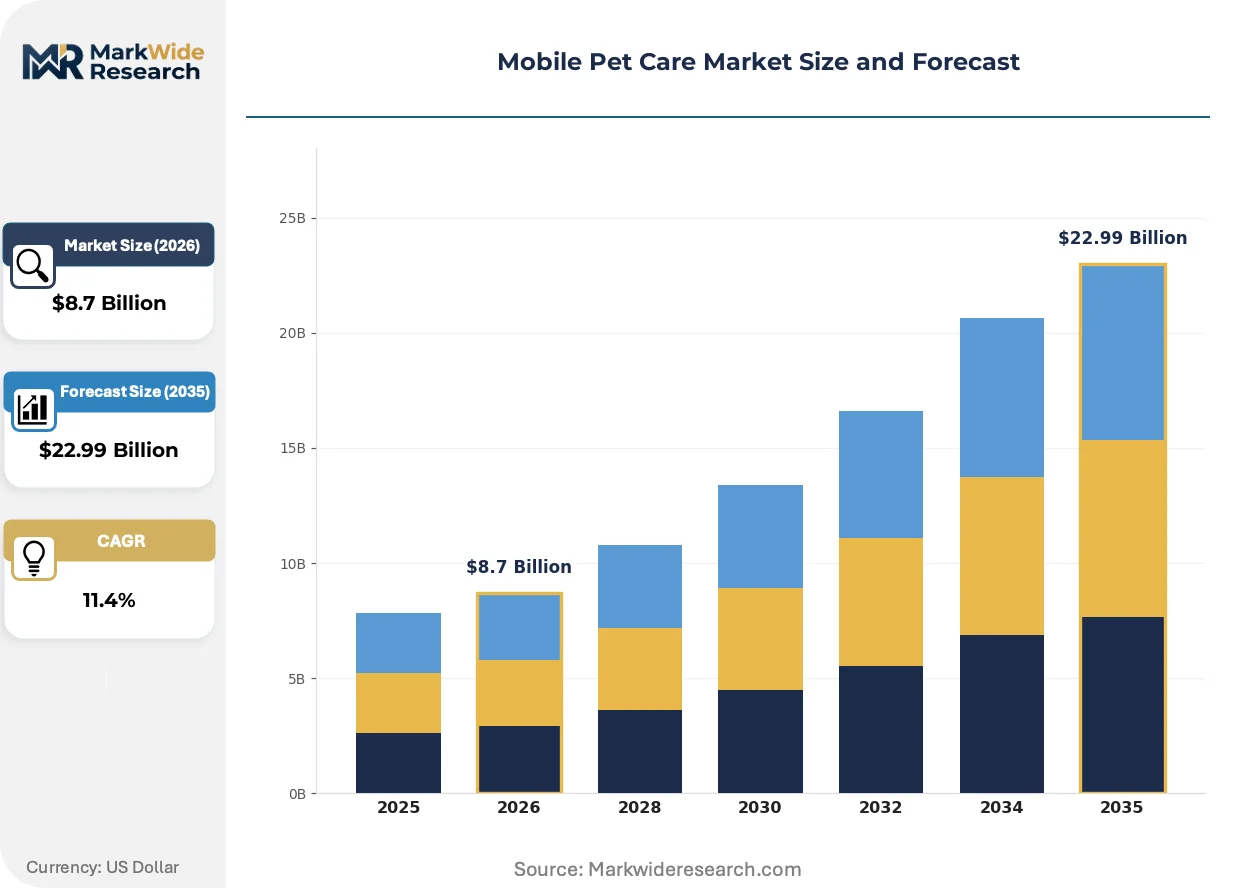
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Grooming, Veterinary, Training, Pet Sitting Customer Type: Pet Owners, Corporate Clients, Shelters, Breeders Vehicle Type: Vans, Trucks, Trailers, Mobile Units Technology: Telemedicine, GPS Tracking, Scheduling Apps, Online Payments |
| Companies Covered | 4 Paws Mobile Spa, My Pet Mobile Vet, Blue Wheelers, Woofie's Pet Ventures, Aussie Mobile Vet Pty Ltd, HousePaws Mobile Veterinary Service, Dial a Dog Wash Ltd, Mobile Pet Vet, LLC, La Boit Specialty Vehicles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Pet Care Market Emerging Trajectories
Service delivery models are bifurcating between technology-heavy telemedicine platforms and equipment-intensive mobile clinics, with GPS tracking and remote diagnostics compressing the coordination layer between dispatch and field units.
Telemedicine integration is electrifying diagnostic workflows by enabling real-time specialist consultation during field appointments. Suburban veterinary networks are adopting remote triage protocols at accelerating pace. This convergence is compressing specialist referral timelines and expanding service scope for generalist mobile units.
State veterinary medical boards are tightening pharmaceutical dispensing protocols for controlled substances transported in commercial vehicles. Mobile operators must maintain dual inventory tracking systems and secure storage compartments. Fleet-scale providers with dedicated compliance staff are absorbing these costs more efficiently than independent practitioners.
Subscription-based wellness plans are displacing transactional appointment booking among time-constrained professionals in dense metropolitan corridors. Corporate benefits administrators are negotiating group rates that bundle preventive care with behavioral consultations. This shift is most visible in United States coastal cities where employer-sponsored pet benefits have achieved critical penetration.
Mobile Pet Care Market Segmentation
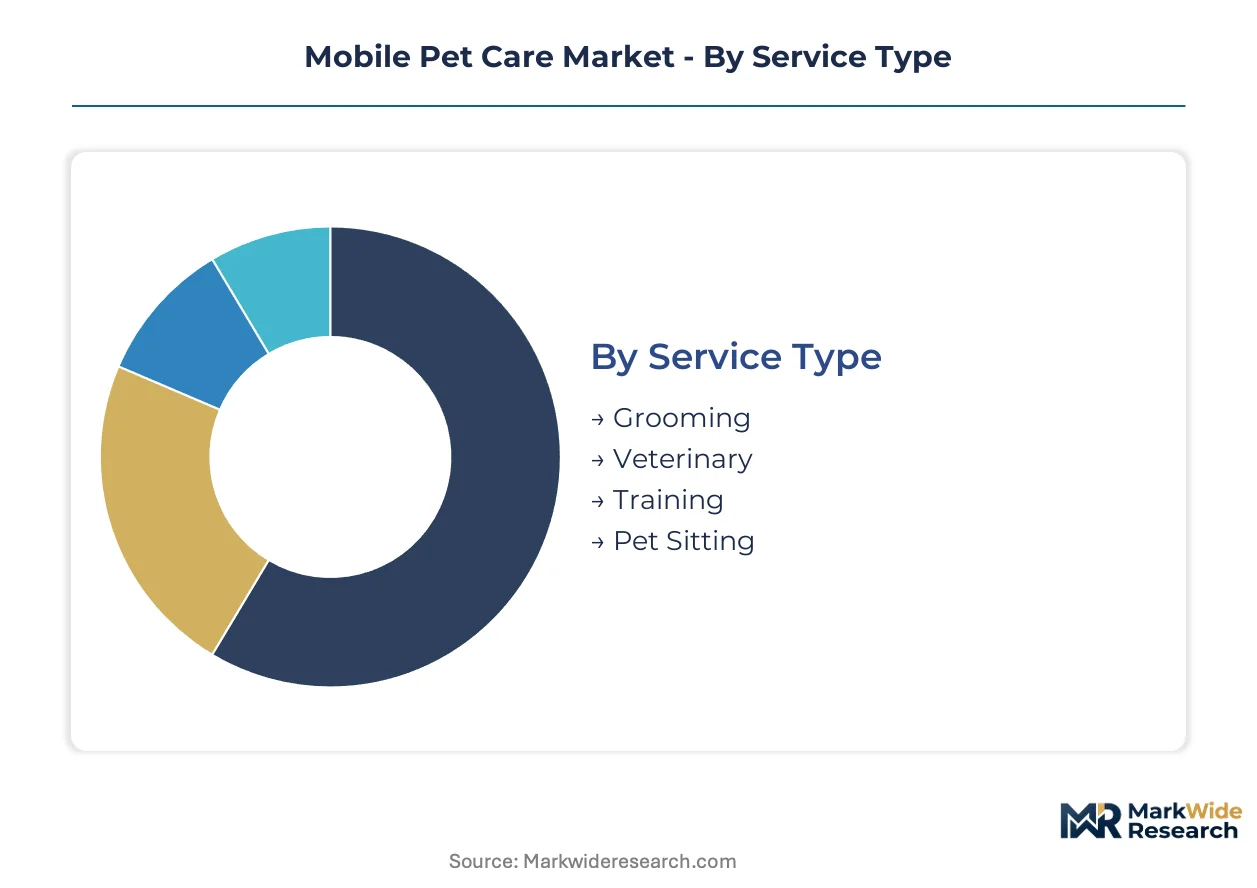
Mobile pet care operators configure service portfolios around capital intensity, regulatory exposure, and route density economics. Segment selection determines vehicle modification requirements, staffing competencies, and reimbursement eligibility across metropolitan and suburban corridors.
Service Type:
Veterinary and grooming services demand the heaviest upfront capital outlays for specialized equipment and climate-controlled vehicle modifications.
- Veterinary:Purpose-built mobile units carry anesthesia machines, digital radiography systems, and surgical suites that require FDA-compliant pharmaceutical storage and state board certification. Demand concentrates in United States suburban corridors where brick-and-mortar clinic density remains thin and telemedicine parity legislation expands reimbursement eligibility for remote diagnostic triage.
- Grooming:Hydraulic grooming tables, high-velocity dryers, and water reclamation systems dominate vehicle fit-outs, with recurring appointment cycles generating predictable revenue streams. Australian metro regions show concentrated adoption through standardized package offerings that compete on volume rather than premium positioning.
- Training:Lower equipment barriers favor behavioral specialists operating from modified vans with portable training apparatus and anxiety-reduction environments.
- Pet Sitting:Minimal capital requirements enable rapid market entry through unmodified personal vehicles and smartphone dispatch platforms.
Most installed capacity flows through Veterinary. Expansion is steepest in Training as anxiety-prone breeds drive demand for at-home behavioral intervention.
Customer Type:
Margin profiles diverge sharply between individual consumers seeking convenience and institutional buyers negotiating multi-year volume commitments.
- Pet Owners:Time-constrained professionals in dense metropolitan corridors generate the deepest margin pools through subscription-based wellness plans and premium white-glove service tiers. United States coastal cities exhibit the highest plan penetration where employer-sponsored pet benefits have achieved critical mass.
- Corporate Clients:Employer-sponsored pet wellness programs deliver volume stability with lower per-visit yields, insulating operators from consumer discretionary volatility through multi-year contractual terms.
- Shelters:Municipal and nonprofit contracts prioritize cost efficiency over service breadth, favoring scaled operators with dedicated regulatory staff.
- Breeders:Specialized reproductive health and neonatal care requirements demand veterinary-grade mobile units with controlled substance transport authority.
Revenue concentration tilts toward Pet Owners. Corporate Client contracts are climbing fastest as benefits administrators bundle preventive care with behavioral consultations.
Vehicle Type:
Chassis selection governs payload capacity, route flexibility, and overnight storage compliance under municipal zoning frameworks.
- Vans:Compact footprints navigate high-density metropolitan cores where parking constraints and residential zoning restrict larger vehicle deployment. DOT commercial vehicle regulations impose driver certification protocols that disproportionately burden single-unit operators.
- Trucks:Heavy-duty platforms accommodate comprehensive veterinary surgical suites and multiple holding compartments, extending service radii into suburban corridors with limited infrastructure.
- Trailers:Detachable units enable overnight storage separation from towing vehicles, circumventing municipal restrictions on commercial vehicle parking in protected residential zones.
- Mobile Units:Purpose-built chassis integrate climate-controlled holding compartments and specialized HVAC systems requiring capital outlays that extend fleet expansion payback periods.
Deployment concentrates in Vans. Trailer configurations are expanding most quickly where zoning reforms unlock overnight storage flexibility.
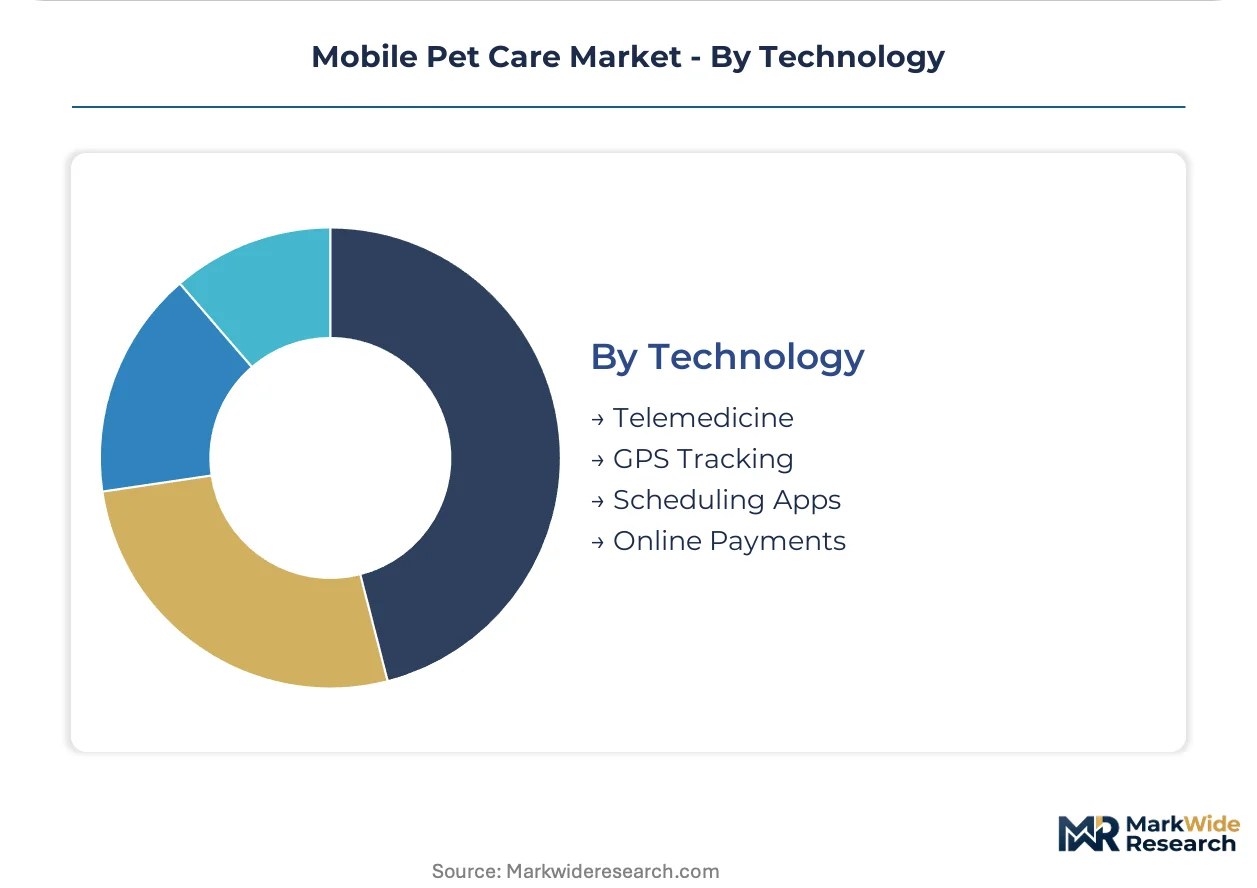
Technology:
Digital infrastructure investments separate scaled multi-vehicle fleets from independent practitioners on coordination efficiency and labor utilization.
- Telemedicine:Real-time specialist consultation and remote diagnostic triage compress referral timelines while expanding service scope for generalist mobile units. State veterinary medical boards govern prescription authority, creating compliance costs that favor operators with dedicated regulatory staff.
- GPS Tracking:Route optimization algorithms compress labor idle time between appointments, improving unit economics for fleet operators with density-sufficient appointment volumes.
- Scheduling Apps:Proprietary platforms enable dynamic appointment clustering and cancellation backfill that sustain premium positioning in competitive metropolitan corridors.
- Online Payments:Subscription billing integration supports wellness plan enrollment and automated recurring revenue capture.
GPS Tracking commands the widest deployment. Telemedicine is gaining share fastest as suburban veterinary networks accelerate remote triage protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Veterinary technician concentrations and mobile fleet operator density cluster in metropolitan corridors with thin brick-and-mortar infrastructure and elevated pet ownership rates.
United States
Suburban sprawl around Dallas-Fort Worth and Phoenix generates concentrated demand for at-home veterinary services. The FDA and state veterinary medical boards govern pharmaceutical dispensing authority for mobile units. Fleet operators in Texas and Arizona deploy purpose-built vehicles with surgical suites into exurban zones lacking stationary clinic access.
Australia
Metropolitan pet density in Sydney and Melbourne accelerates adoption of standardized grooming packages delivered via van-based fleets. The TGA regulates veterinary pharmaceutical transport and storage protocols for commercial vehicles. Blue Wheelers anchors volume-driven operations across Australian capital cities with route-optimized dispatch infrastructure.
United Kingdom
Time-constrained professionals in Greater London drive subscription wellness plan penetration for mobile grooming and veterinary triage. The country's national veterinary regulator enforces controlled substance tracking requirements for mobile dispensing. Dial a Dog Wash operates across British suburban corridors with hydraulic grooming table installations in compact van configurations.
Germany
Employer-sponsored pet benefits in Munich and Frankfurt corporate clusters expand corporate client contract volumes. The KBA governs commercial vehicle modification standards for mobile veterinary units. Specialized fabricators in Bavaria supply climate-controlled chassis to regional fleet operators serving high-rise residential concentrations.
Canada
Veterinary service gaps across Ontario and British Columbia exurbs accelerate telemedicine-integrated mobile fleet deployment. Health Canada regulates pharmaceutical storage and prescription authority within modified commercial vehicles. Operators in Toronto and Vancouver corridors leverage GPS-enabled dispatch to compress deadhead mileage between scattered suburban appointments.
Mobile Pet Care Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across bifurcated service tiers. Purpose-built mobile unit fabricators and multi-vehicle fleet operators occupy distinct competitive strata from independent practitioners operating single-van grooming services. Three archetypes dominate: premium white-glove specialists with proprietary scheduling infrastructure, volume-driven standardized package providers, and equipment-intensive veterinary surgical unit operators. Competitive moves concentrate on fleet expansion through vehicle procurement partnerships and geographic densification via route optimization technology licensing.
Within the premium-tier segment, My Pet Mobile Vet and HousePaws Mobile Veterinary Service exemplify divergent capital deployment strategies. My Pet Mobile Vet anchors proprietary scheduling infrastructure sustaining premium positioning in dense metropolitan corridors. HousePaws occupies the equipment-intensive archetype with specialist veterinary configurations in purpose-built mobile units. Blue Wheelers represents the volume-driven standardized model competing across Australian metro regions through package commoditization and route density optimization.
| Leading Market Players |
|---|
| 4 Paws Mobile Spa |
| My Pet Mobile Vet |
| Blue Wheelers |
| Woofie's Pet Ventures |
| Aussie Mobile Vet Pty Ltd |
| HousePaws Mobile Veterinary Service |
| Dial a Dog Wash Ltd |
| Mobile Pet Vet, LLC |
| La Boit Specialty Vehicles |
| Others |
Supply Flow & Price Mechanics
Climate-controlled HVAC systems and veterinary-grade anesthesia machines anchor capital outlays for mobile unit fabricators, compressing margins for fleet operators who must recover equipment costs through subscription wellness plans or premium per-visit pricing in dense metropolitan corridors.
Pricing Analysis
Bundled subscription wellness plans displace unbundled transactional appointments among time-constrained professionals in United States coastal cities. Three-tier pricing structure across premium white-glove, standardized package, and economy van-based tiers separates My Pet Mobile Vet's proprietary scheduling infrastructure from Blue Wheelers' volume-driven Australian operations. Price differentiation hinges on telemedicine integration depth and climate-controlled surgical suite certification. Pricing pressure stems from DOT commercial vehicle regulations that disproportionately burden single-unit operators with compliance costs. Corporate client contracts exhibit lowest price sensitivity through multi-year employer-sponsored pet benefit terms, while individual pet owners in suburban corridors show highest elasticity to per-visit rates.
Supply Chain Analysis
Regional distribution centers for modified vehicle chassis cluster in Bavaria, Texas, and Ontario, feeding hub-and-spoke patterns into metropolitan fleet depots. Component fabrication draws from Germany's KBA-certified specialty vehicle builders, United States DOT-compliant modification shops, and Canadian Health Canada-regulated pharmaceutical storage installers. Raw material dependencies center on aluminum alloy chassis, medical-grade stainless steel surgical surfaces, and precision HVAC compressor units. Supply chain risk concentrates in single-source vulnerability for veterinary-grade anesthesia machines lacking unified specifications across multi-vendor procurement. Distribution runs through fleet operator direct procurement and third-party vehicle leasing channels serving independent practitioners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile pet care market functions as a stable compounder where recurring subscription revenue from wellness plans generates predictable cash flows insulated from consumer discretionary volatility.
For Market Incumbents: Lock in route density advantages through GPS-enabled dispatch platform licensing to independent practitioners, converting competitive threats into revenue-sharing partners. Deepen backward integration into purpose-built mobile unit fabrication through exclusive partnerships with KBA-certified German chassis suppliers, capturing margin pools currently flowing to third-party modifiers. Defend against telemedicine-enabled new entrants by embedding remote diagnostic triage into existing proprietary scheduling infrastructure.
For New Entrants and Emerging Players: Telehealth parity legislation in Texas and Arizona opens a window for veterinary service models targeting exurban zones lacking brick-and-mortar clinic infrastructure. Behavioral service integration represents the most penetrable white-space segment, with anxiety-prone breed demand underserved by equipment-intensive surgical unit operators. Corporate client contracts offer the clearest go-to-market angle through employer-sponsored pet wellness program pitches to benefits administrators in United States coastal cities.
For Investors and Strategic Acquirers: Consolidation pressure builds where single-unit operators face disproportionate DOT compliance costs and licensed veterinary technician scarcity constrains expansion. The mobile pet care market sustains long-term viability through demographic tailwinds in urban pet density and employer benefit program penetration. Acquisition targets should display fleet-scale regulatory staff and multi-vehicle route optimization technology. Watch telemedicine prescription authority liberalization by state veterinary medical boards as the critical inflection signal for service scope expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Platform Integration | Compresses specialist referral timelines while expanding generalist mobile unit service scope through FDA-compliant remote diagnostic protocols. |
| Route Optimization Technology Licensing | Converts competitive independent operators into revenue-sharing partners while densifying metropolitan appointment clustering. |
| Corporate Wellness Contract Expansion | Insulates revenue from consumer discretionary volatility through multi-year employer-sponsored pet benefit terms. |
| Backward Integration into Chassis Fabrication | Captures margin pools from KBA-certified German and DOT-compliant United States specialty vehicle builders. |
| Behavioral Service Capability Buildout | Addresses anxiety-prone breed demand underserved by equipment-intensive veterinary surgical unit operators. |
Methodological Framework
Multiple input streams — fleet operator financial disclosures, state veterinary medical board regulatory filings, and municipal zoning ordinance databases — were reconciled against primary interviews with mobile unit fabricators, fleet operations directors, and corporate benefits administrators. Secondary validation drew from DOT commercial vehicle regulation updates, FDA veterinary pharmaceutical dispensing guidance, and telemedicine parity legislation tracking across United States state legislatures. Bottom-up service volume estimates and top-down market sizing approaches were triangulated to constrain projection variance.
Cross-referencing historical fleet deployment patterns against panel input from veterinary practice management consultants shaped the analytical framework across the analysis window. Segmentation dimensions modeled encompass service type capital intensity, customer type margin profiles, vehicle type payload classifications, and technology integration tiers. CAGRs were derived through logistic diffusion curves for telemedicine adoption and linear extrapolation for grooming service recurrence rates. Forecast inputs incorporated veterinary technician labor pool constraints and municipal parking regulation liberalization scenarios.
Revisions become necessary when state veterinary medical boards tighten controlled substance transport protocols or municipal zoning frameworks shift overnight vehicle storage permissions. Forecasts reflect assumptions about telehealth parity legislation expansion and employer-sponsored pet benefit penetration rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Pad Market
Pet Care Products
Smart Pet Leash Market
Pet Care Products
India Pet Food Market
Pet Care Products
China Pet Clothing Market
Pet Care Products
Automatic and Smart Pet Feeder Market
Pet Care Products
Vegan Cat Food Market
Pet Care Products
Cat Cage Market
Pet Care Products
Animal Bedding Products Market
Pet Care Products
Fish Based Pet Food Market
Pet Care Products
UAE Dog Food Market
Pet Care Products
Europe Organic Pet Food for Cats and Dogs Market
Pet Care Products
Large Breed Dog Food Market
Pet Care Products
Organic Dog Food Market
Pet Care Products
Cat Calming Treats Market
Pet Care Products
Dog Water Bottle Market
Pet Care Products
Dog Vitamins Market