
 Compression and Shapewear Market | 2026-2036
Compression and Shapewear Market Size, Share, and Industry Trends Forecast 2026-2036
Compression and Shapewear Market Outlook
Asset-light licensing and third-party manufacturing partnerships are reshaping competitive entry in compression and shapewear, lowering capital barriers for new brands. Spanx Inc. leverages its direct-to-consumer infrastructure to control margin capture across digital channels. Nike Inc. anchors its position through performance-grade fabric R&D that bridges athletic and recovery applications. Under Armour Inc. competes by integrating biometric-compatible compression into its training apparel lines.
Compression and shapewear encompasses form-fitting garments engineered with elastomeric blends—typically 15-40% spandex combined with nylon or polyester—to apply graduated mechanical pressure for body contouring, athletic performance, or post-operative recovery. Manufacturing employs circular knitting or warp-knitting techniques to achieve targeted compression zones measured in millimeters of mercury. Bodysuits and leggings command the largest volume positions within product type segments, while shorts represent the fastest-expanding category among fitness enthusiasts. Spandex-dominant material formulations sustain premium pricing, whereas cotton blends occupy value-tier positioning through mass retail distribution.
The U.S. FDA regulates medical-grade compression garments as Class I devices, requiring substantiated pressure claims for post-surgical and venous insufficiency applications. The EU REACH regulation and OEKO-TEX Standard 100 restrict azo dyes and phthalates in textiles sold across European markets, elevating compliance costs for imported shapewear. China's GB standards for textile safety add a third compliance layer for brands sourcing manufacturing domestically. Stakeholders must monitor how evolving textile chemical regulations in major consumer markets will reshape material sourcing strategies and supplier qualification timelines.
Market Dynamics
The compression and shapewear market is being reshaped by the convergence of medical-grade certification requirements with athleisure performance standards, forcing manufacturers to bridge historically separate supply chains and testing protocols.
Growth Catalysts
- Post-surgical recovery protocols:Physician endorsement of graduated compression garments for venous insufficiency and cosmetic surgery recovery is expanding reimbursable channels in the United States. Medical device classification creates pricing power distinct from fashion-tier products.
- Elastomeric blend innovation:Advanced circular knitting techniques now enable zoned compression mapping that varies pressure gradients across garment sections. This precision engineering supports both athletic performance claims and clinical efficacy substantiation.
- REACH compliance differentiation:The EU's tightening restrictions on azo dyes and phthalates in textile imports are elevating material sourcing standards. Brands with certified supply chains capture shelf space as retailers face liability exposure.
Market Restraints
- Spandex cost volatility:Petroleum-derived elastane prices fluctuate with crude oil markets and regional refinery capacity, compressing margins for mid-tier producers locked into fixed retail pricing agreements.
- Asian manufacturing concentration:Over 70 percent of circular knitting capacity sits in coastal China provinces, creating geopolitical and logistics concentration risk that brands cannot easily diversify without substantial qualification timelines.
- Compression measurement standardization gaps:Millimeters of mercury testing protocols vary between ISO, AATCC, and proprietary brand methods, creating friction in cross-border trade and consumer confusion about efficacy claims.
Strategic Opportunities
- Biometric-integrated garments:Embedding textile electrodes and stretch sensors into compression bases enables real-time muscle oxygenation and recovery metrics. This convergence attracts digital health investors and sports medicine partnerships.
- India domestic manufacturing:The country's PLI scheme for technical textiles offers capital subsidies that offset the cost of migrating production from China. Early movers capture tariff advantages into Middle Eastern and African markets.
- Direct-to-consumer subscription models:Postpartum and post-surgical patients require sequential sizing as bodies change. Automated replenishment programs with telehealth integration lock in lifetime value exceeding traditional retail economics.
Industry Challenges
- Compression garment fit specialists:Proper sizing requires anthropometric expertise that mass retail associates lack. Brands must build digital fitting tools or certified fitter networks to reduce return rates that erode unit economics.
- Dual certification timelines:Securing both FDA Class I device registration and OEKO-TEX Standard 100 certification extends product development cycles by 8-14 months, delaying revenue recognition for seasonal collections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compression and Shapewear Market |
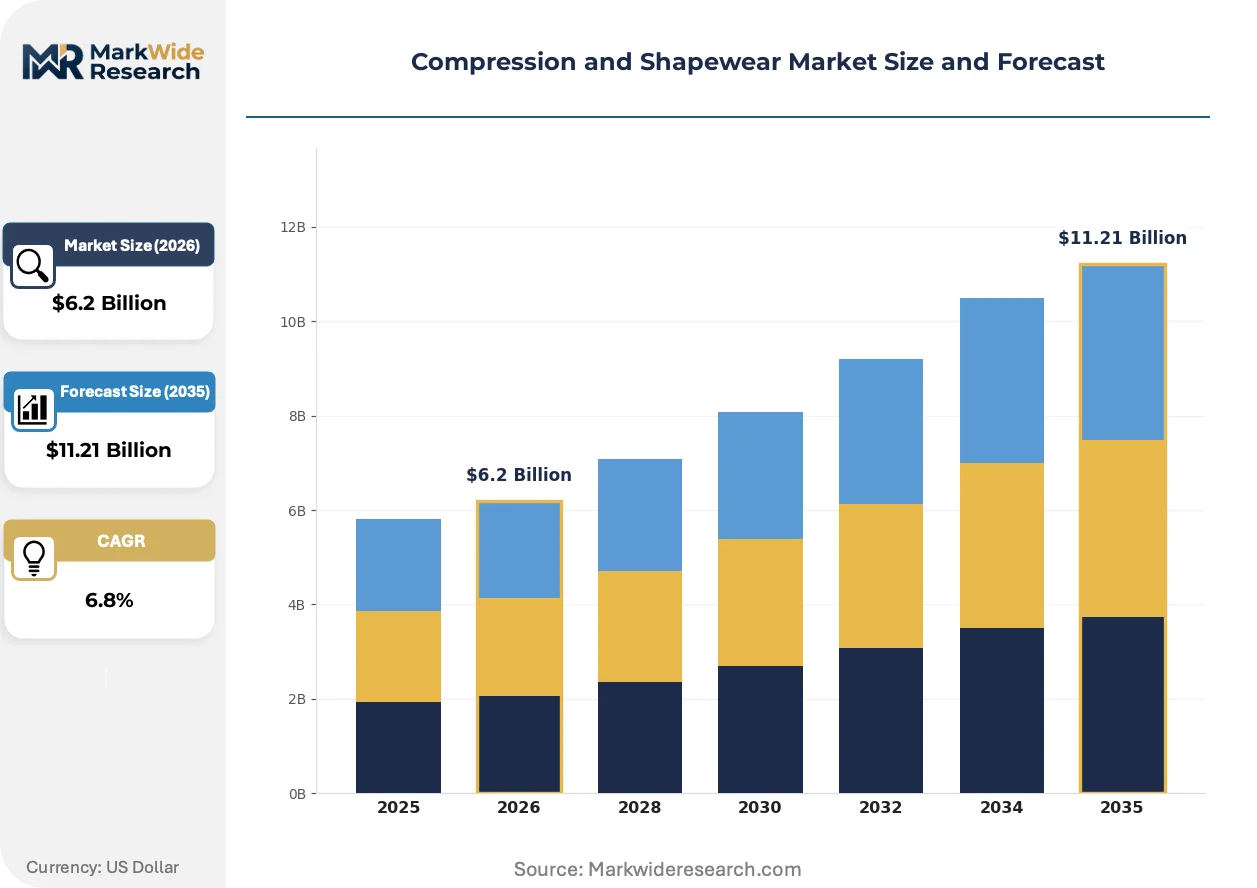
| Market Size in 2026 | $6.2 Billion |
| Market Size in 2035 | $11.21 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shorts, Bodysuits, Tops, Leggings Material: Spandex, Nylon, Polyester, Cotton End User: Women, Men, Fitness Enthusiasts, Post-Surgery Patients Distribution Channel: Online Retail, Specialty Stores, Department Stores, Brand Outlets |
| Companies Covered | Spanx Inc., Nike Inc., Adidas AG, Under Armour Inc., Triumph International Corporation, Leonisa SA, Wacoal America Inc., Ann Chery, 2XU Pty Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compression and Shapewear Market Strategic Shifts
Active developments in smart textiles, regulatory chemistry standards, and channel architecture are compressing the traditional boundaries between medical device and apparel supply chains.
Seamless knitting technology is migrating from basic shapewear toward medical-grade graduated compression with embedded structural support zones. Athletic brands and post-surgical suppliers now source from the same equipment manufacturers, collapsing the historical separation between performance and recovery garment production. This convergence pressures pure-play medical device manufacturers to match fashion-cycle speed or cede younger patient demographics.
EU REACH Annex XVII restrictions on N-methyl-2-pyrrolidone solvent residues in spandex production are forcing reformulation of elastomeric fibers. Manufacturers serving European markets must certify new chemical pathways or face import blockage at Rotterdam and Hamburg ports. Premium brands with pre-qualified sustainable material pipelines are capturing market share as mass retailers scramble for compliant supply.
Patients recovering from cosmetic procedures increasingly purchase compression garments through telehealth platforms rather than hospital discharge bundles. This disintermediation of traditional durable medical equipment channels allows direct brands to capture margin previously allocated to institutional procurement. The shift is most pronounced in the United States, where high-deductible health plans make out-of-pocket price sensitivity acute among elective surgery patients.
Compression and Shapewear Market Segmentation
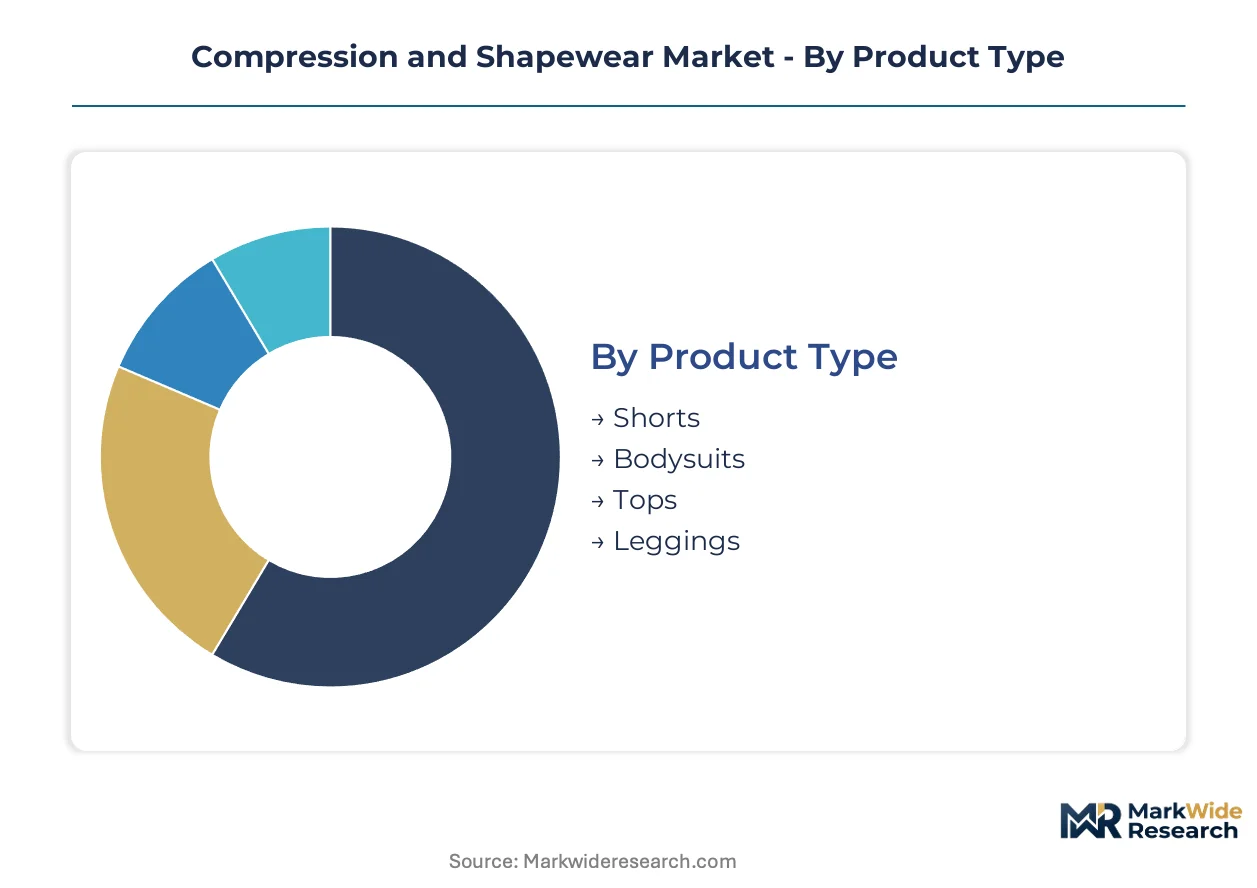
Compression and shapewear segmentation reveals divergent margin structures across product architecture, material chemistry, and patient versus consumer end-uses. Manufacturers must align production capabilities with the specific certification and channel requirements of each segment cluster.
Product Type:
Volume concentration across garment silhouettes reflects divergent use-case permanence and sizing complexity in consumer wardrobes.
- Bodysuits:Full-torso construction with integrated compression zones spanning abdomen, waist, and hip regions. Post-surgical recovery protocols in the United States specify bodysuit formats for abdominal and liposuction procedures, driving medical-grade demand through durable medical equipment channels.
- Leggings:Graduated compression legwear engineered with 15-25 mmHg pressure gradients for athletic recovery and venous insufficiency management. Fitness enthusiasts in the United States purchase replacement pairs at higher frequency than other silhouettes, sustaining volume velocity through direct-to-consumer subscriptions.
- Shorts:Mid-thigh compression garments with targeted glute and quadriceps support zones. The fastest-expanding category among fitness enthusiasts seeking crossover athletic-recovery functionality.
- Tops:Upper-body compression including arm sleeves, chest binders, and postural support vests. Occupational and athletic applications dominate with lower average selling prices than lower-body counterparts.
Bodysuits command the established base. The steepest expansion runs through shorts.
Material:
Chemical composition determines compliance tier eligibility and price positioning across regulatory jurisdictions.
- Spandex:Elastane-dominant blends delivering 20-40% stretch recovery with graduated pressure retention. REACH Annex XVII solvent restrictions are forcing European-market suppliers to certify alternative polymerization pathways, elevating qualification costs for mass-market brands.
- Nylon:Polyamide base fibers with superior abrasion resistance and moisture-wicking properties. Athletic compression lines in the United States favor nylon-spandex constructions for durability under repeated wash cycles.
- Polyester:Cost-optimized synthetic base with lower elasticity coefficients than nylon. Value-tier shapewear distributed through department stores relies on polyester-dominant blends to hit mass-market price points.
- Cotton:Natural fiber blends prioritizing breathability over compression precision. Post-surgical patients with skin sensitivity preferences drive limited demand through specialty medical suppliers.
Spandex formulations anchor premium positioning. The steepest compliance-driven substitution is occurring in polyester alternatives.
End User:
Customer archetype segmentation separates reimbursable medical channels from discretionary retail purchase patterns.
- Women:Historically dominant demographic with purchase concentration across maternity, postpartum, aesthetic surgery recovery, and daily shapewear applications. Sizing complexity and seasonal collection turnover sustain higher SKU counts than other segments.
- Post-Surgery Patients:Physician-directed purchasers requiring FDA Class I device certification for compression claims. Reimbursement channel expansion in the United States is accelerating volume growth faster than traditional retail segments.
- Fitness Enthusiasts:Performance-oriented buyers seeking athletic-recovery crossover functionality. Biometric-integrated garment interest concentrates within this cohort.
- Men:Emerging segment with demand concentrating in athletic compression and post-operative gynecomastia recovery. Lower current penetration but expanding product availability through direct-to-consumer brands.
Women command the established base. The steepest expansion runs through post-surgery patients.
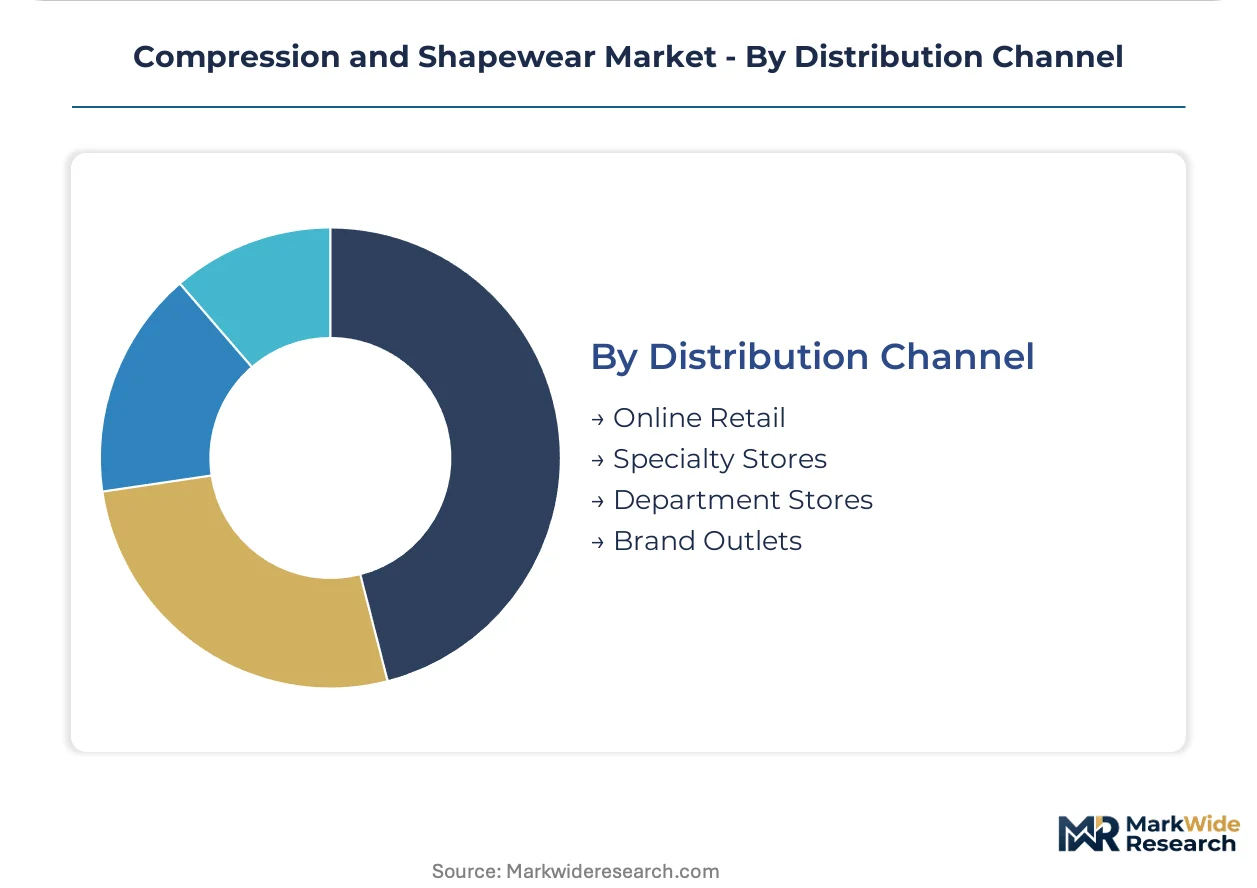
Distribution Channel:
Channel architecture determines margin capture rates and regulatory documentation requirements for compression claims.
- Online Retail:Direct-to-consumer platforms enabling telehealth-integrated fitting tools and subscription replenishment. Post-surgical patients in the United States increasingly bypass hospital discharge bundles for direct online purchase.
- Specialty Stores:Certified fitter networks providing anthropometric measurement services for medical-grade garment dispensing. Required for proper sizing of post-operative compression with insurance documentation.
- Brand Outlets:Captive retail channels controlling full margin stack and customer data capture. Spanx and similar vertically integrated operators concentrate flagship locations in major United States metropolitan markets.
- Department Stores:Mass retail distribution for fashion-tier shapewear without medical compression claims. Inventory turns faster but average unit economics compress under promotional pricing calendars.
Online retail commands the established base. The steepest expansion runs through specialty stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in compression and shapewear tilt toward manufacturing concentration in Asia against premium consumption in Western markets, with regulatory divergence creating compliance arbitrage opportunities for qualified suppliers.
United States
Post-surgical recovery protocols and expanding durable medical equipment reimbursement channels drive domestic demand for FDA Class I certified garments. The FDA regulates medical-grade compression claims under device classification rules that elevate substantiation requirements above fashion-tier products. New York and Los Angeles anchor specialty retailer networks where certified fitters dispense prescription-grade garments.
Germany
Graduated compression adoption for venous insufficiency management sustains steady clinical demand through statutory health insurance channels. ECHA REACH Annex XVII restrictions on textile solvents force reformulation of elastomeric fiber production for European market access. The North Rhine-Westphalia textile cluster around Mönchengladbach hosts circular knitting equipment manufacturers serving both medical and athletic garment producers.
China
Coastal provinces in Zhejiang and Guangdong concentrate over two-thirds of global circular knitting capacity for compression textiles. GB standards for textile safety add compliance layers for domestic market sales beyond export requirements. The Yangtze River Delta manufacturing corridor faces migration pressure as brands diversify toward Vietnam and Bangladesh to mitigate tariff exposure.
India
Technical textile production incentives under the PLI scheme attract compression garment manufacturing investment from multinational brands seeking China alternatives. BIS certification requirements for imported textiles create qualification barriers that domestic producers exploit. Tamil Nadu's Tiruppur knitwear cluster expands into medical-grade compression as European buyers seek REACH-compliant supply alternatives.
Brazil
Post-aesthetic surgery compression demand concentrates in São Paulo and Rio de Janeiro metropolitan cosmetic surgery markets. ANVISA medical device registration requirements for therapeutic compression claims extend product development timelines for imported brands. The São Paulo state industrial belt hosts domestic shapewear manufacturers competing on cost against Asian imports through Mercosur tariff preferences.
Compression and Shapewear Market Competitive Environment
On the supply side, the industry is bifurcated between vertically integrated apparel conglomerates and specialized medical device manufacturers, with asset-light licensing models eroding traditional capital barriers. Strategic archetypes include DTC-native shapewear brands controlling digital margin stacks, athletic apparel multinationals leveraging performance fabric R&D, and pure-play medical suppliers with certified fitter networks. Competitive moves center on biometric integration partnerships and third-party manufacturing qualification to diversify beyond China concentration.
Within the athletic-crossover tier, Nike Inc., Under Armour Inc., and 2XU Pty Ltd occupy positions that bridge performance training and recovery applications. Spanx Inc. exemplifies the DTC-native archetype through captive digital infrastructure. Leonisa SA and Triumph International Corporation represent established intimate apparel specialists extending into medical-grade compression. Wacoal America Inc. anchors the certified fitter network model through specialty retail partnerships. Adidas AG sits within the scale-driven multinational tier with technical textile sourcing advantages.
| Leading Market Players |
|---|
| Spanx Inc. |
| Nike Inc. |
| Adidas AG |
| Under Armour Inc. |
| Triumph International Corporation |
| Leonisa SA |
| Wacoal America Inc. |
| Ann Chery |
| 2XU Pty Ltd. |
| Others |
Value Chain & Pricing Dynamics
Coastal China's concentration of circular knitting capacity for elastomeric textiles concentrates upstream leverage among Zhejiang and Guangdong mill operators, pushing margin capture toward garment finishers with FDA Class I certification and direct-to-consumer channel control.
Pricing Analysis
Post-surgical patients and durable medical equipment channels anchor three-tier pricing stratification across premium medical-grade, standard athletic-crossover, and economy fashion-tier levels. Price differentiation rests on FDA device certification status and OEKO-TEX Standard 100 compliance tier, with REACH Annex XVII solvent restrictions elevating European-market qualification costs. Cost compression in mass retail polyester blends intensifies as petroleum-derived spandex prices fluctuate with crude oil markets. Hospital procurement committees exhibit lowest price sensitivity; fitness enthusiasts purchasing through direct-to-consumer platforms show highest elasticity.
Supply Chain Analysis
Extended payment terms from 90 to 120 days dominate supplier-finance arrangements as brands manage working capital through Asian manufacturing partnerships. Raw material sourcing draws from petroleum-based elastane producers, nylon polyamide suppliers, and azo dye chemistries facing REACH restriction. Geographic concentration spans coastal China provinces, Vietnam's emerging knitwear corridor, and India's Tiruppur cluster expanding under PLI scheme subsidies. Single-source vulnerability concentrates in circular knitting equipment manufacturers based in Germany's North Rhine-Westphalia textile cluster. Distribution runs through direct-to-consumer platforms, certified fitter specialty networks, and hospital discharge bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compression and shapewear functions as a service-attach market where telehealth-integrated fitting subscriptions and sequential sizing replenishment programs expand recurring revenue faster than unit sales of base garments.
For Market Incumbents: Entrench FDA Class I certification pipelines as a defensive moat against athletic brands crossing into reimbursable medical channels. Deepen backward integration into REACH-compliant elastomeric fiber production to offset European import qualification delays. Control certified fitter network density in United States metropolitan markets to lock hospital system procurement relationships. For New Entrants and Emerging Players: Establish a beachhead in biometric-integrated athletic recovery garments where sports medicine partnerships offer faster validation cycles than medical device pathways. Target men's compression as the most penetrable demographic with lowest incumbent saturation. Pursue telehealth platform integration as the primary go-to-market angle for post-surgical patient acquisition. For Investors and Strategic Acquirers: Capital is best deployed toward asset-light licensing operators with pre-qualified sustainable material pipelines and direct-to-consumer infrastructure. Long-term viability favors archetypes bridging medical reimbursement expansion with athleisure crossover demand. Watch FDA guidance on software-as-medical-device classification for biometric garment claims as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Pipeline Certification | ECHA Annex XVII solvent restrictions force reformulation of elastomeric fibers for European market access. |
| Telehealth Platform Integration | Post-surgical patients bypass hospital discharge bundles for direct digital purchase with automated sizing. |
| Biometric Sensor Embedding | Textile electrodes enable real-time muscle oxygenation metrics attracting sports medicine partnerships. |
| India PLI Manufacturing Migration | Capital subsidies offset production relocation costs from China toward tariff-advantaged export positioning. |
| Certified Fitter Network Expansion | Anthropometric expertise reduces return rates and secures insurance documentation for medical-grade dispensing. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with compression garment brand managers, circular knitting mill technical directors, hospital purchasing committee members, certified fitter network operators, and sports medicine clinicians. Secondary validation drew from FDA 510(k) device filings, ECHA REACH substance restriction updates, OEKO-TEX Standard 100 certification databases, United States durable medical equipment reimbursement schedules, and customs trade data for elastomeric textile imports. Bottom-up patient population modeling and top-down apparel market sizing were triangulated against manufacturer production disclosures.
Calibration against historical volume shifts in post-surgical recovery protocols and athletic crossover adoption anchored the analytical framework across the projection horizon. Segmentation dimensions spanned product architecture, material chemistry compliance tier, end-user archetype, and distribution channel regulatory intensity. CAGRs were derived from elasticity-adjusted demand curves incorporating spandex price volatility and reimbursement expansion scenarios. Industry-specific inputs included physician endorsement velocity for graduated compression protocols and REACH Annex XVII implementation timelines.
Sensitivities concentrate around crude oil price trajectories affecting elastane input costs, FDA software-as-medical-device guidance evolution, and geopolitical disruption to coastal China manufacturing corridors. Forecasts reflect documented assumptions on reimbursement channel expansion and regulatory compliance cost pass-through. Macroeconomic contraction in elective surgery volumes, ECHA solvent restriction acceleration, or breakthrough biodegradable elastomer commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
New Smart Wardrobe Market
Apparel & Footwear
Maternity Apparels Market
Apparel & Footwear
Streetwear Market
Apparel & Footwear
Men Shirts Market
Apparel & Footwear
Ballet Pointe Shoes Market
Apparel & Footwear
US Thermal Underwear Market
Apparel & Footwear
Custom Cycling Clothing Market
Apparel & Footwear
Plus Size Women's Clothing Market
Apparel & Footwear
Innerwear Market
Apparel & Footwear
Global Sleepwear and Loungewear Market
Apparel & Footwear
Global Women Pajamas Suits Market
Apparel & Footwear
Decorated Apparel Market
Apparel & Footwear
Platform Shoes Market
Apparel & Footwear
Insulated Jacket Market
Apparel & Footwear
Women's Shirts and Blouses Market
Apparel & Footwear
Vegan Women's Fashion Market