
 Global Wireless Headphones Market | 2026-2036
Global Wireless Headphones Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wireless Headphones Market Intelligence
A reliance on outsourced component manufacturing is shifting toward greater in-house control over proprietary chipsets and acoustic drivers. Apple Inc. leverages its custom H-series and W-series chips to create a tightly integrated user experience across its ecosystem. Sony Corporation competes on the basis of advanced active noise cancellation and high-resolution audio processing technologies. Bose Corporation sustains its premium market position through specialized acoustic engineering and patented audio waveguide technology.
Wireless headphones are audio output devices that receive signals without a physical cable, typically using radio frequency or infrared transmission. Key performance parameters include frequency response, typically 20Hz to 20kHz, and connectivity protocols like Bluetooth 5.x with specific codec support. The True Wireless product type represents the fastest-growing category, displacing traditional in-ear and on-ear models. Within end-user segments, demand from Consumers for general use constitutes the largest volume, while the Professionals segment offers higher margins.
Market access is governed by regulations for radio frequency emissions and electronic device safety. Compliance with FCC Part 15 rules in the United States and CE marking directives, including RoHS in Europe, is mandatory. China's MIIT similarly certifies radio transmission equipment, influencing component selection for devices sold in that market. Future competitive advantage will depend on integrating advanced features like spatial audio and health monitoring sensors.
Market Dynamics
The finalization of the Bluetooth LE Audio standard is the central force shaping the market. This technological framework enables new product capabilities and use cases, compelling manufacturers to innovate beyond core audio performance to maintain competitive differentiation.
Growth Catalysts
- Bluetooth LE Audio Standard:The completion of this specification unlocks new features, including high-quality, low-power audio transmission and the Auracast broadcast audio function, creating new product development cycles.
- Gamers Segment Demand:The requirement for low-latency, high-fidelity audio within the competitive Gamers segment provides a consistent demand stream for specialized, performance-oriented wireless headphone models.
- Manufacturing Concentration:China's vast consumer electronics manufacturing ecosystem and large domestic market create economies of scale and a rapid product iteration environment, accelerating feature adoption.
Market Restraints
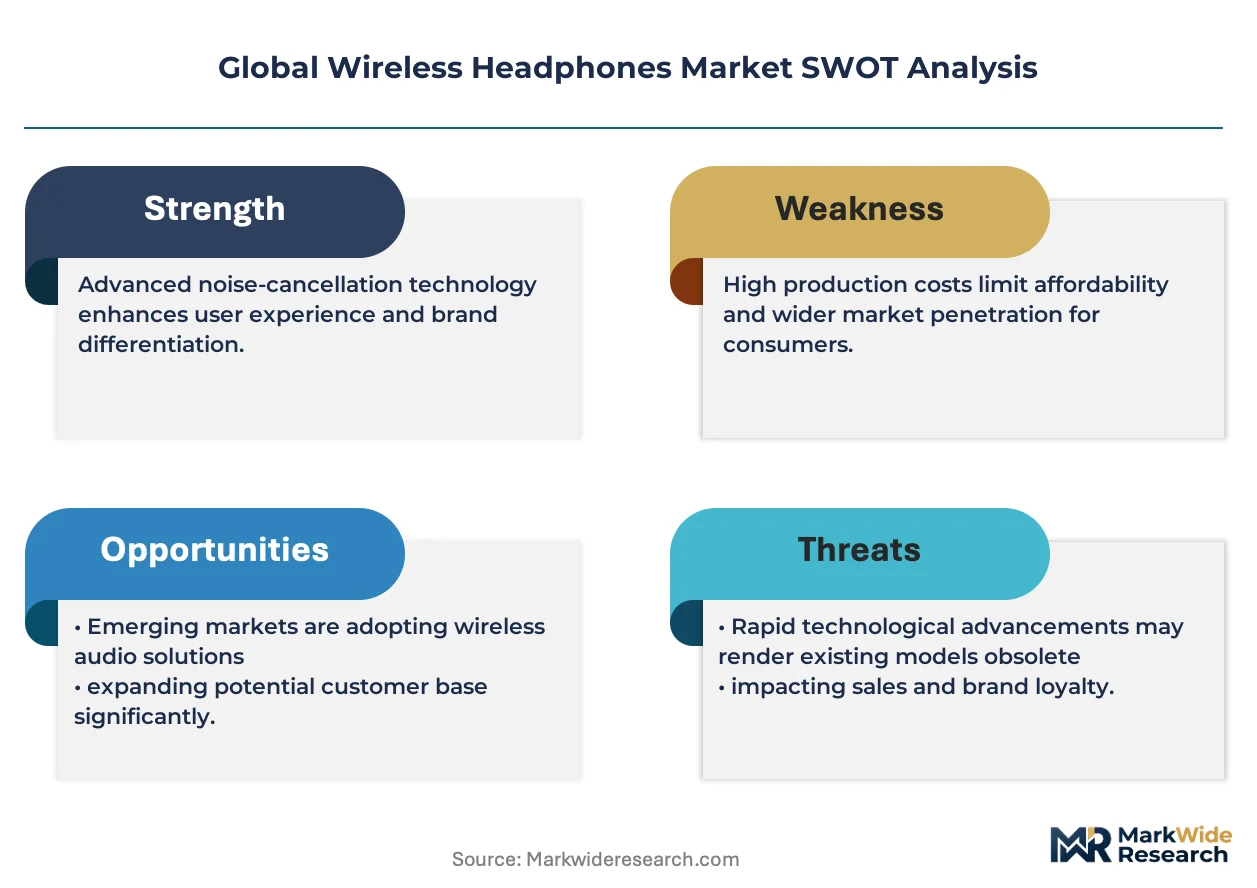
- Battery Technology Limits:The physical size and energy density of batteries constrain the operational time of True Wireless earbuds, especially when using power-intensive features like active noise cancellation and health sensors.
- Proprietary Chipset Dependence:A reliance on a few advanced semiconductor foundries for custom audio and connectivity chipsets creates supply chain vulnerabilities and potential production bottlenecks for headphone manufacturers.
- Regulatory Divergence:Navigating differing radio-frequency compliance standards, such as FCC Part 15 in the United States and MIIT rules in China, adds complexity and cost to global product launches.
Strategic Opportunities
- Health Sensor Integration:Incorporating biometric sensors for health and fitness monitoring, such as heart rate or body temperature tracking, opens a new market for personal wellness devices beyond simple audio playback.
- Public Broadcast Audio:The Auracast feature within LE Audio creates opportunities for adoption in public venues like airports, museums, and conference centers, allowing users to tune into shared audio streams.
- Emerging Market Penetration:Targeting consumers in Southeast Asian and Latin American markets with mid-range products offers significant volume growth potential as smartphone adoption in these regions continues to expand.
Industry Challenges
- Audio Codec Licensing:Securing licenses for essential high-resolution and low-latency audio codecs involves complex negotiations and royalty payments, representing a significant barrier for new entrants and smaller firms.
- Certification Delays:The lengthy and rigorous testing processes required for mandatory certifications, including CE marking in Europe and FCC approval in the US, can substantially delay product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wireless Headphones Market |
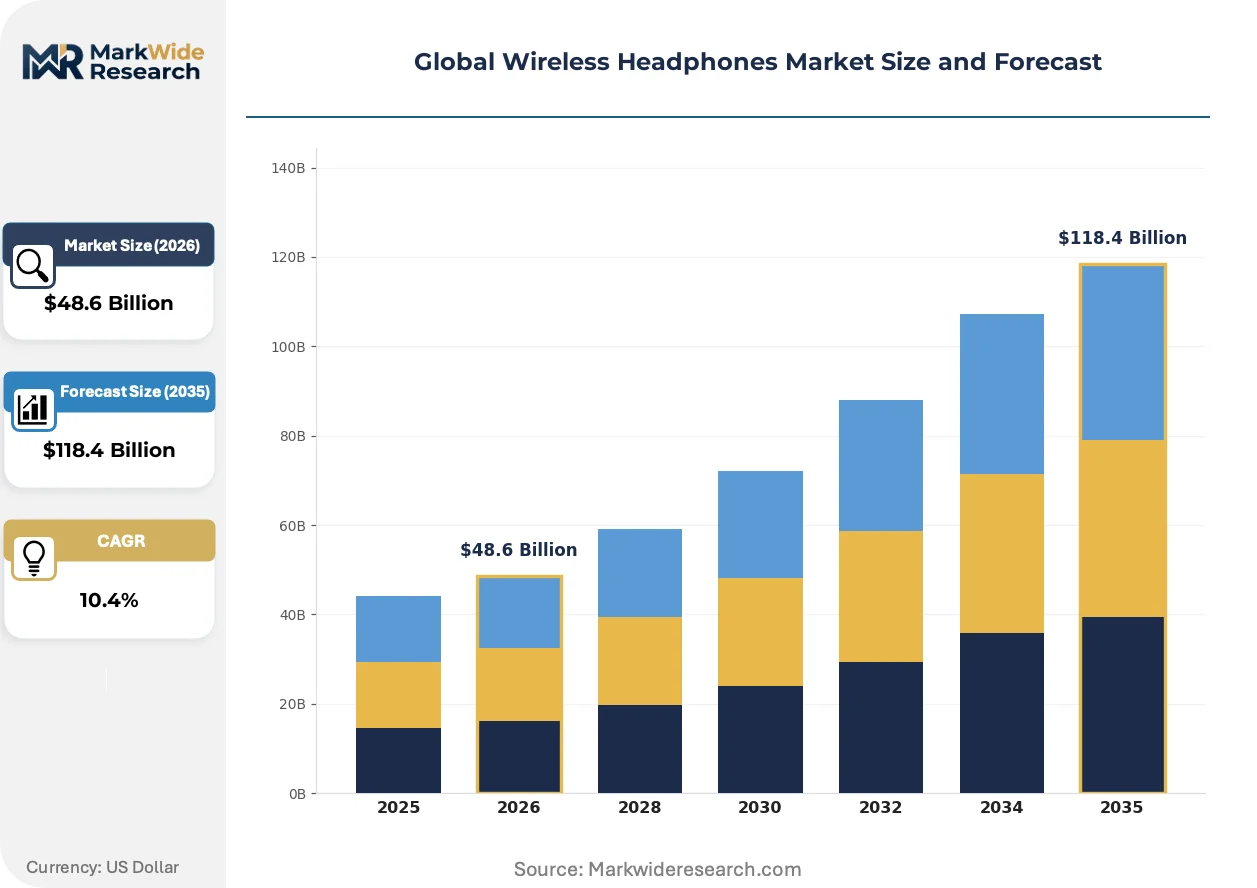
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $118.4 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Over-Ear, On-Ear, In-Ear, True Wireless Technology: Bluetooth, NFC, Infrared, RF End User: Consumers, Gamers, Professionals, Athletes Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Others |
| Companies Covered | Apple Inc., Sony Corporation, Samsung Electronics, Bose Corporation, Sennheiser Electronic GmbH & Co. KG, Jabra, Harman International Industries, Xiaomi, Audio-Technica Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wireless Headphones Market Strategic Shifts & Innovations
The functional scope of wireless headphones is expanding beyond audio reproduction. Devices are evolving into wearable computing platforms, integrating advanced processing and sensing capabilities to deliver personalized, context-aware experiences for users across different environments.
Spatial audio processing, which creates an immersive three-dimensional soundscape, is a primary software-driven innovation. This technology is being adopted by Consumers seeking more engaging media experiences and by Gamers who require precise audio cues for positional awareness. This advanced audio rendering capability is converging with on-device inertial measurement units to enable dynamic head-tracking for a more realistic and interactive experience.
European Union regulations concerning the right to repair and battery replaceability are influencing hardware design. These directives compel a shift away from permanently sealed, unibody constructions that are difficult for consumers or technicians to service. The True Wireless product segment is most impacted, pushing engineering teams to develop new modular designs that facilitate easier battery replacement without compromising form factor or water resistance.
User expectations for seamless connectivity are altering product design priorities. Consumers demand effortless audio source switching between multiple devices, such as a laptop for work, a smartphone for calls, and a smart TV for entertainment. This behavior is challenging the traditional single-point pairing model and favors ecosystem-centric approaches that offer robust multipoint Bluetooth connections, a feature particularly valued within the Professionals segment.
Global Wireless Headphones Market Segmentation
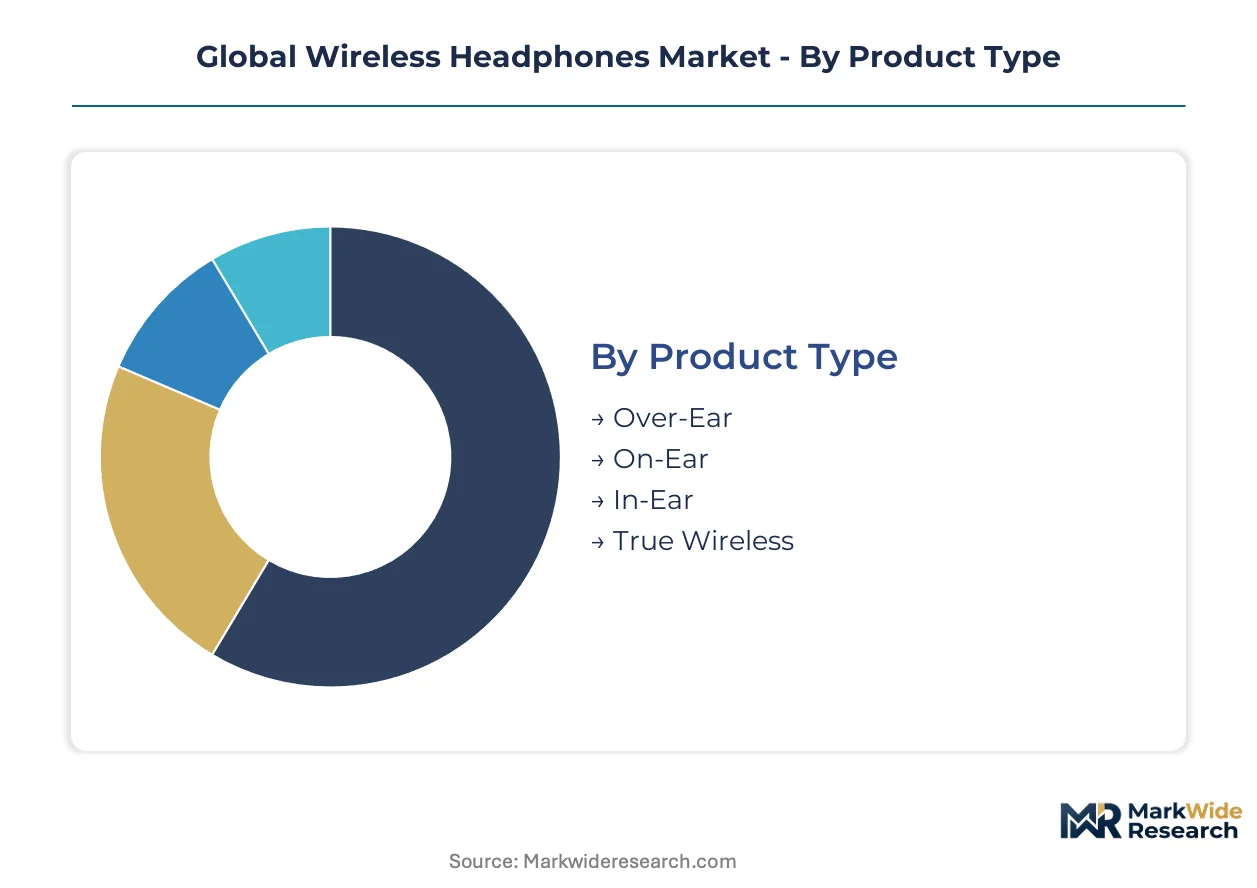
Market segmentation provides a structured view of the wireless headphones industry, highlighting distinct product offerings, technological underpinnings, and consumer behaviors. Understanding these segments is crucial for manufacturers to tailor product development and for retailers to optimize distribution strategies. This analysis illuminates where value is created and consumed across the market.
Product Type:
Buyers in the wireless headphones market differentiate their choices primarily based on form factor and portability requirements.
- True Wireless:These earbuds feature completely independent left and right units without any connecting wires, prioritizing ultimate portability and compact design. Demand is expanding most quickly among consumers seeking seamless integration with smartphones and active lifestyles.
- In-Ear:Characterized by small earpieces inserted directly into the ear canal, these models offer a balance of sound isolation, portability, and generally good audio quality. This form factor remains popular for everyday use and fitness activities due to its secure fit.
- Over-Ear:These headphones fully enclose the ear, providing excellent passive noise isolation and often superior audio fidelity due to larger drivers. They are favored by audiophiles and users who prioritize comfort for extended listening sessions.
- On-Ear:Lighter than over-ear models, these headphones rest on the ear, offering a less immersive experience but improved portability compared to full-sized options. They appeal to users seeking a compromise between compact size and traditional headphone feel.
Volume sits with In-Ear models; growth tilts toward True Wireless.
Technology:
The underlying transmission technology dictates the primary application and connectivity range for wireless headphones.
- Bluetooth:This short-range wireless standard is the dominant technology, offering broad compatibility with smartphones, computers, and other consumer electronics. The finalization of Bluetooth LE Audio is enabling new features like Auracast broadcast audio.
- RF:Radio Frequency technology provides a stable, low-latency connection over a greater range than Bluetooth, often preferred for dedicated gaming headsets and home theater applications. These solutions minimize audio delay critical for competitive gaming.
- NFC:Near Field Communication facilitates quick and effortless pairing of headphones with compatible devices through a simple tap. This technology enhances user convenience by streamlining the initial connection process.
- Infrared:Infrared transmission requires a direct line of sight between the transmitter and receiver, typically used in older home entertainment systems or specific niche applications. Its range and flexibility are limited compared to other wireless protocols.
Bluetooth technology commands the largest share, while RF solutions cater to specialized, high-performance niches.
End User:
Different end-user segments demand specific performance characteristics and feature sets from their wireless headphones.
- Consumers:This segment represents the largest volume of buyers, primarily seeking general-purpose headphones for music, calls, and entertainment. Affordability, ease of use, and a balanced feature set are key purchasing criteria.
- Gamers:This competitive segment requires headphones with ultra-low latency, precise spatial audio, and clear microphone quality to gain a competitive edge. Specialized drivers and connectivity protocols are essential for immersive gameplay.
- Professionals:Users in this segment prioritize features such as advanced active noise cancellation, superior microphone clarity for conference calls, and comfort for prolonged wear in office environments. High-margin products often target these specific needs.
- Athletes:This segment demands durable, sweat-resistant, and securely fitting headphones designed to withstand rigorous physical activity. Features like heart rate monitoring sensors are increasingly integrated into these specialized devices.
The Consumer segment drives overall market volume, with Gamers representing a significant high-growth opportunity.
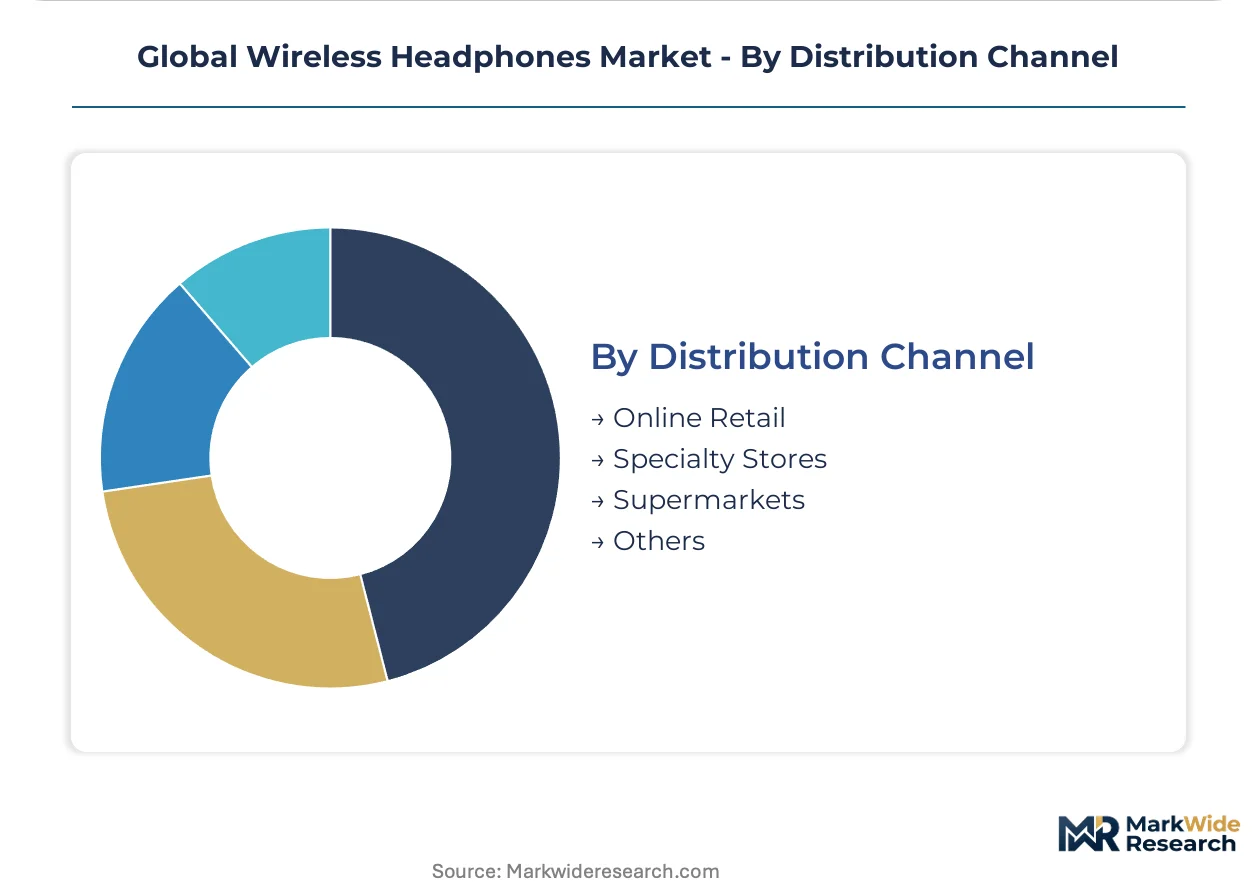
Distribution Channel:
Accessibility and purchasing preferences heavily influence the choice of distribution channels for wireless headphones.
- Online Retail:E-commerce platforms offer an extensive selection, competitive pricing, and the convenience of home delivery, making them a primary sales channel for a wide range of wireless headphone brands. This channel captures significant market share.
- Specialty Stores:These outlets provide expert product knowledge, hands-on demonstrations, and personalized recommendations, catering to audiophiles and consumers seeking premium or high-fidelity audio equipment. They maintain importance for higher-value purchases.
- Supermarkets:Mass-market retailers offer a limited selection of entry-level and mid-range wireless headphones, often targeting impulse buys or budget-conscious consumers. These stores provide broad geographic reach for basic models.
- Others:This category encompasses a variety of sales points including consumer electronics chains, department stores, and direct-to-consumer websites. These channels collectively broaden market access and cater to diverse shopping preferences.
Online Retail channels dominate sales, while Specialty Stores maintain importance for high-value transactions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's robust manufacturing ecosystem anchors the global wireless headphones market, providing a critical base for production and innovation. This concentration facilitates rapid product development cycles and allows for economies of scale, influencing global pricing and feature adoption. Other key regions contribute through consumer demand, technological advancement, and regulatory frameworks.
China
Domestic demand from a large consumer base and the Gamers segment drives significant volume for wireless headphones. The MIIT certifies radio transmission equipment, influencing component selection and design for devices sold within the country. Shenzhen and the Pearl River Delta serve as primary hubs for consumer electronics manufacturing and assembly.
United States
Consumers and Professionals in the United States demand advanced features like spatial audio and health monitoring sensors. Compliance with FCC Part 15 rules is mandatory for all radio frequency emitting devices, ensuring market access. Silicon Valley and other tech clusters foster innovation in audio processing and connectivity technologies.
Germany
The German market prioritizes high-resolution audio processing and advanced active noise cancellation technologies. CE marking directives and RoHS compliance are essential for product entry across Europe, alongside emerging EU right to repair regulations. Munich and Berlin host significant research and development activities in specialized acoustic engineering.
Japan
Japanese consumers exhibit a strong preference for high-fidelity audio and sophisticated designs, driving demand for premium wireless headphones. METI regulations and JIS standards guide product development and market introduction for electronic devices. Tokyo and Osaka remain critical centers for major consumer electronics companies and audio technology innovation.
Brazil
Growing smartphone adoption in Brazil fuels demand for mid-range wireless headphones, representing a significant volume growth opportunity. The national telecommunications agency, ANATEL, regulates wireless device certification and spectrum usage. São Paulo acts as a major distribution and consumer hub, connecting manufacturers to a broad South American market.
Global Wireless Headphones Market Key Industry Players
Global majors compete with regional champions across technological innovation and market access within the wireless headphones industry. The market exhibits a tiered structure, with premium brands focusing on advanced features and mass-market players emphasizing affordability. Strategic archetypes include innovation leaders, diversified electronics conglomerates, and specialized audio firms. Portfolio diversification into health sensors and spatial audio, alongside strategic partnerships for codec licensing, are dominant competitive moves.
Within the innovation-driven tier, Apple Inc. and Sony Corporation exemplify premium innovation with proprietary chipsets and advanced audio processing. Apple leverages its custom H-series and W-series chips to create a tightly integrated user experience across its ecosystem. Sony competes on the basis of advanced active noise cancellation and high-resolution audio processing technologies. Xiaomi Corporation represents the high-volume, value-oriented segment, leveraging its broad consumer electronics ecosystem and manufacturing capabilities to deliver accessible products to a wider market.
| Leading Market Players |
|---|
| Apple Inc. |
| Sony Corporation |
| Samsung Electronics |
| Bose Corporation |
| Sennheiser Electronic GmbH & Co. KG |
| Jabra |
| Harman International Industries |
| Xiaomi |
| Audio-Technica Corporation |
| Others |
Cost & Logistics Intelligence
Consumer demand for advanced features like spatial audio and health monitoring sensors compels manufacturers to invest in complex components. This investment in turn shapes supply chain configurations and influences end-product pricing strategies.
Pricing Analysis
Warranty and service bundling often differentiates premium wireless headphones, offering extended support or accidental damage protection. The dominant pricing structure is a tiered premium-mid-economy differentiation, reflecting varying feature sets and brand perception. Price differentiation drivers include brand premium from companies like Apple Inc. and specialized acoustic engineering from Bose Corporation, while pricing softness runs through the mid-range segment due to intense competition from high-volume players like Xiaomi. Consumers represent the most price-sensitive segment, while Professionals prioritize feature sets over cost.
Supply Chain Analysis
Logistics and freight costs influence the final price of wireless headphones, particularly for products assembled in Asia and shipped globally. Component manufacturing and assembly heavily concentrate in China, with supporting ecosystems in Vietnam and Malaysia. The industry draws from proprietary chipsets, advanced acoustic drivers, and specialized lithium-ion batteries. A structural risk exists in single-source vulnerability for advanced audio and connectivity chipsets from a few foundries. Downstream distribution primarily occurs through Online Retail channels, supplemented by specialty stores for premium models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global wireless headphones market is a supply-constrained story, with advanced chipset manufacturing capacity acting as a bottleneck. This constraint props up pricing for high-performance models and limits rapid scaling for new entrants.
For Market Incumbents:
Deepen proprietary chipset development and acoustic engineering capabilities to counter commoditization of basic models. Expand existing ecosystem integration, similar to Apple's H-series and W-series chips, to lock in users and differentiate premium offerings. Invest significantly in R&D for next-generation features like spatial audio processing and advanced active noise cancellation. This strategy defends market share against emerging value-oriented competitors.
For New Entrants and Emerging Players:
Health sensor integration offers a technology-first wedge into the wearable computing market beyond audio. Target underpenetrated mid-range segments in Southeast Asian markets, leveraging growing smartphone adoption for volume growth. Focus on the Athletes segment with durable, sweat-resistant products featuring biometric monitoring. A direct-to-consumer online sales model can bypass established distribution channels and reduce overheads.
For Investors and Strategic Acquirers:
The window for entry favors strategic acquirers seeking to consolidate intellectual property in specialized acoustic engineering or software for spatial audio. Long-term viability over the next 5-10 years hinges on securing core component supply chains and differentiating through software features. Target innovative mid-size firms with strong patent portfolios in low-latency audio or health monitoring sensors. The signal to watch is widespread adoption of Auracast broadcast audio in public venues, indicating new revenue streams.
| Strategic Initiative | Industry Significance |
|---|---|
| In-house Chipset Development | This secures critical supply and enables tighter hardware-software integration for companies like Apple Inc. |
| Health Sensor Integration | Expands the functional scope of wireless headphones into personal wellness devices for Athletes. |
| Auracast Ecosystem Partnerships | Facilitates adoption of public broadcast audio in venues like airports, leveraging Bluetooth LE Audio. |
| Modular Design for Repairability | Addresses EU right to repair regulations, extending product lifecycle and consumer trust. |
| Emerging Market Distribution Expansion | Captures significant volume growth potential in regions like Southeast Asia with mid-range products. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a robust foundation for market sizing. This was triangulated with primary interviews conducted with product managers, R&D directors, supply chain executives, and retail channel managers across key regions. Secondary validation drew from MIIT certifications, FCC filings, EU RoHS directives, and company annual reports. Both bottom-up market sizing and top-down revenue analysis were employed for comprehensive data reconciliation.
Product type, technology, end user, distribution channel, and geographic region were modeled at a granular level across the analysis window. The analytical framework integrated historical trend analysis with future growth projections to derive compound annual growth rates. Key industry-specific inputs included Bluetooth LE Audio adoption rates and the expansion of the competitive Gamers segment. This approach ensured a detailed understanding of market dynamics.
Several conditions sit outside the modeled scope, including unforeseen geopolitical trade tensions and disruptive new material science breakthroughs in battery technology. Forecasts reflect assumptions regarding technological progression and regulatory stability. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Automated Laundromat Services Market
Consumer Electronics
Professional Headset Market
Consumer Electronics
Europe Soundbar Market
Consumer Electronics
Handheld Device Accessories Market
Consumer Electronics
Soft Support Products Market
Consumer Electronics
Nail Art Printer Market
Consumer Electronics
Gaming Mouse & Keyboards Market
Consumer Electronics
4K Television Market
Consumer Electronics
Gaming Keyboard Market
Consumer Electronics
US Mobile Phone Accessories Market
Consumer Electronics
Stylus Pen Market
Consumer Electronics
True Wireless Stereo Market
Consumer Electronics
Wireless Speakers Market
Consumer Electronics
Asia-Pacific Gaming Keyboard Market
Consumer Electronics
Wet Wipes Market
Consumer Electronics
Smart Home Projector Market