
 Consumer Electronics Market | 2026-2036
Consumer Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Electronics Market Analysis
Aftermarket service revenue is narrowing as manufacturers shift toward subscription-based software ecosystems. Apple leverages its integrated hardware-software architecture to sustain premium pricing power across device categories. Samsung Electronics anchors global display supply through captive OLED production, while Foxconn dominates contract manufacturing scale for multinational brands.
Consumer electronics encompass finished electrical devices designed for personal use, typically operating on semiconductor-based architectures with power consumption thresholds from milliwatts in wearables to hundreds of watts in gaming systems, serving entertainment, communication, and productivity functions. Smartphones and laptops represent mature volume pools where margin compression has intensified, whereas wearable devices and MicroLED displays capture expanding premium segments as health-monitoring capabilities and panel efficiency improve.
The US FCC governs electromagnetic emissions and spectrum allocation for wireless devices, while the EU Ecodesign Framework and REACH restrict hazardous substances in component sourcing. Japan's METI enforces recycling quotas under home appliance recycling laws, forcing producers to design for disassembly. Stakeholders must track evolving battery passport requirements and right-to-repair mandates that threaten locked-in service revenue models.
Market Dynamics
Subscription-based software ecosystems are displacing hardware-centric profit pools as manufacturers lock recurring revenue into device lifecycles. This shift restructures competitive advantage around platform stickiness rather than component specifications.
Growth Catalysts
- EU Green Deal:Material compliance mandates accelerate circular design investments among manufacturers targeting European residential buyers.
- Shenzhen cluster concentration:Component supply proximity reduces lead times for global brands sourcing semiconductors and display modules.
- Health-monitoring capabilities:Wearable devices capture premium positioning as biometric sensors integrate with personal wellness platforms.
Market Restraints
- Rare earth supply concentration:Magnet and battery material dependencies create input cost volatility for motor and power management subsystems.
- RoHS directive friction:Hazardous substance restrictions complicate legacy component sourcing and supplier qualification timelines.
- MicroLED technical limitation:Mass transfer yield constraints suppress panel output and sustain OLED incumbent advantage in premium displays.
Strategic Opportunities
- India PLI scheme:Production-linked incentives attract assembly capacity relocation from coastal China manufacturing zones.
- Smart home integration:Device interoperability standards create white space for ecosystem orchestration platforms in residential automation.
- Right-to-repair mandates:Service revenue unbundling opens independent repair channel partnerships and spare parts marketplaces.
Industry Challenges
- Semiconductor process engineering talent:Advanced node fabrication expertise scarcity constrains in-house chip design ambitions.
- Battery passport compliance:Supply chain traceability systems require capex-heavy digitization of mineral sourcing documentation.
- Legacy system integration:Proprietary connector and protocol ecosystems impede cross-brand smart home device interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Electronics Market |
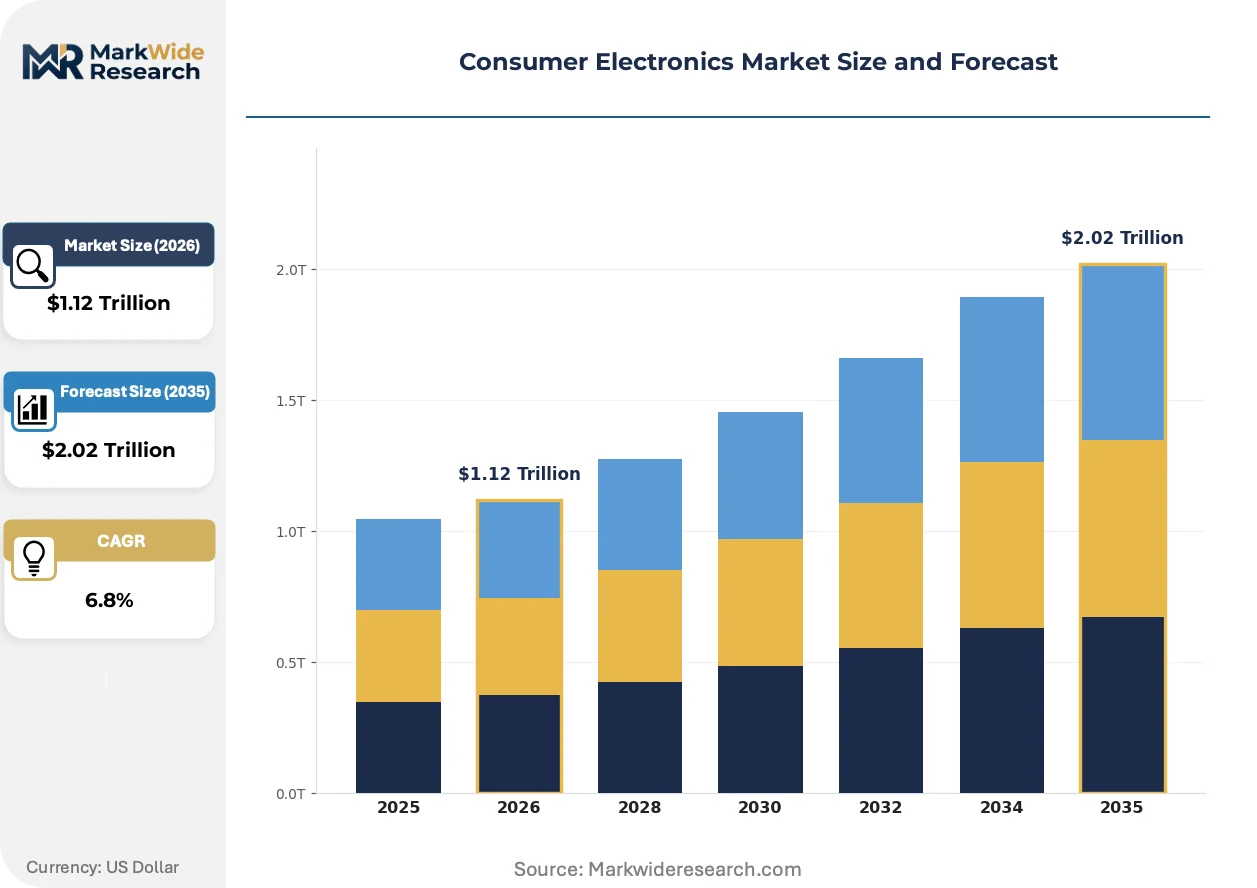
| Market Size in 2026 | $1.12 Trillion |
| Market Size in 2035 | $2.02 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Laptops, Tablets, Wearable Devices Technology: OLED, LCD, QLED, MicroLED End User: Individual Consumers, Educational Institutions, Corporates, Retailers Distribution Channel: Online Retail, Brick-and-Mortar Stores, Wholesale, Direct Sales |
| Companies Covered | Sony, BYD, Apple, Dell, HP, Samsung Electronics, LG, Lenovo, Foxconn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Electronics Market Emerging Trajectories
Active matrix technologies are compressing display power budgets while computational photography redistributes imaging value from lens hardware to signal processing. These shifts privilege semiconductor architecture over mechanical precision.
MicroLED backlighting is migrating from laboratory demonstration to commercial television and wearable form factors. Samsung Electronics and Apple anchor early volume commitments for tablets and smartwatches. This migration is compressing OLED premium pricing power and forcing display makers to reallocate capex toward gallium nitride epitaxy capacity.
EU Ecodesign Framework requirements are tightening standby power limits and mandating repairability scoring for smartphones and laptops. Manufacturers must redesign thermal management and battery accessibility. Germany and France lead enforcement, with non-compliant devices facing market withdrawal threats from national surveillance authorities.
Enterprise procurement of device fleets is consolidating around unified endpoint management platforms that bundle hardware, software, and lifecycle services. Traditional value-added resellers lose margin to direct manufacturer relationships. This pattern concentrates in North American and Western European corporate technology refresh cycles.
Consumer Electronics Market Segmentation
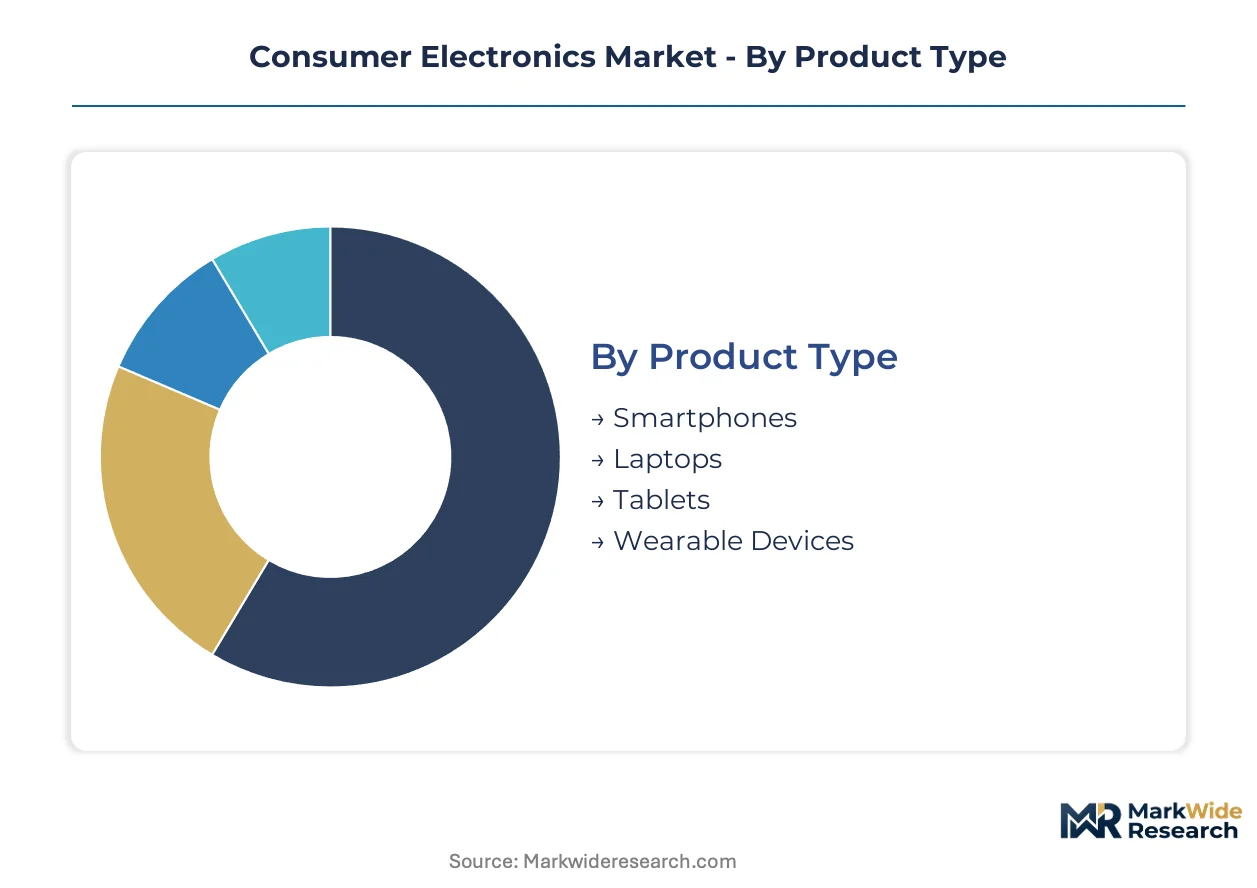
Segmentation in consumer electronics reveals how profit pools split between mature hardware categories and emerging premium niches. Manufacturers allocate R&D and marketing resources differently across these boundaries, with subscription attach rates and component sourcing strategies varying sharply by segment.
Product Type:
Cost tier differentiation separates high-frequency replacement categories from extended-lifecycle equipment, dictating go-to-market cadence and service revenue potential.
- Smartphones:Mature semiconductor architectures dominate bill-of-materials, with application processors and camera modules capturing disproportionate value. Replacement cycles have extended to 36-48 months in developed markets, compressing volume growth and forcing manufacturers toward trade-in programs and financing bundles.
- Wearable Devices:Biometric sensor fusion—combining optical heart rate, SpO2, and ECG—drives medical-adjacent positioning and premium pricing. Demand concentrates among health-conscious consumers in North America and Western Europe, where insurance wellness programs subsidize device purchases.
- Laptops:Enterprise fleet procurement and education sector tenders sustain volume, though ARM-based architectures are eroding x86 incumbent margins.
- Tablets:Content consumption and stylus-enabled creative workflows define the remaining addressable market after smartphone screen size expansion absorbed casual use cases.
Smartphones command the established base. The steepest expansion runs through Wearable Devices.
Technology:
Display panel technology segmentation tracks manufacturing yield maturity and capital intensity, with foundry capacity allocation determining competitive access.
- OLED:Organic electroluminescent layers enable self-emissive pixels without backlighting, delivering contrast ratios exceeding 1,000,000:1 and flexible substrate compatibility. Samsung Display and LG Display anchor supply through captive vapor deposition capacity, with Chinese panel makers expanding Gen 6 flexible OLED lines to challenge Korean incumbent pricing power.
- MicroLED:Inorganic III-nitride emitters eliminate organic degradation pathways and enable modular scaling to arbitrary dimensions. Mass transfer yield constraints—transferring millions of microscopic chips per substrate—suppress commercial volume and sustain laboratory-to-factory timelines despite Apple's and Samsung's early tablet and smartwatch commitments.
- LCD:Liquid crystal polarization modulation with LED edge or direct backlighting retains cost advantage in large-format television and entry-tier monitor applications.
- QLED:Quantum dot photoluminescent enhancement layers extend LCD color gamut without abandoning mature TFT-LCD fabrication infrastructure.
LCD retains volume leadership in cost-sensitive applications. MicroLED climbs the fastest toward premium positioning as yield improvements accelerate.
End User:
Customer type segmentation determines pricing architecture, with procurement sophistication and lifecycle management requirements varying across institutional versus individual buyers.
- Individual Consumers:Direct-to-consumer channels and carrier subsidy programs dominate, with brand equity and ecosystem lock-in driving repeat purchase decisions.
- Corporates:Unified endpoint management requirements and security certification mandates favor enterprise-grade device families with extended support commitments.
- Educational Institutions:Volume tenders with multi-year refresh cycles and ruggedized specifications define procurement, with Chrome OS and iPadOS capturing distinct institutional preferences.
- Retailers:Point-of-sale hardware, inventory management handhelds, and customer-facing display installations constitute specialized commercial demand with custom industrial design requirements.
Individual Consumers anchor manufacturer marketing investment. Corporates gain share fastest as hybrid work policies institutionalize device provisioning.
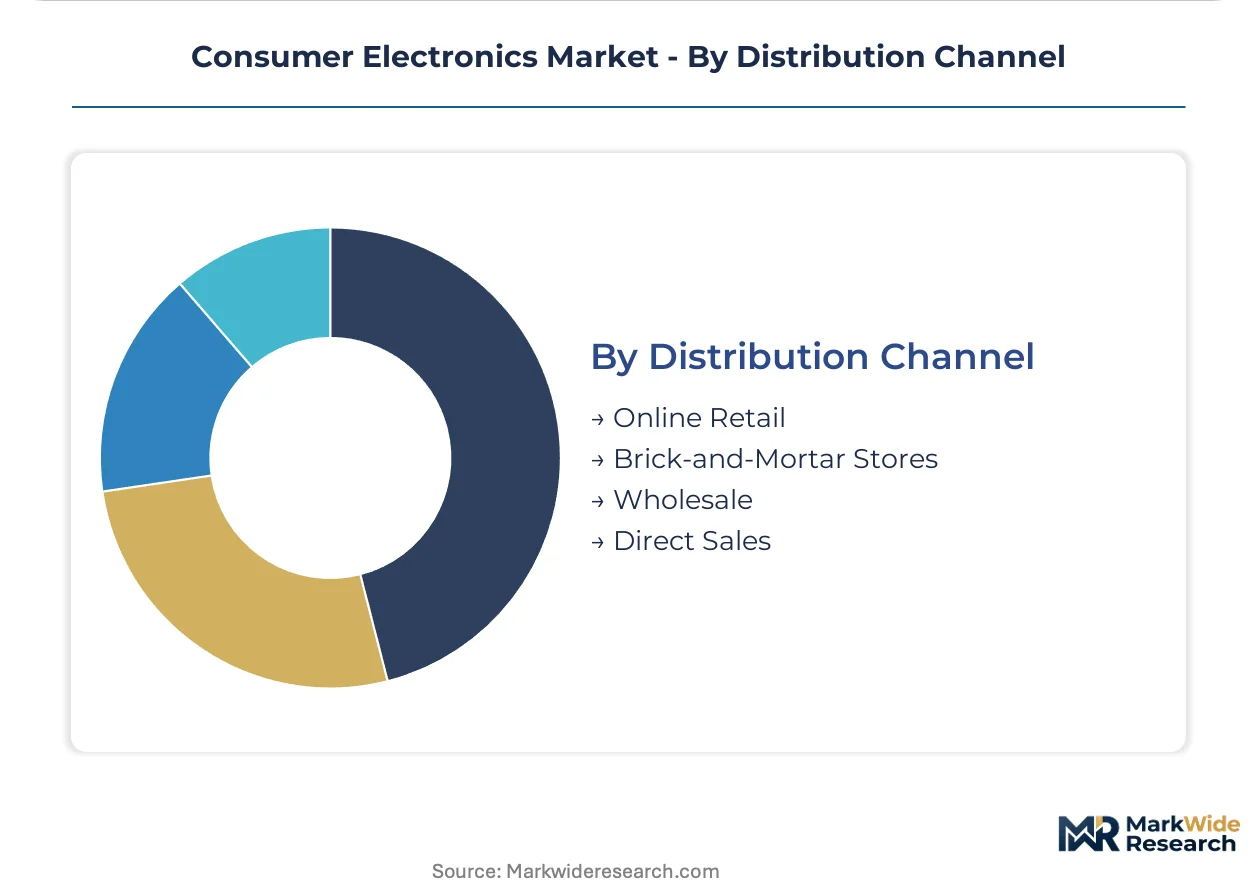
Distribution Channel:
Channel mix reflects inventory risk allocation and customer acquisition cost tradeoffs, with direct relationships displacing intermediary margin extraction.
- Online Retail:Platform aggregators and manufacturer direct-to-consumer sites capture smartphone and laptop volume, with logistics infrastructure and return processing capabilities determining competitive position.
- Brick-and-Mortar Stores:Experiential retail—hands-on device interaction and immediate technical support—retains importance for premium product launches and complex ecosystem sales.
- Wholesale:Volume aggregation for secondary markets and regional distributors sustains access in markets with underdeveloped e-commerce infrastructure.
- Direct Sales:Enterprise account teams and institutional procurement relationships capture corporate and education sector contracts with customized service level agreements.
Online Retail commands transaction volume. Direct Sales expands most quickly as manufacturers build institutional sales capabilities and bypass channel margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Chinese buyers prioritize ecosystem-integrated devices with local service compatibility. German and Japanese markets emphasize repairability scoring and extended product lifecycles under circular economy mandates.
United States
Enterprise fleet procurement and insurance-subsidized wellness devices drive commercial demand. The FCC governs electromagnetic emissions and spectrum allocation for wireless devices. Austin and Seattle anchor hardware design and cloud service integration hubs respectively.
China
Domestic brands capture smartphone and wearable volume through super-app ecosystem lock-in. MIIT enforces GB standards for device interoperability and network access. Shenzhen's manufacturing cluster supplies semiconductors and display modules to global brands.
Germany
Industrial automation and premium automotive integration sustain demand for ruggedized tablets and AR headsets. The EU Ecodesign Framework mandates repairability scoring and standby power limits. Bavaria's precision engineering corridor concentrates R&D for industrial-grade consumer devices.
Japan
Aging demographics propel health-monitoring wearables and simplified interface designs. METI enforces home appliance recycling quotas under extended producer responsibility laws. Kansai's Osaka-Kobe manufacturing zone specializes in compact sensor modules and battery systems.
India
Price-sensitive smartphone demand and education sector tablet tenders define volume procurement. The PLI scheme attracts assembly capacity relocation with production-linked incentives. Tamil Nadu's Sriperumbudur electronics corridor hosts Foxconn and Dixon manufacturing facilities.
Consumer Electronics Market Vendor Landscape
Capability concentration sits with integrated hardware-software architects; scale advantage sits with contract manufacturers and component suppliers. The market structures around three tiers: ecosystem orchestrators commanding premium pricing, display and semiconductor specialists capturing component value, and assembly-scale operators extracting manufacturing margin. Dominant competitive moves include captive production of critical subsystems and direct-to-consumer channel expansion bypassing traditional retail.
Within the ecosystem orchestrator tier, Apple and Samsung Electronics exemplify divergent approaches to platform control. Apple occupies a position defined by vertical hardware-software integration and service revenue attachment. Samsung Electronics anchors display supply through captive OLED production while spanning multiple device categories. Foxconn represents the scale-driven assembly archetype, manufacturing devices for multinational brands without direct consumer market presence.
| Leading Market Players |
|---|
| Sony |
| BYD |
| Apple |
| Dell |
| HP |
| Samsung Electronics |
| LG |
| Lenovo |
| Foxconn |
| Others |
Supply Flow & Price Mechanics
Shenzhen's electronics manufacturing cluster concentrates semiconductor and display module capacity, translating component scarcity dynamics into asymmetric pricing power for brands with captive supply arrangements versus those exposed to spot-market volatility.
Pricing Analysis
Long-term offtake contracts dominate strategic component procurement, with OLED panel supply secured through multi-year agreements between Samsung Display and Apple while smaller manufacturers absorb spot-market premiums. Three-tier pricing structure across premium, standard, and economy levels separates ecosystem-integrated devices from white-label alternatives, with certification tiers under EU Ecodesign and RoHS creating additional stratification. Pricing pressure stems from ARM-based architecture commoditization in laptops and tablets, compressing margins for x86 incumbents. Enterprise fleet buyers exhibit lowest price sensitivity due to total-cost-of-ownership framing, whereas education sector tenders in India drive aggressive cost competition.
Supply Chain Analysis
Export-control regimes restricting advanced semiconductor manufacturing equipment to China fragment foundry capacity allocation, forcing supply chain reconfiguration around Taiwan, South Korea, and Vietnam assembly zones. Rare earth magnet and lithium-ion battery materials draw from concentrated Chinese refining and Korean cell production, creating input dependencies for motor and power management subsystems. Single-source vulnerability runs through TSMC's advanced node fabrication for application processors. Distribution runs through direct-to-consumer channels and enterprise account teams, with traditional wholesale margins eroding as manufacturers bypass intermediary layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against cloud-streamed computing and extended-reality interfaces that threaten to displace traditional device categories.
For Market Incumbents: Build switching-cost moats through health-data platform lock-in and seamless multi-device synchronization. Samsung Electronics and Apple already execute this through biometric sensor fusion and cross-product continuity features. Defensive consolidation requires captive OLED or MicroLED capacity to secure display supply against Chinese panel maker expansion. Vertical integration into custom silicon design—exemplified by Apple's M-series processors—preserves margin against ARM licensing commoditization. For New Entrants and Emerging Players: India's Tamil Nadu electronics corridor offers underpenetrated assembly capacity where PLI incentives reduce landed cost disadvantages against Shenzhen incumbents. White-space targets include ruggedized tablets for German industrial automation and simplified-interface wearables for Japan's aging demographics. Go-to-market through insurance wellness program partnerships replicates the subsidy model that drove North American wearable adoption. For Investors and Strategic Acquirers: Long-term, this sits as a platform-ecosystem play because recurring software revenue attachment determines valuation multiples beyond hardware margin extraction. Acquisition targets should display semiconductor design capabilities or health-regulatory clearances that accelerate time-to-market. The signal to watch is right-to-repair mandate enforcement breadth—aggressive unbundling of service revenue would compress incumbent cash flows and redirect value toward independent repair marketplaces.| Strategic Initiative | Industry Significance |
|---|---|
| Custom Silicon Development | Apple's M-series and Google's Tensor chips demonstrate margin preservation against Qualcomm licensing. |
| Health Regulatory Clearance | FDA ECG and SpO2 approvals enable medical-adjacent positioning and insurance subsidy eligibility. |
| Display Technology Transition | MicroLED mass transfer yield improvements would disrupt Samsung and LG OLED captive supply advantages. |
| Direct-to-Consumer Channel Expansion | Enterprise account teams bypass value-added reseller margin extraction in North American fleet procurement. |
| Circular Design Certification | German repairability scoring compliance under EU Ecodesign protects European market access against withdrawal threats. |
Methodological Framework
A spread of perspectives from semiconductor procurement executives, display panel manufacturing leads, enterprise IT directors, health insurance wellness program managers, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, MIIT GB standard publications, EU Ecodesign directive enforcement records, and hyperscaler device ecosystem disclosures. Bottom-up bill-of-materials analysis and top-down category spending estimates were triangulated against trade flow data from Chinese customs and Korean export statistics.
Demand-supply-balance framing anchored the forecast framework, with smartphone replacement cycle extension, wearable health-monitoring penetration curves, and enterprise fleet refresh patterns modeled across product type, display technology, and end-user segmentation dimensions. CAGRs were derived from installed base evolution and average selling price trajectory analysis. Industry-specific inputs included semiconductor foundry capacity allocation announcements and PLI scheme disbursement timelines for Indian manufacturing relocation.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-streamed computing providers or extended-reality hardware entrants would shift outcomes beyond modeled boundaries. Material shifts in EU battery passport compliance timelines or US-China semiconductor equipment export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Gaming Laptops and Desktops Market
Consumer Electronics
Global Home Audio System Market
Consumer Electronics
Consumer Electronics Electric Motor Market
Consumer Electronics
Instant Camera's Consumable Market
Consumer Electronics
HiFi Electronics Market
Consumer Electronics
Home Entertainment Devices Market
Consumer Electronics
Smart Aquarium Devices Market
Consumer Electronics
UAE Consumer Electronics Market
Consumer Electronics
US Mobile Phone Accessories Market
Consumer Electronics
Smart DJ Controller Market
Consumer Electronics
Vape Cartridge Market
Consumer Electronics
Headsets for PC Market
Consumer Electronics
Global Tablet Keyboards Market
Consumer Electronics
True Wireless Stereo Market
Consumer Electronics
Pillow Holder for Tablets Market
Consumer Electronics
China Massage Equipment Market