
 Sleep Headphones Market | 2026-2036
Sleep Headphones Market Size, Share, and Industry Trends Forecast 2026-2036
Sleep Headphones Market Insights
Memory foam is recalibrating cost structures across the sleep headphones category as manufacturers substitute traditional silicone padding with pressure-relieving open-cell formulations. Bose Corporation leverages its acoustic engineering heritage to sustain premium positioning in the active noise cancellation segment. AcousticSheep LLC anchors the headband category with fleece-wrapped designs optimized for side-sleepers. Sony Corporation differentiates through proprietary driver miniaturization that competes on audio fidelity against bulkier over-ear alternatives.
Sleep headphones are wearable audio devices engineered for extended nocturnal use, typically incorporating sub-20 Hz low-frequency response, Bluetooth Low Energy connectivity, and biocompatible skin-contact materials to deliver ambient sound or noise masking without sleep disruption. The headband segment dominates unit volumes due to its compatibility with supine and lateral sleeping positions, while active noise cancellation technology captures disproportionate margin pools as consumers trade up from basic white noise functionality. Wireless Bluetooth configurations lead retail sell-through across online channels, though wired variants persist in clinical settings where electromagnetic sensitivity concerns persist among sleep disorder patients.
The Federal Communications Commission governs radio frequency emissions for wireless sleep headphones sold in the United States, while the European Telecommunications Standards Institute enforces RED compliance for Bluetooth implementations across EU member states. Japan's Ministry of Internal Affairs and Communications certifies radio law conformance, creating a fragmented compliance landscape that elevates testing costs for multi-region launches. Stakeholders must monitor evolving electromagnetic field exposure limits and battery transport regulations as product architectures integrate larger cells to support all-night operation.
Market Dynamics
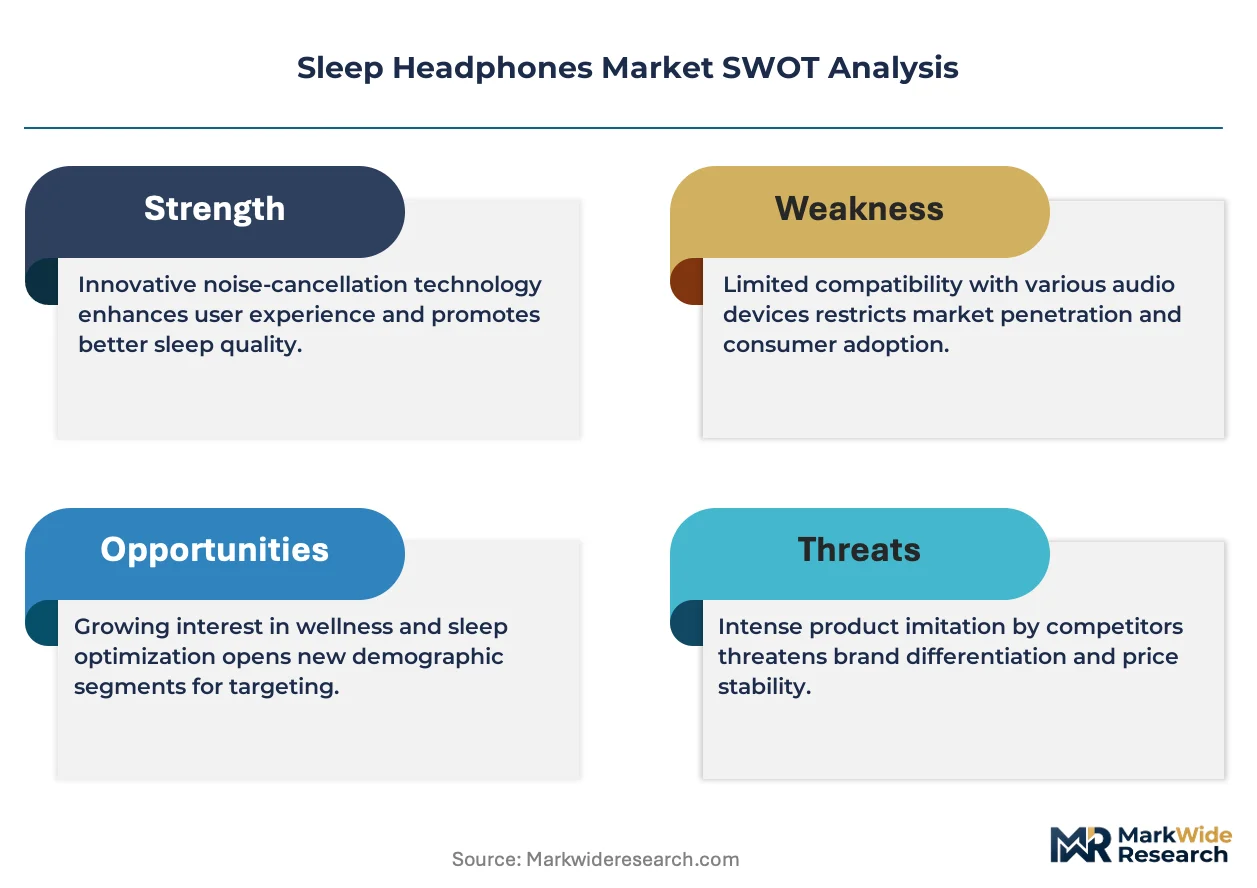
Memory foam substitution is compressing material costs while Bluetooth Low Energy certification requirements are fragmenting compliance spend across multi-region launches, creating divergent margin structures between single-market and global suppliers.
Growth Catalysts
- EU Radio Equipment Directive:Electromagnetic exposure standards are tightening procurement specifications for sleep clinics and wellness centers across Germany, France, and the Netherlands, favoring certified headband-style devices.
- Biocompatible skin-contact materials:Open-cell foam formulations are displacing silicone padding in side-sleeping applications, reducing pressure-point complaints and extending average usage duration.
- Sleep hygiene prioritization:Consumer willingness to pay for noise-masking solutions is concentrating demand in the United States, Japan, and Germany, where clinical sleep disorder diagnoses are rising.
Market Restraints
- Polyurethane foam price volatility:Petrochemical feedstock fluctuations are squeezing gross margins for memory foam-dependent manufacturers, particularly those without backward integration into resin supply.
- Electromagnetic sensitivity concerns:Wired variants persist in clinical settings where FCC emission limits create patient hesitation, limiting wireless penetration among sleep disorder specialists.
- Battery transport regulations:Larger cell architectures required for all-night operation are triggering IATA and DOT hazardous material compliance costs that elevate landed costs for direct-to-consumer channels.
Strategic Opportunities
- Japan's Ministry of Internal Affairs certification:Radio law conformance requirements create first-mover advantages for brands establishing local testing partnerships before competitors complete multi-year approval cycles.
- Active noise cancellation convergence:Miniaturized driver technology is merging with biometric sleep tracking, opening premium positioning for devices that combine acoustic masking with circadian rhythm monitoring.
- Sleep clinic channel expansion:Direct procurement relationships with hospital-affiliated sleep centers in the United States bypass retail margin compression while building clinical credibility for consumer crossover.
Industry Challenges
- Bluetooth SIG certification timelines:Interoperability testing queues are extending product launch windows by four to six months, delaying revenue recognition for seasonal sleep hygiene purchasing cycles.
- Acoustic engineering talent scarcity:Driver miniaturization expertise concentrates among former mobile audio engineers, forcing compensation premiums for in-house transducer design capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleep Headphones Market |
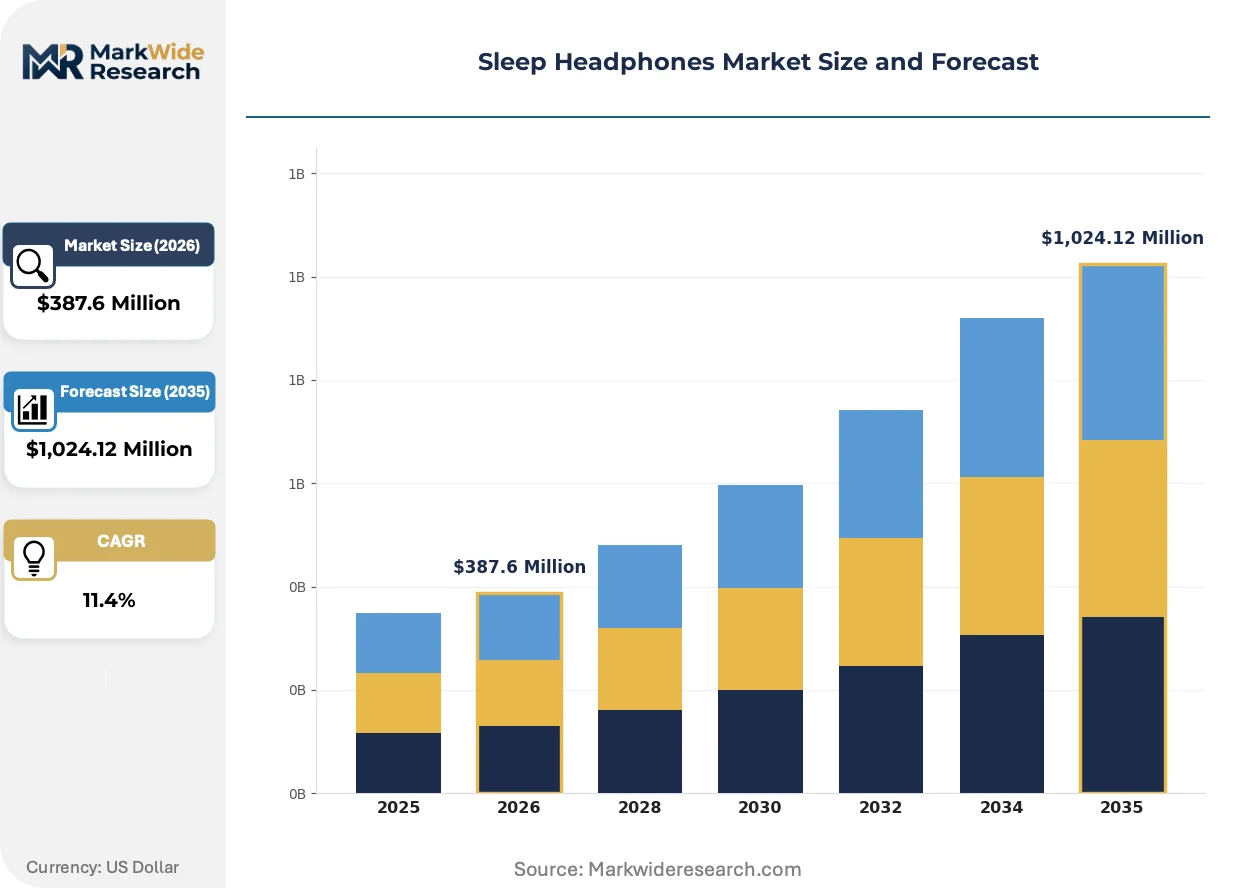
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Over-ear, In-ear, Headband, Sleep Mask Technology: Wireless, Bluetooth, Active Noise Cancellation, White Noise Target Audience: Fitness Enthusiasts, Frequent Travelers, Sleep Disorders, Students Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Mass Merchants |
| Companies Covered | Bose Corporation, Kokoon Technology, AcousticSheep LLC, Sony Corporation, MUSICOZY, Soundcore, Anker, Navly, SnoozeBand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleep Headphones Market Trends and Innovations
Open-cell foam architectures are redrawing competitive boundaries as pressure-relief performance becomes the primary purchasing criterion for side-sleepers. Regulatory fragmentation around electromagnetic exposure is simultaneously elevating compliance costs and creating certification-based segmentation.
Phase-change material integration is expanding into temperature-regulating headband cores that dissipate heat buildup during extended nocturnal wear. Side-sleepers in the United States and Germany are adopting these configurations fastest, driving premium tier expansion as manufacturers reposition thermal comfort as a distinct performance attribute from acoustic isolation.
Japan's Ministry of Internal Affairs and Communications is enforcing stricter radio law conformance verification for Bluetooth implementations, extending certification timelines and elevating testing costs for multi-region product launches. Sleep headphone vendors targeting Japanese distribution are responding by establishing captive testing relationships with Tokyo-based electromagnetic compatibility laboratories to compress approval cycles.
Direct-to-consumer channel consolidation is compressing traditional retail margins as sleep hygiene brands bypass electronics superstores in favor of specialized wellness platforms and clinical referral networks. Subscription-based replacement programs for foam padding and driver components are displacing one-time transactions in the United States, locking in recurring revenue streams while reducing customer acquisition costs through sleep clinic endorsement pipelines.
Sleep Headphones Market Segmentation
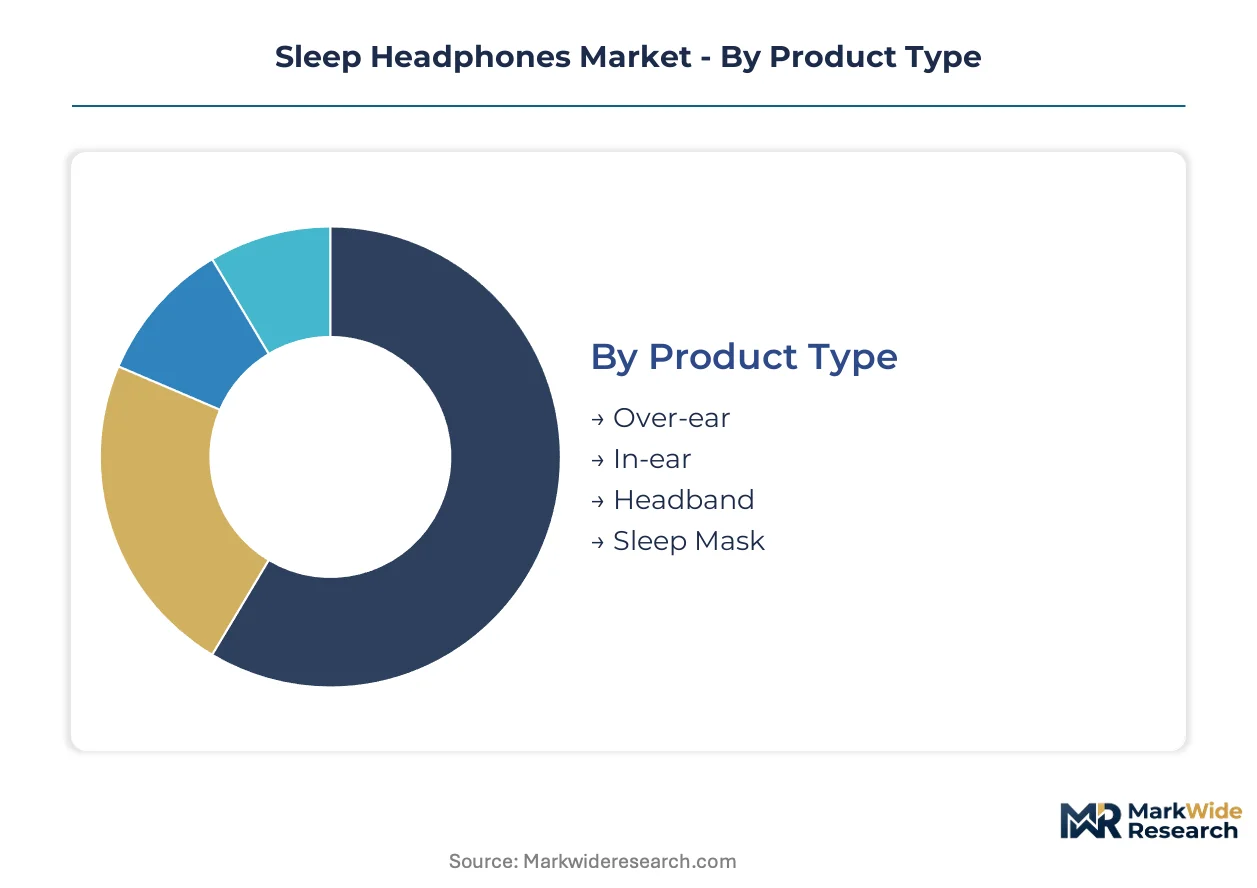
Sleep headphone architectures diverge sharply between clinical-grade precision and consumer convenience, with material science and connectivity standards determining addressable market scope. Segment boundaries are hardening as FCC and EU Radio Equipment Directive certifications create technical moats between professional and mass-market tiers.
Product Type:
Headband configurations dominate unit volumes through side-sleeping compatibility, while active noise cancellation over-ear models command disproportionate margin pools in premium sleep hygiene applications.
- Over-ear:Circumaural designs with memory foam cushioning deliver acoustic isolation through passive damping and active cancellation layers. Demand concentrates among diagnosed sleep disorder patients in Germany and the United States where clinical recommendations favor pressure distribution across larger surface areas.
- In-ear:Miniaturized silicone or foam-tipped inserts optimized for minimal protrusion during lateral positioning. Frequent travelers in Japan and domestic flight corridors favor these for packability, though electromagnetic sensitivity concerns limit penetration in hospital-affiliated sleep clinics.
- Headband:Fleece-wrapped or mesh-constructed bands with embedded flat drivers. Side-sleepers drive volume expansion across direct-to-consumer channels.
- Sleep Mask:Integrated light-blocking fabrics with bone-conduction or near-ear audio elements. Wellness center procurement is expanding fastest for this hybrid category.
Mature deployment sits with headband configurations. Newer deployment is concentrated in sleep mask hybrids combining photic blocking with acoustic masking.
Technology:
Wireless architectures are displacing tethered alternatives as Bluetooth Low Energy certification costs stabilize, though wired persistence in clinical settings reflects electromagnetic exposure liability concerns.
- Wireless:Radio frequency transmission operating under FCC Part 15 and EU RED frameworks. Online retail channels in the United States and Germany show strongest sell-through as consumers prioritize bedroom mobility.
- Bluetooth:Short-range wireless protocol with SIG interoperability certification. Battery transport regulations under IATA guidelines are elevating landed costs for direct-to-consumer shipments.
- Active Noise Cancellation:Feed-forward and feed-back microphone arrays generating inverse waveforms. Sleep clinics in Japan are expanding procurement of certified units.
- White Noise:Pre-programmed or algorithmic sound generation without external audio input. Students and price-sensitive segments sustain volume in mass merchant channels.
Certification-heavy deployment sits with active noise cancellation. Volume expansion is climbing fastest in white noise implementations for education and co-living applications.
Target Audience:
Clinical diagnosis rates are reshaping audience prioritization as sleep disorder prescriptions create reimbursement-adjacent demand distinct from wellness-motivated purchasing.
- Sleep Disorders:Insomnia, sleep apnea, and circadian rhythm disruption patients under physician care. Germany's statutory health insurance system and United States Medicare Advantage plans are expanding coverage for prescribed devices.
- Frequent Travelers:Aviation and long-distance rail passengers seeking portable noise masking. Japan's domestic route density and Germany's intercity rail network sustain concentrated demand.
- Fitness Enthusiasts:Recovery-focused athletes using sleep tracking integration. Specialty stores are building bundled offerings.
- Students:Dormitory and shared-housing residents managing environmental noise. Mass merchant price points dominate this segment.
Reimbursement-linked deployment sits with sleep disorder patients. Demographic expansion is gaining share fastest among students in urban housing markets.
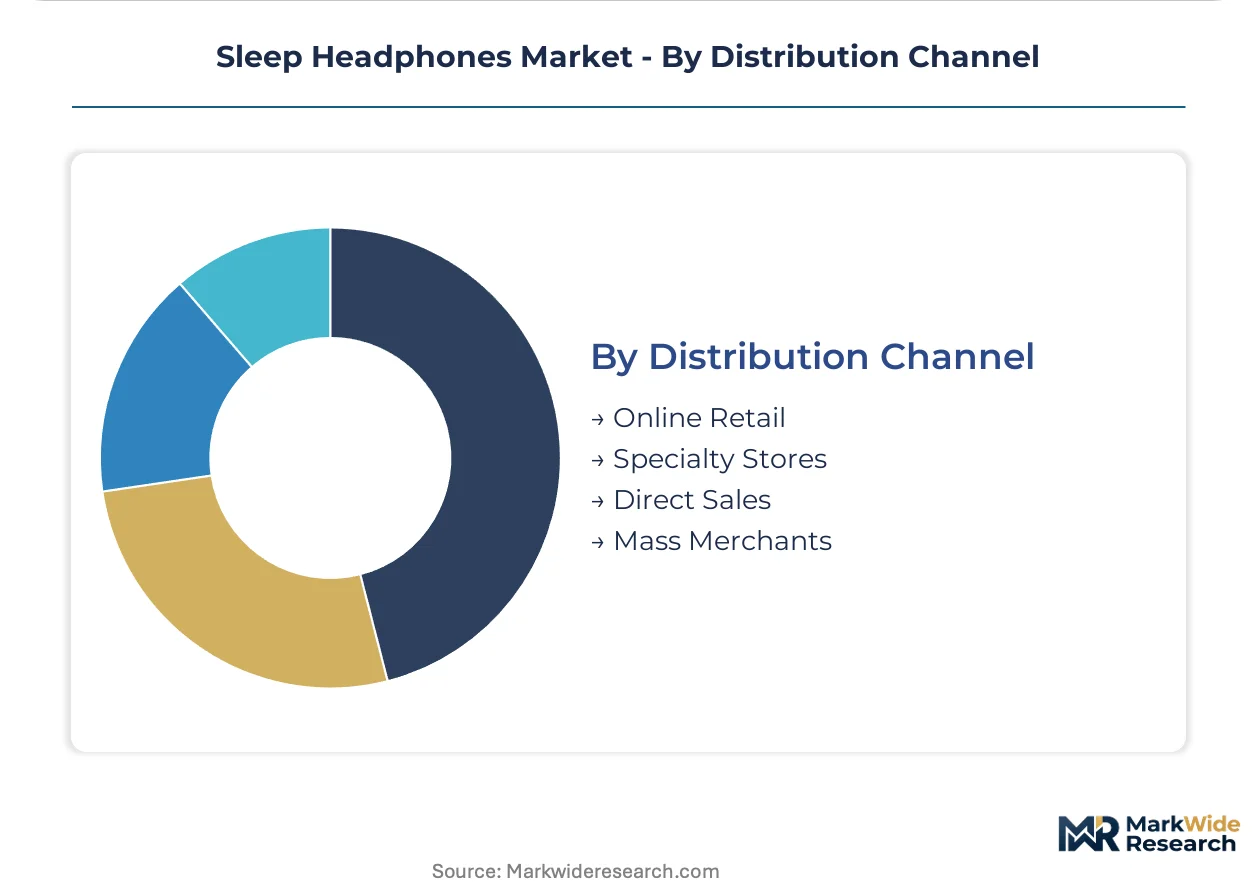
Distribution Channel:
Channel strategy is bifurcating between clinical credibility building and margin preservation, with sleep clinic endorsement pipelines reducing customer acquisition costs for subscription-based replacement programs.
- Direct Sales:Manufacturer-controlled e-commerce and clinical referral networks. United States hospital-affiliated sleep centers are bypassing retail markups through procurement relationships.
- Online Retail:Third-party marketplace and direct-to-consumer platforms. Germany's specialized wellness platforms are displacing electronics superstores.
- Specialty Stores:Sleep-focused retailers and wellness boutiques. Premium positioning depends on in-person fitting services.
- Mass Merchants:Big-box electronics and general merchandise retailers. Price compression is most severe in this channel.
Margin-preserving deployment sits with direct sales. Volume expansion is climbing fastest in online retail as search-engine optimization replaces physical shelf placement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer willingness to pay for sleep hygiene solutions concentrates in the United States, Germany, and Japan, with clinical sleep disorder diagnoses rising fastest in these markets. Sleep clinics and wellness centers across these geographies are expanding procurement of headband-style devices certified under tightening electromagnetic exposure standards.
United States
Hospital-affiliated sleep centers in Boston and the San Francisco Bay Area are bypassing retail markups through direct procurement relationships with manufacturers. The FCC governs radio frequency emissions for wireless devices, creating compliance costs that favor established suppliers with in-house certification expertise. Subscription-based replacement programs for foam padding are displacing one-time transactions, locking in recurring revenue streams through clinical endorsement pipelines.
Germany
Statutory health insurance system expansion is driving reimbursement-adjacent demand for prescribed sleep disorder devices in Munich and Hamburg metropolitan areas. The EU Radio Equipment Directive enforces RED compliance for Bluetooth implementations, tightening procurement specifications for sleep clinics across Bavaria and North Rhine-Westphalia. Specialized wellness platforms are displacing electronics superstores, compressing traditional retail margins.
Japan
Domestic route density sustains concentrated demand among frequent travelers in Tokyo and Osaka, while sleep clinics in Nagoya expand procurement of certified active noise cancellation units. The Ministry of Internal Affairs and Communications enforces stricter radio law conformance verification, extending certification timelines for multi-region launches. Vendors are establishing captive testing relationships with Tokyo-based electromagnetic compatibility laboratories to compress approval cycles.
United Kingdom
Wellness-motivated purchasing in London and the Southeast is converging with NHS sleep clinic procurement pilot programs in Manchester and Birmingham. CE marking requirements under EU-UK alignment protocols govern electromagnetic exposure standards for Bluetooth-enabled wearables. Direct-to-consumer brands are building clinical credibility through partnerships with hospital-affiliated sleep centers in the Midlands.
South Korea
Recovery-focused athletes in Seoul and Busan are driving demand for sleep tracking integration in premium headband configurations. The Korea Communications Commission certifies radio law conformance for wireless audio devices, creating regulatory overlap with EU and Japanese standards. Manufacturing clusters in Gyeonggi Province are supplying memory foam components to global sleep headphone assemblers.
Sleep Headphones Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with acoustic engineering heritage determining premium positioning while material science capabilities govern cost-competitive tiers. The vendor base organizes around three strategic archetypes: heritage audio brands leveraging transducer miniaturization expertise, sleep-focused specialists optimizing side-sleeping ergonomics, and consumer electronics platforms exploiting supply chain scale. Competitive moves concentrate on M&A for acoustic engineering talent and vertical integration into biocompatible foam formulations.
Within the heritage audio tier, Bose Corporation and Sony Corporation occupy positions defined by proprietary driver technology and brand equity in noise cancellation applications. AcousticSheep LLC anchors the specialist segment with fleece-wrapped headband designs optimized for nocturnal ergonomics. These three exemplify divergent paths to margin preservation: engineering-led premium pricing, clinical credibility through sleep-focused positioning, and material differentiation for side-sleeping comfort.
| Leading Market Players |
|---|
| Bose Corporation |
| Kokoon Technology |
| AcousticSheep LLC |
| Sony Corporation |
| MUSICOZY |
| Soundcore |
| Anker |
| Navly |
| SnoozeBand |
| Others |
Pricing and Supply Chain Analysis
Sleep clinic procurement specifications for FCC and EU RED certified headband devices are forcing manufacturers to absorb elevated electromagnetic compliance costs while maintaining retail accessibility, compressing margins for non-integrated assemblers and accelerating tier consolidation.
Pricing Analysis
Volume expansion concentrates in economy-tier white noise headbands while margin pools accrue to premium active noise cancellation configurations. Three-tier pricing structure across premium, standard, and economy levels separates certification-heavy clinical-grade units from direct-to-consumer wellness devices. Cost compression in the mid-tier is intensifying because memory foam substitution has commoditized pressure-relief performance. Students and dormitory residents exhibit highest price sensitivity, whereas sleep disorder patients under physician care demonstrate lowest sensitivity due to reimbursement adjacency.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese Bluetooth module suppliers and South Korean lithium-polymer cell manufacturers. Memory foam feedstock draws from Chinese petrochemical processors and German chemical specialists, while acoustic driver fabrication centers on Japanese precision manufacturers and Chinese contract assemblers. Tariff exposure on electronics components elevates landed costs for North American distribution. Distribution runs through direct-to-consumer platforms, hospital-affiliated sleep clinic procurement networks, and specialized wellness retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification-capable suppliers as electromagnetic compliance costs and Bluetooth SIG testing timelines force sub-scale assemblers toward exit or acquisition.
For Market Incumbents: Hedge against margin erosion by securing captive testing relationships with Tokyo-based electromagnetic compatibility laboratories before Japanese radio law conformance timelines extend further. Deepen backward integration into open-cell foam formulations to offset polyurethane price volatility and differentiate pressure-relief performance. Prioritize direct procurement partnerships with hospital-affiliated sleep centers in Boston and the San Francisco Bay Area to bypass retail margin compression. For New Entrants and Emerging Players: The price-point gap between premium active noise cancellation headbands and economy white noise alternatives offers white-space entry for hybrid sleep mask configurations with integrated photic blocking. Target wellness center procurement channels in Germany's statutory health insurance expansion zones where reimbursement pathways are forming. Pursue go-to-market alignment with specialized wellness platforms displacing electronics superstores. For Investors and Strategic Acquirers: The window for entry favors acoustic engineering talent pools and certification-capable manufacturing footprints over brand equity alone. Long-term viability hinges on five-to-ten year regulatory convergence around electromagnetic exposure standards and biometric integration capabilities. Monitor Bluetooth SIG certification queue lengths as an inflection indicator for product launch velocity and revenue recognition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Bluetooth SIG Certification Acceleration | Compresses four-to-six month testing queues to capture seasonal sleep hygiene purchasing cycles. |
| Captive Electromagnetic Testing Partnership | Tokyo-based laboratory relationships circumvent Japanese Ministry of Internal Affairs approval bottlenecks. |
| Backward Integration into Foam Formulations | In-house production of open-cell architectures insulates against petrochemical feedstock volatility. |
| Sleep Clinic Direct Procurement | Hospital-affiliated center partnerships in the United States build clinical credibility and recurring replacement revenue. |
| Biometric Sleep Tracking Convergence | Miniaturized driver integration with circadian rhythm monitoring opens premium positioning above acoustic-only devices. |
Research Methodology
Trade databases, customs filings, and Bluetooth SIG certification registries formed the secondary backbone, supplemented by primary interviews with acoustic engineering directors, sleep clinic procurement managers, wellness platform category buyers, and memory foam supply specialists. Bottom-up unit volume estimates derived from point-of-sale data across direct-to-consumer channels and hospital-affiliated procurement networks were cross-validated against top-down market sizing from component supplier shipment disclosures.
Bottom-up modeling of headband, over-ear, in-ear, and sleep mask configurations across wireless, Bluetooth, active noise cancellation, and white noise technologies was reconciled with top-down macroeconomic and demographic trend analysis across the projection horizon. CAGRs were derived from segment-level growth rate synthesis and regulatory impact scenario weighting. Forecast inputs incorporated EU Radio Equipment Directive compliance cost trajectories, battery transport regulation evolution under IATA guidelines, and sleep disorder diagnosis rate projections from clinical registry data.
Inputs from certification registries and customs databases were available through the study window; gaps in proprietary supplier cost structures and unreported direct procurement contract values introduce uncertainty bands around margin estimates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
China Refurbished Smartphone Market
Consumer Electronics
Vape Market
Consumer Electronics
Noise Cancelling Headphones Market
Consumer Electronics
Closed Back Studio Headphone Market
Consumer Electronics
Global Smart Earbuds Market
Consumer Electronics
In-Ear-Monitors (Iems) Market
Consumer Electronics
Portable Laptop Stands Market
Consumer Electronics
Tattoo Stencil Printer Market
Consumer Electronics
Consumer Electronics Retail Market
Consumer Electronics
Asia-Pacific Gaming Keyboard Market
Consumer Electronics
Wrist Dive Computer Market
Consumer Electronics
Earbuds Market
Consumer Electronics
Portable Smart Speaker Market
Consumer Electronics
LAMEA Refurbished and Used Mobile Phones Market
Consumer Electronics
Mexico Smart TV Market
Consumer Electronics
Gaming Computer Market