
 Screen Privacy Protectors Market | 2026-2036
Screen Privacy Protectors Market Size, Share, and Industry Trends Forecast 2026-2036
Screen Privacy Protectors Market Insights
China is reshaping supply dynamics for screen privacy protectors through expanded polymer film extrusion and tempered glass finishing capacity. 3M leverages deep materials science and optical coating patents to sustain premium positioning across enterprise channels. ZAGG competes through broad retail distribution and device-specific SKUs, while PanzerGlass dominates European smartphone accessory shelves with chemically strengthened glass formulations.
Screen privacy protectors are optical-grade filters, typically multi-layer PET or tempered glass constructions with microlouver technology that narrows viewing angles to approximately 60 degrees, designed to prevent visual data exposure in public or shared workspaces. Tempered glass variants command higher unit economics due to scratch resistance and touch sensitivity preservation, while adhesive film maintains volume leadership in price-sensitive corporate bulk procurement. Application segmentation shows laptops and monitors generating the strongest margin pools as enterprise refresh cycles integrate privacy hardware into standard IT deployment packages.
FCC guidelines on electronic device accessories influence US market entry requirements for signal-transparent films, while REACH compliance in Europe governs adhesive chemical composition and recyclability labeling. China's GB standards and MIIT regulations shape export certification pathways for domestic manufacturers. Stakeholders must monitor evolving e-waste directives and right-to-repair legislation that could mandate removability and material disclosure across major economies.
Market Dynamics
Enterprise IT refresh cycles are embedding privacy hardware as standard procurement, converting screen protectors from aftermarket accessories into bundled security infrastructure. This shift compresses pricing power for standalone suppliers while elevating optical-grade specifications across bulk contracts.
Growth Catalysts
- EU AI Act stringency:European corporations are layering physical screen security atop digital compliance frameworks, mandating visual privacy controls in shared workspaces and public-facing terminals.
- Financial services vertical:US banking and insurance regulators enforce visual data protection protocols, requiring microlouver filters on all customer-facing displays and trader workstations.
- Polymer film extrusion scale-up:China's expanded PET and tempered glass finishing capacity is reducing unit input costs for multi-layer optical constructions.
Market Restraints
- Adhesive chemical volatility:REACH compliance in Europe mandates reformulation of pressure-sensitive adhesives, raising certification costs for film-based privacy filters.
- Supply concentration in East Asia:Tempered glass finishing and microlouver lamination capacity clusters in China and South Korea, exposing procurement timelines to regional logistics disruptions.
- Touch sensitivity trade-offs:Thicker glass formulations degrade haptic response, limiting adoption in stylus-dependent creative and medical imaging workflows.
Strategic Opportunities
- India's hybrid workforce expansion:IT procurement teams in Mumbai and Bangalore are initiating bulk privacy filter trials for financial services back-office operations.
- Automotive display integration:Center-stack and rear-seat entertainment screens in premium vehicles represent an emerging application for narrow-viewing-angle optical films.
- Right-to-repair mandates:EU and US state-level legislation is creating demand for removable, non-destructive adhesive formulations that preserve screen integrity during device servicing.
Industry Challenges
- Optical coating talent scarcity:Thin-film deposition and microlouver engineering expertise concentrates at 3M and a handful of Japanese specialty chemical firms.
- FCC signal transparency certification:US market entry requires documented electromagnetic transparency for adhesive films, extending product launch timelines by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screen Privacy Protectors Market |
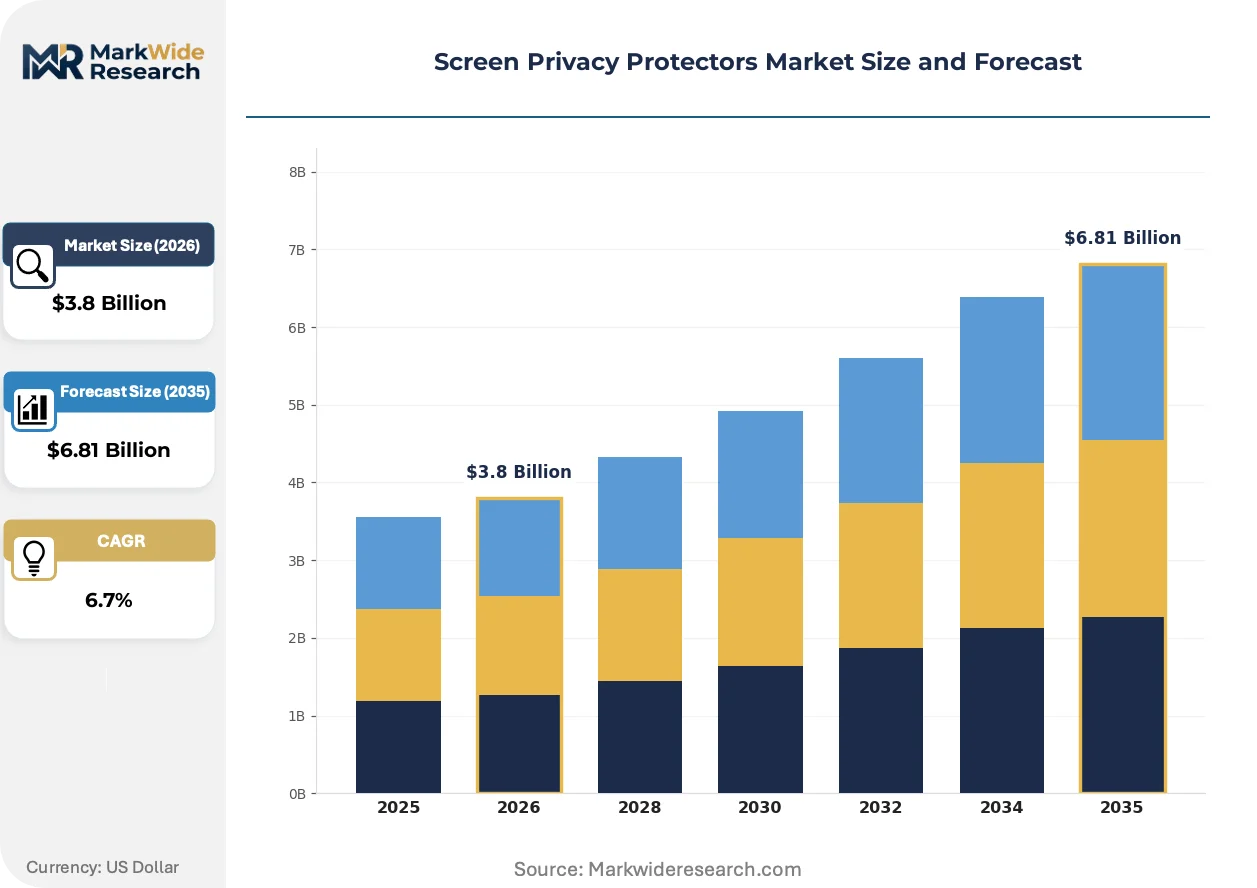
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Film, Tempered Glass, Flip Case, Magnetic Application: Smartphones, Tablets, Laptops, Monitors Material: Polymer, Glass, Nano-Coating, Metal End User: Consumers, Businesses, Educational Institutions, Government |
| Companies Covered | 3M, ZAGG, Belkin, PanzerGlass, OtterBox, Targus, Fellowes, Kensington, Tech Armor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screen Privacy Protectors Market Trends and Innovations
Active-matrix switching technology and biometric-aware displays are converging with static microlouver films, creating adaptive privacy layers that respond to user presence and ambient threat detection.
Nano-patterned light-blocking films are digitizing the transition from fixed-viewing-angle privacy to dynamic, software-controllable opacity. Enterprise security teams in US financial services are piloting these electrochromic constructions for trading floor deployments. This technology is digitizing how visual data protection integrates with centralized IT policy management, compressing the distinction between physical and logical access controls.
REACH chemical disclosure requirements in Europe are forcing adhesive reformulation across the supply base. Manufacturers must now document full material composition and recyclability pathways for PET substrates and silicone pressure-sensitive layers. Tempered glass variants with removable adhesive backings are capturing preference share in German and French corporate procurement as e-waste liability shifts to device owners.
Device-as-a-service leasing models are unbundling privacy hardware from initial equipment procurement. IT asset managers in US healthcare systems now specify privacy filters as separate line items with independent replacement cycles. This pattern is most visible in hospital networks undergoing EHR workstation refreshes, where three-year screen leases pair with annual privacy film replacement schedules.
Screen Privacy Protectors Market Segmentation
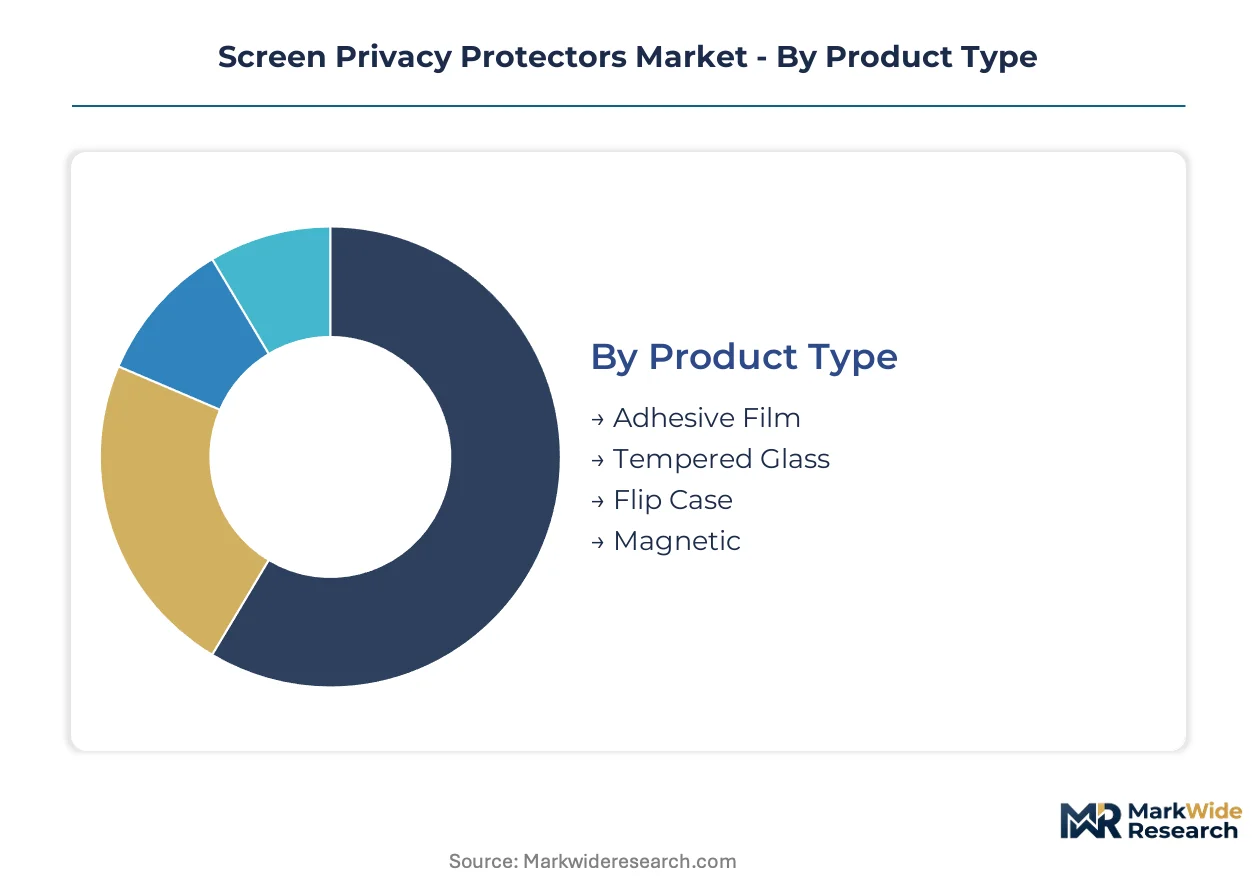
Screen privacy protector segmentation reveals divergent replacement cycles across materials and end-use contexts. Enterprise procurement patterns favor standardized bulk purchasing with shorter refresh intervals, while consumer segments exhibit device-tethered replacement behavior tied to hardware upgrade cycles.
Product Type:
Replacement velocity varies dramatically across construction formats, with adhesive films turning over fastest due to wear-driven degradation and tempered glass commanding longer service intervals.
- Adhesive Film:Multi-layer PET constructions with microlouver optical coatings enable sub-millimeter thickness and flexible deployment across curved displays. Corporate IT procurement in US financial services drives volume through annual refresh schedules tied to workstation lease cycles.
- Tempered Glass:Chemically strengthened silica formulations with oleophobic surface treatments preserve touch sensitivity and scratch resistance. German and French corporate procurement increasingly specifies removable adhesive backings to satisfy e-waste liability shifts.
- Flip Case:Integrated physical barriers combining hinged covers with auxiliary privacy filters. Demand concentrates among mobile professionals in transit-heavy Asian urban corridors.
- Magnetic:Detachable filter assemblies using rare-earth attachment systems for temporary privacy deployment. Gaining preference in shared workspace environments requiring intermittent protection.
Adhesive film dominates installed base. Tempered glass is where expansion concentrates.
Application:
Margin structure inverts across display sizes, with larger-format deployments commanding premium pricing per unit while smartphone-scale volumes drive aggregate revenue.
- Smartphones:Device-specific SKU proliferation matches rapid handset release cycles from Apple, Samsung, and Chinese OEMs. PanzerGlass captures European retail shelf space through chemically strengthened formulations optimized for curved-edge displays.
- Tablets:Mid-format privacy filters serve field service technicians and healthcare bedside documentation workflows. Touch sensitivity trade-offs limit adoption in stylus-dependent creative applications.
- Laptops:Standardized aspect ratios enable universal-fit SKUs with enterprise-friendly bulk packaging. US healthcare EHR workstation refreshes pair three-year device leases with annual privacy film replacement schedules.
- Monitors:Large-format microlouver installations command the strongest margin pools as IT security teams mandate visual privacy controls on all customer-facing displays and trader workstations.
Smartphones dominate installed base. Laptops are gaining share fastest.
Material:
Supply concentration in East Asian chemical processing clusters shapes material availability and certification timelines for Western markets.
- Polymer:PET substrate extrusion and microlouver lamination capacity clusters in China and South Korea. REACH compliance mandates ongoing adhesive reformulation for European market access.
- Glass:Tempered glass finishing requires ion-exchange chemical strengthening baths with proprietary salt formulations. 3M optical coating patents sustain premium positioning across enterprise channels.
- Nano-Coating:Electrochromic and active-matrix switching layers enable software-controllable opacity. US financial services trading floors pilot these adaptive constructions for centralized IT policy integration.
- Metal:Rare-earth magnetic components enable detachable filter assemblies with reusable attachment systems. Supply exposure to Chinese export controls creates procurement timeline risk.
Polymer dominates installed base. Nano-coating represents the steepest expansion trajectory.
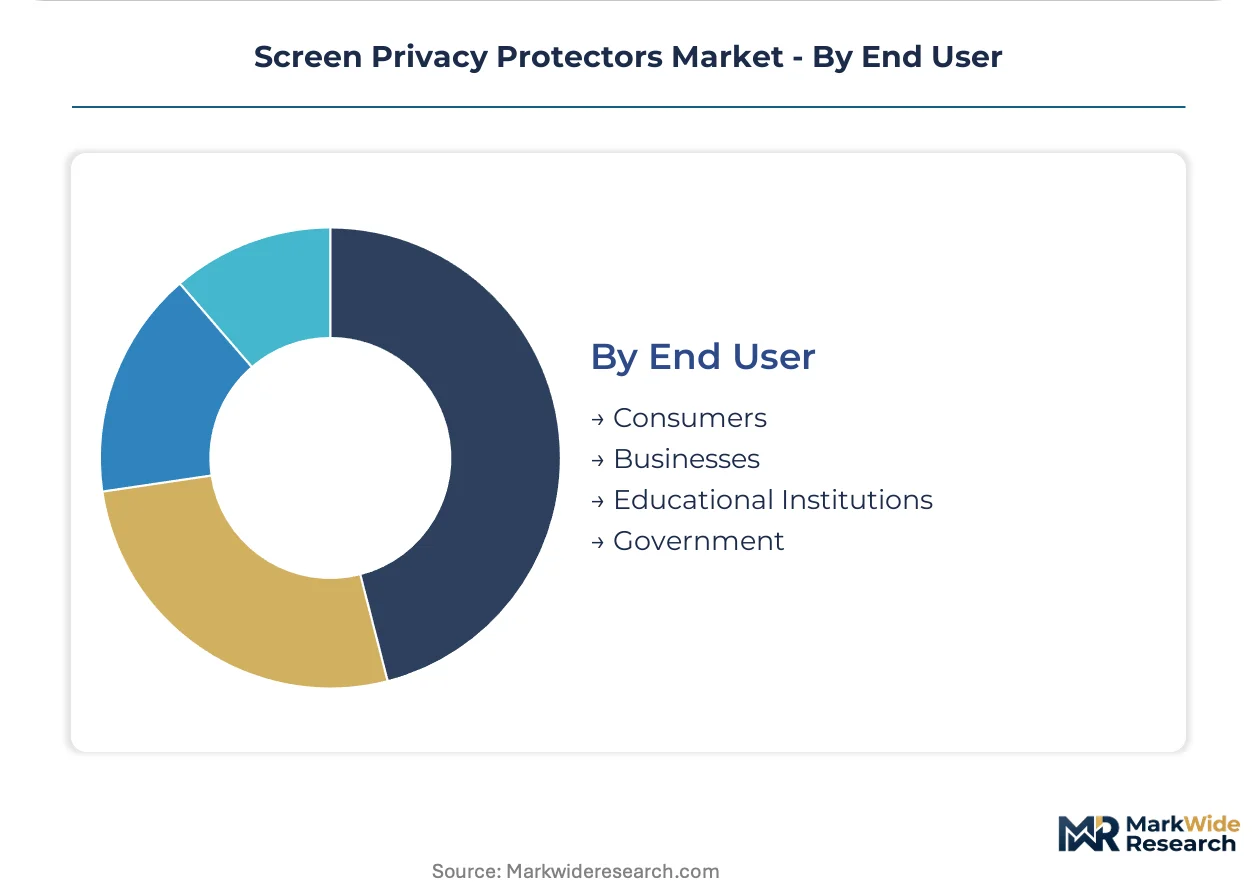
End User:
Procurement sophistication and compliance stringency separate institutional buyers from individual consumers, with regulatory mandates driving standardization in regulated verticals.
- Consumers:Price-sensitive aftermarket purchasing through retail and e-commerce channels. ZAGG competes through broad distribution and device-specific SKU matching.
- Businesses:Enterprise IT refresh cycles embed privacy hardware as bundled security infrastructure. EU AI Act stringency pushes European corporations toward physical screen security as compliance layering.
- Educational Institutions:Bulk procurement for shared device fleets in library and laboratory settings. Budget constraints favor adhesive film over tempered glass specifications.
- Government:Classified workspace protocols mandate narrow-viewing-angle controls on all displays processing sensitive information. FCC signal transparency certification extends product launch timelines.
Consumers dominate installed base. Businesses are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States procurement prioritizes enterprise-grade optical specifications for regulated verticals, while European demand layers physical screen security atop digital compliance frameworks. Asian markets split between premium tempered glass retail consumption and bulk adhesive film deployment for hybrid workforces.
United States
Financial services and healthcare verticals mandate microlouver filters on all customer-facing displays and trader workstations. FCC guidelines on electronic device accessories influence market entry requirements for signal-transparent films. Enterprise IT procurement teams in New York and Chicago drive bulk purchasing for hybrid workforce deployments.
Germany
Corporate procurement increasingly specifies removable adhesive backings to satisfy e-waste liability shifts under REACH compliance. The EU AI Act pushes corporations toward physical screen security as a compliance layer. Industrial clusters in Bavaria and Baden-Württemberg concentrate tempered glass finishing capacity for European distribution.
China
Expanded polymer film extrusion and tempered glass finishing capacity reduces unit input costs for multi-layer optical constructions. GB standards and MIIT regulations shape export certification pathways for domestic manufacturers. Manufacturing concentration in the Yangtze River Delta and Pearl River Delta feeds global supply chains.
India
IT procurement teams in Mumbai and Bangalore initiate bulk privacy filter trials for financial services back-office operations. BIS certification requirements govern adhesive chemical composition for imported films. Karnataka and Maharashtra host expanding enterprise technology deployment for hybrid workforce security infrastructure.
Japan
Thin-film deposition and microlouver engineering expertise concentrates among specialty chemical firms serving precision optical markets. METI standards influence electrochromic and active-matrix switching layer development. Industrial clusters in Kanto and Kansai regions supply advanced nano-coating technologies for adaptive privacy applications.
Screen Privacy Protectors Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around optical-grade specification leaders and high-volume fabricators serving distinct procurement channels. Three archetypes dominate: materials science specialists with patent-protected coating technologies, retail-distributed brands with device-specific SKU proliferation, and contract manufacturers serving enterprise bulk procurement. Competitive moves center on adhesive reformulation for regulatory compliance and capacity expansion in polymer extrusion.
Among materials science specialists, 3M leverages deep optical coating patents to sustain premium positioning across enterprise channels. ZAGG competes through broad retail distribution and device-specific SKU matching. PanzerGlass occupies a position within European smartphone accessory retail through chemically strengthened glass formulations. These three exemplify how capability depth, scale reach, and geographic focus create defendable positions across divergent customer segments.
| Leading Market Players |
|---|
| 3M |
| ZAGG |
| Belkin |
| PanzerGlass |
| OtterBox |
| Targus |
| Fellowes |
| Kensington |
| Tech Armor |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese PET extrusion and tempered glass finishing is compressing supplier margins while enabling aggressive pricing postures for bulk enterprise contracts. This utilization dynamic rewards buyers with volume leverage while squeezing standalone film fabricators into commodity positioning.
Pricing Analysis
Contract-based long-term offtake agreements dominate enterprise procurement, with annual refresh schedules tied to IT lease cycles creating predictable revenue streams for suppliers. Price differentiation rests on optical-grade certification tier and volume scale, with microlouver precision specifications commanding premiums in financial services verticals. Pricing pressure stems from China's expanded polymer film capacity flooding mid-tier segments with lower-cost alternatives. Adhesive film buyers in educational institutions exhibit highest price sensitivity, while government classified workspace procurement shows least sensitivity due to mandated compliance requirements.
Supply Chain Analysis
Export-control regimes on rare-earth magnetic components and advanced optical coating equipment limit technology transfer from Japanese specialty chemical firms to emerging manufacturers. Supply concentrates in China for PET substrate extrusion, South Korea for microlouver lamination, and Germany for tempered glass chemical strengthening. Raw material dependencies include optical-grade PET resin, silicone pressure-sensitive adhesives, and ion-exchange salt formulations for glass strengthening. Single-source vulnerability in thin-film deposition equipment creates procurement timeline risk. Distribution runs through enterprise IT resellers, OEM bundling agreements, and retail consumer electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise IT refresh cycles signal cyclical recovery as deferred security infrastructure spending converts privacy hardware from discretionary accessory to mandated procurement line item.
For Market Incumbents: Entrench optical-grade specification leadership through deeper patent licensing of microlouver engineering expertise, while expanding captive PET extrusion capacity in Yangtze River Delta clusters to offset margin compression from Chinese commodity entrants. Threat substitution from electrochromic active-matrix technologies demands accelerated R&D investment in software-controllable opacity layers. For New Entrants and Emerging Players: Establish a beachhead in India's financial services back-office procurement trials by offering BIS-certified adhesive films with localized logistics support from Karnataka and Maharashtra distribution nodes. White-space opportunity concentrates in automotive center-stack display integration for premium vehicle OEMs, with removable magnetic attachment systems addressing right-to-repair compliance requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enterprise IT bundling specialists with three-year workstation lease attachments and annual privacy filter replacement schedules. Long-term viability over the next decade hinges on regulatory mandate durability across GDPR, EU AI Act, and US financial services visual data protection protocols. Acquisition target archetype: mid-scale optical coating specialists with REACH-compliant adhesive formulations and established German corporate procurement relationships. Signal to watch: electrochromic pilot adoption rates on US trading floors as inflection indicator for technology substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Adhesive Reformulation for REACH Compliance | ECHA chemical disclosure mandates force full material composition transparency across European supply chains. |
| Capacity Expansion in Polymer Film Extrusion | Yangtze River Delta manufacturing clusters reduce unit input costs for multi-layer optical constructions. |
| Enterprise IT Bundling Partnership | Three-year device lease cycles with annual privacy filter replacements generate predictable recurring revenue. |
| Active-Matrix Switching R&D Investment | US financial services trading floor pilots validate software-controllable opacity for centralized policy management. |
| Automotive Display Integration Program | Premium vehicle center-stack and rear-seat entertainment screens represent emerging narrow-viewing-angle applications. |
Research Methodology
Operator-level perspectives from IT procurement managers, optical coating engineers, enterprise security officers, and adhesive formulation chemists anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through SEC filings of listed component suppliers, customs trade data for PET film and tempered glass imports, FCC equipment authorization databases, and ECHA REACH registration dossiers. Bottom-up demand modeling across end-user segments triangulated against top-down supply capacity assessments from Chinese MIIT production statistics and German industrial cluster output data.
Scenario-bracketing around regulatory enforcement intensity and enterprise IT spending cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product construction format, application display size, material substrate type, and end-user procurement sophistication tier. CAGRs derived from elasticity-adjusted demand curves incorporating replacement cycle velocity and compliance mandate diffusion rates. Industry-specific forecast inputs encompassed EU AI Act implementation timelines and US financial services visual data protection protocol adoption curves.
Stress conditions across adhesive chemical cost volatility, logistics disruption severity in East Asian shipping lanes, and electrochromic technology substitution pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory mandate durability and enterprise procurement standardization trajectories. Material shifts in right-to-repair legislation scope or rare-earth export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Middle East and Africa Smartphones Market
Consumer Electronics
Smart Audio Devices Market
Consumer Electronics
Mobile Cases and Covers Market
Consumer Electronics
China Refurbished Smartphone Market
Consumer Electronics
Electronic Products Rental Market
Consumer Electronics
Vape Market
Consumer Electronics
Asia-Pacific Professional Audio-Visual Systems Market
Consumer Electronics
Pet Monitoring Camera Market
Consumer Electronics
FMCG Market
Consumer Electronics
Consumer Electronics Repair and Maintenance Market
Consumer Electronics
Europe Gaming Headset Market
Consumer Electronics
Consumer Electronic Accessories Market
Consumer Electronics
Digital Voice Recorder Market
Consumer Electronics
Armenia Consumer Goods Market
Consumer Electronics
Smart Home Projector Market
Consumer Electronics
Wrist Watch Market