
 Pet Cameras Market | 2026-2036
Pet Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Cameras Market Analytics
Online pet specialty retail is reshaping how consumers discover and purchase monitoring hardware, with subscription bundling replacing one-time transactions as the dominant commercial logic. Petcube leverages its integrated tele-veterinary platform to sustain recurring revenue streams beyond hardware margins. Furbo Dog Camera anchors the premium interactive segment through proprietary treat-dispensing mechanics and AI-powered bark alerts. Wyze Labs competes on manufacturing scale, occupying the sub-$50 entry tier through direct-to-consumer logistics control.
Pet cameras are network-connected imaging devices engineered for remote animal observation, typically integrating CMOS sensors with 1080p resolution, infrared night vision arrays, and cloud-enabled two-way audio codecs for real-time owner-pet interaction. Their commercial purpose centers on anxiety reduction for separated animals and behavioral documentation for veterinary or training intervention. Indoor cameras dominate unit shipments as apartment-dwelling pet ownership expands in dense metropolitan zones. Wi-Fi connection types lead installation preference where broadband penetration supports continuous streaming, while interactive cameras with treat-tossing and laser-pointer functions capture the fastest-growing feature tier as owners seek engagement beyond passive surveillance.
The Federal Communications Commission governs wireless spectrum allocation for cloud-reliant pet camera data transmission, while the Consumer Product Safety Commission monitors lithium-ion battery thermal standards in mobile and outdoor units. The California Consumer Privacy Act shapes firmware architecture, compelling manufacturers to localize video storage and strengthen encryption protocols for household footage. Stakeholders must weigh subscription dependency against hardware margin erosion as the installed base saturates among early adopters and competition shifts toward software differentiation and data services.
Market Dynamics
Subscription bundling is restructuring the Pet Cameras Market, converting hardware vendors into recurring-revenue platforms and compressing pure-device margins while elevating software and data-service valuations.
Growth Catalysts
- FCC Broadband Investment:Federal Communications Commission infrastructure spending expands addressable households by reducing connectivity dead zones in suburban and rural United States.
- Mesh Wi-Fi Standards:IEEE 802.11ax and Wi-Fi 6E protocols eliminate streaming interruptions that previously degraded real-time pet interaction experiences.
- Shenzhen Component Cluster:Concentrated CMOS sensor and lithium-polymer battery manufacturing in Guangdong Province drives 1080p camera module cost curves downward.
Market Restraints
- Cloud Storage Cost Volatility:Amazon Web Services and Microsoft Azure pricing fluctuations compress subscription gross margins for firmware-dependent vendors.
- Lithium-Ion Thermal Standards:Consumer Product Safety Commission battery safety testing extends outdoor camera certification timelines by four to six months.
- Smartphone Substitution:Dedicated pet camera demand faces pressure from repurposed old phones running free monitoring applications with basic motion detection.
Strategic Opportunities
- Veterinary Telehealth Integration:Remote diagnostic video feeds create new reimbursement pathways through pet insurance providers and employer wellness programs.
- India Urban Pet Ownership:Mumbai and Bangalore apartment complexes represent underpenetrated demand as nuclear family structures and disposable incomes rise.
- California Privacy Localization:California Consumer Privacy Act mandates for encrypted edge storage create differentiation for vendors with on-device AI processing.
Industry Challenges
- Computer Vision Talent Scarcity:Behavioral algorithm development requires scarce machine-learning engineers with veterinary domain expertise.
- Multi-Protocol Integration Complexity:Simultaneous support for Alexa, Google Assistant, and Apple HomeKit fragments firmware development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Cameras Market |
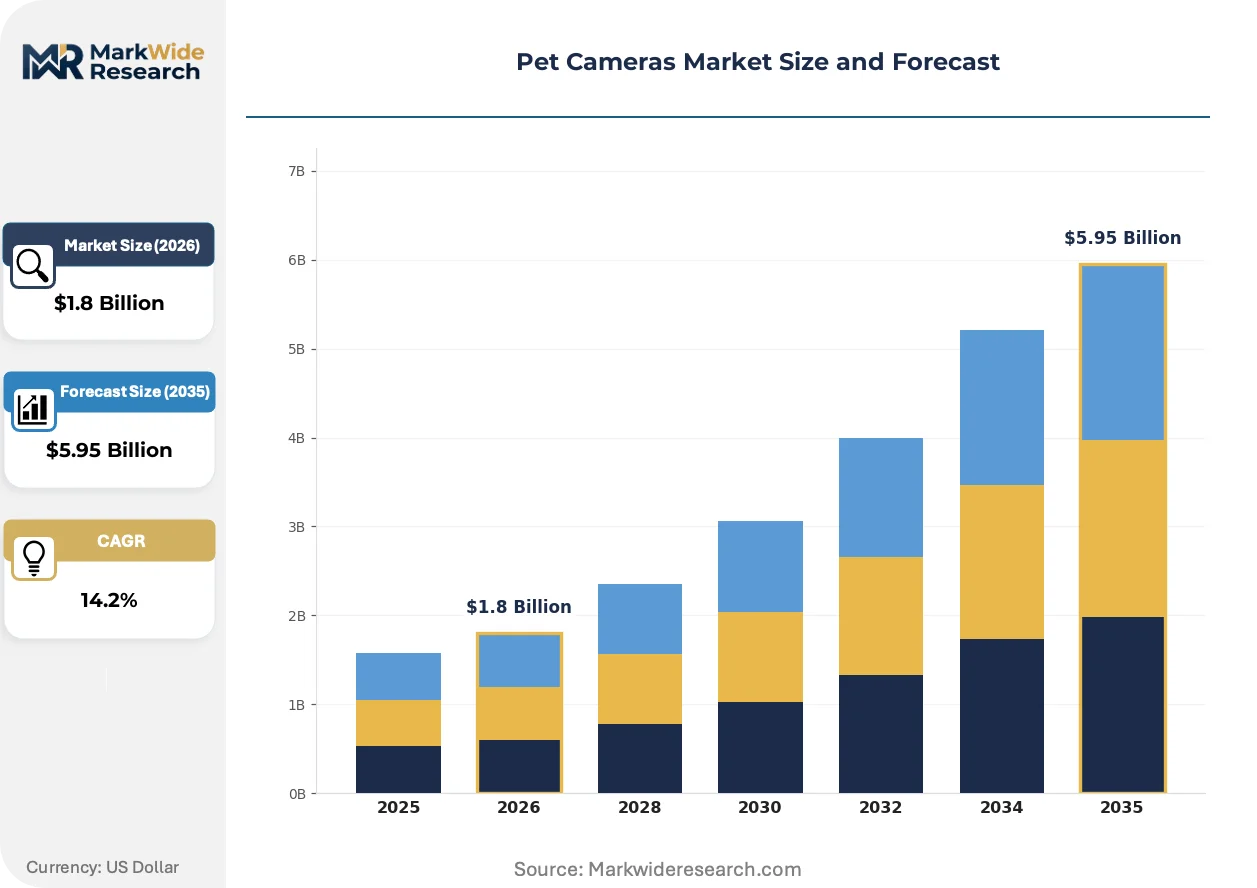
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Cameras, Outdoor Cameras, Interactive Cameras, Monitoring Cameras Connection Type: Wi-Fi, Wired, Bluetooth, Cellular Feature: Night Vision, Two-Way Audio, Motion Detection, HD Video End User: Pet Owners, Veterinary Clinics, Pet Shelters, Trainers |
| Companies Covered | Petcube, Inc, Furbo Dog Camera, Zmodo, PetChatz, SpotCam Co., Ltd., Wyze Labs, Inc., SKYMEE, Inc., PETKIT, Eufy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Cameras Market Evolving Landscape
Edge computing architectures and on-device inference are redistributing processing loads away from cloud dependencies, altering cost structures and data governance frameworks across the industry.
On-device AI accelerators are virtualizing behavioral analysis functions previously executed in remote data centers. Multi-pet households in dense metropolitan United States markets adopt these systems fastest to reduce latency during separation anxiety episodes. This virtualization compresses recurring cloud compute expenses while complicating over-the-air firmware update architectures.
California Consumer Privacy Act enforcement is tightening video retention and encryption mandates for household footage. Manufacturers now localize storage on SD cards or network-attached storage to avoid cross-border data transfer liabilities. Indoor camera segments face the steepest compliance cost increases as they handle the highest volume of continuous recording streams.
Subscription bundling is displacing one-time hardware transactions as the dominant commercial logic. Direct-to-consumer channels and veterinary clinic partnerships capture growing share from traditional electronics retail. China and United States markets exhibit the most pronounced shift, where Petcube and Furbo anchor recurring-revenue platforms against Wyze's hardware-centric positioning.
Pet Cameras Market Segmentation
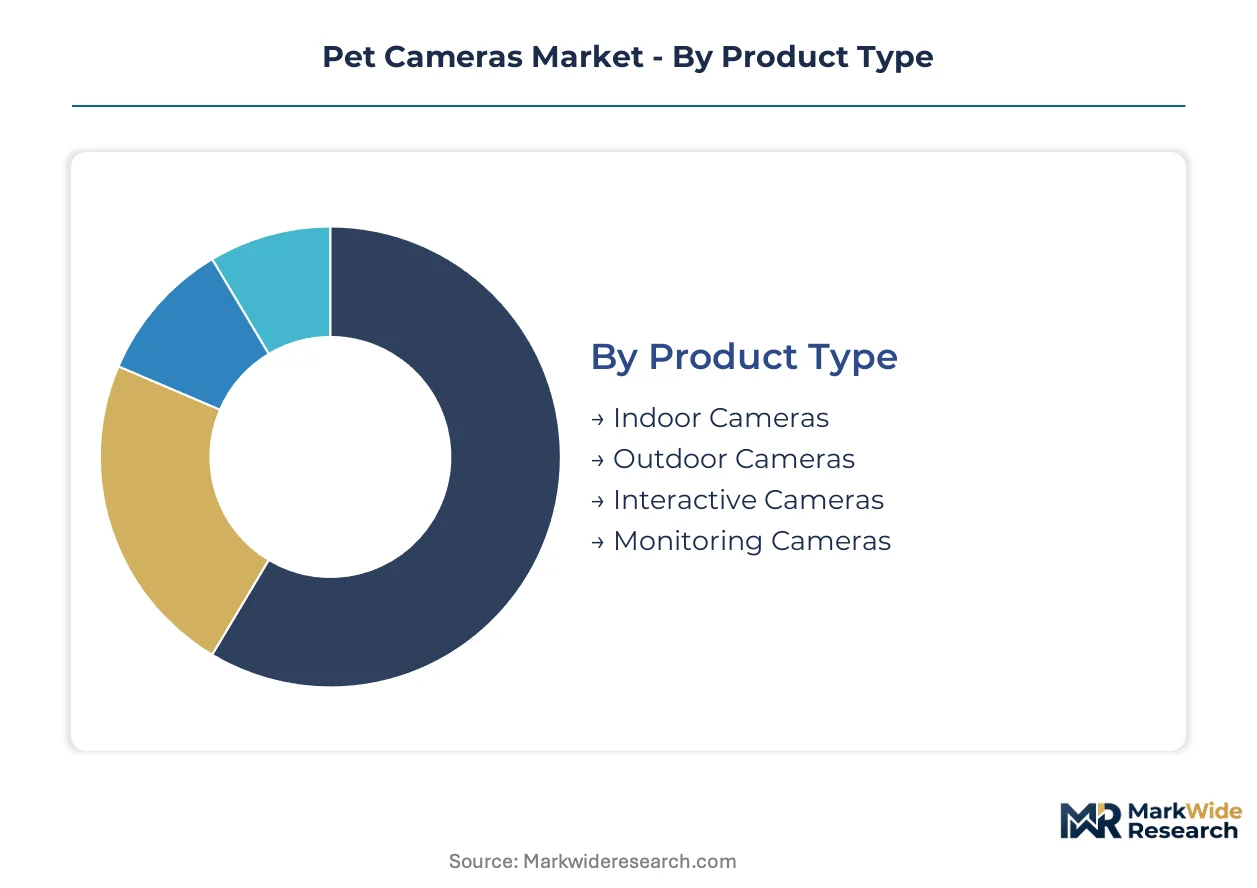
Pet camera segmentation reveals how hardware specifications, connectivity infrastructure, and end-use applications create distinct value tiers. Manufacturers configure product lines around apartment-dwelling indoor monitoring, outdoor perimeter surveillance, and veterinary diagnostic workflows.
Product Type:
Indoor cameras anchor volume shipments as metropolitan apartment ownership concentrates in dense urban United States markets.
- Indoor Cameras:Compact CMOS sensor units with 1080p resolution and infrared night vision arrays dominate installation in rental properties where drilling restrictions prevent permanent mounting. Multi-unit households in Brooklyn and San Francisco drive replacement cycles as owners upgrade from basic monitoring to AI-powered behavioral analysis.
- Outdoor Cameras:Weatherized IP65-rated housings with extended temperature tolerance protect lithium-polymer batteries in sub-zero climates. Rural United States properties with acreage requirements generate demand for solar-panel accessory compatibility and cellular backup connectivity.
- Interactive Cameras:Treat-dispensing mechanics and laser-pointer modules convert passive observation into engagement tools for separation anxiety management.
- Monitoring Cameras:Continuous cloud-recording architectures with 30-day retention cycles serve liability documentation needs in commercial boarding facilities.
Established volume favors Indoor Cameras; emerging adoption favors Interactive Cameras.
Connection Type:
Network architecture choices reflect broadband penetration gradients and installation permanence requirements across household types.
- Wi-Fi:IEEE 802.11ax protocol support eliminates buffering in mesh-networked homes where multiple 4K streams compete for bandwidth. FCC infrastructure investments in suburban United States counties expand addressable households previously excluded by connectivity dead zones.
- Cellular:LTE and 5G modules bypass router dependency for vacation-property monitoring and vehicle-based applications. Monthly data plan costs constrain mass-market penetration despite eliminating installation complexity.
- Wired:Ethernet Power-over-Ethernet configurations deliver uninterrupted power and bandwidth for commercial kennel operations with 24/7 recording mandates.
- Bluetooth:Short-range pairing protocols enable initial device setup and temporary proximity-based control without internet dependency.
Wi-Fi captures the dominant installed base; Cellular climbs the fastest as mobile data pricing compresses.
Feature:
Capability bundling separates entry-tier hardware from premium subscription-dependent platforms.
- Two-Way Audio:Full-duplex codecs with echo cancellation enable real-time voice interaction for behavioral correction and anxiety soothing. Shenzhen-based component integration has driven BOM costs below five dollars, making this standard across all price tiers.
- Motion Detection:On-device AI inference reduces false alerts by distinguishing pet movement from environmental shadows and HVAC air currents. California Consumer Privacy Act compliance pressures favor edge processing to minimize cloud video transfer.
- Night Vision:940nm infrared LED arrays provide illumination invisible to animal eyes, preventing sleep disruption during nocturnal monitoring.
- HD Video:1080p60 streaming specifications satisfy insurance documentation requirements for bite incidents and property damage claims.
Two-Way Audio has achieved universal inclusion; Motion Detection with on-device AI represents the steepest expansion trajectory.
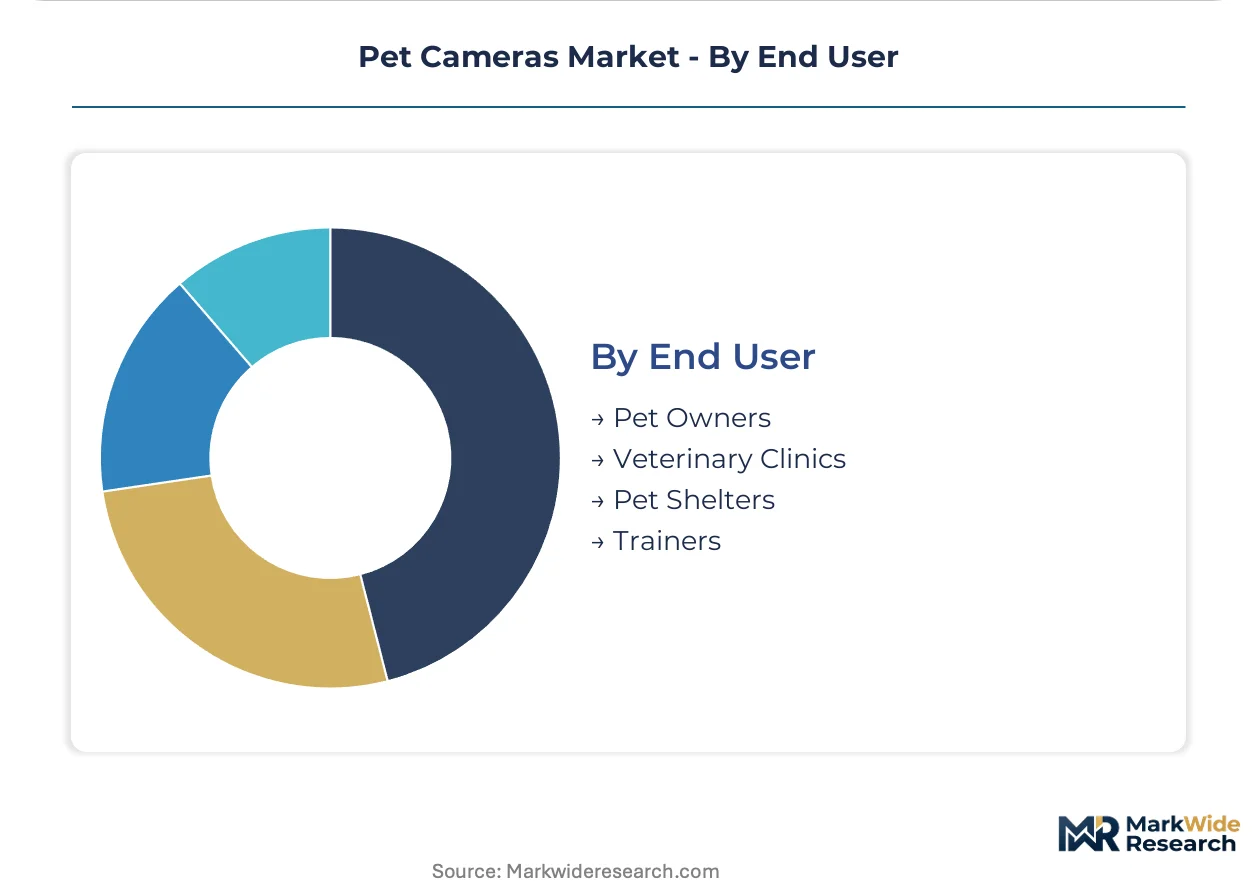
End User:
Customer archetypes span individual consumers, institutional care providers, and professional service businesses with diverging procurement patterns.
- Pet Owners:Direct-to-consumer channels and veterinary clinic partnerships capture growing share from electronics retail as subscription bundling displaces one-time transactions. Multi-pet households in dense metropolitan zones adopt fastest to reduce latency during separation anxiety episodes.
- Veterinary Clinics:Telehealth-integrated platforms create reimbursement pathways through pet insurance providers and employer wellness programs. Diagnostic video feeds require HIPAA-grade encryption and integration with practice management software.
- Pet Shelters:Nonprofit procurement budgets prioritize durability and multi-user access controls over feature depth. Grant-funded installations in municipal facilities drive volume through standardized RFP specifications.
- Trainers:Behavioral documentation requirements favor cameras with timestamped event logging and slow-motion playback for gait analysis.
Pet Owners command the revenue base; Veterinary Clinics present the highest margin expansion potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Federal Communications Commission's broadband infrastructure investments underwrite United States market expansion by eliminating connectivity dead zones in suburban and rural counties. Shenzhen's electronics manufacturing cluster anchors component cost curves for CMOS sensors and lithium-polymer batteries.
United States
Multi-unit pet-owning households in Brooklyn and San Francisco drive replacement cycles toward AI-powered behavioral analysis. FCC broadband spending expands addressable households previously excluded by streaming interruptions. Greater Los Angeles and Pacific Northwest metros concentrate tele-veterinary platform adoption through employer wellness program partnerships.
China
Shenzhen-based CMOS sensor manufacturers compress 1080p camera module costs through concentrated Guangdong Province production. MIIT wireless equipment certification governs mesh Wi-Fi protocol compliance for cloud-reliant data transmission. Yangtze River Delta metros absorb premium interactive camera volumes as disposable incomes rise among nuclear family structures.
Germany
REACH chemical safety standards and RoHS directive compliance shape lithium-ion battery thermal specifications for outdoor camera imports. Berlin-Brandenburg and Bavaria concentrate smart home integration demand where Alexa and Google Assistant multi-protocol support commands premium positioning. CE marking requirements extend certification timelines for firmware-dependent vendors.
India
Mumbai and Bangalore apartment complexes represent underpenetrated demand as nuclear family structures and disposable incomes rise. BIS electronics safety certification governs power adapter standards for Wi-Fi-enabled indoor units. Maharashtra and Karnataka metros drive direct-to-consumer channel experimentation as subscription bundling displaces traditional electronics retail.
Japan
METI energy efficiency standards shape standby power consumption limits for always-on monitoring devices. Kanto and Kansai metros concentrate aging-population pet ownership where tele-veterinary reimbursement pathways integrate with employer wellness programs. JIS quality benchmarks differentiate premium-tier hardware against Shenzhen-origin entry-level alternatives.
Pet Cameras Market Competitive Landscape
On the supply side, the industry is bifurcated between subscription-platform vendors and hardware-centric manufacturers. Tiered competitive dynamics separate recurring-revenue integrators from margin-compressed device specialists. Strategic archetypes include tele-veterinary platform bundlers, direct-to-consumer logistics controllers, and component-integrated original design manufacturers. Dominant competitive moves encompass firmware differentiation through on-device AI acceleration and veterinary clinic partnership channel capture.
Within the subscription-platform tier, Petcube anchors recurring-revenue positioning through tele-veterinary integration, while Furbo Dog Camera exemplifies premium interactive hardware anchoring. Wyze Labs occupies the scale-driven entry tier through manufacturing cost control and direct-to-consumer distribution. These three vendors collectively illustrate the market's tripartite segmentation across premium service bundling, mid-market feature depth, and sub-fifty-dollar hardware accessibility.
| Leading Market Players |
|---|
| Petcube, Inc |
| Furbo Dog Camera |
| Zmodo |
| PetChatz |
| SpotCam Co., Ltd. |
| Wyze Labs, Inc. |
| SKYMEE, Inc. |
| PETKIT |
| Eufy |
| Others |
Value Network & Pricing Analysis
Shenzhen's concentrated CMOS sensor and lithium-polymer battery manufacturing anchors cost curves for camera modules, compressing hardware margins while pushing value capture toward subscription software tiers and veterinary service bundling downstream.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates subscription-integrated platforms from hardware-only vendors. Price differentiation rests on AI feature depth and tele-veterinary integration rather than resolution specifications alone. Cost compression in the economy tier is intensifying because Wyze Labs' direct-to-consumer logistics control forces BOM discipline across competitors. Multi-pet households in dense metros show lowest price sensitivity; grant-funded municipal shelters exhibit highest.
Supply Chain Analysis
Foxconn and BYD Electronics hold dominant contract-manufacturing capacity for pet camera assembly, with secondary clustering at Flex and Jabil facilities. Component sourcing draws from China for CMOS sensors, South Korea for memory modules, and Japan for precision optics. Single-source vulnerability concentrates in Shenzhen lithium-polymer cell supply. Distribution runs through direct-to-consumer channels and veterinary clinic partnerships, displacing traditional electronics retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on subscription-driven switching costs that tether pet owners to integrated tele-veterinary platforms, with regulatory entrenchment deepening through CCPA-mandated data localization requirements.
For Market Incumbents: Pre-empt smartphone substitution threats by accelerating on-device AI deployment that free monitoring apps cannot replicate. Deepen backward integration into Guangdong component supply to defend margin position against Shenzhen cost curves. Capture veterinary clinic channel control before reimbursement pathways solidify around competitor platforms.
For New Entrants and Emerging Players: Mumbai and Bangalore apartment complexes offer white-space expansion as nuclear family structures and disposable incomes rise. Target commercial boarding facilities with multi-user access controls and 30-day cloud retention that incumbent consumer platforms underserve. Deploy grant-funded municipal shelter RFPs as referenceable beachhead accounts.
For Investors and Strategic Acquirers: Capital is best deployed toward tele-veterinary-integrated platforms with recurring revenue visibility and HIPAA-grade encryption infrastructure. Long-term viability across a five-to-ten year window favors vendors with on-device AI processing that minimizes AWS/Azure dependency. Watch pet insurance provider reimbursement policy shifts as the inflection signal for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Telehealth Integration | Creates reimbursement pathways through pet insurance providers and employer wellness programs. |
| On-Device AI Acceleration | Reduces cloud compute expenses while satisfying CCPA edge-storage mandates for household footage. |
| Direct-to-Consumer Channel Expansion | Captures margin previously allocated to electronics retail through logistics control. |
| Multi-Protocol Smart Home Certification | Commands premium positioning where Alexa, Google Assistant, and Apple HomeKit compatibility converges. |
| Cellular Connectivity Module Addition | Addresses vacation-property and vehicle-based applications beyond Wi-Fi-dependent indoor use. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC broadband deployment data, MIIT wireless certification filings, and Shenzhen customs export records. Interviews with tele-veterinary platform executives, pet insurance reimbursement specialists, CMOS sensor procurement leads, and veterinary clinic practice managers informed demand-side validation. Bottom-up unit shipment estimates triangulate against top-down subscription revenue analysis across the projection horizon.
Forecast inputs span connection type, product tier, feature bundling, and end-user archetype across the modeling period. CAGRs derive from segment-level growth rate reconciliation with macro broadband penetration curves and pet ownership demographic shifts. Veterinary telehealth reimbursement policy trajectories and cloud storage cost volatility represent key modeled variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by smartphone-native monitoring apps or hyperscaler cloud entrants would shift outcomes. Quarterly review of pet insurance provider platform partnerships and FCC infrastructure spending disbursements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Refurbished Computer and Laptop Market
Consumer Electronics
Wrist Watch Market
Consumer Electronics
Smart Mirror TV Market
Consumer Electronics
Ultraman Peripheral Market
Consumer Electronics
Global Laptop Skins Market
Consumer Electronics
Smart Aquarium Devices Market
Consumer Electronics
Subwoofer Market
Consumer Electronics
True Wireless Stereo Earbuds Market
Consumer Electronics
Headphones Market
Consumer Electronics
Used and Refurbished Smartphone Market
Consumer Electronics
China Smartphone Market
Consumer Electronics
Global 4K TV Market
Consumer Electronics
Wet Wipes Market
Consumer Electronics
Smart TV Sticks Market
Consumer Electronics
Consumer Electronics Market
Consumer Electronics
In-Ear-Monitors (Iems) Market