
 LAMEA Refurbished and Used Mobile Phones Market | 2026-2036
LAMEA Refurbished and Used Mobile Phones Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Refurbished and Used Mobile Phones Market Insights
The premium-commodity split in LAMEA refurbished handsets is rebalancing around certification depth rather than brand alone. Apple Inc. leverages its authorized refurbishment pipeline to sustain premium pricing in South Africa and the UAE. Samsung Electronics anchors mid-tier volume through its Galaxy Upcycling program and regional service partnerships. Cashify competes on inspection automation, while Back Market differentiates through warranty standardization across multiple LAMEA markets.
Refurbished and used mobile phones encompass pre-owned wireless communication devices restored to functional operating condition through component replacement, software reset, and cosmetic reconditioning, typically graded by screen integrity, battery health percentage, and OEM authentication status. These devices serve primary commercial purposes in extending technology access to budget-constrained consumers and reducing electronic waste accumulation in markets with limited formal recycling infrastructure. Smartphones command the dominant value share given their higher residual utility and replacement part availability, while feature phones retain structural importance in rural segments where durability and basic connectivity outweigh application demands. The condition dimension shows Grade A units capturing disproportionate margin pools as consumer trust in visual and functional parity with new devices strengthens.
South Africa's NRCS battery safety mandates and Nigeria's Standards Organisation of Nigeria (SON) import certification requirements shape product eligibility and cross-border trade flows for refurbished devices entering LAMEA markets. The UAE's TDRA type-approval framework adds another compliance layer for devices distributed through Dubai's re-export hubs. Stakeholders must monitor evolving extended producer responsibility legislation across key LAMEA states and calibrate refurbishment depth against shifting import duty structures on used electronics.
Market Dynamics
Certification depth is overtaking brand recognition as the primary sorting mechanism for refurbished handset value in LAMEA markets, with battery health transparency and OEM authentication status now commanding price premiums that previously accrued to logo alone.
Growth Catalysts
- South Africa's NRCS battery safety mandates:These standards force refurbishment depth upgrades that reduce fire-risk incidents and build consumer trust in secondary markets. Compliance investments by formal refurbishers create competitive moats against informal operators.
- Student populations in secondary schools:Price-sensitive educational demand clusters across Nigeria, Kenya, and Egypt drive volume absorption of Grade B and C devices that fail cosmetic standards but retain full functionality.
- Galaxy Upcycling program infrastructure:Samsung's component recovery and redistribution networks reduce spare part lead times for mid-tier refurbishment operations throughout the Gulf states and North Africa.
Market Restraints
- Import duty volatility on used electronics:Nigeria's SON certification requirements and unpredictable tariff adjustments create working capital traps for cross-border traders moving devices through Lagos-Ibadan corridors.
- Lithium-ion cell supply concentration:Battery replacement costs absorb 35-45% of refurbishment economics, with genuine OEM cells channeling through Dubai's re-export hubs at prices that compress margin pools for independent operators.
- Authentication protocol fragmentation:Incompatible IMEI verification systems across UAE TDRA, South Africa NRCS, and Nigeria SON databases force redundant testing expenditures on multi-market distributors.
Strategic Opportunities
- Rural connectivity gaps in Ethiopia and Tanzania:Feature phone refurbishment for agricultural value-chain communication remains underserved by current premium-focused operator strategies.
- Extended producer responsibility legislation:Draft e-waste frameworks in Kenya and Ghana position formal refurbishment networks to capture compliance-linked collection incentives before informal channels organize.
- AI-powered diagnostic automation:Machine vision for component grading and predictive failure modeling converges with cloud-based inventory platforms to reduce inspection labor costs per unit.
Industry Challenges
- Certified technician scarcity:Microsoldering and board-level repair capabilities concentrate in Lagos, Johannesburg, and Dubai, creating recruitment bottlenecks for scaling operations in secondary cities.
- Software lock standardization delays:Inconsistent OEM policies on FRP removal and iCloud authentication create warranty liability exposure for refurbishers handling estate-sourced devices.
- Reverse logistics infrastructure gaps:Collection density outside major metropolitan corridors remains insufficient to feed refurbishment pipelines at target unit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Refurbished and Used Mobile Phones Market |
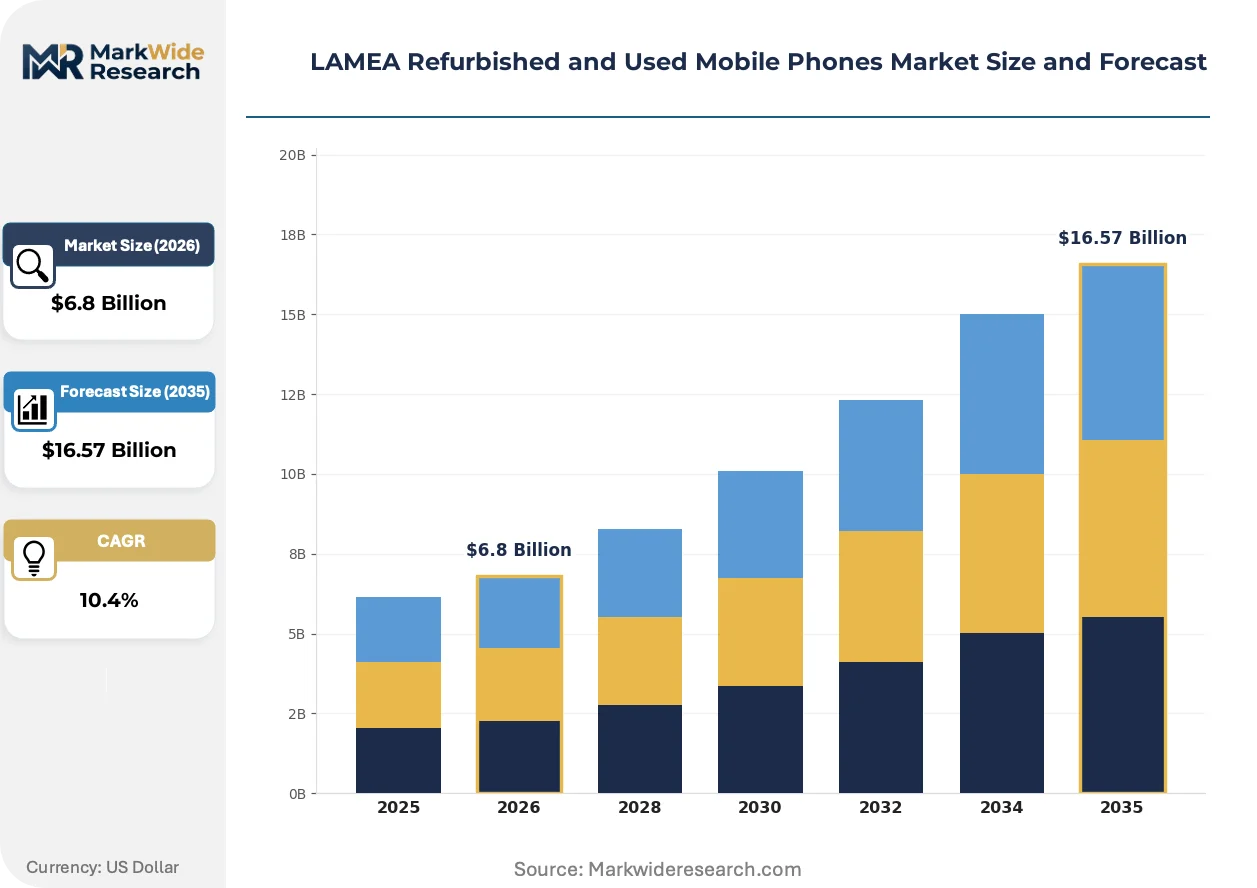
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $16.57 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Feature Phones, Tablets, Accessories Condition: Refurbished, Used, Open-Box, Grade A Sales Channel: Online Retail, Offline Retail, Resellers, Direct Sales Customer Type: Individuals, Corporates, Schools, NGOs |
| Companies Covered | Apple Inc., Samsung Electronics, Amazon, Verizon Communications, AT&T Inc., Back Market, Cashify, Tecno, Infinix, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Refurbished and Used Mobile Phones Market Trends and Innovations
Diagnostic automation and authentication transparency are compressing information asymmetries that historically disadvantaged secondary-market buyers, while regulatory pressure on battery safety is accelerating formalization of previously informal refurbishment channels.
Automated optical inspection systems for screen microfracture detection and battery impedance testing are overtaking manual technician assessment as the quality gate for Grade A certification. Large refurbishment facilities in South Africa and the UAE deploy these systems to process volume contracts for corporate fleet refresh programs. The technology compresses per-unit labor costs while expanding the addressable supply of devices that qualify for warranty-backed resale.
South Africa's NRCS battery safety standards and Nigeria's SON import certification framework are forcing cross-border traders to consolidate through formal channels with documented testing protocols. These regulations eliminate fire-sale arbitrage opportunities for uncertified devices while creating compliance cost barriers that favor scaled operators with in-house testing laboratories. The UAE's TDRA type-approval requirements add a third compliance layer for Dubai-based re-export hubs serving multiple LAMEA destinations.
Secondary school procurement coordinators and small-business owners are bypassing traditional retail channels to source certified pre-owned devices directly from refurbishment platform marketplaces. This channel compression disintermediates distributor margins and shifts pricing power toward inspection-transparent sellers with standardized warranty terms. The pattern concentrates in Nigeria's Lagos-Ibadan corridor and South Africa's Gauteng province, where digital literacy and platform penetration enable direct matching between refurbishers and volume buyers.
LAMEA Refurbished and Used Mobile Phones Market Segmentation
Segmentation in LAMEA refurbished mobile phones reveals how capital deployment, certification depth, and channel infrastructure shape competitive returns. Each dimension carries distinct margin structures and regulatory exposure across the region's fragmented supply landscape.
Product Type:
Capital intensity varies sharply across product categories, with component sourcing networks and testing equipment requirements driving divergent investment thresholds.
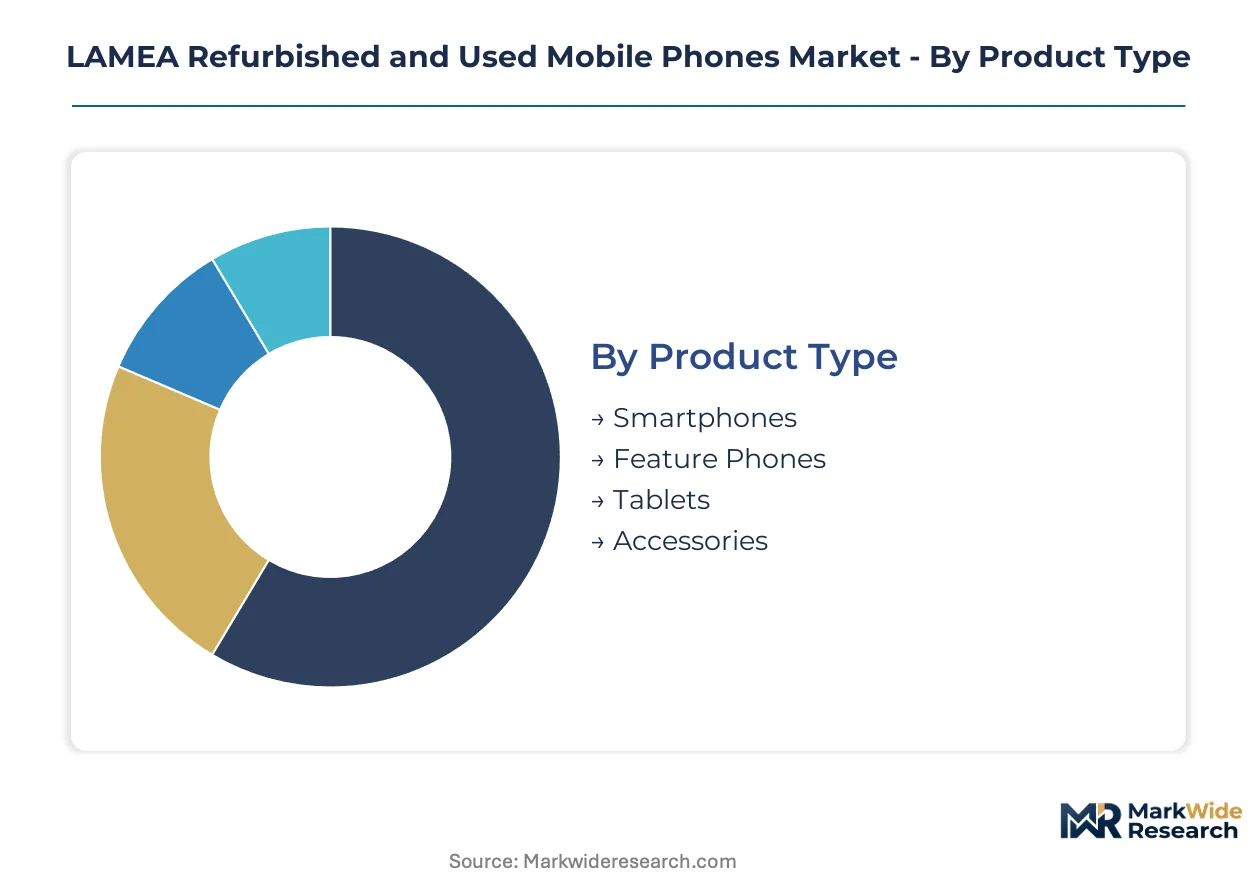
- Smartphones:Multi-core processors, OLED display panels, and lithium-polymer battery modules demand sophisticated diagnostic platforms and OEM-authorized component channels. Nigeria's Lagos-Ibadan corridor concentrates refurbishment volume for mid-tier Android devices serving student populations and small-business owners who prioritize application compatibility over cosmetic perfection.
- Feature Phones:Simplified circuit architectures and standardized keypad assemblies reduce tooling requirements, though durable casing materials and extended battery life specifications sustain rural demand in Ethiopia and Tanzania where agricultural value-chain communication depends on reliable voice connectivity.
- Tablets:Larger form factors and specialized digitizer components create spare part scarcity that elevates procurement costs for independent operators lacking Samsung or Apple direct sourcing agreements.
- Accessories:Chargers, protective cases, and audio peripherals require minimal technical refurbishment but face margin compression from unbranded import competition through Dubai's re-export hubs.
Smartphones absorb the bulk of installed capacity; feature phones are expanding most quickly in rural connectivity gaps.
Condition:
Certification depth and warranty backing separate segments by customer risk tolerance and price elasticity across LAMEA markets.
- Refurbished:Component replacement, software reset, and cosmetic reconditioning to manufacturer-authorized standards with documented battery health percentages. South Africa's NRCS battery safety mandates and UAE TDRA type-approval frameworks elevate compliance costs that favor scaled operators with in-house testing laboratories.
- Used:Functional devices sold as-is without systematic restoration, typically sourced from estate liquidations or corporate fleet refreshes. IMEI verification gaps and software lock inconsistencies create warranty liability exposure that restricts channel options.
- Open-Box:Retail returns with original packaging and accessory completeness, commanding modest premiums where visual newness signals reduce buyer hesitation in Egypt's secondary cities.
- Grade A:Visual and functional parity with new devices, certified through automated optical inspection for screen microfractures and battery impedance testing. Corporate procurement coordinators in South Africa's Gauteng province source Grade A units directly from refurbishment platforms to bypass distributor markups.
Refurbished units dominate value capture; Grade A certification is climbing the fastest as procurement transparency improves.
Sales Channel:
Channel configuration determines working capital intensity and customer acquisition economics across LAMEA's uneven digital infrastructure.
- Online Retail:Platform marketplaces with standardized warranty terms and inspection transparency reports. Kenya's mobile money integration enables transaction completion where card penetration remains limited, though last-mile logistics costs erode margin in secondary cities.
- Offline Retail:Physical storefronts with technician-assisted selection and immediate device handover. Lagos-Ibadan corridor informal repair clusters feed secondary distribution networks with uncertified inventory that competes on price alone.
- Resellers:Intermediary networks aggregating supply from multiple refurbishment sources, absorbing authentication protocol fragmentation costs across UAE TDRA, South Africa NRCS, and Nigeria SON verification systems.
- Direct Sales:Manufacturer-authorized refurbishment pipelines from Apple and Samsung with premium positioning and extended warranty backing, concentrated in South Africa and UAE metropolitan markets.
Online retail captures the steepest expansion trajectory; offline retail retains the largest transaction volume.
Customer Type:
Procurement scale and specification requirements segment buyers by contract structure and replacement cycle predictability.
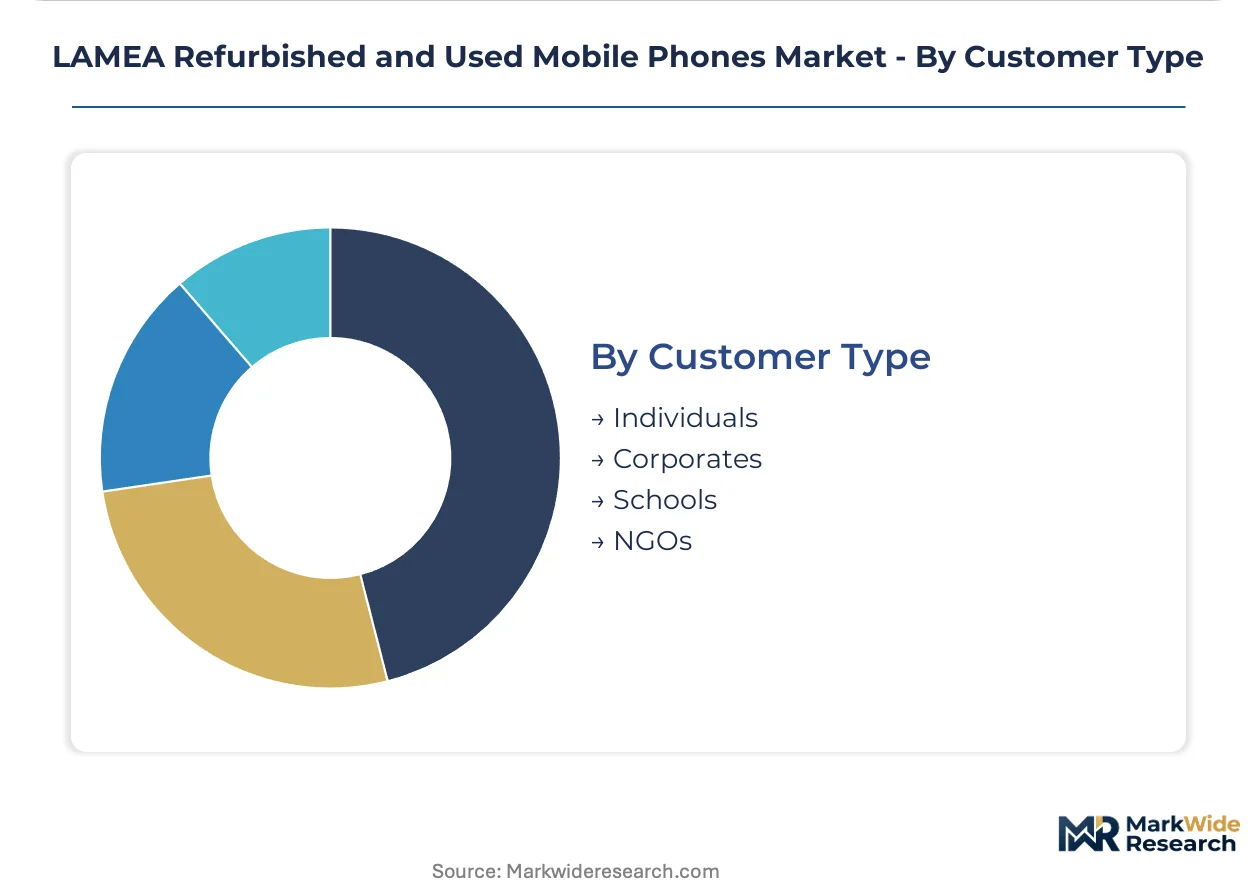
- Individuals:Single-unit purchases driven by price sensitivity and immediate replacement need, with Grade B and C devices finding absorption among Nigeria's secondary school students prioritizing functionality over cosmetic standards.
- Corporates:Fleet refresh programs with volume contracts and standardized device configurations, processed through large refurbishment facilities in South Africa and UAE with automated diagnostic systems.
- Schools:Educational procurement coordinators sourcing certified pre-owned devices for student technology access programs, bypassing traditional retail channels to align budgets with device specifications.
- NGOs:Donor-funded distribution targeting digital inclusion objectives in underserved regions, with feature phone refurbishment for agricultural communication remaining structurally underserved by premium-focused operator strategies.
Individuals account for the dominant transaction count; corporates are gaining share fastest through formalized fleet refresh pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos anchors refurbished handset distribution across LAMEA, with the Lagos-Ibadan corridor feeding secondary networks that stretch from Nigeria into Ghana and Senegal.
Nigeria
Student populations in Lagos and Ibadan drive absorption of Grade B and C devices that prioritize functionality over cosmetic standards. The Standards Organisation of Nigeria enforces import certification requirements that reshape cross-border trade flows through Lagos ports. Informal repair clusters in Lagos-Ibadan corridor feed secondary distribution networks with uncertified inventory competing on price alone.
South Africa
Corporate fleet refresh programs in Johannesburg and Cape Town sustain demand for Grade A certified devices with documented battery health percentages. The National Regulator for Compulsory Specifications mandates battery safety standards that force refurbishment depth upgrades and reduce fire-risk incidents. Large refurbishment facilities in Gauteng province deploy automated diagnostic systems to process volume contracts.
United Arab Emirates
Dubai's re-export hubs serve as the primary channel for genuine OEM battery cells and component sourcing across Gulf states and North Africa. The Telecommunications and Digital Government Regulatory Authority type-approval framework adds compliance layers for devices distributed through Dubai's free zones. Scaled operators with in-house testing laboratories capture margin pools from multi-market distributors facing redundant authentication expenditures.
Kenya
Mobile money integration enables online marketplace transactions where card penetration remains limited, though last-mile logistics costs erode margins in secondary cities. Draft extended producer responsibility legislation positions formal refurbishment networks to capture compliance-linked collection incentives. Nairobi concentrates diagnostic technician capabilities while Mombasa handles import logistics for regional redistribution.
Egypt
Secondary city procurement coordinators source open-box retail returns where visual newness signals reduce buyer hesitation in Alexandria and Suez Canal zones. Educational technology access programs drive institutional demand for certified pre-owned devices with standardized warranty terms. Cairo's refurbishment infrastructure remains underdeveloped relative to demand scale, creating supply gaps filled by informal channels.
LAMEA Refurbished and Used Mobile Phones Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and warranty standardization, with authorized OEM pipelines commanding price premiums that informal operators cannot match. The vendor base stratifies into three tiers: manufacturer-authorized refurbishment programs, platform marketplaces with inspection transparency, and informal repair clusters competing on price alone. Dominant competitive moves include strategic partnerships with component distributors and geographic expansion through Dubai's re-export hub infrastructure.
Within the platform marketplace tier, Back Market and Cashify exemplify inspection-automation and warranty-standardization archetypes respectively. Apple Inc. and Samsung Electronics anchor the manufacturer-authorized tier through direct refurbishment pipelines. Among regional specialists, Tecno and Infinix occupy positions serving mid-tier volume segments where component recovery networks reduce spare part lead times.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Amazon |
| Verizon Communications |
| AT&T Inc. |
| Back Market |
| Cashify |
| Tecno |
| Infinix |
| Others |
Pricing and Supply Chain Analysis
Lithium-ion battery cell costs absorb the dominant share of refurbishment economics, channeling from OEM suppliers through Dubai's re-export hubs to compress margin pools for independent operators across Nigeria's Lagos-Ibadan corridor and South Africa's Gauteng province.
Pricing Analysis
Certification depth serves as the value-based pricing anchor, with Grade A units commanding premiums for documented battery health percentages and automated optical inspection validation. Three-tier pricing structure across premium, standard, and economy levels separates manufacturer-authorized refurbishment pipelines from platform marketplaces and informal repair clusters. Price differentiation rests on OEM authentication status and warranty backing length. Cost compression in mid-tier segments is intensifying because genuine battery cell scarcity elevates replacement expenses. Student populations in Nigerian secondary schools exhibit the highest price sensitivity, while corporate fleet procurement coordinators in Johannesburg demonstrate the lowest.
Supply Chain Analysis
Regional distribution centers in Dubai, Lagos, and Johannesburg anchor hub-and-spoke patterns that feed secondary networks across Gulf states, West Africa, and Southern Africa. Component sourcing concentrates in the United Arab Emirates, China, and South Korea for display panels, battery modules, and processor chipsets. Raw material dependencies include lithium carbonate for cells, rare earth elements for magnets, and copper for circuit interconnects. Single-source vulnerability in genuine OEM battery supply creates structural risk for independent refurbishers lacking direct Samsung or Apple agreements. Distribution runs through formal refurbishment facilities with in-house testing laboratories, bypassing informal repair clusters that compete on price alone.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LAMEA refurbished handset sector is becoming a vertical-integration race, with players pursuing upstream control over battery cell supply and downstream capture of corporate fleet procurement channels to defend margin position.
For Market Incumbents: Extend certification infrastructure investments to comply with South Africa's NRCS battery safety mandates and Nigeria's SON import requirements, creating compliance moats against informal operators. Backward integration into component recovery networks reduces spare part lead times and compresses procurement costs for mid-tier refurbishment operations. Channel control through direct platform marketplaces disintermediates distributor markups in the Lagos-Ibadan corridor. For New Entrants and Emerging Players: Launch via mobile money-integrated online retail platforms targeting Kenya's price-sensitive individual buyers where card penetration remains limited. White-space targets include rural feature phone refurbishment for agricultural value-chain communication in Ethiopia and Tanzania, plus estate-sourced device aggregation in Egypt's secondary cities. The most penetrable segment is Grade B and C devices for student populations prioritizing functionality over cosmetic standards. For Investors and Strategic Acquirers: Draft extended producer responsibility legislation in Kenya and Ghana is the leading indicator that formal refurbishment networks will capture compliance-linked collection incentives before informal channels organize. Long-term viability over the next decade rests on scaled operators with in-house testing laboratories and multi-market authentication capabilities. Acquisition target archetypes include diagnostic automation technology providers and regional component distributors with Dubai re-export hub access. The signal to monitor is consolidation of cross-border traders through formal channels with documented testing protocols.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Diagnostic Automation | Machine vision for component grading reduces inspection labor costs per unit in South African facilities. |
| Battery Safety Certification Investment | NRCS compliance creates competitive moats against informal operators in Johannesburg and Cape Town markets. |
| Mobile Money Platform Integration | Kenya's M-Pesa integration enables transaction completion where card penetration remains limited. |
| Component Recovery Network Expansion | Samsung's Galaxy Upcycling program reduces spare part lead times for mid-tier refurbishment operations. |
| Direct-to-Institutional Sales Channel | School procurement coordinators bypass retail markups to source certified pre-owned devices directly. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with refurbishment facility operators, diagnostic technicians, corporate procurement coordinators, mobile money platform managers, and component distributors. Secondary sources included NRCS battery safety standards documentation, SON import certification frameworks, UAE TDRA type-approval records, and Dubai customs re-export statistics. Bottom-up unit economics modeling and top-down market sizing triangulation validated volume and value estimates.
Segmentation granularity modeled product type at the device category level, condition at the certification tier level, sales channel at the platform configuration level, and customer type at the procurement scale level across the analysis window. CAGRs derived from regression analysis against macroeconomic indicators and technology replacement cycle patterns. Industry-specific forecast inputs included student population growth in Nigerian secondary schools and corporate fleet refresh cycle frequencies in South Africa's Gauteng province.
Import duty volatility on used electronics, lithium-ion cell supply concentration, and authentication protocol fragmentation are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Electric Water Bottle Market
Consumer Electronics
Refurbished Electronics Market
Consumer Electronics
Soft Support Products Market
Consumer Electronics
Ultraman Peripheral Market
Consumer Electronics
Gaming Mouse & Keyboards Market
Consumer Electronics
Pet Monitoring Camera Market
Consumer Electronics
Global Earphones and Headphones Market
Consumer Electronics
Smart Phones Market
Consumer Electronics
Wireless Earphone Market
Consumer Electronics
Latin America Consumer Electronics Market
Consumer Electronics
Electronic Products Rental Market
Consumer Electronics
Mechanical Keyboard Market
Consumer Electronics
Shoe Shining Machine Market
Consumer Electronics
Ergonomic Mouse Market
Consumer Electronics
Tattoo Machine Market
Consumer Electronics
Headset Market