
 Stress Ball Market | 2026-2036
Stress Ball Market Size, Share, and Industry Trends Forecast 2026-2036
Stress Ball Market Insights
Workforce ergonomics expertise is redrawing how employers evaluate stress relief procurement for distributed teams. 4Imprint leverages its promotional products catalog to anchor corporate bulk orders across North American offices. Quality Logo Products competes through customization depth, sustaining repeat engagement from HR departments seeking branded wellness kits.
Stress balls are pliable, hand-held objects typically molded from polyurethane foam, gel-filled elastomers, or rubber compounds, designed for repetitive squeezing to reduce muscular tension and promote blood circulation. Foam stress balls dominate volume due to low unit cost and screen-print compatibility for promotional campaigns. Gel stress balls command premium positioning among therapy centers where tactile resistance calibration supports rehabilitation protocols. The distribution channel structure shows online retail capturing share from specialty stores as procurement shifts to e-procurement platforms with configurable minimum order quantities.
REACH restricts phthalate plasticizer content in PVC-based stress balls sold across European member states, while FDA guidelines govern latex allergen labeling for products distributed through U.S. therapy channels. The Consumer Product Safety Commission enforces small-part standards for stress balls marketed to children, constraining minimum dimensions and surface coating specifications. Stakeholders must monitor evolving chemical disclosure mandates across multiple jurisdictions to preempt formulation redesign cycles.
Market Dynamics
Corporate wellness program expansion is restructuring procurement volumes for ergonomic stress relief tools, with HR departments now mandating tactile wellness devices as standard components of distributed workforce kits rather than discretionary promotional items.
Growth Catalysts
- REACH Phase-out of Phthalate Plasticizers:European ECHA enforcement is accelerating reformulation toward TPU and silicone alternatives, opening premium positioning for compliant manufacturers.
- Tech Sector Hybrid Office Mandates:United States technology employers are integrating stress balls into standardized remote work starter packages, creating predictable bulk order cycles.
- Polyurethane Foam Process Advances:Cold-cure molding improvements are compressing unit costs while maintaining screen-print fidelity for promotional branding.
Market Restraints
- Petrochemical Feedstock Volatility:Polyol and isocyanate price swings destabilize foam stress ball margins without long-term supply contracts.
- Single-Source Gel Compound Concentration:Medical-grade elastomer formulations depend on three German chemical suppliers, creating geographic supply risk.
- Latex Allergen Labeling Burden:FDA mandatory disclosure requirements for natural rubber derivatives add compliance overhead for therapy channel distribution.
Strategic Opportunities
- India Corporate Wellness Underpenetration:BIS certification alignment for stress relief products could unlock IT services sector procurement at scale.
- ISO 13485 Medical Device Pathway:Rehabilitation center demand for calibrated resistance devices creates regulatory tailwind for certified manufacturers.
- E-Procurement Platform Integration:PunchOut catalog connectivity with SAP Ariba and Coupa is capturing share from traditional distributor relationships.
Industry Challenges
- Rehabilitation Protocol Customization:Physical therapy networks require SKU proliferation for resistance gradation, fragmenting production runs.
- Dual Certification Timeline Compression:Simultaneous FDA device registration and REACH substance dossier preparation strains regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stress Ball Market |
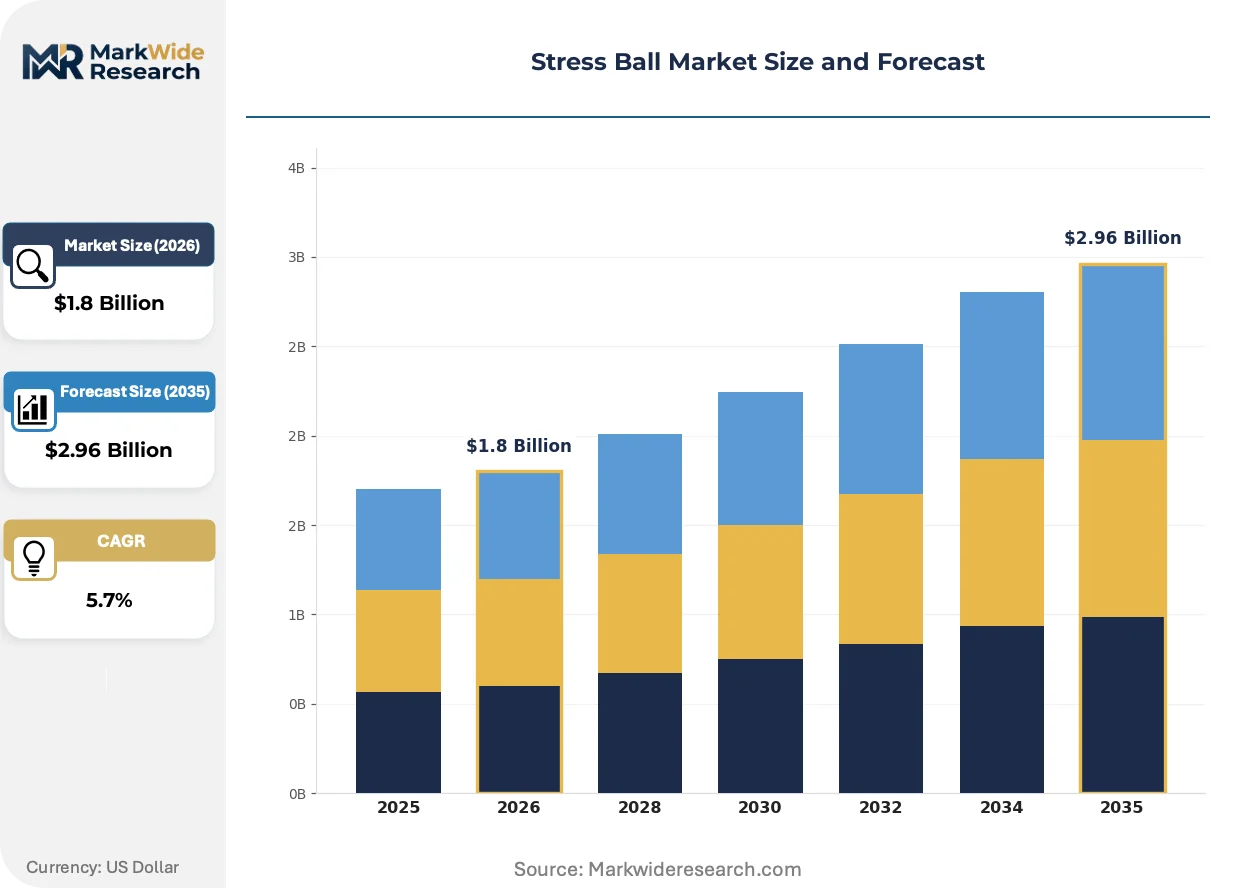
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Stress Balls, Gel Stress Balls, Rubber Stress Balls, Custom Shape Stress Balls End User: Schools, Corporates, Therapy Centers, Home Use Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale Material: Polyurethane, PVC, Silicone, Others |
| Companies Covered | YoYa Toys, 4Imprint, Stressballs.com, Fansteck, Quality Logo Products, Neliblu, Totally Promotional, Chuchik, Impresa Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stress Ball Market Trends and Innovations
Material science convergence with occupational health protocols is redefining product specifications, shifting competitive advantage from decoration fidelity to biomechanical validation and chemical transparency documentation.
Biometric sensor integration is decomposing the traditional stress ball category boundary. Embedded pressure-sensitive resistors from Texas Instruments now capture grip strength metrics for telehealth platforms. Kaiser Permanente and Cleveland Clinic rehabilitation networks are piloting these connected devices for remote patient monitoring, compressing the addressable market toward medical-grade suppliers and away from commodity promotional vendors.
REACH Annex XVII restrictions on phthalate content above 0.1% in toys and childcare articles are forcing PVC formulation abandonment across European member states. German manufacturers are absorbing TPU compound cost premiums to maintain market access. The therapy-grade segment faces the steepest compliance burden, as gel-filled products previously relied on plasticized PVC for tactile consistency.
Subscription-based wellness kit replenishment is displacing one-time bulk orders among Fortune 500 employers. Amazon Business and Staples Advantage are capturing this recurring revenue stream through auto-replenishment algorithms calibrated to employee headcount changes. The United States technology corridor from Seattle to Austin shows the highest adoption velocity, with HRIS platform integration enabling frictionless budget allocation.
Stress Ball Market Segmentation
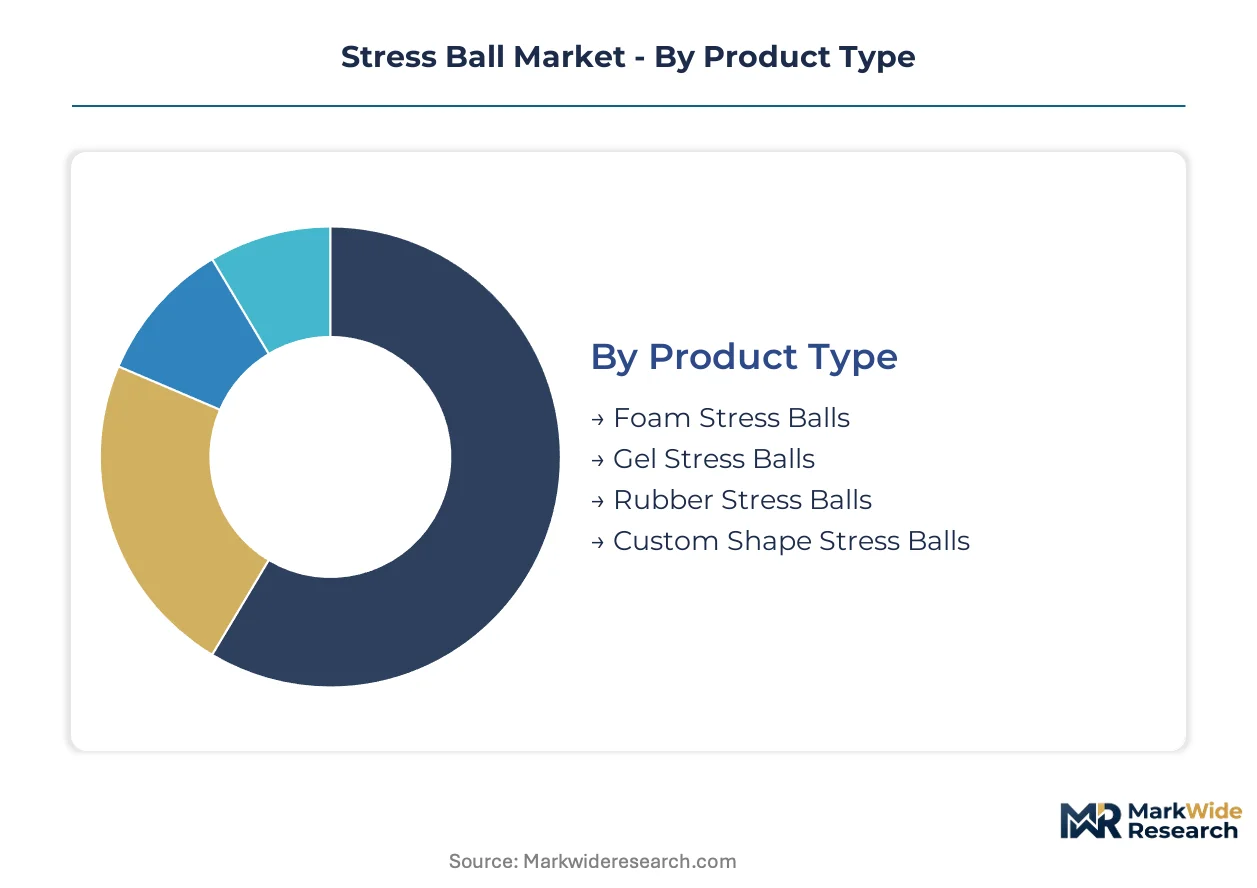
Segmentation in the stress ball market reveals divergent vulnerability to substitution threats, with promotional commodity grades facing squeeze from digital wellness apps while therapy-calibrated variants build moats through clinical validation. Understanding these fault lines clarifies where formulation investment and channel strategy should concentrate.
Product Type:
Foam stress balls confront the most acute substitution pressure from fidget spinners and desk toys, while gel and rubber variants defend position through functional differentiation that cheaper alternatives cannot replicate.
- Foam Stress Balls:Molded from open-cell polyurethane with densities ranging from 25 to 45 kg/m³, these units accommodate high-fidelity screen printing for logo reproduction. Procurement from United States technology employers now favors these for hybrid office starter kits, though unit margins compress under bulk order pressure.
- Gel Stress Balls:Medical-grade elastomer compounds deliver calibrated tactile resistance across 5-15 durometer ratings. Demand concentrates in Cleveland Clinic and Kaiser Permanente rehabilitation networks where grip strength metrics inform telehealth protocols, creating regulatory barriers to substitution.
- Rubber Stress Balls:Natural and synthetic rubber latex formulations provide high rebound characteristics favored by athletic training facilities.
- Custom Shape Stress Balls:Injection-molded or rotocast geometries replicate branded objects, animals, or anatomical forms for promotional campaigns.
Foam stress balls anchor the volume base while gel stress balls gain share at the steepest rate.
End User:
Cost tier stratification separates institutional buyers with standardized procurement protocols from fragmented consumer segments where price sensitivity dominates.
- Schools:Bulk acquisition through district-level purchasing cooperatives favors minimum order quantities above 5,000 units with CPSIA small-part compliance mandatory. Budget constraints push these buyers toward foam formulations despite durability trade-offs.
- Corporates:HR departments at Fortune 500 employers now mandate tactile wellness devices as standard distributed workforce kit components rather than discretionary promotional items, with Amazon Business auto-replenishment capturing recurring revenue.
- Therapy Centers:Physical therapy networks require SKU proliferation for resistance gradation, fragmenting production runs but commanding 3-4x unit premiums over promotional grades.
- Home Use:Individual consumers purchase through online retail with minimal brand loyalty and high price elasticity.
Corporate procurement anchors the volume base while therapy center demand gains share at the steepest rate.
Distribution Channel:
Channel margin structures diverge sharply, with e-procurement platforms compressing distributor markups while specialty stores defend position through customization services.
- Online Retail:Amazon Business and Staples Advantage punchout catalogs integrate with SAP Ariba and Coupa, capturing share from traditional distributor relationships through configurable minimum order quantities and headcount-calibrated auto-replenishment.
- Specialty Stores:Promotional products distributors such as 4Imprint and Quality Logo Products sustain repeat engagement through decoration depth and proofing services that self-service platforms cannot replicate.
- Supermarkets:Mass retail placement reaches home use segments with impulse-purchase pricing but minimal margin contribution.
- Wholesale:Distributor intermediaries serve smaller corporate accounts without direct platform integration capabilities.
Online retail anchors the volume base while specialty stores defend share through service differentiation.
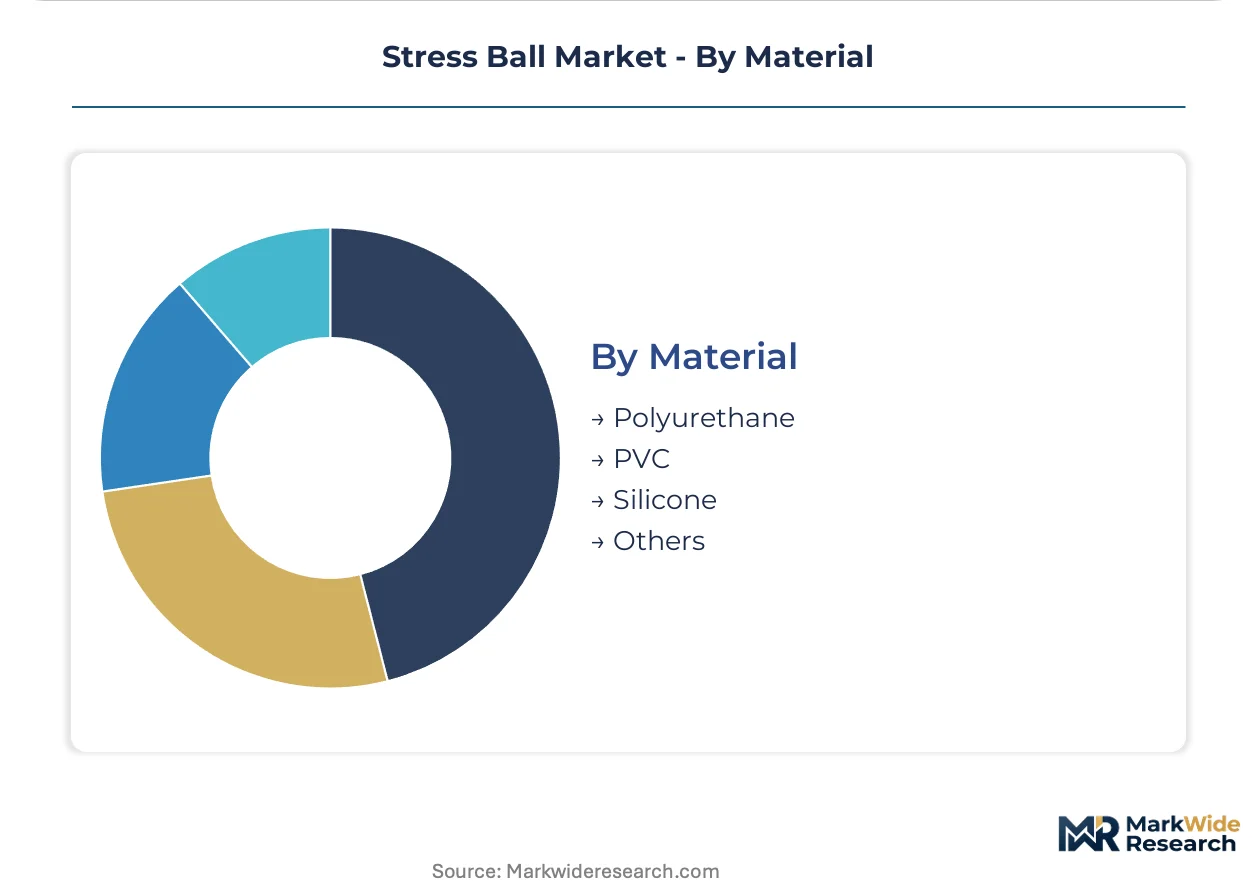
Material:
Regulatory compliance timelines are forcing rapid material transitions, with REACH phthalate restrictions eliminating incumbent formulations faster than substitution economics would otherwise dictate.
- Polyurethane:Cold-cure molding advances compress unit costs while maintaining screen-print fidelity, dominating foam stress ball production for promotional applications with petrochemical feedstock volatility the primary margin risk.
- PVC:Plasticized formulations previously delivered tactile consistency for gel-filled products but face forced abandonment across European member states under ECHA enforcement, with German manufacturers absorbing TPU cost premiums to maintain market access.
- Silicone:Medical-grade platinum-cured compounds command premium positioning for therapy applications with superior biocompatibility and temperature stability.
- Others:TPU and natural rubber latex serve niche specifications with latex allergen labeling adding FDA compliance overhead for therapy channel distribution.
Polyurethane anchors the volume base while silicone gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States employers distribute stress balls through standardized wellness kits for hybrid workers, while German buyers prioritize REACH-compliant formulations over unit cost. Indian procurement remains episodic and price-sensitive, concentrated in IT corridor bulk orders.
United States
Tech sector employers from Seattle to Austin mandate tactile wellness devices in remote work starter packages, creating predictable procurement cycles through Amazon Business auto-replenishment. FDA latex allergen labeling requirements govern therapy channel distribution. Corporate headquarters clusters in Silicon Valley and Manhattan anchor promotional bulk order volumes.
Germany
Industrial Mittelstand employers absorb TPU compound cost premiums to maintain European market access under ECHA enforcement. REACH Annex XVII phthalate restrictions eliminate PVC formulations faster than substitution economics would dictate. Manufacturing concentration in North Rhine-Westphalia supplies compliant gel-filled variants to rehabilitation networks.
China
Export-oriented fabricators in the Yangtze River Delta cold-cure polyurethane foam at scale for North American promotional buyers. GB standards for toy safety align with CPSIA small-part requirements for child-facing SKUs. Shenzhen and Guangzhou trading companies intermediate between domestic production and overseas e-procurement platforms.
India
IT services employers in Bengaluru and Hyderabad pilot bulk stress ball procurement for employee retention, though BIS certification gaps delay standardization. CDSCO medical device pathways remain underutilized for therapy-grade imports. Mumbai promotional distributors serve episodic corporate gifting demand without recurring revenue structures.
United Kingdom
London-based HR departments source through Staples Advantage punchout catalogs integrated with SAP Ariba for distributed workforce kits. UKCA marking transitions create temporary regulatory friction for EU-sourced inventory. Financial services clusters in the City and Canary Wharf sustain premium customization demand for client-facing wellness programs.
Stress Ball Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with promotional products distributors commanding recurring corporate relationships while commodity foam fabricators compete on unit economics. The vendor base separates into three strategic archetypes: catalog-based promotional distributors with decoration depth, medical-grade compound specialists serving rehabilitation networks, and offshore volume fabricators feeding e-procurement platforms. Competitive moves concentrate on e-procurement platform integration and REACH-compliant formulation transitions.
Among North American promotional distributors, 4Imprint and Quality Logo Products occupy positions within the catalog-based tier, anchoring corporate bulk order flows through proofing services and customization depth that self-service platforms cannot replicate. These entities exemplify the service-differentiation archetype defending share against Amazon Business and Staples Advantage automation.
| Leading Market Players |
|---|
| YoYa Toys |
| 4Imprint |
| Stressballs.com |
| Fansteck |
| Quality Logo Products |
| Neliblu |
| Totally Promotional |
| Chuchik |
| Impresa Products |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between North American promotional distributors and Yangtze River Delta fabricators lock in polyurethane foam supply while freezing unit costs against petrochemical volatility. These contracts tether price visibility to volume commitments, compressing margin uncertainty for bulk procurement cycles.
Pricing Analysis
Spot purchasing dominates promotional-grade foam stress balls where Amazon Business and Staples Advantage algorithms calibrate pricing to employee headcount fluctuations. Three-tier pricing structure across therapy-certified, corporate-branded, and economy promotional levels separates gel-filled medical devices from screen-printed commodities. Pricing pressure stems from cold-cure molding advances that compress polyurethane unit costs without quality sacrifice. Schools and district purchasing cooperatives exhibit highest price sensitivity, while Kaiser Permanente rehabilitation networks absorb premium positioning for calibrated resistance devices.
Supply Chain Analysis
Just-in-time inventory strategies predominate among promotional distributors serving episodic corporate gifting demand, whereas therapy-grade manufacturers maintain strategic stockpiles of medical-grade silicone compounds to buffer German chemical supplier concentration. Production gravity centers on China's Yangtze River Delta for polyurethane foam, Germany's North Rhine-Westphalia for compliant gel formulations, and India's Bengaluru-Hyderabad corridor for emerging IT services procurement. Raw material dependencies span polyol and isocyanate feedstocks, TPU compounds, and platinum-cured silicone. Single-source vulnerability concentrates in three German elastomer suppliers serving medical-grade applications. Distribution runs through e-procurement platform punchout catalogs integrated with SAP Ariba and Coupa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based wellness kit replenishment is expanding faster than hardware unit sales, converting one-time promotional transactions into recurring revenue streams with superior lifetime value economics.
For Market Incumbents: Shield corporate relationships from Amazon Business automation by deepening customization services and proofing capabilities that self-service platforms cannot replicate. Fortify supply security through backward integration into polyurethane foam molding or captive TPU compound sourcing to offset German supplier concentration risk. Prioritize ISO 13485 certification investment to capture rehabilitation network demand with regulatory barriers. For New Entrants and Emerging Players: Differentiate on REACH-compliant formulation transparency, targeting European ECHA enforcement gaps left by PVC-dependent incumbents. India's IT services corridor offers the most penetrable geography, with BIS certification alignment unlocking standardized procurement absent today. Deploy direct e-procurement platform integration as the primary go-to-market angle, bypassing traditional distributor markups. For Investors and Strategic Acquirers: Medical-grade compound specialists with FDA device registrations and Kaiser Permanente network relationships represent the priority acquisition archetype. Long-term viability favors suppliers with clinical validation moats over commodity promotional fabricators facing digital wellness app substitution. Watch biometric sensor integration adoption rates as the inflection signal separating medical-grade from promotional tier viability.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Transition | TPU and silicone substitution preserves European market access under ECHA phthalate enforcement. |
| E-Procurement Platform Integration | PunchOut catalog connectivity with SAP Ariba captures recurring corporate wellness kit revenue. |
| ISO 13485 Medical Device Certification | Rehabilitation network entry requires calibrated resistance validation for grip strength protocols. |
| Biometric Sensor Embedding | Texas Instruments pressure-sensitive resistors enable telehealth platform integration for remote monitoring. |
| Subscription-Based Replenishment Models | Auto-replenishment algorithms calibrated to headcount changes displace one-time bulk orders. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with HR procurement managers at Fortune 500 employers, physical therapy network administrators, promotional products distributors, polyurethane foam plant managers, and German elastomer compound specialists. Secondary validation drew from ECHA REACH substance dossiers, FDA device registration databases, customs trade data for polyurethane feedstocks, and SEC filings from promotional products distributors. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, material, and distribution channel dimensions.
Across the analysis window, volume and value outputs reflect segmentation by foam density grade, gel durometer calibration, corporate versus therapy end-use, and e-procurement platform penetration. CAGRs were derived from regression analysis of procurement cycle data and material substitution timelines. Forecast inputs incorporated REACH Annex XVII compliance deadlines, tech sector hybrid office policy durability, and cold-cure molding cost compression curves.
The analysis sits within stated boundaries; outcomes outside sustained corporate wellness program expansion or accelerated REACH enforcement would require recalibration. Forecasts reflect documented assumptions regarding petrochemical feedstock stability and rehabilitation network sensor adoption rates. Revision becomes warranted when ECHA extends phthalate restrictions beyond current toy and childcare article scopes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Automated Laundromat Services Market
Consumer Electronics
Adult Sex Dolls Market
Consumer Electronics
China Smartphone Market
Consumer Electronics
Nanopresso Market
Consumer Electronics
Wireless Earphone Market
Consumer Electronics
Asia-Pacific Gaming Keyboard Market
Consumer Electronics
Earphones Market
Consumer Electronics
Nail Art Printer Market
Consumer Electronics
United States Gaming Peripherals Market
Consumer Electronics
Kindle E-Reader Accessories Market
Consumer Electronics
Sports Electronics Market
Consumer Electronics
Mechanical Keyboard Market
Consumer Electronics
Portable Speaker Market
Consumer Electronics
Global Digital Watch Market
Consumer Electronics
Portable Stick Market
Consumer Electronics
Smart DJ Controller Market