
 Used and Refurbished Smartphone Market | 2026-2036
Used and Refurbished Smartphone Market Size, Share, and Industry Trends Forecast 2026-2036
Used and Refurbished Smartphone Market Outlook
The EU Ecodesign for Sustainable Products Regulation is broadening the addressable market for circular electronics by mandating repairability scores and spare parts availability across member states. Back Market leverages its pan-European certified refurbishment network to capture premium resale margins in France and Germany. Samsung Electronics Co., Ltd. anchors its Galaxy Upcycling program with in-house component recovery lines that reduce reliance on third-party parts suppliers.
Used and refurbished smartphones are pre-owned mobile devices that undergo diagnostic testing, component replacement, and software restoration to meet functional performance thresholds such as minimum battery health percentages and display integrity standards; these devices serve cost-conscious consumers and institutional buyers seeking computing access without new-product premiums. The condition segment stratifies across refurbished, used, open-box, and like-new tiers, with refurbished units commanding the strongest margin pools due to warranty attachment and quality certification. Online marketplaces dominate volume throughput, though authorized reseller channels capture higher trust premiums from enterprise and educational institution accounts.
The EU Green Deal and REACH frameworks constrain hazardous substance thresholds in refurbished device components, while the US EPA electronics recycling standards shape cross-border material recovery protocols for lithium-ion batteries and rare earth elements. India's BIS certification requirements for imported pre-owned electronics create compliance barriers that favor domestic refurbishment operators with established testing infrastructure. Stakeholders must monitor how right-to-repair legislation evolves across jurisdictions to anticipate shifts in parts availability, warranty obligations, and competitive positioning between manufacturer-led and independent refurbishment channels.
Market Dynamics
The EU Ecodesign for Sustainable Products Regulation is forcing rapid recalibration across refurbishment value chains, mandating repairability scores and spare parts availability that favor operators with in-house diagnostic infrastructure over asset-light resellers.
Growth Catalysts
- Right-to-repair mandates:The EU Green Deal and national transpositions in France and Germany require manufacturers to supply spare parts for minimum seven-year windows, expanding the addressable pool of serviceable devices for certified refurbishers.
- Enterprise fleet turnover:Fortune 500 IT procurement teams are expanding certified pre-owned device programs to meet Scope 3 emissions targets while preserving capital expenditure flexibility.
- India's urban middle-class expansion:Tier-2 city retailers in Gujarat and Tamil Nadu are driving volume through localized refurbishment hubs that bypass import duties on fully assembled new devices.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material refining for replacement battery packs concentrates in Chinese processing facilities, exposing margin structures to export control volatility and shipping cost spikes.
- Display panel technical obsolescence:OLED burn-in thresholds and foldable screen durability limits create irrecoverable failure modes that shrink the refurbishable device pool faster than diagnostic tooling evolves.
- BIS certification friction:India's Bureau of Indian Standards mandates fresh safety testing for each imported pre-owned electronics batch, adding 45-90 day customs delays that erode inventory turns for cross-border operators.
Strategic Opportunities
- Ghana's emerging secondary market:Accra's informal repair clusters are formalizing through partnerships with European take-back schemes, creating first-mover advantage for operators establishing ISO-compliant testing facilities in West Africa.
- Component-level AI diagnostics:Machine vision systems trained on battery health signatures and solder joint integrity are converging with automated disassembly robotics to cut per-unit refurbishment labor hours.
- Educational institution procurement channels:K-12 districts and community colleges in Texas and Ohio are piloting certified pre-owned tablet programs under new state-level circular economy purchasing guidelines.
Industry Challenges
- Surface-mount rework technician scarcity:Microsoldering expertise for logic board repair remains concentrated in Shenzhen and Seoul training pipelines, constraining capacity expansion in European and North American facilities.
- Software lock authentication complexity:Apple's Activation Lock and Google's Factory Reset Protection protocols require original credential verification that delays device processing and increases write-off rates for unrecoverable units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Used and Refurbished Smartphone Market |
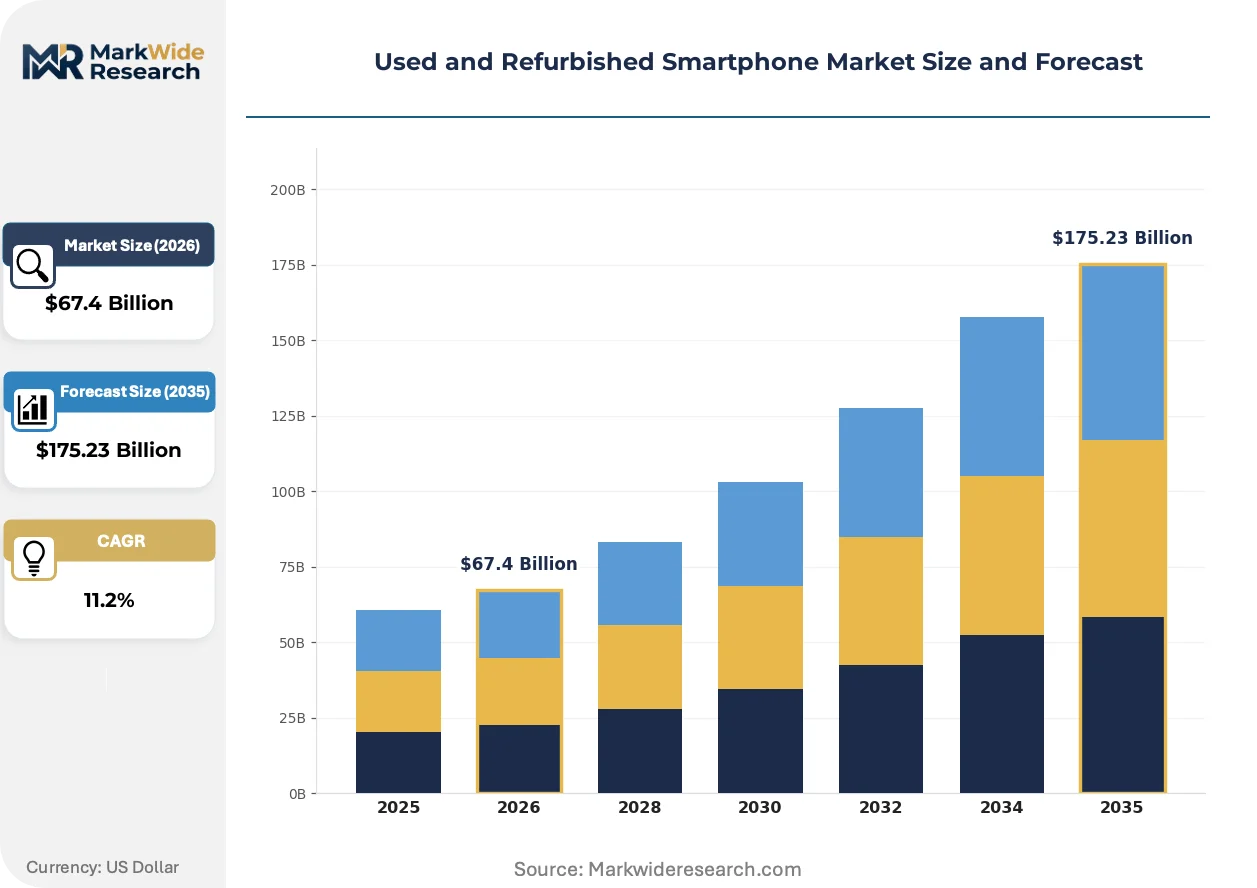
| Market Size in 2026 | $67.4 Billion |
| Market Size in 2035 | $175.23 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Tablets, Phablets, Wearables Condition: Refurbished, Used, Open-Box, Like New Sales Channel: Online Marketplace, Retail Store, Authorized Reseller, Direct Sales End User: Consumers, Businesses, Educational Institutions, Nonprofits |
| Companies Covered | Back Market, Verizon Communications Inc., Apple Inc., Best Buy Co., Inc., AT&T Inc., Samsung Electronics Co., Ltd., eBay Inc., Swappa, Amazon.com, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Used and Refurbished Smartphone Market Strategic Shifts
Automated diagnostic platforms and blockchain-based provenance tracking are compressing trust premiums that previously favored manufacturer-led channels, while regulatory pressure on repairability is accelerating investment in component recovery infrastructure.
AI-powered battery health prediction algorithms are expanding into refurbishment workflows, enabling graders to forecast remaining cycle life from voltage curve signatures rather than full discharge testing. German and Dutch operators are adopting these systems fastest, cutting per-device testing time from 45 minutes to under 8 minutes. This compression is expanding into premium pricing tiers as warranty attach rates rise for algorithm-certified units.
REACH substance restrictions are tightening hazardous material thresholds in replacement components across EU member states, forcing suppliers to reformulate solder alloys and battery electrolytes. Refurbishment operators in Poland and Romania must now document full material declarations for lithium-ion cells to maintain CE marking eligibility. The compliance burden is concentrating volume among mid-sized operators with dedicated regulatory affairs functions.
Enterprise buyers are consolidating vendor relationships around certified pre-owned specialists who bundle device-as-a-service contracts with end-of-life take-back guarantees. This procurement consolidation is displacing spot-market purchasing through auction platforms, particularly in healthcare and financial services verticals where data sanitization documentation carries liability weight. The shift is most visible in German automotive supplier networks and Dutch hospital systems.
Used and Refurbished Smartphone Market Segmentation
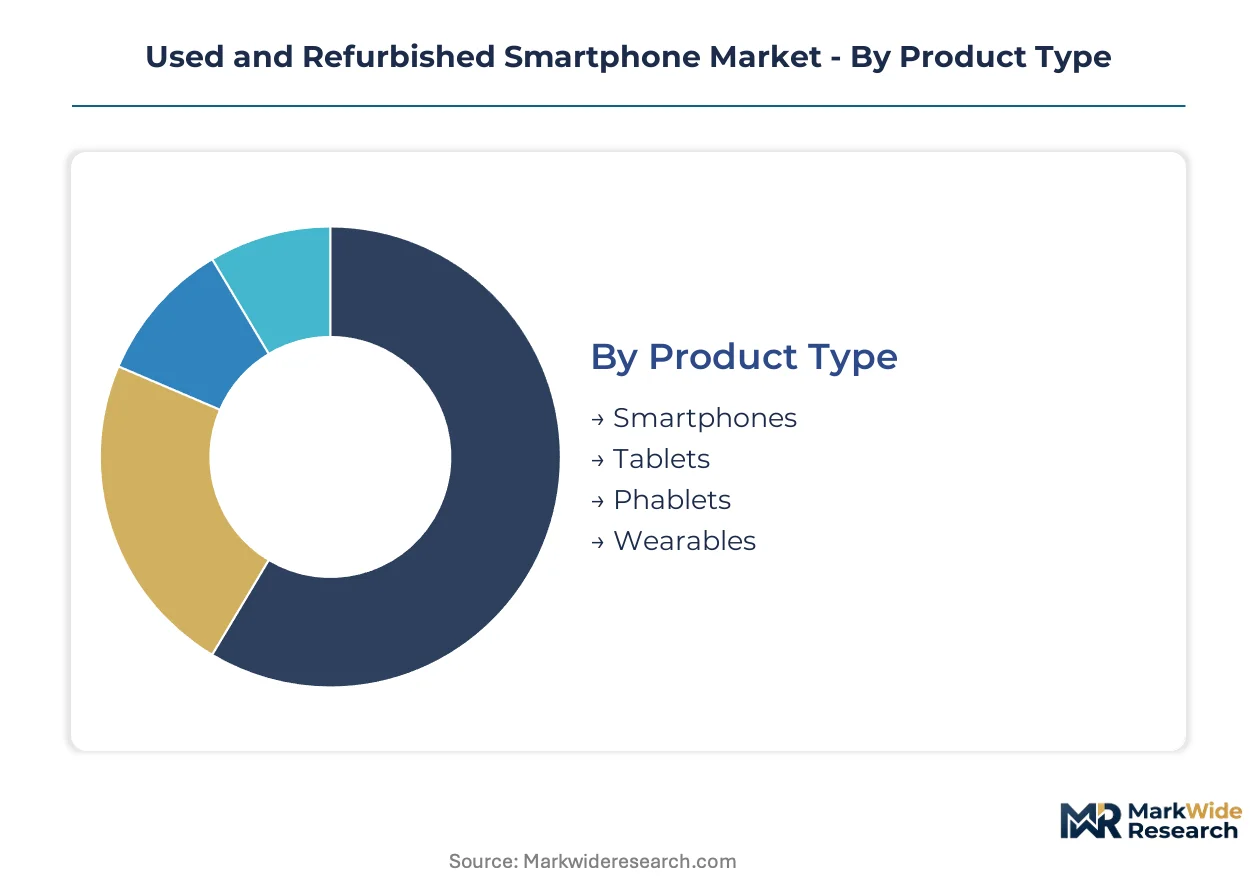
Segmentation in the used and refurbished smartphone market determines margin capture, warranty attachment rates, and channel selection. Distinct condition tiers and sales channels serve fundamentally different risk appetites and procurement workflows across consumer and institutional buyers.
Product Type:
Smartphones dominate refurbishment economics as standalone devices with standardized diagnostic protocols, while tablets and wearables embed into broader ecosystem strategies with divergent recovery value profiles.
- Smartphones:These units undergo battery health verification, display calibration, and logic board functional testing against OEM performance thresholds. Demand concentrates in India's tier-2 cities where localized refurbishment hubs bypass import duties on fully assembled new devices, driven by urban middle-class cost sensitivity.
- Tablets:Larger form factors require specialized screen lamination equipment and digitizer calibration tools that raise per-unit refurbishment capital intensity. Educational institutions in Texas and Ohio are piloting certified pre-owned tablet programs under state-level circular economy purchasing guidelines, creating institutional volume anchors.
- Phablets:Hybrid devices occupy narrow inventory bands with limited parts interchangeability across generations.
- Wearables:Compact architectures and sealed battery designs restrict component-level repair viability to surface-level refurbishment.
Volume placements concentrate in Smartphones; the faster expansion belongs to Tablets.
Condition:
Condition tiers stratify pricing power through warranty differentiation and certification depth, with quality signaling mechanisms determining channel access and buyer trust premiums.
- Refurbished:Units complete diagnostic testing, component replacement, and software restoration to meet minimum battery health percentages and display integrity standards. Enterprise procurement teams across Fortune 500 companies are expanding certified pre-owned device fleets to meet Scope 3 emissions targets while preserving capital expenditure flexibility.
- Like New:Open-box returns and minimal-use devices command narrow discounts against new retail with full warranty transferability. Online marketplaces dominate volume throughput for this tier, though authorized reseller channels capture higher trust premiums from enterprise and educational institution accounts.
- Used:As-is sales without functional certification limit buyer recourse and compress margin structures.
- Open-Box:Retail returns with original packaging intact serve price-sensitive consumers seeking near-new aesthetics.
Volume placements concentrate in Refurbished; the faster expansion belongs to Like New.
Sales Channel:
Channel selection determines authentication burden, data sanitization liability exposure, and buyer demographic access across institutional and consumer segments.
- Online Marketplace:Platforms aggregate fragmented supply and compress trust premiums through rating systems and return policies. Germany and Dutch operators are adopting AI-powered battery health prediction algorithms fastest, cutting per-device testing time from 45 minutes to under 8 minutes for algorithm-certified units sold through digital channels.
- Authorized Reseller:Certified pre-owned specialists bundle device-as-a-service contracts with end-of-life take-back guarantees, consolidating procurement relationships in healthcare and financial services verticals where data sanitization documentation carries liability weight.
- Retail Store:Physical inspection and immediate fulfillment serve consumers prioritizing tactile verification over price optimization.
- Direct Sales:Manufacturer-led refurbishment programs control parts authentication and software lock verification, reducing write-off rates for unrecoverable units.
Volume placements concentrate in Online Marketplace; the faster expansion belongs to Authorized Reseller.
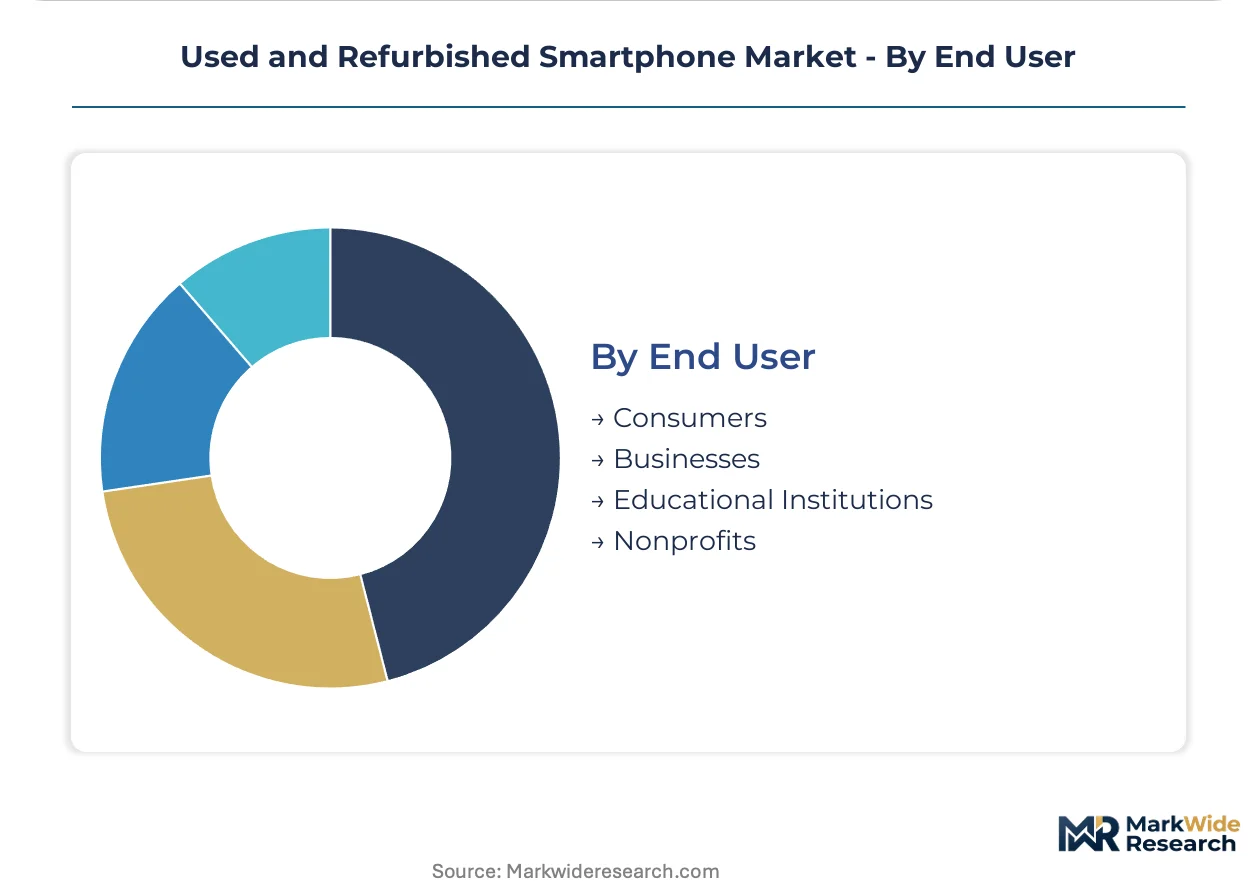
End User:
End-user segmentation drives warranty term structure, volume pricing tiers, and compliance documentation requirements across procurement workflows.
- Consumers:Individual buyers prioritize cost reduction against new-device premiums with shorter warranty horizons and higher price elasticity. India's urban middle-class expansion in Gujarat and Tamil Nadu drives volume through localized refurbishment hubs that bypass import duties on fully assembled new devices.
- Businesses:Enterprise IT procurement teams require Scope 3 emissions documentation, data sanitization certificates, and end-of-life take-back guarantees to satisfy circular economy mandates and preserve capital expenditure flexibility.
- Educational Institutions:K-12 districts and community colleges in Texas and Ohio pilot certified pre-owned tablet programs under new state-level circular economy purchasing guidelines, creating procurement consolidation opportunities.
- Nonprofits:Mission-driven organizations seek computing access expansion with donor-funded device refresh cycles and limited technical support infrastructure.
Volume placements concentrate in Consumers; the faster expansion belongs to Businesses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refurbishment capacity concentrates in China and Southeast Asia while consumption gravity shifts toward India, Europe, and North American enterprise buyers. This production-consumption divide shapes cross-border trade flows and regulatory compliance burdens across the value chain.
United States
Enterprise fleet turnover drives volume as Fortune 500 IT procurement teams expand certified pre-owned device programs to meet Scope 3 emissions targets. The EPA electronics recycling standards shape material recovery protocols for lithium-ion batteries. Dallas-Fort Worth and Austin host growing refurbishment clusters serving educational institution pilots under Texas circular economy purchasing guidelines.
Germany
REACH substance restrictions and the EU Ecodesign for Sustainable Products Regulation tighten hazardous material thresholds in replacement components. The right-to-repair transposition mandates seven-year spare parts availability from manufacturers. Berlin and Hamburg anchor pan-European certified refurbishment networks capturing premium resale margins through warranty-backed quality signaling.
India
Urban middle-class buyers in Gujarat and Tamil Nadu drive volume through localized refurbishment hubs that bypass import duties on fully assembled new devices. BIS certification requirements for imported pre-owned electronics create compliance barriers favoring domestic operators with established testing infrastructure. Ahmedabad and Chennai host the densest concentrations of tier-2 city retailers formalizing supply chains.
France
The national repairability index mandates disclosure scores that channel consumer preference toward certified refurbishers with documented diagnostic protocols. ANSM and CNIL oversight extends to data sanitization certification for enterprise device flows. Paris anchors take-back scheme partnerships with West African markets formalizing Accra's emerging secondary market.
China
Cathode material refining for replacement battery packs concentrates processing capacity exposed to export control volatility. MIIT standards govern component recovery line investments by manufacturer-led programs. Shenzhen and Dongguan host the deepest microsoldering expertise pipelines constraining capacity expansion in European and North American facilities.
Used and Refurbished Smartphone Market Competitive Environment
The competitive structure tilts toward platform aggregators and manufacturer-led refurbishment programs over independent repair operators. Consolidation pressure concentrates volume among mid-sized operators with dedicated regulatory affairs functions capable of navigating CE marking and BIS compliance burdens. Two strategic archetypes dominate: pan-European certified refurbishment networks leveraging warranty attachment for premium pricing, and carrier-led trade-in programs controlling device sourcing through subscription bundling. Geographic expansion and component recovery infrastructure investment represent the dominant competitive moves.
Within the platform-aggregator tier, Back Market exemplifies the pan-European certified refurbishment model, while Amazon.com, Inc. and eBay Inc. occupy positions as volume-aggregating marketplaces compressing trust premiums through rating systems and return policies. Samsung Electronics Co., Ltd. anchors manufacturer-led refurbishment through in-house component recovery lines, reducing reliance on third-party parts suppliers. Apple Inc. represents the closed-ecosystem archetype controlling software lock authentication and parts authentication protocols that shape write-off rates for unrecoverable units.
| Leading Market Players |
|---|
| Back Market |
| Verizon Communications Inc. |
| Apple Inc. |
| Best Buy Co., Inc. |
| AT&T Inc. |
| Samsung Electronics Co., Ltd. |
| eBay Inc. |
| Swappa |
| Amazon.com, Inc. |
| Others |
Value Chain & Pricing Dynamics
Enterprise procurement teams at Fortune 500 companies anchor pricing power through volume-based device-as-a-service contracts that bundle certified pre-owned hardware with end-of-life take-back guarantees. This buyer concentration forces refurbishment operators toward tiered certification pricing that separates warranty-backed premium tiers from economy-grade as-is sales.
Pricing Analysis
Margin tightening in the refurbished tier reflects REACH compliance costs for reformulated solder alloys and battery electrolytes. Pricing stratifies across premium, standard, and economy tiers based on certification depth and warranty attachment rates. Cost-down pressure accelerates as AI-powered diagnostics compress per-unit testing labor from 45 minutes to under 8 minutes. Consumers in India's tier-2 cities exhibit highest price elasticity, while German healthcare systems accept premium pricing for data sanitization documentation.
Supply Chain Analysis
Dual-sourcing requirements from European operators mandate qualified suppliers across both Chinese cathode processing facilities and South Korean battery cell manufacturers. Component recovery draws from concentrated lithium-ion refining capacity in China, display panel supply in South Korea, and microsoldering expertise pipelines in Shenzhen. Single-source vulnerability concentrates in Chinese export control exposure for cathode materials. Distribution runs through pan-European certified refurbishment networks and carrier-led trade-in programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The used and refurbished smartphone market sits at a technology-transition phase where AI-powered diagnostic platforms displace manual grading workflows. Machine vision systems trained on battery health signatures are replacing legacy discharge testing protocols.
For Market Incumbents: Deepen component recovery infrastructure investments to reduce reliance on Chinese cathode material suppliers amid export control volatility. Establish in-house diagnostic robotics capabilities before automated grading becomes table stakes. Samsung Electronics Co., Ltd.'s Galaxy Upcycling program demonstrates how captive component lines defend margin structures against third-party parts inflation.
For New Entrants and Emerging Players: Launch via ISO-compliant testing facilities in Ghana's emerging formalization corridor, where European take-back scheme partnerships create first-mover positioning. Target educational institution procurement channels in Texas and Ohio piloting circular economy purchasing guidelines. Bundle tablet refurbishment with K-12 data sanitization certification to bypass consumer marketplace saturation.
For Investors and Strategic Acquirers: The window for entry favors mid-sized operators with dedicated regulatory affairs functions capable of navigating CE marking and BIS compliance burdens. Long-term viability hinges on component recovery infrastructure rather than asset-light marketplace aggregation. Watch for BIS certification friction resolution in India as inflection signal for cross-border inventory turn recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Component Recovery Infrastructure Investment | In-house cathode processing reduces exposure to Chinese export control volatility. |
| AI Diagnostic Platform Deployment | Machine vision systems cut per-unit testing labor hours and expand warranty attach rates. |
| Pan-European Certification Network Expansion | CE marking compliance captures premium resale margins in Germany and France. |
| Educational Institution Procurement Partnership | Texas and Ohio circular economy pilots create institutional volume anchors for tablets. |
| West African Testing Facility Establishment | ISO-compliant operations in Accra formalize informal repair clusters for European take-back flows. |
Study Parameters
Trade databases, regulatory filings, and industry association reports formed the secondary backbone for supply chain mapping and compliance burden quantification. Primary interviews with refurbishment facility operators, enterprise IT procurement managers, and regulatory affairs specialists at CE marking consultancies combined with secondary validation. Bottom-up triangulation across device throughput estimates and top-down cross-checks against circular economy spending disclosures anchored volume projections.
Historical trendline analysis of refurbishment volume growth, battery replacement cycle compression, and enterprise fleet turnover rates informed the analytical framework across the projection horizon. Segmentation dimensions modeled include condition tier, sales channel, and end-user vertical alongside regional regulatory cluster differentiation. CAGRs derived from fitted growth curves applied to certified pre-owned device adoption curves and right-to-repair mandate implementation timelines.
Export control escalation, BIS certification processing delays, and OLED burn-in technical obsolescence are the dominant revision risks for forecast assumptions. Deviation in Chinese cathode material export restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Speaker Market
Consumer Electronics
Tablet Market
Consumer Electronics
Sleep Headphones Market
Consumer Electronics
Tattoo Machine Market
Consumer Electronics
Home Entertainment Devices Market
Consumer Electronics
Wireless Mouse Market
Consumer Electronics
Headset Market
Consumer Electronics
Global Smart Earbuds Market
Consumer Electronics
Silicone Sex Doll Market
Consumer Electronics
Global Laptop Skins Market
Consumer Electronics
Digital Writing Instruments Market
Consumer Electronics
Smart Home Projector Market
Consumer Electronics
China Smartphone Market
Consumer Electronics
US Mobile Phone Accessories Market
Consumer Electronics
North America Wireless Anc Headphone Market
Consumer Electronics
United States Stylus Pen Market