
 Gaming Gadgets Market | 2026-2036
Gaming Gadgets Market Size, Share, and Industry Trends Forecast 2026-2036
Gaming Gadgets Market Intelligence
Specialized component manufacturing in Taiwan and China is realigning the supply chain for high-performance gaming peripherals. This shift affects how brands source key parts like mechanical switches and optical sensors. Razer Inc. specializes in the premium peripheral market for competitive players, focusing on low-latency and ergonomic designs. In contrast, Logitech leverages its extensive distribution network to serve a broad spectrum of users from casual to professional gamers. Corsair competes by offering an integrated ecosystem of components and peripherals for PC building enthusiasts.
Gaming gadgets encompass a range of electronic peripherals designed to enhance user control, immersion, and performance in video games. These devices often feature technical specifications such as high-polling rates for mice, low-latency wireless connectivity, and customizable actuation points in keyboards. Their primary purpose is to provide a competitive advantage or a more engaging entertainment experience. While gaming keyboards and mice remain mature product types, VR headsets and specialized gaming chairs represent high-growth segments. Demand from professional gamers and streamers for devices with advanced motion sensors and haptic feedback is driving product development.
The market operates under stringent electronic device regulations that vary by region. In the United States, the FCC sets standards for wireless emissions from Bluetooth and Wi-Fi enabled gadgets. In Europe, all electronic products must carry the CE marking, indicating compliance with health, safety, and environmental protection standards, including RoHS directives on hazardous substances. Navigating these disparate compliance requirements for wireless spectrum allocation and material safety is a critical consideration for manufacturers aiming for market access across multiple continents.
Market Dynamics
The central structural force shaping the gaming gadgets market is the professionalization of eSports. This shift drives a feedback loop where demand for higher-performance peripherals from competitive players accelerates innovation cycles for features like advanced haptics and optical sensors.
Growth Catalysts
- eSports Professionalization:The global expansion of professional gaming leagues, especially in South Korea, creates a consistent demand cycle for high-performance keyboards, mice, and headsets with minimal latency and superior ergonomics for competitive advantage.
- Broadband Infrastructure Expansion:Government-led initiatives to expand high-speed internet access in emerging economies like Brazil and India are unlocking new populations of online gamers, creating fresh demand for entry-level and mid-range gaming peripherals.
- Advanced Haptic Systems:The integration of sophisticated haptic feedback technology provides deeper immersion and new forms of gameplay information, attracting both casual and hardcore gamers seeking more engaging entertainment experiences beyond visual and audio cues.
Market Restraints
- Semiconductor Price Volatility:Gaming peripherals depend on microcontrollers, sensors, and wireless chips, making their production costs highly sensitive to price fluctuations and supply shortages in the global semiconductor market, which can compress manufacturer margins.
- Component Supply Concentration:A heavy reliance on a few specialized manufacturers in Taiwan and China for critical components like mechanical keyboard switches and optical mouse sensors creates significant supply chain vulnerability and geopolitical risk.
- Mobile Gaming Substitution:The increasing power of smartphones, combined with a growing ecosystem of mobile-specific controllers and peripherals, presents a substitute for casual users who might otherwise invest in PC or console gaming setups.
Strategic Opportunities
- Professional Simulation Crossover:High-precision gaming peripherals, such as flight sticks and steering wheels with force feedback, are finding new applications in professional training simulators for industries like aviation, logistics, and healthcare.
- Expansion into Latin America:A growing middle class and strengthening digital infrastructure in countries like Mexico and Brazil represent a significant, underpenetrated market for gaming gadgets across all price points.
- Augmented Reality Integration:Developing peripherals that can interact with AR overlays offers a new frontier for immersive gameplay, moving beyond the confines of screen-based interaction to blend digital content with the physical environment.
Industry Challenges
- Complex Regulatory Navigation:Manufacturers face significant operational hurdles in managing disparate compliance requirements, such as FCC standards for wireless emissions in the US and CE marking with RoHS directives in Europe.
- Intellectual Property Disputes:The rapid pace of innovation leads to a contentious environment for patents related to proprietary technologies like low-latency wireless protocols and unique haptic feedback mechanisms, resulting in frequent legal challenges.
- Haptic Engineering Talent Gap:A shortage of engineers with specialized expertise in designing and integrating advanced haptic feedback systems and sensor fusion algorithms constrains the pace of next-generation product development for many firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaming Gadgets Market |
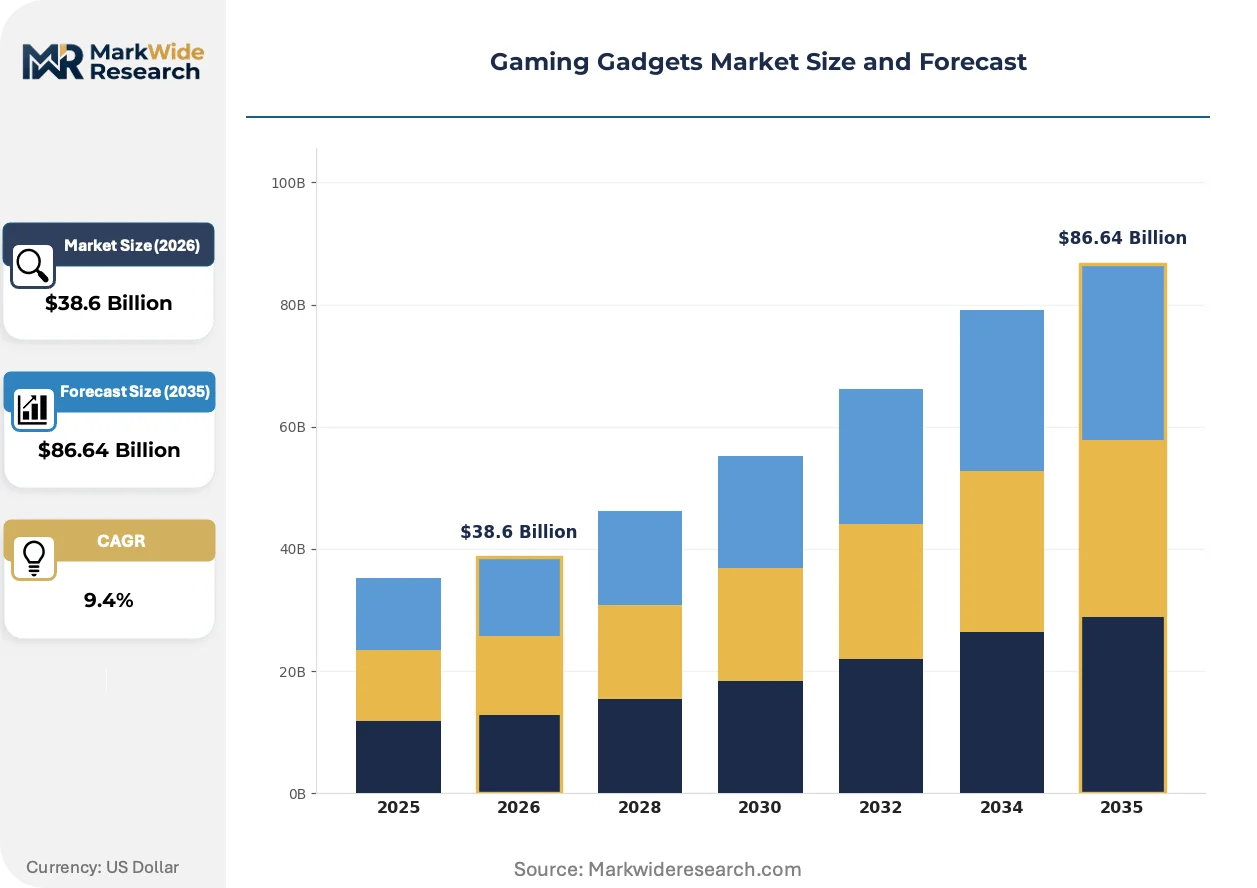
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $86.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gaming Controllers, VR Headsets, Gaming Keyboards, Gaming Mice, Gaming Chairs, Gaming Headphones Technology: Wireless, Wired, Bluetooth, RGB Lighting, Haptic Feedback, Motion Sensors Application: Console Gaming, PC Gaming, Mobile Gaming, Cloud Gaming, eSports, Game Development End User: Casual Gamers, Professional Gamers, Streamers, Game Developers, Content Creators, Competitive Players |
| Companies Covered | Logitech, Razer Inc., Corsair, SteelSeries, HyperX, Turtle Beach, Sony Corporation, Microsoft Corporation, Nintendo Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaming Gadgets Market Strategic Shifts & Innovations
Personalization is the defining theme, moving beyond cosmetic customization to encompass software-driven performance tuning. Integrated ecosystems that synchronize lighting, settings, and profiles across a user's peripherals are becoming standard as brands compete on user experience, not just hardware specifications.
Advanced wireless protocols using proprietary 2.4GHz connections now deliver performance indistinguishable from wired counterparts. Competitive gamers and eSports professionals are the primary adopters, seeking to eliminate cable drag without any latency penalty. This technology is unifying the desktop experience, allowing mice, keyboards, and headsets to operate seamlessly within a single, high-performance wireless ecosystem.
European Union directives like RoHS, which restricts hazardous substances in electronics, are compelling design changes across the industry. This regulation forces a costly re-engineering of internal components and materials, impacting supply chain sourcing for all manufacturers aiming to access the EU market. Firms must maintain stringent compliance documentation and verification processes, adding operational complexity.
A direct-to-consumer sales model is gaining significant momentum over traditional retail distribution. This approach disrupts the reliance on major electronics retailers, granting brands direct control over customer relationships, product messaging, and pricing strategy. This trend is most visible in North America, where brands effectively use influencer marketing and online communities to drive traffic to proprietary webstores.
Gaming Gadgets Market Segmentation
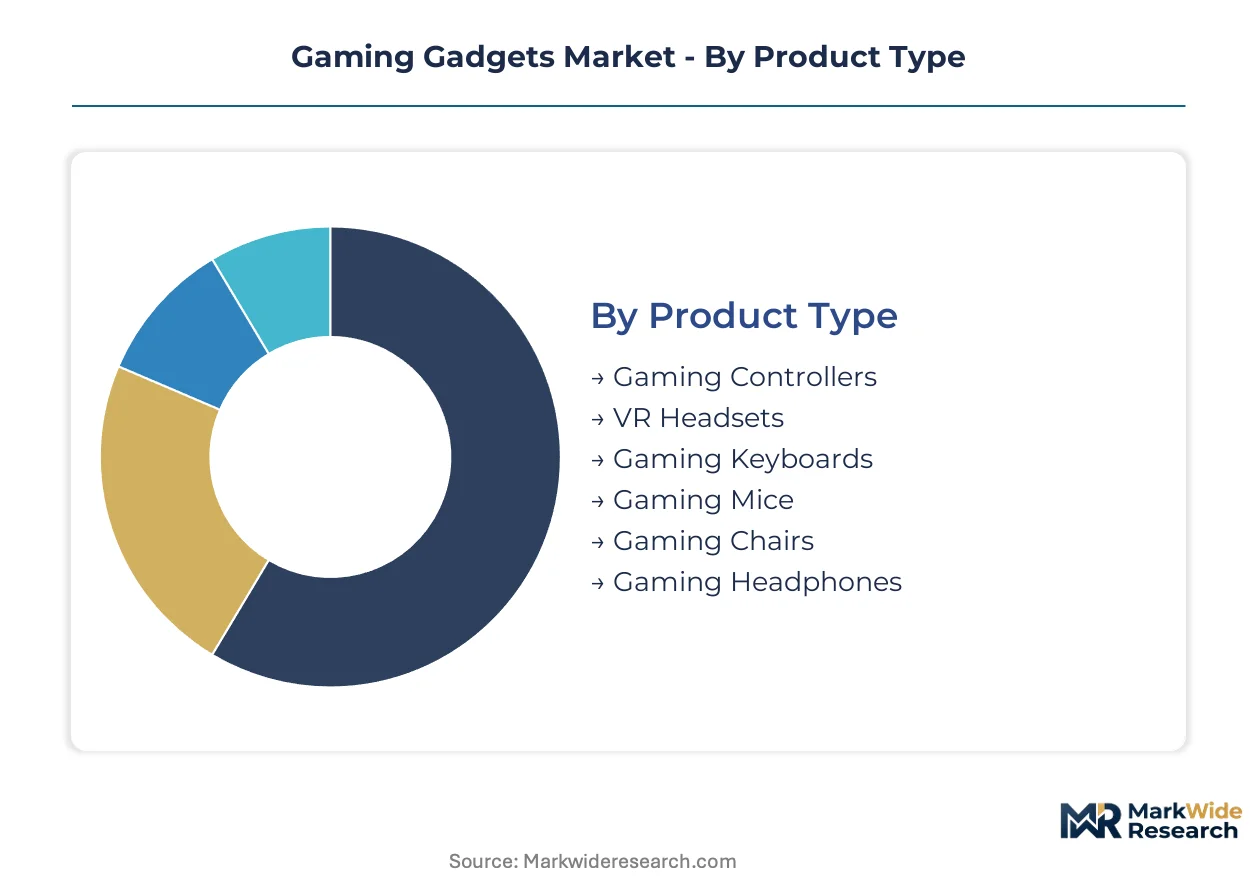
The gaming gadgets market exhibits diverse product offerings and technological integrations, reflecting varied user preferences and performance requirements. Understanding these distinct segments allows manufacturers to tailor their product development and market strategies effectively. This detailed segmentation highlights areas of concentrated demand and innovation within the industry.
Product Type:
The product type segmentation reveals a spectrum from highly customizable peripherals to standardized hardware, catering to different user needs and technical specifications.
- Gaming Controllers:These input devices provide tactile feedback and precise control for console and PC gaming, often featuring programmable buttons and ergonomic designs. Demand concentrates in console-dominant markets like the United States, driven by new console generations.
- VR Headsets:Immersive display devices combine high-resolution screens and advanced motion tracking to create virtual environments, offering unparalleled immersion for simulation and interactive experiences. South Korea shows strong demand, fueled by professional gaming culture and technology adoption.
- Gaming Keyboards:These input devices feature mechanical switches, customizable RGB lighting, and anti-ghosting technology for rapid, accurate keystrokes.
- Gaming Mice:High-precision optical or laser sensors, adjustable DPI settings, and programmable buttons define these devices, crucial for competitive gameplay requiring swift, accurate movements. Professional gamers prioritize low-latency wireless models.
- Gaming Chairs:Ergonomically designed seating solutions provide comfort and support during prolonged gaming sessions, often with lumbar support and recline functions.
- Gaming Headphones:These audio devices offer spatial sound, noise cancellation, and clear microphone communication, essential for team-based online gaming.
Leading the category by volume: Gaming Keyboards. Growing fastest: VR Headsets.
Technology:
Supply concentration in specialized component manufacturing significantly influences the technology segment, dictating availability and cost for advanced features in gaming gadgets.
- Wireless:Advanced proprietary 2.4GHz connections deliver low-latency performance comparable to wired options, eliminating cable drag for competitive players. This technology is critical for eSports professionals seeking unhindered movement.
- Wired:Traditional connectivity offers consistent, lag-free performance and reliable power delivery, often preferred for its simplicity and lower cost in entry-level peripherals.
- Bluetooth:This short-range wireless technology provides convenient connectivity for mobile gaming and casual use, supporting broader device compatibility.
- RGB Lighting:Customizable lighting systems enhance aesthetic appeal and can provide in-game notifications, driving demand among PC building enthusiasts.
- Haptic Feedback:Sophisticated vibration and force feedback systems provide tactile sensations, deepening immersion and conveying in-game information. Demand from professional gamers accelerates innovation in this area.
- Motion Sensors:Accelerometers and gyroscopes enable intuitive control and gesture-based interactions, particularly in VR headsets and specialized controllers.
These technologies collectively define the performance benchmarks, with Wireless setting the standard for responsiveness and Haptic Feedback expanding most quickly.
Application:
Different customer types drive distinct application segments, each requiring specific gadget functionalities and performance levels to optimize their gaming experiences.
- Console Gaming:This segment utilizes peripherals designed for PlayStation, Xbox, and Nintendo platforms, emphasizing ease of use and integrated ecosystem compatibility. Demand for specialized controllers and headsets remains strong.
- PC Gaming:Peripherals for personal computers demand high precision and customization, including mechanical keyboards and high-polling rate mice, catering to a diverse user base from casual to competitive.
- Mobile Gaming:This rapidly expanding segment relies on smartphone-compatible controllers and accessories, enhancing portability and control for on-the-go play. Emerging economies show substantial demand for these gadgets.
- Cloud Gaming:This application streams games over the internet, necessitating low-latency input devices and stable wireless connectivity to minimize perceived lag.
- eSports:Professional competitive gaming requires ultra-low latency, durable, and highly precise peripherals, driving innovation in sensor technology and ergonomic design. South Korea leads demand for high-performance devices.
- Game Development:Developers use specialized input devices and VR equipment for creating and testing games, often requiring high-fidelity simulation tools.
The broadest user base resides in PC Gaming, while Cloud Gaming demonstrates significant growth potential by expanding access to new player demographics.
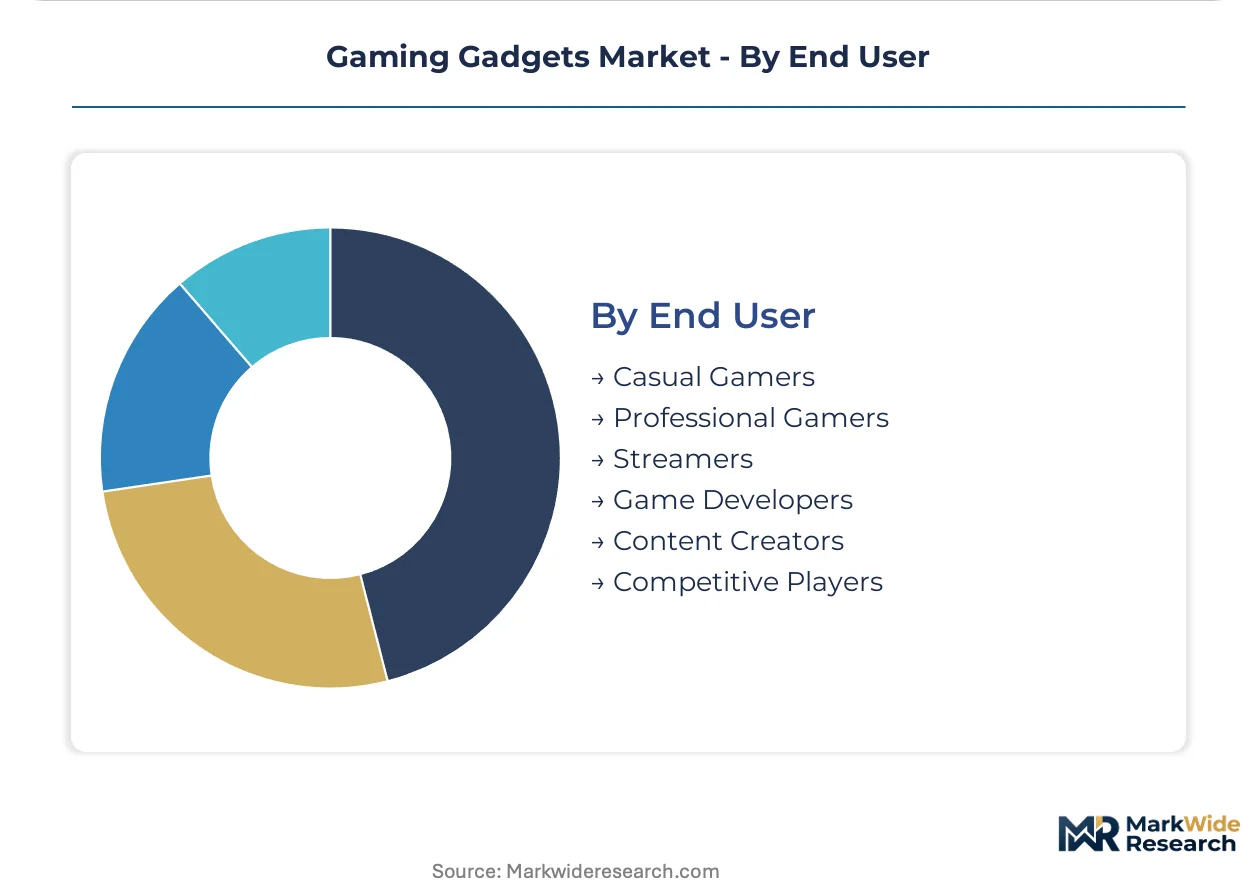
End User:
Profit margins vary significantly across end-user segments, influenced by their willingness to invest in premium features versus prioritizing cost-effectiveness and accessibility.
- Casual Gamers:This broad segment prioritizes affordability and ease of use, seeking reliable, functional gadgets for recreational play without extensive customization.
- Professional Gamers:These individuals demand peak performance, ultra-low latency, and ergonomic durability from their peripherals, often investing in top-tier equipment for competitive advantage. Their purchasing decisions influence product innovation.
- Streamers:Content creators require high-quality audio, reliable capture devices, and visually appealing peripherals to engage their audience and enhance broadcast quality. Streamers often drive trends for integrated lighting systems.
- Game Developers:This group utilizes specialized input devices and VR/AR equipment for creating and testing games, focusing on precision and compatibility with development tools.
- Content Creators:Beyond streaming, this segment includes video editors and graphic designers who use gaming peripherals for their precision and customizable controls.
- Competitive Players:Similar to professional gamers, this segment seeks every possible edge through high-performance, low-latency gear, often focusing on specific technical specifications for their chosen titles.
Demand from Professional Gamers drives the premium segment, whereas Casual Gamers represents a substantial volume segment with diverse needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized component manufacturing in Taiwan anchors the global supply chain for gaming gadgets. Demand concentration is notable in South Korea, driven by professional gaming culture and technological advancements. Europe and the United States also represent significant markets with distinct regulatory landscapes.
South Korea
Professional gaming culture and eSports professionalization drive significant demand for high-performance gaming peripherals and VR headsets. The country implements stringent national electronic safety standards for all imported and domestically produced gadgets. Seoul's tech hubs foster continuous innovation in advanced motion sensors and haptic feedback systems for next-generation devices.
United States
Console gaming and the large streamer community generate consistent demand for specialized controllers, high-end PCs, and audio peripherals. The FCC sets strict standards for wireless emissions from Bluetooth and Wi-Fi enabled gadgets. California's tech centers remain crucial for game development and the advancement of immersive VR technologies.
China
Specialized component manufacturing and a vast PC gaming user base fuel both supply and demand for gaming gadgets. GB standards ensure product quality and safety for electronic devices entering the domestic market. Shenzhen's extensive electronics manufacturing ecosystem remains central to the global supply chain for mechanical switches and optical sensors.
Germany
PC building enthusiasts and a strong eSports presence create demand for high-performance keyboards, mice, and integrated ecosystems. All electronic products must carry the CE marking, indicating compliance with health and safety standards including RoHS directives. Bavaria's engineering firms contribute to the development of precision components and advanced haptic systems.
Brazil
Government-led broadband infrastructure expansion unlocks new online gamer populations, driving demand for entry-level and mid-range gaming peripherals. The national telecommunications agency, ANATEL, regulates wireless spectrum allocation for electronic gadgets. São Paulo's growing tech adoption fosters vibrant gaming communities and increased consumer spending on accessories.
Gaming Gadgets Market Key Industry Players
Global majors compete with regional champions across product innovation and distribution networks within the gaming gadgets market. The market exhibits a tiered structure, with a segment dedicated to premium peripheral specialists and another focused on broad-spectrum distributors. Integrated ecosystem providers also carve out distinct niches, offering comprehensive solutions for PC building enthusiasts. Companies primarily engage in portfolio diversification and strategic partnerships to expand their market reach and technological capabilities.
On the premium-tier vector, Razer Inc. exemplifies a specialist in high-performance peripherals for competitive players, focusing on low-latency and ergonomic designs. This company targets users prioritizing peak performance and precision. Logitech, a global Inc., occupies a position as a broad-spectrum provider, leveraging its extensive distribution network to serve a wide range of users from casual to professional gamers. Corsair, another Inc., anchors the integrated ecosystem segment, offering components and peripherals designed for PC building enthusiasts seeking cohesive setups. These players collectively represent different strategic approaches to market penetration and customer engagement.
| Leading Market Players |
|---|
| Logitech |
| Razer Inc. |
| Corsair |
| SteelSeries |
| HyperX |
| Turtle Beach |
| Sony Corporation |
| Microsoft Corporation |
| Nintendo Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Professional gamers' demand in South Korea drives premium pricing for specialized components. This concentration allows manufacturers to maintain higher margins for advanced peripherals.
Pricing Analysis
Warranty and service bundling often differentiate premium gaming gadgets from economy models, influencing perceived value. Pricing stratifies across premium, standard, and economy tiers. Brand premium from companies like Razer and customization levels drive price differentiation in high-end peripherals. Cost compression in entry-level segments stems from intense competition and mobile gaming substitution. Casual gamers exhibit the highest price sensitivity, whereas professional gamers prioritize performance over cost.
Supply Chain Analysis
Dual-sourcing requirements for critical components are increasingly common, yet supply concentration in Taiwan and China persists for mechanical keyboard switches and optical mouse sensors. The market relies heavily on microcontrollers and wireless chips sourced from a limited number of specialized manufacturers. Component supply concentration creates significant single-source vulnerability and geopolitical risk. Distribution runs through a hybrid model, with direct-to-consumer sales gaining momentum alongside traditional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gaming gadgets market is a consolidation play, as semiconductor price volatility and complex regulatory navigation pressure smaller manufacturers. This forces weaker players to exit or seek acquisition.
For Market Incumbents: Acquire specialized haptic engineering talent to overcome the industry talent gap. Incumbents like Razer and Logitech must invest in R&D to counter mobile gaming substitution. Deepen vertical integration into component manufacturing in Taiwan or China to mitigate supply chain vulnerability. Expanding distribution networks in Latin America provides a defensive play against market saturation in mature regions.
For New Entrants and Emerging Players: Price-point gaps exist between premium eSports peripherals and entry-level gadgets for casual gamers. New entrants can target underpenetrated markets like Brazil with mid-range, feature-rich products. Focus on augmented reality integration offers a white-space opportunity for immersive gameplay beyond screen-based interaction. A direct-to-consumer sales model with influencer marketing provides an effective go-to-market angle.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to diversify portfolios into high-growth segments like VR headsets. Long-term viability hinges on companies demonstrating strong intellectual property in advanced haptic systems and low-latency wireless protocols. Target archetype: Vertically integrated mid-cap specialists with proprietary sensor technology. The signal to watch is successful navigation of complex compliance requirements, particularly CE marking and FCC standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Haptics R&D | Deepens immersion and competitive advantage for professional gamers. |
| Expand Direct-to-Consumer Channels | Enhances brand control and customer relationships for manufacturers. |
| Secure Component Supply Agreements | Mitigates supply chain vulnerability from semiconductor price volatility. |
| Pursue Augmented Reality Integration | Unlocks new immersive gameplay experiences beyond current devices. |
| Navigate Global Regulatory Compliance | Ensures market access across diverse regions like the EU and US. |
Research Approach
FCC standards, CE marking directives, and industry reports formed the secondary backbone, validated by primary interviews. Conversations with eSports professionals, peripheral manufacturers, and channel partners provided qualitative insights. This approach combined top-down market sizing with bottom-up validation from industry stakeholders.
Historical trendline analysis informed the projection horizon, capturing past growth drivers and market shifts. Segmentation dimensions modeled included product type, technology, application, end-user, and regional demand. Compound annual growth rates were derived from a multi-variant regression model. Input costs for semiconductors and broadband infrastructure expansion influenced forecast adjustments across the modeling period.
Inputs from manufacturer financial reports and regulatory filings were available through the study window; gaps in emerging market consumer spending data introduce uncertainty bands. Forecasts reflect assumptions documented regarding technological advancements and eSports professionalization. Deviation in global semiconductor supply stability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Global NFT Gaming Market
Gaming
Racing Games Market
Gaming
China Casino Tourism Market
Gaming
Gaming Simulator Market
Gaming
Mobile Gaming Market
Gaming
Global Battle Royale Games Market
Gaming
Online Casual Games Market
Gaming
Cloud Gaming Market
Gaming
Global Online Adventure Games Market
Gaming
Africa Gaming Market
Gaming
Global Online Board Games Market
Gaming
Online Casino Market
Gaming
Serious Games Market
Gaming
Southeast Asia Gaming Market
Gaming
VR Gaming Console Market
Gaming
Gaming Software Market