
 Online Casual Games Market | 2026-2036
Online Casual Games Market Size, Share, and Industry Trends Forecast 2026-2036
Online Casual Games Market Analytics
Mobile app storefronts is tilting toward algorithmic discovery and direct-to-consumer billing, reducing platform tax exposure for studios. Zynga leverages its portfolio of puzzle franchises to sustain recurring revenue through live-service content updates. Electronic Arts anchors its casual segment with mobile adaptations of established intellectual property. Epic Games competes through its storefront's lower commission structure and cross-platform account systems.
Online casual games comprise low-barrier digital entertainment products featuring short session lengths, minimal onboarding, and intuitive mechanics designed for intermittent play across smartphones, browsers, and social platforms. These titles employ lightweight client architectures, cloud-save synchronization, and adaptive difficulty algorithms to maintain engagement without dedicated hardware investment. Puzzle and card game types command the largest player bases and longest retention curves among genre categories. Mobile platforms generate the dominant share of session volume, though social media-embedded distribution is capturing incremental reach through instant-play formats that bypass traditional installation friction.
FCC oversight of in-app purchase disclosures and COPPA-mandated parental consent requirements shape monetization architecture for titles targeting younger demographics, while GDPR and emerging state-level privacy statutes in California constrain cross-border player data utilization. ESRB content descriptors and platform-holder policies further delineate permissible advertising integrations and reward-based engagement mechanics. Stakeholders must monitor evolving interoperability mandates and antitrust scrutiny of storefront commission structures that could redistribute value capture between developers and distribution gatekeepers.
Market Dynamics
Algorithmic content discovery on mobile storefronts is compressing user acquisition costs while fragmenting player attention across hyper-casual and hybrid-casual formats. This shift forces studios to prioritize live-service retention mechanics over upfront monetization.
Growth Catalysts
- GDPR-compliant first-party data frameworks:European publishers invest in consent management platforms to sustain personalized advertising revenue under tightened privacy rules.
- Instant-play distribution via social platforms:ByteDance and Meta embed cloud-streamed titles that bypass app store installation friction, expanding addressable audiences in Southeast Asia.
- Hyper-casual prototyping pipelines:Automated A/B testing tools compress development cycles, letting studios validate mechanics within 48-hour development sprints.
Market Restraints
- IDFA deprecation impact:Apple's App Tracking Transparency framework degrades attribution accuracy, inflating customer acquisition costs for iOS-first publishers.
- Supply concentration in ad tech:Meta and Google capture over 80 percent of mobile advertising inventory, creating pricing power asymmetry against mid-sized studios.
- Technical debt from rapid prototyping:Hyper-casual studios accumulate unmaintainable codebases that block pivoting to deeper monetization systems.
Strategic Opportunities
- Underpenetrated rural India:Jio's affordable data tariffs and localized payment rails unlock first-time smartphone users in tier-3 cities.
- Convergence of casual games and fintech:Play-to-earn mechanics integrated with mobile wallets create sticky engagement loops in Brazil and Nigeria.
- Regulatory tailwind from India's PLI scheme:Domestic game development incentives reduce tax exposure for studios establishing local entities.
Industry Challenges
- Live-ops talent scarcity:Economies balancing event design, data science, and community management command 40 percent salary premiums over generalist developers.
- Cross-platform certification complexity:COPPA compliance for titles with mixed-age audiences requires segregated data architectures that delay launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Casual Games Market |
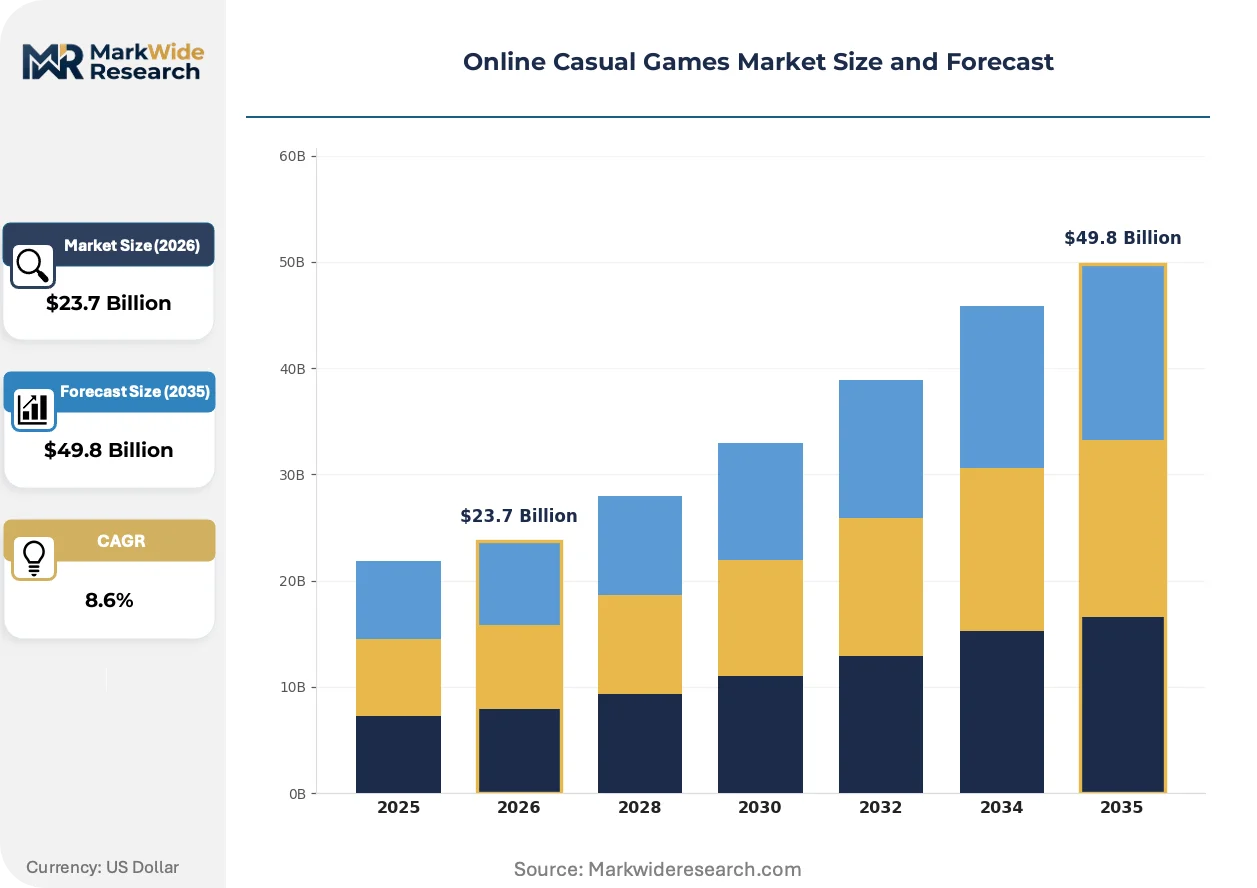
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Puzzle, Card, Arcade, Word Platform: Web-Based, Mobile, Social Media, Console Monetization Model: Freemium, Ad-Supported, Subscription, One-Time Purchase Player Demographics: Casual Gamers, Teenagers, Adults, Seniors |
| Companies Covered | Riot Games, Take-Two Interactive, Zynga, FreePlay, Chess.com, Jam City, Electronic Arts, DoubleDown Interactive, Epic Games, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Casual Games Market Evolving Landscape
Cloud-streaming infrastructure is dissolving hardware barriers while AI-generated content pipelines compress production timelines for asset-heavy genres. These forces collectively shift value capture toward distribution platforms with superior data infrastructure.
Rewarded video advertising is migrating from interruptive interstitials to opt-in engagement layers that preserve session flow. Mid-core casual studios adopt this format fastest, seeing 15-25 percent eCPM premiums over traditional placements. The structural consequence is a bifurcation between studios with sophisticated mediation stacks and those dependent on single-network waterfalls.
GDPR's enforcement arm, the CNIL in France, has imposed fines exceeding 50 million euros on ad-tech violations, forcing publishers to implement granular consent flows. The industrial consequence is a 12-18 month compliance backlog for titles with legacy data architectures. Children's titles targeting European audiences now segregate data entirely, accepting higher operational overhead for market access.
Player acquisition is fragmenting across TikTok's Spark Ads and influencer-led download campaigns, displacing Facebook's historical dominance in casual game marketing. Southeast Asian studios lead this pivot, allocating 60 percent of UA budgets to short-form video channels. The geographic concentration reflects younger demographics and lower CPMs in Indonesia, Vietnam, and the Philippines compared to saturated North American markets.
Online Casual Games Market Segmentation
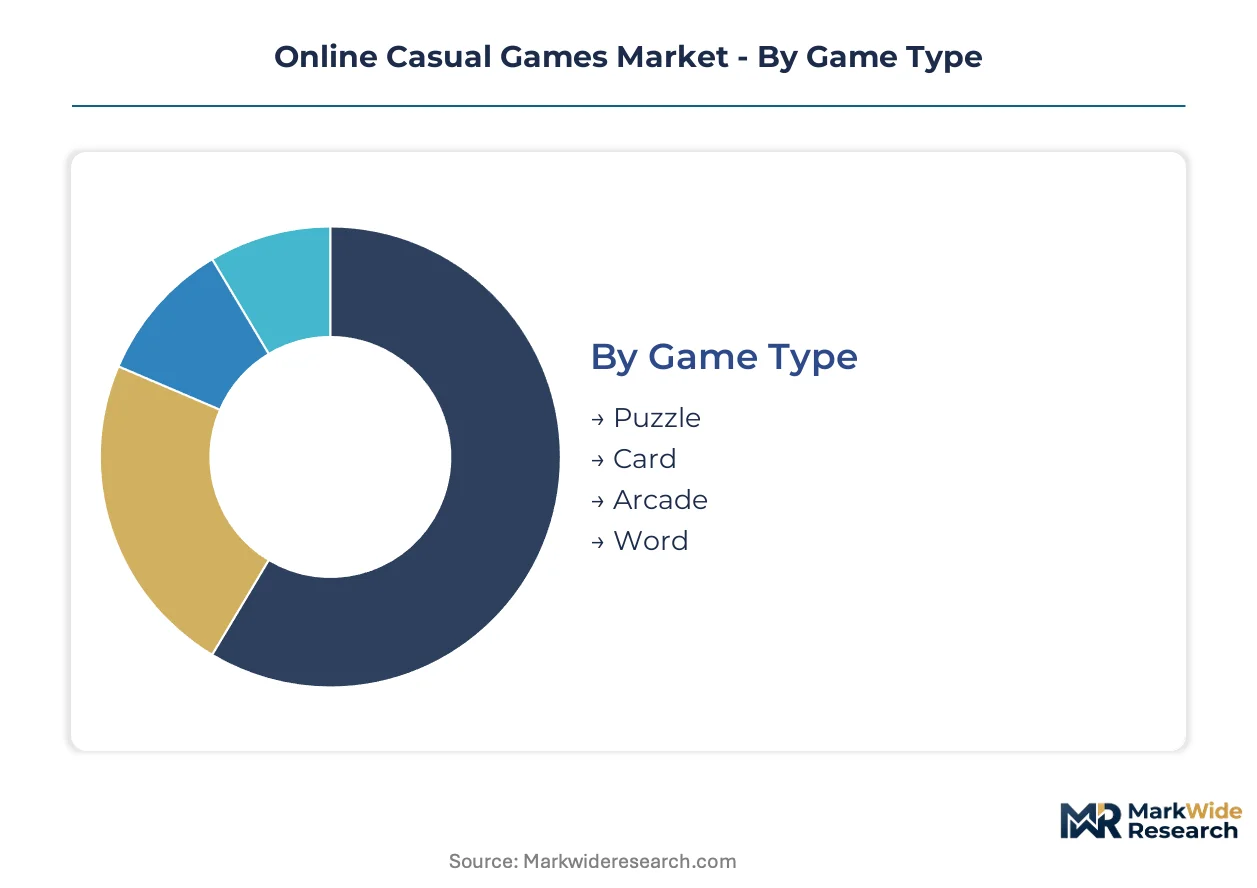
Segmentation in the online casual games market reveals divergent development cycles and monetization physics across game types, platforms, and audience cohorts. Studios optimize portfolio allocation by matching live-service infrastructure to segment-specific retention curves and session patterns.
Game Type:
Puzzle titles turn over content fastest with weekly level drops, while card games sustain multi-year engagement arcs through social competition layers.
- Puzzle:Match-3 and logic variants dominate session volume through algorithmically generated level progressions. Demand concentrates among working-age commuters in Japan and South Korea seeking sub-three-minute play loops. GDPR-compliant data architectures constrain personalized difficulty tuning in European deployments.
- Card:Solitaire and collectible variants anchor the longest retention curves through daily reward streaks and tournament structures. Senior demographics in the United States and Germany generate disproportionate revenue per user via subscription conversions.
- Arcade:Reflex-based mechanics attract hyper-casual prototyping studios validating concepts through 48-hour development sprints.
- Word:Crossword and anagram formats leverage existing cultural literacy without localization barriers, expanding fastest in India and Nigeria.
Puzzle anchors the volume base while Word gains share at the steepest rate.
Platform:
Development cost tiers stratify sharply, with social media instant-play formats requiring fractional engineering investment versus console certification overhead.
- Mobile:Native iOS and Android clients capture dominant session share through push-notification re-engagement and wallet-integrated billing. Southeast Asian studios in Indonesia and Vietnam prioritize this channel for its lower customer acquisition costs versus saturated North American markets.
- Web-Based:Browser-based HTML5 architectures bypass storefront commissions entirely, appealing to mid-sized publishers in Brazil seeking margin preservation. Technical constraints on asset fidelity limit genre suitability to puzzle and word categories.
- Social Media:ByteDance and Meta's cloud-streamed embeds eliminate installation friction, expanding fastest among first-time smartphone users in rural India.
- Console:Nintendo Switch and PlayStation adaptations command premium pricing but require COPPA-compliant segregated data architectures that extend launch timelines.
Mobile anchors the volume base while Social Media climbs the fastest.
Monetization Model:
Revenue predictability increases with customer commitment depth, from volatile ad-supported yields to locked-in subscription streams.
- Freemium:Hybrid models combining free base access with cosmetic and progression purchases generate the highest revenue concentration among puzzle and card titles. Apple's App Tracking Transparency framework degrades attribution accuracy for iOS-first publishers, inflating acquisition costs.
- Ad-Supported:Rewarded video placements preserve session flow better than interstitials, commanding eCPM premiums of 15-25 percent for mid-core casual studios with sophisticated mediation stacks.
- Subscription:Apple Arcade and Google Play Pass bundles provide revenue floor guarantees that attract narrative-driven word game developers seeking funding stability.
- One-Time Purchase:Premium pricing without ongoing monetization survives only in console-adjacent ports where intellectual property recognition justifies upfront outlays.
Freemium anchors the volume base while Subscription expands most quickly.
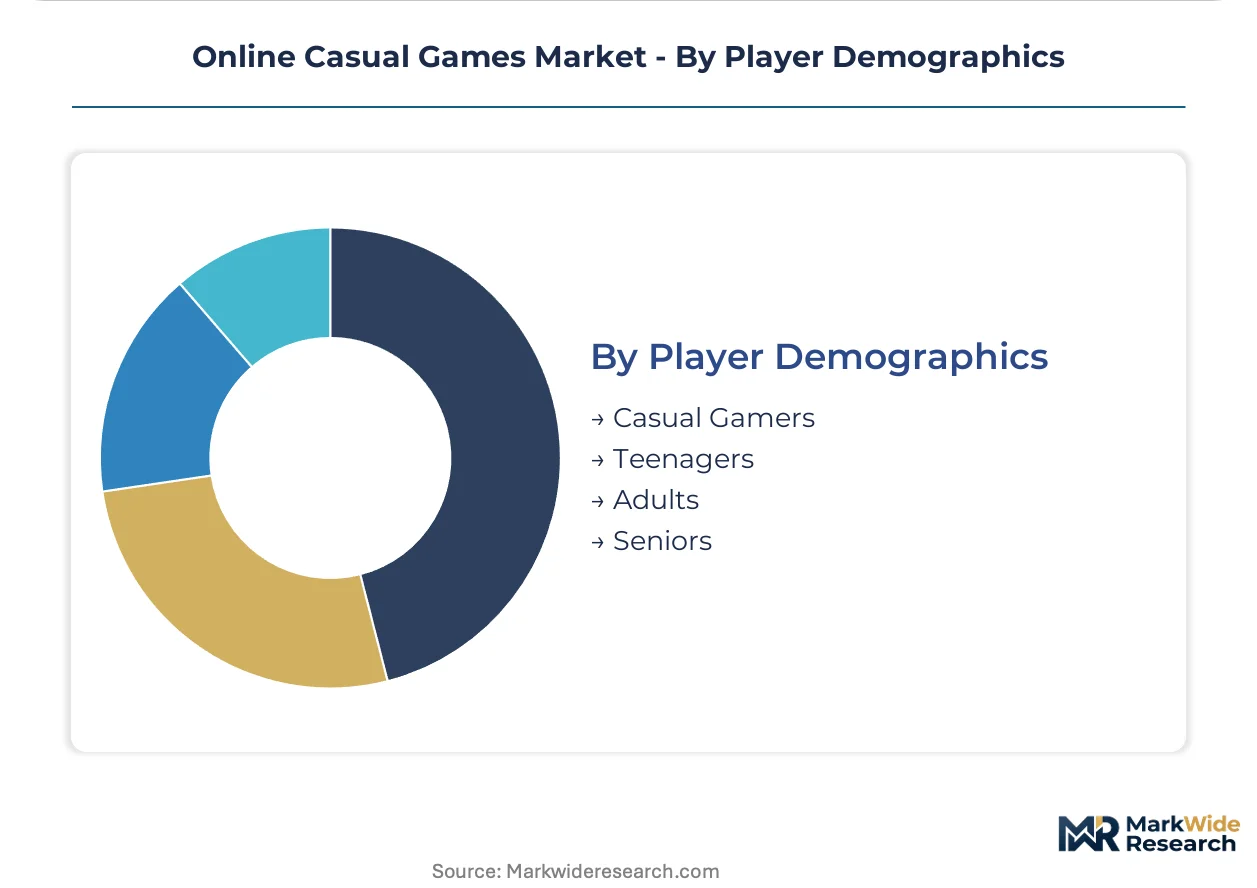
Player Demographics:
Monetization maturity varies by age cohort, with teenagers generating volume but adults converting revenue at superior rates.
- Casual Gamers:The broad non-identifying segment encompasses intermittent players across all age brackets, representing the default addressable audience for hyper-casual publishers.
- Teenagers:TikTok-native acquisition channels and influencer-led campaigns dominate reach, with COPPA-mandated parental consent requirements shaping monetization architecture for titles targeting this cohort.
- Adults:Working-age players aged 25-45 deliver the highest lifetime value through consistent in-app purchase velocity and subscription tolerance.
- Seniors:Card and word game concentration among players over 55 generates stable revenue with lower churn, particularly in Germany and Japan where tablet penetration exceeds smartphone preference.
Adults anchors the volume base while Seniors gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC oversight of in-app purchase disclosures anchors the United States as the regulatory benchmark shaping monetization architectures worldwide. Studios navigate COPPA-mandated parental consent requirements and GDPR's extraterritorial reach while targeting divergent demographic clusters across national markets.
United States
Working-age commuters in New York and Los Angeles generate concentrated session volume during transit intervals, driving demand for sub-three-minute puzzle loops. COPPA enforcement by the FTC constrains data collection for titles targeting mixed-age audiences, forcing segregated server architectures. Austin and San Francisco host the largest concentration of live-ops talent, with studios competing for event designers and data scientists at 40 percent salary premiums.
China
MIIT licensing requirements for game publication create extended approval timelines that filter market entrants and concentrate revenue among established publishers. ByteDance's TikTok-native distribution channels capture growing share of player acquisition budgets, displacing traditional storefront dependence. Shenzhen and Hangzhou anchor development clusters where hyper-casual prototyping pipelines compress concept validation to 48-hour sprints.
Japan
METI's oversight of consumer protection in digital commerce shapes disclosure standards for gacha-style monetization mechanics prevalent in card game variants. Senior demographics in Tokyo and Osaka demonstrate superior subscription conversion rates and lower churn compared to younger cohorts. Kyoto-based studios specialize in narrative-driven word games that leverage cultural literacy without localization barriers.
Germany
GDPR enforcement by the KBA and LfDI authorities imposes granular consent flows that extend compliance backlogs to 12-18 months for legacy data architectures. Berlin and Hamburg concentrate mid-sized publishers investing in first-party data frameworks to sustain personalized advertising revenue. Munich hosts the largest European cluster of puzzle game specialists optimizing algorithmic difficulty tuning under tightened privacy constraints.
Brazil
ANVISA's limited direct jurisdiction over digital entertainment creates regulatory clarity that attracts publishers seeking margin preservation through web-based HTML5 distribution. São Paulo and Rio de Janeiro anchor development activity where convergence of casual games and fintech creates sticky engagement loops integrated with mobile wallets. Play-to-earn mechanics gain traction among first-time smartphone users in tier-3 cities accessing affordable data tariffs.
Online Casual Games Market Competitive Landscape
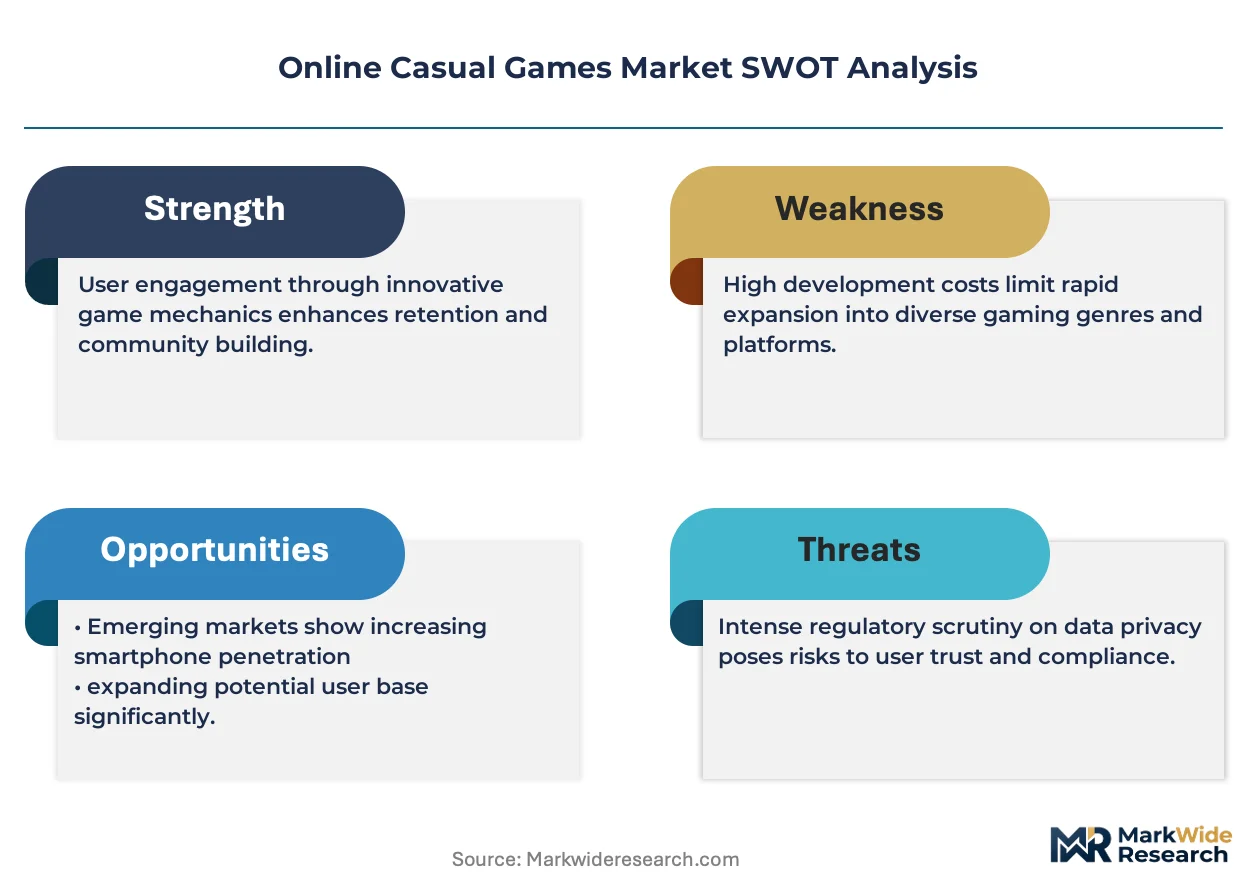
Portfolio-heavy conglomerates and specialized casual studios split the market between recurring revenue optimization and rapid concept validation. Consolidation pressure concentrates value capture among entities with proprietary distribution channels and live-service infrastructure. Three archetypes dominate: IP-anchored publishers leveraging transmedia recognition, algorithmic discovery specialists optimizing for storefront placement, and hyper-casual factories running automated A/B testing pipelines. Competitive moves center on M&A absorption of proven franchises and direct-to-consumer billing systems that reduce platform tax exposure.
Within the IP-anchored tier, Electronic Arts and Take-Two Interactive exemplify publishers extending console and PC recognition into mobile casual adaptations. Zynga occupies a position between conglomerate scale and casual specialization, representing the puzzle-centric live-service archetype with sustained content update cadences. Epic Games anchors the platform-competitor archetype, leveraging storefront commission structures and cross-platform account systems to attract studio distribution outside dominant mobile app stores.
| Leading Market Players |
|---|
| Riot Games |
| Take-Two Interactive |
| Zynga |
| FreePlay |
| Chess.com |
| Jam City |
| Electronic Arts |
| DoubleDown Interactive |
| Epic Games |
| Others |
Value Network & Pricing Analysis
Undercapacity in Southeast Asian live-ops talent pools drives simultaneous wage inflation and project delays, compressing studio margins while forcing pricing adjustments in outsourced development services. This utilization squeeze cascades into publisher procurement decisions, tilting contract structures toward revenue-sharing rather than fixed-fee arrangements.
Pricing Analysis
Geographic price spreads separate North American live-ops talent premiums from Southeast Asian engineering arbitrage. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and platform-holder partnership status. Price differentiation hinges on GDPR-compliant data architecture maturity and proprietary mediation stack sophistication. Pricing pressure stems from IDFA deprecation degrading attribution accuracy and inflating customer acquisition costs. Hyper-casual studios exhibit highest price sensitivity due to volatile ad-supported yields, while card game specialists with subscription bases demonstrate lowest sensitivity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for studios with cross-border publishing operations. Development capacity concentrates in Vietnam, Indonesia, and India where Jio's data tariffs and localized payment rails expand addressable audiences. Raw material dependencies center on cloud infrastructure from AWS, Azure, and Google Cloud Platform alongside ad-tech inventory from Meta and Google. Single-source vulnerability in mobile advertising inventory creates pricing power asymmetry against mid-sized studios. Distribution runs through mobile app storefronts, social media instant-play embeds, and direct-to-consumer web channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect around storefront commission structures and cross-platform account interoperability, with Epic Games' lower-rate model and unified login systems forcing competitive recalibration across distribution channels.
For Market Incumbents: Insulate recurring revenue streams by deepening first-party data frameworks under GDPR-compliant consent architectures, countering IDFA deprecation impacts. Acquire live-ops talent clusters in Austin and Berlin to offset 40 percent salary premiums. Prioritize direct-to-consumer billing systems that reduce platform tax exposure. For New Entrants and Emerging Players: Pursue underpenetrated rural India where Jio's affordable data tariffs unlock first-time smartphone users in tier-3 cities. Target Brazil's fintech-casual convergence for play-to-earn mechanics integrated with mobile wallets. Deploy TikTok-native influencer campaigns as primary go-to-market channel. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cloud-streaming infrastructure and AI-generated content pipelines. Long-term viability favors studios with proprietary distribution channels and live-service infrastructure over hyper-casual prototyping factories. Target acquisition archetype: mid-sized publishers with GDPR-compliant data architectures and proven retention curves. Monitor regulatory scrutiny of storefront commission structures as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Billing Launch | Reduces Apple and Google platform tax exposure while capturing customer relationship data. |
| Live-Ops Talent Cluster Acquisition | Secures scarce event designers and data scientists commanding salary premiums in Austin and Berlin. |
| GDPR-Compliant Consent Platform | Enables sustained personalized advertising revenue under CNIL and KBA enforcement timelines. |
| Cloud-Streaming Infrastructure Partnership | Dissolves hardware barriers for ByteDance and Meta instant-play distribution in rural India. |
| Hyper-Casual Prototyping Pipeline | Compresses concept validation to 48-hour sprints through automated A/B testing tools. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with mobile game studio CEOs, live-ops directors, platform partnership leads, and ad-tech mediation specialists. Secondary validation drew from SEC filings of publicly traded publishers, Sensor Tower mobile intelligence data, App Annie session metrics, and GDPR enforcement disclosures from CNIL and KBA. Bottom-up triangulation across individual title performance combined with top-down market sizing anchored the analysis.
Calibration against historical CAGRs and installed base penetration curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include game type, platform architecture, monetization model, and player demographic cohort. CAGRs derived from trend extrapolation and technology diffusion patterns. Forecast inputs incorporated IDFA deprecation impact trajectories and cloud-streaming infrastructure deployment timelines.
Macroeconomic conditions sit as an overlay; deviation in smartphone penetration rates, data tariff pricing, or advertising CPMs would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and platform policy stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Game API Market
Gaming
Global Electronic Table Games (ETG) Market
Gaming
Asia-Pacific Casino Gambling Market
Gaming
Gaming Gadgets Market
Gaming
Global Game Testing Service Market
Gaming
Global Casino and Gaming Market
Gaming
Global Esports Market
Gaming
Africa Gaming Market
Gaming
China Casino Tourism Market
Gaming
Connected Game Console Market
Gaming
Latin America Mobile Gaming Market
Gaming
Global Trading Card Games Market
Gaming
Traditional Casual Games Market
Gaming
Board Games Market
Gaming
Mobile Game Software Market
Gaming
United States Gaming Market