
 Southeast Asia Gaming Market | 2026-2036
Southeast Asia Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Gaming Market Outlook
Capital-intensity divergence between cloud infrastructure deployers and asset-light mobile publishers is bifurcating competitive trajectories across the region. Garena leverages its Singapore-based server architecture to sustain low-latency multiplayer experiences across six ASEAN markets. Tencent anchors regional distribution through localized publishing partnerships, while Nintendo differentiates via first-party intellectual property that commands premium hardware attach rates.
Southeast Asia Gaming encompasses interactive software and hardware systems designed for entertainment, competition, and social engagement through real-time rendering engines, touch interfaces, and networked multiplayer protocols operating on devices ranging from sub-$100 smartphones to dedicated GPU clusters. Mobile platforms dominate addressable reach given smartphone penetration exceeding fixed broadband in rural Philippines and Indonesian archipelago markets. Free-to-Play monetization captures the largest player base while in-app purchase mechanics concentrate revenue extraction among competitive gamers and esports participants seeking cosmetic differentiation and progression acceleration.
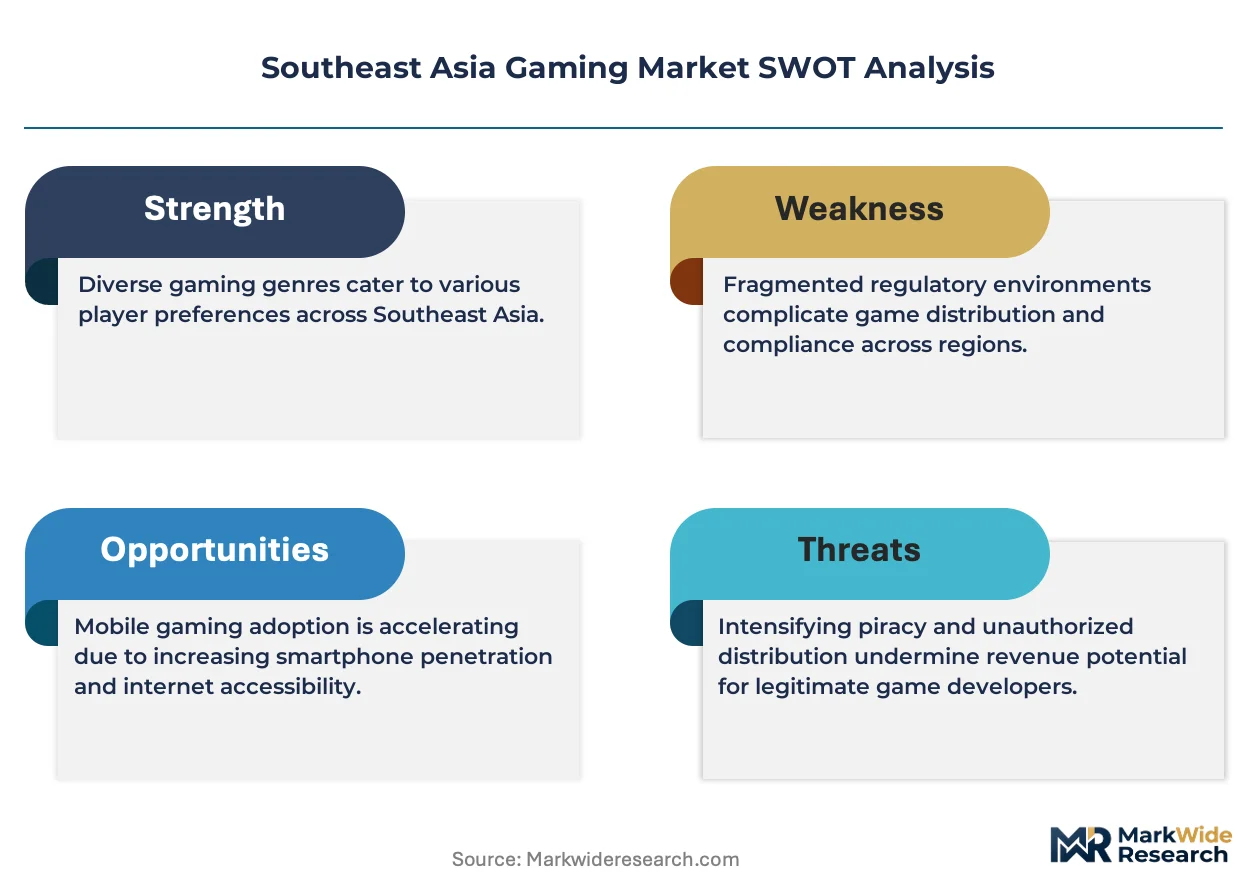
Indonesia's Ministry of Communication and Informatics content rating system, Thailand's Film and Video Act enforcement by the NBTC, and Vietnam's GVN licensing requirements collectively elevate compliance barriers for foreign publishers seeking market access. These frameworks shape product localization timelines, age-gating mechanics, and revenue recognition patterns. Stakeholders must monitor evolving data sovereignty mandates and esports betting regulations that could redraw permissible monetization architectures.
Market Dynamics
Data localization mandates and TRAI-style content rating frameworks across ASEAN states are bifurcating publisher compliance architectures, forcing foreign operators to establish domestic server infrastructure and localized rating systems or cede market access to regional competitors.
Growth Catalysts
- Smartphone penetration:Sub-$100 device availability across rural Philippines and Indonesian archipelago markets expands addressable player bases beyond fixed broadband constraints.
- Indonesia's content rating system:The Ministry of Communication and Informatics framework creates regulatory clarity that accelerates foreign publisher entry timelines versus ambiguous enforcement environments.
- Mobile esports tournament infrastructure:Competitive gaming circuits in Thailand and Vietnam concentrate high-value player segments and accelerate in-app purchase velocity among cosmetics-seeking participants.
Market Restraints
- Server infrastructure capex:GVN licensing requirements and data sovereignty mandates in Vietnam force publishers to deploy domestic GPU clusters rather than leverage regional cloud arbitrage.
- Content localization timelines:Thailand's NBTC Film and Video Act enforcement creates age-gating engineering requirements that extend product launch windows by 4-8 months versus unregulated markets.
- Payment rail fragmentation:Indonesia's Java corridor concentrates e-wallet adoption while Philippine rural markets remain cash-preferred, complicating unified monetization architecture deployment.
Strategic Opportunities
- Java corridor studio density:Indonesia's concentrated game development talent pool offers acquisition targets for publishers seeking in-house live-ops capabilities.
- Esports betting regulatory evolution:Thailand and Vietnam legislative frameworks may permit skill-based wagering mechanics that unlock new revenue architectures prohibited in mature Asian markets.
- Cloud-edge hybrid infrastructure:Convergence of 5G rollout and Singapore-based server architecture enables sub-50ms latency experiences previously requiring dedicated hardware.
Industry Challenges
- Live-streaming talent scarcity:Vietnam and Philippines markets face acute shortages of bilingual content creators capable of cross-border audience aggregation.
- Multi-jurisdiction compliance engineering:Simultaneous adherence to Indonesia's rating system, Thailand's NBTC enforcement, and Vietnam's GVN requirements fragments QA and legal resourcing.
- Legacy hardware support obligations:Extended Android 8-10 device penetration in rural Indonesian markets constrains engine upgrade cycles and feature parity across player segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Gaming Market |
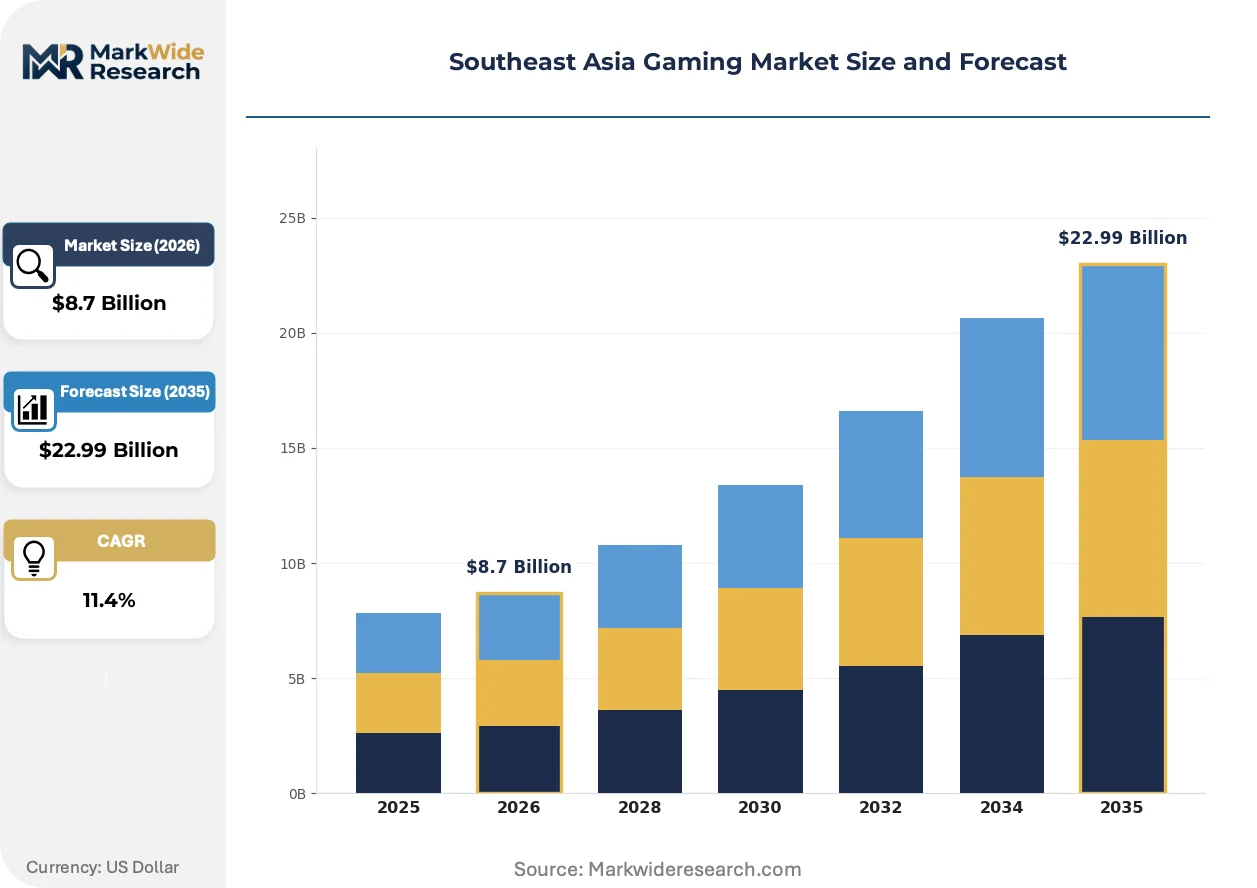
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform: Mobile, PC, Console, Cloud Gaming Game Type: Action, RPG, Sports, Strategy Monetization Model: Free-to-Play, Subscription, Pay-to-Play, In-App Purchases End User: Casual Gamers, Competitive Gamers, Esports Players, Streamers |
| Companies Covered | IGG Inc., Asiasoft Corporation Public Company Limited, Garena, NCSoft, Com2uS Holdings Corporation, Tencent, Nintendo Co., Ltd., Sony Group Corporation, NetEase Games, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Gaming Market Strategic Shifts
Real-time rendering pipelines and touch-native control schemes are compressing development cycles while regulatory fragmentation forces architectural specialization rather than regional platform standardization.
Edge computing nodes deployed across Jakarta, Bangkok, and Ho Chi Minh City are miniaturizing multiplayer latency to sub-30ms thresholds previously achievable only through Singapore hub-and-spoke topology. Indonesian mobile publishers with Java corridor server access now deliver competitive FPS experiences on sub-$100 smartphones. This infrastructure democratization is compressing the performance gap between premium and mass-market device tiers.
Thailand's NBTC has intensified Film and Video Act enforcement against unlicensed game distribution, creating compliance moats that favor established publishers with localized legal infrastructure. Foreign operators without Bangkok-based regulatory affairs teams face extended review queues. Mobile esports titles with real-money tournament mechanics attract disproportionate scrutiny, forcing product architecture pivots toward cosmetic-only monetization in that jurisdiction.
Player acquisition economics in Vietnam have inverted as GVN licensing requirements filter out speculative publishers, concentrating marketing spend among compliant operators. Vietnamese gamers now exhibit higher lifetime value profiles due to reduced competitive clutter in official distribution channels. This buyer concentration rewards patient capital deployment over rapid user accumulation strategies dominant in unregulated emerging markets.
Southeast Asia Gaming Market Segmentation
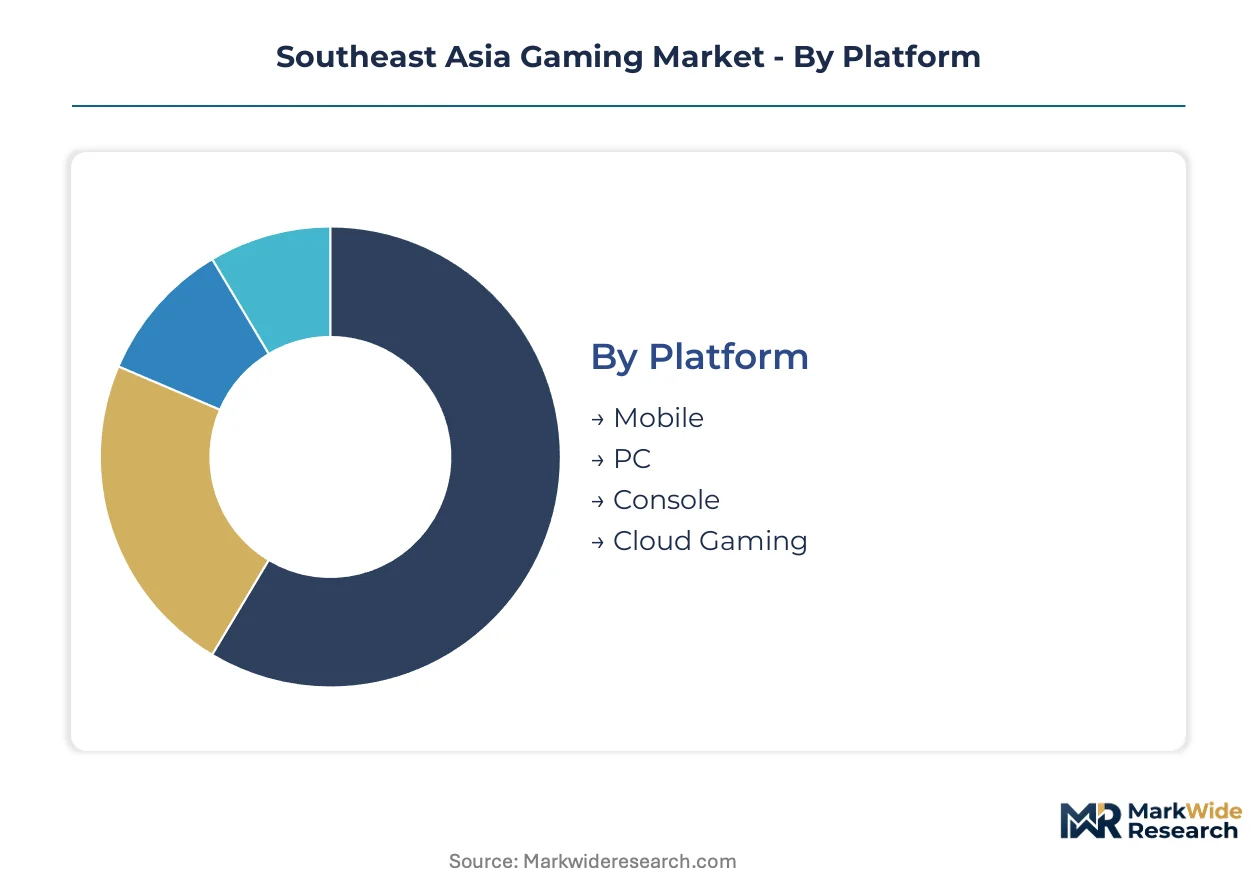
Platform diversity across Southeast Asia creates divergent monetization physics. Smartphone ubiquity in Indonesian archipelago markets contrasts with console concentration in Thai urban centers, forcing publishers to architect separate go-to-market strategies per hardware tier.
Platform:
Mobile platforms dominate domestic consumption across rural Philippines and Indonesian outer islands where fixed broadband remains sparse. PC and console segments concentrate in export-led tournament infrastructure and Singapore-based regional hub operations.
- Mobile:Touch-native control schemes and sub-$100 Android device penetration enable mass-market reach across Java corridor and Philippine rural markets. Indonesian Ministry of Communication and Informatics content rating compliance accelerates foreign publisher entry timelines versus ambiguous enforcement environments. Competitive esports circuits in Thailand and Vietnam concentrate high-value player segments and accelerate in-app purchase velocity among cosmetics-seeking participants.
- PC:GPU-dependent rendering pipelines and mechanical keyboard peripheral ecosystems anchor competitive FPS and MOBA experiences. Vietnamese GVN licensing requirements filter speculative publishers, concentrating marketing spend among compliant operators and elevating player lifetime value profiles through reduced channel clutter.
- Console:Dedicated hardware attach rates concentrate in Thai and Malaysian urban households with disposable income for premium first-party intellectual property. Nintendo's regional distribution partnerships leverage localized retail presence.
- Cloud Gaming:Edge computing nodes across Jakarta, Bangkok, and Ho Chi Minh City compress latency to sub-30ms thresholds, democratizing high-fidelity experiences on mass-market devices without dedicated GPU investment.
Mobile commands the established base. The steepest expansion runs through Cloud Gaming.
Game Type:
Development cost tiers stratify across engine complexity and live-ops infrastructure requirements. Action and RPG categories demand sustained content pipelines, while Sports and Strategy segments leverage licensed IP and asynchronous multiplayer architectures.
- Action:Real-time rendering engines and precision input mechanics dominate mobile esports tournament circuits across Indonesia and Vietnam. Thailand's NBTC Film and Video Act enforcement creates age-gating engineering requirements that extend product launch windows.
- RPG:Progression systems and gacha monetization mechanics extract revenue from narrative-driven player investment. Indonesian Java corridor studio density offers acquisition targets for publishers seeking in-house live-ops capabilities.
- Sports:Licensed athlete and league intellectual property commands premium positioning in Thai and Malaysian markets with established football viewership culture.
- Strategy:Asynchronous multiplayer protocols reduce server infrastructure capex burdens while sustaining engagement through clan-based social mechanics.
Action titles anchor current revenue concentration. RPG mechanics are gaining share fastest through gacha monetization maturation.
Monetization Model:
Payment rail fragmentation across ASEAN states complicates unified architecture deployment. Indonesia's Java corridor e-wallet density contrasts with Philippine cash-preferred rural markets, forcing geographic customization.
- Free-to-Play:Zero-entry-cost distribution maximizes addressable reach across sub-$100 smartphone penetration in rural Philippines and Indonesian archipelago markets. Cosmetic-only monetization pivots satisfy Thailand's NBTC scrutiny of real-money tournament mechanics.
- In-App Purchases:Battle pass and gacha systems concentrate revenue extraction among competitive gamers seeking progression acceleration. Vietnamese official distribution channels reward patient capital deployment over rapid user accumulation.
- Subscription:Recurring revenue models concentrate in Singapore and Malaysian urban markets with credit card penetration and cloud gaming service adoption.
- Pay-to-Play:Upfront purchase mechanics retain niche positioning for premium narrative experiences and remastered console intellectual property.
Free-to-Play sustains the volume base. In-App Purchases deliver the steepest revenue trajectory.
End User:
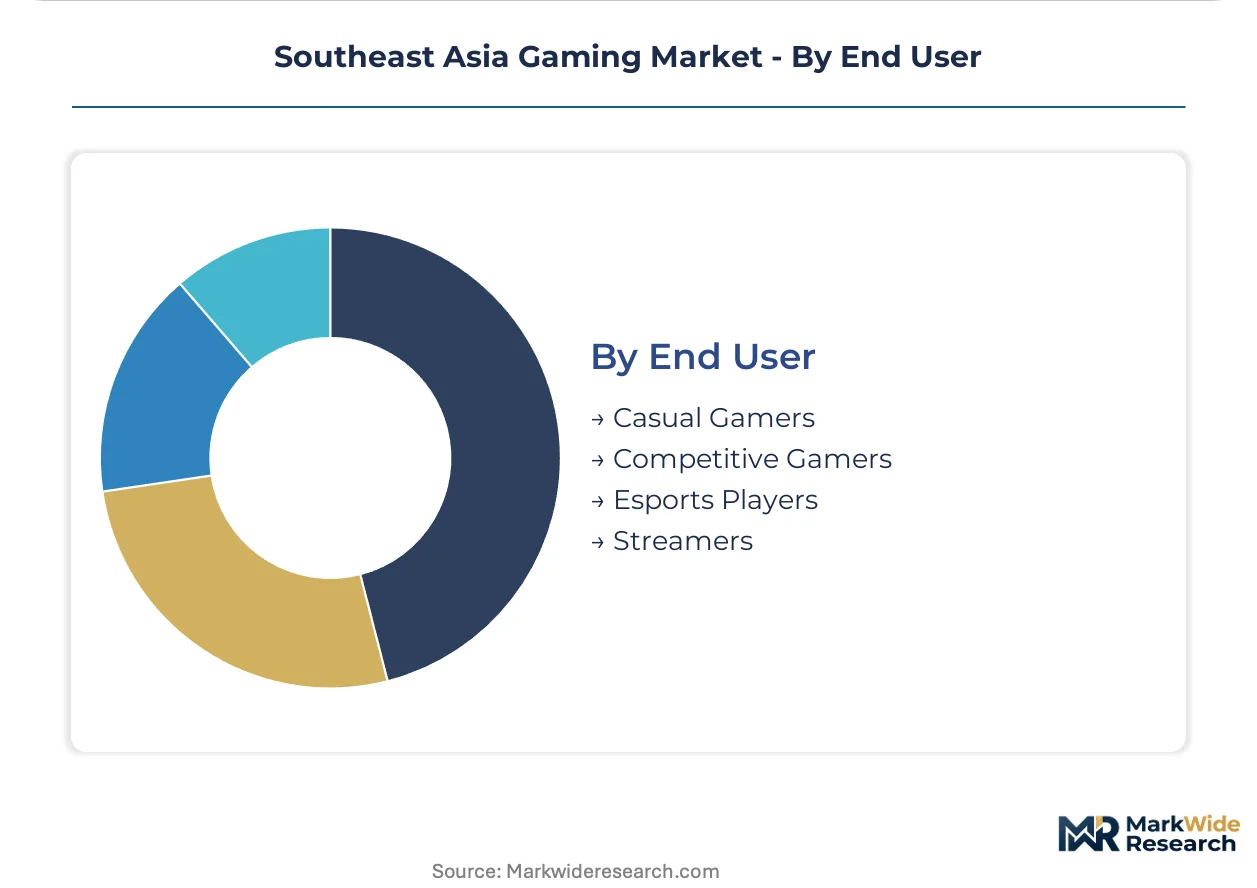
Customer maturity and spending velocity diverge across casual mass-market engagement versus competitive high-intensity segments. Live-streaming talent scarcity in Vietnam and Philippines constrains cross-border audience aggregation for creator-dependent monetization.
- Casual Gamers:Fragmented session patterns and low monetization conversion dominate sub-$100 device penetration across rural Indonesian and Philippine markets. Extended Android 8-10 device support obligations constrain engine upgrade cycles.
- Competitive Gamers:Ranked ladder participation and tournament entry fees concentrate in Thailand and Vietnam mobile esports infrastructure. GVN licensing requirements elevate compliance barriers that filter speculative publishers.
- Esports Players:Professional circuit participation and team sponsorships anchor Singapore-based server architecture investments for sub-50ms latency requirements.
- Streamers:Bilingual content creator scarcity across Vietnam and Philippines limits cross-border audience aggregation and influencer marketing efficiency.
Casual Gamers represent the installed base. Competitive Gamers show the fastest expansion through tournament infrastructure maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Southeast Asia. Indonesian and Philippine rural markets exhibit extreme price sensitivity on sub-$100 smartphones. Singapore and Thai urban centers absorb premium hardware and subscription services with minimal volume contraction.
Indonesia
Smartphone-first consumption dominates across the Java corridor and outer archipelago islands where fixed broadband remains sparse. The Ministry of Communication and Informatics content rating system accelerates foreign publisher entry timelines through regulatory clarity. Jakarta and Bandung concentrate the region's highest density of game development studios and live-streaming talent pools.
Thailand
Console attach rates concentrate in Bangkok and Chiang Mai urban households with disposable income for premium first-party intellectual property. The NBTC intensifies Film and Video Act enforcement against unlicensed distribution, creating compliance moats favoring established publishers. Mobile esports tournament infrastructure in Bangkok draws millions of competitive gamers and accelerates in-app purchase velocity.
Vietnam
GVN licensing requirements filter speculative publishers, concentrating marketing spend among compliant operators and elevating player lifetime value profiles. Ho Chi Minh City anchors edge computing node deployment that compresses multiplayer latency to sub-30ms thresholds. The official distribution channel concentration rewards patient capital deployment over rapid user accumulation strategies.
Singapore
Cloud gaming service adoption and credit card penetration support recurring revenue models unavailable in cash-preferred neighboring markets. Singapore-based server architecture enables Garena to sustain low-latency multiplayer experiences across six ASEAN markets. The city-state functions as regional hub for regulatory affairs teams managing multi-jurisdiction compliance engineering.
Philippines
Extended Android 8-10 device penetration in rural markets constrains engine upgrade cycles and forces legacy hardware support obligations. Cash-preferred payment rails in provincial areas complicate unified monetization architecture deployment. Manila and Cebu City concentrate bilingual live-streaming talent capable of cross-border audience aggregation.
Southeast Asia Gaming Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Southeast Asia Gaming Market. Mobile-first publishers with asset-light distribution models capture mass-market volume while cloud infrastructure deployers absorb capital-intensive server capex burdens. Three archetypes dominate: regional platform operators with localized compliance infrastructure, global IP holders with premium hardware attach strategies, and mobile specialists with Java corridor live-ops capabilities. Competitive moves concentrate on acquisition of Indonesian studio talent and edge computing node deployment across Jakarta, Bangkok, and Ho Chi Minh City.
Within the regional platform operator tier, Garena and Tencent exemplify divergent approaches to ASEAN market access. Garena anchors its position through Singapore-based server architecture that sustains low-latency multiplayer across six markets. Tencent occupies a position reliant on localized publishing partnerships rather than owned infrastructure. Among Korean and Japanese IP holders, NCSoft and Nintendo Co., Ltd. represent contrasting hardware strategies—NCSoft within PC and mobile competitive ecosystems, Nintendo through premium console attach rates in Thai and Malaysian urban centers.
| Leading Market Players |
|---|
| IGG Inc. |
| Asiasoft Corporation Public Company Limited |
| Garena |
| NCSoft |
| Com2uS Holdings Corporation |
| Tencent |
| Nintendo Co., Ltd. |
| Sony Group Corporation |
| NetEase Games |
| Others |
Value Chain & Pricing Dynamics
Long-term server capacity reservation contracts with Singapore-based cloud operators lock in both GPU cluster access and predictable per-hour compute pricing for publishers serving six ASEAN markets. These arrangements insulate compliant operators from spot-market volatility while forcing speculative entrants into higher-cost domestic infrastructure deployment.
Pricing Analysis
After-sales live-ops revenue through battle pass renewals and seasonal cosmetic drops drives lifetime value for established mobile publishers. Three-tier pricing structure across premium, standard, and economy levels segments Indonesian e-wallet users from Philippine cash-preferring rural markets. Price differentiation hinges on localization depth and server latency guarantees. Cost compression in mass-market tiers is intensifying because legacy Android 8-10 support obligations extend engineering overhead. Competitive gamers in Thailand and Vietnam show least price sensitivity; casual players across Indonesian outer islands exhibit extreme elasticity.
Supply Chain Analysis
Singapore and Indonesia anchor regional server infrastructure deployment, while Vietnam and Thailand concentrate edge computing node manufacturing partnerships. GPU silicon draws from Taiwan fabrication and South Korea memory packaging. Single-source vulnerability in advanced node availability threatens domestic cluster expansion timelines. Distribution runs through Jakarta and Bangkok-based publisher operations with localized compliance teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud gaming streaming services pose imminent substitution pressure against hardware-dependent console attach models, forcing incumbents to defend platform loyalty through exclusive content pipelines.
For Market Incumbents: Shield market position by deepening Java corridor studio acquisitions to capture live-ops talent scarcity, while accelerating edge node deployment across Ho Chi Minh City and Bangkok to sustain sub-30ms latency guarantees against cloud-native entrants. Regulatory compliance infrastructure in Indonesia's Ministry of Communication and Informatics framework serves as the priority defensive moat. For New Entrants and Emerging Players: Anchor in Philippine rural markets where cash-preferred payment rails and extended Android legacy device penetration have deterred capital-intensive publishers. Target bilingual streamer acquisition in Manila and Cebu City to unlock cross-border audience aggregation. Partner with Indonesian e-wallet operators to bypass fragmented bank infrastructure. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors compliant operators with GVN licensing and NBTC enforcement track records. Long-term viability centers on patient capital deployment into Vietnamese official distribution channels where filtered competition elevates player lifetime value. Watch for esports betting regulatory liberalization in Thailand as inflection signal for skill-based wagering revenue architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Java Corridor Studio Acquisition | Captures concentrated live-ops talent and accelerates in-house content pipeline development. |
| Edge Computing Node Deployment | Ho Chi Minh City and Bangkok installations compress latency below console-equivalent thresholds. |
| GVN Licensing Compliance Investment | Vietnam's regulatory filter rewards compliant operators with reduced marketing competitive clutter. |
| Cross-Border Streamer Network Buildout | Manila and Cebu City bilingual talent unlocks Philippines-Vietnam audience aggregation efficiency. |
| E-Wallet Payment Rail Integration | Indonesia's Java corridor digital payment density enables unified monetization architecture deployment. |
Study Parameters
Operator-level perspectives from game development studio heads, regulatory affairs leads at multinational publishers, esports tournament operators, and cloud infrastructure procurement officers anchored the qualitative base. These inputs combined with secondary validation against GVN licensing databases, NBTC enforcement records, Indonesian Ministry of Communication and Informatics content rating registries, and Singapore data center capacity disclosures. Bottom-up smartphone penetration models and top-down addressable market estimates underwent triangulation.
Sensitivity analysis tested forecast robustness across alternative regulatory enforcement scenarios and 5G rollout pace assumptions over the projection horizon. The analytical framework segmented by platform, game type, monetization model, and end user archetype across country-specific adoption curves. CAGRs derived from installed base growth, average revenue per user maturation, and premium tier penetration trajectories. Cloud gaming service adoption curves and esports tournament prize pool expansion served as industry-specific demand inputs.
Decision-makers should treat outputs as directional under sustained data localization mandate enforcement and stable smartphone subsidy policies; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in ASEAN regulatory harmonization and edge infrastructure deployment milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Europe Serious Gaming Market
Gaming
Australia Gaming Gadgets Market
Gaming
Germany Gaming Headset Market
Gaming
VR Gaming Accessories Market
Gaming
Global Online Gambling and Betting Market
Gaming
Cloud Gaming Market
Gaming
Virtual Sports Market
Gaming
Video Game Software Market
Gaming
South Korea Subscription-Based Gaming Market
Gaming
Global Battle Royale Games Market
Gaming
China Subscription-Based Gaming Market
Gaming
North America Gaming Market
Gaming
Global Game Testing Service Market
Gaming
Game API Market
Gaming
Saudi Arabia Entertainment and Amusement Market
Gaming
LAMEA Gaming Posters Market