
 Serious Games Market | 2026-2036
Serious Games Market Size, Share, and Industry Trends Forecast 2026-2036
Serious Games Market Intelligence
Cloud-native game engine architectures is reshaping how serious games deploy across enterprise and institutional buyers. Cisco Systems leverages its networking infrastructure to deliver low-latency streaming of training simulations to distributed corporate workforces. Triseum LLC specializes in art and calculus educational games that anchor its position within higher education institutions. Grendel Games competes in healthcare rehabilitation by designing motion-controlled therapy titles that physicians prescribe to stroke patients.
Serious games constitute interactive software applications engineered with specific learning or training objectives rather than entertainment value alone, typically incorporating real-time feedback loops, adaptive difficulty algorithms, and measurable competency assessment protocols. The primary commercial purpose centers on accelerating skill acquisition, reducing training costs, and enabling risk-free practice of high-stakes procedures across defense, medical, and industrial contexts. Military Training applications dominate procurement budgets due to multi-year defense contracts and live-fire cost avoidance, while Health Simulations represent the fastest-expanding segment as hospitals seek alternatives to cadaver-based surgical education. Virtual Reality technology captures premium pricing despite hardware constraints because immersive presence demonstrably improves retention rates in pilot and procedural training.
The FDA governs medical simulation software as Class II devices when used for diagnostic or therapeutic training, compelling developers to submit 510(k) premarket notifications. The EU AI Act and GDPR impose algorithmic transparency and biometric data restrictions on adaptive learning platforms deployed across European educational institutions. Stakeholders must monitor how divergent transatlantic compliance requirements fragment development roadmaps and inflate certification costs for cross-border serious game vendors.
Market Dynamics
Cloud-native deployment architectures are compressing the capital requirements for enterprise serious game distribution, enabling vendors to bypass on-premise infrastructure investments and reach institutional buyers through browser-based streaming protocols.
Growth Catalysts
- Defense procurement modernization:Multi-year military training contracts in the United States prioritize simulation-based alternatives to live-fire exercises, with the Department of Defense mandating virtual rehearsal platforms for combat readiness certification.
- EU AI Act compliance infrastructure:European educational institutions demand algorithmic transparency in adaptive learning platforms, creating procurement specifications that favor vendors with pre-built audit trails and explainable difficulty-adjustment systems.
- Motion-capture hardware commoditization:Consumer-grade depth sensors and haptic controllers originally developed for entertainment markets now enable stroke rehabilitation applications at price points accessible to outpatient clinics.
Market Restraints
- Clinical validation cost structures:FDA 510(k) premarket notification pathways for Class II medical device software impose documentation burdens exceeding two million dollars per submission, excluding smaller developers from healthcare segments.
- Biometric data governance fragmentation:GDPR Article 9 restrictions on processing special-category data in Germany and France conflict with adaptive learning algorithms that require physiological feedback loops, forcing dual codebase maintenance.
- Specialized talent scarcity:The intersection of instructional design, game engine programming, and domain expertise in surgical procedures or aviation systems limits production capacity across the vendor base.
Strategic Opportunities
- Indian vocational training digitization:The country's PLI scheme for skill development and state-level ITI modernization programs create procurement pipelines for localized safety training simulations in manufacturing and construction trades.
- Convergence of VR and AI tutoring:Large language models integrated with immersive environments enable real-time Socratic dialogue in medical diagnosis training, compressing the feedback loop between student error and corrective guidance.
- Brazilian healthcare regionalization:ANVISA's streamlined software registration pathways for low-risk therapeutic devices open distribution channels to municipal hospital networks previously served only by paper-based rehabilitation protocols.
Industry Challenges
- Cross-platform certification timelines:Serious games deployed across VR headsets, desktop browsers, and mobile tablets require separate validation protocols for each hardware configuration, extending product launch cycles by eight to fourteen months.
- Legacy LMS integration complexity:Enterprise buyers demand SCORM and xAPI compatibility with decades-old learning management infrastructure, forcing vendors to maintain deprecated API support rather than native cloud-native architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serious Games Market |
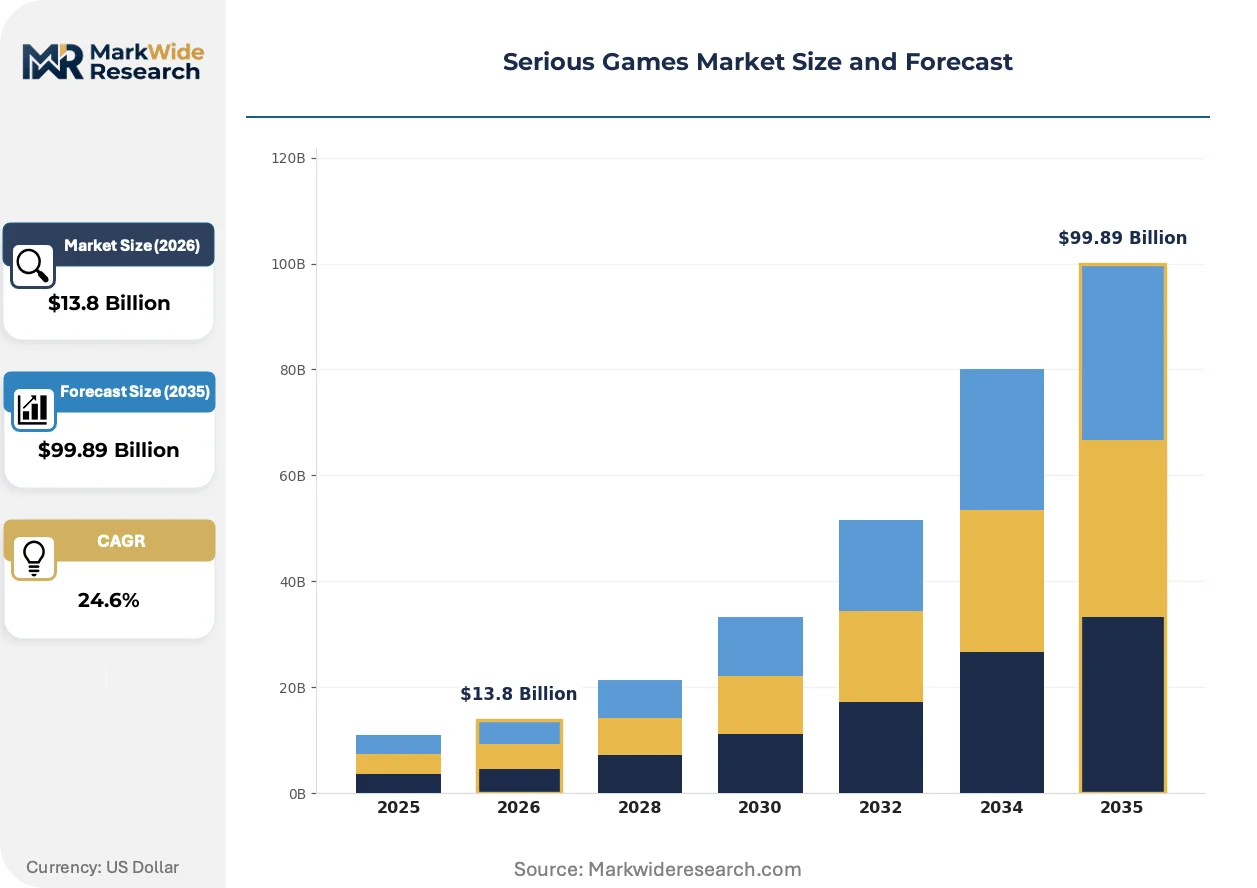
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $99.89 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Corporate Training, Educational Games, Health Simulations, Military Training Technology: Virtual Reality, Augmented Reality, Mobile Platforms, PC Games End User: Healthcare Providers, Educational Institutions, Defense Forces, Corporations Content Type: Simulations, Interactive Scenarios, Serious Role-Playing, Problem-Solving Games |
| Companies Covered | Applied Research Associates Inc., Tygron BV, Designing Digitally, Inc., Cisco Systems, MPS Interactive Systems, Diginext (CS Group), Grendel Games, Triseum LLC, CCS Digital Education Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serious Games Market Strategic Shifts & Innovations
Generative AI systems are rewriting content production economics for scenario-based training, collapsing the traditional bottleneck of manual scriptwriting and 3D asset creation that previously constrained customization for niche industrial applications.
Neural radiance fields (NeRF) and Gaussian splatting techniques are collapsing the cost structure for photorealistic environment reconstruction. Military and aviation training buyers in the United States now commission site-specific simulations from smartphone-captured imagery rather than dedicated photogrammetry teams. This compression eliminates the six-month lead time previously required for facility digitization.
The EU AI Act's risk-classification framework for educational technologies is mandating algorithmic impact assessments before adaptive learning platforms deploy in Dutch and Finnish secondary schools. Developers must document training data provenance and establish human oversight protocols for real-time difficulty adjustments. Healthcare simulation vendors are responding by segregating European and North American product branches to isolate compliance scope.
Hospital procurement committees are consolidating vendor relationships around integrated platforms that combine surgical simulation with competency tracking and continuing medical credit administration. This bundling displaces the previous pattern of point-solution purchases from specialized studios. The concentration is most visible in German university hospital networks, where centralized IT governance now mandates single-source contracts for all digital training assets.
Serious Games Market Segmentation
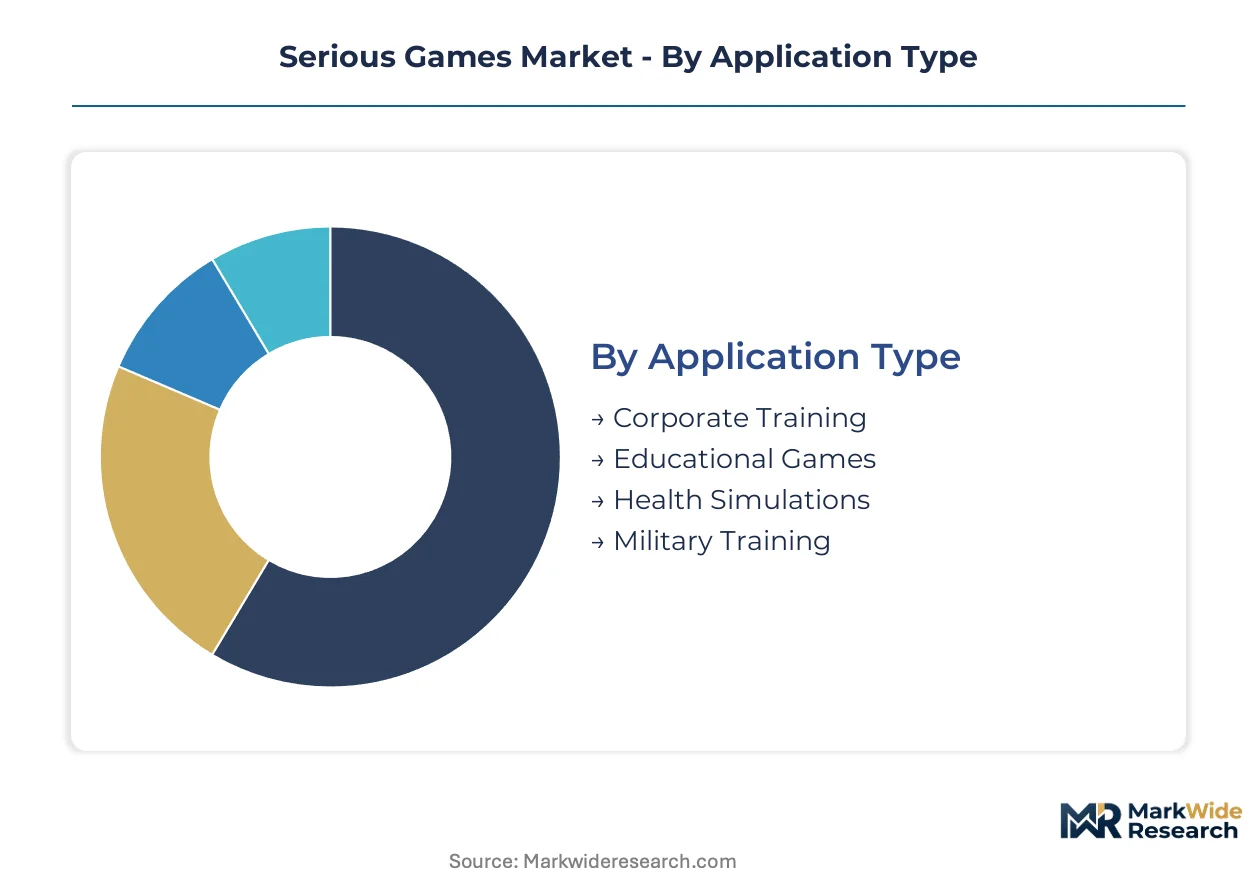
Segmentation in the serious games market reveals how procurement priorities diverge across institutional buyers with distinct compliance requirements and training cost structures. Defense departments, hospital networks, and corporate L&D functions each impose incompatible technical specifications that fragment vendor specialization.
Application Type:
The use-case spectrum spans risk-mitigation training for high-stakes professions through foundational skill-building for general workforces, with each application carrying divergent validation burdens and contract durations.
- Military Training:Combat rehearsal platforms integrate live-fire cost avoidance metrics into procurement specifications. The United States Department of Defense mandates virtual certification for combat readiness, anchoring multi-year simulation contracts that sustain vendor revenue stability across hardware refresh cycles.
- Health Simulations:Surgical training modules and patient education tools face FDA Class II device classification when used for diagnostic or therapeutic instruction. German university hospital networks now consolidate procurement around bundled platforms combining simulation with competency tracking and continuing medical credit administration.
- Corporate Training:Safety protocols and technical skill modules deploy through browser-based streaming to distributed workforces. Cisco Systems leverages its networking infrastructure to deliver low-latency enterprise training at reduced capital requirements.
- Educational Games:Art and calculus instruction titles anchor positions within higher education institutions through adaptive learning algorithms. Triseum LLC specializes in this segment with discipline-specific content validated for academic credit transfer.
Established volume favors Military Training; emerging adoption favors Health Simulations.
Technology:
Cost tier separation runs from premium immersive hardware through accessible browser-based delivery, with each tier imposing distinct development timelines and certification protocols.
- Virtual Reality:Head-mounted displays with six-degrees-of-freedom tracking generate demonstrable retention improvements in pilot and procedural training. Premium pricing persists despite hardware constraints because immersive presence compresses skill acquisition timelines measurably.
- Mobile Platforms:Smartphone and tablet delivery enables outpatient stroke rehabilitation at price points accessible to municipal clinic budgets. Grendel Games competes in this segment with motion-controlled therapy titles that physicians prescribe for home-based recovery protocols.
- Augmented Reality:Overlay systems project procedural guidance onto physical workspaces for manufacturing and maintenance training. Industrial buyers in Germany commission automotive safety simulations through AR headsets for KBA-funded vocational programs.
- PC Games:Desktop browser and installed software retain dominance in corporate L&D for SCORM and xAPI compatibility with legacy learning management infrastructure.
VR commands premium margins; mobile platforms are climbing the fastest on unit volume.
End User:
Customer type determines procurement cycle length, with defense and healthcare buyers imposing extended validation timelines that contrast with corporate rapid-deployment expectations.
- Defense Forces:National military procurement offices specify multi-year simulation contracts with live-fire cost avoidance justification. The United States mandates virtual rehearsal platforms for combat certification, creating predictable revenue windows for qualified vendors.
- Healthcare Providers:Hospital networks and outpatient clinics demand FDA 510(k) clearance for Class II training software, excluding smaller developers through documentation burdens exceeding two million dollars per submission.
- Educational Institutions:European secondary schools and universities require algorithmic transparency under EU AI Act risk-classification frameworks, mandating training data provenance documentation and human oversight protocols for adaptive difficulty systems.
- Corporations:Enterprise L&D departments prioritize cloud-native deployment architectures that bypass on-premise infrastructure investments and reach distributed workforces through browser-based streaming protocols.
Defense procurement sustains longest contract cycles; healthcare providers are gaining share fastest on simulation digitization urgency.
Content Type:
Maturity gradients separate physics-based environment replication from narrative-driven behavioral training, with each content architecture demanding distinct production expertise and validation evidence.
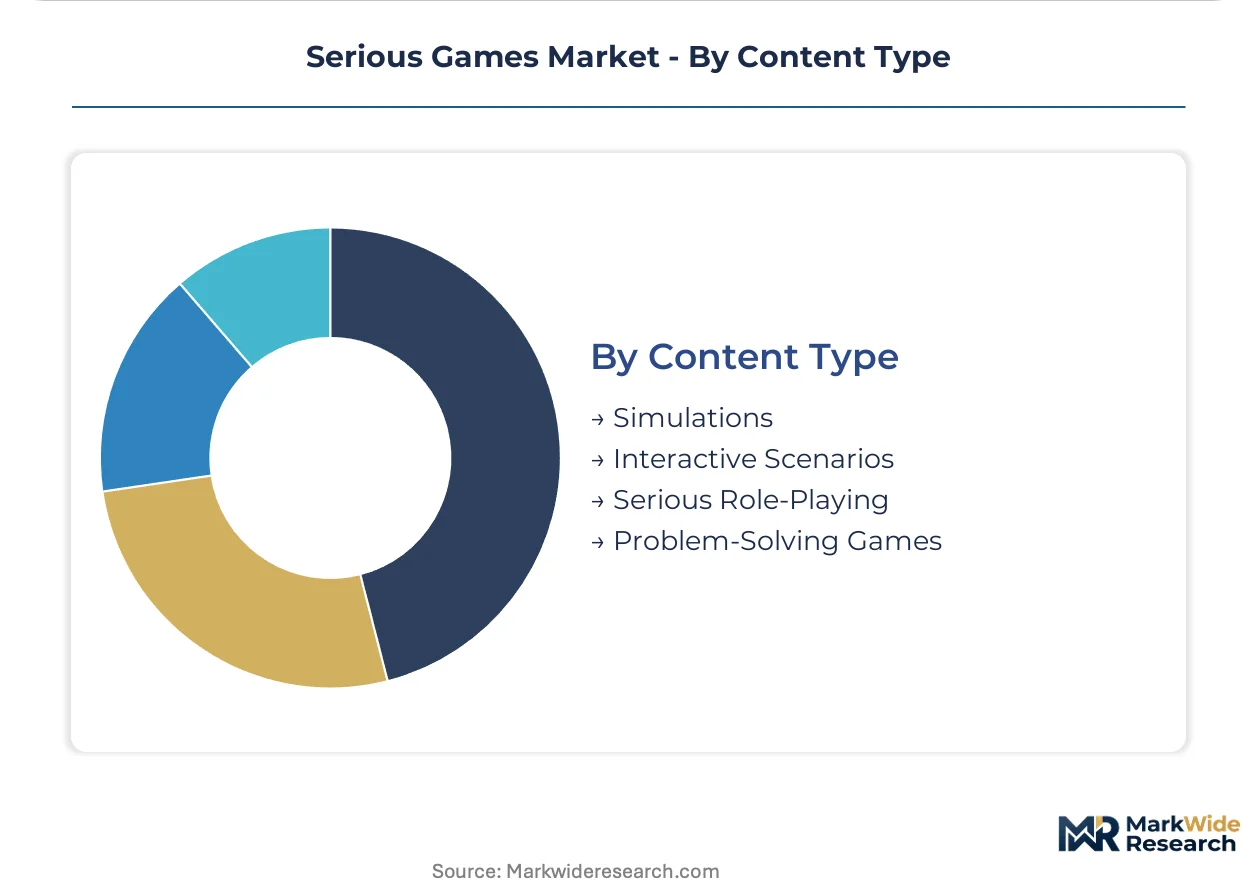
- Simulations:Physics engines replicate surgical procedures, flight dynamics, and industrial equipment operation with measurable competency assessment protocols. Neural radiance fields and Gaussian splatting now collapse photorealistic environment reconstruction costs from smartphone-captured imagery.
- Interactive Scenarios:Branching narrative structures adapt to learner decisions in ethics, customer service, and crisis management training. Generative AI systems rewrite content production economics by collapsing manual scriptwriting bottlenecks.
- Serious Role-Playing:Avatar-based social interaction develops negotiation, leadership, and cultural competency skills through peer collaboration. Large language models integrated with immersive environments enable real-time Socratic dialogue in medical diagnosis training.
- Problem-Solving Games:Puzzle architectures target specific cognitive skill development in mathematics, logic, and systems thinking for academic and corporate assessment contexts.
Simulations dominate procurement budgets; interactive scenarios show steepest expansion trajectory on AI-assisted production economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in serious games tilt toward net-importing healthcare systems in Western Europe and North America, while India and Brazil emerge as net exporters of vocational training content. Procurement patterns diverge sharply between defense-heavy importers and education-focused domestic developers.
United States
Defense procurement anchors import demand through multi-year simulation contracts from the Department of Defense. The FDA regulates medical training software as Class II devices under 510(k) pathways, compelling clinical validation investments exceeding two million dollars per submission. Boston and San Francisco clusters concentrate health simulation startups seeking hospital network partnerships.
Germany
The KBA and federal education ministries fund automotive safety and vocational training simulations, creating sustained domestic procurement pipelines. GDPR Article 9 restrictions on biometric data processing force adaptive learning vendors to maintain dual codebases for European deployment. Stuttgart and Munich industrial corridors anchor AR-based manufacturing training deployments.
India
The PLI scheme for skill development and state-level ITI modernization programs generate procurement for localized safety training in manufacturing trades. The country's national education regulator mandates digitization compliance timelines that accelerate simulation adoption. Karnataka and Maharashtra technology corridors host domestic developers serving vocational training export markets.
Brazil
ANVISA's streamlined software registration for low-risk therapeutic devices opens distribution to municipal hospital networks previously limited to paper-based rehabilitation. State-level healthcare regionalization programs consolidate procurement around digital training platforms. São Paulo and Rio de Janeiro metropolitan clusters concentrate health simulation implementation partnerships.
United Kingdom
NHS procurement frameworks prioritize bundled platforms combining surgical simulation with competency tracking and continuing medical credit administration. The national data protection authority enforces algorithmic transparency requirements for adaptive learning in secondary education. London and Oxford academic medical centers anchor health simulation validation partnerships.
Serious Games Market Key Industry Players
On the supply side, the industry is bifurcated between defense-contract incumbents with multi-year revenue stability and agile specialists serving healthcare and education verticals. Tier-one vendors anchor procurement through integrated platform bundling, while mid-tier players compete on domain-specific customization. Three archetypes dominate: networking infrastructure leveragers, discipline-specific content studios, and motion-controlled therapy developers. Competitive moves concentrate on strategic partnerships with hospital networks and cloud-native architecture transitions that bypass legacy LMS integration burdens.
Among networking infrastructure leveragers, Cisco Systems exemplifies the enterprise distribution archetype through low-latency streaming capabilities. Triseum LLC and Grendel Games occupy positions within specialized verticals—higher education discipline-specific content and motion-controlled rehabilitation therapy respectively—demonstrating how domain expertise creates defensible procurement relationships outside defense contracting channels.
| Leading Market Players |
|---|
| Applied Research Associates Inc. |
| Tygron BV |
| Designing Digitally, Inc. |
| Cisco Systems |
| MPS Interactive Systems |
| Diginext (CS Group) |
| Grendel Games |
| Triseum LLC |
| CCS Digital Education Ltd |
| Others |
Cost & Logistics Intelligence
Freight corridors connecting Shenzhen to Rotterdam dictate cost differentials across hardware-dependent VR training systems, compressing margins for European distributors while amplifying pricing power for cloud-native vendors bypassing physical component sourcing. This logistics asymmetry concentrates procurement leverage among buyers with established vendor relationships in Germany and the United States, forcing price stratification between immersive hardware tiers and browser-accessible alternatives.
Pricing Analysis
Current-generation VR headsets with six-degrees-of-freedom tracking command premium positioning against prior-generation desktop simulations and emerging next-gen haptic suites. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated surgical modules from SCORM-compliant corporate training and basic educational titles. Price differentiation centers on certification grade and geographic delivery cost, with FDA 510(k) pathways adding substantial documentation burdens that smaller developers cannot absorb. Cost compression in the standard tier is intensifying because consumer-grade depth sensors from entertainment markets now enable therapy applications at reduced hardware price points. Corporate L&D departments exhibit highest price sensitivity due to budget scrutiny, while defense procurement offices demonstrate lowest sensitivity given live-fire cost avoidance justification.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for motion-capture hardware and haptic controller components. Manufacturing concentration centers on China for consumer-grade sensors, Taiwan for advanced display panels, and Germany for precision-engineered industrial training equipment. Raw material dependencies span rare earth elements for VR headset magnetics, lithium-ion cells for wireless controllers, and specialized polymers for durable medical-grade peripherals. Single-source vulnerability persists for high-fidelity force-feedback actuators used in surgical simulation. Distribution runs through enterprise software procurement channels, hospital GPO contracts, and defense acquisition frameworks rather than retail consumer pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams including competency tracking, continuing medical credit administration, and adaptive algorithm updates expand faster than hardware sales, transforming vendor economics toward recurring subscription models.
For Market Incumbents: Insulate platform positions by deepening integration with hospital IT governance frameworks and defense procurement certification pathways. Vertical integration into cloud-native streaming infrastructure reduces dependency on third-party networking partnerships. Threat substitution from generative AI content tools demands accelerated R&D in real-time adaptive difficulty systems to maintain differentiation against automated scenario generation. For New Entrants and Emerging Players: Brazilian municipal hospital networks offer the most penetrable entry point given ANVISA's streamlined software registration for low-risk therapeutic devices. Indian state-level ITI modernization programs under the PLI scheme create secondary white-space for localized safety training modules. Go-to-market execution should anchor on physician prescription workflows for motion-controlled rehabilitation titles, bypassing centralized hospital procurement committees. For Investors and Strategic Acquirers: Discipline-specific content studios with validated academic credit transfer agreements represent priority acquisition archetypes given their defensible procurement relationships in higher education. Long-term viability across the analysis window hinges on algorithmic transparency compliance infrastructure for EU AI Act risk-classification frameworks. Signal to monitor: consolidation velocity among German university hospital networks around bundled platform contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Architecture Transition | Cisco Systems leverages networking infrastructure to bypass legacy LMS integration burdens for enterprise distribution. |
| Regulatory Compliance Infrastructure | Pre-built audit trails for EU AI Act algorithmic transparency requirements accelerate procurement in Dutch and Finnish secondary schools. |
| Motion-Capture Hardware Commoditization | Consumer-grade depth sensors enable stroke rehabilitation applications at outpatient clinic price points previously inaccessible. |
| Neural Radiance Field Content Production | Smartphone-captured imagery collapses photorealistic environment reconstruction costs for site-specific military training simulations. |
| Hospital System Partnership Consolidation | German university hospital networks mandate single-source contracts combining surgical simulation with competency tracking and CME administration. |
Research Approach
Desk research of FDA 510(k) premarket notification databases, EU AI Act regulatory guidance documents, and defense procurement contract disclosures preceded structured interviews with simulation platform CTOs, hospital biomedical engineers, corporate L&D procurement officers, and defense training command staff. Primary fieldwork combined with secondary validation against SEC filings from publicly traded networking infrastructure vendors and trade data from customs records. Bottom-up triangulation across installed base estimates and top-down reconciliation against aggregate procurement budgets anchored volume and value outputs.
Assumption sets held cloud-native deployment adoption curves and regulatory compliance timeline trajectories within observed patterns while varying defense budget allocation priorities and healthcare digitization urgency across regional clusters. The analytical framework modeled segmentation across application type, technology tier, end-user category, and content architecture throughout the forecast period. CAGRs derived from regression analysis against historical procurement cycles and forward-looking contract pipeline visibility. Industry-specific inputs included live-fire cost avoidance metrics for military training and cadaver-based surgical education displacement rates for health simulations.
The forecast holds incumbent behavior within observed patterns; aggressive platform bundling moves by networking infrastructure leveragers or generative AI content automation entrants would shift outcomes materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
North America Gaming Hardware and Accessories Market
Gaming
Advanced Digital Gaming Market
Gaming
Latin America Gaming Headsets Market
Gaming
PC Games Market
Gaming
Germany Gaming Headset Market
Gaming
Mobile Gaming Market
Gaming
Global Gaming Headset Market
Gaming
Cloud Gaming Market
Gaming
VR Melee Games Market
Gaming
Europe Gaming Peripherals Market
Gaming
Global 3D Gaming Console Market
Gaming
Online Strategy Games Market
Gaming
Singapore Gaming Gadgets Market
Gaming
Playstation Network (PSN) Market
Gaming
Global Casino and Gaming Market
Gaming
FPS Game Market