
 VR Gaming Accessories Market | 2026-2036
VR Gaming Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
VR Gaming Accessories Market Analytics
The capital-intensity divergence between in-house motion-tracking fabrication and outsourced controller assembly is redrawing competitive boundaries. Meta Platforms leverages its captive supply of custom haptic engines to tighten hardware-software integration. Sony Group Corporation anchors its accessories business through proprietary PlayStation VR ecosystem lock-in. HTC Corporation competes by specializing in enterprise-grade tracking sensors that command premium positioning.
VR gaming accessories comprise electromechanical peripherals—haptic controllers with six-degrees-of-freedom tracking, head-mounted displays with 90–120 Hz refresh rates, and capacitive sensor gloves—designed to translate physical movement into immersive digital environments. Controllers dominate accessory type revenue due to their universal requirement across all VR platforms, while glove-based input devices represent the fastest-growing segment as finger-tracking precision becomes a differentiator in simulation use cases. Compatibility segmentation tilts toward PC-tethered systems where upgrade cycles outpace console-locked alternatives, concentrating margin pools in modular, replaceable components.
The FCC enforces electromagnetic emissions standards that dictate wireless controller latency thresholds, while the EU AI Act and GDPR impose biometric data handling rules on devices capturing physiological signals through glove sensors. Product designers must navigate REACH substance restrictions for skin-contact materials in prolonged-wear headsets. Stakeholders should monitor how emerging eye-tracking regulations in multiple jurisdictions reshape privacy architecture and hardware certification requirements.
Market Dynamics
Immersive fitness applications are reshaping demand architecture by converting health-conscious consumers into first-time VR hardware purchasers, creating a parallel demand stream beyond core gaming demographics.
Growth Catalysts
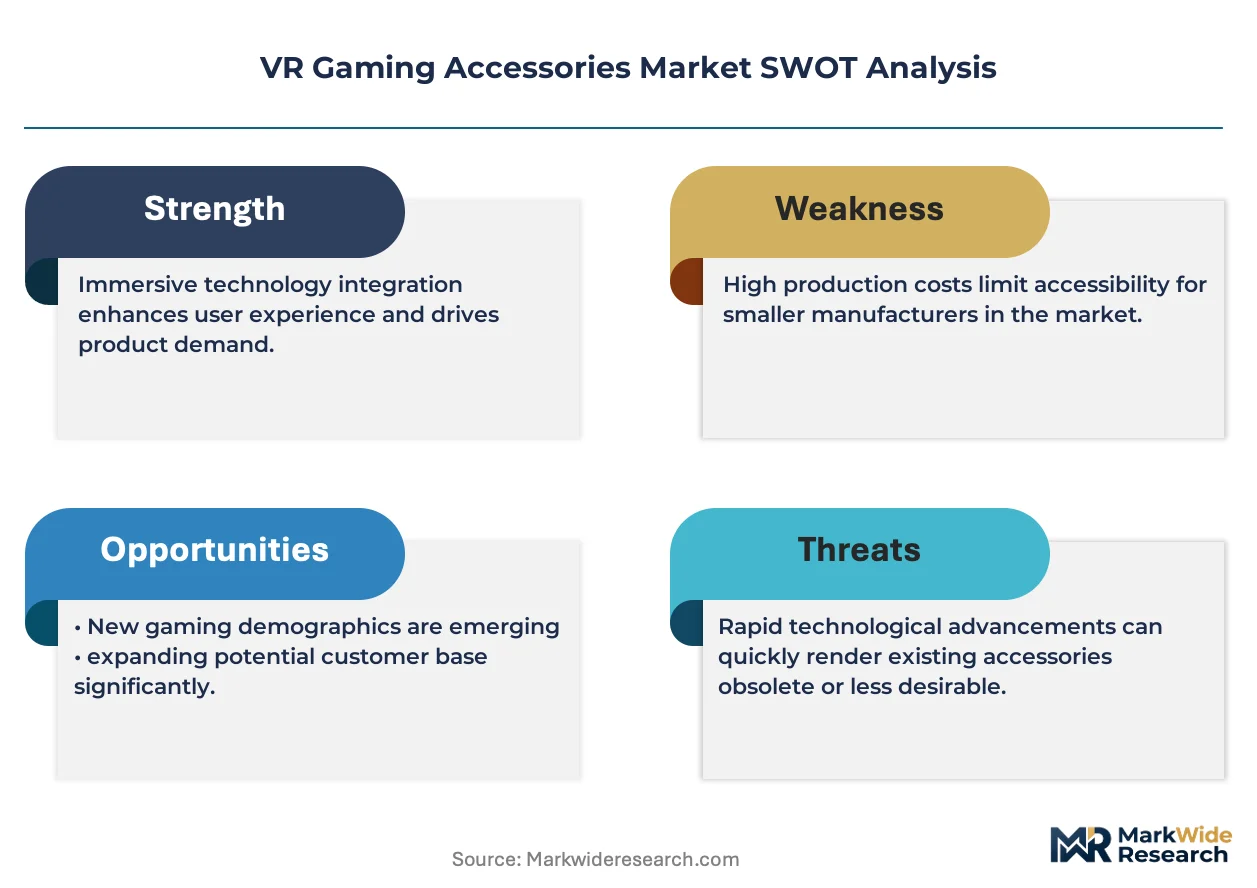
- REACH and RoHS frameworks:EU substance restrictions on hazardous materials in wearable electronics are accelerating compliant material innovation, opening premium positioning for certified peripherals in European distribution channels.
- FCC electromagnetic emissions standards:Wireless latency thresholds for controllers are pushing radio frequency engineering investments that simultaneously improve performance and create defensible technical moats.
- Immersive fitness vertical:Health applications requiring full-body tracking are expanding addressable user bases beyond traditional gaming into wellness and rehabilitation segments.
Market Restraints
- Custom haptic engine supply concentration:Captive fabrication capabilities concentrate among vertically integrated platform holders, constraining independent peripheral manufacturers' access to differentiated tactile feedback systems.
- Biometric data handling compliance:GDPR and EU AI Act requirements for physiological signal capture through glove sensors impose architectural constraints that extend development timelines and certification costs.
- Console ecosystem lock-in:Proprietary compatibility standards fragment addressable markets and prevent component standardization that would reduce manufacturing scale economies.
Strategic Opportunities
- Enterprise simulation applications:Medical training and industrial safety programs are creating demand for precision finger-tracking gloves that command pricing premiums unavailable in consumer gaming.
- Modular PC-tethered upgrade cycles:Replaceable component architectures in open ecosystems allow peripheral vendors to capture recurring revenue from enthusiast segments with compressed replacement intervals.
- Eye-tracking regulatory preparation:Early alignment with emerging biometric privacy frameworks in multiple jurisdictions positions compliant vendors for first-mover advantage as standards crystallize.
Industry Challenges
- Motion-tracking engineering talent scarcity:Six-degrees-of-freedom algorithm development and inertial measurement unit calibration require specialized expertise concentrated among platform holders and select component suppliers.
- Skin-contact material certification timelines:REACH compliance testing for prolonged-wear headset materials extends product development cycles and complicates rapid iteration strategies.
- Hardware-software integration complexity:Achieving sub-20ms motion-to-photon latency demands simultaneous optimization across sensor fusion, wireless transmission, and display pipeline engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR Gaming Accessories Market |
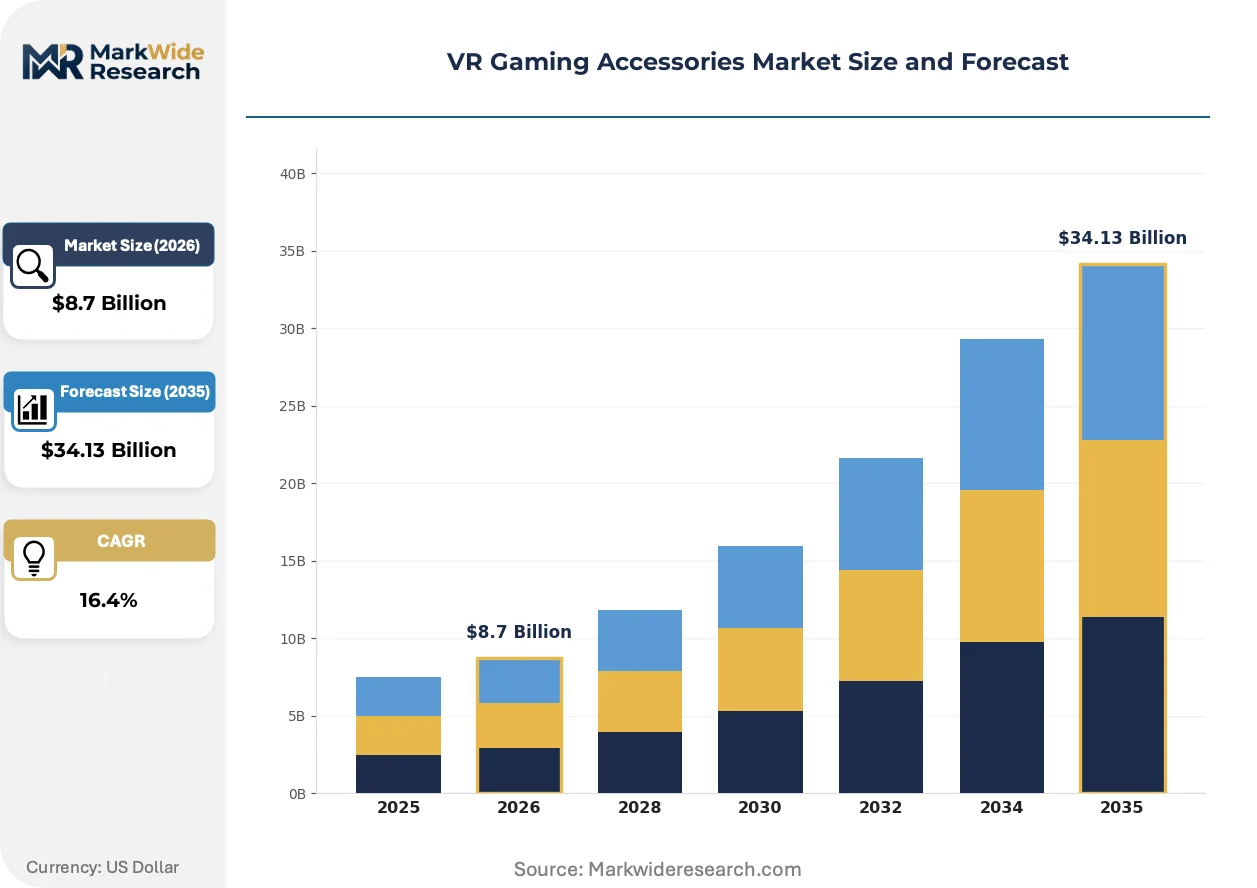
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Accessory Type: Controllers, Headsets, Sensors, Gloves Compatibility: PC, PlayStation, Xbox, Mobile Use Case: Educational, Fitness, Entertainment, Simulation Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Meta Platforms, Sony Group Corporation, HTC Corporation, Valve Corporation, Microsoft Corporation, Logitech International, Razer Inc., Corsair Gaming, KIWI design, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR Gaming Accessories Market Evolving Landscape
Three distinct vectors are compressing development cycles and redistributing value capture across the VR peripheral stack: electromechanical component evolution, biometric privacy architecture, and procurement model fragmentation.
Capacitive sensor arrays with individual finger joint resolution are supplanting legacy controller-based input for simulation and training applications. Medical education programs and industrial safety trainers are adopting these gloves at accelerated procurement cadences. This supplanting is compressing pricing power in traditional handheld controller segments while opening premium tiers for precision input devices.
GDPR and the EU AI Act are mandating on-device processing architectures for physiological signal data captured through wearable sensors. Manufacturers must redesign data pipelines to minimize cloud transmission of biometric information. Glove-based input devices face the most stringent compliance requirements, driving hardware encryption module adoption among European-market suppliers.
Enterprise buyers are fragmenting procurement across specialized vendors rather than consolidating with platform-integrated peripheral suppliers. Healthcare simulation departments now source tracking gloves, haptic vests, and eye-tracking modules from independent specialists. This pattern is most visible in United States academic medical centers and German industrial training facilities.
VR Gaming Accessories Market Segmentation
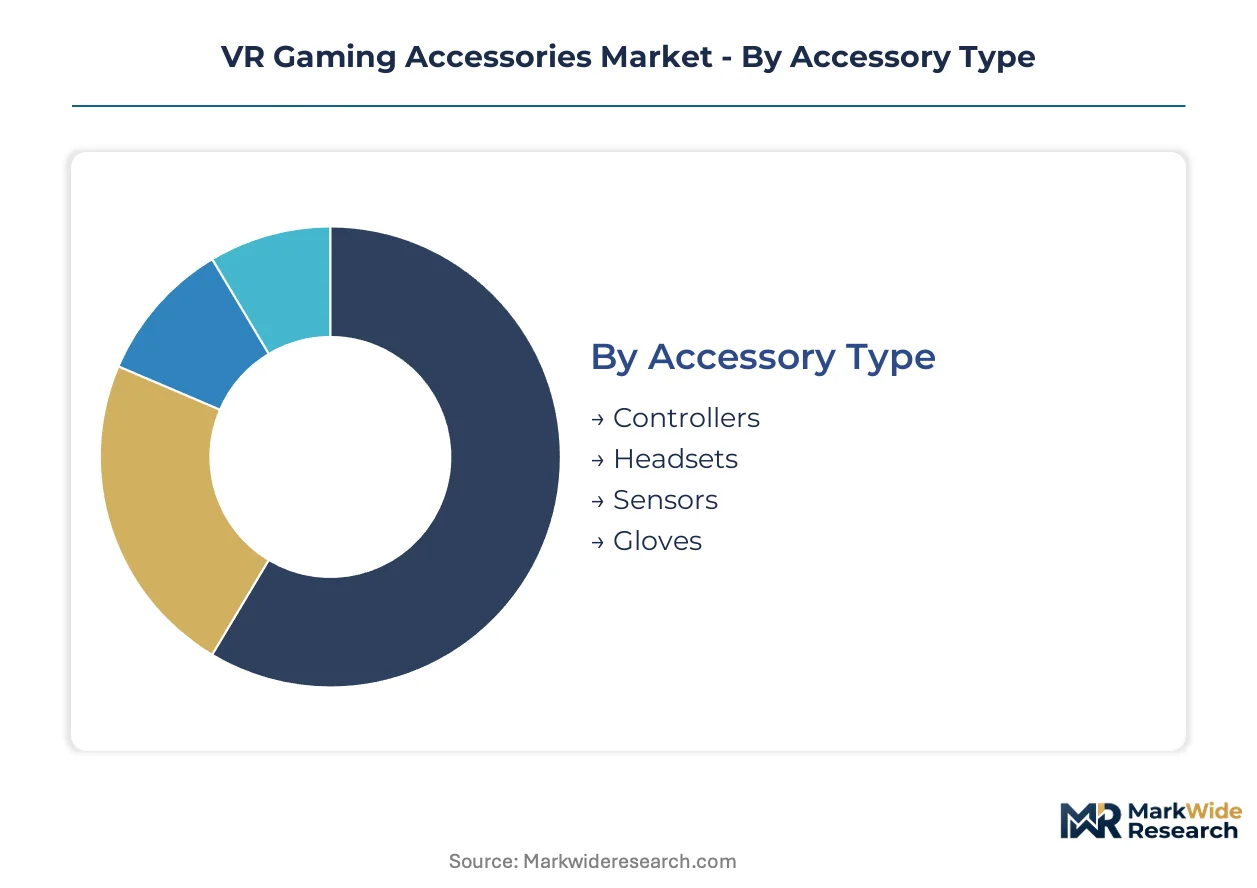
Segmentation in VR gaming accessories reveals how regulatory frameworks, platform architectures, and use-case specialization create distinct margin pools. Each dimension carries unique compliance burdens and procurement patterns that reshape competitive positioning across hardware categories.
Accessory Type:
REACH and RoHS substance restrictions apply differentially based on skin-contact duration and electronic complexity, concentrating certification investments in prolonged-wear categories.
- Controllers:Handheld electromechanical peripherals with six-degrees-of-freedom tracking and haptic feedback engines. FCC electromagnetic emissions standards govern wireless latency thresholds for these devices, with Meta Platforms and Sony maintaining captive supply chains for differentiated tactile systems.
- Gloves:Capacitive sensor arrays capturing individual finger joint resolution for precision input. GDPR and EU AI Act biometric data handling rules impose on-device processing requirements for these physiological signal capture devices, extending development timelines for European market entry.
- Headsets:Head-mounted displays with 90–120 Hz refresh rates requiring REACH-compliant materials for prolonged skin contact.
- Sensors:External tracking devices enabling spatial positioning without direct wearability constraints.
Established volume favors Controllers; emerging adoption favors Gloves.
Compatibility:
Platform lock-in architectures fragment addressable markets and prevent component standardization that would reduce manufacturing scale economies.
- PC:Open ecosystem tethered systems supporting modular component replacement and compressed upgrade cycles among enthusiast segments. United States distribution channels concentrate margin pools in replaceable peripherals for this category.
- PlayStation:Proprietary ecosystem with hardware-software integration controlled by Sony Group Corporation, constraining third-party peripheral access to differentiated features.
- Xbox:Microsoft-controlled compatibility standards with limited native VR accessory support currently.
- Mobile:Smartphone-dependent systems requiring low-power, lightweight designs for untethered operation.
Enthusiast spending concentrates in PC; ecosystem lock-in secures PlayStation.
Use Case:
Application-specific requirements reshape hardware specifications and procurement cadences across institutional and consumer segments.
- Simulation:Medical training and industrial safety programs demand precision finger-tracking and sub-20ms latency. German industrial training facilities and United States academic medical centers source these systems from specialized vendors at premium pricing tiers.
- Fitness:Health applications requiring full-body tracking are expanding addressable user bases beyond traditional gaming demographics, with immersive wellness programs driving first-time hardware purchases among health-conscious consumers.
- Entertainment:Core gaming applications prioritizing visual immersion and controller-based interaction.
- Educational:Institutional procurement with extended certification timelines and volume pricing requirements.
Procurement value concentrates in Simulation; volume expansion favors Fitness.
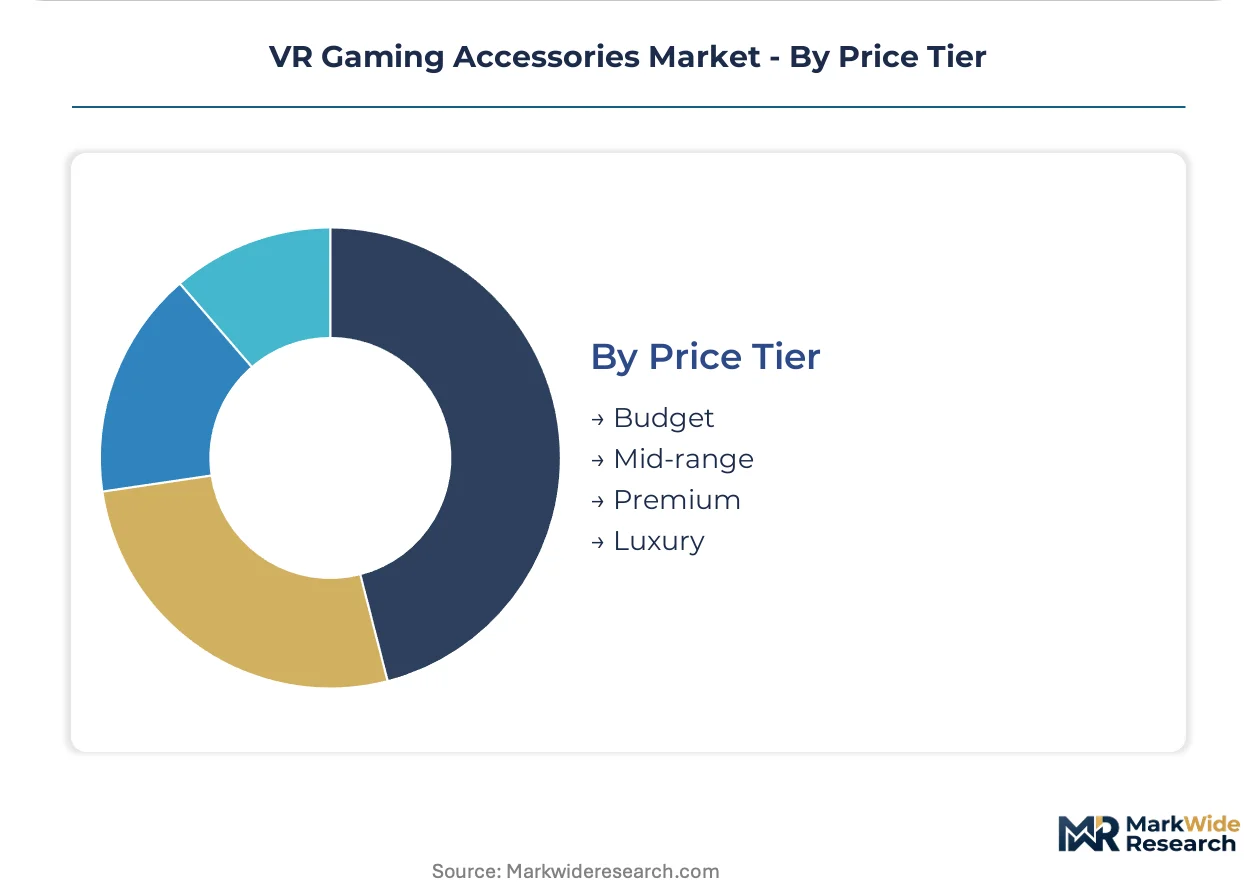
Price Tier:
Component certification costs and material compliance investments stratify pricing architecture across market entry points.
- Premium:Enterprise-grade tracking sensors and medical simulation gloves commanding pricing premiums through precision engineering and regulatory compliance. REACH-certified materials and hardware encryption modules for GDPR alignment justify positioning above mass-market alternatives.
- Mid-range:Consumer enthusiast peripherals balancing performance specifications with upgrade cycle accessibility.
- Budget:Entry-level controllers and mobile-compatible headsets with reduced feature sets for price-sensitive first-time purchasers.
- Luxury:Limited-edition designs and bespoke material configurations with minimal volume contribution.
Margin capture concentrates in Premium; volume penetration favors Mid-range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows of VR gaming accessories into the United States exceed outbound shipments by a substantial margin, while Germany and China function as net exporters of precision tracking components and electromechanical assemblies respectively.
United States
Immersive fitness applications and enterprise simulation contracts drive hardware procurement across health-conscious consumer and institutional segments. FCC electromagnetic emissions standards enforce wireless latency thresholds for controller certification, compressing product development timelines for market entry. Meta Platforms and Sony maintain extensive retail distribution networks concentrated in California and Texas metro corridors, anchoring domestic volume capture.
Germany
Industrial training facilities and academic medical centers source precision finger-tracking gloves at premium procurement cadences. ECHA REACH substance restrictions mandate compliant material sourcing for prolonged-wear headset components, extending certification timelines. Bavaria and Baden-Württemberg host specialized sensor manufacturers supplying European enterprise simulation markets with sub-20ms latency tracking systems.
China
Domestic manufacturing scale supports controller assembly and haptic engine production for global platform holders. MIIT radio frequency regulations govern wireless transmission standards for export-bound peripherals. Guangdong and Jiangsu provinces concentrate electromechanical component fabrication, with Shenzhen-based suppliers capturing volume contracts for capacitive sensor glove modules.
Japan
Console ecosystem loyalty sustains proprietary peripheral demand through hardware-software integration requirements. METI technical standards and JIS certification protocols impose quality benchmarks for wearable electronics entering domestic distribution. Tokyo-Osaka corridor retailers maintain dedicated VR accessory sections, reflecting enthusiast segment density in metropolitan clusters.
South Korea
Display panel integration capabilities position domestic suppliers for headset component contracts with global brands. MFDS and Korean Agency for Technology and Standards regulate electromagnetic compatibility for consumer electronics, aligning with export market requirements. Seoul Capital Area technology parks host motion-tracking algorithm development teams serving both gaming and industrial simulation verticals.
VR Gaming Accessories Market Competitive Landscape
Concentration sits with platform-integrated technology conglomerates that command captive supply chains and proprietary ecosystem lock-in. The competitive structure tilts toward vertical integration, with in-house motion-tracking fabrication creating technical moats that independent peripheral vendors struggle to replicate. Three archetypes dominate: ecosystem-anchored platform holders, enterprise-grade precision specialists, and modular component suppliers for open PC ecosystems. Dominant competitive moves include strategic partnerships with fitness application developers and geographic expansion through certified distribution channels in REACH-regulated European markets.
Among platform-integrated technology conglomerates, Meta Platforms and Sony Group Corporation exemplify ecosystem-anchored archetypes that leverage hardware-software integration for peripheral differentiation. HTC Corporation occupies a position within the enterprise-grade precision specialist tier, commanding premium positioning through specialized tracking sensor offerings. These three entities represent the structural concentration that independent manufacturers navigate when accessing differentiated haptic systems and motion-tracking capabilities.
| Leading Market Players |
|---|
| Meta Platforms |
| Sony Group Corporation |
| HTC Corporation |
| Valve Corporation |
| Microsoft Corporation |
| Logitech International |
| Razer Inc. |
| Corsair Gaming |
| KIWI design |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with Shenzhen-based electromechanical suppliers lock in haptic engine access and price visibility for tier-one peripheral vendors, while spot-market glove sensor procurement exposes mid-tier manufacturers to MIIT radio frequency certification delays and cost volatility.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with REACH-certified materials and hardware encryption modules for GDPR alignment commanding substantial premiums over mass-market alternatives. Price differentiation rests on certification grade and volume scale, with enterprise simulation contracts showing lowest sensitivity due to precision requirements. Cost compression in budget-tier controller segments is intensifying because of captive haptic engine supply concentration among platform holders. Fitness application developers demonstrate highest price sensitivity, compressing margins for entry-level headset bundles.
Supply Chain Analysis
Container availability constraints on the Shenzhen-Los Angeles trade lane are extending inbound lead times for capacitive sensor arrays and inertial measurement units. Manufacturing gravity centers on China, South Korea, and Taiwan, with Guangdong and Jiangsu provinces feeding electromechanical component fabrication. The supply chain draws from rare earth magnet suppliers for haptic engines, display panel integrators in South Korea, and REACH-compliant polymer compounders in Germany. Single-source vulnerability concentrates in custom motion-tracking algorithm firmware. Distribution runs through platform-holder retail networks in California and Texas metro corridors, supplemented by specialized enterprise vendors serving German industrial training facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among United States academic medical centers and German industrial training facilities is shifting buyer power toward institutional purchasers with volume leverage and extended certification requirements.
For Market Incumbents: Consolidate captive haptic engine supply chains through backward integration into precision actuator fabrication, defending against emerging modular PC peripheral vendors. Deepen hardware-software integration moats by embedding proprietary motion-tracking algorithms directly into controller firmware. Prioritize REACH certification investments for prolonged-wear headset materials to maintain European distribution channel access against regulatory tightening. For New Entrants and Emerging Players: Anchor in enterprise simulation applications where precision finger-tracking gloves command pricing premiums unavailable in consumer gaming. Target medical training programs and industrial safety verticals with sub-20ms latency specifications. Pursue go-to-market partnerships with independent fitness application developers seeking hardware-agnostic peripheral compatibility. For Investors and Strategic Acquirers: Capital is best deployed toward enterprise-grade precision specialists with GDPR-compliant on-device processing architectures and established contracts with German industrial training facilities. Long-term viability favors vendors positioned across the analysis window for emerging eye-tracking regulatory frameworks. Monitor biometric privacy legislation crystallization in multiple jurisdictions as inflection indicator for hardware encryption module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Certification | Unlocks premium positioning in European distribution channels constrained by ECHA substance restrictions. |
| On-Device Biometric Processing Architecture | Aligns hardware pipelines with GDPR and EU AI Act requirements for glove sensor data handling. |
| Enterprise Simulation Partnership Program | Captures procurement value from United States academic medical centers and German industrial trainers. |
| Haptic Engine Backward Integration | Reduces dependency on Meta Platforms and Sony captive supply for differentiated tactile feedback systems. |
| Fitness Application Developer Alliance | Expands addressable user base beyond core gaming into health-conscious consumer segments. |
Research Methodology
The analysis maps haptic controllers, capacitive sensor gloves, head-mounted displays, and external tracking sensors, each validated through hardware engineering directors, regulatory compliance officers, and enterprise procurement managers at simulation training facilities. Primary interviews with CTOs at fitness application developers and channel partners in California and Texas retail networks combined with secondary validation from FCC equipment authorization databases, ECHA REACH registration dossiers, and MIIT radio frequency filings. Bottom-up component cost modeling and top-down platform shipment triangulation anchored volume estimates.
Consistency checks against external benchmarks validated outputs across the projection horizon, with segmentation dimensions spanning accessory type, compatibility architecture, use case specialization, and price tier certification grade. CAGRs derived from installed base growth curves and replacement cycle compression in PC-tethered enthusiast segments. Forecast inputs incorporated REACH compliance timeline extensions and emerging eye-tracking regulatory preparation costs.
Underlying assumptions cover sustained immersive fitness application adoption and stable electromagnetic emissions standards, with deviation risk concentrated in biometric privacy legislation acceleration and custom haptic engine supply disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Virtual Reality (VR) in Gaming Market
Gaming
Global Online Adventure Games Market
Gaming
Serious Games Market
Gaming
Australia Gaming Gadgets Market
Gaming
VR Gaming Console Market
Gaming
Global Tarot Cards Market
Gaming
North America Gaming Market
Gaming
MMORPG Gaming Market
Gaming
Saudi Arabia Entertainment and Amusement Market
Gaming
Puzzle Video Game Market
Gaming
Europe Gaming Peripherals Market
Gaming
Game Applications Market
Gaming
North America in-Game Advertising Market
Gaming
China in-Game Advertising Market
Gaming
Slot Machine Market
Gaming
France Online Gambling Market