
 Global NFT Gaming Market | 2026-2036
Global NFT Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Global NFT Gaming Market Foresight
Software-defined asset leasing is rebalancing how virtual goods generate recurring value for publishers and players alike. Sky Mavis leverages its Ronin sidechain infrastructure to sustain low-cost transactions for its player base. Animoca Brands anchors its portfolio strategy across multiple blockchain ecosystems rather than single-chain dependence. Immutable competes through its zero-knowledge rollup technology that eliminates gas fees for end users.
NFT gaming denotes interactive entertainment software where non-fungible tokens serve as verifiable digital assets on distributed ledgers, with smart contracts automating ownership transfers and royalty distributions. These systems primarily enable player-driven economies where virtual items carry persistent value outside individual game environments. Mobile platforms command the largest addressable audience due to smartphone penetration in emerging markets, while free-to-play monetization models accelerate user acquisition by removing upfront payment barriers. RPG genres concentrate the deepest asset customization demand, driving repeat engagement through character progression systems tied to tradable collectibles.
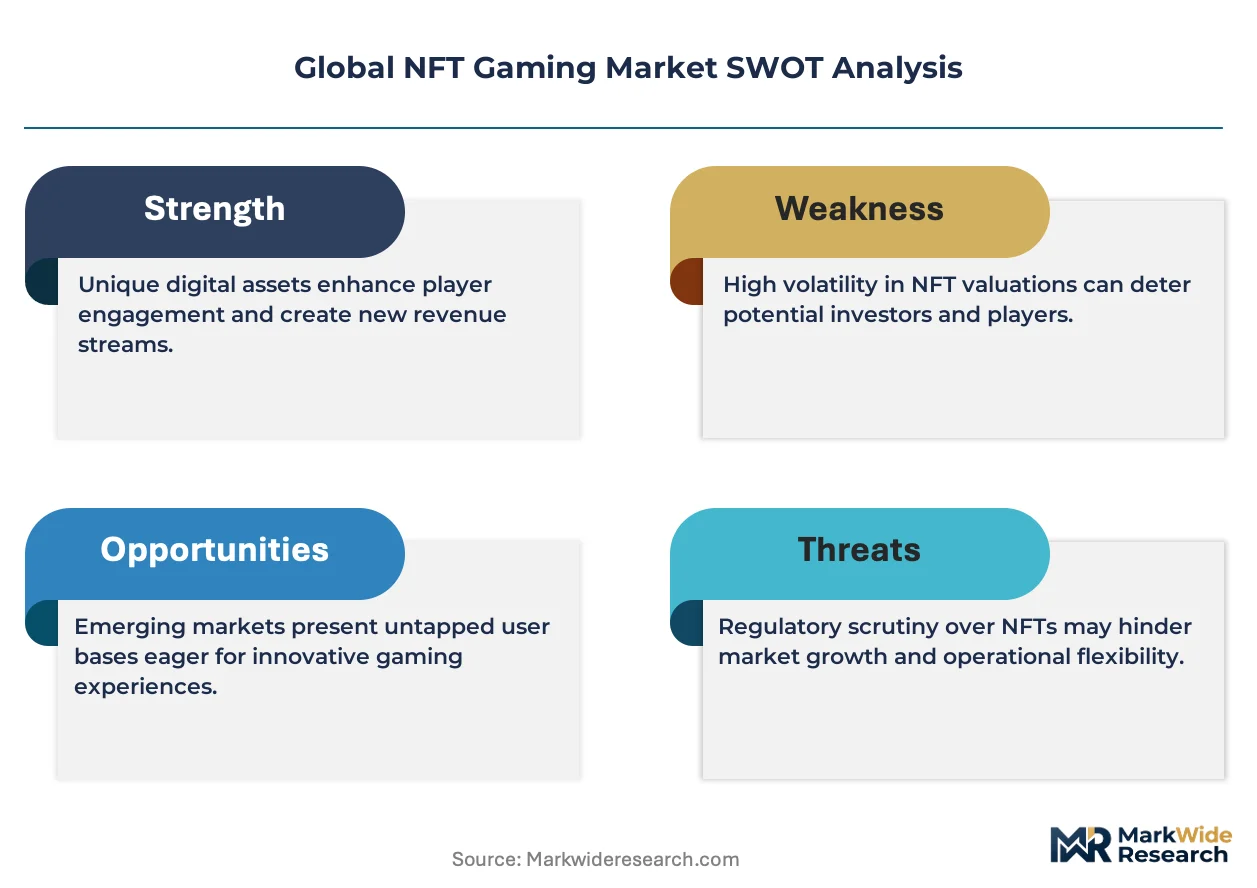
The SEC in the United States scrutinizes token distributions as potential securities offerings, compelling developers to restructure reward mechanisms. The EU's MiCA framework imposes reserve requirements and consumer disclosure standards on issuers of utility and payment tokens. Japan's FSA and JVCEA maintain registration mandates for crypto-asset exchanges facilitating in-game item trading. Stakeholders must monitor evolving jurisdictional classifications that determine whether play-to-earn rewards constitute taxable income, unregistered securities, or exempt virtual commodities.
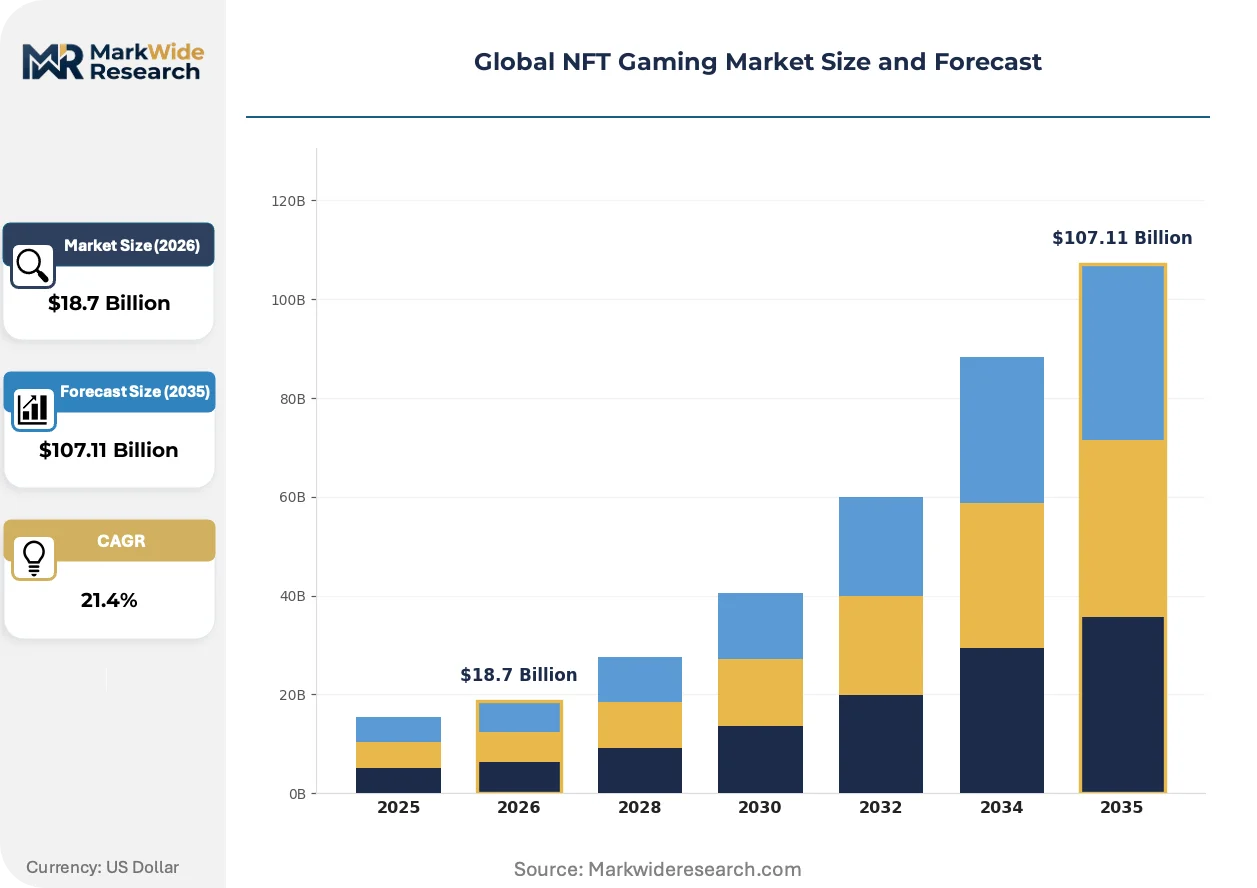
Market Dynamics
The EU's MiCA framework is forcing publishers to restructure token economics across all jurisdictions, triggering a wholesale redesign of how virtual assets are issued, traded, and monetized within interactive entertainment ecosystems.
Growth Catalysts
- Layer-2 scaling infrastructure:Zero-knowledge rollups and sidechains slash transaction costs below one cent, enabling micro-transaction economies that sustain player liquidity in emerging markets.
- Philippines mobile penetration:Smartphone-first gaming populations in Southeast Asia drive asset trading volume through peer-to-peer marketplaces integrated directly into wallet applications.
- Japan's JVCEA registration pathway:Clear exchange licensing rules for crypto-asset trading reduce legal uncertainty for publishers targeting East Asian monetization.
Market Restraints
- Ethereum base-layer gas volatility:Network congestion spikes during NFT minting events can push transaction fees above $50, pricing out casual asset traders.
- US SEC securities classification risk:Uncertainty over whether play-to-earn rewards constitute unregistered securities offerings compels developers to cap token yields or exclude American users.
- Wallet private key management:Self-custody requirements create permanent asset loss risk that mainstream audiences associate with poor user experience.
Strategic Opportunities
- Brazil's unbanked gamer population:Stablecoin-denominated prize pools bypass traditional banking infrastructure for 45 million adults without formal financial access.
- AI-generated procedural assets:Machine learning tools reduce art production costs while expanding unique item variety for RPG customization systems.
- India's PLI scheme for electronics manufacturing:Domestic smartphone production incentives accelerate device affordability for first-time mobile gamers in tier-2 and tier-3 cities.
Industry Challenges
- Smart contract security auditing:Exploit vulnerabilities in token bridges have resulted in over $2 billion in cumulative losses, demanding specialized blockchain security talent that commands premium compensation.
- Cross-chain asset interoperability:Fragmented liquidity across Ethereum, Polygon, Solana, and Avalanche forces publishers to maintain redundant infrastructure or sacrifice player choice.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global NFT Gaming Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $107.11 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: PC, Mobile, Console, Web-based Game Genre: Action, Strategy, RPG, Simulation Monetization Model: Pay-to-Play, Free-to-Play, Subscription, In-Game Purchases Player Type: Casual, Hardcore, Competitive, Social |
| Companies Covered | Sky Mavis, Animoca Brands, Dapper Labs, Immutable, The Sandbox, Axie Infinity, Illuvium, Mythical Games, Gala Games, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global NFT Gaming Market Shifts & Advancements
Tokenized asset leasing is expanding into subscription-like revenue models that decouple ownership from access, reshaping how publishers monetize virtual goods without requiring outright purchase.
Zero-knowledge proof technology is expanding into end-user transaction verification, enabling gas-free gameplay on Immutable's zkEVM chain. Mid-core RPG studios in South Korea and Vietnam are migrating asset minting to these rollups. The structural compression of transaction costs is expanding into entirely new player segments previously excluded by fee barriers.
The EU's MiCA regulation mandates reserve backing for asset-referenced tokens and imposes strict consumer disclosure standards on issuers. Publishers must now segregate player funds and submit to national financial authority audits. RPG titles with complex in-game currencies face the steepest compliance burden, with several studios relocating issuance entities to Switzerland to leverage Swiss FINMA's clearer virtual asset guidelines.
Player guilds are displacing individual asset ownership as the dominant accumulation model, with Philippine-based gaming collectives pooling NFTs and distributing earnings through smart-contract revenue splits. This cooperative structure concentrates buying power for high-value virtual land and rare character skins. The behavioral shift is most visible in Axie Infinity's scholarship system, where asset-less players rent NFTs from guild managers in exchange for revenue shares.
Global NFT Gaming Market Segmentation
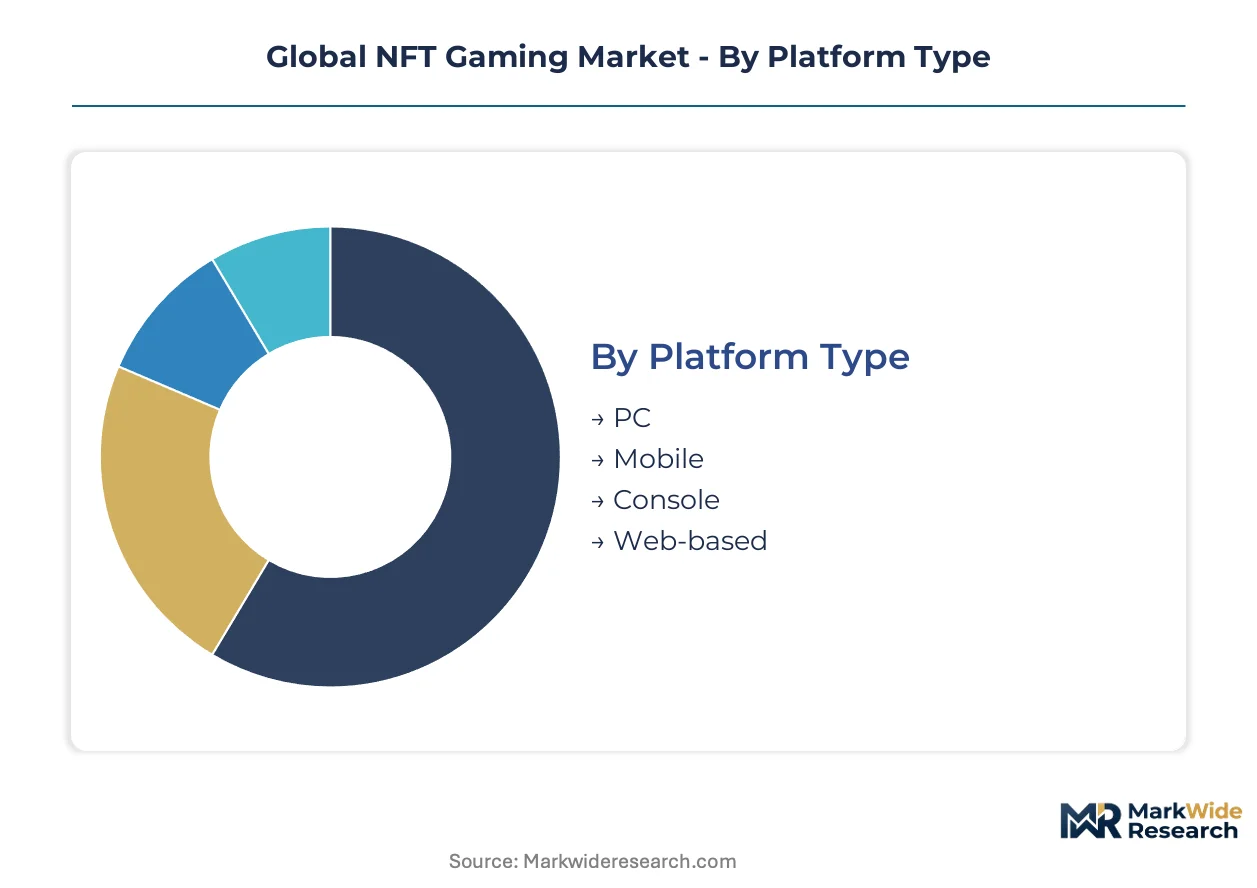
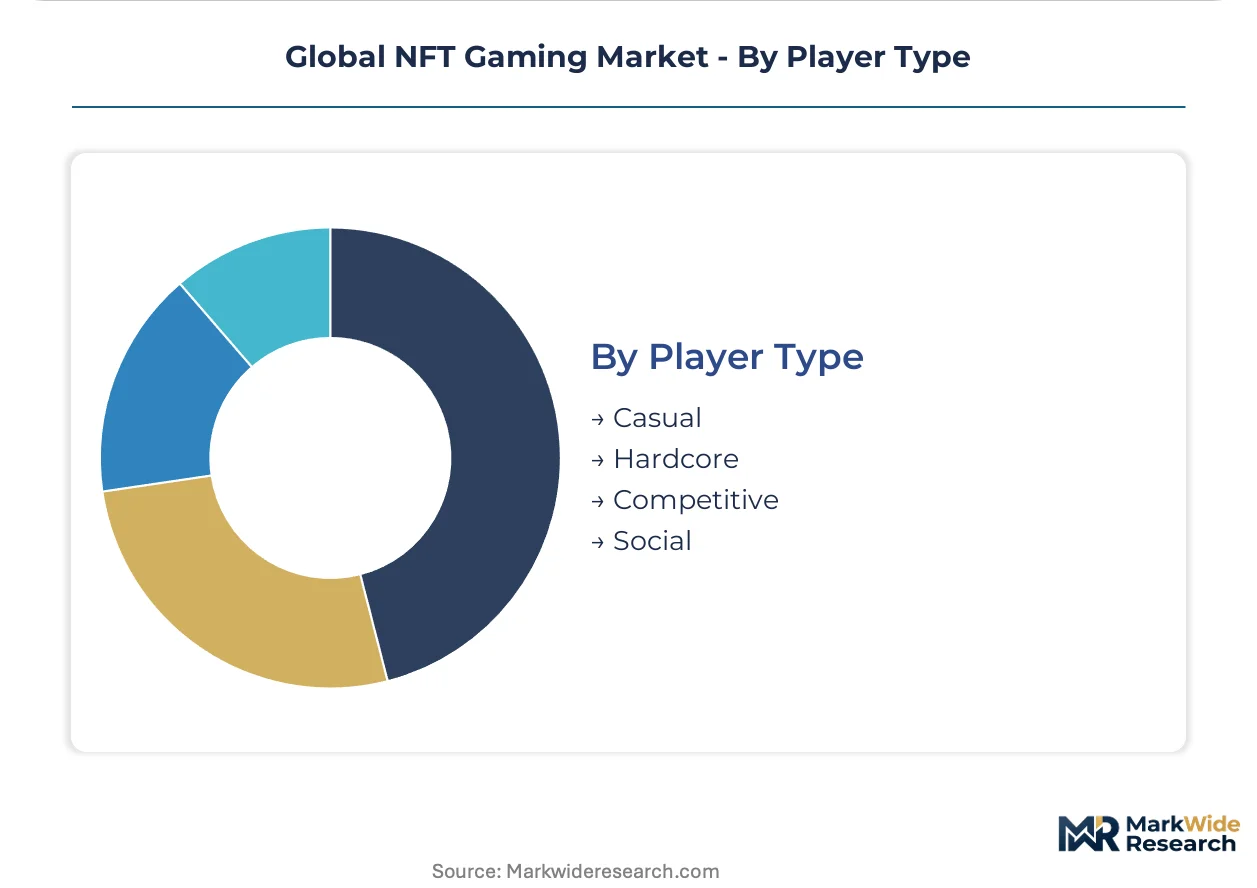
Platform choice dictates infrastructure requirements and transaction cost tolerances for NFT gaming publishers. Genre selection shapes asset complexity and recurring monetization depth. Player type determines wallet onboarding friction and long-term retention economics.
Platform Type:
Hardware accessibility and network latency requirements drive publisher platform prioritization decisions.
- PC:Desktop environments support complex wallet integrations and high-fidelity graphics rendering for asset-intensive RPGs. Korean and Vietnamese studios concentrate development here due to established esports infrastructure and fiber broadband penetration. Ethereum mainnet compatibility remains standard, though Layer-2 migration is accelerating.
- Mobile:Smartphone-first deployment dominates Southeast Asian player acquisition, with Android devices commanding volume leadership in the Philippines and Indonesia. Touch-optimized wallet interfaces and stablecoin-denominated microtransactions sustain daily active user engagement in emerging markets.
- Console:Closed ecosystem architectures from Sony and Nintendo impose strict cryptographic asset restrictions, limiting native NFT functionality to experimental third-party titles. Regulatory uncertainty in Japan and the US further constrains publisher investment.
- Web-based:Browser-native execution eliminates download friction and enables instant wallet connection through MetaMask and similar extensions. Southeast Asian internet cafes and shared-device environments favor this lightweight access model.
Mobile leads on scale; web-based gains share fastest among capital-constrained publishers.
Game Genre:
Asset customization depth correlates directly with player willingness to pay gas fees and hold volatile tokens.
- RPG:Character progression systems generate persistent item demand through equipment upgrades and cosmetic skins. South Korean studios leverage zero-knowledge rollups to eliminate transaction friction for equipment trading. Axie Infinity's breeding mechanics established the template for generative asset economies.
- Strategy:Land ownership and resource extraction mechanics create territorial competition with measurable economic returns. Vietnamese publishers concentrate here, deploying play-to-earn reward structures tied to territory control.
- Action:Fast-twitch gameplay limits on-chain interaction windows, pushing asset verification to post-match settlement layers. Brazilian and Mexican player bases show strongest engagement with stablecoin prize tournaments.
- Simulation:Virtual real estate and resource management attract non-traditional gamers seeking passive yield generation. Swiss regulatory clarity on asset-backed tokens supports issuance entities domiciled in Zug.
RPG leads on scale; strategy climbs fastest as guild-based asset pooling matures.
Monetization Model:
Upfront payment barriers versus lifetime value extraction tradeoffs reshape token distribution legal risk profiles.
- Free-to-Play:Zero entry cost maximizes user acquisition velocity in price-sensitive emerging markets. Philippine and Indonesian player bases convert through scholarship systems rather than direct NFT purchase. SEC securities classification risk compels US market exclusion or yield capping.
- In-Game Purchases:Item shop revenue decouples from token price volatility through stablecoin denomination. Japanese JVCEA registration requirements apply to exchange-like functionality within wallet-integrated marketplaces.
- Pay-to-Play:Upfront NFT minting generates immediate treasury funding but creates regulatory scrutiny under EU MiCA consumer disclosure mandates. Swiss FINMA guidelines offer clearer issuance pathways for premium-tier titles.
- Subscription:Recurring fiat revenue provides predictable cash flow independent of token market cycles. Asset leasing mechanics within subscription tiers face uncertain classification under MiCA reserve requirements.
Free-to-play leads on scale; in-game purchases expand most quickly as regulatory clarity emerges.
Player Type:
Time investment and skill commitment determine acceptable complexity thresholds for wallet management and guild participation.
- Casual:Fragmented session patterns favor simple asset ownership verification without active trading requirements. Mobile-first Southeast Asian demographics dominate this segment, with scholarship programs removing direct purchase barriers.
- Hardcore:Sustained daily engagement supports complex multi-chain portfolio management and guild leadership roles. Korean and Japanese player concentrations drive demand for high-skill competitive environments with substantial prize pools.
- Competitive:Tournament-focused participation requires stablecoin-denominated prize guarantees and transparent smart contract distribution. Brazilian unbanked populations access prize pools through PIX-integrated off-ramps.
- Social:Community-driven asset ownership emphasizes collective identity expression over individual financial returns. Philippine gaming collectives pool resources for shared virtual land acquisition.
Casual leads on scale; competitive climbs fastest as esports infrastructure tokenizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where NFT gaming studios domicile their token issuance entities, with Switzerland and Singapore attracting publishers fleeing stricter EU and US compliance costs. The cost-of-compliance gap between jurisdictions now exceeds operational savings from cheaper labor markets.
Philippines
Mobile-first gaming populations and scholarship-based asset pooling drive the world's highest per-capita play-to-earn participation rates. The country's central bank maintains watchlist status for virtual asset service providers without formal licensing mandates. Metro Manila hosts the densest concentration of gaming guilds managing rented NFT portfolios for asset-less players.
United States
SEC securities classification uncertainty compels developers to exclude American users or cap token yields, constraining domestic market development. The agency's enforcement actions against unregistered token distributions have triggered legal restructuring of reward mechanisms. Austin and San Francisco retain development talent despite regulatory headwinds, with studios pivoting toward infrastructure rather than token-issuing products.
Switzerland
FINMA's clearer virtual asset guidelines attract EU publishers relocating issuance entities to escape MiCA reserve requirements. The regulator's non-prescriptive approach to utility token classification reduces compliance overhead for RPG titles with complex in-game economies. Zug's Crypto Valley clusters legal and custody infrastructure serving cross-border token operations.
South Korea
Zero-knowledge rollup adoption concentrates among mid-core RPG studios seeking gas-free equipment trading mechanics. The country's Game Rating and Administration Committee maintains prohibition on blockchain elements in domestic game releases, forcing publishers to target export markets. Seoul's Pangyo Techno Valley houses the largest concentration of Layer-2 migration engineering talent.
Vietnam
Strategy genre development dominates as territorial competition mechanics align with local publisher expertise in resource extraction economies. The State Bank of Vietnam's draft crypto-asset framework remains pending, creating operational clarity gaps for token-denominated prize pools. Ho Chi Minh City anchors development studios serving Philippine and Indonesian player bases through mobile-optimized deployments.
Global NFT Gaming Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with infrastructure providers capturing recurring revenue while content studios face hit-driven volatility. The publisher base concentrates around three archetypes: sidechain operators monetizing transaction throughput, multi-chain portfolio holders diversifying ecosystem exposure, and zero-knowledge specialists eliminating end-user gas fees. M&A activity targets wallet infrastructure and security auditing capabilities, while geographic expansion prioritizes regulatory clarity over market size.
Among infrastructure-centric operators, Sky Mavis, Animoca Brands, and Immutable occupy distinct positions within the competitive hierarchy. Sky Mavis exemplifies the vertically integrated sidechain model, controlling both the Ronin network and flagship content properties. Animoca Brands represents multi-chain portfolio diversification, holding equity and token positions across Ethereum, Polygon, and Solana ecosystems rather than single-chain dependence. Immutable anchors the zero-knowledge rollup specialization, licensing gas-free transaction infrastructure to third-party RPG studios. These three entities collectively illustrate how technical architecture choices—sidechain versus multi-chain versus rollup—now determine competitive positioning more than content quality alone.
| Leading Market Players |
|---|
| Sky Mavis |
| Animoca Brands |
| Dapper Labs |
| Immutable |
| The Sandbox |
| Axie Infinity |
| Illuvium |
| Mythical Games |
| Gala Games |
| Others |
Supply & Pricing Matrix
The EU's MiCA framework gates qualified supply for premium-tier token issuance, compelling publishers to relocate entities to Switzerland or Singapore to access compliant infrastructure and sustain pricing power for regulated asset classes.
Pricing Analysis
Capacity additions in South Korea and Vietnam are reshaping price floors for gas-free transaction infrastructure as zero-knowledge rollup providers compete for RPG studio contracts. Pricing stratifies across premium, standard, and economy tiers based on certification level under Swiss FINMA guidelines and customization depth for guild-managed asset pools. Cost compression in the standard tier is intensifying because Layer-2 providers are eliminating end-user gas fees to capture volume. Casual mobile-first players in Southeast Asia exhibit the highest price sensitivity, while hardcore competitive gamers in Japan and Korea accept premium pricing for guaranteed stablecoin prize pools.
Supply Chain Analysis
Freight costs for specialized blockchain security auditing talent command premium compensation as exploit vulnerabilities in token bridges have accumulated substantial losses. Supply concentrates in the Philippines for gaming guild operations, South Korea for zero-knowledge engineering, and Switzerland for regulatory-compliant issuance entities. Infrastructure draws from Ethereum mainnet compatibility layers, Layer-2 rollup sequencers, and sidechain validator networks. Single-source vulnerability in bridge smart contracts creates systemic exposure for cross-chain asset transfers. Distribution runs through wallet-integrated marketplaces and peer-to-peer scholarship systems rather than traditional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as player guilds displace individual ownership and concentrate buying power toward premium-specification virtual assets with verified scarcity and compliant issuance frameworks.
For Market Incumbents: Deepen backward integration into Layer-2 infrastructure to capture transaction fee revenue and defend against rollup specialists commoditizing gas-free gameplay. Secure Swiss FINMA-compliant issuance entities before MiCA reserve requirements fully phase in. Invest in security auditing capabilities as exploit losses have elevated specialist talent premiums.
For New Entrants and Emerging Players: Mobile wallet providers represent the most penetrable channel partner type for bypassing download friction in Southeast Asian internet cafes. Target Brazil's unbanked gamer population through PIX-integrated stablecoin prize pools. Pursue white-label zero-knowledge rollup licensing from established infrastructure providers rather than building proprietary chains.
For Investors and Strategic Acquirers: Roll-up economics work for security auditing specialists because smart contract exploit losses have concentrated demand for verified blockchain security talent. Long-term viability hinges on regulatory clarity maturing across the EU MiCA implementation window. Monitor JVCEA registration pathways in Japan as the inflection indicator for East Asian institutional capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Layer-2 Infrastructure Licensing | Zero-knowledge rollup providers capture recurring revenue from RPG studios eliminating gas fees. |
| Regulatory Entity Relocation | Swiss FINMA guidelines reduce compliance overhead for publishers fleeing EU MiCA reserve mandates. |
| Guild Partnership Programs | Philippine gaming collectives pool NFT buying power and distribute earnings through smart contracts. |
| Security Auditing Acquisition | Bridge exploit losses exceeding billions concentrate demand for specialized blockchain security talent. |
| Stablecoin Prize Pool Integration | Brazil's PIX off-ramp infrastructure enables unbanked gamers to access tournament winnings without traditional banking. |
Research Methodology
Coverage spans Southeast Asia, East Asia, Europe, and Latin America, with primary inputs from each region combining structured interviews with blockchain infrastructure engineers, gaming guild operators, regulatory compliance officers, and token economics designers. Secondary validation draws from SEC enforcement filings, EU MiCA regulatory texts, Swiss FINMA guidance documents, and national central bank watchlist announcements. Bottom-up triangulation across player wallet activity data and top-down reconciliation against publisher token issuance disclosures ensures cross-verification.
Rate-of-change decomposition separates volume growth from value compression across the projection horizon. Segmentation dimensions modeled include platform type, game genre, monetization model, and player archetype alongside regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to historical Layer-2 adoption patterns and guild formation velocity. Forecast inputs incorporate MiCA implementation timelines and JVCEA registration pipeline status.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to securities classification rulings by the SEC and reserve requirement interpretations under EU MiCA. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
VR Racing Gaming Market
Gaming
Global Online Board Games Market
Gaming
Gaming Gadgets Market
Gaming
Europe Video Game Software Market
Gaming
Gaming Hardware Market
Gaming
Europe Gaming Peripherals Market
Gaming
AAA Games Market
Gaming
MMORPG Gaming Market
Gaming
Gaming As a Service Market
Gaming
Asia-Pacific Casino Gambling Market
Gaming
Advanced Digital Gaming Market
Gaming
Galgames Market
Gaming
Shooter Game Market
Gaming
Videogames Market
Gaming
Game Engine Management Market
Gaming
Asia-Pacific Video Game Software Market