
 Simulation Video Game Market | 2026-2036
Simulation Video Game Market Size, Share, and Industry Trends Forecast 2026-2036
Simulation Video Game Market Insights
Modular content bundling is pivoting how publishers package simulation experiences, splitting base games from seasonal expansions and creator-tool add-ons. Electronic Arts leverages its live-service infrastructure to sustain recurring revenue across The Sims franchise. Paradox Interactive anchors its position through deep DLC ecosystems that extend player lifetime value. SCS Software competes in vehicle simulation by dominating the North American and European trucking sub-genres with disciplined geographic expansion.
A simulation video game replicates real-world systems, activities, or environments through algorithmic modeling, physics engines, and user-driven scenario generation, serving entertainment, training, and educational purposes. Life simulation titles command established margin pools through persistent content cycles and community-created assets. Vehicle simulation represents the fastest-growing game type as hardware peripheral ecosystems and esports leagues deepen player investment. Platform segmentation shows PC sustaining premium monetization while Virtual Reality emerges as a high-engagement, low-penetration frontier for cockpit and construction experiences.
The ESRB rating system in the United States and PEGI framework across European markets shape content boundaries and marketing channels for simulation publishers targeting younger demographics. China's SAMR and NPPA approval processes govern market access, requiring localization compliance and content modification for domestic release. Stakeholders must monitor regulatory friction between creative authenticity and jurisdiction-specific content standards as cloud streaming and cross-platform distribution blur traditional territorial controls.
Market Dynamics
Live-service monetization architectures are restructuring how publishers capture value, replacing upfront retail purchases with persistent revenue streams through seasonal content drops and creator-marketplace commissions.
Growth Catalysts
- China's MIIT approval pathway:Domestic content localization mandates create captive demand for compliant foreign titles, accelerating publisher investment in Simplified Chinese localization teams and regional server infrastructure.
- Educational procurement:Vocational training institutions and STEM curricula adoption of simulation platforms for heavy machinery certification and medical procedure rehearsal expands institutional licensing revenue pools.
- Peripheral hardware ecosystems:Force-feedback steering wheels, flight yokes, and haptic construction controllers deepen player investment and extend session duration in vehicle and equipment simulation sub-genres.
Market Restraints
- Silicon supply concentration:GPU and CPU fabrication bottlenecks in Taiwan and South Korea constrain hardware refresh cycles that drive simulation fidelity upgrades and replacement demand.
- China's NPPA content modification:Skeleton removal, blood color alteration, and time-play restrictions for minors impose localization costs and release delays that compress foreign publisher margins.
- Cloud infrastructure costs:Real-time physics computation and multiplayer synchronization requirements resist cost-efficient streaming delivery, limiting platform expansion beyond dedicated local hardware.
Strategic Opportunities
- India's BIS certification pathway:Emerging middle-class hardware adoption and English-language accessibility create first-mover advantages for publishers establishing localized pricing and payment infrastructure.
- Virtual Reality cockpit convergence:Headset hardware maturation combined with seated play ergonomics is automating immersive training applications for aviation and emergency response sectors.
- EU CSRD sustainability reporting:Corporate ESG mandates drive demand for supply chain and carbon-footprint simulation tools for executive training and stakeholder communication.
Industry Challenges
- Physics engine talent scarcity:Specialized computational geometry and fluid dynamics expertise required for authentic vehicle handling and material deformation remains concentrated among legacy simulation studios.
- Cross-platform certification friction:Sony, Microsoft, and Nintendo hardware validation timelines create staggered release windows that fragment multiplayer communities and marketing momentum.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Simulation Video Game Market |
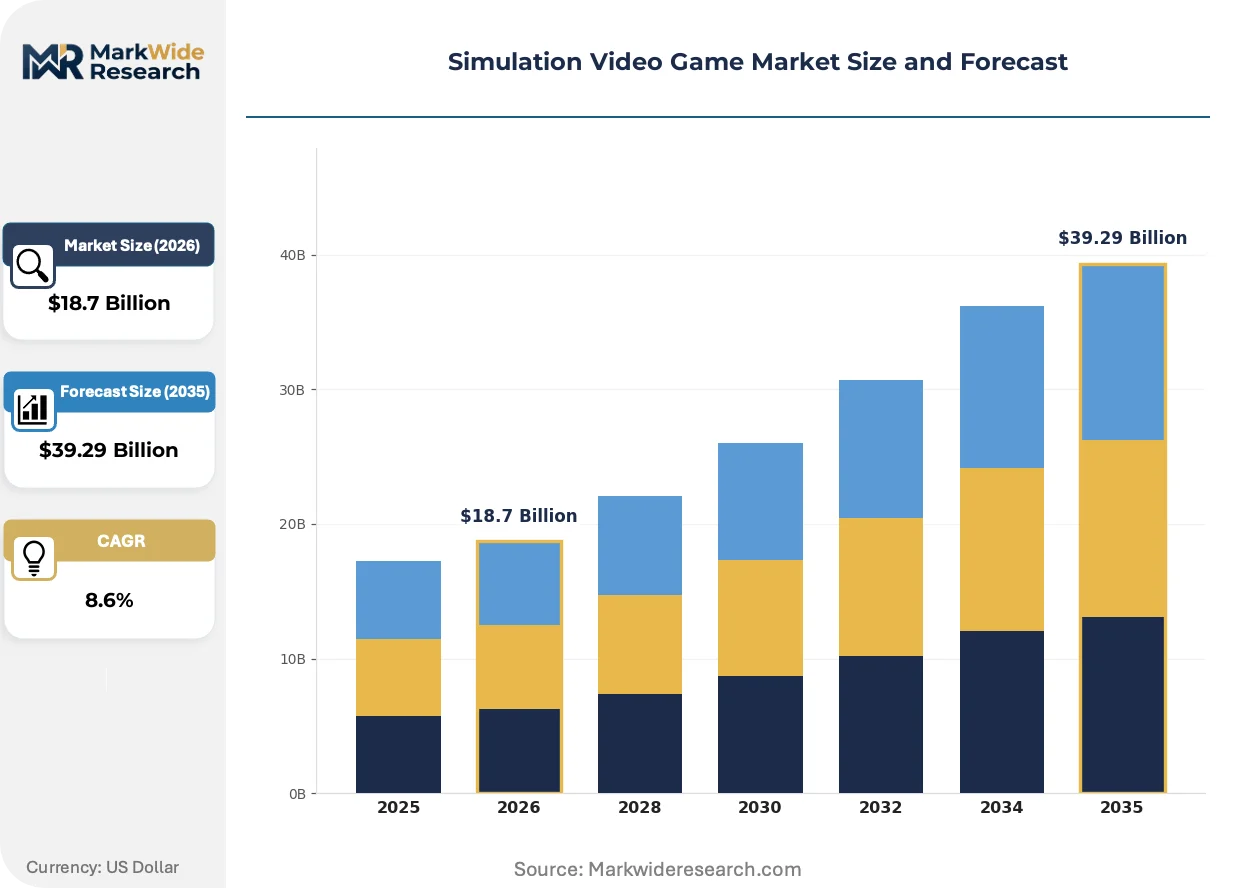
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Life Simulation, Vehicle Simulation, Construction Simulation, Flight Simulation Platform: PC, Console, Mobile, Virtual Reality Target Audience: Casual Gamers, Hardcore Gamers, Educational Institutions, Professional Simulators Monetization Model: Premium, Freemium, Subscription, In-Game Purchases |
| Companies Covered | Electronic Arts, Ubisoft Entertainment, Microsoft, Sony Interactive Entertainment, Nintendo, Paradox Interactive, SCS Software, Frontier Developments, GIANTS Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Simulation Video Game Market Trends and Innovations
Generative systems are compressing content production pipelines, enabling player-driven scenario generation that reduces publisher dependency on handcrafted expansion packs while extending engagement half-life.
Procedural terrain and traffic systems is automating world-scale environment creation for open-world vehicle simulation. SCS Software and competitors adopt these tools to accelerate map expansion across previously uneconomical geographic regions. The technology compresses artist-hour requirements from months to weeks for comparable land-mass coverage.
China's SAMR age-rating enforcement and real-name verification mandates reshape monetization architecture for titles seeking domestic release. Publishers must decouple cosmetic economies from randomized reward mechanics and implement hard spending caps for minor accounts. Free-to-play simulation titles face the most severe compliance-driven revenue model reconstruction.
Creator-marketplace revenue sharing is displacing first-party expansion packs as the primary content velocity engine. The Sims Workshop and comparable platforms enable amateur asset creators to capture direct payments from players, with publishers extracting platform fees rather than bearing production risk. North American and Western European player bases demonstrate highest willingness-to-pay for community-crafted content.
Simulation Video Game Market Segmentation
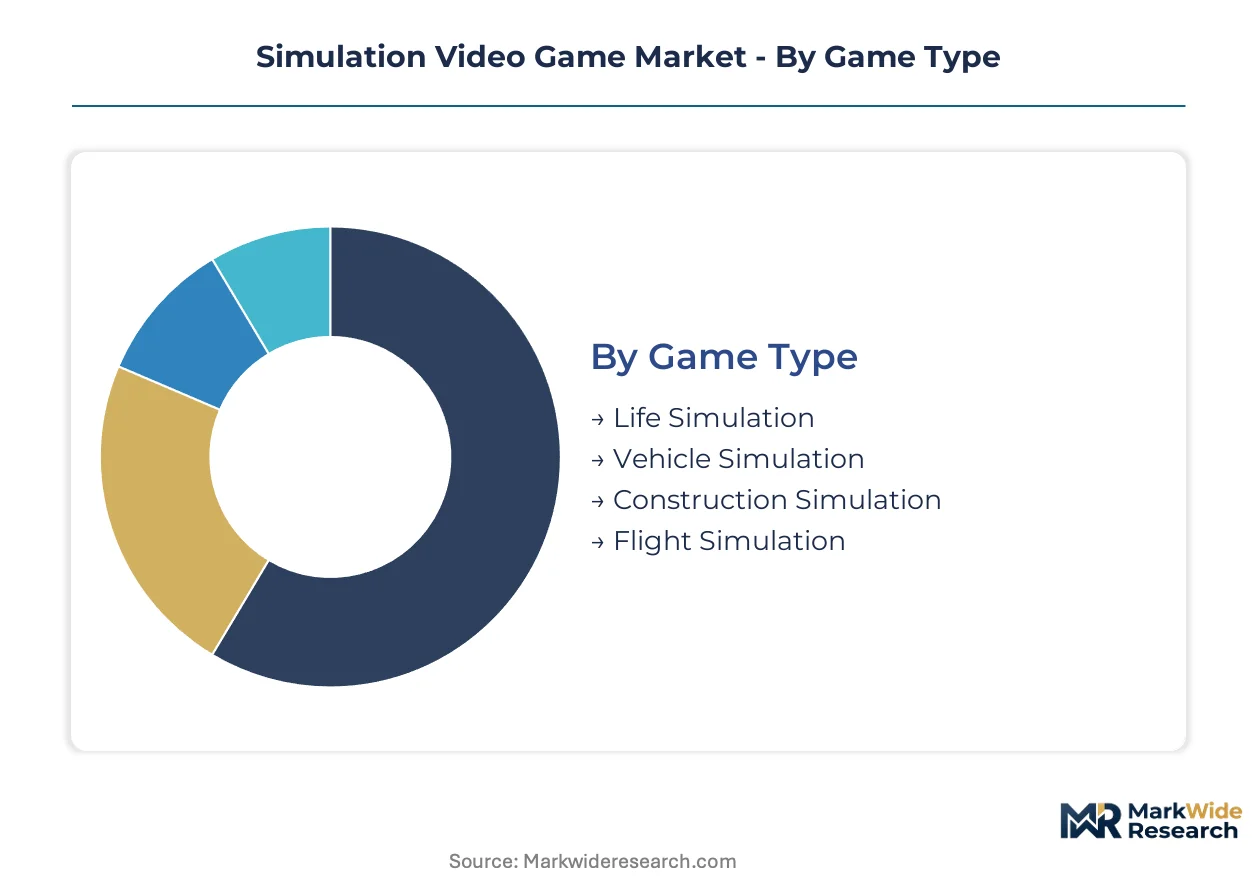
Simulation publishers configure product architecture around distinct player investment profiles and hardware capabilities. Segmentation determines monetization depth, content velocity, and peripheral ecosystem compatibility across entertainment and professional training use cases.
Game Type:
Player session duration and hardware attachment intensity separate buyers across simulation genres.
- Life Simulation:Persistent avatar systems and social relationship mechanics sustain multi-year engagement cycles. Demand concentrates in the United States and Western Europe where creator-marketplace participation generates recurring platform fees for publishers.
- Vehicle Simulation:Physics-engine fidelity requirements and force-feedback peripheral ecosystems deepen player capital expenditure. North American and European trucking sub-genres dominate volume through licensed vehicle partnerships and map expansion DLC.
- Construction Simulation:Heavy equipment licensing agreements and procedural terrain deformation mechanics define technical scope. Institutional procurement for vocational training supplements consumer demand.
- Flight Simulation:FAA and EASA certification alignment for training applications creates dual-use revenue streams. Cockpit peripheral ecosystems and real-world navigation data licensing constrain independent developer entry.
Life Simulation leads volumes today; Vehicle Simulation is gaining share fastest.
Platform:
Hardware refresh cycles and input modality flexibility shape publisher technical investment priorities.
- PC:Open hardware architecture enables mod support and peripheral driver customization that sustains premium pricing tiers. Steam Workshop integration and direct-to-consumer distribution preserve margin capture for independent studios.
- Console:Sony PlayStation and Microsoft Xbox certification timelines standardize quality benchmarks but fragment multiplayer communities across staggered release windows. Physical retail presence sustains discoverability for family-oriented simulation titles.
- Mobile:Touch-control limitations constrain physics fidelity, tilting portfolio composition toward management-layer abstraction rather than direct manipulation mechanics. China's MIIT approval requirements govern release timing for foreign publishers.
- Virtual Reality:Seated cockpit ergonomics and hand-tracking controller maturation automate immersive training applications for aviation and emergency response sectors. Hardware penetration remains below mass-market thresholds despite engagement depth advantages.
PC anchors revenue concentration; Virtual Reality is climbing the fastest despite low base penetration.
Target Audience:
Skill acquisition intent and time availability differentiate player willingness to tolerate steep learning curves.
- Casual Gamers:Short-session design patterns and forgiving failure mechanics prioritize accessibility over authenticity. Mobile and console platforms concentrate this demand through family-sharing features and simplified control schemes.
- Hardcore Gamers:Deep systems mastery and community-driven content creation sustain extended engagement half-lives. PC platform dominance reflects mod support tolerance and peripheral investment willingness.
- Educational Institutions:Curriculum alignment requirements and institutional procurement cycles extend sales timelines but reduce price sensitivity. Vocational certification partnerships in Germany and Australia validate simulation fidelity for regulatory bodies.
- Professional Simulators:Regulatory compliance mandates and liability considerations demand deterministic physics outcomes rather than entertainment-optimized approximations. Aviation and medical sub-segments concentrate procurement authority.
Casual Gamers dominate unit volumes; Educational Institutions are expanding most quickly as STEM adoption accelerates.
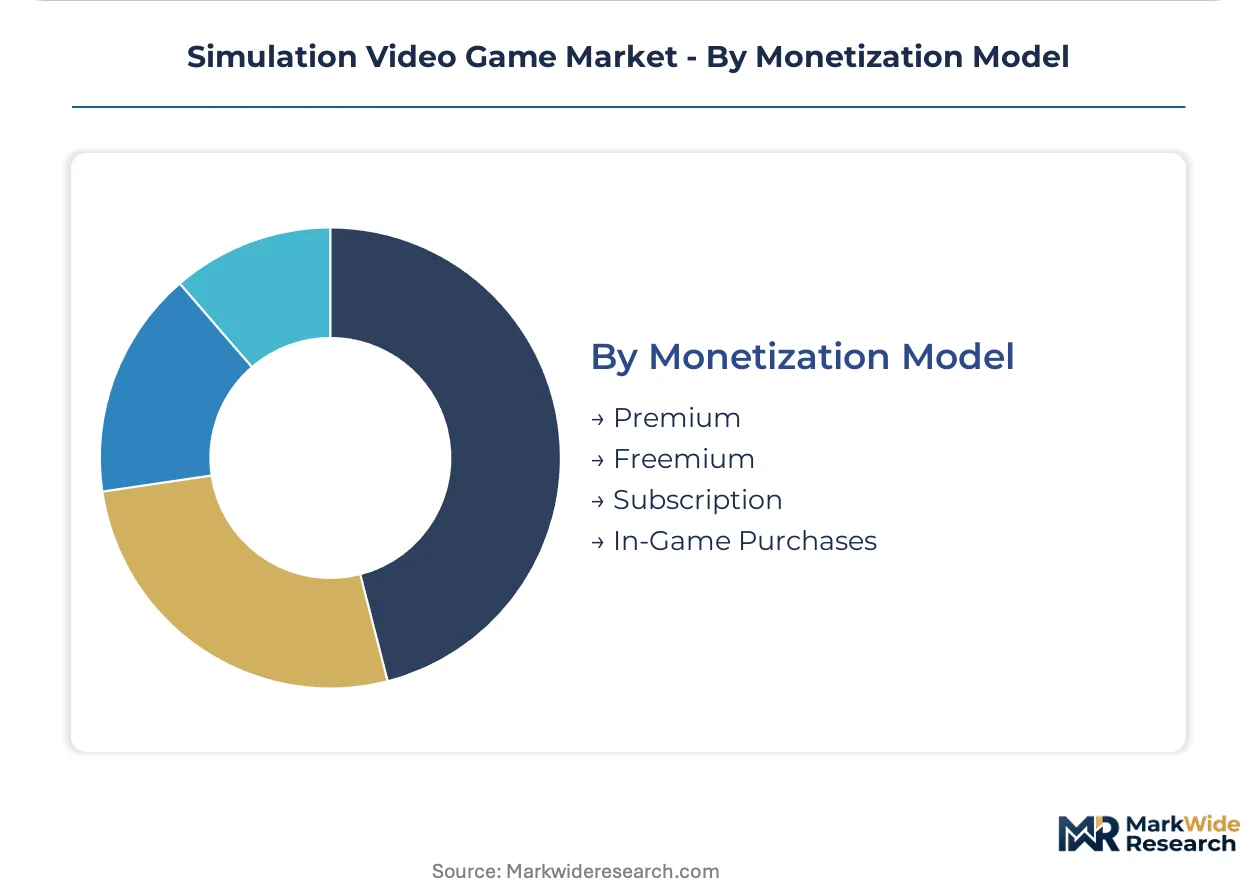
Monetization Model:
Revenue predictability and player acquisition friction trade off across upfront and ongoing payment structures.
- Premium:Single-transaction ownership models preserve content completeness but forfeit ongoing service revenue. Boxed retail and digital storefront presence sustain discovery for established franchises.
- Freemium:Zero-entry pricing expands addressable audience but requires careful progression pacing to convert non-paying users. China's SAMR spending caps for minors constrain revenue architecture for domestic release.
- Subscription:Catalog access bundling reduces individual title risk while capturing predictable recurring revenue. Xbox Game Pass and PlayStation Plus integration extends simulation title longevity beyond traditional sales curves.
- In-Game Purchases:Cosmetic and convenience microtransactions sustain live-service economics without gameplay fragmentation. Creator-marketplace revenue sharing displaces first-party expansion pack production risk.
Premium retains margin leadership; Subscription is capturing share fastest through platform bundling strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The simulation video game industry traces its commercial roots to United States garage developers and early PC gaming clusters that pioneered physics engines and sandbox mechanics during the 1980s and 1990s.
United States
PC and console ecosystems sustain premium monetization through Steam Workshop integration and direct-to-consumer distribution. The ESRB rating system shapes content boundaries for younger demographics. Seattle and Austin clusters host established studios deploying live-service architectures for persistent revenue streams.
China
Domestic hardware adoption and esports venue expansion drive demand for vehicle and life simulation titles. MIIT content approval requirements and NPPA age-rating mandates impose localization costs and release delays. Shanghai and Shenzhen development hubs concentrate regional server infrastructure for compliant foreign publishers.
Germany
Vocational training institutions procure construction and vehicle simulation platforms for heavy machinery certification. The PEGI framework governs marketing channels across European markets. Munich and Hamburg studios anchor the European trucking sub-genre through licensed vehicle partnerships.
Japan
Console platform loyalty sustains family-oriented simulation franchises through physical retail presence. METI standards influence hardware peripheral certification timelines. Tokyo and Osaka metropolitan areas concentrate flight simulation development aligned with aviation training applications.
United Kingdom
Creator-marketplace participation generates recurring platform fees through community-crafted content distribution. The CMA reviews platform bundling strategies affecting subscription catalog access. Cambridge and Guildford clusters specialize in procedural terrain systems for open-world vehicle simulation.
Simulation Video Game Market Competitive Landscape
Premium-margin players sit above commodity-margin players across content velocity and peripheral ecosystem depth. The market structures around three tiers: live-service specialists sustaining decade-long franchises, DLC ecosystem architects maximizing player lifetime value, and geographic niche dominators capturing sub-genre loyalty. Consolidation pressures concentrate among mid-tier studios facing physics engine talent scarcity. Dominant competitive moves include strategic partnerships with hardware peripheral manufacturers and portfolio diversification into educational licensing verticals.
Within the live-service tier, Electronic Arts exemplifies recurring revenue architecture through persistent content cycles. Paradox Interactive occupies a position as a DLC ecosystem specialist extending engagement through modular expansion packs. SCS Software anchors the geographic niche category with disciplined regional map expansion. These three represent distinct archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Electronic Arts |
| Ubisoft Entertainment |
| Microsoft |
| Sony Interactive Entertainment |
| Nintendo |
| Paradox Interactive |
| SCS Software |
| Frontier Developments |
| GIANTS Software |
| Others |
Pricing and Supply Chain Analysis
Physics-engine talent concentration in Eastern European development clusters compresses labor-cost differentials between premium-tier live-service titles and mid-market releases, widening pricing spreads as studios compete for scarce computational geometry expertise.
Pricing Analysis
Subscription-anchored hybrid models dominate revenue architecture, combining base-game access with seasonal content passes and creator-marketplace commission tiers. Price differentiation rests on peripheral ecosystem depth and live-service infrastructure maturity, with force-feedback hardware bundles commanding substantial premiums. Pricing pressure stems from cloud infrastructure costs resisting efficient streaming delivery, squeezing margins on multiplayer-synchronized experiences. Casual mobile segments exhibit highest price sensitivity, while professional training procurement demonstrates lowest elasticity due to regulatory certification requirements.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for GPU and CPU fabrication, constraining hardware refresh cycles that drive simulation fidelity upgrades. Raw material dependencies span silicon wafers, rare-earth magnets for haptic peripherals, and high-bandwidth memory modules. Tariff exposure on semiconductor imports from concentrated Asian fabrication hubs threatens peripheral hardware pricing stability. Distribution runs through Steam Workshop and platform-holder digital storefronts, with direct-to-consumer channels preserving margin capture for independent studios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Simulation video games constitute a late-cycle quality market where player investment in peripheral ecosystems and creator-marketplace participation locks in premium-tier demand, with educational procurement accelerating toward FAA and EASA-aligned training specifications.
For Market Incumbents: Anticipate regulatory fragmentation between China's NPPA content modification mandates and Western rating frameworks by maintaining parallel localization pipelines. Consolidate physics-engine talent through acquisition of Eastern European specialist studios before competitive bidding escalates. Prioritize backward integration into peripheral hardware partnerships to secure force-feedback ecosystem control against substitute input technologies. For New Entrants and Emerging Players: Direct-to-creator distribution channels offer lowest-friction entry for vocational training modules targeting India's BIS certification pathway and English-language accessibility. White-space concentrates in construction simulation for emerging market infrastructure development, where institutional procurement cycles reduce customer acquisition costs. Lead with modular SaaS pricing to bypass upfront capital barriers in price-sensitive educational verticals. For Investors and Strategic Acquirers: Platform holders with subscription catalog bundling strategies are the most active acquirer in this space, seeking live-service infrastructure to extend content velocity. Long-term viability favors studios with proprietary physics engines and established DLC ecosystems over asset-assembly operations. Monitor China's MIIT approval velocity as inflection indicator for foreign publisher margin compression and regional server infrastructure investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Live-Service Infrastructure Investment | Electronic Arts sustains decade-long franchise economics through persistent content cycles and creator-marketplace commission extraction. |
| DLC Ecosystem Expansion | Paradox Interactive extends player lifetime value through modular expansion packs that deepen systems mastery engagement. |
| Peripheral Hardware Partnership | Force-feedback steering wheel and flight yoke bundling locks in vehicle simulation player investment and extends session duration. |
| Educational Licensing Vertical | FAA and EASA certification alignment creates dual-use revenue streams for aviation training applications beyond entertainment. |
| Procedural Terrain Technology | SCS Software compresses artist-hour requirements for map expansion across previously uneconomical geographic regions. |
Research Methodology
Multiple input streams — executive interviews with live-service operations leads, procurement directors at vocational training institutions, and platform-holder partnership managers — were reconciled against secondary validation from Steam revenue estimates, MIIT approval filings, and ESRB rating databases. Primary fieldwork captured monetization architecture decisions and localization cost structures across US, Chinese, and German market entry strategies. Bottom-up title-level revenue modeling and top-down market sizing triangulated volume and value outputs.
Data-stream reconciliation anchored forecast construction across game type, platform, target audience, and monetization model segmentation dimensions. CAGRs were derived from trend-line extrapolation of hardware refresh cycles, educational procurement adoption curves, and creator-marketplace revenue share trajectories. Physics-engine talent scarcity and cloud infrastructure cost trajectories served as simulation-specific forecast inputs throughout the projection horizon.
The model assumes a particular technology adoption path for virtual reality headset penetration; alternative pathways for seated cockpit ergonomics maturation would alter the outlook for immersive training application revenue splits. Forecasts reflect assumptions regarding China's NPPA regulatory enforcement consistency and silicon supply chain normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Playstation Network (PSN) Market
Gaming
Puzzle Video Game Market
Gaming
Casino Gaming Equipment Market
Gaming
Flat Gaming Monitors Market
Gaming
Traditional Casual Games Market
Gaming
Serious Games Market
Gaming
Arcade Games Market
Gaming
Australia Casino Tourism Market
Gaming
Gaming Hardware Market
Gaming
Global Online Simulation Games Market
Gaming
VR Racing Gaming Market
Gaming
United States Gaming Accessories Market
Gaming
Australia Gaming Gadgets Market
Gaming
Shooter Game Market
Gaming
Gaming Gadgets Market
Gaming
Global Game Testing Service Market