
 Gaming Simulator Market | 2026-2036
Gaming Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
Gaming Simulator Market Intelligence
The capital-intensity divergence between compact home setups and full-motion commercial platforms is collapsing as component costs fall and software-defined motion algorithms mature. CXC Simulations leverages its aerospace heritage to dominate the ultra-premium consumer segment with FAA-certified home cockpit architectures. D-BOX Technologies Inc. anchors the theatrical and arcade channel through its proprietary haptic actuation systems deployed across cinema chains and esports venues. CKAS Mechatronics Pty Ltd. competes aggressively in the Asia-Pacific training market with locally manufactured motion bases that undercut European rivals on landed cost.
Gaming simulators are electromechanical systems that replicate vehicle or environmental dynamics through integrated motion platforms, visual projection arrays, and control loading mechanisms, typically operating at refresh rates exceeding 120 Hz with latency below 20 milliseconds to prevent simulator sickness. Their primary commercial purpose spans entertainment immersion, certified pilot and driver training, and rehabilitation therapy where safe repetition of motor tasks accelerates recovery. Hardware retains the largest revenue share due to the irreplaceable physicality of motion bases, force-feedback steering assemblies, and cockpit enclosures, though haptic feedback software layers are capturing disproportionate margin expansion as recurring licensing models replace perpetual sales. The entertainment application remains mature in developed markets while professional training and therapeutic research segments accelerate fastest where regulatory certification creates switching costs.
The FAA governs flight simulator qualification levels in the United States, directly determining which devices can log creditable training hours toward pilot certification and thus shaping procurement criteria for aviation academies. The EU AI Act and CE marking requirements under the Machinery Directive impose conformity obligations on simulators employing adaptive algorithms or autonomous motion profiling, particularly affecting European manufacturers like Cruden and Vesaro. ISO 9001 and ISO 13485 certifications increasingly gate institutional sales in medical rehabilitation and defense procurement channels. Stakeholders must monitor how emerging neurodiversity accommodation standards and evolving esports governance frameworks reshape hardware specifications and liability exposure.
Market Dynamics
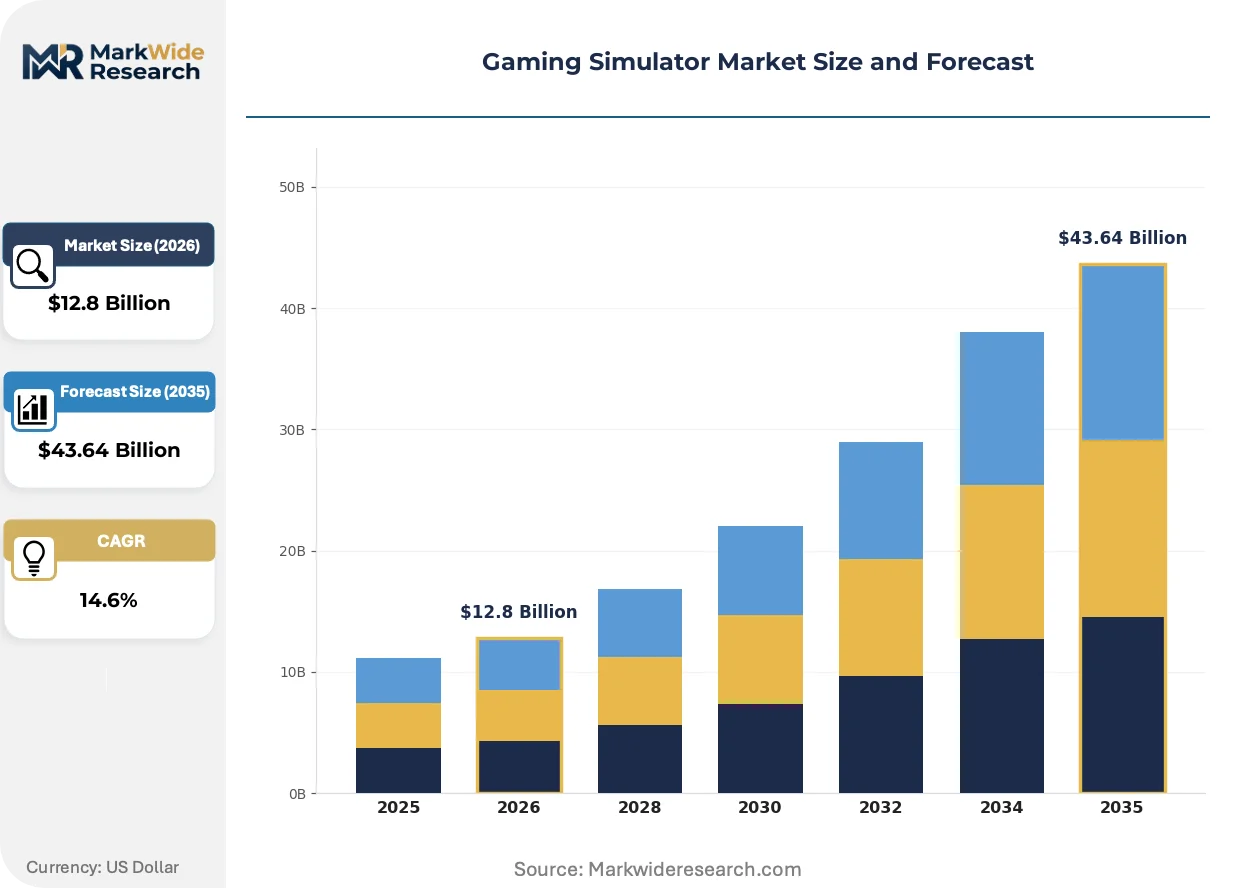
Software-defined motion algorithms are collapsing the cost barrier between compact consumer setups and full-motion commercial platforms, redrawing competitive boundaries across the entire hardware stack.
Growth Catalysts
- FAA certification pathways:The FAA's expanded qualification levels for advanced aviation training devices allow flight schools to log creditable hours on lower-cost simulators, accelerating institutional procurement cycles.
- Defense procurement expansion:United States military training centers are scaling simulator deployments for pilot readiness and vehicle crew certification, creating sustained demand for high-fidelity motion platforms.
- Cloud-rendered visualization:Edge computing architectures now stream photorealistic environments to lower-specification hardware, democratizing access to previously workstation-dependent fidelity tiers.
Market Restraints
- Precision actuator supply concentration:German and Japanese specialty motor manufacturers control critical components for six-degree-of-freedom motion bases, exposing buyers to extended lead times and currency volatility.
- CE marking complexity under EU AI Act:Simulators employing adaptive motion profiling face expanded conformity assessment obligations, lengthening European market entry timelines for non-EU manufacturers.
- Substitute training modalities:Extended reality headsets with inside-out tracking deliver adequate spatial immersion for basic procedural training at fraction of installed simulator cost.
Strategic Opportunities
- India's aviation training infrastructure:The Directorate General of Civil Aviation's expanding approved training organization network creates addressable demand for certified flight simulation devices in underserved secondary cities.
- Neurodiversity accommodation standards:Emerging accessibility mandates for sensory-sensitive interfaces open product differentiation avenues through adjustable motion intensity and customizable haptic feedback profiles.
- Esports venue haptic integration:Cinema chains and dedicated esports arenas are retrofitting spectator seating with synchronized motion actuators, creating a theatrical distribution channel distinct from home or institutional sales.
Industry Challenges
- Embedded systems engineering talent scarcity:The intersection of real-time control software, mechanical dynamics, and safety-critical certification requirements constrains development velocity for mid-tier manufacturers.
- ISO 13485 compliance timeline:Medical rehabilitation applications require quality management system certification that adds 12-18 months to product commercialization schedules.
- Legacy simulator integration friction:Training centers with decade-old host computers face data bus incompatibility when upgrading to modern visual or motion systems, forcing costly infrastructure overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaming Simulator Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $43.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Accessories, Sensor End User: Individual Gamers, Arcade Owners, Educational Institutions, Professional Trainers Technology: Virtual Reality, Augmented Reality, Motion Tracking, Haptic Feedback Application: Entertainment, Training, Research, Therapy |
| Companies Covered | CXC Simulations, D-BOX Technologies Inc., CKAS Mechatronics Pty Ltd., 3D Perception, Playseat, RSEAT Ltd., Vesaro, Eleetus, Cruden, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaming Simulator Market Strategic Shifts & Innovations
Convergence between entertainment-grade immersion expectations and professional certification requirements is forcing hardware architectures to serve dual-use specifications from initial design.
Stewart platform mechanics are yielding to cable-driven parallel kinematics in mid-range motion bases. Flight schools and driver training centers in Australia and Canada are adopting these lighter structures for easier facility installation. This physical architecture is decomposing the traditional trade-off between payload capacity and real estate footprint, enabling motion-equipped training in converted retail spaces previously excluded by structural load limits.
The EU Ecodesign for Sustainable Products Regulation now mandates modular hardware design and energy consumption disclosures for electromechanical equipment sold in member states. Simulator manufacturers must redesign power supplies and motion amplifiers for circular material recovery. European producers including Dutch and Swedish specialists are accelerating in-house recycling program development to maintain market access.
Subscription licensing for haptic feedback software layers is displacing perpetual seat sales in institutional procurement. Aviation academies and defense training centers in the United States are negotiating multi-year software access agreements that bundle continuous algorithm updates with hardware maintenance. This purchasing pattern shift concentrates vendor relationships and raises switching costs for buyers seeking to migrate between ecosystem providers.
Gaming Simulator Market Segmentation
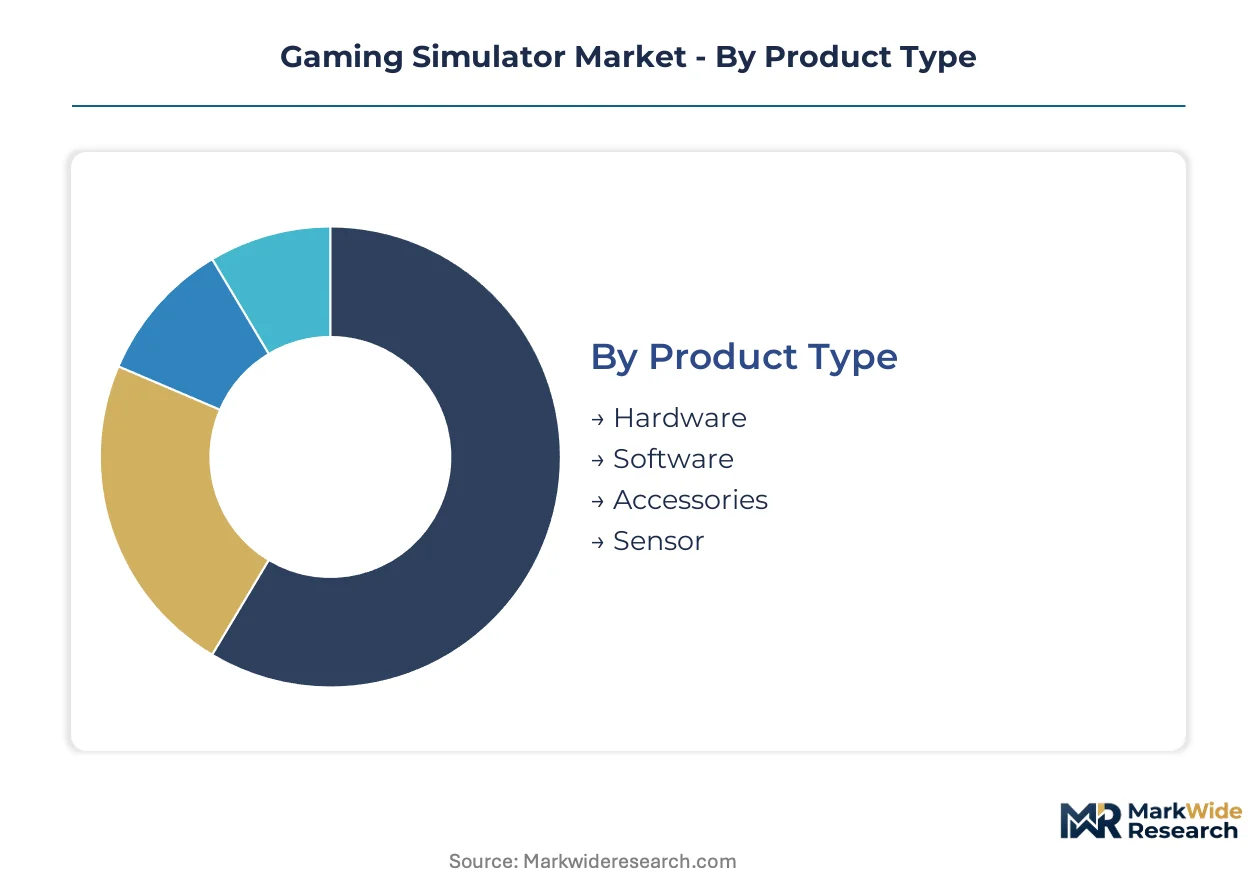
Segmentation in gaming simulators reveals how substitute technologies pressure different product tiers unevenly. Understanding these pressure gradients helps vendors allocate R&D resources and anticipate which customer groups will migrate to lower-cost alternatives first.
Product Type:
Motion bases and cockpit enclosures face the strongest substitution pressure from cloud-rendered visualization and extended reality headsets, while software layers demonstrate stickier recurring revenue models.
- Hardware:Integrated motion platforms, force-feedback steering assemblies, and cockpit enclosures constitute the physical foundation of simulator systems. Defense training centers in the United States and commercial flight schools in Australia are expanding procurement of FAA-certified hardware despite capital intensity. The irreplaceable physicality of six-degree-of-freedom motion bases sustains demand even as visualization commoditizes.
- Software:Real-time physics engines, haptic feedback algorithms, and scenario authoring tools operate on subscription licensing models that displace perpetual sales. Aviation academies negotiate multi-year software access agreements bundling continuous algorithm updates with hardware maintenance, raising switching costs and concentrating vendor relationships.
- Accessories:Pedal sets, yokes, throttle quadrants, and button boxes extend hardware ecosystem functionality.
- Sensor:Inertial measurement units, optical tracking arrays, and load cells capture user input and motion platform feedback.
Hardware retains volume leadership; software holds the steepest expansion curve through recurring licensing conversion.
End User:
Cost tier stratification separates institutional buyers with certification requirements from price-sensitive consumers where substitute modalities gain traction fastest.
- Individual Gamers:Home cockpit enthusiasts and sim racing hobbyists drive demand for compact, affordable setups. Extended reality headsets with inside-out tracking deliver adequate spatial immersion for basic procedural training at fraction of installed simulator cost, pressuring this segment most directly.
- Arcade Owners:Location-based entertainment venues deploy coin-operated racing and flight simulators requiring durability and high throughput. Cinema chains and dedicated esports arenas are retrofitting spectator seating with synchronized motion actuators, creating a theatrical distribution channel distinct from home or institutional sales.
- Educational Institutions:Universities and technical colleges use simulators for STEM education and vocational training programs.
- Professional Trainers:Flight schools, military training centers, and driver academies require certified devices for creditable training hours.
Professional trainers command premium pricing through certification requirements; individual gamers represent the largest addressable population but face the strongest substitute erosion.
Technology:
Application maturity varies sharply across immersion modalities, with newer interfaces competing against established motion platforms on installation footprint and capital efficiency.
- Virtual Reality:Head-mounted displays with six-degrees-of-freedom tracking deliver complete visual immersion at lower hardware cost than projection arrays. The FAA's expanded qualification levels for advanced aviation training devices allow flight schools to log creditable hours on lower-cost simulators, accelerating institutional procurement cycles for VR-integrated systems.
- Augmented Reality:Transparent displays overlay digital instrumentation onto physical cockpit environments, preserving situational awareness. Medical rehabilitation applications in Germany and Japan employ AR overlays for motor task training where environmental grounding accelerates recovery protocols.
- Motion Tracking:Optical and inertial systems capture limb position and cockpit control manipulation for physics engine input.
- Haptic Feedback:Vibration motors, force-feedback actuators, and tactile surface arrays communicate terrain texture and control loading to users.
Motion tracking underpins system integration across all applications; virtual reality is climbing the fastest as edge computing democratizes photorealistic streaming.
Application:
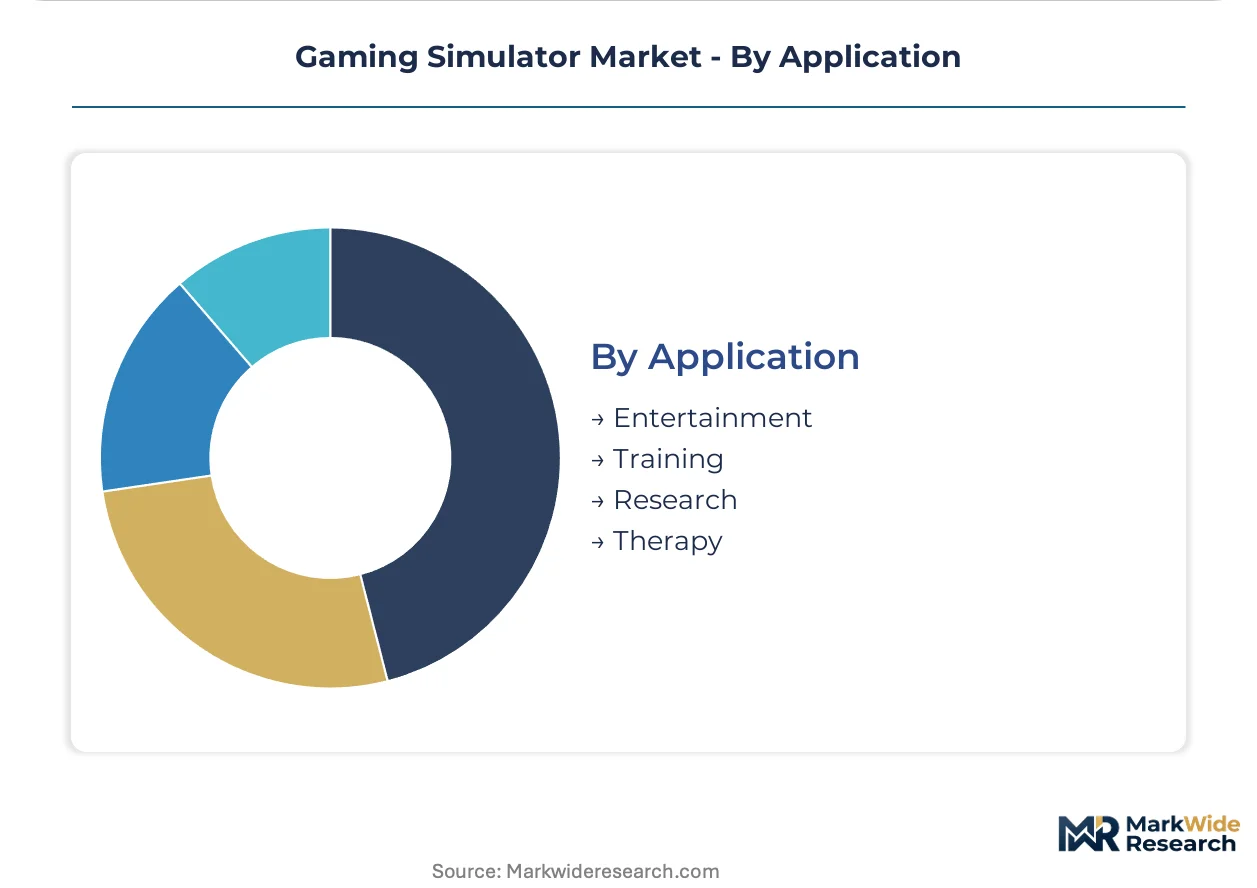
Regulatory certification creates divergent margin profiles between entertainment and professional use cases, with therapeutic applications requiring the most demanding quality management compliance.
- Entertainment:Immersion-driven consumer and location-based experiences prioritize visual fidelity and motion intensity over certification. The EU Ecodesign for Sustainable Products Regulation mandates modular hardware design and energy consumption disclosures, forcing European arcade operators and home users toward upgradeable, recyclable system architectures.
- Training:Certified pilot, driver, and crew instruction requires devices meeting FAA, EASA, or national military qualification standards. India's Directorate General of Civil Aviation is expanding its approved training organization network, creating addressable demand for certified flight simulation devices in underserved secondary cities.
- Research:Universities and automotive manufacturers employ simulators for human factors studies and vehicle dynamics validation.
- Therapy:Medical rehabilitation centers use repetitive motor task simulation for stroke recovery and neurological rehabilitation. ISO 13485 certification requirements add 12-18 months to product commercialization schedules, gating institutional sales and protecting incumbents with established quality systems.
Training commands the highest revenue per unit through certification premiums; therapy is gaining share fastest as neurodiversity accommodation standards expand reimbursable indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Institutional buyers in the United States absorb premium hardware costs for FAA-certified systems, while consumer markets in India and Southeast Asia prioritize affordability and mobile-first solutions.
United States
Defense procurement and commercial aviation training budgets drive sustained demand for high-fidelity motion platforms. The FAA governs flight simulator qualification levels, directly determining which devices log creditable training hours toward pilot certification. Flight schools in Florida and Arizona are expanding simulator deployments to meet pilot shortage mitigation targets.
Germany
Automotive manufacturers and industrial training centers anchor institutional demand for driver simulation systems. The EU AI Act and CE marking requirements under the Machinery Directive impose conformity obligations on adaptive motion profiling systems. Stuttgart and Munich host clusters of precision actuator suppliers serving six-degree-of-freedom motion base manufacturers.
China
Esports venue construction and military pilot training modernization create dual demand channels. GB standards and MIIT regulations shape product compliance for electromechanical training equipment. Shenzhen and Shanghai concentrate domestic motion platform assembly operations targeting price-sensitive Asia-Pacific markets.
India
The Directorate General of Civil Aviation's expanding approved training organization network generates demand for certified flight simulation devices in secondary cities. PLI scheme incentives for electronics manufacturing attract component suppliers to Tamil Nadu and Karnataka. Flight schools in Hyderabad and Bengaluru are retrofitting facilities with lower-cost aviation training devices.
Australia
Flight training centers and driver academies adopt cable-driven parallel kinematics for easier facility installation. The TGA and national vocational education standards influence therapeutic and training device procurement criteria. Sydney and Melbourne host regional headquarters for Asia-Pacific simulator distribution and technical support operations.
Gaming Simulator Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the gaming simulator market. The upper tier commands premium positioning through certification relationships and proprietary motion algorithms. Mid-tier competitors differentiate on landed cost and regional service proximity. Dominant competitive moves include strategic partnerships with flight schools for multi-year software licensing and geographic expansion into underserved aviation training markets.
Within the aerospace-heritage tier, CXC Simulations represents integrated design-to-certification capabilities. D-BOX Technologies Inc. and CKAS Mechatronics Pty Ltd. exemplify contrasting geographic anchoring strategies for haptic actuation and motion base manufacturing respectively. These three occupy positions spanning ultra-premium consumer, theatrical distribution, and Asia-Pacific cost-optimized procurement channels.
| Leading Market Players |
|---|
| CXC Simulations |
| D-BOX Technologies Inc. |
| CKAS Mechatronics Pty Ltd. |
| 3D Perception |
| Playseat |
| RSEAT Ltd. |
| Vesaro |
| Eleetus |
| Cruden |
| Others |
Cost & Logistics Intelligence
Multi-year software licensing agreements with bundled hardware maintenance lock in both supply access and price visibility for institutional buyers, insulating aviation academies from spot-market volatility in precision actuator components while committing vendors to fixed service obligations under FAA certification requirements.
Pricing Analysis
After-sales service contracts and algorithm update subscriptions now generate the majority of lifetime value in institutional procurement. Three-tier pricing structure across FAA-certified, CE-marked, and non-certified hardware levels separates professional trainers from arcade operators and home consumers. Cost compression in the consumer tier is intensifying because extended reality headsets deliver adequate immersion at fraction of installed simulator cost. Individual gamers exhibit highest price sensitivity, while defense training centers absorb premium hardware costs without material negotiation.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain European manufacturers dependent on Asian-sourced rare-earth magnets and Japanese precision motors. Manufacturing gravity centers on Germany, Japan, and China for six-degree-of-freedom motion base components. Specialty actuator production rests on neodymium magnet supply, high-torque servo motors, and aluminum alloy castings. Single-source vulnerability in German and Japanese motor suppliers exposes buyers to extended lead times. Distribution runs through authorized regional service centers for installation and certification support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through multi-year enterprise licensing consolidation at aviation academies and defense training centers, fragmenting the vendor landscape into ecosystem-locked relationships that resist switching.
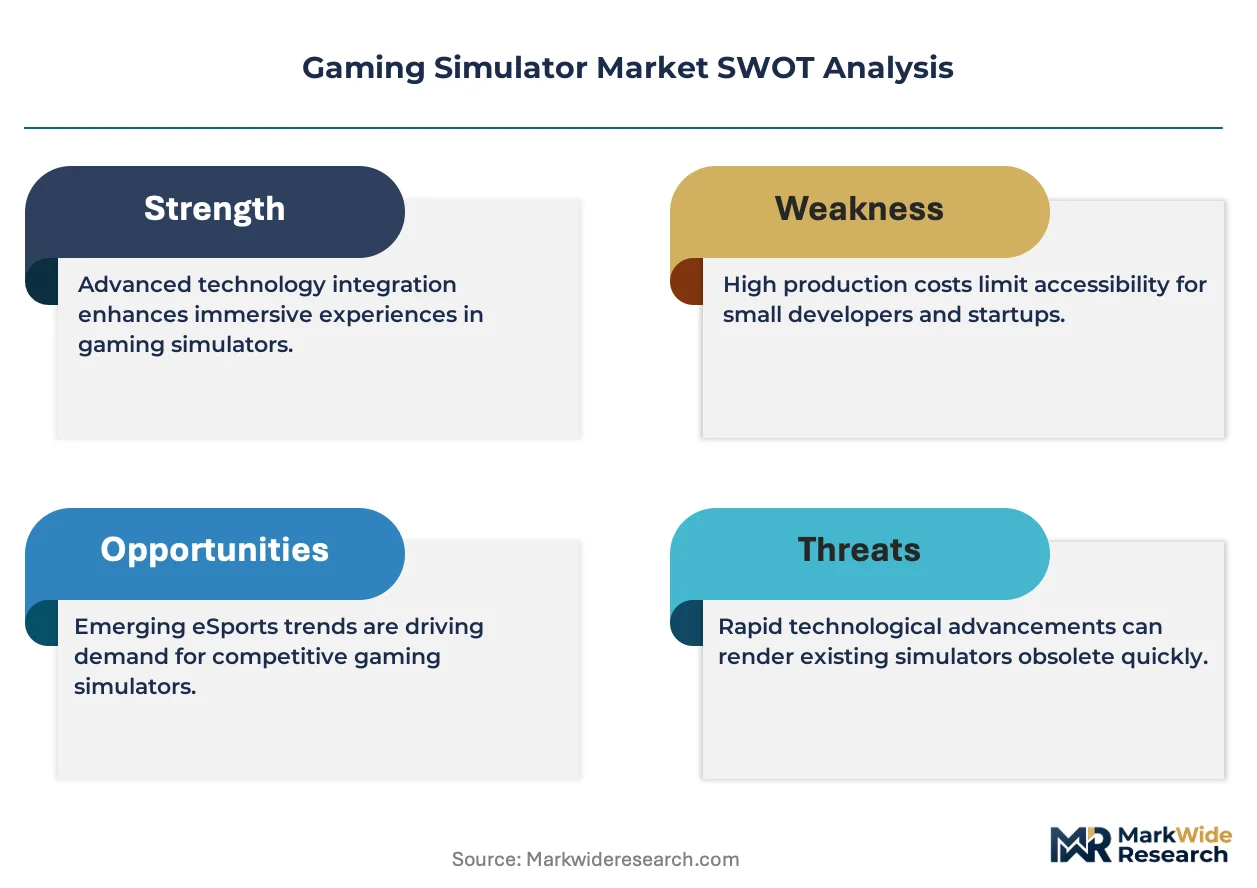
For Market Incumbents: Shield recurring revenue streams by deepening captive supply of haptic feedback algorithms and motion control software. Acquire ISO 13485 certification capabilities ahead of medical rehabilitation market expansion. Vertical integration into precision actuator sourcing mitigates single-supplier vulnerability from German and Japanese specialty motor manufacturers. For New Entrants and Emerging Players: FAA Part 60 certification fast-track programs open procurement access to flight schools in Florida and Arizona facing pilot shortage mitigation targets. India's Directorate General of Civil Aviation approved training organization expansion in Hyderabad and Bengaluru offers the most penetrable geography. Partner with regional technical universities for co-development of lower-cost cable-driven parallel kinematics systems. For Investors and Strategic Acquirers: Specialist haptic software developers with existing FAA relationships represent the highest-conviction acquisition archetype for long-term viability. Monitor esports venue retrofit cycles as an inflection indicator for theatrical distribution channel expansion. Cloud-rendered visualization commoditization threatens hardware-centric business models while elevating software-layer valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FAA Certification Investment | Unlocks creditable training hour logging at aviation academies in Florida and Arizona. |
| Software Licensing Transition | Converts perpetual hardware sales into recurring revenue with higher customer lifetime value. |
| Cable-Driven Kinematics Adoption | Reduces facility installation costs for flight schools in converted retail spaces. |
| EU Ecodesign Compliance | Mandates modular hardware architecture for circular material recovery in member states. |
| Esports Venue Partnership | Creates theatrical distribution channel through synchronized spectator seating retrofits. |
Research Approach
A standing panel of flight school operations directors, defense procurement officers, haptic software engineers, and arcade venue managers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against FAA qualification databases, EU AI Act conformity assessment records, and customs trade data for precision actuator imports. Bottom-up unit economics triangulated against top-down aviation training budget allocations.
Consistency checks validated volume and value outputs against defense procurement disclosures and commercial flight school capital expenditure patterns. The analytical framework segments across hardware-software-accessories-sensor product types, individual-arcade-educational-professional end users, and entertainment-training-research-therapy applications. CAGRs derive from installed base growth rates and replacement cycle timing. Edge computing penetration and cloud-rendered visualization adoption serve as technology-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained FAA certification pathway stability and EU regulatory enforcement continuity; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as extended reality headset fidelity improvements and neurodiversity accommodation standard evolution reshape hardware specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Chinese Gaming Industry Market
Gaming
United States Gaming Market
Gaming
Europe Casino Gambling Market
Gaming
Global Online Adventure Games Market
Gaming
Virtual Reality (VR) in Gaming Market
Gaming
Puzzle Video Game Market
Gaming
Mobile Game Software Market
Gaming
Global Subscription-Based Gaming Market
Gaming
AAA Games Market
Gaming
Global Gaming Headset Market
Gaming
Metaverse in Gaming Market
Gaming
Game Applications Market
Gaming
VR Melee Games Market
Gaming
Global Tarot Cards Market
Gaming
Global Online Gambling and Betting Market
Gaming
VR Gaming Accessories Market