
 Gaming Software Market | 2026-2036
Gaming Software Market Size, Share, and Industry Trends Forecast 2026-2036
Gaming Software Market Analysis
Chinese game engine development is decoupling from Western middleware dependencies as domestic studios scale proprietary toolchains. Tencent Interactive Entertainment anchors Asia-Pacific distribution through its WeGame platform and minority stakes across dozens of studios. Epic Games leverages its Unreal Engine licensing to extend influence beyond gaming into film and automotive visualization. Microsoft Gaming competes through subscription bundling via Game Pass, while Nintendo sustains premium hardware-software integration with its first-party IP strategy.
Gaming software comprises executable code, asset pipelines, and runtime environments that render interactive experiences across computing devices, typically requiring GPU acceleration and low-latency network stacks for multiplayer synchronization. The primary commercial purpose is to monetize engagement through unit sales, recurring subscriptions, or in-game economies. Mobile Games now generate the largest revenue pool among product types, though Cloud Computing infrastructure is the fastest-expanding technology layer as latency-sensitive streaming displaces local installation. Console Games remain the most margin-concentrated segment due to exclusive IP and closed ecosystem control, while AR applications occupy niche enterprise training budgets outside entertainment.
The EU Digital Services Act and GDPR impose transparency and age-verification mandates on platform holders, while the US FTC scrutinizes in-game monetization mechanics under consumer protection statutes. China's NMPA and MIIT enforce content approval queues and youth playtime restrictions that directly shape release calendars and revenue recognition timing. Japan's METI promotes esports professionalization through visa and prize-money regulations that expand the addressable talent pool. Stakeholders must monitor evolving classification of loot-box mechanics across jurisdictions to anticipate compliance costs and design constraints.
Market Dynamics
Cloud gaming infrastructure is electrifying distribution economics by eliminating local hardware requirements and collapsing the barrier between content libraries and device endpoints. This shift reconfigures monetization from unit sales toward recurring access fees, pressuring publishers to rebuild asset pipelines for streaming latency rather than disk optimization.
Growth Catalysts
- 5G Network Rollout:Mobile carriers in South Korea and the United States are prioritizing edge computing deployments that reduce round-trip latency for streamed interactive content below 20 milliseconds.
- Subscription Bundling Models:Platform holders now aggregate hundreds of titles into flat-rate catalogs, expanding addressable audiences beyond traditional purchase-intent gamers.
- EU Digital Services Act:Transparency mandates on recommendation algorithms and age-gating are forcing platform redesigns that incidentally improve parental control features and reduce churn.
Market Restraints
- Data Center Energy Costs:GPU-intensive rendering at scale requires continuous power draw that tracks volatile electricity pricing in Germany and California.
- Content Approval Queues:China's NMPA maintains multi-month review backlogs that delay revenue recognition and compress marketing windows for seasonal releases.
- Input Device Standardization:Fragmented controller protocols across smart TVs, smartphones, and set-top boxes force redundant QA cycles and limit cross-platform feature parity.
Strategic Opportunities
- Enterprise Training Applications:Industrial simulation using game engines is penetrating aviation maintenance and surgical rehearsal markets previously served by specialized CAD vendors.
- India's Broadband Expansion:Fiber-to-the-home initiatives in Maharashtra and Karnataka are creating first-time cloud gaming addressability among 400 million smartphone users.
- Cross-Media IP Exploitation:Real-time rendering pipelines originally built for interactive entertainment are now licensing into film previsualization and automotive design review workflows.
Industry Challenges
- Live Operations Talent Scarcity:Persistent content economies require data scientists and community managers that traditional game studios never staffed, creating wage inflation in Seattle and Helsinki.
- Anti-Cheat Arms Race:Kernel-level detection systems trigger false positives that generate refund requests and reputation damage, particularly in free-to-play battle royale formats.
- Localization Pipeline Complexity:Simultaneous global launches now demand voice acting and cultural adaptation across 12+ languages, stretching project management systems designed for English-first releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaming Software Market |
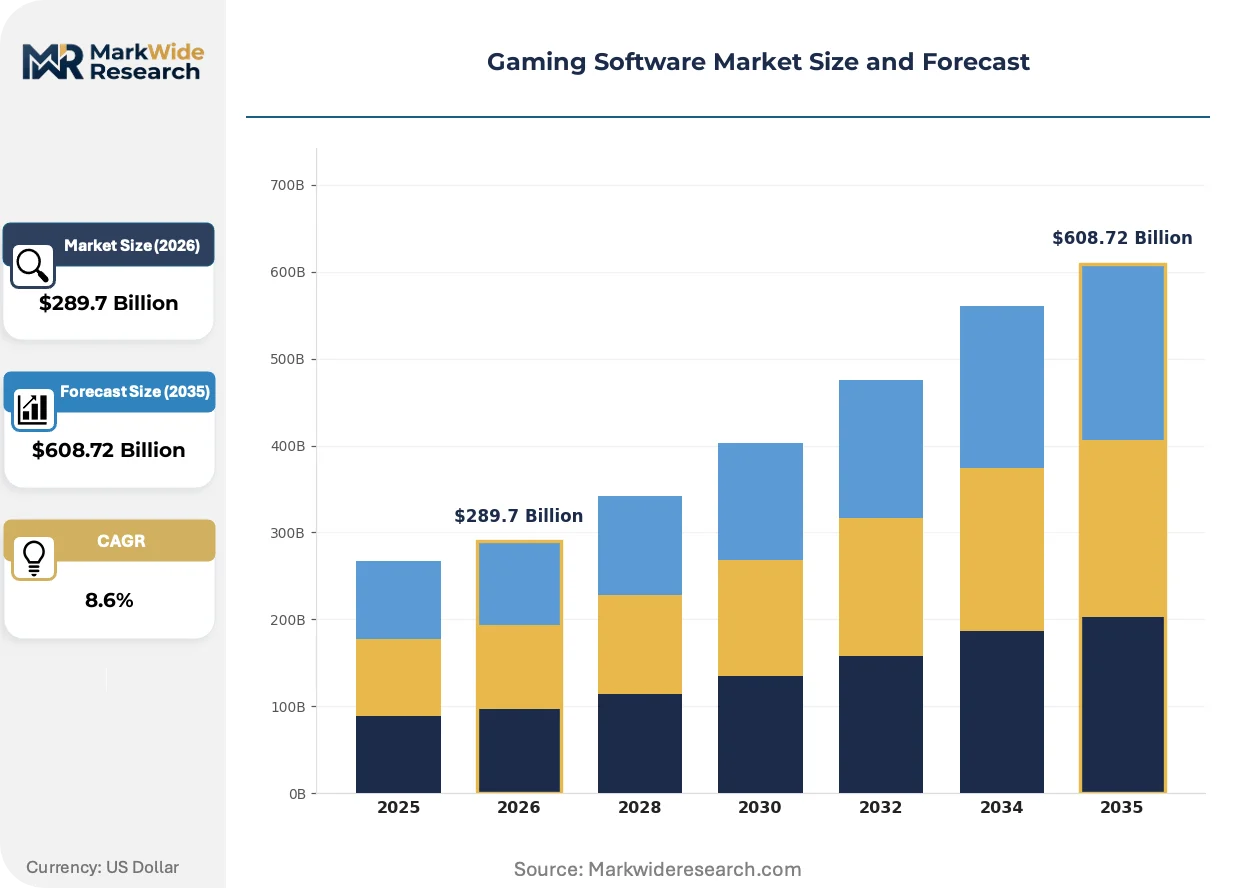
| Market Size in 2026 | $289.7 Billion |
| Market Size in 2035 | $608.72 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PC Games, Console Games, Mobile Games, Online Games End User: Casual Gamers, Professional Gamers, Educational Institutions, Corporate Training Distribution Channel: Digital Download, Retail Stores, Subscription Services, Cloud Gaming Technology: AR, VR, Cloud Computing, Game Engines |
| Companies Covered | NetEase Games, Electronic Arts, Sony Interactive Entertainment, Roblox Corporation, Take-Two Interactive, Tencent Interactive Entertainment, Nintendo, Epic Games, Microsoft Gaming, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaming Software Market Emerging Trajectories
Generative AI tooling is compressing asset production timelines while regulatory fragmentation around loot-box classification forces simultaneous compliance architecture across multiple jurisdictions. Publishers now compete on operational velocity as much as creative differentiation.
Neural radiance fields (NeRFs) and procedural generation pipelines are electrifying environment creation by reducing manual modeling hours for open-world terrain. Mid-size studios in Poland and Sweden are adopting these tools to match visual fidelity previously achievable only with triple-A headcounts. The technology is compressing pre-production cycles from 18 months toward 8-month concept-to-vertical-slice timelines.
The EU's Digital Services Act transparency requirements are mandating algorithmic explainability for content recommendation systems that drive 70% of catalog discovery on major platforms. Publishers must now document how engagement metrics influence visibility rankings, creating documentation burdens that favor established legal teams. Mobile storefronts in France and Germany are responding by segregating youth-directed content into separate algorithmic pools.
Cross-platform progression systems are displacing siloed save data as the default player expectation, forcing backend infrastructure investments that synchronize state across console, PC, and mobile endpoints. This behavior concentrates in the United States and United Kingdom where multi-device ownership rates exceed 80% among 18-34 demographics. First-party platform holders are responding with identity services that lock social graphs into ecosystem-specific networks.
Gaming Software Market Segmentation
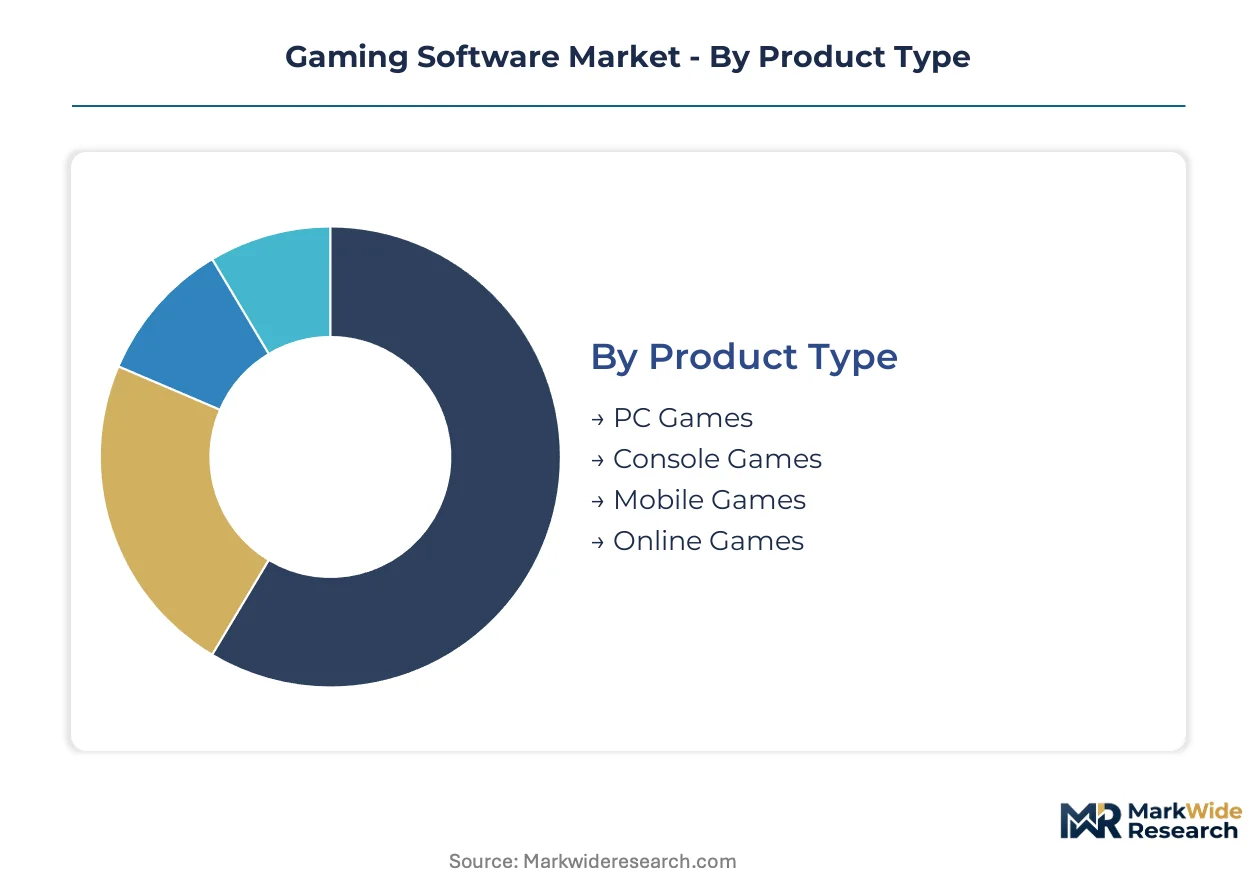
Gaming software segmentation reveals divergent margin structures and infrastructure dependencies across delivery modes. Publishers calibrate development budgets and monetization mechanics to the technical constraints and audience expectations of each category.
Product Type:
Supply concentration in first-party IP and closed hardware ecosystems creates divergent profitability profiles across delivery platforms.
- PC Games:Open hardware standards enable modding communities and direct-to-consumer storefronts that bypass platform fees. Steam and Epic Games Store compete on revenue split terms while hardware diversity in Germany and South Korea forces extensive compatibility testing.
- Console Games:Exclusive licensing agreements and proprietary SDKs concentrate development talent around Sony, Microsoft, and Nintendo ecosystems. Japan's METI visa pathways for esports professionals expand the addressable competitive player base for tournament-ready titles.
- Mobile Games:Touch-optimized monetization through in-app purchases dominates revenue in India and Brazil where smartphone penetration outpaces PC or console ownership.
- Online Games:Persistent server architectures require live operations staffing that traditional retail publishers never maintained.
Today's leader: Console Games. Tomorrow's challenger: Mobile Games.
End User:
Customer lifetime value calculations vary dramatically between impulse-driven casual engagement and skill-based competitive ecosystems.
- Casual Gamers:Session-based play patterns favor ad-supported or micro-transaction models with minimal onboarding friction. China's MIIT youth playtime restrictions directly compress daily active user metrics for this segment.
- Professional Gamers:Hardware sponsorships and prize pools create secondary revenue streams beyond software sales. South Korea's dedicated esports stadium infrastructure and United States collegiate scholarship programs professionalize talent pipelines.
- Educational Institutions:Institutional procurement cycles favor perpetual licenses over subscription models due to budget approval timelines.
- Corporate Training:Boeing and Siemens deploy Unreal Engine simulations for maintenance protocols that reduce physical equipment wear.
Casual Gamers deliver volume. Corporate Training delivers margin expansion.
Distribution Channel:
Channel economics determine whether publishers capture 70% or 30% of end-user spend after platform fees and retail markups.
- Digital Download:Direct storefront relationships eliminate physical manufacturing and retail margin stacking. EU Digital Services Act transparency mandates now require algorithmic disclosure for recommendation-driven discovery.
- Retail Stores:Collector's editions and hardware bundles sustain shelf presence for franchise launches in Japan and France where physical collectibility retains cultural significance.
- Subscription Services:Microsoft Game Pass and Sony PlayStation Plus aggregate catalogs that expand addressable audiences beyond purchase-intent buyers. Revenue recognition shifts from point-of-sale to amortized access fees.
- Cloud Gaming:5G edge deployments in Seoul and Los Angeles reduce latency below 20 milliseconds, enabling smartphone streaming of console-quality assets without local storage.
Subscription Services are gaining share fastest. Cloud Gaming holds the steepest expansion trajectory.
Technology:
Underlying technology layers determine which development competencies studios must build in-house versus license from specialized vendors.
- AR:Enterprise maintenance overlays in aviation and logistics outpace consumer entertainment applications. Hardware limitations in field-of-view and outdoor visibility constrain mass adoption.
- VR:Meta's Quest ecosystem and Sony's PSVR2 compete on standalone versus tethered architectures. Motion sickness mitigation remains a design constraint for session length.
- Cloud Computing:GPU virtualization at scale enables streaming without local rendering hardware. Data center energy costs in California and Germany track volatile electricity pricing.
- Game Engines:Epic's Unreal and Unity's runtime environments license into film previsualization and automotive design review workflows beyond interactive entertainment.
Game Engines anchor current development. Cloud Computing reshapes delivery economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States publishers monetize through subscription bundling while Chinese studios navigate content approval queues that compress release windows. This divergence shapes how capital allocates across development pipelines and live operations infrastructure.
United States
Esports viewership growth and Game Pass subscription expansion drive demand concentration. The FTC scrutinizes in-game monetization mechanics under consumer protection statutes. Seattle and Los Angeles anchor development clusters where live operations talent scarcity inflates wages.
China
Domestic studios scale proprietary game engines to reduce Western middleware dependencies. The NMPA and MIIT enforce youth playtime restrictions and content approval queues. Shenzhen and Hangzhou host Tencent Interactive Entertainment's distribution networks and minority studio investments.
Japan
Premium hardware-software integration sustains margin concentration in first-party IP. METI promotes esports professionalization through visa and prize-money regulations. Tokyo and Osaka development clusters supply exclusive titles for closed console ecosystems.
South Korea
5G edge computing deployments reduce streaming latency below 20 milliseconds for cloud gaming adoption. National infrastructure investment prioritizes esports stadium development. Seoul anchors dedicated competitive gaming venues and professional talent pipelines.
Germany
The EU Digital Services Act imposes transparency mandates on recommendation algorithms and age-verification systems. Volatile electricity pricing in data center regions pressures GPU-intensive cloud rendering economics. Berlin and Munich host middleware licensing operations and automotive visualization partnerships.
Gaming Software Market Vendor Landscape
United States producers anchor one tier; Chinese specialists hold distribution scale through platform control. The market structures around first-party IP exclusivity, middleware licensing, and subscription aggregation. Three archetypes dominate: closed ecosystem hardware-software integrators, engine licensors extending into adjacent verticals, and platform holders bundling third-party catalogs. Competitive moves concentrate on strategic partnerships for cloud infrastructure and portfolio diversification across media formats.
Within the platform-holder tier, Tencent Interactive Entertainment and Microsoft Gaming exemplify divergent geographic strategies. Epic Games occupies a position bridging middleware licensing with cross-media pipeline development. These three entities represent how scale concentrates around distribution control and technology licensing rather than unit sales alone.
| Leading Market Players |
|---|
| NetEase Games |
| Electronic Arts |
| Sony Interactive Entertainment |
| Roblox Corporation |
| Take-Two Interactive |
| Tencent Interactive Entertainment |
| Nintendo |
| Epic Games |
| Microsoft Gaming |
| Others |
Supply Flow & Price Mechanics
Subscription bundling by Microsoft Game Pass and Sony PlayStation Plus is compressing unit-sale margins and forcing publishers to rebuild asset pipelines for amortized revenue recognition, which in turn concentrates development budgets around live-service titles with recurring monetization potential.
Pricing Analysis
Platform-holder revenue splits determine effective pricing power, with Steam and Epic Games Store competing on 12% versus 30% take rates that directly flow to developer margins. Three-tier pricing structure across premium, standard, and economy levels stratifies across exclusive first-party IP, cross-platform AAA releases, and catalog backfill titles. Pricing pressure stems from subscription aggregation that collapses perceived value of individual purchases. Casual mobile gamers in India and Brazil exhibit highest price sensitivity, while corporate training buyers at Boeing and Siemens accept premium licensing for simulation deployments.
Supply Chain Analysis
Direct-to-consumer digital storefronts handle hyperscale distribution, eliminating physical manufacturing and retail markup layers. Development talent concentrates in the United States, Japan, and Poland where engine licensing operations and first-party studios anchor production pipelines. GPU silicon from TSMC's foundries in Taiwan and memory components from South Korean suppliers rest on semiconductor fabrication capacity. Single-source vulnerability in advanced node chip supply creates chokepoint exposure for cloud rendering infrastructure. Distribution runs through platform-holder identity services that lock social graphs and save-state synchronization into ecosystem-specific networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between China's content approval queues and the EU's algorithmic transparency mandates creates cost-structure differentiation that rewards geographic portfolio diversification.
For Market Incumbents: Hedge against subscription fatigue by maintaining selective exclusive IP that drives hardware adoption outside bundled catalogs. Tencent Interactive Entertainment's WeGame platform investments demonstrate channel control leverage against storefront dependency. Backward integration into proprietary game engines reduces Unreal Engine licensing exposure as Chinese studios decouple from Western middleware. For New Entrants and Emerging Players: Cloud gaming infrastructure partnerships offer lowest-friction entry path, bypassing the capital intensity of console hardware development. India's fiber-to-the-home expansion in Maharashtra and Karnataka represents the most penetrable geography for first-time addressable audiences. Target enterprise training applications where aviation maintenance and surgical rehearsal budgets exceed entertainment licensing economics. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-size studios possessing live-operations infrastructure but lacking first-party platform distribution. Five-to-ten year viability hinges on operational velocity in generative AI tooling adoption rather than creative differentiation alone. Watch for NMPA approval queue clearance rates as inflection signal for Chinese revenue recognition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Engine Development | Chinese studios reduce Western middleware dependency as MIIT promotes domestic toolchain standards. |
| Cloud Infrastructure Partnership | 5G edge deployments in Seoul and Los Angeles enable sub-20 millisecond streaming latency for smartphone endpoints. |
| Cross-Media IP Licensing | Unreal Engine pipelines penetrate film previsualization and automotive design review workflows beyond gaming. |
| Live Operations Talent Acquisition | Data scientists and community managers command wage premiums in Seattle and Helsinki development clusters. |
| Enterprise Simulation Vertical | Boeing and Siemens maintenance protocols reduce physical equipment wear through game-engine deployments. |
Methodological Framework
Coverage spans the United States, China, Japan, South Korea, and Germany, with primary inputs from each market cluster combining structured interviews with game development executives, platform engineering leads, live operations directors, and regulatory affairs specialists. Secondary validation draws from SEC filings, NMPA approval databases, EU Digital Services Act implementation guidance, and hyperscaler capex disclosures. Bottom-up project pipeline analysis triangulates against top-down subscription revenue modeling.
Granularity-level framing models product type, distribution channel, end-user archetype, and technology layer at country-level resolution across the analysis window. CAGRs derive from installed base projections for 5G-enabled devices, cloud gaming subscriber forecasts, and esports viewership trajectories. Segment-specific growth rates incorporate content approval queue durations for China, electricity pricing volatility for German data center economics, and METI visa pathway expansion for Japanese competitive gaming talent pools.
Regulatory reclassification of loot-box mechanics, NMPA approval backlog resolution, and 5G network deployment delays are the dominant revision risks that could compress or extend growth trajectories. Forecasts reflect assumptions around subscription adoption curves and cloud infrastructure investment cycles without deterministic certainty. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Mobile Game Software Market
Gaming
United States Gaming Market
Gaming
Russia in-Game Advertising Market
Gaming
South Korea Subscription-Based Gaming Market
Gaming
Europe Video Game Software Market
Gaming
Asia-Pacific in-Game Advertising Market
Gaming
China in-Game Advertising Market
Gaming
Latin America Mobile Gaming Market
Gaming
Middle East and Africa Gaming Headsets Market
Gaming
Shooter Game Market
Gaming
Connected Game Console Market
Gaming
VR Gaming Market
Gaming
China Casino Tourism Market
Gaming
United Kingdom Online Gambling Market
Gaming
Board Games Market
Gaming
Global Battle Royale Games Market