
 Global Online Board Games Market | 2026-2036
Global Online Board Games Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Board Games Market Foresight
Casual gamers migrating from physical tabletop formats is bifurcating demand between synchronous multiplayer enthusiasts and asynchronous mobile players. Tencent Holdings Ltd. leverages its WeChat ecosystem to dominate social distribution channels across Asia. Chess.com anchors competitive tournament infrastructure with dedicated server architecture and Elo rating systems. Asmodee Digital specializes in licensed digital adaptations of established tabletop franchises.
Online board games constitute software-based recreations of tabletop strategy, card, and tile-based games delivered through networked platforms with matchmaking algorithms, turn-state synchronization, and cross-device save continuity. These platforms employ client-server architectures with sub-200ms latency thresholds to preserve strategic decision integrity across asynchronous and synchronous play modes. The freemium monetization model captures the widest user funnel through ad-supported entry tiers while subscription pools concentrate among dedicated strategy and role-playing communities. Mobile platforms lead install volume globally, though desktop environments retain higher average revenue per user in competitive strategy categories where screen precision affects gameplay outcomes.
The EU AI Act and GDPR impose algorithmic transparency and data portability requirements on matchmaking systems and user progression databases. China's SAMR enforces minor protection rules limiting playtime and monetization depth for users under eighteen. The FTC in the United States scrutinizes loot-box mechanics and dark-pattern design in in-app purchase flows. Stakeholders must monitor evolving age-verification mandates and cross-border data localization rules as these determine market access architecture and platform compliance costs.
Market Dynamics
Cloud gaming infrastructure standardization is compressing latency thresholds below 200ms, enabling synchronous multiplayer integrity that physical-to-digital migrants demand for competitive tabletop experiences.
Growth Catalysts
- China's MIIT cloud gaming standards:These technical mandates accelerate platform compliance investments, forcing infrastructure upgrades that benefit cross-border latency performance for East Asian matchmaking pools.
- Casual gamer migration from physical tabletop:This demographic shift expands addressable user bases beyond legacy hobbyist communities, creating network effects that reduce customer acquisition costs for freemium platforms.
- GDPR data portability rules:The EU framework reduces switching friction between platforms, intensifying competitive pressure that drives feature innovation and retention engineering investments.
Market Restraints
- Server infrastructure concentration:Hyperscaler dependency in East Asian markets creates single-point-of-failure risks for tournament-grade synchronous play during regional bandwidth congestion events.
- SAMR minor protection enforcement:China's under-eighteen playtime caps compress monetizable session windows, forcing platform architecture redesigns that fragment global product roadmaps.
- Input cost volatility in GPU cloud instances:Cryptocurrency mining demand cycles create pricing instability for real-time rendering infrastructure, squeezing margins on graphics-intensive digital board game adaptations.
Strategic Opportunities
- India's underpenetrated mobile gaming base:Low-cost Android device penetration creates first-mover advantages for localized asynchronous strategy titles with regional language interfaces.
- AI-assisted matchmaking convergence:Machine learning algorithms paired with behavioral biometrics enable predictive player pairing that reduces churn in competitive ladder systems.
- FTC dark-pattern scrutiny tailwinds:Regulatory pressure on manipulative in-app purchase design creates differentiation opportunities for transparent monetization architectures that build long-term trust equity.
Industry Challenges
- Cross-platform synchronization engineering:Maintaining turn-state integrity across iOS, Android, and desktop clients requires specialized distributed systems talent that commands premium compensation in tight labor markets.
- Elo rating system IP complexity:Licensing disputes over competitive ranking algorithms create legal friction for platforms seeking tournament legitimacy comparable to Chess.com's established infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Board Games Market |
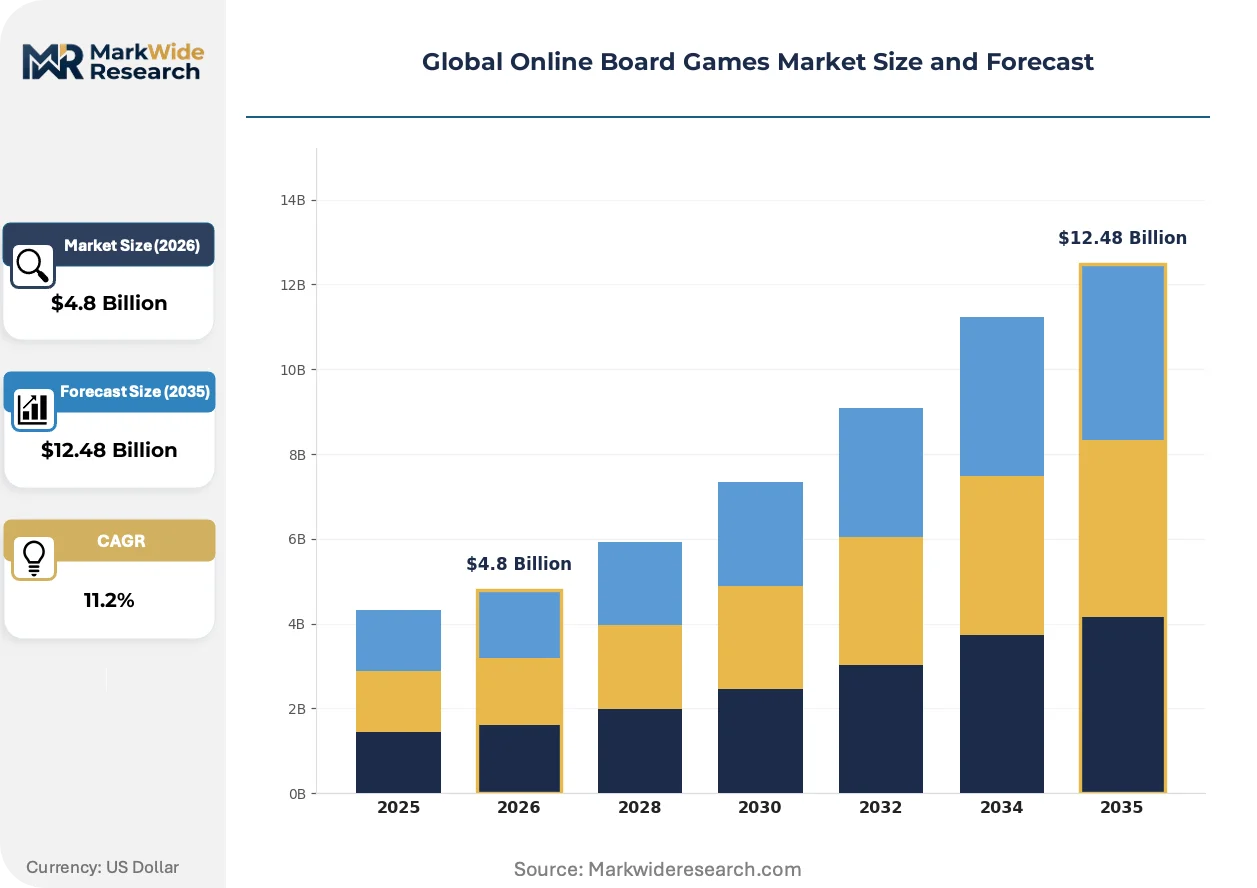
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Strategy, Casual, Puzzle, Role-Playing, Trivia, Simulation Platform: Mobile, Desktop, Tablet, Console, Web-Based, Smart TV Monetization Model: Freemium, Subscription, Pay-to-Play, Ad-Supported, In-App Purchases, Premium Target Audience: Children, Teens, Young Adults, Adults, Seniors, Casual Gamers |
| Companies Covered | Zynga Inc., Tencent Holdings Ltd., Scopely, Supercell OY, Marmalade Game Studio, Asmodee Digital, Nintendo Co., Ltd., GungHo Online Entertainment, Chess.com, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Board Games Market Shifts & Advancements
Edge computing deployment is compressing physical distance between players and game state servers, eliminating geographic latency penalties that previously fragmented global matchmaking pools into regional silos.
WebAssembly runtime technology is miniaturizing client-side game logic execution, enabling browser-based play without native app installation. Casual players in emerging markets adopt this friction-reduced access mode fastest, bypassing app store download barriers. The technology is miniaturizing platform distribution costs while expanding reach into low-storage devices.
The EU AI Act's algorithmic transparency mandates now require explainable matchmaking logic for competitive ranking systems. Platform operators must document decision criteria that pair players, exposing proprietary competitive balance formulas to regulatory audit. Tournament-grade infrastructure providers in Germany and France face the steepest compliance engineering timelines.
Subscription bundling is displacing standalone app purchases across mobile distribution channels. Amazon Prime Gaming and Apple Arcade aggregate board game titles into flat-fee catalogs, fragmenting individual title monetization while concentrating buyer attention on featured placements. South Korean and Japanese consumers show highest attachment to these bundled discovery models.
Global Online Board Games Market Segmentation
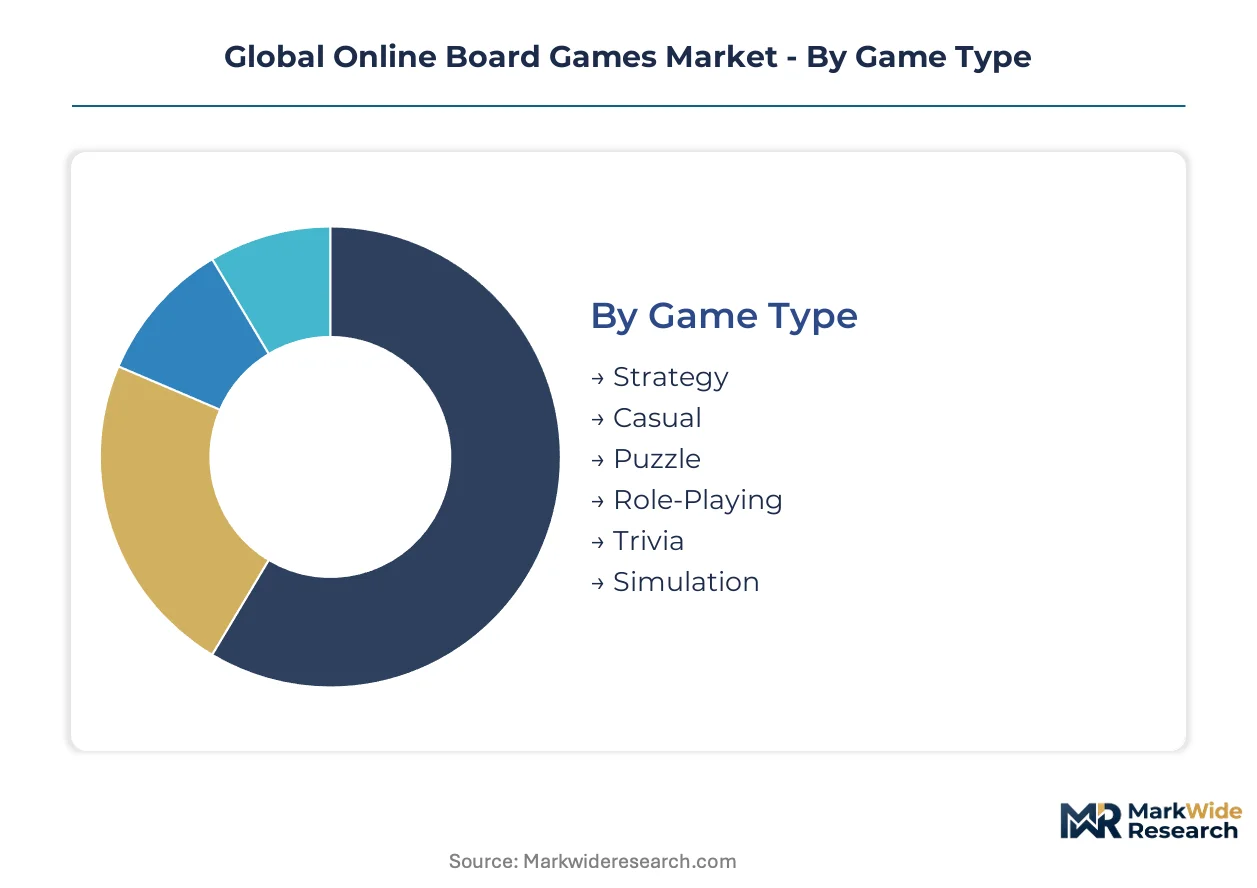
Online board game platforms engineer monetization and distribution around distinct player behavioral profiles. Segment boundaries determine server architecture investments, matchmaking algorithm design, and regulatory compliance scope across age-gated user pools.
Game Type:
Strategy titles flow through desktop channels with subscription pricing, while casual and puzzle formats dominate mobile ad-supported distribution. Role-playing games concentrate in premium storefronts with DLC ecosystems.
- Strategy:Turn-based tactical systems with Elo-rated competitive ladders and sub-200ms latency requirements. Demand concentrates in Germany and South Korea where tournament infrastructure attracts dedicated player investments.
- Casual:Asynchronous match-3 and card mechanics with session times under ten minutes. India's low-cost Android base drives install volume through friction-reduced browser access.
- Puzzle:Single-player logic challenges with daily streak mechanics and minimal server dependency.
- Role-Playing:Narrative-driven campaigns with persistent character progression and guild-based social structures.
- Trivia:Real-time knowledge competitions with live host integration and synchronous audience participation.
- Simulation:Economic and resource-management systems with extended session loops and premium currency sinks.
By volume, Casual leads. By growth pace, Strategy is climbing the fastest.
Platform:
Cost tier structures separate premium desktop experiences from economy mobile deployments, with mid-tier tablet and console positioning capturing family-oriented multiplayer use cases.
- Mobile:Touch-optimized interfaces with aggressive battery-efficiency constraints and app store commission structures. China's SAMR minor protection rules force architecture fragmentation for under-eighteen session caps.
- Desktop:Mouse-precision inputs with higher ARPU in competitive categories where screen real estate affects strategic decision quality. Japan's PC gaming cafes sustain dedicated player bases.
- Tablet:Hybrid touch interfaces bridging mobile convenience with expanded visual field for family co-play scenarios.
- Console:Controller-native adaptations with living-room social positioning and platform-holder certification requirements.
- Web-Based:WebAssembly runtime delivery eliminating download friction for emerging market casual acquisition.
- Smart TV:Remote-control simplified inputs with asynchronous turn notification systems for intermittent living-room engagement.
Mobile captures the widest user funnel. Desktop retains the steepest revenue per player.
Monetization Model:
Customer type determines pricing architecture, with dedicated hobbyists accepting subscription commitments while transient players require ad-supported entry ramps.
- Freemium:Ad-supported base tiers with conversion gates into premium feature unlocks. The EU AI Act's algorithmic transparency mandates expose matchmaking logic to audit exposure for competitive ranking tiers.
- Subscription:Flat-fee catalogs with bundled title access and exclusive content releases. South Korean consumers show strongest attachment to Amazon Prime Gaming and Apple Arcade bundles.
- Pay-to-Play:Upfront purchase with complete feature access and no ongoing monetization mechanics.
- Ad-Supported:Rewarded video integration with optional skip payments and frequency-capped interruption design.
- In-App Purchases:Cosmetic and functional microtransactions with FTC dark-pattern scrutiny forcing transparent flow redesigns.
- Premium:One-time purchase with deluxe content packaging and no subsequent monetization layers.
Freemium dominates install counts. Subscription pools concentrate the highest lifetime value.
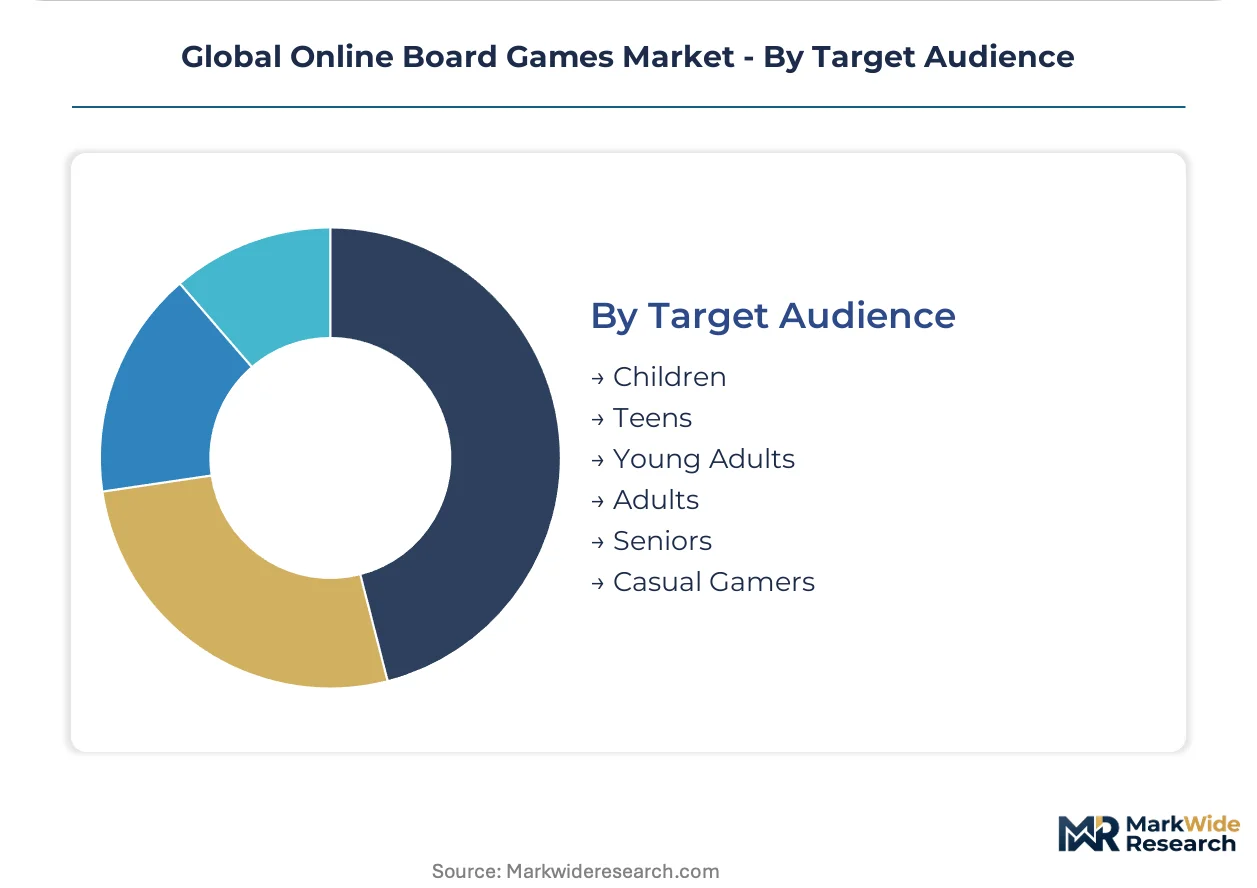
Target Audience:
Geography and maturity intersect in age-gated regulatory exposure, with children's segments triggering GDPR and SAMR compliance investments while adult pools face lighter verification burdens.
- Children:COPPA and GDPR-K age-verification systems with stripped chat functionality and parental dashboard controls. France's CNIL enforces strict data minimization for under-thirteen progression databases.
- Teens:Graduated feature unlocks with China's SAMR playtime caps compressing monetizable evening windows.
- Young Adults:Competitive ladder participation with social distribution integration through WeChat-style platform ecosystems.
- Adults:Tournament-grade infrastructure access with Elo-rated matchmaking and prize pool eligibility.
- Seniors:Accessibility-optimized interfaces with larger touch targets and reduced cognitive load mechanics.
- Casual Gamers:Cross-demographic segment prioritizing low-friction access over competitive depth or community investment.
Young Adults generate the highest session frequency. Children face the steepest regulatory compliance cost per acquired user.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submarine cable landing stations in Busan and Fukuoka anchor East Asian latency performance for synchronous multiplayer infrastructure. These fiber-optic interconnections enable sub-200ms tournament-grade matchmaking pools that physical-to-digital migrants demand.
United States
Cloud gaming data centers in Ashburn, Virginia and Portland, Oregon concentrate server capacity for North American matchmaking. The FTC scrutinizes loot-box mechanics and dark-pattern design in in-app purchase flows. Seattle hosts multiple platform engineering headquarters optimizing cross-platform synchronization architectures.
South Korea
PC gaming cafes in Seoul sustain dedicated player bases for competitive strategy titles with Elo-rated ladders. The country's national gaming regulator enforces strict minor protection rules alongside content rating systems. Busan's submarine cable landing stations anchor regional latency performance for cross-border tournament infrastructure.
Japan
Mobile-first consumption patterns in Tokyo and Osaka drive subscription bundling adoption through carrier-integrated payment systems. METI promotes cloud gaming infrastructure standardization through public-private partnerships. Nagoya's industrial corridor hosts server hardware fabrication supporting regional platform capacity expansion.
Germany
GDPR enforcement by Hamburg's data protection authority shapes algorithmic transparency requirements for matchmaking systems. The EU AI Act mandates explainable competitive ranking logic for tournament-grade platforms. Berlin's startup ecosystem incubates WebAssembly runtime developers reducing browser-based access friction.
China
MIIT cloud gaming standards accelerate infrastructure compliance investments by domestic platform operators. SAMR enforces under-eighteen playtime caps that compress monetizable session windows. Shenzhen's technology corridor concentrates social distribution platform engineering leveraging super-app ecosystem integration.
Global Online Board Games Market Competitive Landscape
Concentration sits with diversified technology conglomerates operating social distribution ecosystems and specialized digital adaptation studios. The vendor base stratifies across three tiers: super-app-integrated platforms with billion-user reach, dedicated competitive infrastructure providers with tournament legitimacy, and licensed adaptation specialists converting established tabletop franchises. Strategic archetypes include social distribution leverage, competitive ranking infrastructure, and intellectual property licensing. Dominant competitive moves encompass ecosystem lock-in through cross-platform progression continuity and regulatory pre-compliance to secure market access ahead of enforcement timelines.
Within the social distribution tier, Tencent Holdings Ltd. exemplifies super-app ecosystem leverage. Among competitive infrastructure specialists, Chess.com occupies a position anchoring tournament-grade server architecture. On the licensed adaptation vector, Asmodee Digital represents tabletop franchise conversion expertise. These three archetypes capture distinct value chain positions without direct functional overlap.
| Leading Market Players |
|---|
| Zynga Inc. |
| Tencent Holdings Ltd. |
| Scopely |
| Supercell OY |
| Marmalade Game Studio |
| Asmodee Digital |
| Nintendo Co., Ltd. |
| GungHo Online Entertainment |
| Chess.com |
| Others |
Supply & Pricing Matrix
China's SAMR minor protection standards gate both server infrastructure qualification and monetization tier differentiation simultaneously, forcing platforms to architect age-gated pricing bands that fragment global product roadmaps while concentrating compliance costs in teen-facing subscription tiers.
Pricing Analysis
Volume-discount tiering structures separate enterprise tournament organizers from individual freemium users across the Global Online Board Games Market. Three-tier pricing stratifies across premium dedicated-server subscriptions, standard matchmaking pools, and economy ad-supported entry levels. Price differentiation rests on latency-grade certification and cross-platform progression depth. Pricing pressure stems from GPU cloud instance volatility driven by cryptocurrency mining demand cycles. Casual mobile players exhibit highest price sensitivity, while competitive strategy communities accept premium subscription commitments.
Supply Chain Analysis
Submarine cable landings at Busan and Fukuoka anchor East Asian latency performance for synchronous multiplayer infrastructure. Server hardware fabrication concentrates in Japan's Nagoya corridor, Taiwan's semiconductor foundries, and South Korea's memory module producers. Raw material dependencies span advanced GPUs, high-bandwidth memory stacks, and fiber-optic cable sheathing. Single-source vulnerability in hyperscaler cloud regions creates tournament disruption risks during bandwidth congestion. Distribution runs through carrier-integrated payment systems in Japan and super-app ecosystems across China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Online Board Games Market sits in early-cycle expansion as casual gamers migrate from physical tabletop formats, creating network effects that compress customer acquisition costs for freemium platforms.
For Market Incumbents: Compound ecosystem lock-in through cross-platform progression continuity and WeChat-style social distribution integration. Defend against WebAssembly runtime disruption by accelerating browser-based feature parity investments. Prioritize regulatory pre-compliance in EU AI Act algorithmic transparency and SAMR minor protection architectures to secure market access ahead of enforcement timelines. For New Entrants and Emerging Players: GDPR data portability fast-tracks reduce switching friction and create white-space entry points. Target India's underpenetrated mobile gaming base with localized asynchronous strategy titles and regional language interfaces. Leverage transparent monetization architectures that differentiate from FTC-scrutinized dark-pattern designs to build trust equity with migrating casual players. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across WebAssembly runtime and edge computing deployment segments, reducing infrastructure barriers for browser-native platforms. Focus acquisition screening on specialized competitive ranking infrastructure providers with Elo-rated tournament legitimacy. Monitor cloud gaming standardization adoption curves as inflection indicators for infrastructure consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Deployment | Busan and Fukuoka server nodes compress latency below 200ms for synchronous tournament integrity. |
| Regulatory Pre-Compliance Investment | EU AI Act algorithmic transparency mandates force explainable matchmaking engineering in Germany and France. |
| WebAssembly Runtime Integration | Berlin startup ecosystems miniaturize client-side logic execution for emerging market browser access. |
| Super-App Ecosystem Partnership | Tencent's WeChat integration anchors social distribution leverage across Asian casual migration flows. |
| Transparent Monetization Architecture | FTC dark-pattern scrutiny creates differentiation opportunities for trust-building subscription flows. |
Research Methodology
The analysis maps synchronous multiplayer infrastructure, asynchronous mobile platforms, and browser-native runtime deployments, each validated through platform engineering directors, cloud procurement officers, tournament organizers, and regulatory compliance leads. Primary fieldwork combined structured interviews with secondary validation against MIIT cloud gaming standards documentation, GDPR enforcement decisions by Hamburg's data protection authority, and SAMR minor protection rule filings. Bottom-up install base modeling triangulated against top-down addressable market sizing across the projection horizon.
Consistency checks validated volume and value outputs against hyperscaler capex disclosures, app store commission structure filings, and subscription bundling attachment rates reported by Amazon Prime Gaming and Apple Arcade. Segmentation dimensions modeled include game type, platform architecture, monetization model, and target audience maturity tiers. CAGRs derived from cohort retention curve analysis and session monetization depth trajectories. Forecast inputs incorporated cloud infrastructure pricing volatility indices and regulatory compliance cost escalators.
Decision-makers should treat outputs as directional under sustained casual migration from physical tabletop formats and stable hyperscaler pricing regimes; material deviation in GPU instance cost cycles or age-verification mandate enforcement would warrant model refresh. Practitioners should keep alternative scenarios live as EU AI Act audit timelines and SAMR playtime cap expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Mobile Game Controller Market
Gaming
Gaming Console Market
Gaming
Mobile Game Software Market
Gaming
Chinese Gaming Industry Market
Gaming
Flat Gaming Monitors Market
Gaming
Europe Gaming Peripherals Market
Gaming
Console Games Market
Gaming
Europe Video Game Software Market
Gaming
Gaming Peripheral Market
Gaming
Gaming As a Service Market
Gaming
Lottery Market
Gaming
Game Engine Management Market
Gaming
Global 3D Gaming Console Market
Gaming
China in-Game Advertising Market
Gaming
Global NFT Gaming Market
Gaming
Saudi Arabia Entertainment and Amusement Market