
 Tumor Lysis Syndrome Market | 2026-2036
Tumor Lysis Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Tumor Lysis Syndrome Market Insights
Subscription-based risk-stratification software is rebalancing how oncology providers procure TLS management protocols, shifting capital outlays into recurring operational budgets. AstraZeneca leverages its hematology portfolio to anchor premium positioning across academic medical centers. Takeda Pharmaceutical Company Limited sustains Japanese market dominance through integrated access programs. Sanofi competes on breadth, extending its hospital formulary presence across European Union member states.
Tumor lysis syndrome denotes a metabolic emergency triggered by massive cancer cell lysis, releasing intracellular potassium, phosphate, and nucleic acids that precipitate acute kidney injury, cardiac arrhythmias, and neuromuscular complications. Rasburicase, a recombinant urate oxidase, enzymatically degrades uric acid into allantoin, a more soluble excretion product, forming the biochemical cornerstone of TLS prophylaxis. Intravenous Solutions command the largest volume share within Product Type segmentation, reflecting institutional preference for controlled electrolyte correction in inpatient settings. Biologics represent the fastest-expanding category, driven by monoclonal antibody penetration in high-burden hematologic malignancies. Among Indication segments, Non-Hodgkin Lymphoma generates disproportionate prophylactic demand due to bulky disease presentation and high cell turnover rates.
FDA oncology drug guidance, EMA's Committee for Medicinal Products for Human Use scientific advice procedures, and WHO Essential Medicines List inclusion criteria collectively shape TLS therapy registration, reimbursement, and procurement standards across developed markets. These frameworks elevate evidence thresholds for new entrants while accelerating pathways for agents demonstrating mortality reduction in randomized trials. Stakeholders must monitor evolving EMA MDR compliance requirements for companion diagnostics that stratify TLS risk prior to high-intensity chemotherapy initiation.
Market Dynamics
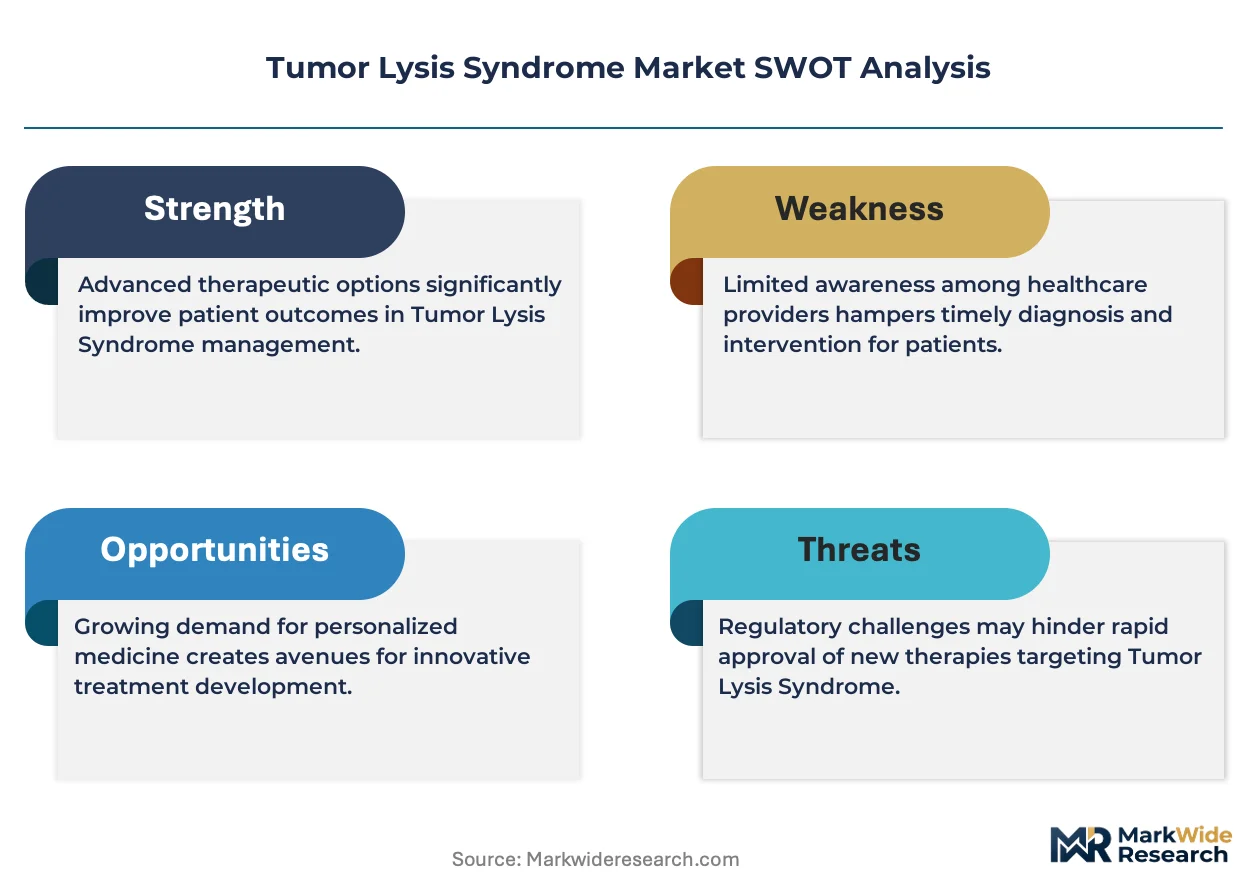
Prophylactic rasburicase protocols are displacing reactive TLS management across academic medical centers, compressing treatment windows and elevating formulary requirements for enzymatic uric acid reduction.
Growth Catalysts
- EMA MDR compliance:Companion diagnostic stratification tools gain accelerated approval pathways, expanding addressable patient pools for high-risk hematology protocols.
- Biologics penetration:Monoclonal antibody expansion in bulky lymphomas generates parallel TLS prophylaxis demand alongside oncologic therapy.
- Japan:Integrated access programs through hospital networks standardize prophylactic administration in high-volume hematology centers.
Market Restraints
- Rasburicase supply concentration:Recombinant enzyme production clusters with limited contract manufacturers, exposing procurement to single-source vulnerability.
- G6PD deficiency screening:Mandatory enzymatic contraindication testing adds diagnostic friction and delays prophylaxis initiation.
- Cost compression:Generic allopurinol substitution pressure constrains premium positioning of urate oxidase therapies in budget-constrained institutions.
Strategic Opportunities
- Subscription risk-stratification software:Recurring revenue models reconfigure capital expenditure into operational budgets for oncology clinics.
- WHO Essential Medicines List inclusion:Procurement standardization across emerging health systems creates formulary anchoring potential.
- Outpatient administration:Subcutaneous formulation development enables shift from inpatient infusion centers to ambulatory settings.
Industry Challenges
- Specialized pharmacy compounding:Cold-chain logistics and short stability windows demand certified personnel for intravenous biologic preparation.
- Cross-border licensing:Patent thickets around recombinant urate oxidase variants complicate biosimilar entry strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tumor Lysis Syndrome Market |
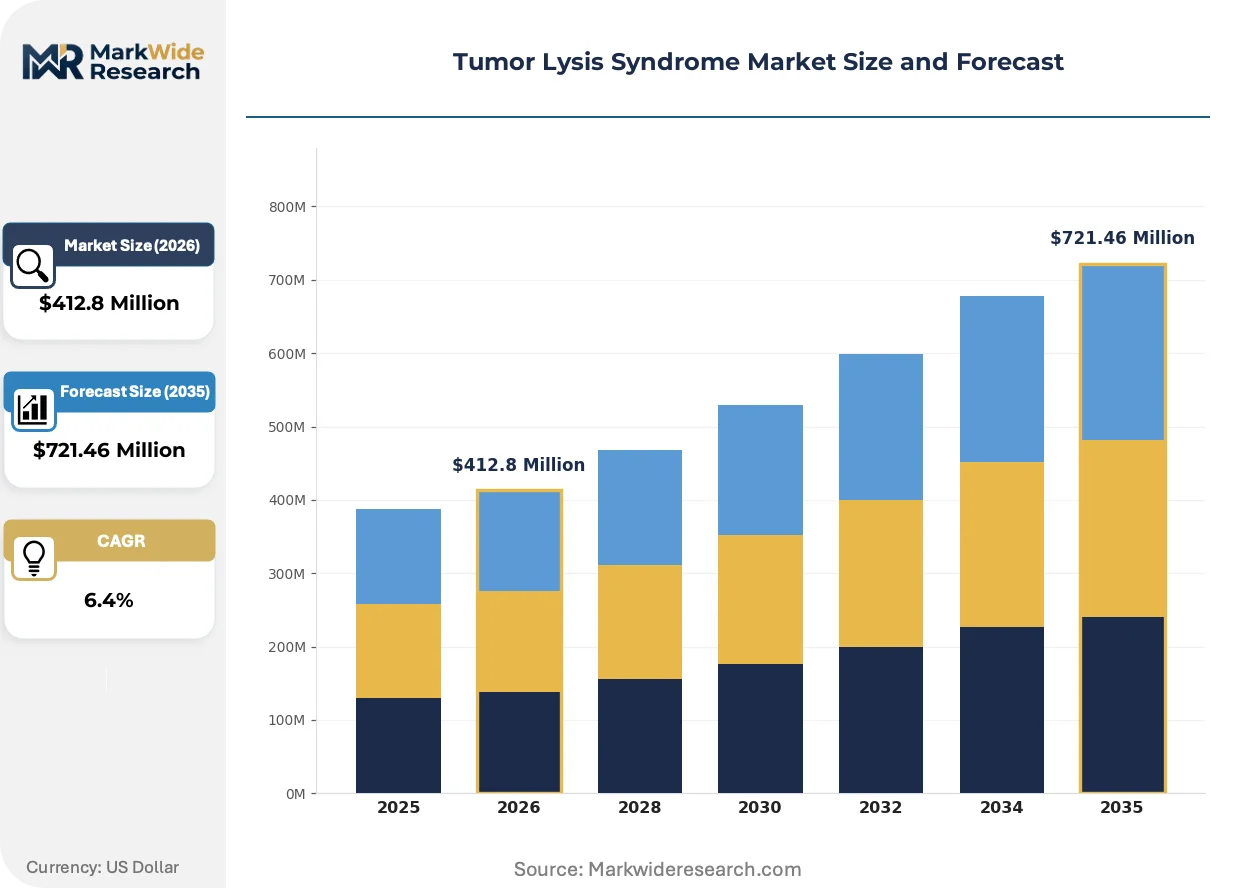
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $721.46 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
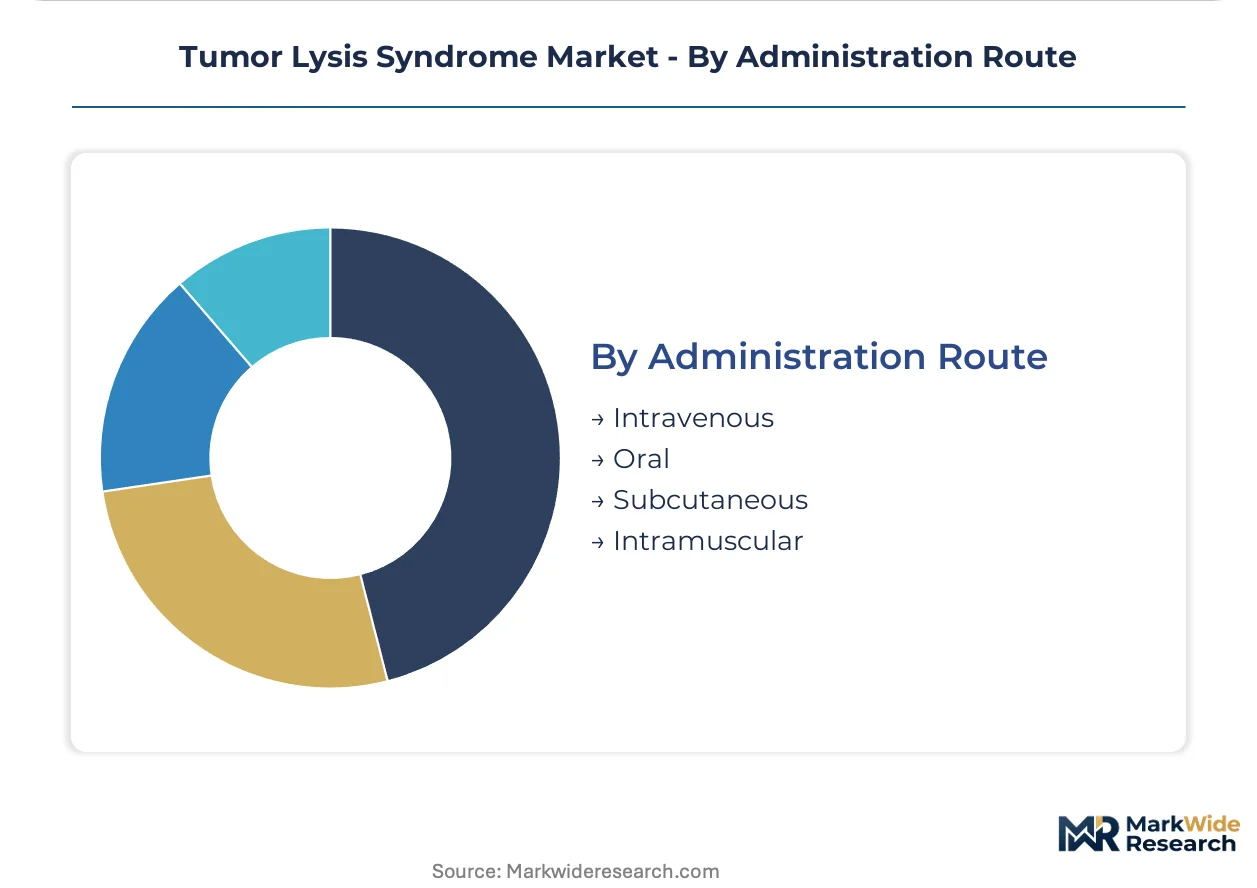
| Segmentation | Product Type: Intravenous Solutions, Chemotherapeutic Agents, Supportive Therapies, Biologics Indication: Acute Lymphoblastic Leukemia, Acute Myeloid Leukemia, Non-Hodgkin Lymphoma, Chronic Lymphocytic Leukemia End User: Hospitals, Oncology Clinics, Research Institutions, Home Care Settings Administration Route: Intravenous, Oral, Subcutaneous, Intramuscular |
| Companies Covered | AstraZeneca, Takeda Pharmaceutical Company Limited, Sanofi, Roche, Johnson & Johnson, Pfizer, Mylan, Ironwood Pharmaceuticals, Harman Finochem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tumor Lysis Syndrome Market Trends and Innovations
Digital risk-scoring algorithms and point-of-care diagnostics are compressing the interval between chemotherapy initiation and prophylactic intervention, reshaping clinical workflow integration.
Continuous glucose monitoring-derived metabolic tracking is converging with TLS prediction models. Academic medical centers in Germany deploy multi-parameter algorithms integrating real-time potassium and uric acid telemetry. This convergence is collapsing the latency between biochemical derangement and clinical response, enabling preemptive rather than reactive dosing protocols.
FDA oncology drug guidance now mandates TLS risk stratification in investigational new drug applications for high-burden hematologic agents. Trial sponsors must submit prophylaxis protocols alongside efficacy data. Early-phase biotech developers in the United States are embedding rasburicase arms into study designs to preempt regulatory queries.
Hospital procurement departments unbundle prophylaxis bundles from chemotherapy purchasing agreements. Standalone TLS management contracts enable competitive sourcing of enzymatic and non-enzymatic components. This pattern concentrates in United States integrated delivery networks seeking formulary flexibility amid pharmacy benefit manager consolidation.
Tumor Lysis Syndrome Market Segmentation
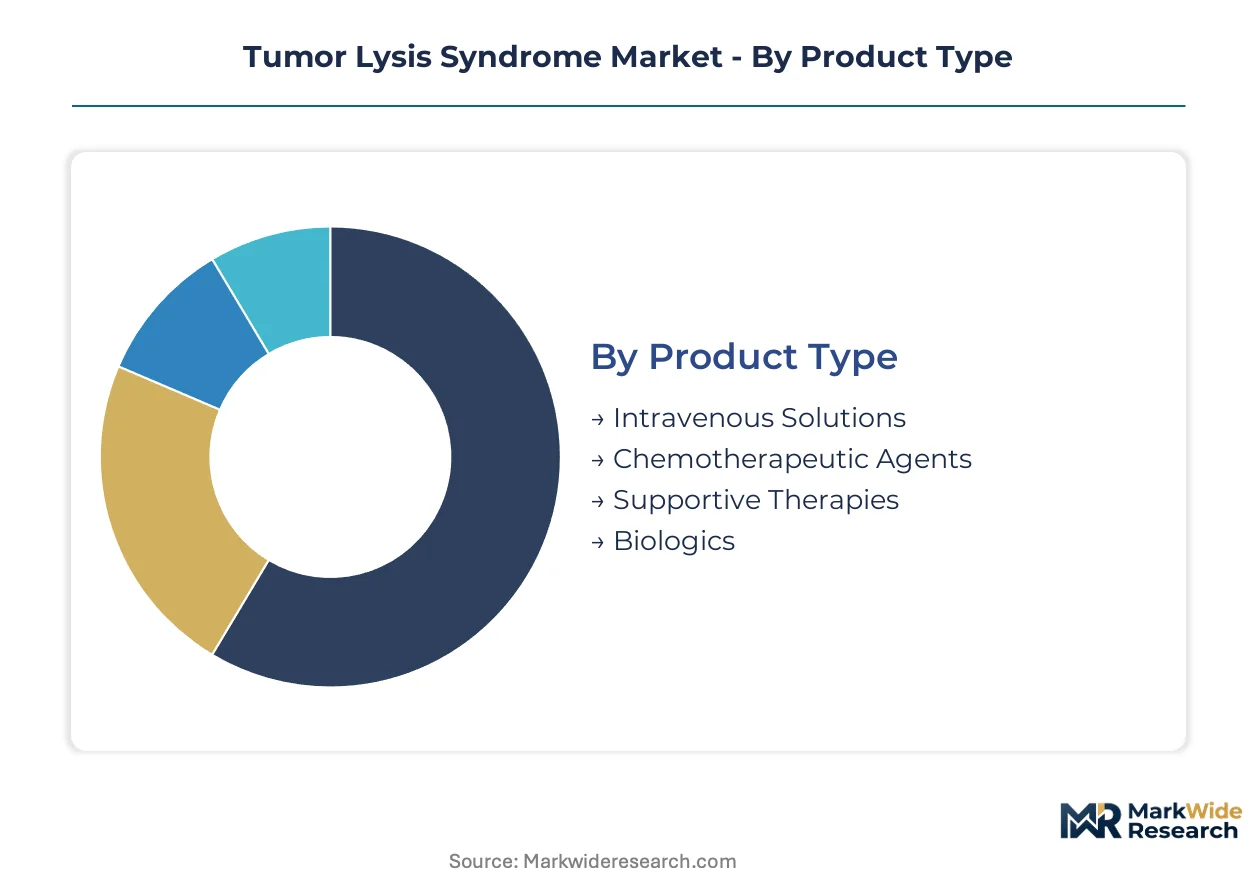
TLS management protocols require precise matching between metabolic intervention intensity and malignancy risk profile. Segmentation reveals how institutional procurement priorities diverge across acute inpatient settings versus emerging ambulatory models.
Product Type:
Upgrade cycles favor enzymatic urate reduction over legacy xanthine oxidase inhibition, reshaping formulary composition across hematology units.
- Intravenous Solutions:Electrolyte correction fluids and crystalloid formulations enable controlled volume resuscitation during acute TLS episodes. Demand concentrates in United States academic medical centers where inpatient admission protocols mandate immediate intravenous access for high-risk lymphoma induction.
- Biologics:Recombinant urate oxidase variants deliver enzymatic degradation of uric acid into soluble allantoin, bypassing renal excretion limitations. German hematology networks deploy these agents preemptively in bulky disease presentations, driven by EMA MDR compliance requirements for companion diagnostic stratification.
- Chemotherapeutic Agents:Cytotoxic induction regimens trigger TLS through rapid tumor cell lysis, requiring parallel prophylaxis administration.
- Supportive Therapies:Phosphate binders and calcium supplementation address electrolyte derangements without direct uric acid modification.
Volume placements concentrate in Intravenous Solutions; the faster expansion belongs to Biologics.
Indication:
Cost tier differentiation separates prophylaxis intensity by malignancy cell turnover velocity and baseline tumor burden.
- Non-Hodgkin Lymphoma:Bulky nodal presentations generate disproportionate TLS risk through rapid cell lysis during monoclonal antibody combination therapy. United States oncology clinics prioritize enzymatic prophylaxis in diffuse large B-cell protocols, constrained by G6PD deficiency screening requirements.
- Acute Lymphoblastic Leukemia:Pediatric and adult protocols with high blast counts demand aggressive metabolic management during induction phases. Japanese hospital networks standardize rasburicase administration through integrated access programs, anchoring premium biologic positioning.
- Acute Myeloid Leukemia:Myeloid blast lysis releases intracellular potassium and phosphate, precipitating cardiac and renal complications.
- Chronic Lymphocytic Leukemia:Lower cell turnover rates permit conservative allopurinol-based prophylaxis in most treatment lines.
Procurement volume tilts toward Non-Hodgkin Lymphoma; steepest expansion trajectory tracks Acute Lymphoblastic Leukemia.
End User:
Customer type determines administration setting complexity and reimbursement pathway structure.
- Hospitals:Inpatient hematology units manage acute TLS episodes through continuous telemetry and dialysis backup. United States integrated delivery networks unbundle TLS prophylaxis from chemotherapy purchasing agreements, enabling competitive sourcing of enzymatic components.
- Oncology Clinics:Outpatient infusion centers adopt subscription-based risk-stratification software, converting capital expenditure into recurring operational budgets. German academic medical centers deploy multi-parameter algorithms integrating real-time metabolic telemetry.
- Research Institutions:Phase I/II trial sponsors embed TLS prophylaxis protocols into investigational new drug applications per FDA oncology drug guidance.
- Home Care Settings:Limited penetration reflects cold-chain logistics requirements and short stability windows for biologic preparation.
Revenue concentration remains with Hospitals; ambulatory transition accelerates fastest in Oncology Clinics.
Administration Route:
Supply concentration in intravenous formulation manufacturing constrains route diversification timelines.
- Intravenous:Controlled infusion enables precise dosing titration during acute metabolic derangement. Contract manufacturers cluster recombinant enzyme production, exposing procurement to single-source vulnerability.
- Subcutaneous:Depot formulations under development target shift from inpatient infusion centers to ambulatory administration. Japanese regulators evaluate stability data for outpatient self-administration protocols.
- Oral:Allopurinol tablets retain formulary presence in budget-constrained institutions facing generic substitution pressure.
- Intramuscular:Limited clinical validation restricts deployment to emergency settings without intravenous access.
Current volume anchors in Intravenous delivery; Subcutaneous development programs gain regulatory traction fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recombinant enzyme production clusters in Switzerland and the United States, while consumption concentrates in hematology treatment centers across Germany, Japan, and the United States. This geographic split shapes procurement patterns and regulatory compliance requirements.
United States
FDA oncology drug guidance mandates TLS risk stratification in investigational new drug applications, compelling trial sponsors to embed prophylaxis protocols. Academic medical centers in Boston and New York Metro deploy multi-parameter algorithms integrating real-time metabolic telemetry. Integrated delivery networks unbundle TLS prophylaxis from chemotherapy purchasing agreements to enable competitive sourcing.
Germany
EMA MDR compliance requirements for companion diagnostic stratification accelerate approval pathways for risk-scoring tools. The country's national pharmaceutical regulator elevates evidence thresholds for new entrants while fast-tracking agents demonstrating mortality reduction. Hematology networks in Bavaria and North Rhine-Westphalia deploy enzymatic prophylaxis preemptively in bulky disease presentations.
Japan
PMDA evaluation of subcutaneous formulation stability data targets outpatient self-administration protocols. METI integrated access programs through hospital networks standardize prophylactic administration in high-volume hematology centers. Tokyo and Osaka academic medical centers anchor premium biologic positioning through standardized induction protocols.
Switzerland
Swissmedic oversight of recombinant enzyme manufacturing concentrates supply-side capacity in Basel and Zurich pharmaceutical clusters. Cold-chain logistics infrastructure supports short stability windows for intravenous biologic preparation. Contract manufacturers face single-source vulnerability exposure due to limited qualified production sites.
United Kingdom
NICE technology appraisals shape reimbursement pathways for enzymatic versus non-enzymatic prophylaxis in NHS hematology units. London and Southeast England academic centers prioritize rasburicase protocols in diffuse large B-cell lymphoma induction. Pharmacy benefit manager consolidation drives formulary flexibility demands across integrated care systems.
Tumor Lysis Syndrome Market Competitive Landscape
Top-tier vendors anchor hospital formulary presence across academic medical centers, while mid-tier specialists compete on regional access programs and biosimilar development. The market structure reflects concentrated biologic production capacity alongside fragmented generic substitution pressure. Three archetypes dominate: integrated pharmaceutical conglomerates with hematology portfolios, recombinant enzyme specialists with manufacturing scale, and emerging biosimilar developers navigating patent thickets. Competitive moves center on subscription-based risk-stratification software deployment and subcutaneous formulation development for ambulatory shift.
Within the integrated pharmaceutical tier, AstraZeneca and Sanofi exemplify divergent geographic anchoring strategies. AstraZeneca represents premium positioning across United States academic medical centers through hematology portfolio depth. Sanofi occupies a position emphasizing European Union hospital formulary breadth across member states. Takeda Pharmaceutical Company Limited anchors Japanese market presence through integrated access programs, exemplifying regional dominance via hospital network standardization.
| Leading Market Players |
|---|
| AstraZeneca |
| Takeda Pharmaceutical Company Limited |
| Sanofi |
| Roche |
| Johnson & Johnson |
| Pfizer |
| Mylan |
| Ironwood Pharmaceuticals |
| Harman Finochem |
| Others |
Pricing and Supply Chain Analysis
Enzymatic premium-tier divergence from generic xanthine oxidase inhibition manifests in bifurcated procurement contracts across United States academic medical centers and budget-constrained community hospitals. This tier split feeds into supply chain configurations where cold-chain biologic distribution commands dedicated logistics networks while oral allopurinol flows through standard pharmaceutical wholesale channels.
Pricing Analysis
Cost-down pressure on enzymatic urate oxidase therapies accelerates because generic allopurinol substitution campaigns by United States pharmacy benefit managers erode formulary anchoring. Pricing stratifies across premium biologic tiers, standard intravenous electrolyte bundles, and economy oral prophylaxis levels. Brand premium and FDA accelerated approval pathway certification separate reimbursable enzymatic protocols from commodity xanthine oxidase inhibition. Oncology clinics demonstrate highest price sensitivity through subscription-based risk-stratification software procurement that converts capital expenditure into operational budgets.
Supply Chain Analysis
EMA MDR compliance certification and FDA current Good Manufacturing Practice qualification gates concentrate recombinant enzyme production in Switzerland, the United States, and select German pharmaceutical clusters. Manufacturing draws from Chinese-sourced fermentation media, specialized filtration membranes, and single-use bioreactor components. Single-source vulnerability exposes procurement to contract manufacturer concentration risk. Distribution runs through hospital-centric specialty pharmacy networks with cold-chain integrity requirements rather than retail pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologic production scale requirements and EMA MDR compliance costs are forcing sub-scale manufacturers toward exit or acquisition, consolidating competitive positioning around hematology portfolio depth.
For Market Incumbents: Acquire companion diagnostic risk-stratification platforms to anchor subscription-based recurring revenue models against generic substitution pressure. Deepen backward integration into recombinant enzyme fermentation capacity in Swiss and German manufacturing clusters to defend against single-source supply disruption. Secure hospital network standardization contracts in Japan and United States integrated delivery networks before biosimilar patent cliff erosion accelerates.
For New Entrants and Emerging Players: Enter via subcutaneous formulation development programs targeting outpatient administration shift in German and Japanese ambulatory oncology settings. Target underpenetrated home care administration protocols where cold-chain logistics innovation can unlock patient self-administration models. Pursue WHO Essential Medicines List inclusion as go-to-market anchor for emerging health system procurement standardization.
For Investors and Strategic Acquirers: Re-rating potential sits with recombinant enzyme specialists possessing captive manufacturing scale given EMA MDR compliance barriers to new production site qualification. Long-term viability favors assets with demonstrated mortality reduction in randomized trials and embedded prophylaxis protocols within FDA oncology drug guidance. Monitor PMDA subcutaneous formulation approval timelines as inflection signal for ambulatory administration market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Development | EMA MDR compliance accelerates risk-stratification tool approval pathways for high-risk hematology protocols. |
| Subcutaneous Formulation Advancement | PMDA evaluation of stability data enables shift from inpatient infusion centers to outpatient self-administration. |
| Integrated Access Program Expansion | Hospital network standardization in Japan anchors premium biologic positioning through METI-coordinated procurement. |
| Subscription Software Platform Launch | Oncology clinics convert capital expenditure into recurring operational budgets via risk-stratification SaaS deployment. |
| WHO Essential Medicines List Inclusion | Procurement standardization across emerging health systems creates formulary anchoring potential for enzymatic prophylaxis. |
Research Methodology
Independent corroboration across regulatory filings, hospital procurement databases, and clinical trial registries underwrites the qualitative findings in this study. Primary interviews with drug development executives, formulary directors at academic medical centers, payer access specialists, and regulatory affairs leads combined with secondary validation from FDA oncology drug guidance documents, EMA CHMP scientific advice procedures, ClinicalTrials.gov protocols, and hospital GPO contract databases. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored segmentation outputs.
Rate-of-change decomposition across the projection horizon separates volume expansion from price-mix effects and regulatory pathway acceleration. The analytical framework models product type, indication severity tier, administration route, and regional regulatory cluster dimensions. CAGRs derived from treatment protocol penetration curves and biologic substitution elasticity parameters incorporate real-time metabolic telemetry adoption rates and companion diagnostic stratification penetration as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rasburicase supply disruption scenarios or accelerated biosimilar entry timelines. Forecasts reflect assumptions regarding EMA MDR compliance timelines, FDA oncology drug guidance enforcement consistency, and hospital procurement unbundling momentum across United States integrated delivery networks. A model refresh is warranted upon material change in PMDA subcutaneous formulation regulatory posture or WHO Essential Medicines List inclusion criteria revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Cancer Profiling Market
Oncology
Musculoskeletal Oncology Therapeutics Market
Oncology
Precision Oncology Market
Oncology
Australia Cancer Treatment Market
Oncology
Cancer API Market
Oncology
Head and Neck Cancer Market
Oncology
Vulvar Cancer Market
Oncology
Pituitary Cancer Market
Oncology
Radiation Oncology Market
Oncology
Intratumoral Cancer Therapies Market
Oncology
Sterile Oncology Injectable Market
Oncology
Asia-Pacific Cancer Biomarkers Market
Oncology
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Global Cancer Treatment Market
Oncology
Small Cell Lung Cancer (SCLC) Therapeutics Market
Oncology
North America Tumor Ablation Market