
 Acute Lymphocytic Leukemia Therapeutics Market | 2026-2036
Acute Lymphocytic Leukemia Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Lymphocytic Leukemia Therapeutics Market Intelligence
A demand rotation toward specialized cancer centers from general hematology units for administering complex cell therapies is reorganizing the care delivery landscape. Novartis leads development in chimeric antigen receptor (CAR-T) cell therapies for relapsed cases. Amgen specializes in its bispecific T-cell engager (BiTE) antibody construct technology. Bristol-Myers Squibb leverages an extensive oncology portfolio to compete across multiple treatment modalities, including immunomodulators.
Acute Lymphocytic Leukemia therapeutics are pharmacological agents designed to eliminate cancerous lymphoblasts from bone marrow and blood. These treatments function through mechanisms such as cytotoxic effects on rapidly dividing cells, targeted inhibition of specific signaling pathways like BCR-ABL, or immune-mediated destruction of tumor cells. The primary purpose is achieving and maintaining remission. Monoclonal antibodies and other targeted therapy options are displacing older chemotherapy agents in certain protocols. Pediatric treatment regimens, in particular, show rapid uptake of these newer, less toxic alternatives.
The US Food and Drug Administration's orphan drug and breakthrough therapy designations are critical for accelerating development. In parallel, the European Medicines Agency's PRIME scheme provides enhanced support for promising medicines. Regulators in Japan, through the PMDA, also offer pathways for innovative oncology drugs. These frameworks directly influence market access speed and shape R&D investment priorities. The strategic decision for developers involves sequencing clinical trials across these jurisdictions to optimize patient access and commercial outcomes.
Market Dynamics
The central structural force is the reorganization of care delivery, with treatment administration for complex cell therapies shifting from general hematology units to a concentrated network of specialized, accredited cancer centers capable of managing their unique logistical and clinical demands.
Growth Catalysts
- Accelerated Regulatory Pathways:Frameworks including the US FDA's orphan drug designation and the European Medicines Agency's PRIME scheme reduce development timelines for novel therapies, encouraging investment in treatments for rare hematological malignancies.
- Pediatric Protocol Evolution:The rapid integration of newer, targeted therapies and immunotherapies into standard-of-care protocols for pediatric ALL provides a consistent demand driver, as clinicians prioritize less toxic and more effective agents over traditional chemotherapy.
- Clinical Trial Infrastructure:A high concentration of advanced clinical trial infrastructure and research investment in the United States accelerates the validation and approval of innovative treatments, particularly for complex cell-based therapies.
Market Restraints
- High Treatment Cost:High costs for treatments like CAR-T cell therapy and complex reimbursement frameworks create significant access barriers, particularly outside of major developed markets.
- Manufacturing Bottlenecks:Manufacturing complexity for autologous cell therapies creates production bottlenecks, limiting patient access and scalability due to the personalized nature of the process.
- Competition from Incumbents:Established, lower-cost chemotherapy regimens present a substitution threat in health systems with constrained budgets or in specific patient populations not eligible for newer agents.
Strategic Opportunities
- Allogeneic Cell Therapy Development:The development of off-the-shelf allogeneic CAR-T therapies presents a significant opportunity to overcome the logistical and cost barriers associated with current autologous treatments.
- Geographic Expansion of Clinical Trials:Expanding clinical trial operations into new regions like South Korea and Brazil can access diverse patient populations and establish an early market presence in underpenetrated areas.
- Combination Therapy Regimens:Investigating novel combinations of targeted agents, immunotherapies, and lower-dose chemotherapy could improve efficacy, manage resistance, and expand the addressable patient population.
Industry Challenges
- Specialized Talent Shortages:A scarcity of healthcare professionals trained in cell therapy administration, including specialized oncologists and nurses, creates an operational bottleneck for treatment centers.
- Capital-Intensive Infrastructure:The high capital expenditure required to build and maintain GMP-compliant manufacturing facilities and accredited treatment centers poses a significant barrier to entry and expansion.
- Logistical Complexity:The "vein-to-vein" logistics for autologous therapies, requiring cryogenic shipping and precise timing, presents a substantial and ongoing operational challenge for providers and manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Lymphocytic Leukemia Therapeutics Market |
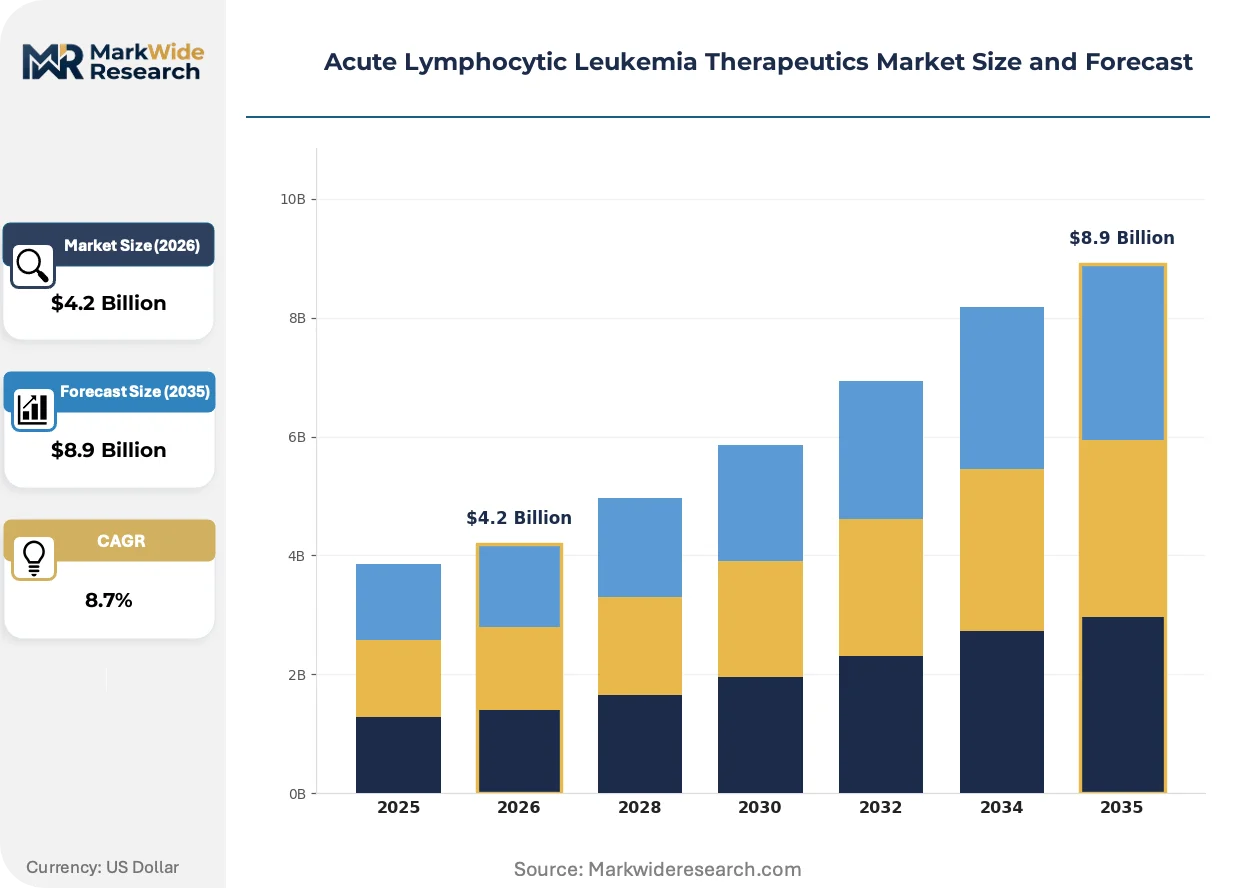
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $8.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Chemotherapy Agents, Tyrosine Kinase Inhibitors, Immunomodulators, Targeted Therapy Therapy Area: Pediatric Treatment, Adult Treatment, Relapsed/Refractory Cases, First-line Therapy End User: Oncology Clinics, Specialized Cancer Centers, Hematology Units, Clinical Research Facilities Delivery Mode: Intravenous, Oral, Subcutaneous, Intrathecal |
| Companies Covered | Amgen, Bristol-Myers Squibb, Novartis, Pfizer, Roche, Jazz Pharmaceuticals, Sanofi, Takeda Pharmaceutical, Gilead Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Lymphocytic Leukemia Therapeutics Market Strategic Shifts & Innovations
Therapeutic innovation is moving decisively from broad-spectrum cytotoxic agents toward highly specific, biologically-driven interventions. This evolution prioritizes targeted mechanisms and immune system engagement, fundamentally changing treatment paradigms from standardized protocols to personalized strategies for acute lymphocytic leukemia.
Bispecific T-cell engager (BiTE) technology provides a mechanism to physically link a patient's T-cells to tumor cells, initiating targeted cytolysis. Oncologists in specialized academic centers are adopting these constructs for patients with relapsed or refractory disease. This approach of leveraging the patient's own immune system is decomposing the traditional, monolithic chemotherapy model into more dynamic, pathway-specific interventions.
Regulatory frameworks like the FDA's accelerated approval pathway and the EMA's PRIME scheme are critical. These programs shorten development timelines and de-risk investment for therapies targeting indications with high unmet need. Consequently, developers of cell and gene therapies are designing global clinical trial programs to leverage these parallel pathways for faster market access in the United States and Europe.
Care delivery for advanced ALL therapies is concentrating within a select group of accredited cell therapy centers. This shift disrupts traditional referral patterns, repositioning community hematologists as diagnostic and referral hubs rather than primary administrators of these complex treatments. The trend is most visible in the United States, where the density of clinical research and academic medical centers dictates the landscape of care.
Acute Lymphocytic Leukemia Therapeutics Market Segmentation
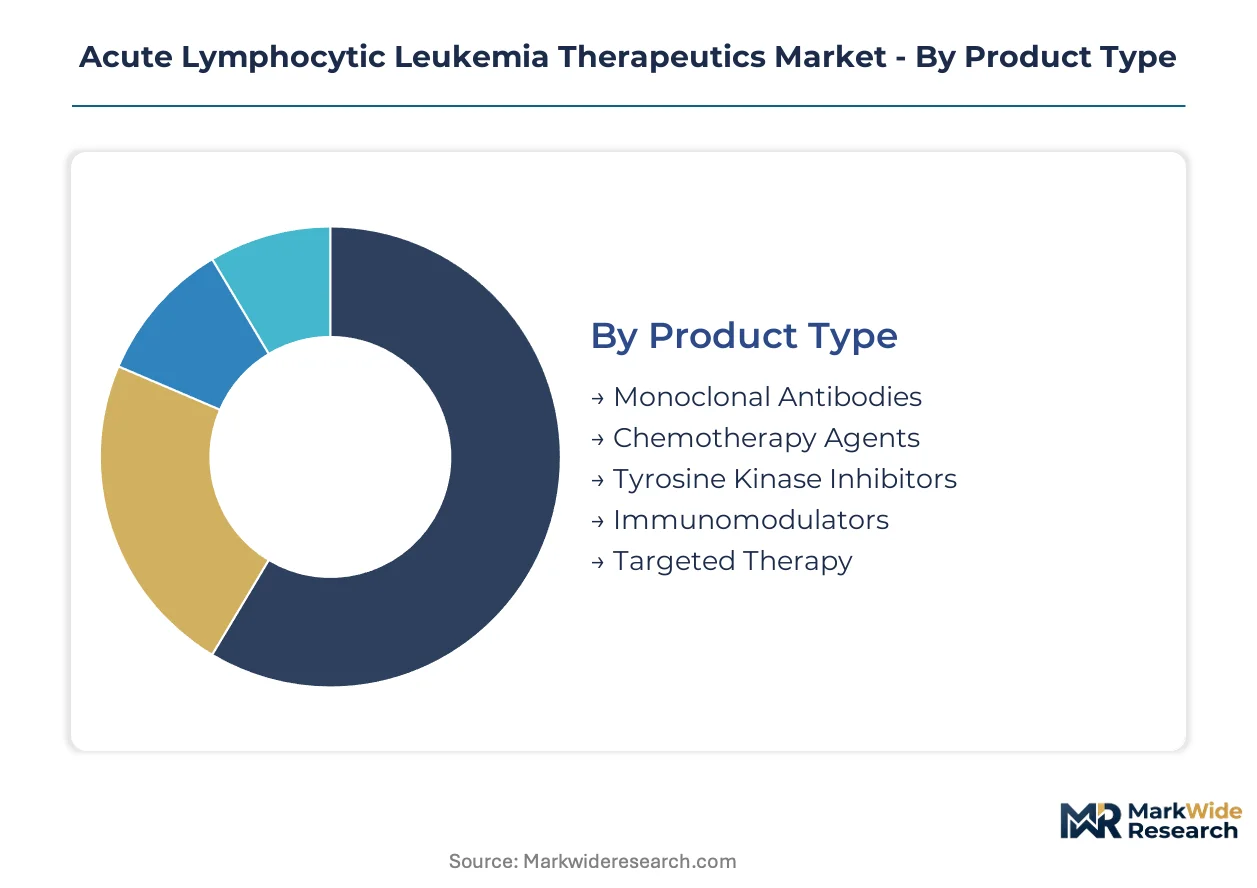
The Acute Lymphocytic Leukemia therapeutics market segments across various dimensions, reflecting the diverse nature of treatment modalities, patient populations, and care delivery models. Understanding these distinctions is critical for developers to align their pipeline with unmet clinical needs and for providers to optimize patient access.
Product Type:
Regulatory bodies like the US FDA and European Medicines Agency prioritize novel product types with breakthrough therapy designations, influencing their market introduction and adoption rates.
- Monoclonal Antibodies:These biologics specifically target antigens on leukemia cells, triggering immune responses or blocking growth signals. Demand is concentrating in relapsed/refractory settings, driven by their high specificity and reduced off-target toxicity compared to conventional chemotherapy.
- Targeted Therapy:This broad category includes agents designed to interfere with specific molecular pathways involved in cancer growth and progression, such as BCR-ABL inhibitors. The US market shows strong demand, supported by robust clinical trial infrastructure and significant research investment.
- Chemotherapy Agents:Traditional cytotoxic drugs kill rapidly dividing cells, including leukemia cells, and form the backbone of many induction and consolidation regimens. These agents maintain a significant presence in initial treatment protocols, particularly in resource-constrained health systems.
- Tyrosine Kinase Inhibitors:These small molecules block the activity of tyrosine kinase enzymes, which are often overactive in certain types of ALL. Their application is specific to Philadelphia chromosome-positive ALL, offering a targeted approach.
- Immunomodulators:These agents modulate the immune system to enhance its anti-tumor activity, often used in combination with other therapies. Their utility is expanding in maintenance phases, aiming to prevent disease recurrence.
Chemotherapy Agents handle the majority of throughput; Monoclonal Antibodies are the fastest mover on share.
Therapy Area:
Therapy area segmentation reflects distinct patient populations and disease stages, each with specific treatment goals and regulatory considerations for drug development.
- Pediatric Treatment:This segment focuses on treatment protocols tailored for children and adolescents with ALL, emphasizing less toxic and highly effective agents. Rapid integration of novel therapies into pediatric protocols in the United States provides a consistent demand driver.
- Relapsed/Refractory Cases:This area addresses patients whose disease has returned or not responded to initial treatment, often requiring advanced and complex cell therapies like CAR-T. Specialized cancer centers in Europe are increasingly adopting these advanced interventions for such challenging cases.
- Adult Treatment:This segment covers therapeutic strategies for adult patients with ALL, which can differ significantly from pediatric protocols due to varying disease biology and patient comorbidities. Treatment often involves intensive chemotherapy, sometimes followed by stem cell transplantation.
- First-line Therapy:This category encompasses the initial treatment regimens administered upon diagnosis, aiming for rapid remission and long-term disease control. The integration of targeted agents into first-line protocols is gradually displacing older, more toxic regimens.
Demand for Pediatric Treatment is expanding most quickly, while Adult Treatment maintains a substantial volume base.
End User:
The operational complexity of advanced therapies drives end-user specialization, requiring significant infrastructure investment and specialized personnel.
- Specialized Cancer Centers:These facilities possess the necessary infrastructure, expertise, and accreditation to administer complex cell therapies and advanced targeted treatments. The care delivery landscape is reorganizing towards these centers, particularly in the United States.
- Clinical Research Facilities:These sites are crucial for conducting clinical trials, validating new therapies, and expanding the evidence base for existing treatments. Investment in these facilities, especially in regions like Japan, accelerates the availability of innovative oncology drugs.
- Oncology Clinics:General oncology clinics manage a broad range of cancer patients and often administer standard chemotherapy regimens and less complex targeted therapies. These clinics frequently serve as referral hubs for patients requiring specialized ALL treatments.
- Hematology Units:These units focus on blood disorders, including ALL, providing diagnostic services and managing initial treatment phases. The administration of highly specialized cell therapies is increasingly shifting away from general hematology units.
The operational requirements for Specialized Cancer Centers drive specialized infrastructure investment, contrasting with the broader reach of Oncology Clinics.
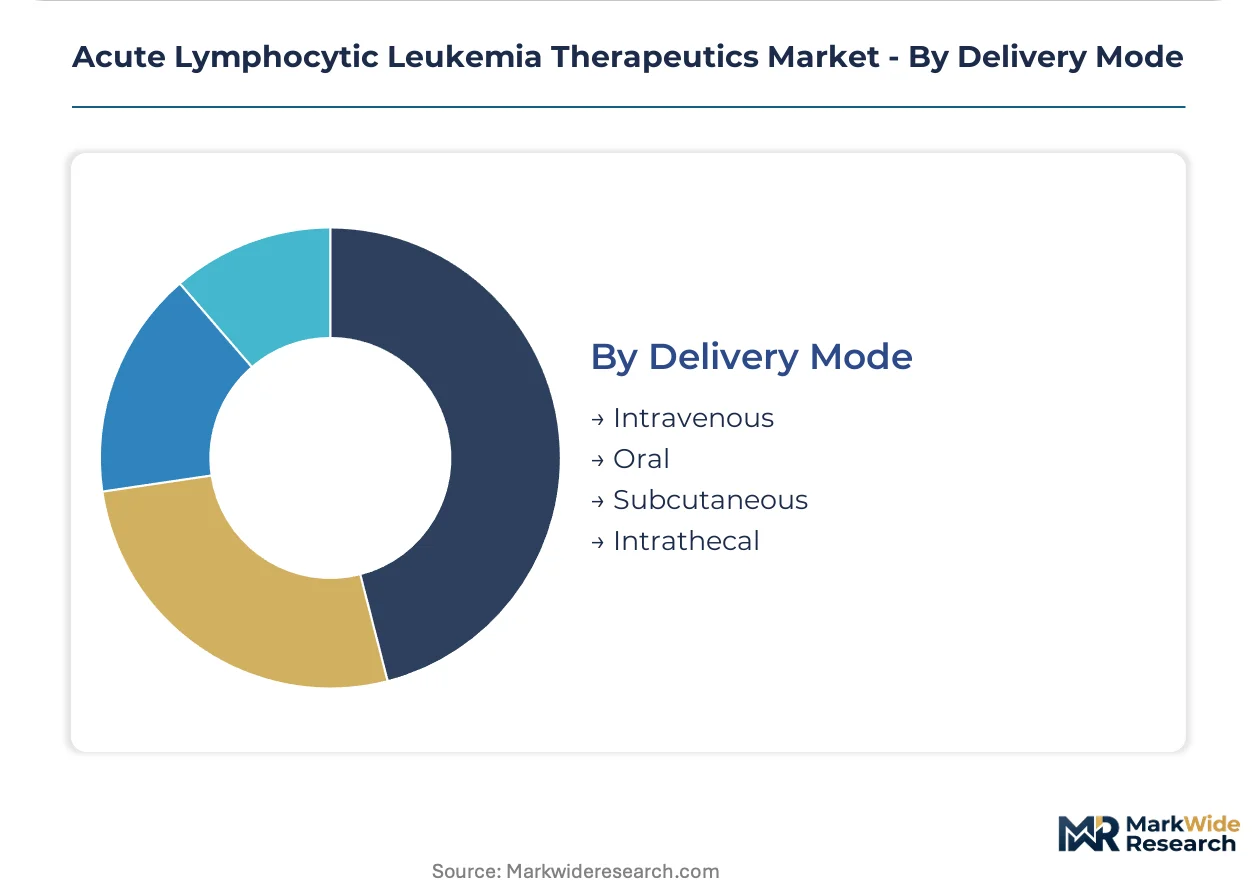
Delivery Mode:
Delivery mode differentiation hinges on pharmacokinetic profiles, patient convenience, and safety considerations for various therapeutic agents.
- Intravenous:This mode involves administering drugs directly into a vein, ensuring rapid and complete systemic bioavailability, crucial for many cytotoxic and biologic agents. Most complex cell therapies and monoclonal antibodies utilize intravenous infusion.
- Oral:Oral administration offers patient convenience and allows for at-home treatment, improving quality of life for many patients. Tyrosine kinase inhibitors are frequently available in oral formulations, facilitating long-term management.
- Subcutaneous:This method involves injecting drugs under the skin, offering an alternative to intravenous infusions for certain biologics and reducing hospital visits. Its use is expanding for maintenance therapies, where patient self-administration is feasible.
- Intrathecal:This specialized delivery route involves injecting drugs directly into the cerebrospinal fluid, primarily used to treat or prevent ALL involvement in the central nervous system. This method addresses a critical sanctuary site for leukemia cells.
While Intravenous administration remains foundational for rapid systemic delivery, Oral options are gaining traction for patient convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The robust clinical trial infrastructure in the United States underwrites its dominant role in the development and adoption of advanced Acute Lymphocytic Leukemia therapeutics. This infrastructure accelerates the validation of innovative treatments, particularly for complex cell-based therapies like CAR-T, driving global market innovation.
United States
Demand for advanced cell therapies and targeted agents concentrates in specialized cancer centers across the United States. The US FDA's orphan drug and breakthrough therapy designations significantly accelerate development timelines for novel ALL treatments. Major academic medical centers in Boston and Houston lead clinical research and patient access for these complex interventions.
Germany
Germany exhibits strong demand for innovative ALL therapeutics, supported by a well-established healthcare system and high research investment. The European Medicines Agency's PRIME scheme provides enhanced support for promising medicines, facilitating faster market access. Biotechnology clusters in Munich and Berlin actively contribute to research and development of new therapeutic modalities.
Japan
Japan demonstrates a growing appetite for targeted ALL therapies, driven by an aging population and a focus on precision medicine. Regulators in Japan, through the PMDA, offer streamlined pathways for innovative oncology drugs, encouraging early adoption. Research institutions in Tokyo and Osaka are key sites for clinical trials and the implementation of advanced treatments.
United Kingdom
The United Kingdom shows increasing integration of novel ALL treatments, particularly for pediatric and relapsed/refractory cases. The National Institute for Health and Care Excellence (NICE) evaluates and recommends new therapies, influencing their uptake within the National Health Service. Specialized cancer centers in London and Manchester are at the forefront of administering complex cell therapies.
South Korea
South Korea is rapidly expanding its capacity for advanced ALL therapeutics, driven by a strong commitment to healthcare innovation and technology adoption. The Ministry of Food and Drug Safety (MFDS) actively supports the development and approval of innovative oncology drugs. Major medical centers in Seoul are becoming significant hubs for clinical trials and specialized treatment delivery.
Acute Lymphocytic Leukemia Therapeutics Market Key Industry Players
Listed leaders compete with private specialists across the Acute Lymphocytic Leukemia therapeutics market, creating a dynamic environment for innovation and market penetration. The market structure is concentrated at the top with established pharmaceutical giants, while smaller biotechs specialize in niche technologies. Strategic partnerships and portfolio diversification are dominant competitive moves among these players.
Among established pharmaceutical companies, Novartis, Amgen, and Bristol-Myers Squibb exemplify the large-cap presence in this therapeutic area. Novartis anchors development in CAR-T cell therapies for relapsed cases, representing a significant investment in advanced biologics. Amgen occupies a position with its bispecific T-cell engager antibody construct technology, showcasing targeted immunotherapy. Bristol-Myers Squibb leverages its extensive oncology portfolio, demonstrating a broad approach across various treatment modalities.
| Leading Market Players |
|---|
| Amgen |
| Bristol-Myers Squibb |
| Novartis |
| Pfizer |
| Roche |
| Jazz Pharmaceuticals |
| Sanofi |
| Takeda Pharmaceutical |
| Gilead Sciences |
| Others |
Cost & Logistics Intelligence
The US FDA's stringent Good Manufacturing Practice (GMP) guidelines gate supply qualification for advanced ALL therapeutics, directly influencing the premium pricing for compliant products.
Pricing Analysis
Volume-based purchasing agreements often determine the cost of acute lymphocytic leukemia therapeutics for large hospital systems. Pricing stratifies across premium, standard, and economy tiers, driven by factors like therapeutic novelty and the level of post-market support. Cost compression intensifies for older chemotherapy agents due to generic competition and established usage patterns. Resource-constrained health systems show the highest price sensitivity, while specialized cancer centers prioritize clinical efficacy over cost.
Supply Chain Analysis
Strategic stockpiling of critical raw materials for cell and gene therapies is preferred over just-in-time models due to manufacturing lead times. Supply concentration for complex biologics draws from specialized facilities primarily in the United States, Germany, and Japan. Key dependencies include specialized cell culture media and viral vectors, creating single-source vulnerability. Logistical complexity, including cryogenic shipping for autologous therapies, presents a significant operational risk for providers, with distribution running through accredited cell therapy centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Acute Lymphocytic Leukemia therapeutics market is experiencing a shift in buyer power, driven by the consolidation of treatment administration into specialized cancer centers.
For Market Incumbents: Compound existing R&D investments in allogeneic cell therapies to counter the manufacturing bottlenecks of autologous treatments. Expand global clinical trial programs, especially in regions like South Korea, to accelerate regulatory approvals and market access. This strategy defends against emerging biotech entrants specializing in niche targeted agents and mitigates rising cost pressures. Control over specialized logistics and cold chain infrastructure serves as a critical lever.
For New Entrants and Emerging Players: Accelerated regulatory pathways, such as the US FDA's breakthrough therapy designation, offer a crucial entry point for novel targeted agents. Focus on underpenetrated adult relapsed/refractory cases, where existing options are often limited and less effective. A go-to-market angle emphasizing superior efficacy and reduced toxicity in specific patient populations will differentiate offerings. Geographic expansion into emerging markets like Brazil can establish early market presence.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the cell therapy development segment, reflecting the need for specialized manufacturing and clinical infrastructure. Long-term viability hinges on companies demonstrating clear clinical differentiation and a path to scalable, cost-effective production. Acquisition targets should be mid-stage biotechs with promising pipeline assets in allogeneic CAR-T or novel BiTE technologies. The signal to watch is successful Phase 3 trial data for off-the-shelf cell therapies.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerate development of allogeneic CAR-T therapies through global clinical programs to address unmet patient needs. |
| Manufacturing Scale-Up | Invest in GMP-compliant facilities to reduce production bottlenecks for autologous treatments, improving patient access. |
| Licensing Agreement | Secure rights to novel targeted agents or immunotherapies from academic research institutions for pipeline expansion. |
| Pipeline Diversification | Broaden oncology portfolio beyond ALL to leverage existing R&D infrastructure and mitigate market specific risks. |
| Strategic Partnership | Collaborate with specialized cancer centers to optimize complex cell therapy administration and enhance patient outcomes. |
Research Approach
A spread of perspectives from drug development executives, specialized oncologists, formulary directors, and hospital procurement managers converged on the working assumptions. Primary interviews were triangulated with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and peer-reviewed oncology journals. This approach ensured comprehensive data capture through both bottom-up market sizing and top-down validation.
Product type, therapy area, end user, delivery mode, and regional regulatory cluster formed the core segmentation dimensions modeled. The analytical framework integrated historical market performance with future projections over the projection horizon. Compound annual growth rates derived from detailed clinical trial success rates and anticipated regulatory approval timelines. Forecast inputs included projected patient populations and evolving treatment guidelines for ALL.
Decision-makers should treat outputs as directional under current clinical practice and reimbursement policy assumptions; material deviation would warrant model refresh. Forecasts reflect these base assumptions regarding therapeutic efficacy and market adoption rates. Revision becomes warranted when unexpected clinical trial failures or regulatory framework shifts cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Liver Cancer Treatment Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Progressive Pulmonary Fibrosis (PPF) Treatment Market
Specialty Medicine
Global Cancer Immunotherapies Market
Specialty Medicine
Fibroadenoma Market
Specialty Medicine
Histamine Toxicity Market
Specialty Medicine
Malignant Pleural Effusion Market
Specialty Medicine
Hemangioma Treatment Market
Specialty Medicine
North America Dry Eye Syndrome Market
Specialty Medicine
Epilepsy Treatment Market
Specialty Medicine
Tularemia Therapeutics Market
Specialty Medicine
Medical Foods for Orphan Diseases Market
Specialty Medicine
Multiple Endocrine Neoplasia Market
Specialty Medicine
Optic Atrophy Management Market
Specialty Medicine
Hairy Cell Leukemia Therapeutics Market
Specialty Medicine
Global Urea Cycle Disorder Market