
 Australia Legal Cannabis Market | 2026-2036
Australia Legal Cannabis Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Legal Cannabis Market Intelligence
The market for pharmaceutical-grade, GMP-certified cannabis flower and oils is decoupling from the less-regulated CBD wellness product category. Cann Group focuses on large-scale cultivation and genetic development to supply raw materials. Little Green Pharma differentiates through its portfolio of locally manufactured, GMP-certified oil-based medicines. Meanwhile, Zelira Therapeutics leverages a clinical trial-led strategy to validate its formulations for specific conditions.
Australia's legal cannabis market comprises products, primarily oils, tinctures, and dried flower, containing defined concentrations of cannabinoids like THC and CBD. These products are accessible only through medical prescription for therapeutic use. Medical cannabis for indications like pain management and anxiety relief constitutes the core of the market's value. CBD oil products, available under different regulatory schedules, represent a high-volume segment with expanding use in wellness-focused applications through pharmacies.
The Therapeutic Goods Administration (TGA) governs product quality and patient access through its Special Access and Authorised Prescriber schemes. Concurrently, the Office of Drug Control (ODC) issues licenses for cultivation, production, and manufacturing, ensuring supply chain security. Future competitive advantage will depend on generating robust clinical data to support product efficacy claims and secure physician confidence.
Market Dynamics
The Australian market's structure is defined by the regulatory tension between the Therapeutic Goods Administration's push for pharmaceutical-grade evidence and the expanding, practitioner-led patient access pathways established under the Special Access Scheme.
Growth Catalysts
- TGA Schemes:The Therapeutic Goods Administration's Special Access and Authorised Prescriber schemes continue to reduce barriers for patients obtaining medical cannabis, serving as a primary market accelerant.
- Chronic Condition Management:Increasing prescription volumes for chronic pain, anxiety, and sleep disorders, driven by greater physician and patient education, form a significant demand base.
- Geographic Concentration:A growing network of specialized cannabis clinics and dispensing pharmacies in populous states like New South Wales and Victoria improves patient access and market visibility.
Market Restraints
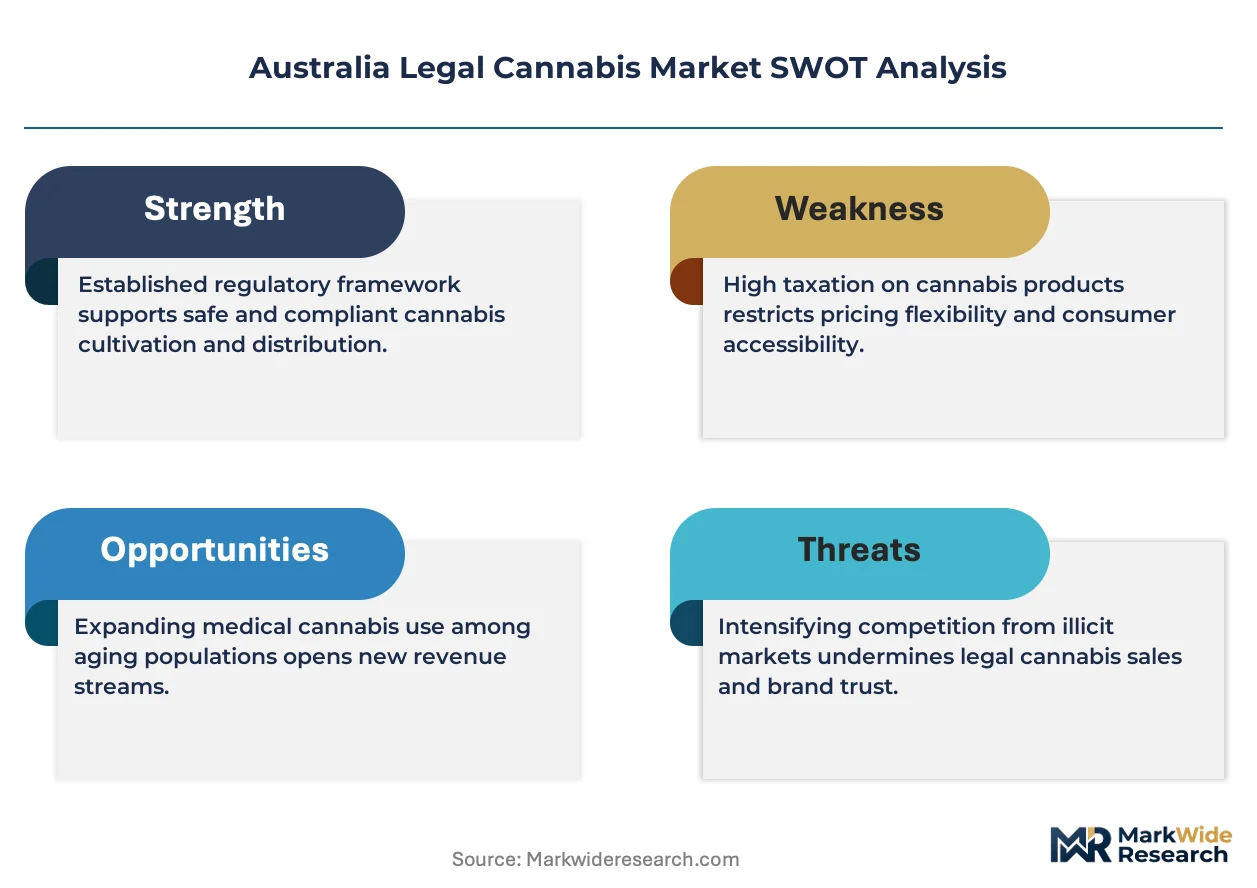
- Regulatory Burden:Navigating the dual licensing requirements of the Office of Drug Control for cultivation and the TGA for product quality presents a significant cost and compliance barrier.
- High Production Costs:The mandate for Good Manufacturing Practice (GMP) certification for most medicinal products elevates operational expenses, impacting affordability compared to illicit sources.
- Substitution from Wellness Channels:Low-concentration CBD products available through pharmacies under Schedule 3 represent a more accessible, lower-cost alternative that can divert consumers from the prescription market.
Strategic Opportunities
- Clinical Trial Validation:Pursuing clinical trials to validate proprietary formulations for specific indications, such as inflammatory bowel disease, can create defensible, high-value market segments.
- Future Regulatory Easing:Potential future down-scheduling of certain cannabinoid compounds by the TGA could unlock new over-the-counter or pharmacist-only product categories, expanding the market.
- Telehealth Expansion:Leveraging telehealth platforms to connect patients in regional and remote Australia with authorized prescribers overcomes geographic barriers to access and consultation.
Industry Challenges
- Physician Education Gap:A persistent shortage of medical practitioners educated and confident in cannabinoid science and dosing protocols acts as a bottleneck for patient access and broader adoption.
- Product Standardization:A lack of standardized product formulations and dosing guidelines across the industry creates variability in therapeutic outcomes, which can erode physician and patient confidence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Legal Cannabis Market |
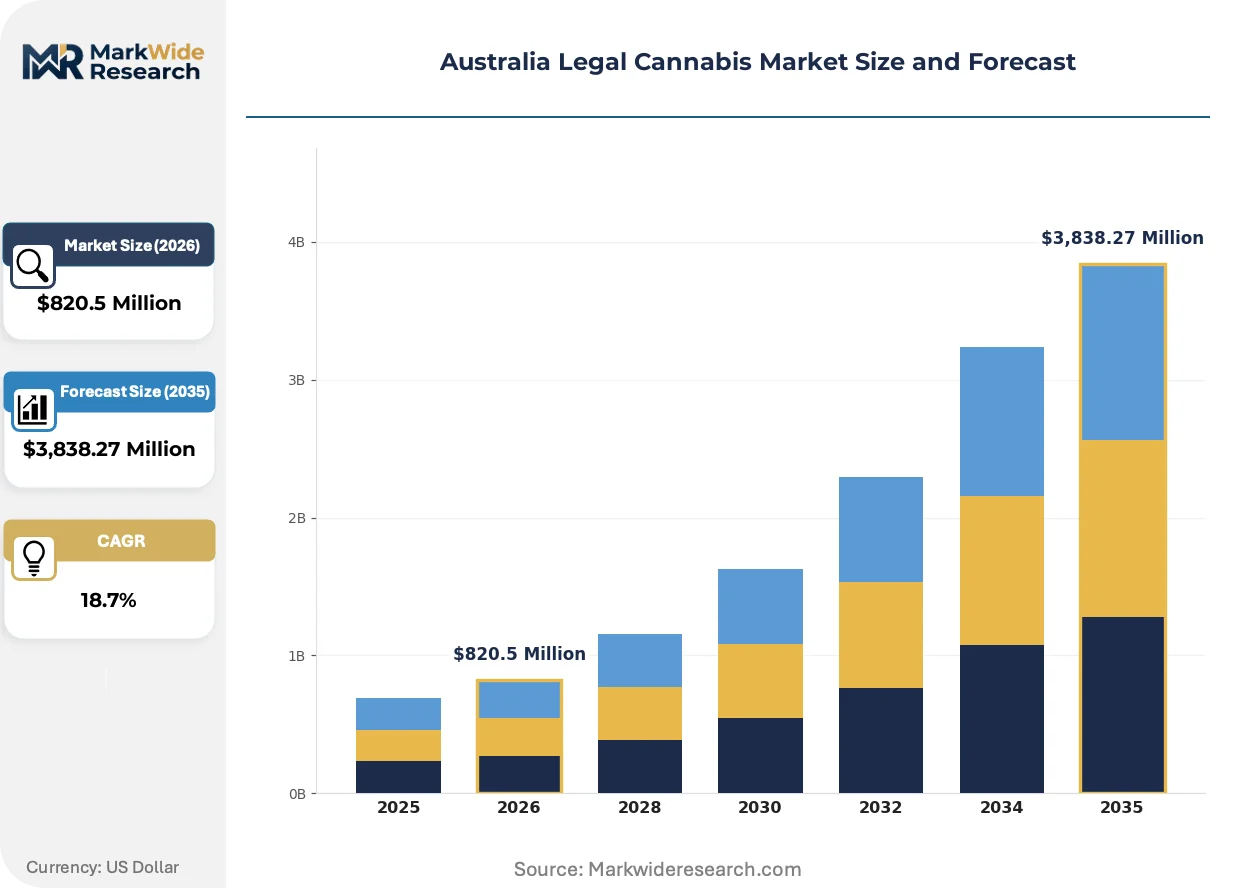
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $3,838.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Cannabis, Recreational Cannabis, CBD Oil, Hemp Products, Tinctures Application: Pain Management, Anxiety Relief, Epilepsy Treatment, Cancer Therapy, Sleep Disorders End User: Pharmacies, Dispensaries, Hospitals, Clinics, Wellness Centers Distribution Channel: Online Stores, Retail Outlets, Direct-to-Consumer, Licensed Distributors, Healthcare Providers |
| Companies Covered | Cann Group, Zelira Therapeutics, AusCann Group Holdings, Little Green Pharma, Althea Group, Vitura Health Limited, Bod Science, Ecofibre, Montu Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Legal Cannabis Market Strategic Shifts & Innovations
The market is maturing from an early focus on patient access to a new phase defined by clinical validation and product specialization. This evolution is driven by regulatory pressures for evidence and a demand for more predictable therapeutic outcomes.
Advanced formulation technologies like nano-emulsification are used to create water-soluble cannabinoid products with improved bioavailability. Pharmaceutical-focused product developers are adopting these methods to enhance control over therapeutic effects. This innovation is electrifying the development pipeline, enabling more sophisticated delivery formats beyond traditional oils, such as fast-acting oral sprays and precisely dosed edibles.
The Therapeutic Goods Administration's ongoing scrutiny of product claims and advertising rules is a significant policy shift. This regulatory pressure compels producers to invest in formal clinical trials to substantiate therapeutic benefits for specific medical conditions. Companies targeting indications like insomnia or anxiety are most affected, as they must now generate robust clinical data to support their marketing and gain prescriber acceptance.
Patient and prescriber preferences are shifting towards condition-specific formulations that are backed by clinical data. This change disrupts the model of prescribing generic THC or CBD products, favoring specialist clinics that can match validated medicines to specific diagnoses. This evolution is most apparent in the chronic pain and neurology segments within major metropolitan centers like Sydney and Melbourne.
Australia Legal Cannabis Market Segmentation
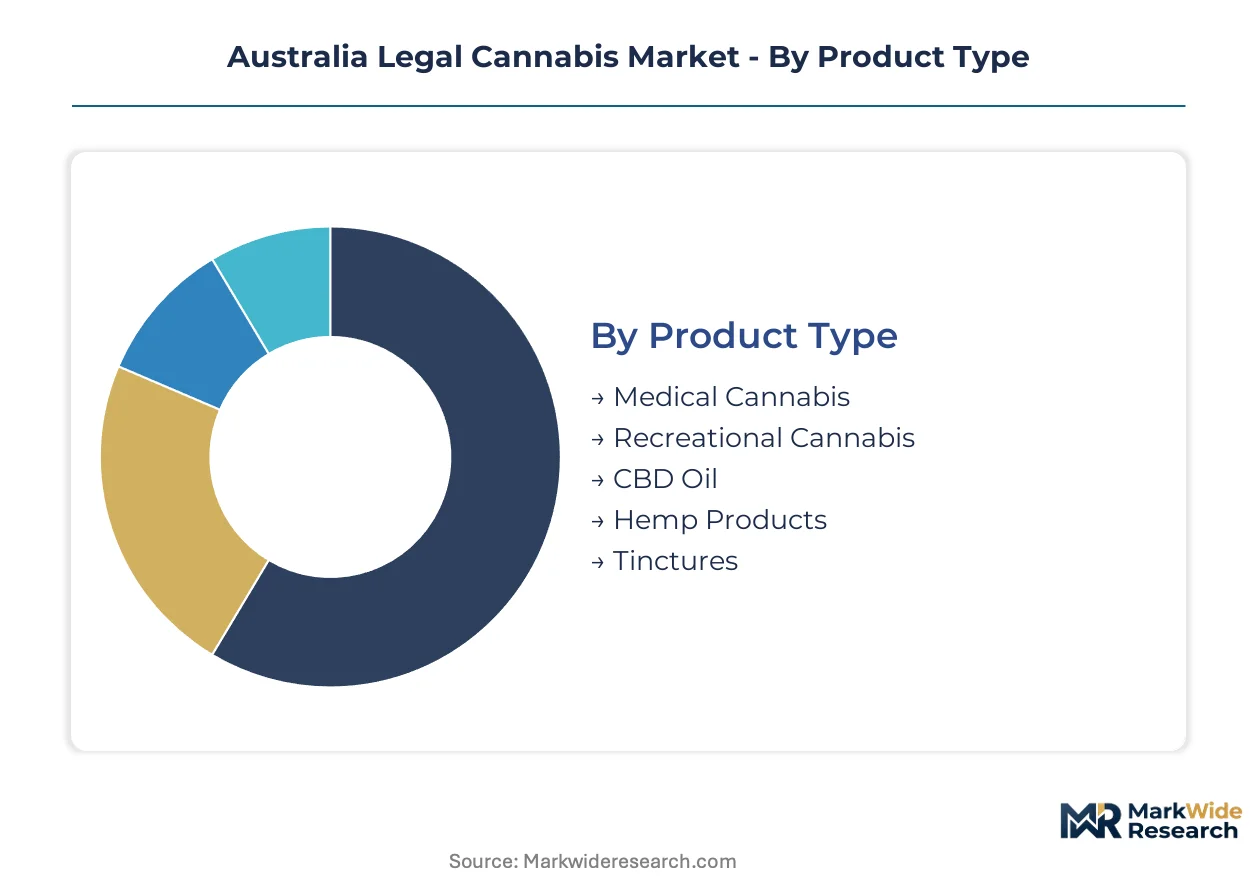
The Australian legal cannabis market's segmentation reveals distinct value pools and access points for patients. Understanding these categories helps stakeholders navigate regulatory complexities and identify areas of concentrated demand. This structured analysis provides clarity on product evolution and therapeutic application.
Product Type:
The legal cannabis market in Australia exhibits a clear split between high-volume, lower-potency products and premium, pharmaceutical-grade offerings.
- Medical Cannabis:These products, including oils, tinctures, and dried flower, contain defined concentrations of cannabinoids like THC and CBD. They are accessible only through medical prescription for therapeutic use, forming the core regulated market.
- CBD Oil:Available under different regulatory schedules, these products represent a high-volume segment with expanding use in wellness-focused applications through pharmacies. Patient access for CBD oils is broadening significantly.
- Recreational Cannabis:This category remains illegal for sale and consumption in Australia, with strict penalties for possession and distribution.
- Hemp Products:These items are derived from industrial hemp, typically containing negligible THC, and are primarily used for food, fiber, or cosmetic purposes.
- Tinctures:Liquid cannabis extracts designed for sublingual administration, offering precise dosing and typically used within the medical prescription framework.
Today's leader: Medical Cannabis. Tomorrow's challenger: CBD Oil.
Application:
Therapeutic applications define the primary demand channels for legal cannabis products across Australia.
- Pain Management:This application constitutes a significant portion of prescription volumes, driven by persistent demand for alternatives to traditional analgesics. Growing physician and patient education supports its continued expansion.
- Anxiety Relief:Increasing prescription volumes for anxiety disorders reflect a growing acceptance of cannabis-based therapies for mental health conditions. Patient demand is particularly strong in populous urban centers.
- Epilepsy Treatment:Specific cannabinoid formulations have demonstrated efficacy in treating certain forms of epilepsy, especially in pediatric cases, driving specialized prescribing.
- Cancer Therapy:Cannabis products are often prescribed to manage cancer-related symptoms such as nausea, appetite loss, and neuropathic pain, improving patient quality of life.
- Sleep Disorders:Patients are increasingly seeking cannabis solutions for insomnia and other sleep disturbances, often after conventional treatments prove ineffective.
Pain Management represents the fastest-growing trajectory for prescribed cannabis products.
End User:
End-user channels dictate patient access and product formulation requirements within the regulated Australian market.
- Pharmacies:These retail outlets are increasingly dispensing prescribed medical cannabis and low-concentration CBD wellness products, enhancing patient accessibility. A growing network of pharmacies is obtaining necessary licenses.
- Clinics:Specialized cannabis clinics, particularly in New South Wales and Victoria, serve as primary consultation points for patients seeking medical prescriptions. These clinics provide expert guidance on cannabinoid therapies.
- Dispensaries:While less prevalent than in other regions, a limited number of dedicated dispensaries operate under strict regulatory oversight for medical cannabis distribution.
- Hospitals:Medical cannabis is occasionally administered or prescribed within hospital settings for specific conditions, often in conjunction with specialist care.
- Wellness Centers:These facilities may offer general health advice and non-prescription hemp-derived products, but they do not dispense regulated medical cannabis.
Clinics are driving patient consultation volumes, while pharmacies are expanding product dispensing reach.
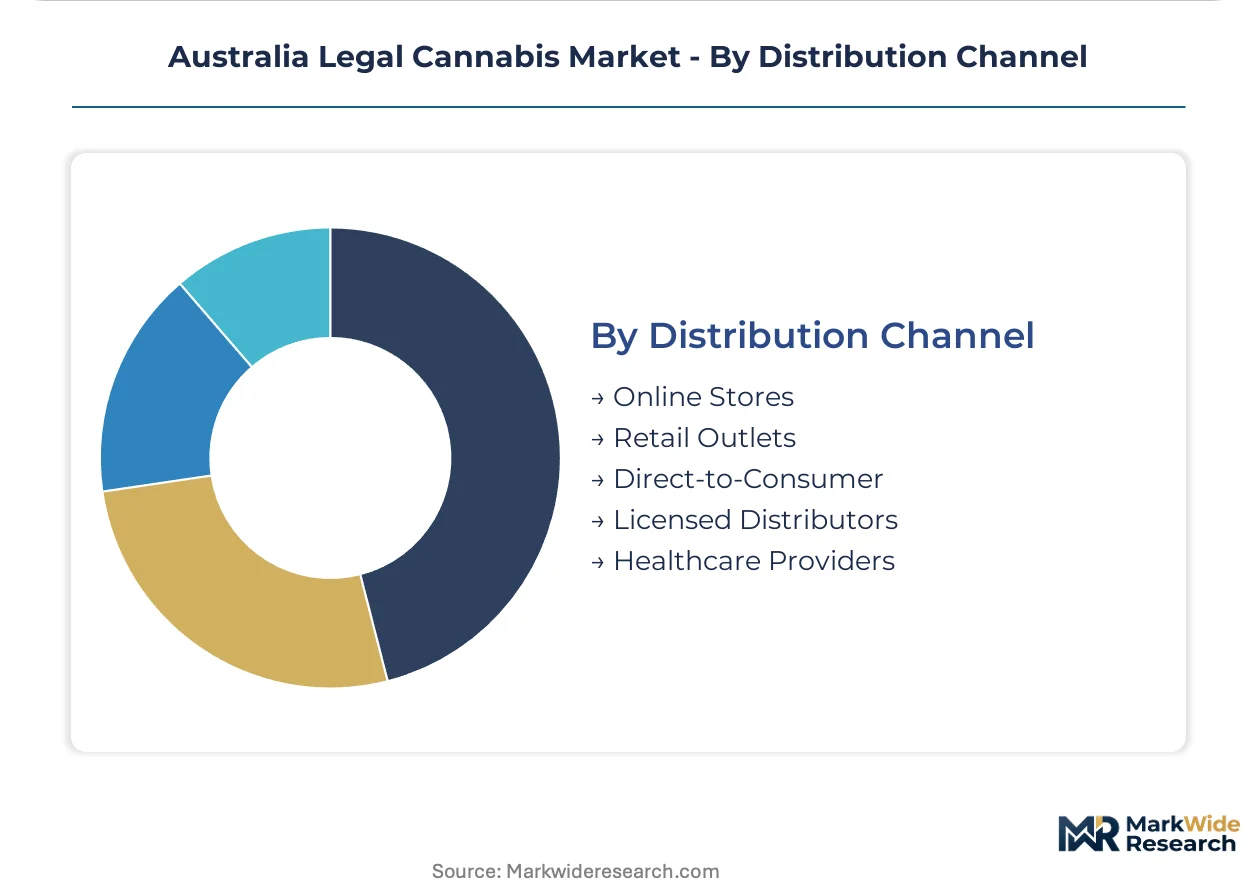
Distribution Channel:
Supply concentration through regulated distribution channels ensures product integrity and patient safety in Australia.
- Healthcare Providers:This channel encompasses authorized prescribers and dispensing pharmacies, forming the backbone of patient access to legal medical cannabis. The TGA's schemes streamline this process.
- Licensed Distributors:Companies holding Office of Drug Control licenses facilitate the secure movement of medicinal cannabis products from cultivators and manufacturers to pharmacies and clinics. Supply chain security is paramount.
- Online Stores:While some online platforms sell hemp products or provide information, direct online sales of prescription medical cannabis are highly regulated and limited.
- Retail Outlets:General retail outlets primarily stock hemp-derived food products and non-therapeutic items, not regulated medical cannabis.
- Direct-to-Consumer:This model is highly restricted for medical cannabis, with most transactions requiring a healthcare provider intermediary.
Healthcare Providers remain central to patient access, with licensed distributors enabling secure supply chains and product traceability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While Canada's legal cannabis market embraces recreational sales, Australia's market maintains a strict medical-only framework. This medical-centric approach has shaped distinct regional dynamics within the country, with demand concentrating in populous states. Evolving TGA schemes and practitioner-led pathways drive this localized growth.
New South Wales
Persistent demand for chronic pain management and anxiety relief drives significant prescription volumes in New South Wales. The Therapeutic Goods Administration's Special Access Scheme facilitates patient access across the state. Sydney acts as a primary hub for specialized cannabis clinics, enhancing patient consultation and prescribing activity. This concentration supports robust market growth.
Victoria
Victoria experiences strong patient uptake for sleep disorders and cancer-related symptom management. The Office of Drug Control ensures licensed cultivation and production facilities operate under strict guidelines. Melbourne houses a growing number of dispensing pharmacies, expanding the reach of medical cannabis products. Pharmaceutical-grade product development is also prominent here.
Queensland
Growing physician education and patient awareness for epilepsy treatment and palliative care contribute to market expansion in Queensland. State-level initiatives support the TGA's efforts to streamline access. Brisbane and the Gold Coast show increasing numbers of authorized prescribers, improving regional patient access. This area also sees interest in telehealth solutions.
Western Australia
Western Australia's market is characterized by demand for pain management and neurological conditions. The TGA's Authorised Prescriber scheme supports specialist doctor involvement. Perth serves as a key distribution point for medical cannabis products, ensuring supply chain integrity. Remote patient access is a significant focus for providers in this vast state.
Australia Legal Cannabis Market Key Industry Players
Top-tier vendors anchor the pharmaceutical-grade segment, while emerging players focus on niche therapeutic applications and CBD wellness products. The market structure is tiered, reflecting varying levels of capital investment and regulatory compliance for different product categories. Archetypes include large-scale cultivators, specialized formulation developers, and patient-centric clinic operators. Companies pursue clinical trial validation and geographic expansion within Australia as dominant competitive moves to secure market share.
Specialists in advanced cannabinoid formulations, Zelira Therapeutics leverages a clinical trial-led strategy for specific conditions and therapeutic validation. Little Green Pharma occupies a position as a provider of locally manufactured, GMP-certified oil-based medicines, emphasizing product quality and local supply chain control. Cann Group represents a key player in large-scale cultivation and genetic development, supplying essential raw materials for the industry's pharmaceutical-grade products. These companies exemplify the diverse approaches to product development and supply chain integration within the Australian legal cannabis market.
| Leading Market Players |
|---|
| Cann Group |
| Zelira Therapeutics |
| AusCann Group Holdings |
| Little Green Pharma |
| Althea Group |
| Vitura Health Limited |
| Bod Science |
| Ecofibre |
| Montu Group |
| Others |
Cost & Logistics Intelligence
Highly skilled labor for GMP-certified cannabis cultivation and processing in Australia drives higher production costs. This influences the premium pricing of pharmaceutical-grade medical cannabis compared to less regulated CBD wellness products, creating distinct pricing tiers.
Pricing Analysis
The bundled service model for medical cannabis consultations and product dispensing influences pricing, often combining per-unit transactional costs for products with consultation fees. Price differentiation stems from GMP certification level, specific cannabinoid formulation complexity, and brand reputation. Pricing softness reflects the availability of lower-cost Schedule 3 CBD products. Patients managing chronic pain show lower price sensitivity for effective medical products, while wellness consumers are highly sensitive to CBD oil costs.
Supply Chain Analysis
Cannabis biomass supply in Australia largely relies on domestic cultivation facilities operating under Office of Drug Control licenses. Raw material dependencies include high-quality cannabis biomass, specialized extraction solvents, and pharmaceutical-grade excipients. A structural risk involves regulatory restrictions and single-source vulnerability for specific genetic strains. Distribution runs through licensed distributors to pharmacies and specialized clinics, ensuring product integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's legal cannabis market presents a geographic-arbitrage opportunity, leveraging its strict medical-only framework and high GMP production standards. This creates a premium market compared to regions with recreational legality and lower cost structures.
For Market Incumbents: Deploy clinical trial validation to secure defensible market segments. Incumbents must invest in robust clinical trials for proprietary formulations targeting specific conditions like inflammatory bowel disease. Expanding local GMP manufacturing capacity further mitigates supply chain risks and strengthens product quality claims against regulatory scrutiny. This strategy also counters the competitive pressure from less-regulated CBD products.
For New Entrants and Emerging Players: Begin with telehealth platforms to bridge geographic access gaps in remote and regional Australia. New entrants can target underserved patient populations by connecting them with authorized prescribers. Focusing on niche therapeutic applications, such as specific neurological conditions, provides a clear differentiation strategy. Partnership with specialized medical practitioners offers a focused go-to-market approach.
For Investors and Strategic Acquirers: Pharmaceutical companies and large healthcare providers are the most active acquirers in this space. The market offers long-term viability over a 5-10 year window, driven by regulatory easing and clinical validation. Acquisition targets should possess strong clinical data and TGA-approved formulations for specific indications. The down-scheduling of certain cannabinoid compounds by the TGA is a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Validates product efficacy for specific conditions, building prescriber confidence and market share. |
| Regulatory Approval Pathway | Secures TGA registration for formulations, creating high barriers to entry for competitors. |
| Manufacturing Scale-Up | Reduces per-unit production costs for GMP-certified products, enhancing affordability and supply. |
| Telehealth Integration | Expands patient access to authorized prescribers, particularly in remote Australian regions. |
| Genetic Development Investment | Improves cannabinoid profiles and yield for cultivation, ensuring consistent raw material supply. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. This combined primary interviews with regulatory officials, medical cannabis prescribers, clinic operators, and pharmaceutical R&D leads, with secondary validation. Secondary data sources included TGA public records, ODC licensing databases, clinical trial registries, and academic literature. Bottom-up and top-down triangulation ensured data integrity.
Segment-weighting applied across product type, application, end-user, distribution channel, and regulatory schedule defined the market model. Volume and value projections across the analysis window derived from historical growth trends and projected market expansion factors. Compound annual growth rates extrapolated from these trends. Patient registration numbers, prescriber adoption rates, and product launch pipelines served as key forecast inputs.
Several conditions sit outside the modeled scope, including recreational cannabis legalization and unforeseen policy shifts. Forecasts reflect assumptions documented regarding current regulatory frameworks and market dynamics. Material deviation in TGA scheduling or ODC licensing triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
CBD Gummies Market
Cannabis/Marijuana
CBD Hemp Oil Market
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market
Cannabis/Marijuana
Cannabis Cultivation Market
Cannabis/Marijuana
Synthetic Cannabinoids Market
Cannabis/Marijuana
Global Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Asia-Pacific CBD Patch Market
Cannabis/Marijuana
Legal Marijuana Market
Cannabis/Marijuana
Missouri Legal Cannabis Market
Cannabis/Marijuana
Europe Cannabidiol (CBD) Market
Cannabis/Marijuana
CBD-Infused Products Market
Cannabis/Marijuana
Medical Marijuana Market
Cannabis/Marijuana
Electric Cannabis Grinders Market
Cannabis/Marijuana
Flavored CBD Powder Market
Cannabis/Marijuana
Cannabigerol (CBG) Market
Cannabis/Marijuana
North America Hemp-Derived Cannabidiol Market