
 Metastatic Breast Cancer Market | 2026-2036
Metastatic Breast Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Metastatic Breast Cancer Market Outlook
Multi-source biologics procurement is restructuring supply relationships across the metastatic breast cancer value chain. F. Hoffmann-La Roche anchors its position through captive manufacturing of HER2-directed antibody-drug conjugates. Eli Lilly and Company differentiates via endocrine innovation pipelines, while AstraZeneca competes aggressively in PARP and ADC segments through partnered development models.
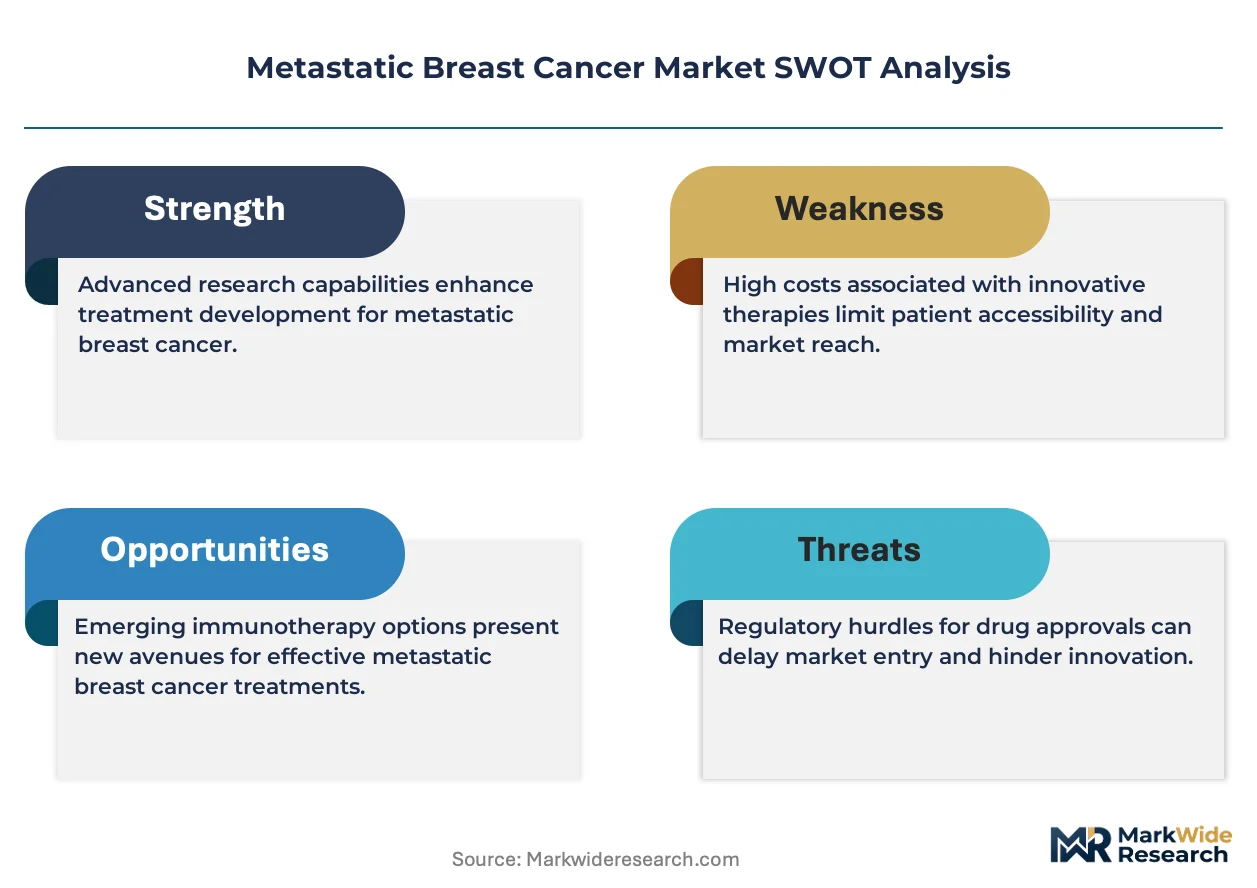
Metastatic breast cancer comprises breast malignancies that have disseminated beyond regional lymph nodes to distant organs, requiring systemic therapy with agents demonstrating median progression-free survival endpoints exceeding established thresholds in Phase III trials. Targeted therapy commands the deepest margin pools as biomarker-selective agents replace cytotoxic backbones in frontline settings. Hormonal therapy sustains durable revenue in hormone receptor-positive populations, while immunotherapy represents the fastest-expanding category despite narrower addressable populations.
FDA oncology center standards, EMA centralized marketing authorization pathways, and NMPA conditional approval frameworks collectively shape clinical trial design, labeling claims, and market access timelines across major jurisdictions. These regulators enforce escalating evidence requirements for accelerated approvals, directly influencing portfolio prioritization decisions among developers. Stakeholders must monitor evolving surrogate endpoint acceptability and post-approval confirmatory trial obligations to preserve commercial positioning.
Market Dynamics
Biomarker-driven patient stratification is restructuring therapeutic selection across the metastatic breast cancer landscape, as HER2, HR, and PD-L1 testing protocols displace empirical chemotherapy protocols in frontline oncology decision-making.
Growth Catalysts
- CMS Oncology Care Model:Value-based reimbursement pathways incentivize biomarker testing prior to therapy initiation, accelerating adoption of companion diagnostic workflows in United States oncology clinics.
- Antibody-drug conjugate platforms:HER2-directed and TROP2-targeting ADCs demonstrate superior progression-free survival versus standard-of-care cytotoxic regimens in Phase III head-to-head trials.
- Japan's PMDA Sakigake designation:Conditional early approval frameworks compress development timelines for breakthrough oncology therapies, attracting sponsor investment in Japan-first registration strategies.
Market Restraints
- Platinum and cytotoxic raw material volatility:Supply concentration for ADC linker-payload chemistries in Chinese and Indian API manufacturers creates input cost instability and qualification delays.
- EMA accelerated approval conditionalities:Post-marketing confirmatory trial obligations impose substantial follow-on investment burdens, with withdrawal risks for therapies failing to replicate early efficacy signals.
- CDK4/6 inhibitor commoditization:Patent expirations and multi-source generic entry compress pricing power in hormone receptor-positive segments, eroding branded endocrine combination margins.
Strategic Opportunities
- Germany's DiGA fast-track pathway:Digital health application reimbursement creates adjacent revenue streams for patient monitoring and adherence tools companion to systemic therapy.
- Brain metastasis penetration:Blood-brain barrier-crossing small molecules and ADCs address an underserved patient population with limited systemic options and high unmet need.
- Artificial intelligence and pathology convergence:Computational biomarker quantification from H&E slides reduces testing turnaround and expands community oncology access to precision selection.
Industry Challenges
- Biomarker assay harmonization:Discordance between central laboratory and point-of-care testing platforms creates treatment selection uncertainty, requiring standardization investments across diagnostic vendors.
- Cell therapy manufacturing scale-up:Autologous CAR-T and TIL therapy production demands specialized GMP infrastructure and skilled vector manufacturing personnel that outpace current workforce supply.
- Real-world evidence collection infrastructure:Post-approval safety and effectiveness monitoring requires interoperable electronic health record systems that fragmented hospital IT environments struggle to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metastatic Breast Cancer Market |
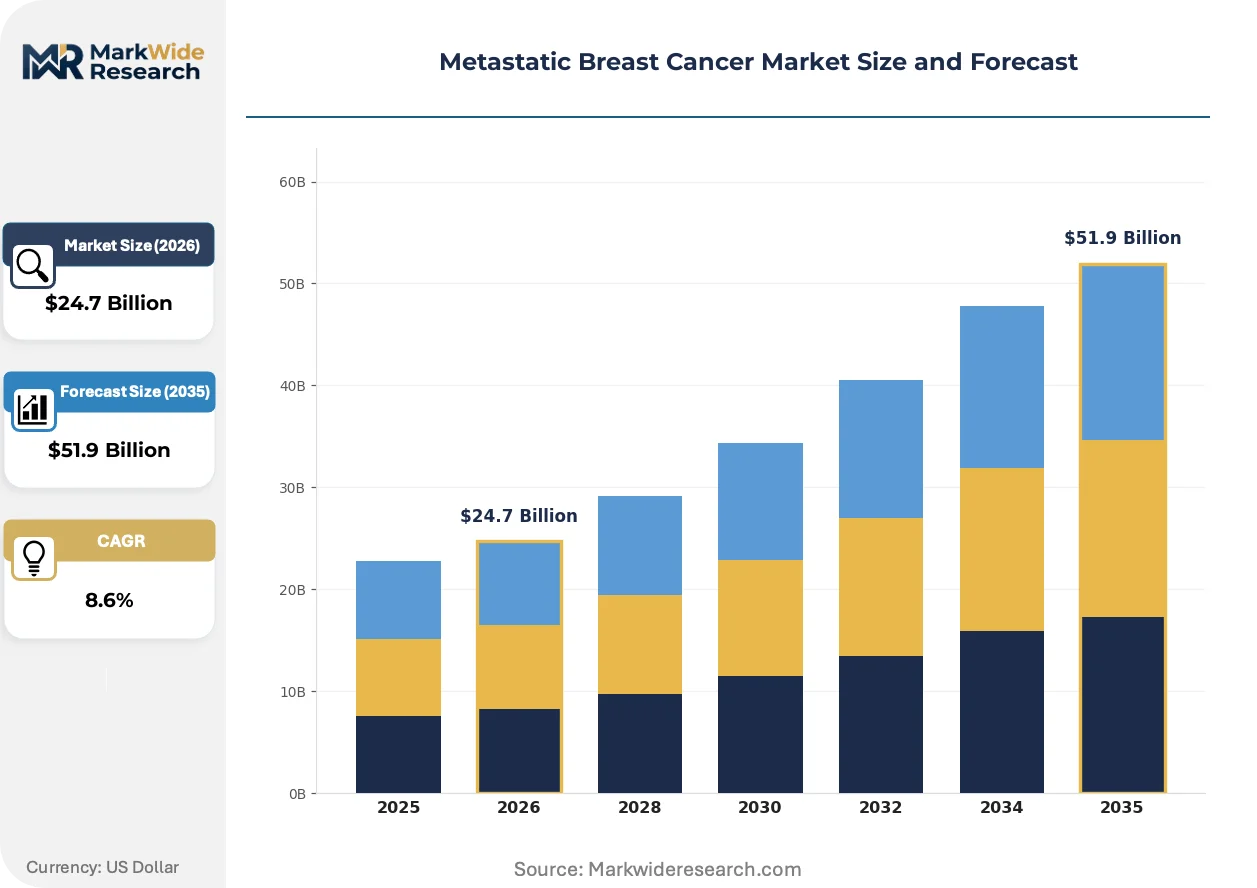
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $51.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Hormonal Therapy, Targeted Therapy, Immunotherapy Treatment Line: First-line, Second-line, Third-line, Combination End User: Oncology Clinics, Hospitals, Diagnostic Laboratories, Homecare Administration Route: Intravenous, Oral, Subcutaneous, Intramuscular |
| Companies Covered | F. Hoffmann-La Roche, Eli Lilly and Company, AstraZeneca, Novartis AG, Pfizer Inc., Merck & Co., Bayer AG, Bristol-Myers Squibb, MacroGenics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metastatic Breast Cancer Market Strategic Shifts
Next-generation sequencing is displacing single-analyte immunohistochemistry as the frontline diagnostic modality, compressing time-to-treatment initiation while expanding actionable alteration detection beyond established companion diagnostic indications.
Artificial intelligence-powered image analysis is automating tumor-infiltrating lymphocyte quantification and treatment response assessment, enabling pathologists at community hospitals to deliver academic-center-equivalent biomarker reporting without specialist on-site presence.
FDA's Project Optimus dose-optimization mandate is reshaping dose-selection paradigms for oncology therapies, requiring sponsors to generate randomized exposure-response data rather than defaulting to maximum-tolerated-dose strategies established in cytotoxic eras.
Oncology procurement at integrated delivery networks is consolidating vendor relationships and demanding outcome guarantees, compressing formulary positions for therapies lacking differentiated real-world performance data and replacing traditional rebate-driven contracting with total-cost-of-care agreements.
Metastatic Breast Cancer Market Segmentation
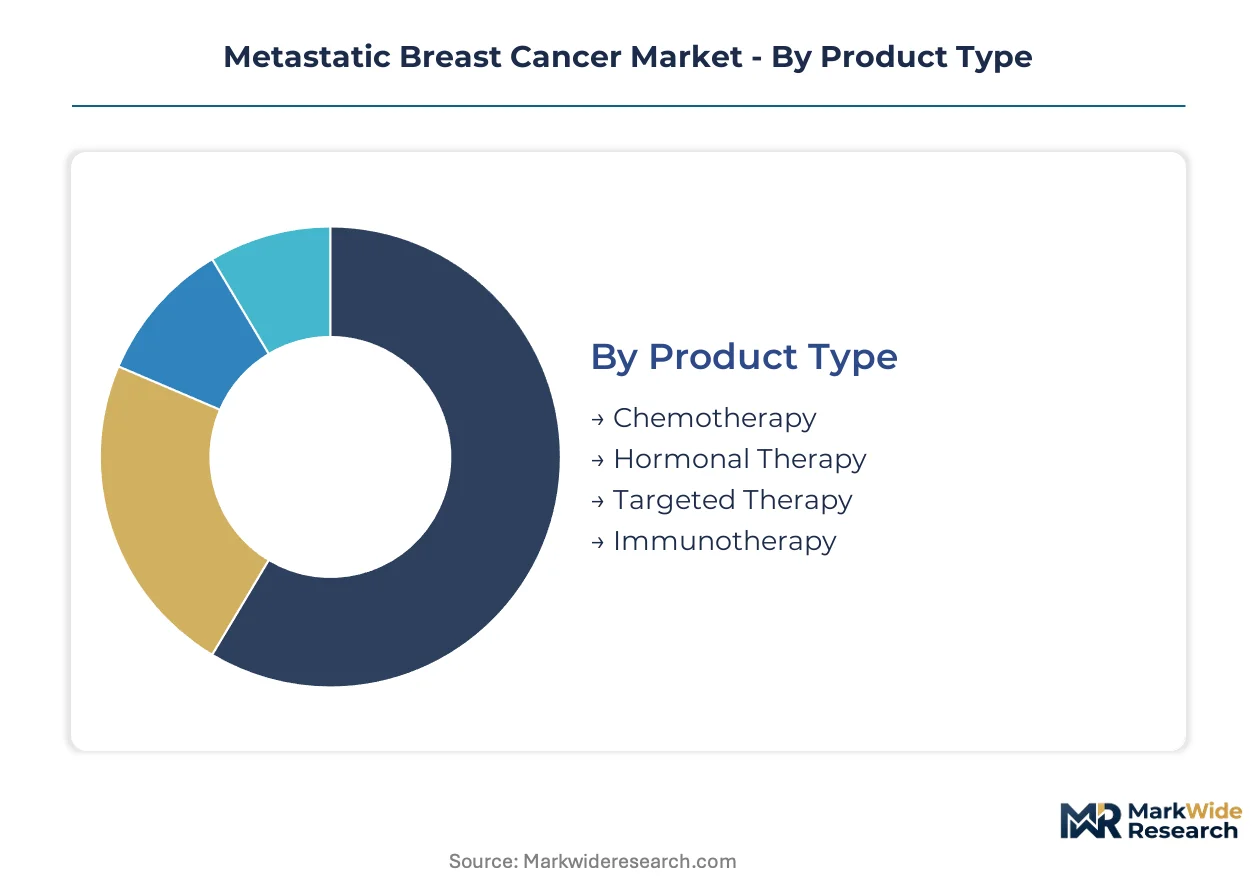
Segmentation in metastatic breast cancer reveals how treatment selection diverges across biomarker status, prior therapy exposure, and care delivery setting. Each dimension carries distinct reimbursement pathways and clinical decision logic that shapes commercial prioritization.
Product Type:
Cost tier separates these modalities, with biologics commanding premium positioning against small-molecule backbones.
- Targeted Therapy:HER2-directed antibody-drug conjugates and CDK4/6 inhibitors demonstrate superior progression-free survival in biomarker-selected populations. United States oncology clinics prioritize these agents under CMS Oncology Care Model incentives that reward biomarker-driven selection over empirical chemotherapy.
- Immunotherapy:PD-1/PD-L1 checkpoint inhibitors address triple-negative subtypes with high tumor mutational burden. Japan's PMDA Sakigake designation accelerates access for novel immunotherapy combinations, attracting sponsor investment in accelerated approval pathways.
- Chemotherapy:Cytotoxic backbones retain utility in later-line settings where targeted options exhaust.
- Hormonal Therapy:Endocrine agents sustain long-duration maintenance in hormone receptor-positive disease.
Volume sits with hormonal therapy; growth tilts toward targeted therapy.
Treatment Line:
Application sequence determines regulatory evidence requirements and pricing power, with frontline settings demanding randomized Phase III data.
- First-line:Initial systemic therapy for de novo metastatic disease or early relapse requires comprehensive biomarker profiling. Germany's statutory health insurance funds mandate companion diagnostic confirmation before reimbursing targeted first-line regimens.
- Combination:Multi-agent protocols integrate targeted and cytotoxic components to delay resistance. Academic medical centers in the United States drive adoption of combination strategies through clinical trial enrollment and protocol development.
- Second-line:Post-progression therapy switches mechanism of action based on emerging resistance patterns.
- Third-line:Late-line options emphasize quality-of-life endpoints and oral administration convenience.
Revenue concentrates in first-line; pipeline investment flows heaviest into combination approaches.
End User:
Customer type dictates procurement scale and decision-making authority, from institutional formulary committees to individual prescribing oncologists.
- Oncology Clinics:Ambulatory infusion centers administer the majority of intravenous biologics and perform real-time treatment response monitoring. United States community oncology practices consolidate purchasing through group purchasing organizations to negotiate rebate structures with manufacturers.
- Hospitals:Inpatient oncology units manage acute complications and administer complex combination regimens requiring intensive monitoring.
- Diagnostic Laboratories:Centralized and point-of-care testing facilities process biomarker assays that gate therapy access.
- Homecare:Subcutaneous and oral agents enable administration outside clinical settings, reducing healthcare utilization costs.
Patient volume flows through oncology clinics; service expansion is gaining share fastest in homecare.
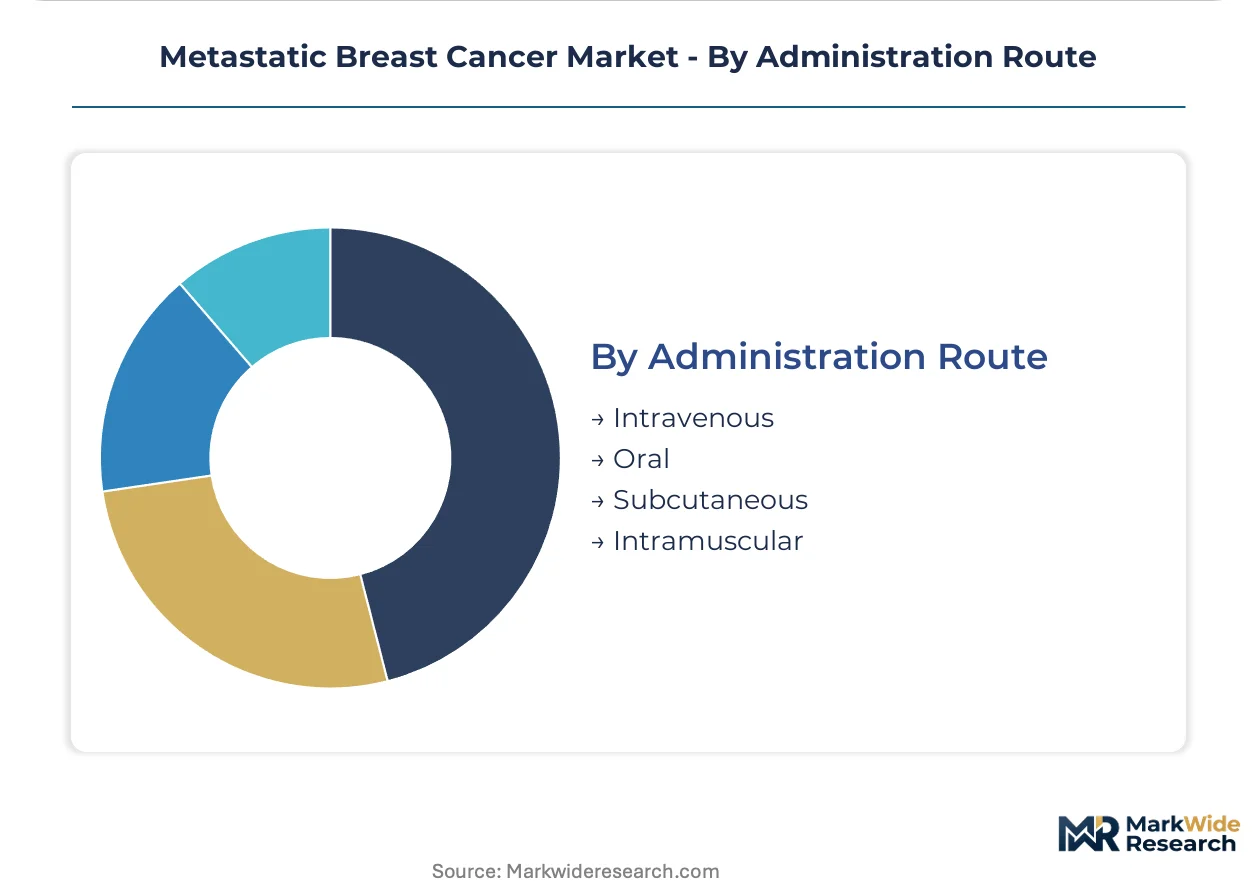
Administration Route:
Supply concentration varies by delivery complexity, with parenteral formulations demanding specialized manufacturing and cold-chain logistics.
- Intravenous:Infusion-dependent biologics require healthcare facility administration and skilled nursing oversight. Japanese hospital pharmacies maintain tight inventory control over intravenous oncology products through centralized procurement systems.
- Oral:Small-molecule kinase inhibitors and endocrine agents enable patient self-administration with adherence monitoring. German sickness funds increasingly favor oral equivalents where available to reduce day-clinic reimbursement burdens.
- Subcutaneous:Self-injectable formulations reduce healthcare facility dependency for maintenance therapy.
- Intramuscular:Depot formulations support extended-release hormonal therapy with reduced injection frequency.
Utilization remains dominated by intravenous delivery; formulation development is climbing the fastest toward subcutaneous alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum and cytotoxic raw material supply from Chinese and Indian API manufacturers anchors geographic demand distribution across metastatic breast cancer therapeutic markets.
United States
Oncology clinics concentrate patient volume in Texas, Florida, and California metro corridors where integrated delivery networks negotiate outcome-based contracts. FDA's Project Optimus dose-optimization mandate reshapes clinical trial design requirements. The Greater Boston biopharma cluster drives early-stage ADC development through academic medical center partnerships.
Germany
Statutory health insurance funds mandate companion diagnostic confirmation before reimbursing targeted first-line regimens in North Rhine-Westphalia and Bavaria. EMA accelerated approval conditionalities impose post-marketing confirmatory trial obligations. The Munich-Frankfurt corridor hosts centralized pathology laboratories processing biomarker assays for community oncology access.
Japan
PMDA Sakigake designation attracts sponsor investment in accelerated approval pathways for novel immunotherapy combinations. Tokyo and Osaka academic medical centers drive adoption of combination strategies through clinical trial enrollment. The Kanto region maintains tight hospital pharmacy inventory control over intravenous oncology products through centralized procurement systems.
United Kingdom
NICE technology appraisals govern NHS England access decisions for HER2-directed antibody-drug conjugates in London and the Southeast. MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for breakthrough oncology therapies. The Cambridge-London life sciences corridor supports computational biomarker quantification from H&E slides.
China
NMPA conditional approval frameworks compress development timelines for domestic biopharma developers in Shanghai and Suzhou biotech parks. National reimbursement drug list negotiations determine market access for CDK4/6 inhibitors. The Yangtze River Delta concentrates ADC linker-payload chemistry manufacturing capacity.
Metastatic Breast Cancer Market Competitive Environment
Strategic partnerships dominate the current landscape as developers seek to share antibody-drug conjugate platform risk and expand biomarker-directed therapy portfolios. The market structure consolidates around large-cap biopharma with captive manufacturing infrastructure, mid-tier specialists with partnered development models, and emerging biotech with novel target biology. Three archetypes define positioning: integrated biologics manufacturers with end-to-end ADC supply chains, endocrine innovation specialists with hormonal therapy depth, and immuno-oncology platform companies with checkpoint inhibitor combinations. M&A activity and technology licensing agreements represent the dominant competitive moves as firms acquire ADC payloads and companion diagnostic capabilities.
Within the integrated biologics tier, F. Hoffmann-La Roche and Novartis AG exemplify archetypes of captive manufacturing scale and global oncology commercial infrastructure. Among endocrine-focused developers, Eli Lilly and Company occupies a position representing hormonal therapy pipeline depth in hormone receptor-positive segments. These three anchors sit within distinct strategic vectors—ADC platform integration, endocrine mechanism expertise, and immuno-oncology combination development—each representing competitive positioning pathways visible across the broader market structure.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Eli Lilly and Company |
| AstraZeneca |
| Novartis AG |
| Pfizer Inc. |
| Merck & Co. |
| Bayer AG |
| Bristol-Myers Squibb |
| MacroGenics Inc. |
| Others |
Value Chain & Pricing Dynamics
Specialized vector manufacturing personnel in the Greater Boston biopharma cluster anchor labor-cost differentials that widen pricing-tier spreads between premium antibody-drug conjugates and standard cytotoxic backbones. ADC payload synthesis expertise concentrates in this corridor, forcing manufacturers to absorb premium wage structures or qualify lower-cost Asian facilities with extended validation timelines.
Pricing Analysis
Service bundling separates premium-tier ADCs with comprehensive patient support programs from unbundled chemotherapy alternatives where adherence monitoring carries separate charges. Three-tier pricing structure across premium, standard, and economy levels reflects biomarker specificity, with HER2-directed agents commanding brand premiums over TROP2-targeting follow-ons. Pricing pressure stems from CDK4/6 inhibitor commoditization as multi-source generics enter hormone receptor-positive segments. Community oncology practices exhibit highest price sensitivity due to CMS Oncology Care Model risk-sharing, while academic medical centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
GMP certification and FDA pre-approval inspection gating constrain supplier qualification for ADC linker-payload chemistries, compressing approved vendor pools. Manufacturing concentrates in China, India, and Switzerland for cytotoxic raw materials and sterile fill-finish capacity. Supply chains draw from platinum-group metals, maytansinoid payloads, and synthetic linker technologies with concentrated API sourcing. Single-source vulnerability runs through Chinese manufacturers of cytotoxic warheads subject to environmental regulatory enforcement. Distribution runs through integrated delivery networks and group purchasing organizations in the United States, with hospital pharmacy centralization in Japan and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibody-drug conjugate platforms are displacing empirical chemotherapy protocols as the dominant therapeutic modality, creating portfolio-restructuring imperatives across developer archetypes.
For Market Incumbents: Acquire companion diagnostic capabilities and biomarker assay platforms to lock in frontline patient selection. Eli Lilly and Company and F. Hoffmann-La Roche should deepen backward integration into ADC payload manufacturing to defend margins against linker-chemistry supply volatility. CDK4/6 inhibitor commoditization threatens hormonal therapy combination revenues, requiring accelerated investment in next-generation endocrine mechanisms. For New Entrants and Emerging Players: The mid-tier pricing gap between premium HER2-directed ADCs and generic cytotoxic backbones offers entry positioning for biosimilar ADC developers with abbreviated regulatory pathways. Brain metastasis penetration represents the most penetrable white-space indication, with limited blood-brain barrier-crossing competition. Target Germany's DiGA fast-track pathway for digital health companion applications to differentiate beyond molecule-only offerings. For Investors and Strategic Acquirers: Re-rating potential sits with immuno-oncology platform companies with checkpoint inhibitor combinations given PD-L1 testing expansion in triple-negative subtypes. Long-term viability across the projection horizon favors developers with diversified ADC pipelines spanning multiple target antigens. Monitor EMA accelerated approval conditionalities as signal for withdrawal risk and post-marketing investment burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | CMS reimbursement pathways reward biomarker-driven selection over empirical chemotherapy in United States oncology clinics. |
| ADC Payload Manufacturing Scale-Up | Captive linker-payload chemistry production insulates against Chinese and Indian API supply volatility. |
| Brain Metastasis Indication Expansion | Blood-brain barrier-crossing formulations address underserved populations with premium pricing potential. |
| Digital Health Companion Development | Germany's DiGA pathway creates adjacent revenue streams for patient monitoring and adherence tools. |
| Japan-First Registration Strategy | PMDA Sakigake designation compresses timelines for novel immunotherapy combinations in Tokyo and Osaka centers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this metastatic breast cancer market analysis. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists validated assumptions on biomarker testing adoption and reimbursement pathway evolution. Secondary sources included FDA oncology center guidance documents, EMA centralized marketing authorization submissions, ClinicalTrials.gov protocol registries, and CMS Medicare claims data. Bottom-up patient-flow modeling and top-down therapeutic class revenue triangulation converged on segment-level estimates.
Reconciliation of prescription audit data, hospital procurement databases, and manufacturer reported volumes stabilized baseline estimates across the modeling period. Segmentation dimensions modeled encompassed treatment line, biomarker status, administration route, and regional regulatory cluster. CAGRs emerged from fitted growth curves calibrated to historical approval velocity and analog therapeutic class penetration patterns. Forecast inputs incorporated companion diagnostic co-approval rates, accelerated approval pathway utilization, and post-marketing confirmatory trial success probabilities.
Underlying measurement precision varies by segment; first-line targeted therapy estimates carry tighter precision than third-line chemotherapy projections due to more robust clinical trial disclosure. Forecasts reflect assumptions on biomarker testing expansion, reimbursement policy stability, and competitive entry timing that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
BRCA Mutation-Positive Ovarian Cancer Market
Oncology
PD1 Resistant Head and Neck Cancer Market
Oncology
Tumor Lysis Syndrome Market
Oncology
Global Proton Therapy Market
Oncology
Global Metastatic Cancer Treatment Market
Oncology
Asia-Pacific Radiation Oncology Market
Oncology
Tumor Ablation Market
Oncology
Unresectable Hepatocellular Carcinoma Market
Oncology
Vulvar Cancer Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Precision Oncology Market
Oncology
Global Skin Cancer Diagnostics and Therapeutics Market
Oncology
Breast Cancer Liquid Biopsy Market
Oncology
Radiation Oncology Market
Oncology
Global Genomics in Cancer Care Market
Oncology
Europe Proton Therapy Market