
 Thiodiglycol Market | 2026-2036
Thiodiglycol Market Size, Share, and Industry Trends Forecast 2026-2036
Thiodiglycol Market Outlook
Pharmaceutical-grade specifications are rotating toward the center of competitive strategy as downstream buyers tighten purity thresholds for solvent and intermediate applications. BASF SE leverages its integrated precursor supply chain to sustain cost advantages across European and Asian markets. Huntsman International LLC anchors its position through specialized thiodiglycol derivatives for polymer manufacturing. LANXESS differentiates via controlled impurity profiles that meet pharmaceutical excipient standards.
Thiodiglycol is a dithioether diol with the molecular formula C4H10O2S, produced primarily through the reaction of ethylene oxide with hydrogen sulfide, functioning as a solvent, chemical intermediate, and stabilizer in organic synthesis. Industrial-grade material dominates current volume flows, serving agrochemical and general chemical manufacturing applications where cost efficiency outweighs purity premiums. Pharmaceutical-grade output represents the fastest-expanding segment, as CDSCO and FDA-aligned quality protocols widen the margin pool for certified producers. Cosmetic-grade supply occupies a narrower niche, constrained by formulation-specific dermatological testing requirements that limit supplier qualification.
EPA standards in the United States and REACH registration requirements in Europe jointly elevate compliance costs for non-specialized producers, effectively filtering market access toward integrated manufacturers with analytical capabilities. China's NMPA and GB standards impose parallel purity and documentation obligations on pharmaceutical-grade exports, creating a multi-jurisdictional compliance landscape. Stakeholders must monitor regulatory divergence between major import markets to anticipate reformulation costs and certification timelines.
Market Dynamics
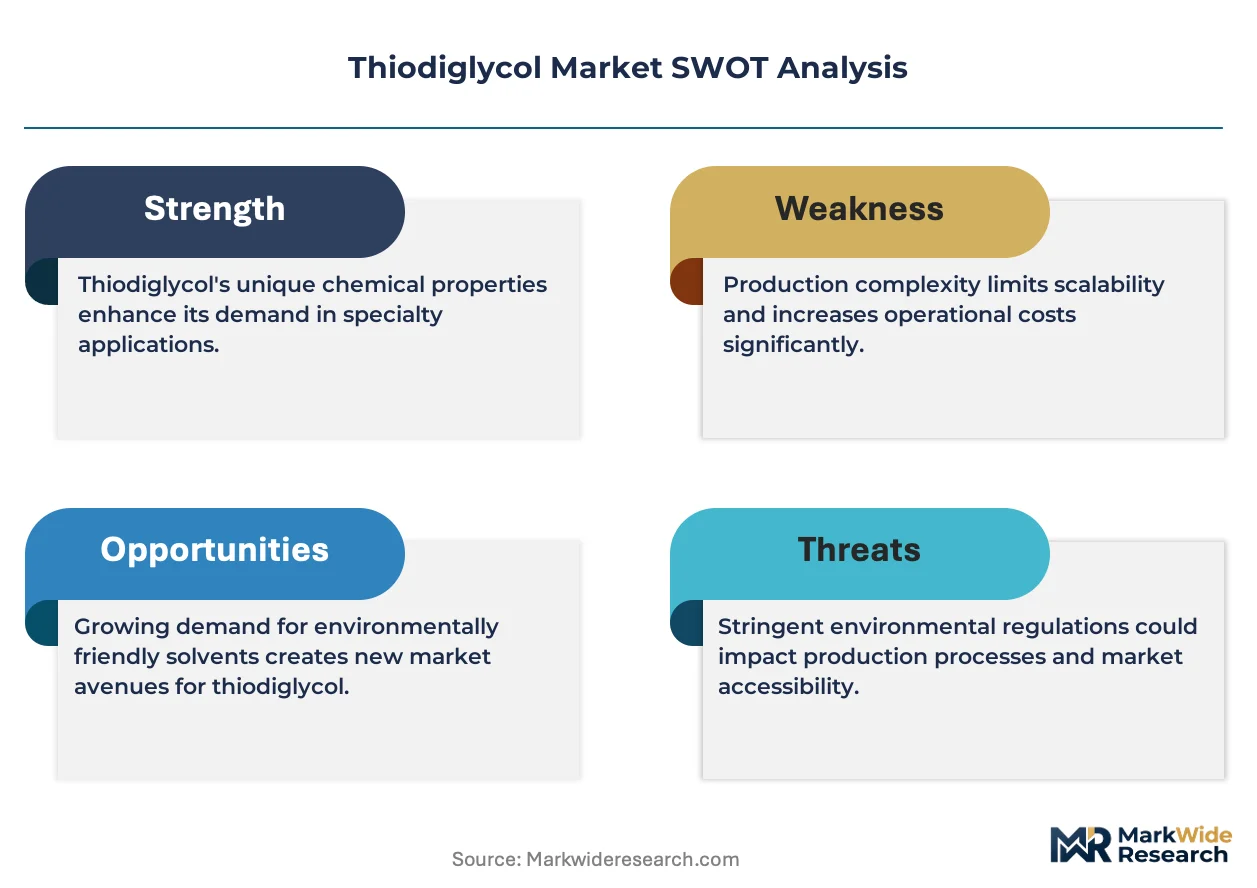
Pharmaceutical-grade purity specifications are compressing margins for commodity producers while rewarding integrated manufacturers with analytical capabilities and captive precursor supply. This bifurcation between certified and industrial-grade supply is restructuring competitive positions across Asian and European production clusters.
Growth Catalysts
- REACH registration thresholds:European ECHA compliance mandates are filtering out non-specialized suppliers, consolidating volume toward certified producers with dedicated quality infrastructure.
- Agrochemical formulators:Sustained demand from crop protection manufacturers in India and China for thiodiglycol as a solvent and stabilizer in active ingredient synthesis.
- Ethylene oxide supply integration:Backward integration into precursor chemicals is lowering unit economics for manufacturers with captive ethylene oxide capacity.
Market Restraints
- Hydrogen sulfide cost volatility:Feedstock price swings tied to petroleum refining output and sulfur recovery economics compress margin predictability for non-integrated producers.
- Chinese production concentration:Over 60% of global capacity resides in Shandong and Jiangsu provinces, creating geographic supply risk and freight cost exposure for distant buyers.
- Diethylene glycol substitution:Lower-cost glycols are penetrating industrial solvent applications where purity thresholds permit formulation flexibility.
Strategic Opportunities
- CDSCO-aligned pharmaceutical exports:Indian formulators seeking US FDA and European EMA qualification are creating certified-grade demand that domestic producers can capture with upgraded quality systems.
- Cosmetic-grade dermatological testing:Formulation-specific safety documentation for personal care applications represents an underserved premium segment with limited qualified suppliers.
- Green chemistry solvent mandates:EU Green Deal procurement preferences for bio-based and reduced-toxicity solvents are elevating thiodiglycol's position versus petroleum-derived alternatives in public sector purchasing.
Industry Challenges
- Analytical chemistry talent scarcity:Qualified personnel for impurity profiling and regulatory documentation are concentrated at large integrated manufacturers, constraining mid-tier facility upgrades.
- Multi-jurisdictional certification timelines:Parallel NMPA, FDA, and EMA qualification processes for pharmaceutical-grade output extend product launch cycles by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thiodiglycol Market |
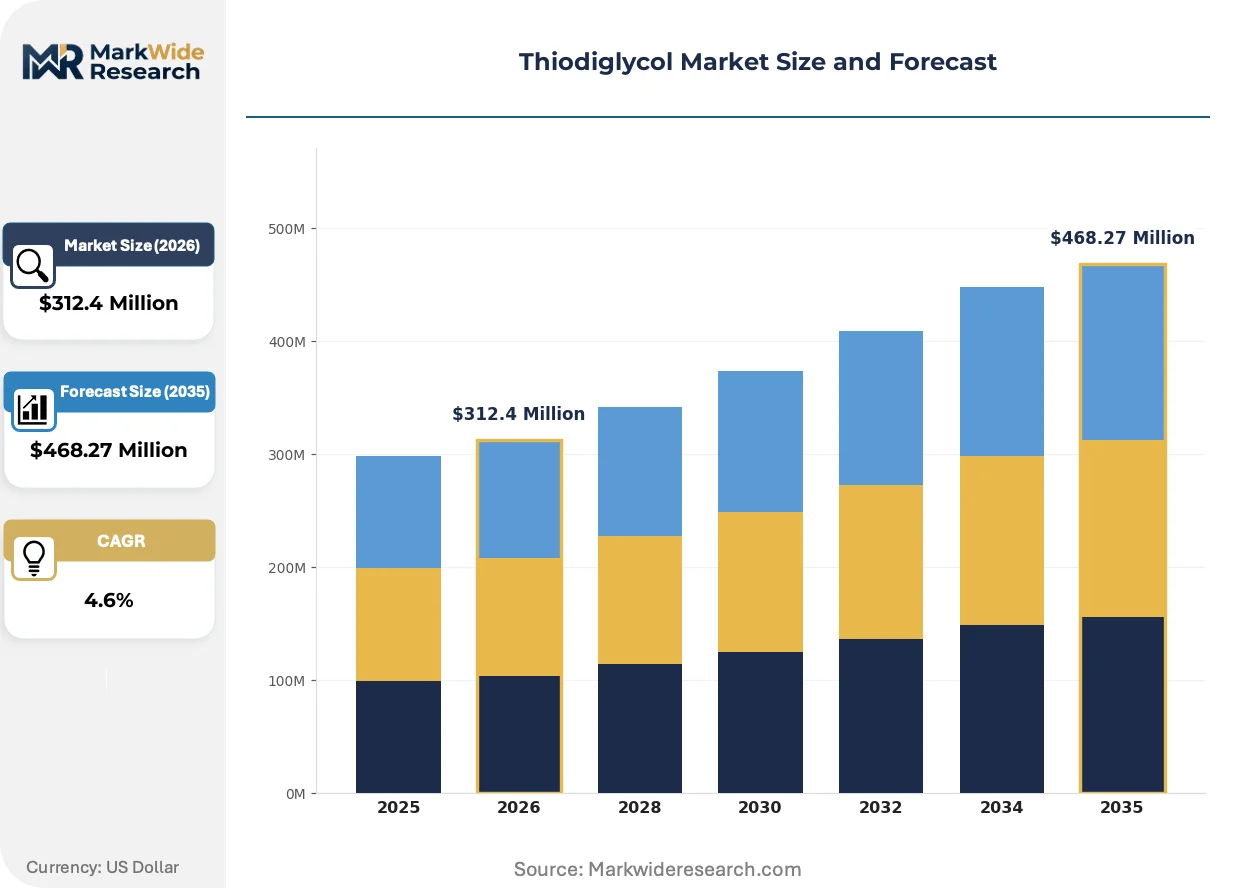
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $468.27 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Cosmetic Grade, Pharmaceutical Grade, Food Grade Application: Chemical Manufacturing, Agriculture, Pharmaceuticals, Cosmetics End User: Manufacturers, Distributors, Retailers, Research Institutions Delivery Mode: Bulk, Drums, Bottles, Containers |
| Companies Covered | BASF SE, Maoming Yunlong Industrial Development Co., Ltd., SONGWON Industrial Co., Ltd., LANXESS, Huntsman International LLC, The Dow Chemical Company, Eastman Chemical Company, TOYOBO, Actylis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thiodiglycol Market Strategic Shifts
Continuous processing technology and real-time analytical monitoring are displacing batch manufacturing economics in thiodiglycol production. These shifts are compressing capital intensity while tightening purity consistency.
Membrane-based purification is supplanting traditional distillation sequences in pharmaceutical-grade production lines. Specialty chemical manufacturers in Germany and Switzerland are adopting ceramic nanofiltration modules to achieve sub-ppm impurity levels without thermal degradation. This technology is enabling single-train facilities to serve multiple regulatory jurisdictions with minimal reconfiguration.
REACH Annex XVII restrictions on residual ethylene oxide content are forcing reformulation of legacy thiodiglycol specifications. European chemical distributors are now requiring certificates of analysis with quantified epoxide levels below 10 ppm. Agrochemical intermediates producers serving EU export markets are absorbing testing costs or switching to certified suppliers with established compliance documentation.
Specification-driven supplier consolidation is visible among Indian pharmaceutical intermediates manufacturers. Large formulators in Hyderabad and Ahmedabad are reducing qualified vendor lists from 15-20 to 3-5 strategic partners with integrated quality systems. This concentration is shifting negotiation leverage toward manufacturers with captive testing laboratories and documented regulatory correspondence histories.
Thiodiglycol Market Segmentation
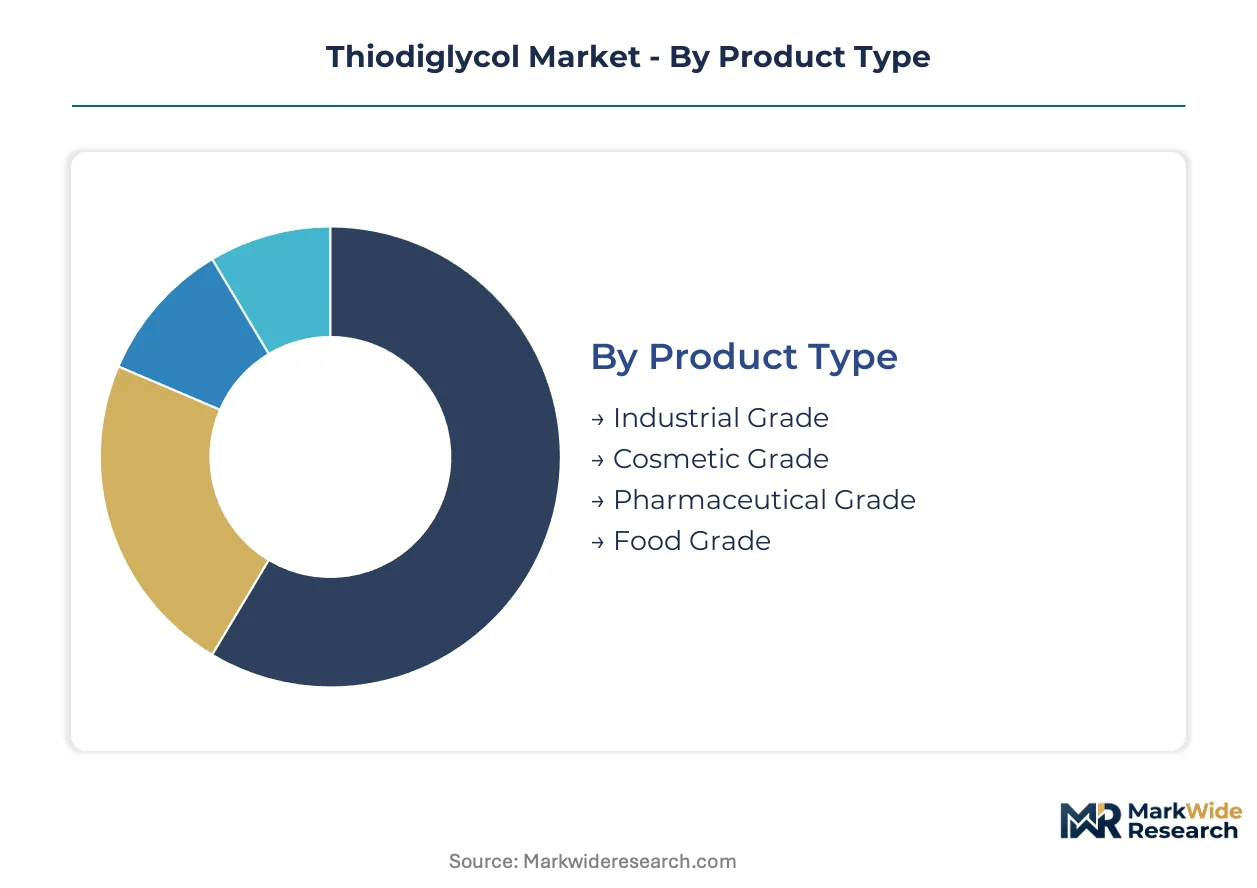
Thiodiglycol's market architecture reflects diverging purity requirements across regulated and unregulated applications. Substitution pressures vary sharply by segment, with industrial-grade material facing the strongest competitive threat from lower-cost glycols while pharmaceutical-grade commands defensive positioning through certification barriers.
Product Type:
Substitution pressure intensifies downward through the purity spectrum, with industrial-grade formulations absorbing the bulk of diethylene glycol displacement while certified grades build protective moats around analytical infrastructure investments.
- Industrial Grade:Standard specifications tolerate higher impurity loads for agrochemical solvents and general chemical synthesis. Demand concentrates among Shandong-based agrochemical formulators serving domestic crop protection markets, though margin compression from diethylene glycol substitution is accelerating supplier consolidation.
- Pharmaceutical Grade:Stringent purity protocols align with FDA, EMA, and NMPA documentation requirements for solvent and intermediate applications. Hyderabad and Ahmedabad pharmaceutical manufacturers are reducing qualified vendor lists, concentrating procurement toward integrated producers with captive testing laboratories.
- Cosmetic Grade:Dermatological safety documentation requirements limit supplier qualification to a narrow tier of certified producers. Formulation-specific testing protocols create sticky customer relationships once initial qualification is achieved.
- Food Grade:FSSAI and FDA food contact regulations impose parallel purity and migration testing obligations. The segment occupies a constrained niche with limited production capacity relative to pharmaceutical-grade infrastructure.
Industrial Grade retains volume leadership; Pharmaceutical Grade holds the steepest expansion curve.
Application:
Cost-tier stratification separates commodity chemical manufacturing from regulated pharmaceutical and cosmetic applications, with purity premiums widening the economic distance between adjacent tiers.
- Chemical Manufacturing:Solvent and stabilizer functions in organic synthesis dominate tonnage flows. Jiangsu province chemical clusters consume substantial industrial-grade volumes for intermediates production where specification flexibility permits cost optimization.
- Pharmaceuticals:Solvent applications in active pharmaceutical ingredient synthesis and excipient formulations demand documented impurity profiles. CDSCO-aligned Indian exporters are upgrading quality systems to capture certified-grade demand from US and European qualification programs.
- Agriculture:Crop protection manufacturers utilize thiodiglycol as a reaction solvent and stabilizer in pesticide synthesis. Indian and Chinese agrochemical formulators sustain steady offtake despite formulation substitution experiments with alternative glycols.
- Cosmetics:Personal care formulations require dermatological safety documentation that limits supplier pools. The segment commands premium pricing but represents a narrower volume opportunity relative to pharmaceutical applications.
Chemical Manufacturing anchors current revenue; Pharmaceuticals is climbing the fastest toward margin leadership.
End User:
Procurement authority concentration favors direct manufacturer relationships over intermediated channels, with large formulators leveraging volume scale to extract quality infrastructure investments from upstream suppliers.
- Manufacturers:Integrated chemical and pharmaceutical producers represent the dominant procurement channel, with backward integration into ethylene oxide supply lowering unit economics for captive thiodiglycol users. BASF SE and Huntsman International LLC anchor demand through specialized derivative production.
- Distributors:European chemical distributors are imposing REACH Annex XVII compliance documentation requirements, filtering supplier bases toward certified producers with established regulatory correspondence histories. Testing cost absorption is reshaping distributor margin structures.
- Research Institutions:Small-volume, high-specification demand from academic and contract research organizations supports premium pricing for documented batches. The segment provides pipeline visibility for emerging applications.
- Retailers:Minimal direct participation given bulk chemical handling requirements and regulatory documentation obligations. Cosmetic-grade retail channels remain underdeveloped relative to industrial procurement pathways.
Manufacturers control procurement volume; Distributors are gaining share fastest through compliance-filtered consolidation.
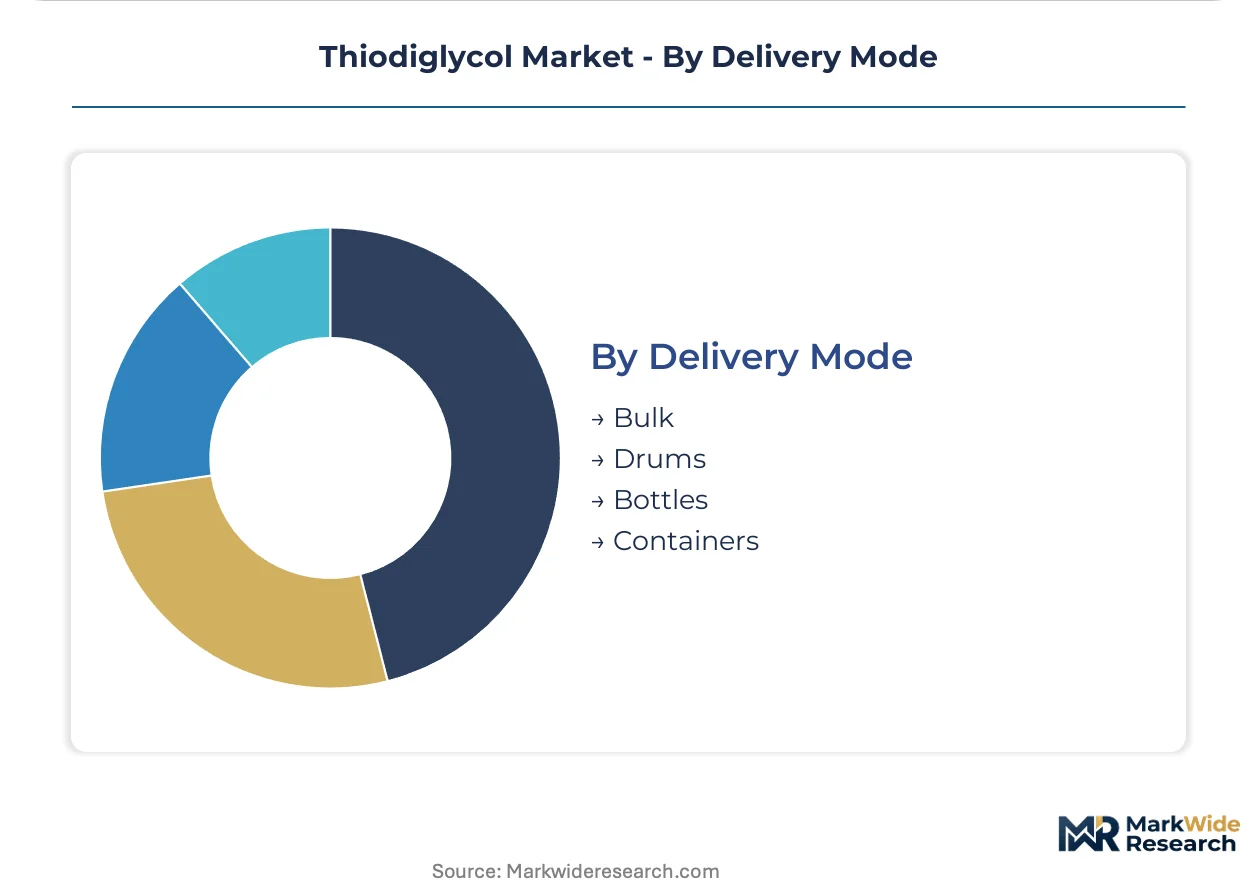
Delivery Mode:
Supply concentration in coastal Chinese provinces shapes logistics economics, with bulk delivery commanding cost advantages for proximate buyers and packaged formats addressing distant or fragmented demand.
- Bulk:Tanker and railcar delivery serves large-volume chemical and pharmaceutical manufacturers with dedicated storage infrastructure. Shandong and Jiangsu production clusters optimize freight economics for East Asian buyers.
- Drums:Intermediate volumes for medium-scale formulators balance handling convenience against per-unit logistics premiums. Standard drum specifications dominate pharmaceutical intermediate shipments.
- Bottles:Laboratory-scale and research-oriented demand requires contamination-controlled packaging with full documentation chains. Premium pricing reflects handling and testing overhead.
- Containers:Flexible intermediate bulk containers serve fragmented cosmetic and specialty chemical buyers with variable offtake patterns. The format is expanding most quickly among European and North American distributors managing multi-customer inventories.
Bulk retains volume leadership; Containers hold the steepest expansion curve among packaged formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers exhibit the lowest price elasticity, absorbing industrial-grade volumes regardless of cost fluctuations, while European pharmaceutical formulators demonstrate the highest sensitivity to purity premiums and documentation reliability.
China
Shandong and Jiangsu provinces house over sixty percent of global production capacity, serving domestic agrochemical formulators and export-oriented pharmaceutical intermediates producers. NMPA and GB standards impose stringent purity documentation on pharmaceutical-grade exports, forcing facility upgrades among smaller producers. The Yangtze River Delta chemical clusters optimize freight economics for East Asian buyers through integrated ethylene oxide supply.
United States
Specialty chemical manufacturers and polymer producers anchor demand, with EPA standards tightening residual impurity thresholds across solvent applications. FDA alignment requirements for pharmaceutical-grade imports extend qualification timelines for foreign suppliers. Gulf Coast petrochemical corridors leverage captive hydrogen sulfide recovery from refining operations to sustain cost-competitive thiodiglycol derivative production.
Germany
REACH Annex XVII restrictions on residual ethylene oxide content below ten ppm are filtering distributor supplier bases toward certified producers with established ECHA correspondence histories. BASF SE anchors European demand through integrated precursor supply chains serving pharmaceutical and polymer applications. The Rhine-Ruhr industrial corridor concentrates analytical chemistry talent for impurity profiling and regulatory documentation.
India
Hyderabad and Ahmedabad pharmaceutical manufacturers are reducing qualified vendor lists from fifteen-to-twenty to three-to-five strategic partners with integrated quality systems. CDSCO-aligned exporters seeking US FDA and European EMA qualification are driving certified-grade demand that domestic producers can capture through upgraded quality infrastructure. Gujarat chemical clusters sustain steady agrochemical offtake despite formulation substitution experiments with alternative glycols.
Switzerland
Specialty chemical manufacturers adopt ceramic nanofiltration modules to achieve sub-ppm impurity levels without thermal degradation, enabling single-train facilities to serve multiple regulatory jurisdictions. Swissmedic documentation requirements for pharmaceutical excipients create sticky customer relationships once initial qualification is achieved. Basel-area industrial parks concentrate membrane-based purification expertise for pharmaceutical-grade production lines.
Thiodiglycol Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated multinational chemical conglomerates commanding analytical capabilities and certification infrastructure while regional Chinese producers compete on unit economics and volume scale. The market structure reflects a bifurcated tier system: certified pharmaceutical-grade suppliers with captive testing laboratories, and commodity industrial-grade producers exposed to diethylene glycol substitution. Three archetypes dominate: backward-integrated precursors specialists, membrane-technology purification leaders, and regional volume players with ethylene oxide supply advantages. Competitive moves concentrate on strategic partnerships for regulatory qualification acceleration and selective capacity expansion in pharmaceutical-grade lines.
Among German-anchored chemical conglomerates, BASF SE and LANXESS occupy positions exemplifying integrated quality infrastructure archetypes, while Huntsman International LLC represents the specialized derivatives tier. Chinese regional producers including Maoming Yunlong Industrial Development Co., Ltd. anchor the cost-competitive industrial-grade segment. Japanese and Korean specialists such as TOYOBO and SONGWON Industrial Co., Ltd. sit within the materials-science tier serving polymer and textile applications with formulation-specific expertise.
| Leading Market Players |
|---|
| BASF SE |
| Maoming Yunlong Industrial Development Co., Ltd. |
| SONGWON Industrial Co., Ltd. |
| LANXESS |
| Huntsman International LLC |
| The Dow Chemical Company |
| Eastman Chemical Company |
| TOYOBO |
| Actylis |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Shandong-based producers and Indian pharmaceutical formulators lock in both supply access and price visibility across multi-year horizons. These arrangements insulate certified-grade buyers from hydrogen sulfide feedstock volatility while committing suppliers to fixed purity documentation protocols.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across European procurement channels. Three-tier pricing structure across pharmaceutical, industrial, and cosmetic grades separates certified producers from commodity suppliers. Cost compression in industrial-grade tiers is intensifying because diethylene glycol substitution erodes margin pools. Agrochemical formulators in India exhibit the highest price sensitivity, while Swiss pharmaceutical excipient buyers absorb purity premiums without volume elasticity.
Supply Chain Analysis
China and India anchor global thiodiglycol production, with Shandong and Jiangsu provinces housing captive ethylene oxide capacity. Feedstock supply draws from petroleum refining hydrogen sulfide recovery and dedicated sulfur processing streams. Single-source vulnerability concentrates in coastal Chinese manufacturing clusters exposed to Yangtze River logistics disruptions. Distribution runs through integrated chemical distributors imposing REACH documentation requirements on downstream buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance services represent a service-attach opportunity expanding faster than base chemical volumes, as pharmaceutical-grade buyers absorb testing and documentation costs as recurring procurement overhead.
For Market Incumbents: Shield certified-grade positioning through captive analytical laboratory investments that diethylene glycol substitutes cannot replicate. Deepen backward integration into ethylene oxide supply to compress unit economics against regional Chinese volume players. Prioritize CDSCO-aligned quality system upgrades to capture Indian pharmaceutical export demand consolidation. For New Entrants and Emerging Players: CDSCO fast-track certification for pharmaceutical-grade output opens procurement doors at Hyderabad and Ahmedabad formulators reducing vendor lists. Target cosmetic-grade dermatological testing as the most penetrable segment, where formulation-specific documentation limits incumbent supplier pools. Lead with membrane-based purification technology to achieve sub-ppm impurity levels without thermal degradation infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward integrated manufacturers with captive precursor supply and established multi-jurisdictional regulatory correspondence histories. Long-term viability hinges on analytical chemistry talent concentration and certification infrastructure that mid-tier facilities cannot replicate. Watch for REACH Annex XVII enforcement intensity as the inflection indicator separating certified from commodity supply tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive ethylene oxide supply lowers unit economics for BASF SE and Huntsman International LLC across European and Asian markets. |
| Membrane Purification Adoption | Ceramic nanofiltration modules enable Swiss and German producers to serve FDA, EMA, and NMPA jurisdictions from single-train facilities. |
| CDSCO Certification Investment | Upgraded quality systems allow domestic Indian producers to capture pharmaceutical-grade demand from US and European qualification programs. |
| Long-term Supply Agreement | Fixed-purity contracts with Shandong producers insulate Indian formulators from hydrogen sulfide feedstock volatility. |
| Green Chemistry Transition | EU Green Deal procurement preferences elevate thiodiglycol positioning versus petroleum-derived solvents in public sector purchasing. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, ECHA registration databases, SEC chemical company filings, and CDSCO export documentation records. Plant managers at Shandong and Jiangsu production facilities, procurement leads at Indian pharmaceutical formulators, European chemical distributors, and technical R&D directors at specialty chemical manufacturers provided operational validation. Bottom-up volume triangulation against top-down value estimates ensures cross-verification of market sizing.
Segmentation dimensions modeled include grade tier, end-use industry, packaging format, and regional production hub across the analysis window. CAGRs derive from regression analysis of historical volume flows and elasticity-adjusted demand projections. Forecast inputs incorporate REACH enforcement timelines, CDSCO qualification pipeline visibility, and ethylene oxide capacity expansion announcements.
Underlying assumptions cover regulatory enforcement continuity, feedstock supply stability, and substitution elasticity thresholds, with deviation risk concentrated in hydrogen sulfide price volatility and multi-jurisdictional certification timeline extensions. Recalibration cycles align with material shifts in ECHA guidance documents and NMPA export protocol amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
North America Calcium Carbonate Market
Bulk Chemicals
Middle East Formaldehyde Market
Bulk Chemicals
Lysine Market
Bulk Chemicals
Aluminum Sulfide Market
Bulk Chemicals
Alkali Metal Hydroxides Market
Bulk Chemicals
Global Ammonium Sulphate Market
Bulk Chemicals
Saudi Arabia Formic Acid Market
Bulk Chemicals
Castor Wax Market
Bulk Chemicals
Global Acrylate Monomers Market
Bulk Chemicals
Isatoic Acid Anhydride Market
Bulk Chemicals
Aluminum Chloride Hexahydrate Market
Bulk Chemicals
Ferrous Oxalate Market
Bulk Chemicals
Caproic Acid Market
Bulk Chemicals
Methyl Mercaptan Market
Bulk Chemicals
Cesium Hydroxide Market
Bulk Chemicals
North America Lime Market