
 White Charcoal Powder Market | 2026-2036
White Charcoal Powder Market Size, Share, and Industry Trends Forecast 2026-2036
White Charcoal Powder Market Analytics
Aftermarket service revenue around filtration system refurbishment is narrowing as industrial buyers shift toward disposable cartridge models. Kishu Binchotan Co., Ltd. leverages its Wakayama prefecture kiln heritage to command premium positioning in ceremonial-grade supply. Fujian Charcoal Industry Co., Ltd. anchors volume production through integrated hardwood sourcing across southern Chinese provinces. Active Char Products specializes in pharmaceutical-grade activation protocols that sustain North American laboratory demand.
White charcoal powder denotes a high-carbon, low-ash material produced through controlled pyrolysis of dense hardwoods such as ubame oak at temperatures exceeding 1,000°C, yielding porosity values of 300–400 m²/g surface area and electrical conductivity below 0.5 S/cm for specialized filtration. The substance serves primarily as an adsorptive medium in gas-phase purification, liquid decolorization, and controlled-release cosmetic matrices. Activated type segments dominate value capture due to post-process steam or chemical activation that expands micropore volume for industrial adsorption tasks. Natural type segments compete on artisanal provenance claims in specialty food and premium skincare channels where unaltered binchotan origin commands price premiums. Powdered morphology leads household and restaurant adoption for direct-use formats, while granulated variants concentrate in fixed-bed water treatment infrastructure where hydraulic flow resistance governs specification.
Japan's METI enforces JIS K 1470 standards for activated carbon purity in potable water applications, while China's SAMR monitors GB/T 12496 compliance for food-contact charcoal materials. The US FDA regulates white charcoal under GRAS determinations when deployed as colorant or processing aid in edible products. REACH registration obligations within the European Union constrain importer documentation burdens for synthetic activation catalyst residues. Stakeholders must track evolving biomass traceability mandates that threaten non-certified supply origins.
Market Dynamics
Japan's METI biomass verification tightening is fragmenting supply chains as artisanal producers lose certification while industrial kilns invest in carbon-14 testing infrastructure, concentrating premium-grade output among heritage operators in Wakayama and Ehime prefectures.
Growth Catalysts
- Cosmetic formulation demand:South Korean skincare manufacturers are expanding ultra-fine grade purchases for pore-refining masks, creating sustained pull from Seoul metropolitan production corridors.
- REACH registration clarity:ECHA guidance on synthetic activation catalyst residues has reduced importer documentation uncertainty, accelerating EU market entry for certified Asian suppliers.
- Potable water infrastructure:JIS K 1470 compliance requirements in Japanese municipal treatment plants are mandating activated carbon replacement cycles, locking in recurring procurement volumes.
Market Restraints
- Hardwood feedstock scarcity:Ubame oak harvesting restrictions in Japanese national forests have compressed domestic raw material availability, forcing price premiums on traditional binchotan grades.
- Activation energy costs:Steam activation protocols require sustained temperatures above 800°C, exposing producers to natural gas price volatility in Chinese and Vietnamese manufacturing zones.
- Synthetic activated carbon substitution:Coal-based and coconut-shell activated carbons from Southeast Asian chemical plants compete on unit cost in industrial decolorization applications.
Strategic Opportunities
- Pharmaceutical-grade protocols:North American laboratory demand for endotoxin-controlled charcoal materials remains underserved by current Asian export capacity.
- Direct-to-restaurant channels:Specialty food-grade powders for tableside water filtration are bypassing traditional distributor markups through e-commerce platforms in urban Japanese and Korean markets.
- EU Green Deal alignment:CSRD reporting requirements on biomass traceability favor suppliers with verified sustainable forestry chain-of-custody documentation.
Industry Challenges
- Carbon-14 assay capacity:The analytical infrastructure for biomass content verification remains concentrated in Tokyo and Osaka testing laboratories, creating bottlenecks for export certification.
- Kiln operator succession:Traditional white charcoal craftsmanship in rural Japanese prefectures faces generational transfer gaps as younger workers migrate to urban manufacturing employment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Charcoal Powder Market |
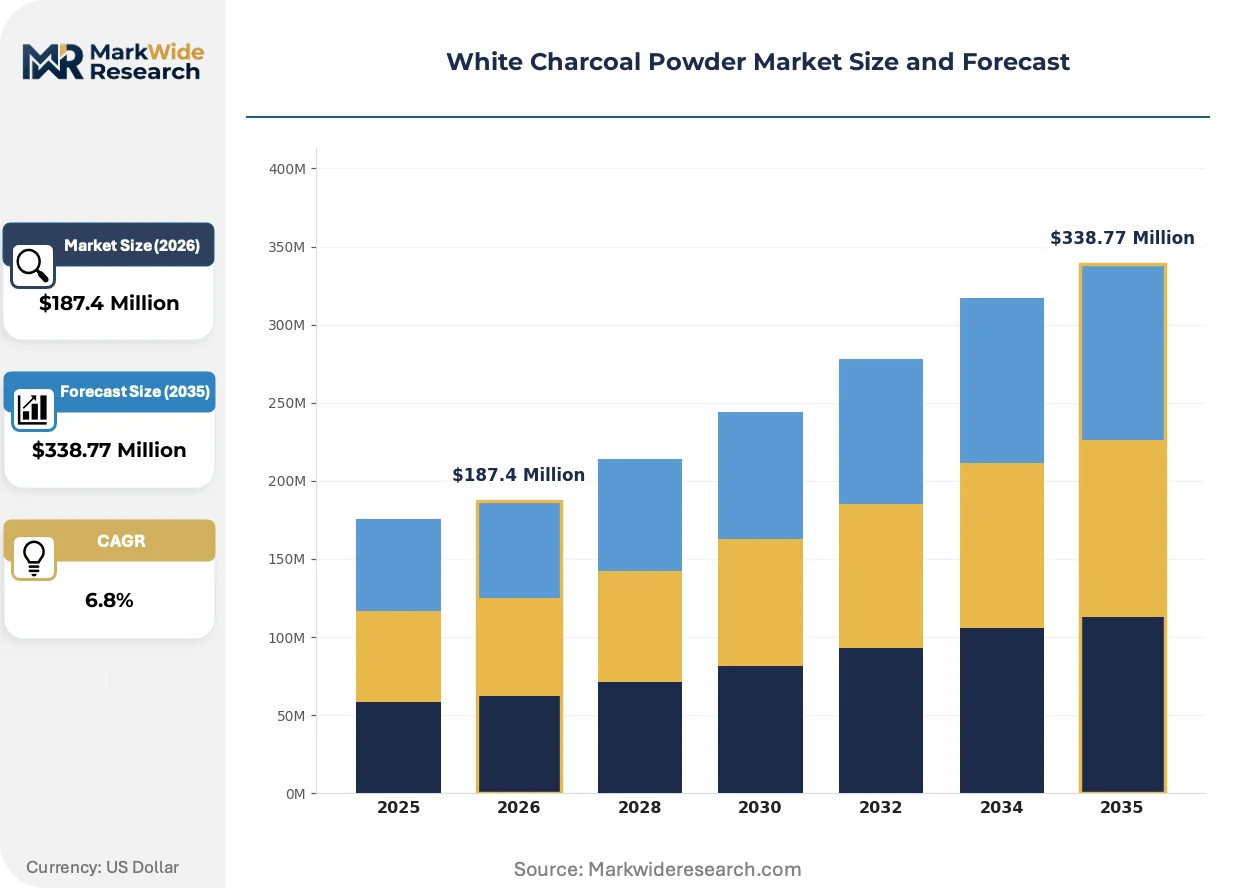
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Activated, Natural, Powdered, Granulated Application: Food Industry, Cosmetics, Water Treatment, Air Purification Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales End User: Households, Restaurants, Industrial Users, Healthcare Providers |
| Companies Covered | Kishu Binchotan Co., Ltd., Active Char Products, Matsubayashi Shoji Co., Ltd., Charcoal House, Fujian Charcoal Industry Co., Ltd., Sugimoto USA Inc., The Charcoal Source, Zhejiang Xinghong Charcoal Co., Ltd., Nature's Way Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Charcoal Powder Market Evolving Landscape
Process instrumentation and supply chain verification technologies are compressing quality assurance timelines while fragmenting traditional artisanal supply hierarchies into traceable, auditable production networks.
Near-infrared spectroscopy paired with blockchain batch tracking is digitizing provenance verification for ceremonial-grade binchotan exports. Heritage producers in Wakayama prefecture are adopting these systems to defend premium positioning against industrial competitors. The technology is digitizing what previously required months of manual documentation into real-time compliance dashboards accessible to Japanese and European importers.
China's SAMR enforcement of GB/T 12496 food-contact material standards is disqualifying unregistered small-scale producers from export eligibility. Fujian-based manufacturers with integrated hardwood sourcing are consolidating volume positions as compliance costs rise. The regulation is compressing supplier counts in southern Chinese production zones while elevating certified facility utilization rates.
Industrial buyers in Osaka-Kobe manufacturing corridors are compressing supplier rosters from multi-vendor arrangements toward single-source contracts with certified heritage producers. Procurement teams prioritize JIS-compliant documentation over unit cost minimization, reversing prior fragmented sourcing patterns. This concentration is most visible in fixed-bed water treatment infrastructure projects where liability exposure governs vendor selection.
White Charcoal Powder Market Segmentation
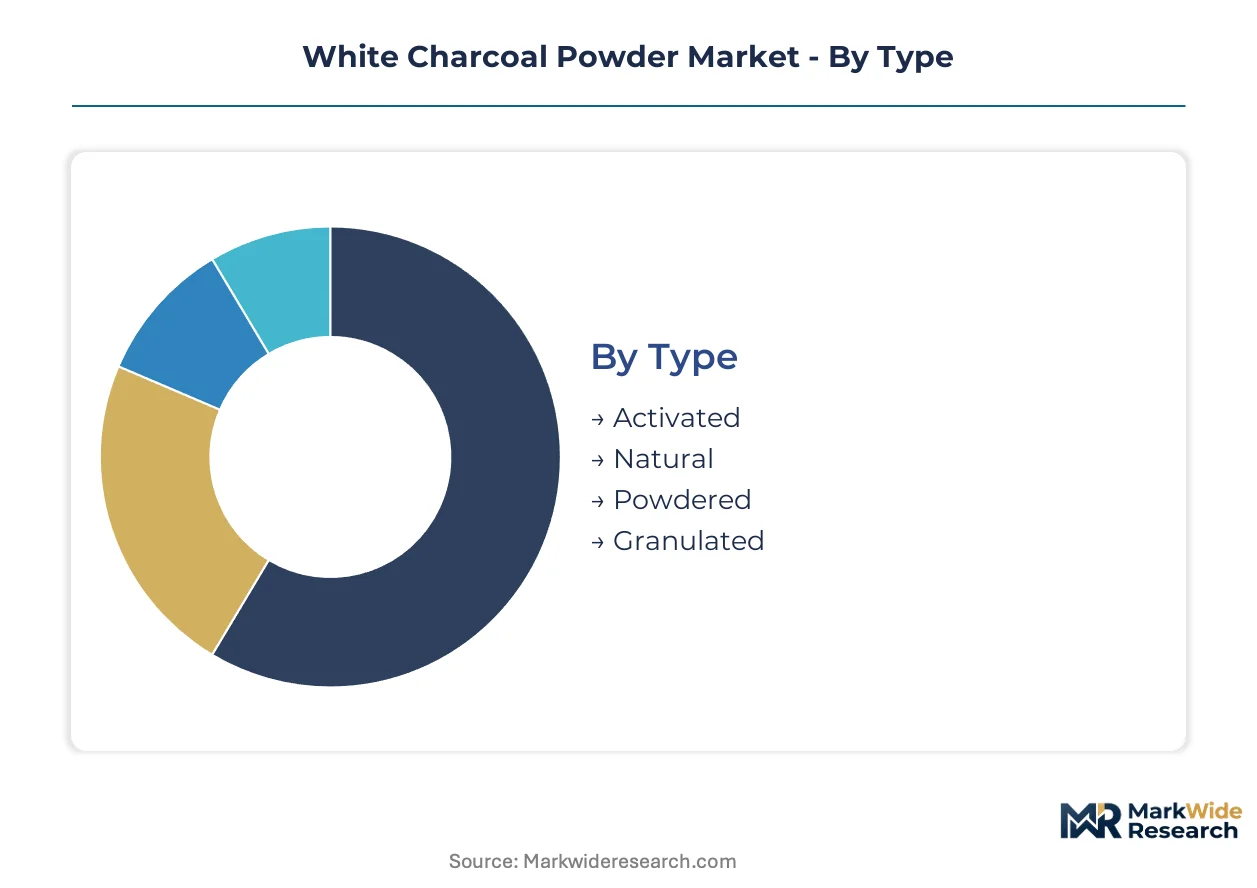
White charcoal powder segmentation reveals competing value capture logics across purity grades, activation protocols, and channel structures. Formulators, procurement officers, and retail buyers each prioritize different technical specifications, creating tiered pricing architectures that reward certification depth.
Type:
The maturity spectrum spans industrial-scale activation infrastructure at one pole and artisanal kiln heritage at the other, with morphology choices downstream of these processing decisions.
- Activated:Post-pyrolysis steam or chemical activation expands micropore volume to 300–400 m²/g surface area, serving industrial adsorption tasks in Osaka-Kobe municipal water treatment plants where JIS K 1470 compliance mandates recurring replacement cycles.
- Natural:Unaltered binchotan retains ceremonial-grade provenance claims, commanding price premiums in specialty food and premium skincare channels where Wakayama prefecture heritage documentation defends margin positioning against industrial competitors.
- Powdered:Fine particle morphology enables direct-use formats in household and restaurant applications across Seoul metropolitan manufacturing corridors.
- Granulated:Larger particle size concentrates in fixed-bed water treatment infrastructure where hydraulic flow resistance governs engineering specifications.
Activated type handles the majority of throughput; Natural type is the fastest mover on share as artisanal provenance claims deepen price differentiation.
Application:
Cost tier segmentation separates commodity purification from premium personal care, with regulatory compliance burdens escalating across food-contact and pharmaceutical adjacencies.
- Cosmetics:Ultra-fine grades integrate into pore-refining masks and cleansers, with South Korean formulators in Seoul metropolitan corridors expanding procurement of sub-micron particle distributions for controlled-release matrices.
- Water Treatment:Municipal and industrial fixed-bed systems demand JIS K 1470 or GB/T 12496 certified materials, locking in recurring procurement volumes from heritage producers with carbon-14 testing infrastructure.
- Food Industry:Tableside water filtration and specialty grilling applications compete on GRAS determination status in North American markets and food-contact material registration in Chinese export zones.
- Air Purification:Gas-phase adsorption applications in residential and commercial HVAC systems compete against synthetic activated carbon substitutes on unit cost.
Water Treatment commands the largest installed base; Cosmetics is expanding most quickly as Seoul-based manufacturers scale ultra-fine grade purchases.
Distribution Channel:
Volume concentration favors direct procurement in industrial segments, while fragmentation characterizes consumer-facing channels where certification transparency competes with convenience.
- Direct Sales:Industrial buyers in Osaka-Kobe manufacturing corridors compress supplier rosters toward single-source contracts with certified heritage producers, prioritizing documentation over unit cost minimization.
- Online Retail:E-commerce platforms enable specialty food-grade powders to bypass traditional distributor markups in urban Japanese and Korean markets, accelerating direct-to-restaurant channel formation.
- Specialty Stores:Premium skincare and ceremonial-grade binchotan rely on provenance storytelling and tactile product demonstration to defend price positioning.
- Supermarkets:Mass-market household adoption concentrates in standardized powdered formats with basic filtration claims and accessible price points.
Direct Sales captures the majority of value; Online Retail is climbing the fastest as digital procurement penetrates restaurant and small industrial buyer segments.
End User:
Customer type segmentation aligns technical sophistication with specification stringency, from household convenience to pharmaceutical-grade endotoxin control.
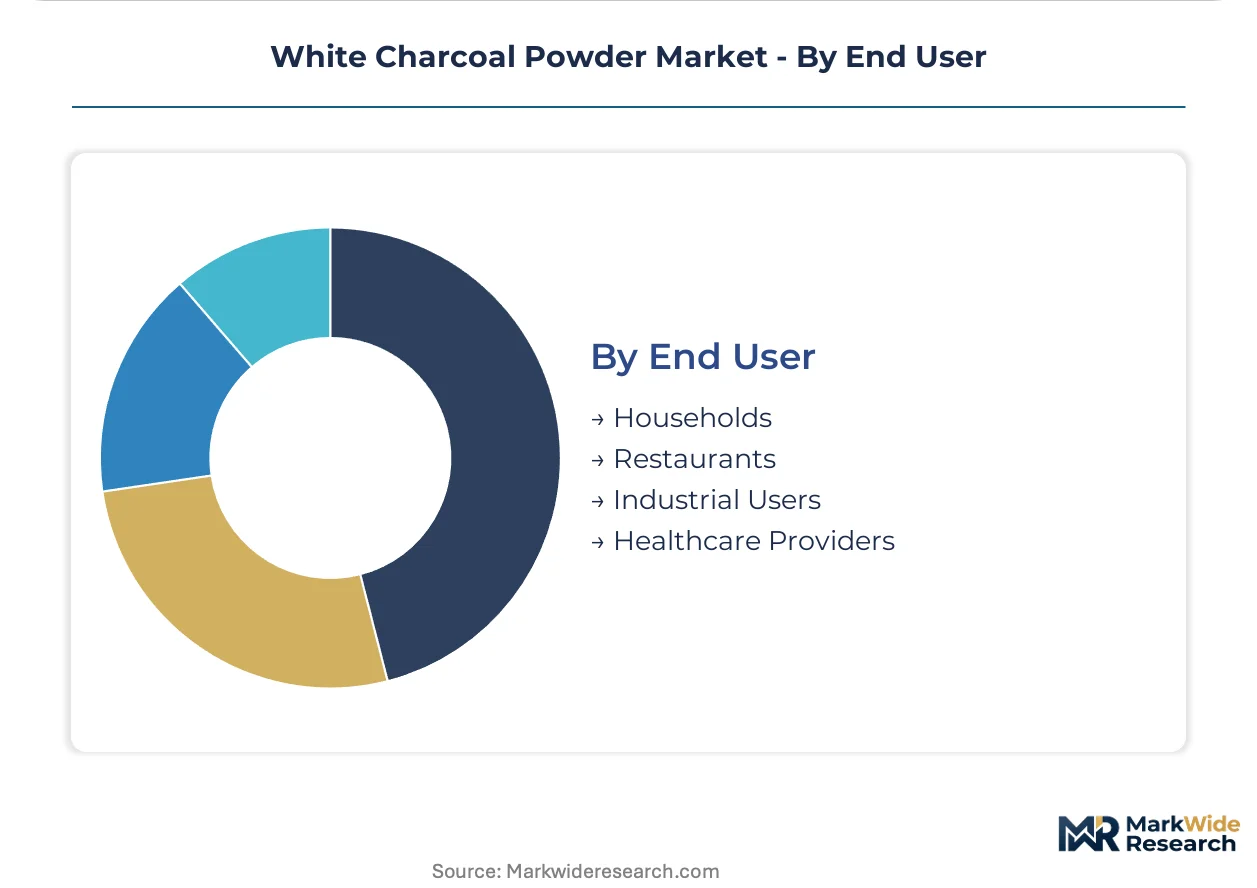
- Industrial Users:Municipal treatment plants and manufacturing facilities mandate certified activation protocols and batch traceability, consolidating procurement around heritage producers with integrated testing infrastructure.
- Restaurants:Specialty dining establishments in Tokyo and Seoul adopt tableside water filtration as experiential differentiation, sourcing through direct e-commerce channels rather than traditional distributors.
- Households:Consumer adoption concentrates in powdered formats for personal water filtration and skincare masking, with price sensitivity governing brand switching behavior.
- Healthcare Providers:North American laboratory demand for endotoxin-controlled charcoal materials remains underserved, creating expansion opportunity for pharmaceutical-grade protocol investment.
Industrial Users represent the dominant demand pool; Healthcare Providers show the steepest expansion trajectory as laboratory certification requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese buyers favor ceremonial-grade natural binchotan for provenance-driven applications, while South Korean manufacturers prioritize ultra-fine activated grades for cosmetic matrices, and Chinese industrial users concentrate on volume-scale water treatment procurement.
Japan
METI's tightened biomass carbon content verification rules are disqualifying artisanal producers lacking carbon-14 testing infrastructure. JIS K 1470 standards govern activated carbon purity in municipal potable water plants. Wakayama and Ehime prefecture heritage operators in the Kansai region are consolidating premium-grade output as certification costs rise.
South Korea
Cosmetics formulators in Seoul metropolitan manufacturing corridors are expanding ultra-fine white charcoal grade purchases for pore-refining masks and cleansers. MFDS cosmetic ingredient regulations mandate documentation for activated carbon materials in skincare applications. Gyeonggi-do province production clusters are scaling sub-micron particle distribution capabilities.
China
SAMR enforcement of GB/T 12496 food-contact material standards is compressing supplier counts in southern Chinese production zones. Fujian-based manufacturers with integrated hardwood sourcing are consolidating volume positions as compliance costs eliminate small-scale competitors. The Pearl River Delta and Yangtze River Delta industrial corridors dominate export-oriented activated carbon production.
United States
FDA GRAS determinations govern white charcoal deployment as colorant or processing aid in edible products. North American laboratory demand for endotoxin-controlled pharmaceutical-grade materials remains underserved by current Asian export capacity. Industrial procurement concentrates in Great Lakes and Northeast municipal water treatment infrastructure.
Germany
ECHA guidance on synthetic activation catalyst residues has reduced importer documentation uncertainty under REACH registration obligations. EU Green Deal CSRD reporting requirements on biomass traceability favor suppliers with verified sustainable forestry chain-of-custody documentation. The Rhine-Ruhr industrial corridor anchors continental activated carbon distribution.
White Charcoal Powder Market Competitive Landscape
Capability concentration sits with heritage kiln operators possessing generational craftsmanship and carbon-14 testing infrastructure; scale advantage sits with integrated hardwood processors controlling southern Chinese feedstock basins. The market structure bifurcates between premium-tier provenance defenders and volume-tier compliance consolidators. Three archetypes dominate: Wakayama prefecture heritage specialists, Fujian-based integrated manufacturers, and North American pharmaceutical-grade protocol developers. Competitive moves center on certification depth investment and direct e-commerce channel formation bypassing traditional distributor markups.
Within the heritage specialist tier, Kishu Binchotan Co., Ltd. and Matsubayashi Shoji Co., Ltd. exemplify provenance-driven positioning anchored in Wakayama prefecture kiln traditions. Fujian Charcoal Industry Co., Ltd. represents the integrated manufacturing archetype with captive hardwood sourcing across southern Chinese provinces. Active Char Products occupies a position in the North American pharmaceutical-grade segment serving laboratory demand for endotoxin-controlled materials.
| Leading Market Players |
|---|
| Kishu Binchotan Co., Ltd. |
| Active Char Products |
| Matsubayashi Shoji Co., Ltd. |
| Charcoal House |
| Fujian Charcoal Industry Co., Ltd. |
| Sugimoto USA Inc. |
| The Charcoal Source |
| Zhejiang Xinghong Charcoal Co., Ltd. |
| Nature's Way Products |
| Others |
Value Network & Pricing Analysis
Wakayama prefecture kiln heritage concentration in Japan's Kansai region feeds directly into premium-tier margin capture for ceremonial-grade binchotan, while Fujian-based integrated manufacturers in southern China anchor volume-tier pricing through captive hardwood sourcing economies.
Pricing Analysis
Long-term offtake contracts dominate industrial procurement in Osaka-Kobe municipal water treatment corridors, while spot purchases govern restaurant and household segments. Three-tier pricing structure across premium ceremonial, standard industrial, and economy powdered grades separates Wakayama heritage documentation from Fujian volume output from unregistered small-scale supply. Pricing pressure stems from synthetic activated carbon substitution in decolorization applications, compressing margins in standard industrial tiers. Industrial buyers exhibit lowest price sensitivity due to JIS K 1470 compliance liability exposure, whereas household consumers switch brands readily on price.
Supply Chain Analysis
Extended payment terms from Osaka-Kobe industrial buyers strain working capital for heritage kiln operators lacking supply-chain finance facilities. Raw material supply concentrates in Japan's Wakayama and Ehime prefectures for ubame oak, and across Fujian, Zhejiang, and Jiangxi provinces in China for integrated hardwood sourcing. Steam activation energy costs, natural gas price volatility, and carbon-14 testing infrastructure bottlenecks create multi-node vulnerability. Distribution runs through direct sales contracts for industrial segments and e-commerce platforms penetrating urban Japanese and Korean restaurant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled provenance verification is transforming this market toward platform-economics dynamics, with heritage producers leveraging interoperable batch-tracking systems to defend premium positioning against industrial competitors.
For Market Incumbents: Harden certification depth investment to offset METI biomass verification tightening that threatens artisanal producers lacking carbon-14 testing infrastructure. Prioritize backward integration into captive ubame oak sourcing in Wakayama prefecture to secure feedstock against Japanese national forest harvesting restrictions. Defend channel control by accelerating direct e-commerce formation bypassing traditional distributor markups in Seoul and Tokyo metropolitan markets.
For New Entrants and Emerging Players: Establish a beachhead in North American pharmaceutical-grade charcoal supply, where endotoxin-controlled material demand remains underserved by current Asian export capacity. Target laboratory procurement officers in Great Lakes and Northeast research corridors with USP-grade activation protocols. Deploy regulatory-first go-to-market positioning emphasizing FDA documentation and GRAS determination support.
For Investors and Strategic Acquirers: Capital is best deployed toward heritage kiln operators possessing generational craftsmanship paired with carbon-14 testing infrastructure, as these assets concentrate premium-tier pricing power. Long-term viability hinges on EU Green Deal CSRD alignment for biomass traceability documentation. Watch for carbon-14 assay capacity expansion in Tokyo and Osaka laboratories as inflection signal for export certification bottleneck resolution.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-14 Testing Infrastructure Investment | METI biomass verification rules disqualify producers lacking Tokyo and Osaka laboratory access. |
| Direct E-Commerce Channel Formation | Seoul and Tokyo restaurant buyers bypass traditional distributor markups through digital procurement platforms. |
| Pharmaceutical-Grade Protocol Development | North American laboratory demand for endotoxin-controlled materials outstrips current Asian export capacity. |
| EU Green Deal CSRD Alignment | Verified sustainable forestry chain-of-custody documentation favors suppliers in European procurement decisions. |
| Backward Integration into Ubame Oak Sourcing | Japanese national forest harvesting restrictions compress domestic raw material availability for traditional binchotan grades. |
Research Methodology
Desk research of JIS K 1470 regulatory filings, SAMR GB/T 12496 enforcement records, and METI biomass certification databases preceded structured interviews with Wakayama prefecture kiln operators, Fujian-based plant managers, Seoul cosmetics formulators, and Osaka-Kobe municipal procurement officers. Secondary validation drew from customs trade data, activated carbon industry association reports, and FDA GRAS determination filings. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Assumptions held METI verification enforcement trajectory and natural gas price bands fixed across the analysis window, while varying cosmetic formulation demand intensity and synthetic activated carbon substitution rates. Segmentation dimensions modeled included activation protocol, morphology grade, application vertical, distribution channel structure, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical procurement cycle data and replacement rate assumptions for municipal water treatment infrastructure.
Sensitivities concentrate around hardwood feedstock availability in Japanese national forests and carbon-14 assay laboratory capacity expansion timelines. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and energy cost trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Ammonium Sulfate Food Grade Market
Bulk Chemicals
Mancozeb Market
Bulk Chemicals
Copper Sulfate Market
Bulk Chemicals
North America Lime Market
Bulk Chemicals
Glyceryl Triacetate (Triacetin) Market
Bulk Chemicals
Coal Tar Pitch Market
Bulk Chemicals
Magnesium Citrate Market
Bulk Chemicals
Global Ground and Precipitated Calcium Carbonate Market
Bulk Chemicals
Sodium Perborate Market
Bulk Chemicals
Asia-Pacific Ammonia Market
Bulk Chemicals
Global Ethylene Market
Bulk Chemicals
Aerospace and Defense Chemical Distribution Market
Bulk Chemicals
Global Molten Sulfur Market
Bulk Chemicals
Europe Quicklime Market
Bulk Chemicals
Borates Market
Bulk Chemicals
China Starch and Starch Derivatives Market