
 Furfuryl Alcohol Market | 2026-2036
Furfuryl Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Furfuryl Alcohol Market Analysis
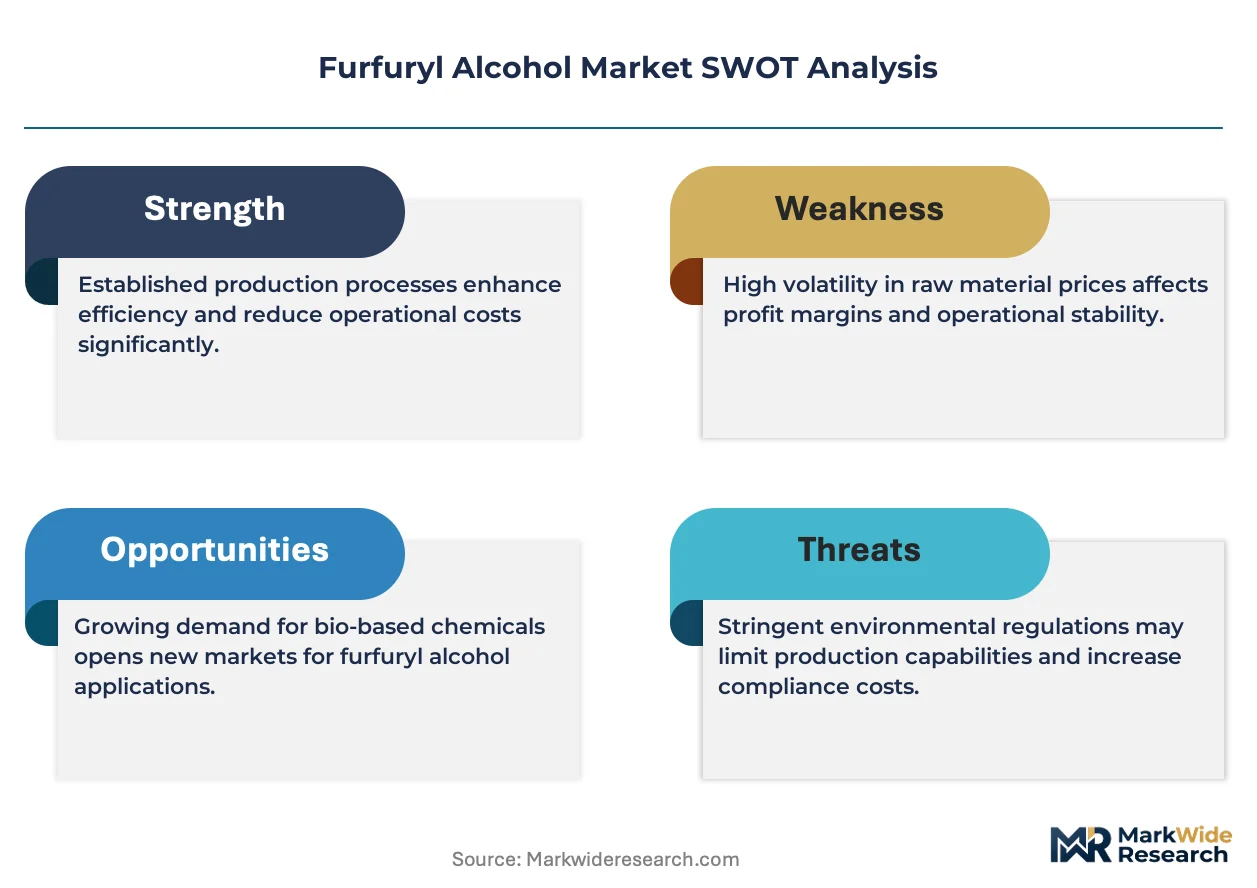
Aftermarket resin refurbishment services is tilting margin pools away from virgin furfuryl alcohol sales toward technical support and binder reformulation. Hongye Holding Group Corporation Limited leverages its captive furfural supply to control raw material costs across the value chain. Pennakem LLC sustains a specialized position in North American pharmaceutical-grade production. TransFurans Chemicals bvba anchors European supply through its Belgian manufacturing base and REACH-compliant product lines.
Furfuryl alcohol is a heterocyclic organic compound derived from furfural hydrogenation, typically containing 98% purity for industrial resin applications and functioning as a reactive monomer in thermosetting furan resins. The substance polymerizes with urea-formaldehyde or phenolic compounds to produce foundry binders that withstand extreme metal casting temperatures. Among product type segments, standard furfuryl alcohol dominates volume while tetrahydrofurfuryl alcohol captures expanding solvent applications. Within end user categories, construction and automotive foundries drive the bulk of consumption, with paints and coatings representing a faster-growing but smaller volume pool.
China's SAMR enforces GB standards on chemical purity and workplace exposure limits that directly shape domestic production specifications and export eligibility. The EU ECHA administers REACH registration requirements that constrain market access for non-compliant Asian suppliers. EPA oversight in the United States governs air emissions from furfural hydrogenation facilities under the Clean Air Act framework. Stakeholders must monitor regulatory divergence between Chinese emission standards and European chemical safety classifications when configuring regional supply strategies.
Market Dynamics
Foundry resin binders face mounting pressure from China's GB emission standards and the EU REACH framework, forcing producers to recertify product lines while steel casters accelerate adoption of lower-emission furan systems. This regulatory divergence is compressing formulation cycles and redrawing competitive boundaries across major supply corridors.
Growth Catalysts
- REACH-compliant furan derivatives:EU chemical safety classifications are accelerating binder reformulation investments, opening certified supply channels for compliant Asian producers.
- Steel casting emission mandates:Foundry operations in Germany and Japan are replacing phenolic-urethane systems with furfuryl alcohol binders to meet tightening workplace exposure limits.
- Shandong-Jiangsu production clusters:East China's concentrated furfural hydrogenation capacity enables integrated cost structures that support export price competitiveness.
Market Restraints
- Furfural feedstock volatility:Corn cob and sugarcane bagasse supply fluctuations in agricultural regions directly compress hydrogenation margins.
- East China supply concentration:Over 60% of global furfuryl alcohol capacity sits within two provinces, creating geographic vulnerability to regional emission shutdowns.
- Biobased epoxy substitution:Construction composites manufacturers are testing lignin-derived alternatives for non-foundry thermoset applications.
Strategic Opportunities
- Pharmaceutical-grade tetrahydrofurfuryl alcohol:Solvent applications in active pharmaceutical ingredient synthesis remain underpenetrated relative to industrial resin demand.
- India's PLI scheme for specialty chemicals:Domestic production incentives could attract furfural hydrogenation investments serving South Asian foundry growth.
- Digital formulation platforms:Binder suppliers are deploying AI-driven resin optimization tools that compress customer technical service response times.
Industry Challenges
- REACH registration timelines:European chemical dossier preparation consumes 18-24 months, delaying market access for new product grades.
- Legacy foundry equipment retrofit costs:Metal casting operations face capital intensity when adapting sand reclamation systems for furan binder chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Furfuryl Alcohol Market |
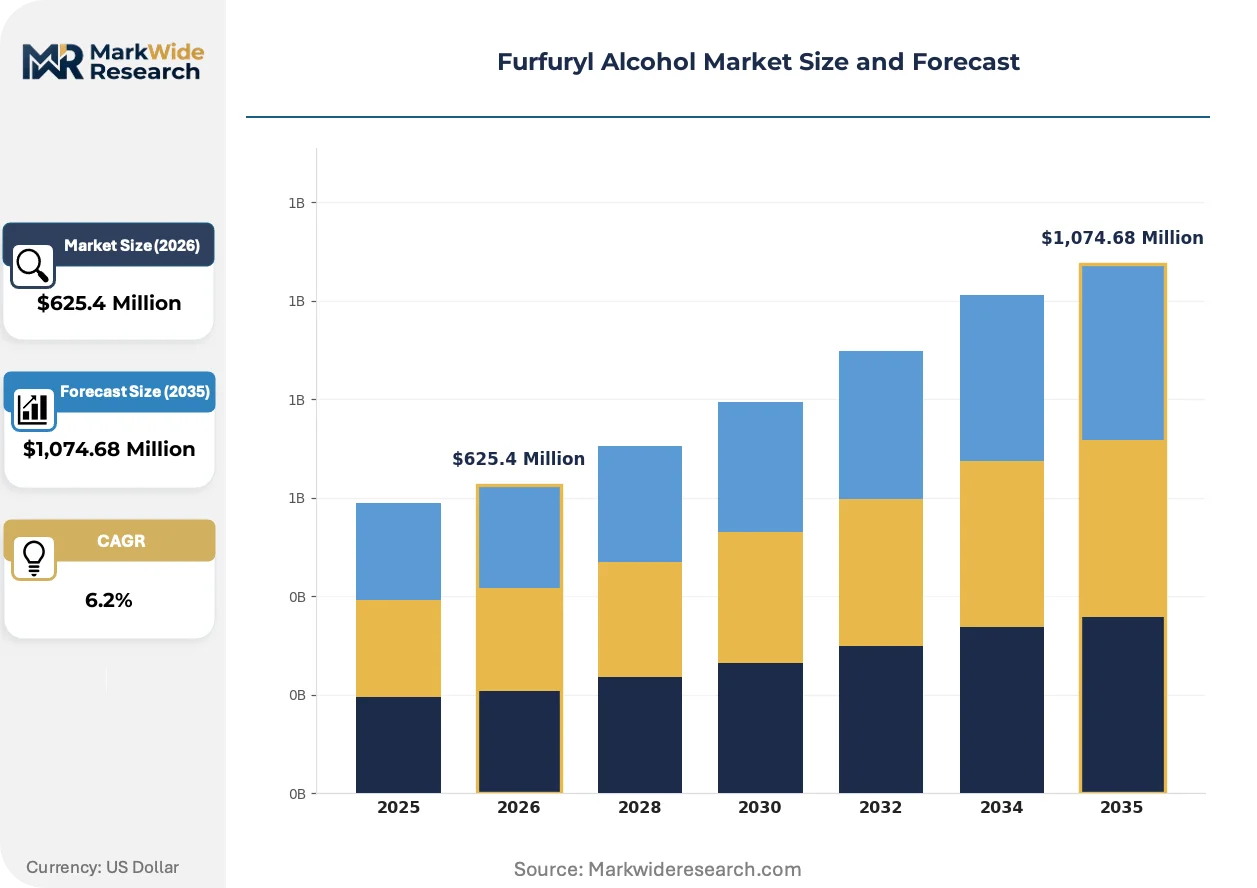
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $1,074.68 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furfuryl Alcohol, Tetrahydrofurfuryl Alcohol, Furfural, Ethyl Furfural Application: Resins, Coatings, Adhesives, Pharmaceuticals End User: Construction, Automotive, Paints & Coatings, Food & Beverages Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Hongye Holding Group Corporation Limited, Pennakem LLC, TransFurans Chemicals bvba, Silvateam S.p.A., International Furan Chemicals B.V., Xingtai Chunlei Furfuryl Alcohol Co., Ltd., Illovo Sugar Africa (Pty) Ltd, Linzi Organic Chemical Inc. Ltd., DalinYebo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Furfuryl Alcohol Market Emerging Trajectories
Active reformulation of furan resin systems is compressing product development cycles while digital tools reshape how binder suppliers engage foundry customers. These shifts are redistributing value capture from commodity alcohol sales toward technical service and specification control.
Hybrid furan-phenolic resin systems is hybridizing traditional binder categories by combining the thermal stability of phenolic networks with furfuryl alcohol's lower emission profile. German automotive foundries are piloting these formulations for engine block casting. The technology is hybridizing procurement decisions, forcing purchasing managers to evaluate total cost of emission compliance rather than resin price per ton.
China's GB standards on volatile organic compound emissions from chemical production facilities are tightening purity specifications for export-eligible furfuryl alcohol. Domestic producers must upgrade distillation and hydrogenation controls to maintain SAMR certification. The construction and automotive foundry segments in East China are absorbing these compliance costs fastest, with Shandong-based suppliers leading facility upgrades.
Aftermarket resin refurbishment services are unbundling from virgin product sales as foundry operators seek to extend binder system life through reformulation rather than replacement. Technical service contracts now capture margin pools that previously flowed to commodity alcohol volumes. This pattern is most visible in European steel casting operations, where REACH documentation requirements favor long-term supplier relationships over spot purchasing.
Furfuryl Alcohol Market Segmentation
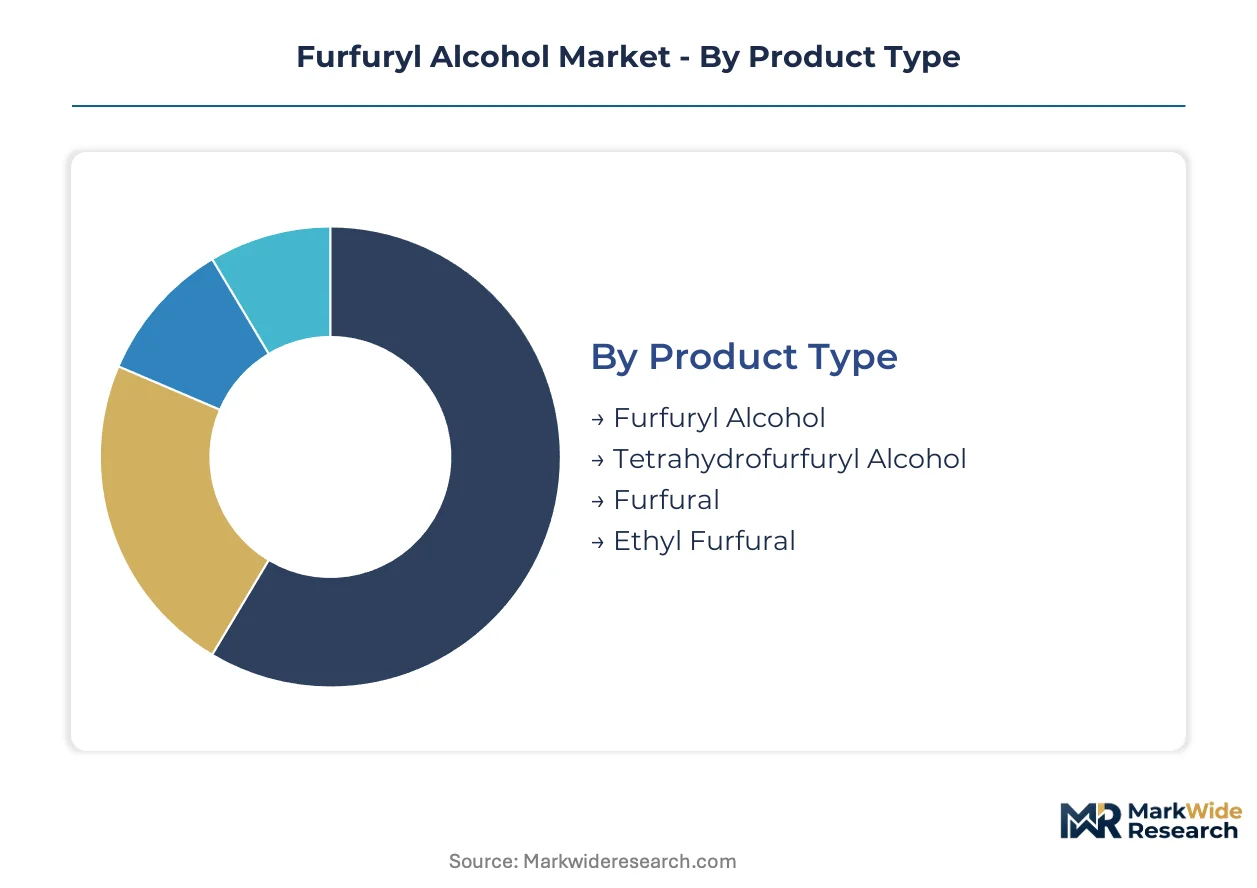
Segmentation in furfuryl alcohol markets reveals how regulatory pressure and end-use specialization split value capture between commodity hydrogenation outputs and performance-grade derivatives. Distinct purity specifications and certification requirements separate industrial resin feedstocks from pharmaceutical solvent applications.
Product Type:
Mature hydrogenation products dominate volume positions while emerging derivatives capture specification premiums in regulated applications.
- Furfuryl Alcohol:The primary hydrogenation product contains 98% purity for industrial resin synthesis, functioning as a reactive monomer in thermosetting furan binders. Foundry operations in Germany and Japan specify this grade for emission-compliant steel casting, with China's Shandong-Jiangsu clusters supplying the bulk of certified export volumes.
- Tetrahydrofurfuryl Alcohol:This saturated derivative serves as a high-boiling solvent in active pharmaceutical ingredient synthesis and electronic cleaning applications. European REACH registration requirements constrain supply sources, creating certified supply premiums for compliant Asian producers serving pharmaceutical formulators.
- Furfural:The aldehyde precursor to furfuryl alcohol hydrogenation, derived from agricultural biomass such as corn cobs and sugarcane bagasse, anchors captive supply chains for integrated producers.
- Ethyl Furfural:A specialized furfural derivative finding niche flavor and fragrance applications, constrained by limited hydrogenation capacity outside dedicated fine chemical facilities.
Furfuryl alcohol retains volume leadership; tetrahydrofurfuryl alcohol holds the steepest expansion curve.
Application:
Application segmentation tracks how thermal performance requirements and emission regulations redistribute demand across thermoset chemistry families.
- Resins:Furan resin binders for foundry sand cores constitute the dominant application, with furfuryl alcohol polymerizing with urea-formaldehyde or phenolic compounds to withstand extreme metal casting temperatures. German automotive foundries are piloting hybrid furan-phenolic systems for engine block casting.
- Coatings:Solvent and reactive diluent applications in corrosion-resistant coatings leverage tetrahydrofurfuryl alcohol's low toxicity profile, gaining share in marine and industrial maintenance formulations.
- Adhesives:Wood bonding applications utilize furan resin thermosets for exterior-grade plywood and particleboard, competing with formaldehyde-based systems on emission compliance metrics.
- Pharmaceuticals:Tetrahydrofurfuryl alcohol serves as a reaction solvent and excipient carrier, with EMA and FDA purity specifications creating barrier-to-entry for uncertified suppliers.
Resin applications command the largest volume position; pharmaceutical-grade solvents are climbing the fastest on regulatory compliance premiums.
End User:
End user segmentation reflects diverging procurement patterns between capital-intensive foundry operations and formulation-driven specialty chemical buyers.
- Construction:Concrete admixtures and corrosion-resistant grouts utilize furfuryl alcohol-derived furan resins for chemical resistance in aggressive environments.
- Automotive:Engine block and transmission housing foundries specify furan binder systems for dimensional stability in high-temperature casting, with emission mandates accelerating phenolic-urethane replacement.
- Paints & Coatings:Industrial maintenance and marine coating formulators specify tetrahydrofurfuryl alcohol for low-VOC compliance in regulated application environments.
- Food & Beverages:Furfural derivatives serve as flavor precursors and extraction solvents, governed by FDA and EFSA food contact regulations.
Automotive foundries absorb the highest specification volumes; paints and coatings are gaining share fastest on solvent substitution trends.
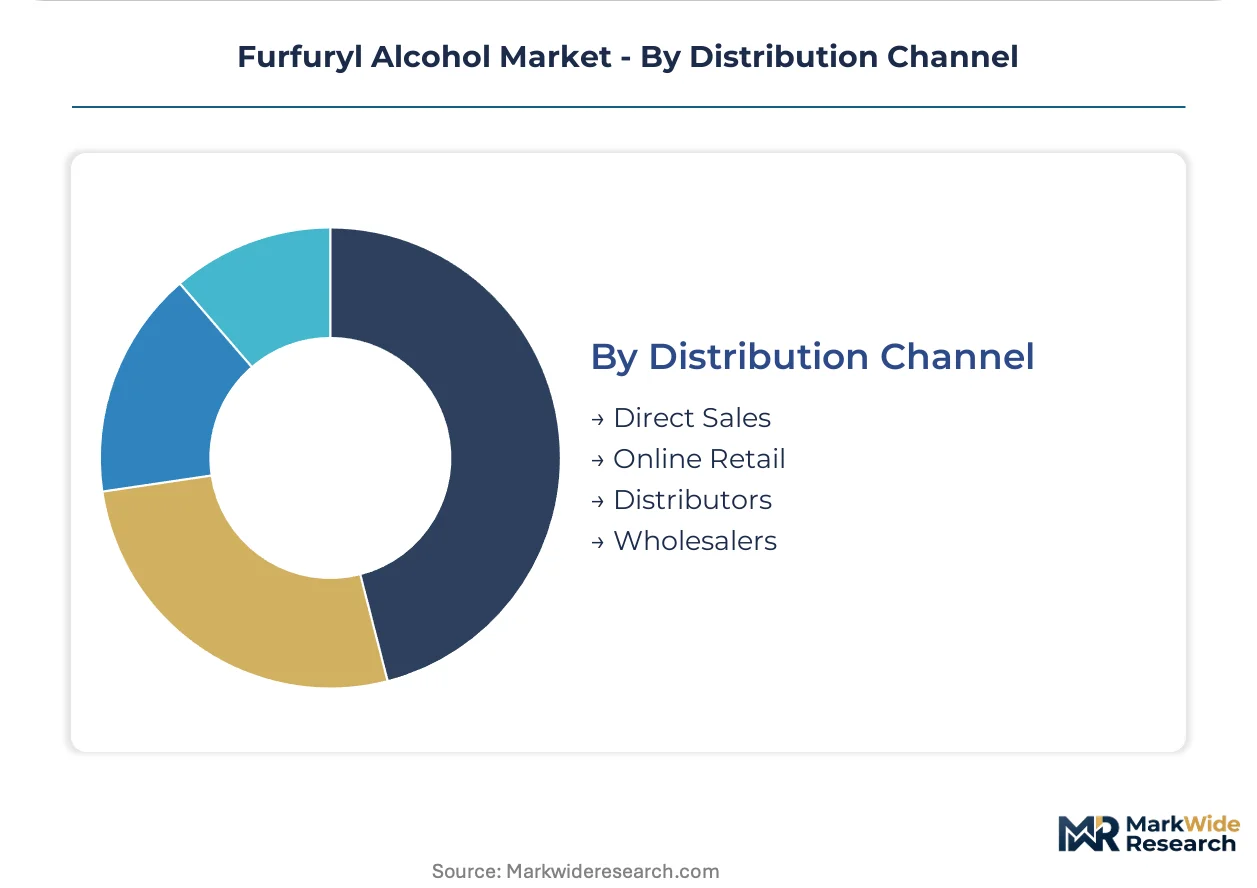
Distribution Channel:
Channel segmentation tracks the unbundling of technical service from commodity supply as foundry operators seek reformulation support alongside virgin product delivery.
- Direct Sales:Large foundry operations procure through mill-direct contracts bundling virgin resin, technical service, and sand reclamation system optimization, capturing margin pools previously flowing to distributors.
- Distributors:Regional chemical distributors serve mid-tier foundries and coating formulators with stocked inventory and formulation guidance, consolidating procurement for multi-site operators.
- Wholesalers:Agricultural supply channels for furfural feedstock derivatives serve smaller resin compounders in fragmented construction adhesive markets.
- Online Retail:Specialty chemical marketplaces list laboratory-grade tetrahydrofurfuryl alcohol for research and small-batch pharmaceutical synthesis, constrained by hazardous material shipping regulations.
Direct sales channels retain the largest volume concentration; distributor-led technical service contracts are expanding most quickly in European REACH-compliant markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry operators in Germany absorb specification premiums with minimal price elasticity, while construction buyers in India and Brazil negotiate aggressively on standard-grade volumes. This demand-elasticity contrast shapes how suppliers configure regional pricing and certification investments.
China
Steel casting operations in Shandong and Jiangsu provinces drive furfuryl alcohol consumption for emission-compliant foundry binders. SAMR enforces GB standards on chemical purity and workplace exposure limits that reshape domestic production specifications. The Yangtze River Delta concentration of furfural hydrogenation capacity enables integrated cost structures supporting export price competitiveness.
Germany
Automotive foundries specify furan binder systems for engine block casting dimensional stability under tightening workplace exposure mandates. ECHA administers REACH registration requirements that constrain market access for non-compliant Asian suppliers. The industrial concentration around Stuttgart and Munich anchors European demand for certified pharmaceutical-grade tetrahydrofurfuryl alcohol derivatives.
United States
EPA oversight under the Clean Air Act framework governs air emissions from furfural hydrogenation facilities, compressing margins for non-upgraded plants. Foundry resin binders face substitution pressure from biobased epoxy alternatives in construction composites. The Gulf Coast petrochemical corridor hosts specialized production serving pharmaceutical solvent applications under FDA purity specifications.
India
Construction and automotive foundry segments absorb standard-grade volumes with high price sensitivity and fragmented procurement patterns. The PLI scheme for specialty chemicals could attract furfural hydrogenation investments serving South Asian foundry growth. Maharashtra and Gujarat industrial clusters concentrate domestic resin compounding capacity for regional construction adhesive markets.
Belgium
REACH-compliant product lines anchor European supply through specialized manufacturing serving pharmaceutical and electronic cleaning solvent applications. EMA purity specifications for tetrahydrofurfuryl alcohol create barrier-to-entry premiums for certified suppliers. The Antwerp-Rotterdam chemical cluster concentrates hydrogenation expertise for high-specification derivative production.
Furfuryl Alcohol Market Vendor Landscape
Captive feedstock controllers and specialized certification holders split the market into distinct margin pools. The vendor base concentrates around integrated agricultural processors and dedicated hydrogenation specialists rather than diversified chemical conglomerates. Two strategic archetypes dominate: backward-integrated producers leveraging captive furfural supply, and specification-focused operators holding REACH or pharmaceutical-grade certifications. Capacity expansion in East China and REACH dossier preparation for European market access represent the dominant competitive moves reshaping competitive boundaries.
Within the captive supply tier, Hongye Holding Group Corporation Limited exemplifies backward integration into agricultural feedstock processing. Among specialized certification holders, Pennakem LLC occupies a position in North American pharmaceutical-grade production, while TransFurans Chemicals bvba anchors European supply through Belgian manufacturing operations. These three companies represent the strategic archetype spectrum from commodity cost control to regulatory compliance premiums.
| Leading Market Players |
|---|
| Hongye Holding Group Corporation Limited |
| Pennakem LLC |
| TransFurans Chemicals bvba |
| Silvateam S.p.A. |
| International Furan Chemicals B.V. |
| Xingtai Chunlei Furfuryl Alcohol Co., Ltd. |
| Illovo Sugar Africa (Pty) Ltd |
| Linzi Organic Chemical Inc. Ltd. |
| DalinYebo |
| Others |
Supply Flow & Price Mechanics
Shanghai-Rotterdam container freight corridors transmit cost volatility from East China hydrogenation clusters into European REACH-compliant product premiums, compressing margins for non-integrated distributors while amplifying price spreads between pharmaceutical-grade and industrial resin grades.
Pricing Analysis
Aftermarket resin refurbishment services now capture lifetime value exceeding virgin product sales in mature foundry relationships. Three-tier pricing structure across pharmaceutical-grade, REACH-certified industrial, and standard foundry grades separates margin pools by certification burden rather than alcohol content alone. Pricing pressure stems from furfural feedstock volatility in drought-affected agricultural regions, squeezing hydrogenation margins for non-captive producers. Construction foundries in India and Brazil exhibit highest price sensitivity, while German automotive casters absorb specification premiums with minimal elasticity.
Supply Chain Analysis
Corn cob and sugarcane bagasse feedstock availability in Shandong, Jiangsu, and Hebei provinces anchors global furfural hydrogenation capacity. Raw material sourcing draws from seasonal agricultural residue collection, coal-derived hydrogen supply, and specialized catalyst imports for selective hydrogenation. Single-source vulnerability concentrates in East China's two-province production cluster, where regional emission enforcement triggers disproportionate supply disruptions. Distribution runs through direct mill contracts for large foundries and regional chemical distributors serving formulation-driven coating and pharmaceutical customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward large foundry operators consolidating procurement through mill-direct contracts, fragmenting distributor influence while concentrating specification control among tier-one automotive and steel casting groups.
For Market Incumbents: Harden REACH dossier defenses through accelerated tetrahydrofurfuryl alcohol registration timelines, locking out Asian competitors facing 18-24 month European market access delays. Deepen captive furfural supply through agricultural processor partnerships in corn belt regions, insulating margin structures from feedstock volatility that threatens non-integrated hydrogenation specialists. For New Entrants and Emerging Players: India's underpenetrated pharmaceutical-grade solvent market offers white-space expansion with PLI scheme tailwinds supporting domestic hydrogenation investments. Target South Asian foundry growth corridors through technical service partnerships rather than commodity volume plays, leveraging formulation expertise gaps in Maharashtra and Gujarat industrial clusters. For Investors and Strategic Acquirers: REACH-certified mid-scale hydrogenation specialists with pharmaceutical-grade tetrahydrofurfuryl alcohol capabilities represent the most defensible acquisition archetype, commanding scarcity premiums as European supply constraints intensify. Monitor EMA purity specification enforcement as the critical inflection signal distinguishing certified from commodity supply tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Furfural Feedstock | Captive agricultural residue processing in Shandong eliminates margin volatility from spot biomass markets. |
| REACH Dossier Completion for Tetrahydrofurfuryl Alcohol | EMA-compliant registration unlocks pharmaceutical solvent premiums unavailable to uncertified Asian competitors. |
| Digital Formulation Platform Deployment | AI-driven resin optimization compresses German automotive foundry technical service response times below incumbent benchmarks. |
| Joint Venture with Indian PLI Beneficiaries | Maharashtra-based hydrogenation partnerships capture South Asian foundry growth while navigating BIS certification requirements. |
| Aftermarket Refurbishment Service Unbundling | Technical service contracts capture margin pools shifting away from virgin furfuryl alcohol spot sales in European steel casting. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across foundry procurement managers, resin formulation chemists, furfural hydrogenation plant managers, and pharmaceutical solvent buyers. Secondary validation incorporated customs trade data for furfural and furfuryl alcohol movements, SEC filings from listed chemical producers, GB standard enforcement records from SAMR, and ECHA REACH registration databases. Bottom-up volume triangulation across end-use segments was cross-checked against top-down hydrogenation capacity assessments.
Calibration against historical price spreads between pharmaceutical-grade and industrial resin tiers informed elasticity assumptions across the projection horizon. Segmentation modeling incorporated grade tier, end-use industry, regional regulatory cluster, and certification status dimensions. CAGRs were derived from demand elasticity coefficients and supply-side capacity addition schedules, with furfural feedstock cost trajectories and REACH enforcement intensity serving as primary scenario variables.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-subsidized Chinese producers or accelerated biobased epoxy substitution in construction composites would shift outcomes beyond modeled ranges. Cross-checking against ECHA registration completion timelines and SAMR emission enforcement records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Sodium Percarbonate Market
Bulk Chemicals
Europe Acetic Acid Market
Bulk Chemicals
Europic Chloride Market
Bulk Chemicals
Europe Lipids Market
Bulk Chemicals
Asia-Pacific Caustic Soda Market
Bulk Chemicals
Sodium Molybdate Market
Bulk Chemicals
North America Hydrochloric Acid Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market
Bulk Chemicals
2,6-Dichlorobenzaldehyde Market
Bulk Chemicals
Hydrochloric Acid Market
Bulk Chemicals
Ceric Ammonium Nitrate Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
Atrazine Market
Bulk Chemicals
Ammonia Storage Tanks Market
Bulk Chemicals
Hydrochloric Acid Electrolysis Market
Bulk Chemicals
Phthalic Anhydride Market