
 Functional Tea Market | 2026-2036
Functional Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Tea Market Intelligence
Organic certification under USDA NOP and EU 2018/848 is bifurcating the competitive landscape into credentialed suppliers and conventional processors. Unilever leverages its global procurement network to secure certified leaf volumes across multiple origins. Tata Consumer Products anchors its portfolio in Indian estate-sourced organic lines with strong domestic distribution. ITO EN dominates Japan's bottled functional tea segment through cold-brew extraction technology and convenience store penetration.
Functional tea comprises Camellia sinensis leaves or botanical infusions formulated with bioactive compounds such as catechins, L-theanine, or adaptogenic herbs, processed through controlled oxidation, steaming, or solvent-free extraction to preserve therapeutic properties. Green tea commands the largest revenue pool due to established clinical evidence for cardiovascular and metabolic benefits, while herbal tea segments register the fastest growth as consumers seek caffeine-free alternatives with targeted wellness positioning. Sachet packaging retains volume leadership in retail channels, though bottled ready-to-drink formats capture expanding share among working professionals seeking portable consumption solutions.
The FDA oversees structure-function claims in the United States, requiring substantiation that prevents disease-treatment language while permitting wellness positioning. EFSA's health claims evaluation in Europe creates a higher evidentiary bar that limits marketing flexibility but rewards companies with approved proprietary research. FSSAI's functional food regulations in India increasingly govern import standards and domestic labeling for ayurvedic ingredient teas. Stakeholders must monitor evolving jurisprudence on adaptogenic and nootropic claims across these jurisdictions to anticipate compliance costs and first-mover positioning in emerging ingredient categories.
Market Dynamics
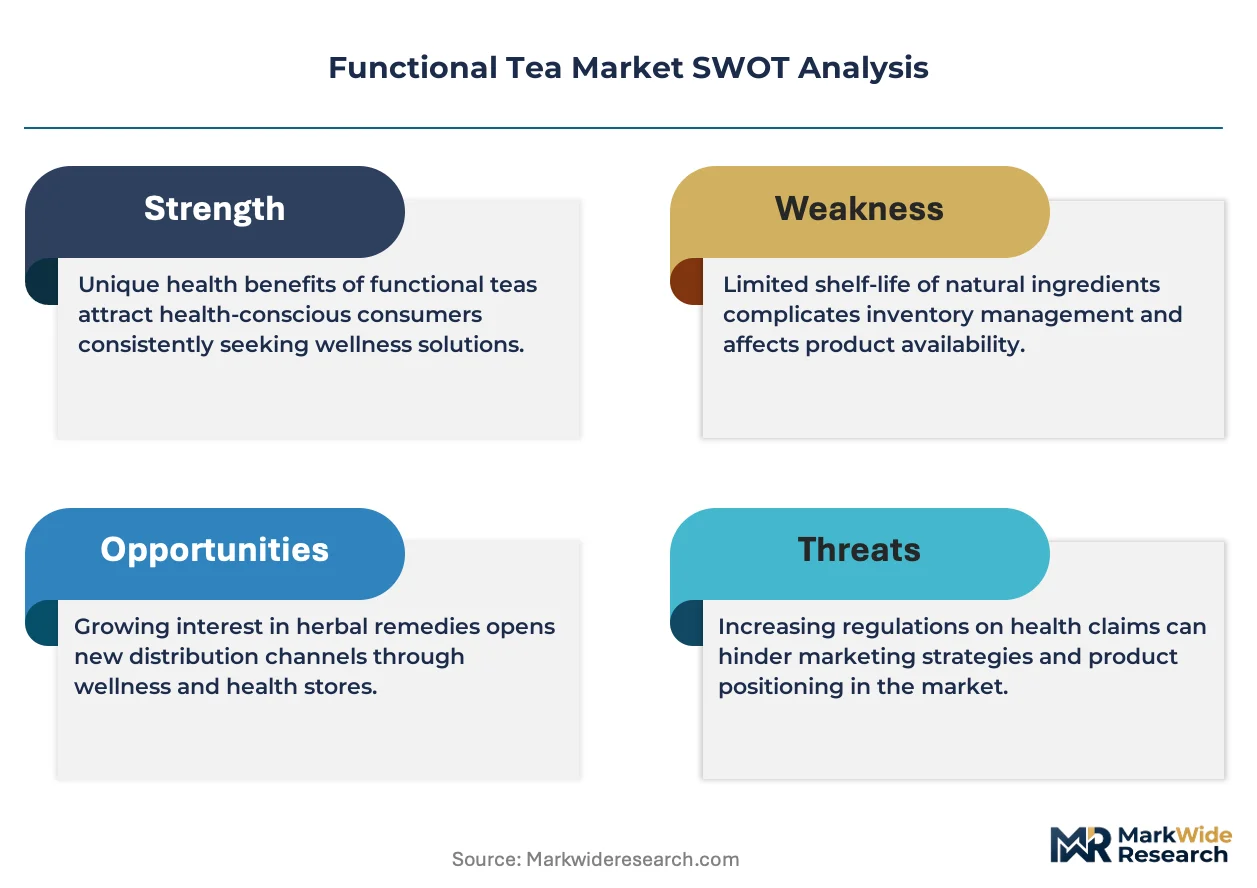
Organic certification mandates under USDA NOP and EU 2018/848 are forcing processors to restructure procurement networks and segregate supply chains, creating a dual-tier competitive landscape between credentialed and conventional operators.
Growth Catalysts
- EU 2018/848 Organic Standards:Certification requirements under this regulation are pulling premium-grade leaf volumes toward compliant processors, expanding shelf space for certified functional tea lines in German and French retail channels.
- Cold-brew Extraction Technology:Low-temperature processing methods preserve catechin and L-theanine bioactivity, enabling bottled ready-to-drink formats to capture working professional demand in urban Japanese and US markets.
- Wellness-focused Millennials:This demographic cohort in metropolitan centers across the United States, Germany, and Japan is driving category expansion through preference for adaptogenic and nootropic ingredient positioning.
Market Restraints
- Camellia sinensis Leaf Input Volatility:Climate-induced harvest fluctuations in Assam and Kenyan highlands create raw material cost instability for processors dependent on estate-sourced volumes.
- EFSA Health Claims Evaluation:Europe's stringent evidentiary requirements for bioactive compound marketing claims limit flexibility in wellness positioning and compress margins for research-intensive substantiation.
- Conventional Black Tea Substitution:Lower-cost commodity tea alternatives retain price-sensitive consumer segments, constraining premium functional tea penetration in mass-market retail.
Strategic Opportunities
- Ayurvedic Ingredient Teas in India:FSSAI's evolving functional food regulations create a governed pathway for domestic and import market expansion of ashwagandha and tulsi formulations.
- Convenience Store Penetration:Cold-chain distribution partnerships with Japan's 7-Eleven and Lawson networks enable single-serve bottled functional tea access to commuter consumption occasions.
- Adaptogen-Nootropic Convergence:Formulation innovation combining rhodiola, lion's mane, and L-theanine targets cognitive performance positioning in US and German professional demographics.
Industry Challenges
- Multi-jurisdictional Compliance Talent:Shortage of regulatory specialists capable of navigating simultaneous FDA structure-function, EFSA health claims, and FSSAI functional food requirements complicates international expansion.
- USDA NOP Certification Timeline:Three-year conversion periods for conventional estate transition to organic status delay supply security for processors seeking certified volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Tea Market |
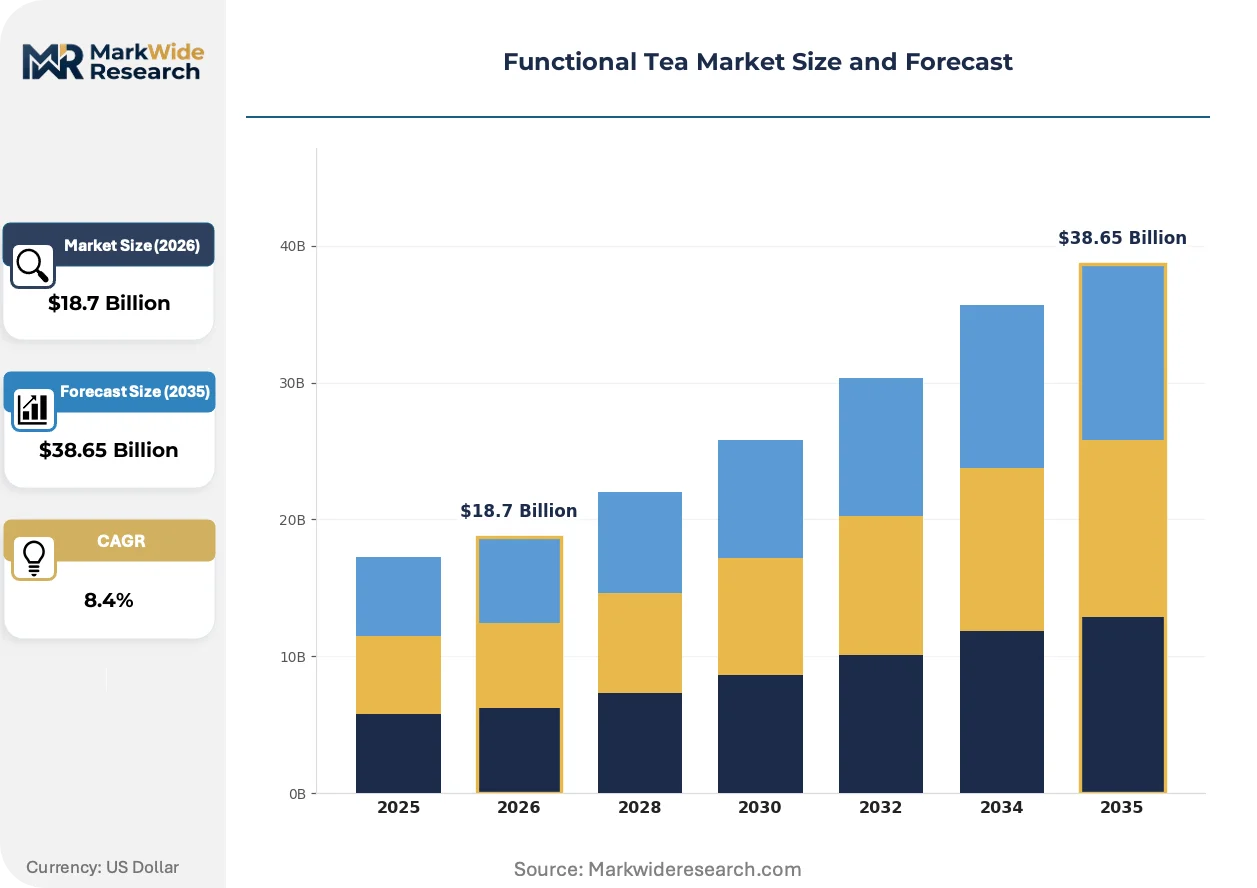
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Tea, Green Tea, Black Tea, Infused Tea Ingredient: Herbs, Spices, Fruits, Flowers Consumer Type: Health Conscious, Millennials, Working Professionals, Seniors Packaging Type: Bulk, Sachets, Bottled, Canisters |
| Companies Covered | Associated British Foods, ITO EN, Unilever, Celestial Seasonings, Organic India, Nestle, Hain Celestial Group, The Republic of Tea, Tata Consumer Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Tea Market Strategic Shifts & Innovations
Cold-chain logistics and bioactive preservation technologies are restructuring how functional tea reaches consumers, while regulatory divergence between jurisdictions creates compliance complexity that rewards specialized operators.
Microencapsulation of catechins and polyphenols is bifurcating the ingredient supply landscape. Sports nutrition and pharmaceutical adjacencies are adopting this technology at accelerated pace. Premium beverage formulators are compressing conventional extraction margins while enabling extended shelf-life claims.
EFSA's 2023 updated guidance on botanical health claims is tightening evidentiary requirements for adaptogenic marketing. This regulatory pressure is forcing reformulation toward EFSA-approved proprietary research investments. German and French functional tea lines are responding with clinical trial partnerships to secure permitted wellness language.
Urban professional consumption is rotating from loose-leaf sachet preparation toward grab-and-go bottled formats. Convenience retail and direct-to-subscription channels are displacing traditional grocery aisle dominance in Tokyo, New York, and London metropolitan zones. Cold-brew extraction patents are concentrating competitive advantage among Japanese and US processors with captive convenience store distribution.
Functional Tea Market Segmentation
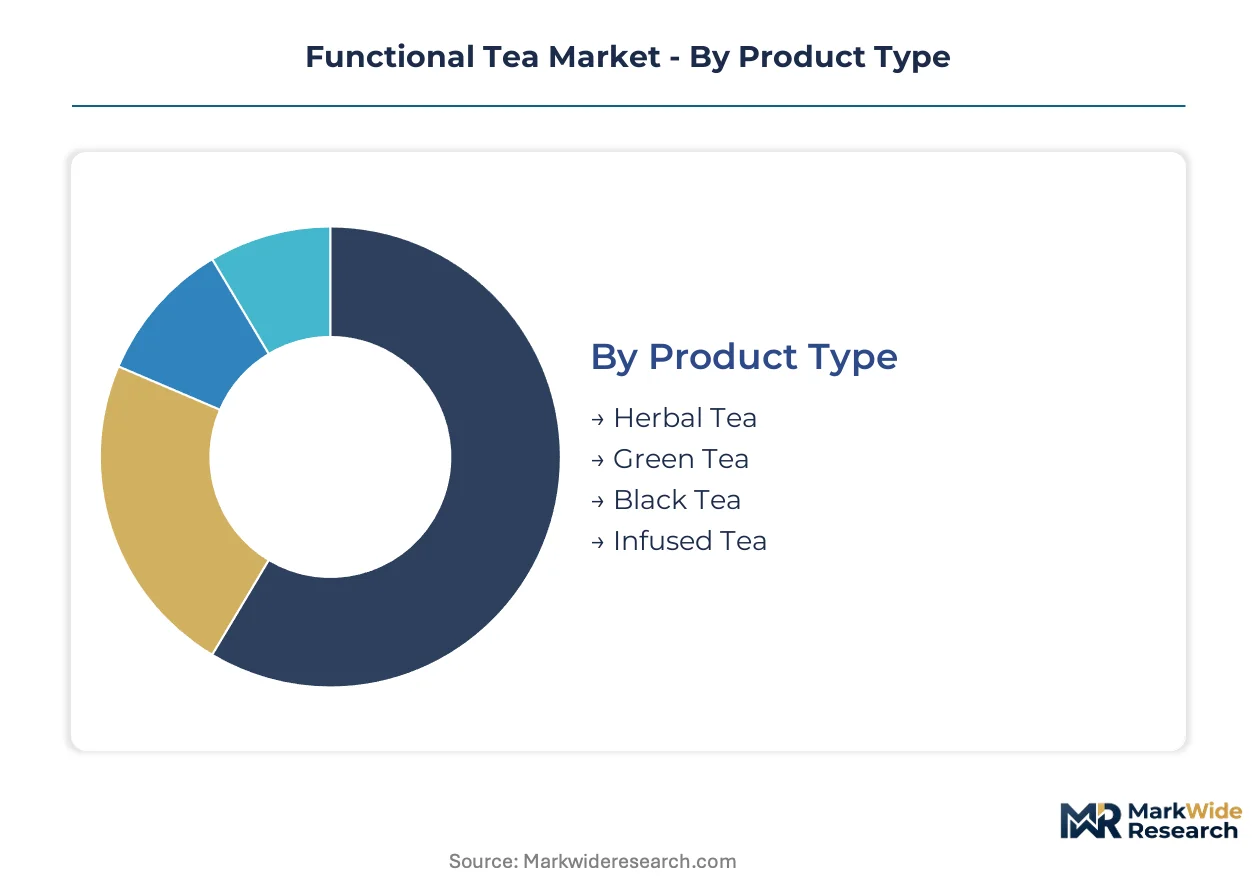
Segmentation in functional tea reveals distinct procurement and consumption patterns that separate premium wellness positioning from commodity substitution threats. Each dimension exposes where bioactive preservation commands price premiums versus where conventional alternatives erode margins.
Product Type:
Green tea and herbal blends face the strongest substitution pressure from conventional black tea in price-sensitive retail channels, while infused and premium-positioned variants defend margin through formulation complexity.
- Herbal Tea:Caffeine-free botanical infusions formulated with chamomile, peppermint, or rooibos for sleep and digestive wellness positioning. Demand concentrates in German and US urban centers where consumers seek evening consumption alternatives without stimulant effects.
- Green Tea:Unoxidized Camellia sinensis leaves processed through steaming or pan-firing to preserve catechin bioactivity. Japanese and US metropolitan professionals drive volume through cardiovascular and metabolic health claims supported by clinical literature.
- Black Tea:Fully oxidized leaves with lower catechin retention but established flavor familiarity. Commodity-grade volumes compete directly with conventional tea, compressing functional premium realization in mass-market retail.
- Infused Tea:Co-processed blends combining base tea with functional additives such as turmeric, ginger, or adaptogenic extracts. Niche positioning targets specific wellness outcomes with higher per-unit pricing.
Green tea anchors the volume base while herbal tea gains share at the steepest rate.
Ingredient:
Cost tier differentiation separates commodity botanical inputs from proprietary extract formulations with verified bioactive standardization.
- Herbs:Whole or cut botanical materials including tulsi, ashwagandha, and lemon balm sourced from Indian and Egyptian growing regions. Ayurvedic ingredient demand in domestic Indian markets and export channels drives procurement concentration.
- Spices:Cinnamon, ginger, turmeric, and cardamom formulations targeting anti-inflammatory and metabolic positioning. Premium pricing depends on curcuminoid or gingerol standardization verified through third-party assay.
- Fruits:Dried berry, citrus peel, and tropical fruit inclusions providing flavor masking and antioxidant marketing claims. Supply chains source from Latin American and Southeast Asian processing centers.
- Flowers:Hibiscus, rose, and jasmine petals for visual differentiation and mild functional positioning. Limited bioactive substantiation constrains premium pricing relative to herb and spice alternatives.
Herb-based formulations command the highest functional premium while spice ingredients expand most quickly across ready-to-drink applications.
Consumer Type:
Application-based targeting separates daily ritual consumption from acute wellness intervention occasions.
- Health Conscious:Broad demographic spanning age cohorts with sustained wellness expenditure and ingredient label scrutiny. Loyalty concentrates in organic-certified and clinically substantiated product lines.
- Millennials:Urban cohort aged 25-40 driving adaptogenic and nootropic ingredient demand through social media discovery and subscription commerce. Preference for sustainable packaging and transparent sourcing.
- Working Professionals:Time-constrained consumers prioritizing convenience formats and cognitive performance claims. Bottled ready-to-drink capture concentrates in Tokyo, New York, and London metropolitan corridors.
- Seniors:Age 65+ segment seeking cardiovascular, joint health, and sleep-specific formulations. Pharmacy and healthcare retail channel preference with higher price tolerance for condition-targeted products.
Working professionals drive the steepest format innovation while health conscious consumers anchor repeat purchase loyalty.
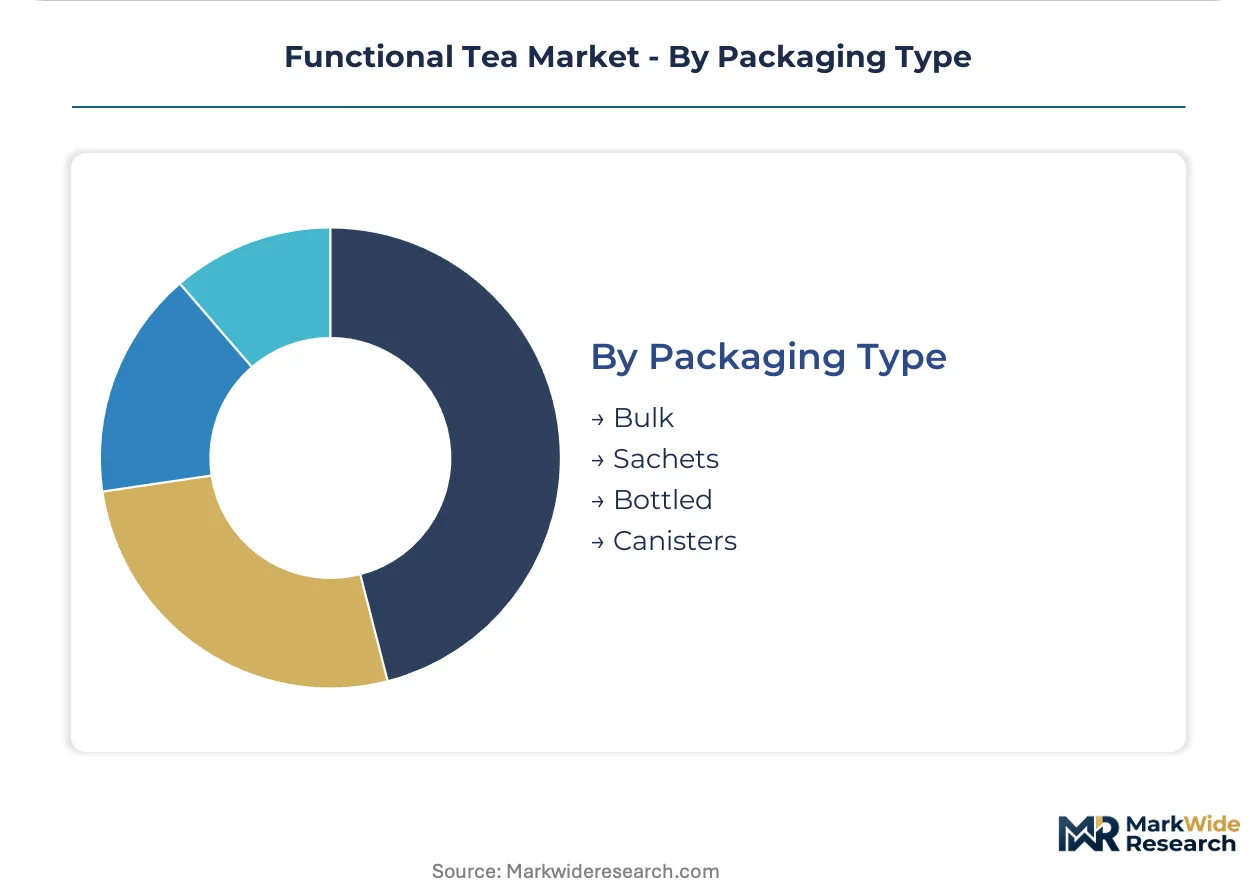
Packaging Type:
Volume concentration in retail grocery separates high-throughput sachet formats from emerging convenience-oriented alternatives.
- Bulk:Loose-leaf presentation in retail or foodservice quantities targeting traditional preparation methods. Hospitality and specialty café channels in Japan and Germany sustain procurement.
- Sachets:Individually wrapped tea bags dominating supermarket aisle distribution and pantry stocking behavior. Cost efficiency and shelf stability preserve volume leadership.
- Bottled:Ready-to-drink cold-brew extraction in PET or glass for immediate consumption. ITO EN's convenience store penetration in Japan and emerging US distribution reshape urban commuter occasions.
- Canisters:Multi-serve rigid packaging for premium loose-leaf and gift positioning. Higher per-unit economics support organic and single-origin marketing claims.
Sachets retain volume leadership while bottled formats climb the fastest through cold-chain distribution expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU 2018/848 organic certification mandates are redirecting premium leaf procurement toward compliant processors across Germany, France, and the Netherlands. Japan's convenience store distribution networks accelerate cold-brew ready-to-drink penetration among urban commuters. India's FSSAI functional food regulations open governed pathways for ayurvedic ingredient teas targeting domestic and export markets.
United States
FDA structure-function claim oversight shapes permissible wellness positioning for adaptogenic and nootropic formulations. Working professionals in New York and Los Angeles metropolitan corridors drive bottled ready-to-drink demand through subscription commerce and convenience retail channels. Cold-brew extraction patents concentrate among processors with captive distribution partnerships.
Germany
EFSA health claims evaluation creates a higher evidentiary bar that limits marketing flexibility but rewards clinical trial investments. Berlin and Hamburg retail channels expand shelf space for EU 2018/848 certified organic lines. German consumers anchor European demand for chamomile and rooibos caffeine-free evening formulations.
Japan
METI industrial standards govern bioactive preservation claims in bottled functional tea segments. Tokyo and Osaka metropolitan zones concentrate convenience store penetration through 7-Eleven and Lawson cold-chain distribution networks. ITO EN dominates commuter consumption occasions with cold-brew extraction technology.
India
FSSAI functional food regulations increasingly govern import standards and domestic labeling for ashwagandha and tulsi ingredient teas. Maharashtra and Karnataka estate networks supply organic-certified leaf volumes for Tata Consumer Products domestic distribution. Ayurvedic formulation demand concentrates in urban wellness-focused consumer segments.
United Kingdom
UK Food Standards Agency implements EU-retained health claims regulations post-Brexit with parallel evidentiary requirements. London metropolitan professionals drive premium loose-leaf and subscription channel growth for adaptogenic blends. Specialist retailers in Manchester and Bristol sustain demand for single-origin organic positioning.
Functional Tea Market Key Industry Players
Listed leaders compete with private specialists across certification tier and format innovation dimensions. The competitive structure bifurcates between multinational beverage conglomerates with global procurement networks and domestic estate-anchored processors with organic supply chain control. Three archetypes dominate: scale-driven multinationals leveraging cold-chain distribution, estate-integrated specialists commanding organic premiums, and convenience-format innovators capturing commuter occasions. M&A activity concentrates on certified estate acquisitions and cold-brew technology licensing.
Among multinational conglomerates, Unilever and Nestle occupy positions defined by global sourcing scale and retail channel breadth. ITO EN exemplifies the convenience-format innovation archetype through Japanese market penetration. Tata Consumer Products and Associated British Foods sit within the estate-integrated tier, with the former anchoring Indian organic supply chains and the latter leveraging European retail distribution density.
| Leading Market Players |
|---|
| Associated British Foods |
| ITO EN |
| Unilever |
| Celestial Seasonings |
| Organic India |
| Nestle |
| Hain Celestial Group |
| The Republic of Tea |
| Tata Consumer Products |
| Others |
Cost & Logistics Intelligence
Conventional black tea substitution in mass-market retail simultaneously redraws procurement geography toward Kenyan and Assam auction houses while compressing functional premium realization across German and US supermarket channels. This input displacement forces processors to defend margin through certification tiering rather than volume scale.
Pricing Analysis
Certification level under USDA NOP and EU 2018/848 creates the primary spread between credentialed organic lines and conventional alternatives. Three-tier pricing structure across premium certified, standard estate-sourced, and economy auction-grade tiers dominates procurement contracts. Cost compression in the economy tier is intensifying because climate-induced harvest volatility in Assam and Kenyan highlands feeds through to raw material instability. Health-conscious consumers in Germany and Japan show least price sensitivity, while US mass-market buyers retain strongest substitution elasticity toward commodity black tea.
Supply Chain Analysis
Strait of Malacca transit underwrites bulk leaf movement from Indian and Sri Lankan processing centers to European blending facilities. Geographic supply concentrates in India, Kenya, and Sri Lanka for Camellia sinensis leaf, with Egypt and India anchoring herbal botanical sourcing. Raw material procurement draws from estate-sourced certified volumes, auction-grade conventional leaf, and solvent-free botanical extracts. Single-source vulnerability in Assam climate exposure threatens supply security for premium green tea lines. Distribution runs through supermarket retail for sachet formats, convenience store cold-chain for bottled RTD, and direct-to-subscription for premium loose-leaf positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German and US retail chains that now demand EU 2018/848 certification as a listing prerequisite, fragmenting processor margin across compliance investment and price negotiation.
For Market Incumbents: Shield certified volume commitments by accelerating backward integration into Indian and Kenyan estate networks before USDA NOP conversion timelines elongate. Cold-brew extraction patent concentration in Japanese and US processors threatens format exclusion for late movers. Prioritize captive supply of organic-certified leaf through long-term estate partnerships in Maharashtra and Karnataka. For New Entrants and Emerging Players: Anchor in India's FSSAI-governed ayurvedic ingredient segment where ashwagandha and tulsi formulations face lower competitive density than saturated green tea markets. Maharashtra urban wellness consumers represent the most penetrable geography for domestic ayurvedic positioning. Pursue direct-to-subscription go-to-market angles targeting millennial discovery through social media ingredient education. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed estate-integrated specialists that captured organic certification early but lack cold-chain distribution scale. Five-to-ten year viability hinges on format diversification beyond sachet dependency. Monitor cold-brew patent licensing activity as the inflection signal for RTD format consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Estate Acquisition | USDA NOP and EU 2018/848 compliance secures premium channel access in German retail. |
| Cold-Brew Patent Licensing | ITO EN's technology concentration enables convenience store penetration in Japanese commuter corridors. |
| Ayurvedic Formulation Pipeline | FSSAI regulatory clarity opens governed pathways for ashwagandha and tulsi export expansion. |
| Direct-to-Subscription Launch | Millennial discovery channels in New York and London bypass supermarket margin compression. |
| Microencapsulation Partnership | Sports nutrition adjacency adoption extends catechin shelf-life claims for pharmaceutical-grade positioning. |
Research Approach
A standing panel of estate procurement managers, regulatory affairs specialists at functional food processors, retail category buyers in German and US channels, and cold-chain logistics coordinators provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against EU 2018/848 regulatory filings, FSSAI functional food notifications, FDA structure-function claim databases, and customs trade records for leaf and botanical inputs. Bottom-up volume triangulation across packaging formats and top-down value reconciliation against certified premium realizations anchored the analytical framework.
Consistency checks validated volume and value outputs against retail audit data from Nielsen and Circana, convenience store distribution metrics from Japanese METI industrial surveys, and organic certification registry counts from USDA and EU databases. Segmentation modeling spanned product type, ingredient category, consumer archetype, and packaging format dimensions across the projection horizon. CAGRs derived from logistic adoption curves for cold-brew formats and linear extrapolation for mature sachet channels, with bioactive preservation technology penetration and regulatory claim approval timelines as industry-specific forecast inputs.
Underlying assumptions cover sustained EU 2018/848 enforcement stringency, stable FSSAI ayurvedic ingredient pathway continuity, and climate volatility patterns in Assam and Kenyan highlands, with deviation risk concentrated in EFSA health claims evaluation delays and cold-chain infrastructure buildout pace in US metropolitan corridors. Practitioners should keep alternative scenarios live as regulatory divergence between FDA structure-function and EFSA evidentiary requirements evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
GCC Functional Food Market
Functional Food and Beverage
Beauty Drinks Market
Functional Food and Beverage
Low Fat Product Market
Functional Food and Beverage
Low Fat Smoothies Market
Functional Food and Beverage
Reduced Sugar Food and Beverages Market
Functional Food and Beverage
Flavored and Functional Water Market
Functional Food and Beverage
Mediterranean Lemon Bioflavonoid Shot Bases Market
Functional Food and Beverage
Vegan Protein Bars Market
Functional Food and Beverage
Mediterranean Healthy-Aging Beverage Ingredients Market
Functional Food and Beverage
Tobacco Alternative Gum Market
Functional Food and Beverage
Functional Foods and Natural Health Products Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
Galacto Oligosaccharides (GOS) Market
Functional Food and Beverage
Natural Functional Food Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market