
 Japan Food Additives Market | 2026-2036
Japan Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Food Additives Market Insights
Premium clean-label specification tiers is reorganizing procurement patterns across Japan's food manufacturing base. Ajinomoto Co., Inc. anchors the flavor enhancer segment through deep fermentation expertise and domestic production scale. BASF SE leverages its synthetic vitamin and carotenoid portfolio to serve Japanese beverage and dairy customers. JAPAN NUTRITION Co., Ltd. specializes in domestically sourced natural extracts for processors seeking shorter supply chains.
Food additives comprise substances incorporated into food products to preserve quality, enhance sensory attributes, or improve processing efficiency, with typical inclusion levels ranging from parts-per-million to several percent by weight depending on functional class and food matrix compatibility. Their primary commercial purpose centers on extending shelf stability, standardizing appearance, and optimizing manufacturing throughput for packaged food producers. Flavor enhancers and natural-source preservatives command disproportionate margin attention as Japanese manufacturers reformulate around METI disclosure guidelines and consumer preference shifts. Emulsifier demand in baked goods and dairy applications sustains volume leadership, while colorant procurement tightens around plant-derived alternatives.
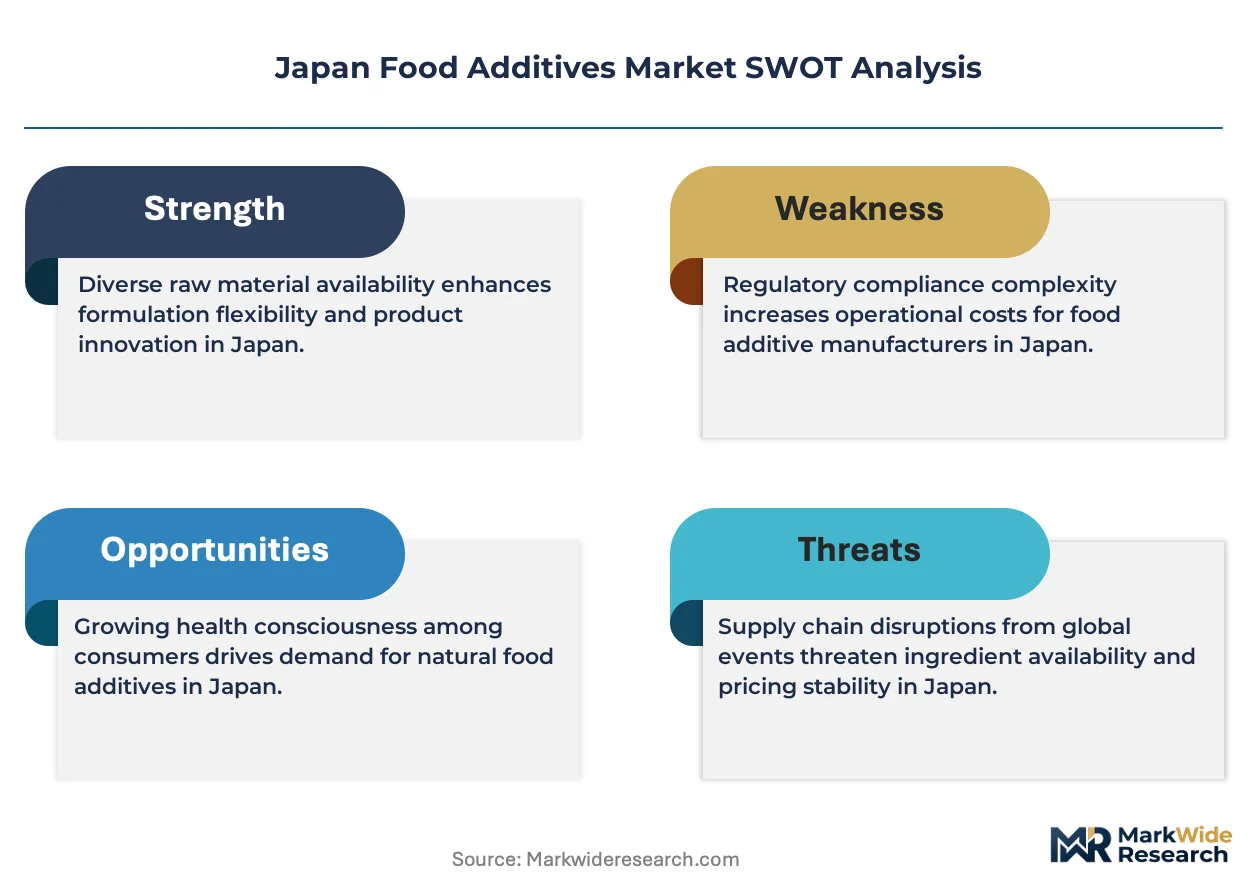
METI enforces Food Labeling Standards that mandate additive disclosure by functional category, compelling reformulation toward shorter ingredient lists. The Ministry of Health, Labour and Welfare (MHLW) administers the Food Sanitation Act specifications for permitted substances and usage limits, directly constraining product development pipelines. Japan Agricultural Standards (JAS) organic certification creates a parallel compliance track for additive sourcing in premium product lines. Stakeholders must monitor pending MHLW reviews of artificial colorant approvals and position natural substitute supply agreements before regulatory transitions tighten.
Market Dynamics
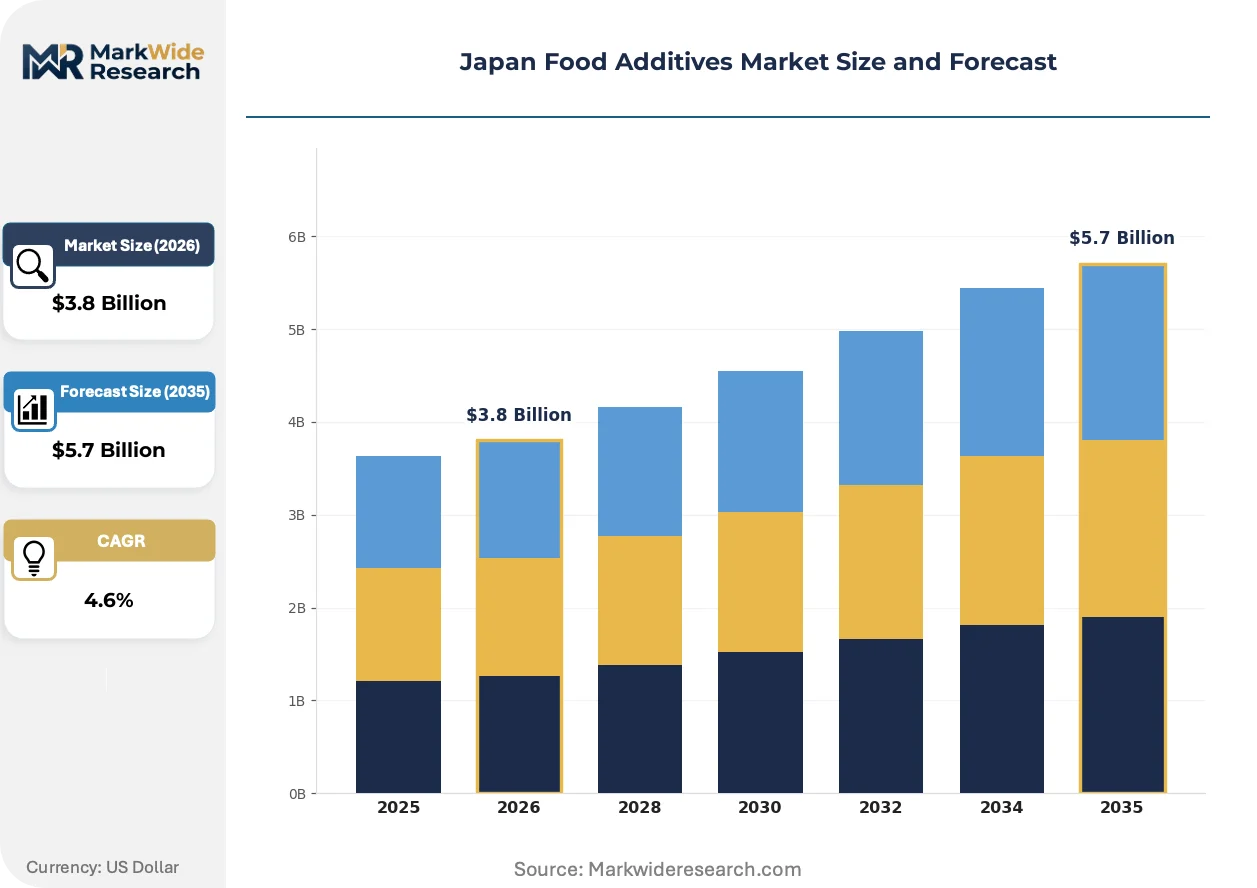
METI's Food Labeling Standards revisions are compressing formulation timelines across Japan's food processing sector, forcing manufacturers to rebuild additive portfolios around shorter ingredient lists before disclosure mandates take full effect.
Growth Catalysts
- Clean-label reformulation mandates:METI disclosure rules are accelerating demand for natural preservatives among ready-to-eat meal producers seeking compliant ingredient decks.
- Fermentation technology advancement:Domestic bioprocessing capabilities are expanding output of umami enhancers derived from traditional koji cultivation methods.
- Kanto processing cluster density:Tokyo's concentrated food manufacturing base generates procurement scale effects for specialty additive distributors serving multiple processors within tight logistics radii.
Market Restraints
- Natural extract input volatility:Weather-dependent yields of plant-derived colorants from domestic agricultural sources create formulation cost uncertainty.
- Single-source fermentation capacity:Ajinomoto's dominance in monosodium glutamate supply concentrates risk for processors dependent on consistent umami additive availability.
- MHLW approval timeline friction:Novel additive substance reviews under the Food Sanitation Act extend product development cycles by 18-36 months versus synthetic alternatives.
Strategic Opportunities
- Kansai underpenetration:Osaka-Kyoto food processing corridors offer additive suppliers lower competitive density than saturated Kanto procurement channels.
- Plant-based protein convergence:Meat alternative manufacturers require emulsifier and texture-modifier portfolios distinct from legacy animal-protein processing formulations.
- JAS organic certification track:Premium product lines seeking organic designation create parallel demand for certified-natural additive sourcing with margin premiums.
Industry Challenges
- Fermentation microbiology talent scarcity:Deep expertise in industrial-scale koji and yeast strain management is concentrated among retiring specialists with limited replacement pipelines.
- Legacy ERP integration friction:Mid-tier processors face system reconfiguration costs when linking batch-level additive traceability to METI-compliant labeling databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Food Additives Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Preservatives, Emulsifiers, Flavor Enhancers, Colorants Formulation: Dry, Liquid, Semi-Solid, Powder End Use: Beverages, Snacks, Baked Goods, Dairy Products Source: Synthetic, Natural, Organic, Others |
| Companies Covered | Feedone Co., Ltd., BASF SE, Ajinomoto Co., Inc., DuPont de Nemours, Inc., Chr. Hansen Holding A/S, Nissin Foods Holdings Co., Ltd, Cargill, Inc., Corbion NV, JAPAN NUTRITION Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Food Additives Market Trends and Innovations
Japan's food additive sector is pivoting from synthetic efficiency toward biological functionality, with fermentation-derived alternatives commanding R&D investment priority across major formulation houses.
Enzymatic extraction methods for plant-based colorants are displacing solvent-based processes in Japanese natural additive manufacturing. Mid-tier beverage processors are adopting these biotechnologies at pilot scale before full production rollout. The shift is compressing synthetic carotenoid demand while elevating domestic botanical supply contracts.
METI's 2023 Food Labeling Standards revision mandates additive disclosure by functional category rather than aggregate listing. Processors must now declare preservatives, colorants, and flavor enhancers separately on packaging. Ready-to-eat meal manufacturers face the steepest reformulation pressure as their multi-additive formulations expose longer ingredient lists to consumer scrutiny.
Buyer concentration among Japan's top ten food processing conglomerates is consolidating procurement decisions into centralized technical teams. Smaller additive distributors are losing direct plant-level relationships as purchasing authority migrates to Tokyo headquarters. This pattern is most visible in dairy applications, where national brands dominate shelf space and negotiate additive supply agreements at corporate scale.
Japan Food Additives Market Segmentation
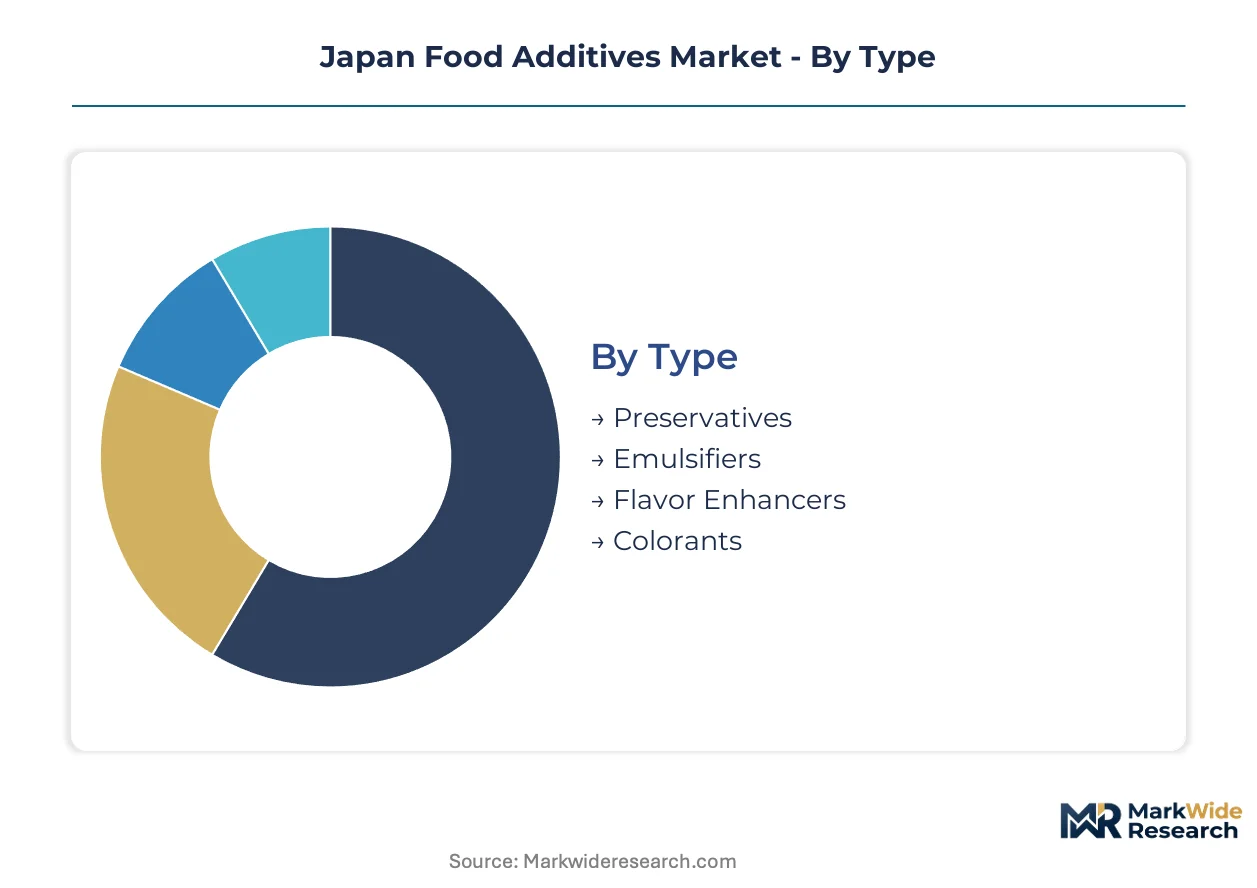
Segmentation in Japan's food additive market reveals how METI disclosure rules and Kanto processing cluster dynamics reshape procurement across functional categories. Manufacturers prioritize segments enabling clean-label reformulation while maintaining shelf stability and sensory performance.
Type:
Preservatives and flavor enhancers anchor domestic production capacity, while colorant development increasingly targets export markets seeking Japanese fermentation expertise.
- Preservatives:Potassium sorbate and sodium benzoate formulations dominate conventional applications, though natamycin and nisin fermentation-derived alternatives are displacing synthetic options in premium ready-to-eat meals. Tokyo-area processors drive procurement volume as they reformulate around METI's additive disclosure mandates.
- Flavor Enhancers:Monosodium glutamate from Ajinomoto's domestic fermentation facilities supplies the bulk of umami functionality, with nucleotide-based enhancers gaining traction in reduced-sodium applications. Kanto beverage manufacturers concentrate demand for clean-label yeast extract alternatives.
- Emulsifiers:Lecithin and mono-diglyceride blends serve baked goods and dairy applications where processing stability requirements limit natural substitution.
- Colorants:Carotenoid and anthocyanin extracts face formulation cost volatility from weather-dependent domestic agricultural yields.
Flavor enhancers hold the largest share; momentum sits with preservatives as natural-source alternatives gain share fastest.
Formulation:
Dry and powder formats command premium logistics efficiency in Japan's dense Kanto distribution network, while liquid formulations concentrate in high-volume beverage processing corridors.
- Dry:Granular preservatives and encapsulated flavor systems enable precise dosing in automated processing lines. Osaka-Kyoto manufacturers favor dry formats for legacy equipment compatibility.
- Powder:Instant dissolution characteristics suit beverage premix applications where batch consistency is critical. Dairy processors in Hokkaido drive specialized powder procurement for recombined milk operations.
- Liquid:Emulsifier concentrates and liquid colorants dominate high-throughput bottling facilities where pump-based dosing reduces handling steps.
- Semi-Solid:Paste emulsifiers and concentrated flavor bases serve artisan-scale bakeries and regional confectionery manufacturers with intermittent production schedules.
Powder formulations lead volume; liquid formats are expanding most quickly in beverage sector automation upgrades.
End Use:
Beverage and dairy applications concentrate procurement authority in Tokyo headquarters, while snacks and baked goods retain more distributed purchasing through regional manufacturing bases.
- Beverages:Acidulants, preservatives, and colorants face the steepest clean-label pressure as health-conscious consumers scrutinize ingredient lists on functional drinks and ready-to-drink teas. Major brands centralize additive specification decisions at corporate technical centers.
- Dairy Products:Emulsifiers and stabilizers maintain volume leadership through fermented milk and processed cheese applications where texture standardization is non-negotiable. Hokkaido's concentrated dairy processing base generates procurement scale effects.
- Baked Goods:Preservative and emulsifier demand sustains steady volumes through Japan's entrenched bread and confectionery consumption patterns.
- Snacks:Flavor enhancer and colorant procurement intensifies around seasonal product launches and limited-edition formulations requiring rapid reformulation cycles.
Dairy products anchor procurement volume; beverages show the steepest expansion trajectory as functional drink categories proliferate.
Source:
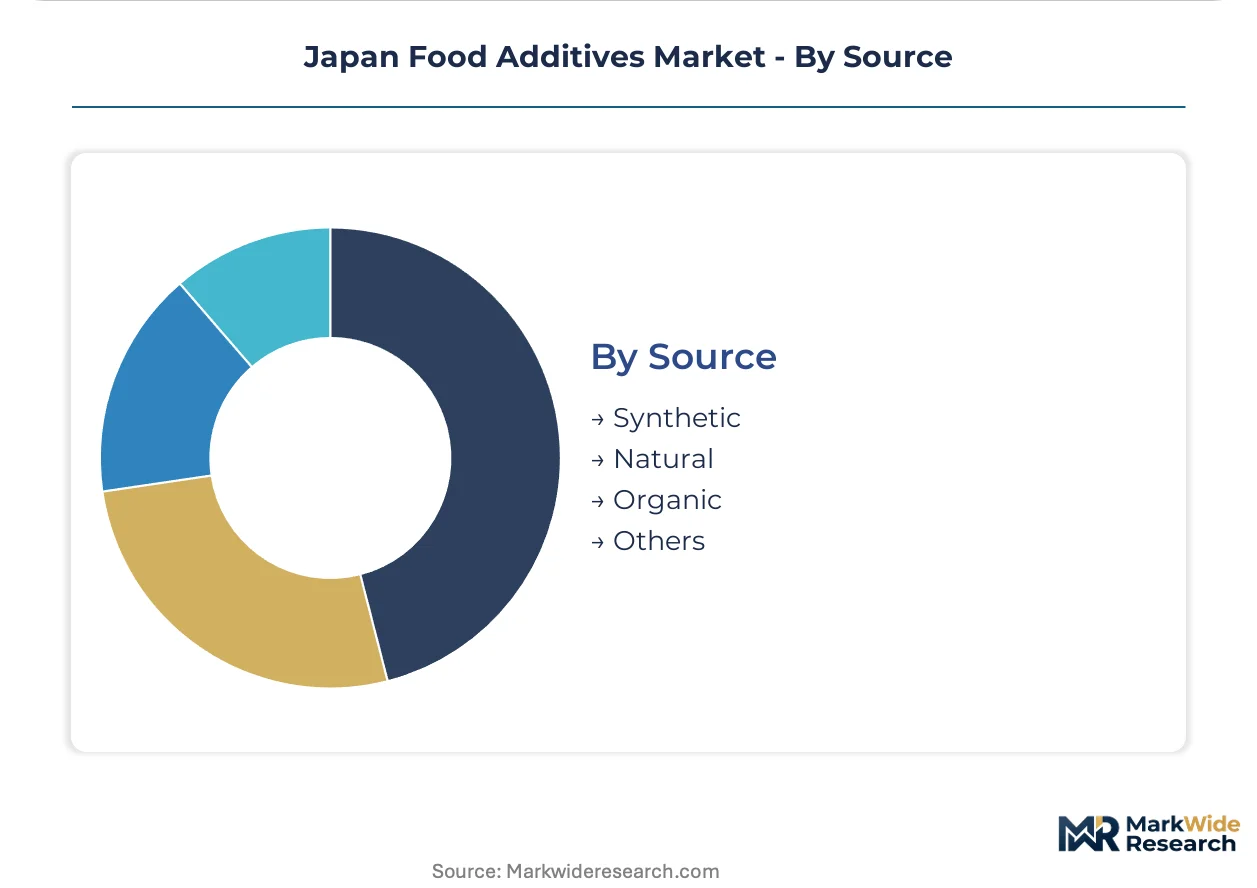
Natural and organic certification tracks command margin premiums, while synthetic alternatives retain cost-sensitive applications pending MHLW approval timelines for novel substitutes.
- Natural:Plant-derived extracts and fermentation-based ingredients capture reformulation investment as processors rebuild portfolios around METI-compliant shorter ingredient lists. JAS organic certification creates parallel premium sourcing requirements.
- Synthetic:Standardized purity and consistent performance sustain demand in mass-market applications where cost constraints outweigh clean-label positioning.
- Organic:Certified-natural additives with full supply chain documentation serve premium product lines seeking JAS organic designation and export market access.
- Others:Hybrid formulations and novel bioprocessing outputs occupy regulatory gray zones pending MHLW Food Sanitation Act review.
Natural sources dominate value; organic certification is gaining share fastest as premium positioning intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports fermentation-derived flavor enhancers and natural preservatives to Southeast Asian processors seeking clean-label alternatives. Domestic procurement concentrates in metropolitan manufacturing corridors where METI disclosure rules drive reformulation investment.
Kanto/Tokyo
Tokyo's dense food processing cluster generates procurement scale for natural preservatives and umami enhancers. METI's Food Labeling Standards revisions compel ready-to-eat meal manufacturers to rebuild additive portfolios around shorter ingredient lists. The metropolitan corridor hosts centralized technical teams from Japan's top ten food conglomerates, consolidating purchasing authority and squeezing regional distributors.
Kansai/Osaka
Osaka-Kyoto food processing corridors offer additive suppliers lower competitive density than saturated Kanto channels. The region's legacy equipment base favors dry format preservatives and encapsulated flavor systems. MHLW's Food Sanitation Act enforcement maintains uniform compliance standards across this secondary manufacturing belt.
Chubu/Nagoya
Nagoya's automotive-industrial spillover supports precision fermentation equipment suppliers serving additive manufacturers. The sub-region's mid-tier processors face ERP reconfiguration costs when linking batch-level traceability to METI-compliant labeling databases. Domestic botanical supply contracts for plant-derived colorants face weather-dependent yield volatility.
Hokkaido
Hokkaido's concentrated dairy processing base generates specialized powder procurement for recombined milk operations. The northern island's dairy applications sustain steady emulsifier and stabilizer demand where texture standardization is non-negotiable. JAS organic certification creates parallel premium sourcing requirements for certified-natural additive tracks.
Kyushu
Kyushu's emerging biotechnology corridor attracts fermentation microbiology talent for industrial-scale koji and yeast strain management. The sub-region's retiring specialist concentration limits replacement pipelines for deep bioprocessing expertise. Regional processors pilot enzymatic extraction methods for plant-based colorants before full production rollout.
Japan Food Additives Market Competitive Landscape
Listed leaders compete with private specialists across disclosure compliance and fermentation scale. The market structure tiers between consolidated flavor enhancer supply and fragmented natural extract sourcing. Three archetypes dominate: integrated fermentation houses, diversified chemical conglomerates, and domestic botanical specialists. Competitive moves concentrate on backward integration into raw material supply and technology licensing for clean-label alternatives.
Within the fermentation tier, Ajinomoto Co., Inc. and JAPAN NUTRITION Co., Ltd. exemplify domestic capability concentration. BASF SE represents the diversified chemical conglomerate archetype serving cross-sector additive demand. These three occupy positions spanning proprietary bioprocessing, synthetic vitamin portfolios, and domestically sourced natural extracts respectively.
| Leading Market Players |
|---|
| Feedone Co., Ltd. |
| BASF SE |
| Ajinomoto Co., Inc. |
| DuPont de Nemours, Inc. |
| Chr. Hansen Holding A/S |
| Nissin Foods Holdings Co., Ltd |
| Cargill, Inc. |
| Corbion NV |
| JAPAN NUTRITION Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Ajinomoto's domestic fermentation capacity utilization above 85 percent creates scale economies that compress unit costs for monosodium glutamate and nucleotide enhancers, simultaneously anchoring price floors for natural-source alternatives and concentrating procurement leverage among Kanto-based ready-to-eat meal manufacturers. This scale dynamic forces smaller additive suppliers to absorb margin compression or exit synthetic preservative segments entirely.
Pricing Analysis
Solvent-based extraction technology commands 15-20 percent price premiums over enzymatic methods for plant-derived colorants, while next-generation koji fermentation platforms under development threaten to collapse this gap. Three-tier pricing structure across premium, standard, and economy levels separates JAS-certified organic additives from conventional natural extracts and synthetic benchmarks. Pricing pressure stems from METI disclosure mandates accelerating reformulation timelines and compressing R&D recovery windows. Mid-tier processors exhibit highest price sensitivity as they lack volume scale to negotiate long-term offtake agreements.
Supply Chain Analysis
Just-in-time inventory strategies dominate Kanto beverage and dairy processors seeking to minimize working capital exposure to weather-dependent botanical yields. Domestic agricultural supply concentrates in Hokkaido and northern Honshu for plant-derived colorants, while fermentation feedstocks draw from corn and tapioca starch imports anchored in Southeast Asian supply contracts. Single-source vulnerability concentrates in Ajinomoto's monosodium glutamate infrastructure. Distribution runs through Tokyo-based technical teams consolidating procurement decisions for Japan's top ten food conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's food additive sector is navigating a cyclical recovery driven by METI's disclosure-driven reformulation wave, which creates temporary demand surges for compliant ingredient portfolios before settling into replacement-rate consumption patterns.
For Market Incumbents: Shield fermentation capacity investments through exclusive supply agreements with Kanto ready-to-eat meal manufacturers facing compressed reformulation timelines. Deepen backward integration into domestic koji strain repositories to secure microbiology talent pipelines against retiring specialist scarcity. METI's pending artificial colorant reviews threaten synthetic portfolio values; accelerate natural substitute R&D to preempt regulatory displacement. For New Entrants and Emerging Players: Differentiate on JAS organic certification track expertise serving premium product lines seeking export market access. White-space opportunities concentrate in Kansai's underpenetrated Osaka-Kyoto corridors and plant-based protein emulsifier portfolios distinct from legacy animal-protein formulations. Target mid-tier processors with ERP-integrated batch traceability solutions linking additive sourcing to METI-compliant labeling databases. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fermentation houses with captive strain libraries and long-term supply agreements with Japan's top ten food conglomerates. Five-to-ten year viability favors specialists with backward integration into domestic agricultural supply contracts rather than import-dependent botanical extractors. Watch MHLW approval timelines for novel bioprocessing outputs as inflection indicators for synthetic substitute displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Domestic Botanical Supply | Hokkaido agricultural contracts reduce weather-dependent yield volatility for plant-derived colorant portfolios. |
| Fermentation Microbiology Talent Acquisition | Kyushu biotechnology corridor recruitment addresses retiring koji specialist scarcity constraining industrial-scale output. |
| JAS Organic Certification Investment | Premium product line positioning captures margin premiums in export-oriented natural additive segments. |
| ERP-Integrated Batch Traceability Deployment | METI-compliant labeling database linkage enables mid-tier processor technical compliance without system reconfiguration friction. |
| Enzymatic Extraction Technology Licensing | Pilot-scale adoption by regional beverage processors accelerates displacement of solvent-based colorant manufacturing methods. |
Research Methodology
Operator-level perspectives from fermentation plant managers, procurement leads at Kanto ready-to-eat meal manufacturers, METI regulatory affairs specialists, and JAS certification auditors anchored the qualitative base for this study. Primary interview findings triangulated against secondary sources including METI Food Labeling Standards documentation, MHLW Food Sanitation Act substance registers, JAS organic certification databases, and customs trade records for fermentation feedstock imports. Bottom-up segment modeling and top-down macro validation converged on volume and value estimates.
Sensitivity analysis tested forecast robustness across natural extract yield volatility scenarios, MHLW approval timeline variations, and METI enforcement intensity assumptions. Segmentation dimensions modeled include additive functional type, formulation format, end-use application, and source certification tier across the projection horizon. CAGRs derived from historical procurement pattern analysis and forward-looking capacity expansion announcements. Industry-specific inputs encompassed koji fermentation output forecasts and domestic agricultural yield projections.
The analysis sits within stated boundaries; outcomes outside sustained METI enforcement intensity, stable domestic agricultural supply, and predictable MHLW review timelines would require recalibration. Forecasts reflect documented assumptions regarding clean-label reformulation velocity and fermentation technology adoption curves. Revision becomes warranted when natural extract input cost volatility crosses thresholds that trigger synthetic additive retention in cost-sensitive applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
South America Food Stabilizers Market
Food Additives and Ingredients
Biscuit Shortening Flakes Market
Food Additives and Ingredients
Africa Food Hydrocolloids Market
Food Additives and Ingredients
Food Grade Calcium Hydroxide Market
Food Additives and Ingredients
Global Crystalline Maltitol Market
Food Additives and Ingredients
Food Processing Ingredients Market
Food Additives and Ingredients
Food Grade Release Agent Market
Food Additives and Ingredients
DATEM Replacement Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market
Food Additives and Ingredients
Mexico Food Enzymes Market
Food Additives and Ingredients
Germany Anticaking Market
Food Additives and Ingredients
Africa Feed Additives Market
Food Additives and Ingredients
Food Encapsulation Market
Food Additives and Ingredients
North America Food Coating Ingredients Market
Food Additives and Ingredients
Modified Milk Ingredients Market
Food Additives and Ingredients
Europe Food Colorants Market