
 Vegan Protein Bars Market | 2026-2036
Vegan Protein Bars Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Protein Bars Market Analysis
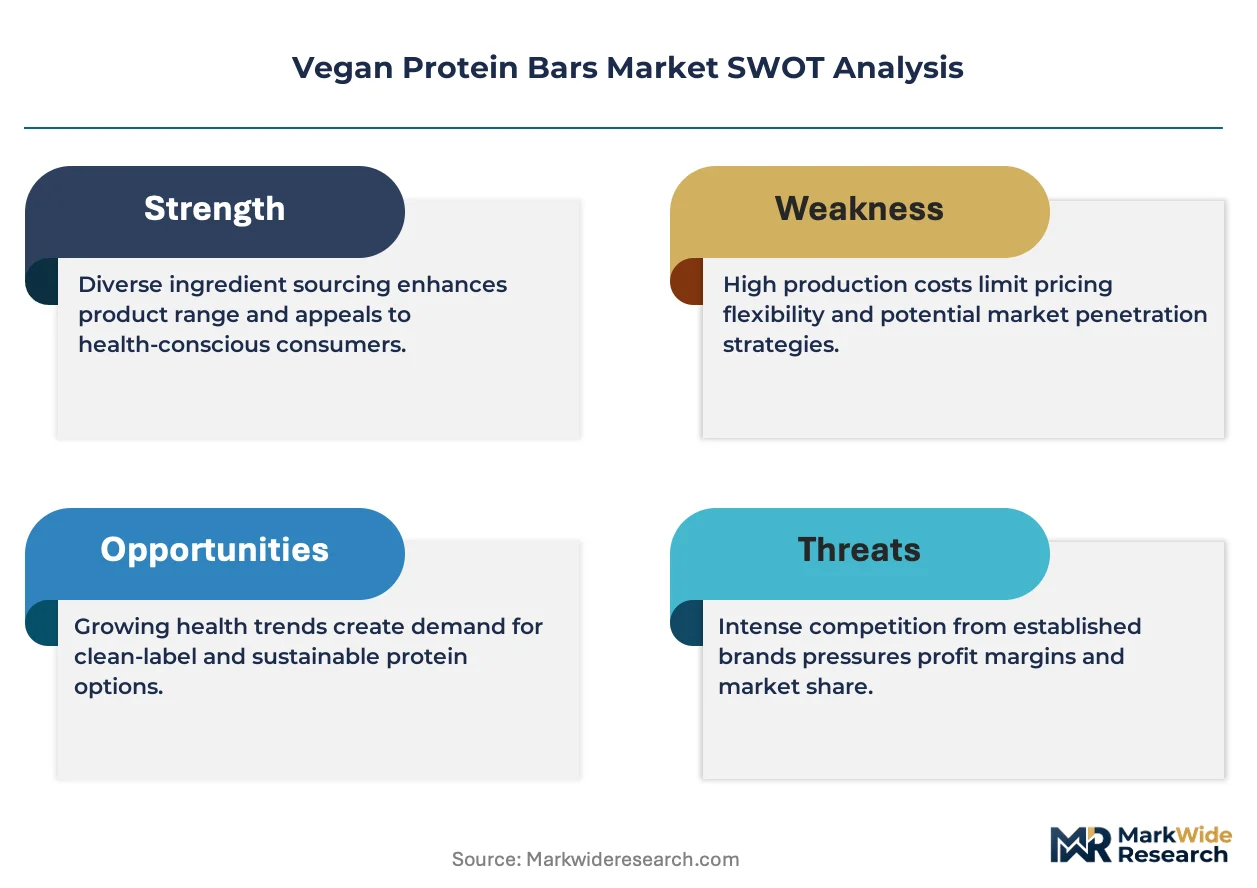
Multi-source ingredient procurement is decoupling from the single-origin supply contracts that once dominated vegan protein bar manufacturing. Orgain leverages its vertically integrated pea protein sourcing to control input costs across North American production. GoMacro competes through certified organic and allergen-free formulations that command premium shelf placement. RXBAR anchors its position with minimalist ingredient lists that reduce label complexity for mainstream grocery buyers.
Vegan protein bars are shelf-stable nutrition products formulated from isolated plant proteins—typically pea, rice, soy, or hemp—combined with binding agents and natural sweeteners to deliver 10–20 grams of protein per serving with complete amino acid profiles. Their primary commercial purpose is to provide portable, allergen-reduced protein supplementation for consumers excluding animal products. Nut-based formulations occupy the largest revenue share due to superior taste masking and established consumer familiarity. Online Retail represents the fastest-growing distribution channel as direct-to-consumer subscriptions reduce price transparency and build purchase habituation.
The FDA governs nutrition labeling and protein content claims under the Federal Food, Drug, and Cosmetic Act, while the USDA oversees organic certification pathways that many vegan bar producers pursue for differentiation. The EU Green Deal and REACH frameworks in Europe impose stricter sustainability reporting on ingredient sourcing, reshaping supplier qualification requirements for brands exporting into the region. Stakeholders must monitor evolving clean-label enforcement thresholds and carbon-footprint disclosure mandates that will determine which formulations retain shelf access across major retail channels.
Market Dynamics
Ingredient traceability mandates under the EU Green Deal are forcing reformulation timelines and supplier audits across the vegan protein bar supply chain, compressing margins for brands dependent on opaque sourcing networks.
Growth Catalysts
- Fitness Enthusiast Demand:Amateur athletes and recreational gym-goers are driving volume expansion as post-workout protein consumption shifts decisively toward plant-based formats.
- REACH Compliance Spillover:European sustainability reporting requirements are accelerating clean-label adoption in North American export-oriented production facilities.
- Pea Protein Isolation Advances:Enzymatic processing improvements are reducing off-flavor compounds in plant isolates, improving palatability thresholds for mainstream grocery buyers.
Market Restraints
- Input Cost Volatility:Organic brown rice protein concentrate prices fluctuate with monsoon-dependent Indian harvest cycles, squeezing formulation budgets.
- Supply Concentration Risk:North American pea protein processing capacity clusters in Saskatchewan and Manitoba, creating regional weather exposure.
- Technical Limitation:Plant protein digestibility scores trail animal-derived alternatives, limiting performance-positioned product claims.
Strategic Opportunities
- German Retail Penetration:Mainstream grocery shelf space expansion in Berlin and Munich offers established brands direct access to Europe's largest vegan consumer base.
- Direct-to-Consumer Subscription Models:Recurring revenue platforms bypass retail slotting fees and capture purchase habituation data for flavor development.
- USDA Organic Certification Pathway:Federal organic labeling provides price-premium justification and defensible shelf positioning against conventional competitors.
Industry Challenges
- Clean-Label Enforcement Thresholds:Evolving FDA guidance on natural sweetener nomenclature requires continuous label redesign and regulatory monitoring.
- Carbon-Footprint Disclosure Mandates:Scope 3 emissions tracking for imported ingredients demands supply chain visibility investments that smaller producers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Protein Bars Market |
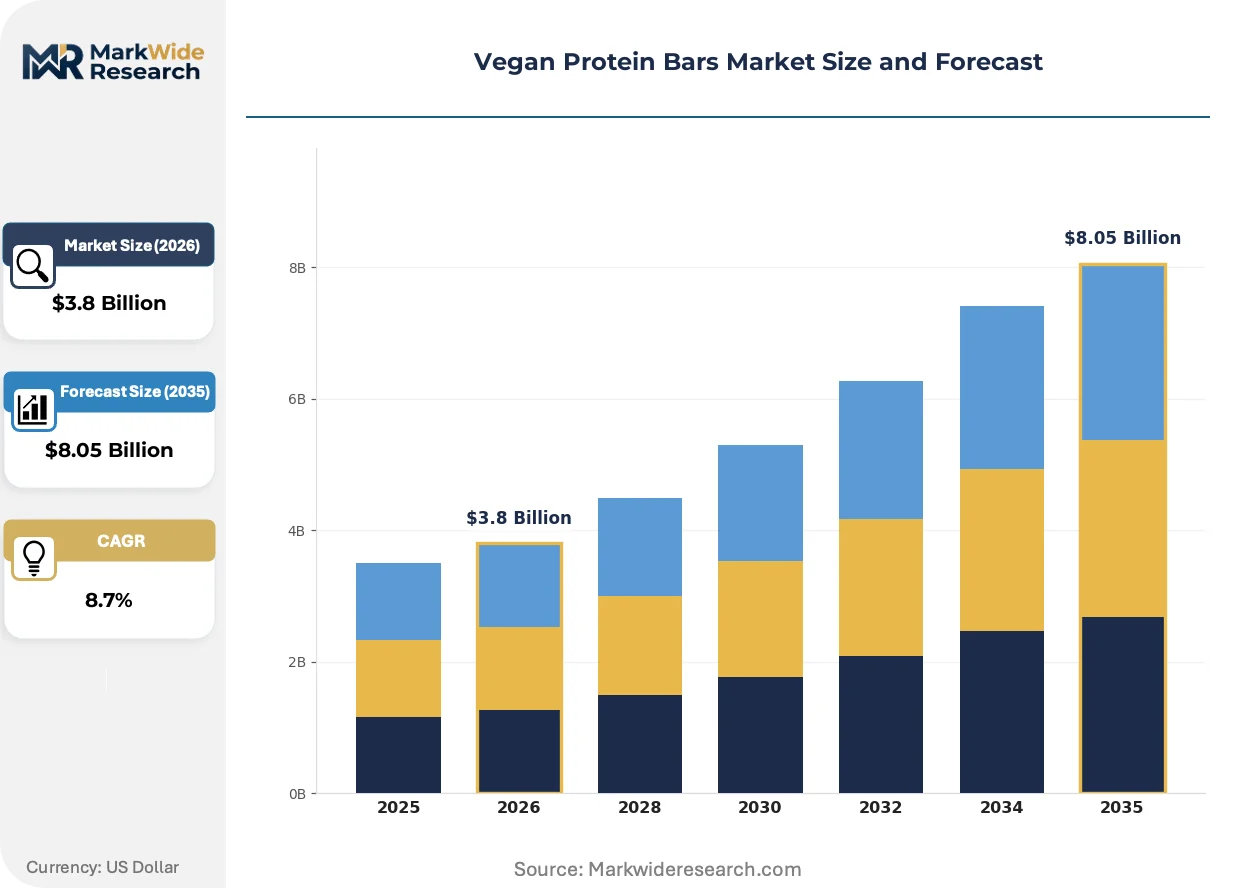
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut-Based, Seed-Based, Grain-Based, Fruit-Based Packaging Type: Individual Packets, Boxes, Pouches, Bulk Distribution Channel: Online Retail, Supermarkets, Health Stores, Convenience Stores Flavor: Chocolate, Vanilla, Berry, Peanut Butter |
| Companies Covered | Larabar, BHU Foods, Bulletproof, 88 Acres, Orgain, GoMacro, NuGo, RXBAR, NoCow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Protein Bars Market Emerging Trajectories
High-pressure processing and enzymatic flavor-masking systems are rewriting formulation economics, while regulatory disclosure requirements and channel fragmentation are redistributing competitive advantage toward vertically integrated producers.
Extrusion-based texturization technology is automating the production of fibrous protein matrices that replicate the mouthfeel of traditional baked bars. Mid-sized contract manufacturers in the American Midwest are adopting these systems to serve private-label clients demanding shorter production runs. The technology is automating batch consistency controls that previously required manual sensory evaluation, reducing defect rates and accelerating new product introduction cycles.
The EU Green Deal's Farm to Fork Strategy is mandating blockchain-enabled ingredient traceability for plant-based foods entering European distribution. This regulatory pressure is disqualifying suppliers unable to provide farm-level documentation, shrinking the qualified supplier pool for export-oriented brands. German and Dutch importers are responding by consolidating procurement around vertically integrated pea protein processors with captive agricultural operations.
Subscription-based replenishment models are displacing impulse purchases at conventional retail for core vegan protein bar consumers. Direct-to-consumer platforms capture recurring revenue and reduce price transparency, while specialty retailers lose traffic to automated delivery schedules. This channel shift concentrates most visibly in urban coastal markets where delivery logistics density supports same-day fulfillment promises.
Vegan Protein Bars Market Segmentation
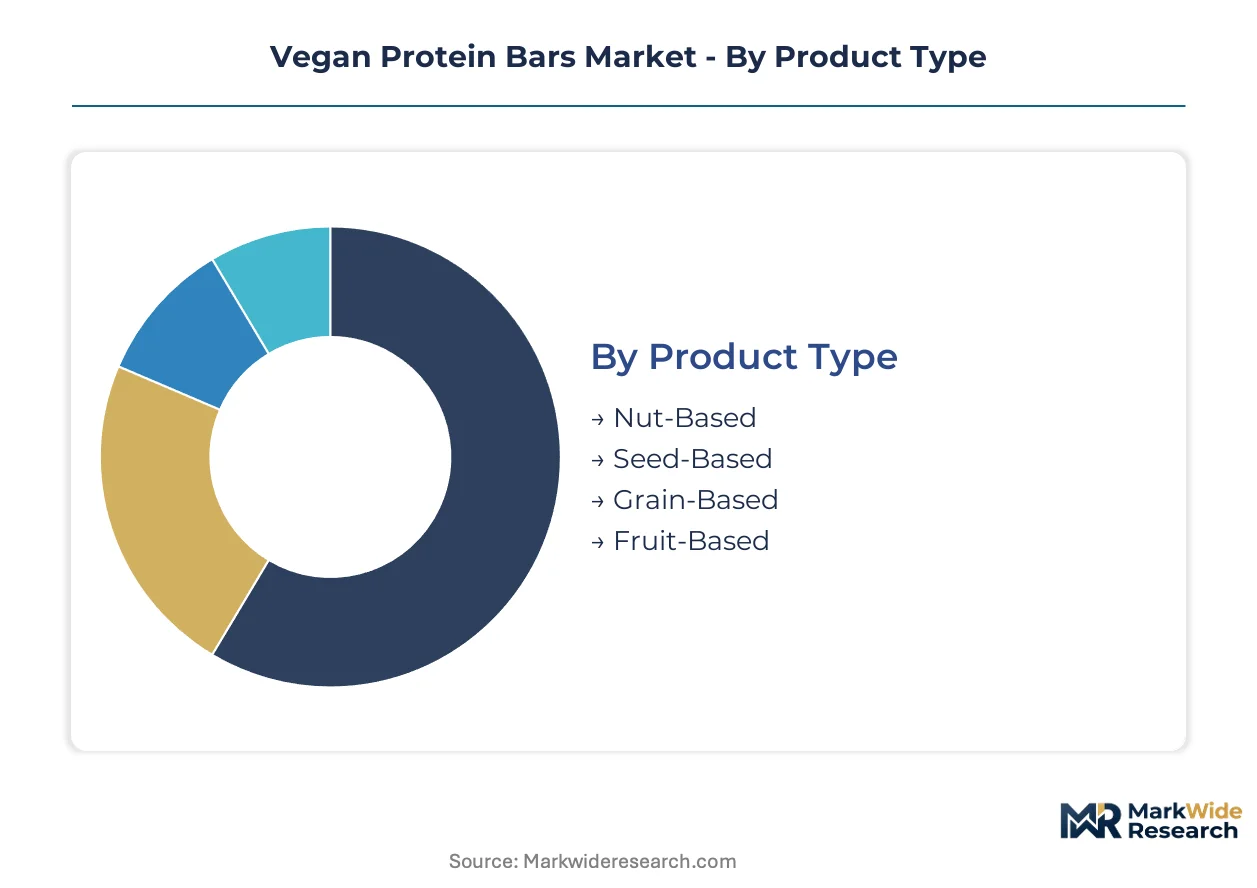
Segmentation in the vegan protein bar market reveals how formulation choices, packaging formats, and channel strategies align with distinct consumer purchasing behaviors. Each dimension carries implications for margin structure, shelf placement negotiations, and supply chain configuration.
Product Type:
Texture and taste masking capabilities drive consumer trial and repeat purchase decisions across formulation categories.
- Nut-Based:Almond, cashew, and peanut protein matrices deliver superior mouthfeel and flavor compatibility, anchoring premium positioning in German mainstream grocery channels where expanded shelf space rewards proven consumer acceptance.
- Seed-Based:Pumpkin, sunflower, and chia protein isolates appeal to allergen-avoidant consumers seeking alternatives to tree nut formulations, with demand concentrating in North American direct-to-consumer subscriptions where ingredient transparency commands subscription loyalty.
- Grain-Based:Brown rice and oat protein concentrates offer cost-advantaged formulations for price-sensitive retail tiers.
- Fruit-Based:Date and dried fruit binding systems provide whole-food positioning for clean-label adherents.
Nut-Based leads on scale; Seed-Based leads on momentum.
Packaging Type:
Portability requirements and consumption occasion fragmentation are reshaping primary packaging specifications across retail and digital channels.
- Individual Packets:Single-serve wrappers dominate impulse purchase environments and gym bag portability, with demand accelerating in convenience store channels where grab-and-go occasions drive volume.
- Boxes:Multi-count cartons anchor pantry-stocking behavior and subscription replenishment models, capturing recurring revenue through automated delivery platforms that reduce price transparency.
- Pouches:Flexible stand-up bags serve family and sharing occasions in club retail formats.
- Bulk:Unwrapped or minimal-packaging formats address zero-waste retail environments and food service applications.
Individual Packets dominate transaction frequency; Boxes dominate customer lifetime value.
Distribution Channel:
Channel selection determines margin capture, data access, and brand control intensity for vegan protein bar producers.
- Online Retail:Direct-to-consumer platforms and marketplace storefronts bypass slotting fees while capturing purchase habituation data, expanding most quickly in urban coastal markets where same-day fulfillment density supports subscription conversion.
- Supermarkets:Mainstream grocery placement validates brand legitimacy and drives trial among non-committed vegan consumers, with German retailers expanding dedicated plant-based sections that reduce competitive clutter.
- Health Stores:Specialty retailers provide curated discovery environments for emerging brands and novel formulations.
- Convenience Stores:Immediate consumption occasions and travel channels support premium single-serve pricing.
Supermarkets anchor volume base; Online Retail captures steepest expansion trajectory.
Flavor:
Familiarity and indulgence perception govern flavor selection, with formulation chemistry constraints limiting viable options for plant protein masking.
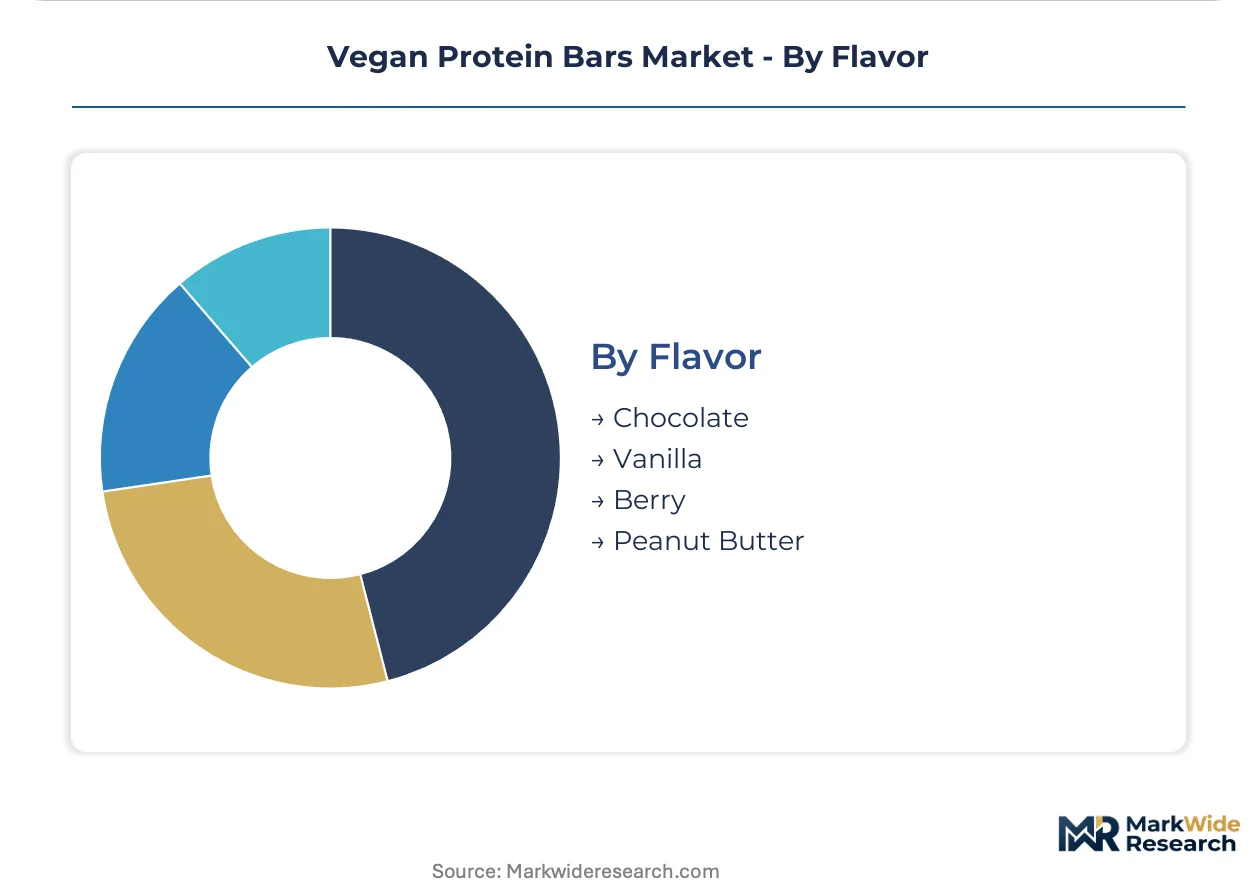
- Chocolate:Cocoa compounds effectively mask pea protein off-notes, supporting the broadest consumer acceptance and commanding the largest revenue share across all retail channels.
- Peanut Butter:Nut butter formulations align with North American taste preferences and sports nutrition positioning, concentrating demand in fitness-oriented consumer segments and post-workout consumption occasions.
- Vanilla:Neutral base profiles support mix-in customization and recipe integration applications.
- Berry:Fruit-forward positioning appeals to wellness-oriented and female-skewing demographic segments.
Chocolate leads on universal penetration; Peanut Butter leads on segment-specific depth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as brands migrate formulation and packaging operations toward jurisdictions with lower compliance burdens. The EU Green Deal's traceability mandates have compressed margins for European contract manufacturers, prompting export-oriented brands to qualify alternative production sites. Saskatchewan's captive pea protein supply chains now attract North American brands seeking upstream cost control.
Germany
Fitness enthusiasts and amateur athletes in Berlin and Munich drive the fastest-growing consumer cohort for plant-based sports nutrition. The EU Farm to Fork Strategy under the European Green Deal mandates blockchain-enabled ingredient traceability, disqualifying suppliers lacking farm-level documentation. Mainstream grocery retailers in Hamburg and Cologne have expanded dedicated vegan shelf sections, reducing competitive clutter for validated brands.
United States
Direct-to-consumer subscription platforms capture recurring revenue from urban coastal markets where same-day fulfillment density supports automated replenishment. The FDA governs nutrition labeling and protein content claims under the Federal Food, Drug, and Cosmetic Act, while the USDA oversees organic certification pathways that producers pursue for price-premium justification. Contract manufacturers in the American Midwest adopt extrusion-based texturization systems to serve private-label clients demanding shorter production runs.
Canada
Health Canada and the PMRA regulate novel food ingredients and pesticide residues in plant protein concentrates entering Canadian distribution. Saskatchewan and Manitoba host concentrated pea protein processing capacity, creating regional weather exposure that brands must hedge through multi-source procurement. Toronto and Vancouver anchor direct-to-consumer logistics networks that bypass conventional retail slotting fees.
United Kingdom
Clean-label adherents in London and Manchester concentrate demand for whole-food positioning and allergen-reduced formulations. Post-Brexit regulatory divergence from EU REACH frameworks creates compliance complexity for brands serving both markets, though UKCA marking requirements remain partially harmonized. Specialty retailers in Edinburgh and Bristol provide curated discovery environments for emerging brands seeking trial among committed vegan consumers.
Netherlands
Dutch importers consolidate procurement around vertically integrated pea protein processors with captive agricultural operations to satisfy EU Green Deal supplier qualification requirements. The Randstad logistics cluster supports rapid distribution into German retail channels, leveraging Rotterdam port infrastructure for ingredient import efficiency. Amsterdam-based direct-to-consumer platforms experiment with subscription models that reduce price transparency and build purchase habituation.
Vegan Protein Bars Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue certified organic and allergen-free positioning to command premium shelf placement. The market structure stratifies across three archetypes: vertically integrated ingredient processors controlling input costs, formulation specialists competing through clean-label certifications, and minimalist brands reducing label complexity for mainstream grocery buyers. Dominant competitive moves include backward integration into captive protein supply and geographic expansion through German retail penetration.
Within the vertically integrated tier, Orgain leverages in-house pea protein sourcing to manage formulation economics across North American production. GoMacro and RXBAR occupy distinct positioning vectors: GoMacro exemplifies the certified-organic archetype with allergen-free formulations, while RXBAR anchors the minimalist-ingredient approach that reduces procurement complexity for conventional retail buyers. These three companies represent the strategic poles—supply control, certification premium, and label simplicity—around which competitive dynamics organize.
| Leading Market Players |
|---|
| Larabar |
| BHU Foods |
| Bulletproof |
| 88 Acres |
| Orgain |
| GoMacro |
| NuGo |
| RXBAR |
| NoCow |
| Others |
Supply Flow & Price Mechanics
Pea protein processing specialists concentrated in Saskatchewan and Manitoba create labor-cost differentials that widen pricing-tier spreads between premium organic formulations and conventional grain-based alternatives. These regional workforce clusters tether formulation economics to prairie agricultural cycles while compressing margins for brands lacking captive supply.
Pricing Analysis
Retailer markup layers absorb 35-50 points of shelf price for branded vegan protein bars, forcing direct-to-consumer subscriptions to compete on net landed cost rather than list price. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified products from conventional clean-label formulations and private-label commodity bars. Price differentiation hinges on certification grade and volume scale, with organic allergen-free commands commanding shelf premiums while grain-based economy tiers face cost compression from input volatility. Fitness enthusiasts show lowest price sensitivity; mainstream grocery trialists exhibit highest elasticity.
Supply Chain Analysis
Organic brown rice protein concentrate supply rests on Indian monsoon-dependent harvest cycles, creating formulation budget vulnerability for brands without multi-source procurement. Pea protein isolation capacity concentrates in Saskatchewan, Manitoba, and select Dutch processing facilities, while natural sweetener inputs draw from Mexican agave operations and Southeast Asian coconut sugar cooperatives. Single-source vulnerability in North American pea protein processing exposes brands to regional weather disruption. Distribution runs through Rotterdam port infrastructure for European-bound finished goods, with domestic North American flows leveraging Midwest contract manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU Green Deal compliance costs and North American production economics, with German retail penetration justifying upstream investment despite European regulatory burden.
For Market Incumbents: Anchor shelf position through backward integration into captive pea protein supply in Saskatchewan, insulating formulation costs from harvest volatility. Defend against emerging seed-based allergen-free entrants by accelerating USDA Organic certification timelines and locking expanded German grocery placement before traceability mandates harden. Prioritize direct-to-consumer subscription infrastructure to capture recurring revenue and reduce price transparency.
For New Entrants and Emerging Players: Specialty retailers in Edinburgh and Bristol offer curated discovery environments with lower slotting fee barriers than mainstream grocery. Target seed-based formulations for allergen-avoidant consumers in North American direct-to-consumer channels where ingredient transparency commands subscription loyalty. Pursue white-label manufacturing partnerships with Midwest extrusion-equipped contract manufacturers to bypass capital-intensive production investment.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized organic-certified brands lacking German retail penetration but holding compliant supply chains. Long-term viability favors vertically integrated processors with farm-level traceability systems already operational. Watch EU Farm to Fork enforcement thresholds as the signal indicating which formulation portfolios retain shelf access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Protein Supply | Captive Saskatchewan processing insulates margins from monsoon-driven rice protein volatility. |
| German Retail Shelf Space Expansion | Berlin and Munich mainstream grocery placement validates brand legitimacy for EU export. |
| Direct-to-Consumer Subscription Launch | Automated replenishment captures purchase habituation data and bypasses slotting fees. |
| USDA Organic Certification Investment | Federal labeling provides price-premium justification against conventional competitors. |
| Blockchain Traceability Implementation | Farm-level documentation satisfies EU Green Deal supplier qualification requirements. |
Methodological Framework
Coverage spans North America and Western Europe, with primary inputs from each region's vegan protein bar value chain. The analysis combines interviews with brand formulation directors, contract manufacturing operations heads, German grocery category buyers, and USDA organic certification specialists with secondary validation from FDA labeling guidance, EU Farm to Fork Strategy documentation, and Nielsen retail audit data. Bottom-up volume modeling triangulates against top-down category spending estimates.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. The analytical framework models segmentation by product type, packaging format, distribution channel, and flavor profile, with cross-cutting analysis of regulatory compliance tier and supply chain integration level. CAGRs derive from trend extrapolation adjusted for input cost volatility and channel shift elasticity. Industry-specific forecast inputs include pea protein processing capacity expansion timelines and German retail shelf space allocation trends.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU traceability enforcement thresholds and monsoon pattern disruption. Projections reflect assumptions about clean-label regulatory stability and direct-to-consumer logistics density expansion. A small set of named triggers—REACH compliance spillover, extrusion technology adoption rates, and carbon-footprint disclosure mandate timing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Soluble Beta Glucan Market
Functional Food and Beverage
Functional Soda Market
Functional Food and Beverage
Asia-Pacific Functional Mushroom Market
Functional Food and Beverage
Keto Ice Cream Market
Functional Food and Beverage
Global Functional Foods Market
Functional Food and Beverage
GCC Functional Food Market
Functional Food and Beverage
Prebiotic Fiber Market
Functional Food and Beverage
Protein Water Market
Functional Food and Beverage
Functional Food and Beverage Market
Functional Food and Beverage
Very Low Calorie Desserts Market
Functional Food and Beverage
Instant Protein Beverages Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market
Functional Food and Beverage
North America Functional Water Market
Functional Food and Beverage
Functional Shots Market
Functional Food and Beverage
Functional Dairy Products Market