
 Rooibos Tea Market | 2026-2036
Rooibos Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Rooibos Tea Market Outlook
The processing-capability gap between vertically integrated South African growers and outsourced-packaging Western brands is reorganizing margin capture across the value chain. Rooibos Ltd. anchors upstream supply through its control of the Clanwilliam processing facility and farmer cooperative networks. Twinings competes in premium European retail channels with blended rooibos SKUs that leverage established grocery distribution. Numi Organic Tea differentiates through certified organic sourcing and direct-trade relationships that bypass conventional auction structures.
Rooibos tea comprises the oxidized and unoxidized needle-like leaves of Aspalathus linearis, a leguminous shrub endemic to South Africa's Cederberg mountain region, containing aspalathin and nothofagin as signature polyphenolic compounds with zero caffeine and low tannin profiles. The plant requires specific sandstone-derived, acidic soils and Mediterranean climate conditions, restricting viable cultivation to a narrow geographic band and creating inherent supply constraints. Loose leaf formats occupy the highest-margin tier in specialty retail, while tea bags dominate household volume through supermarket channels. Organic certification within the form segment commands price premiums in North American and European health food stores, though conventional unflavored variants sustain the bulk of export tonnage.
South Africa's Department of Agriculture enforces rooibos geographic indication protections that limit legal use of the name to domestic origin, while the EU's F-Gas Regulation and REACH frameworks indirectly shape packaging material standards for imported tea products. The USDA's National Organic Program governs certification requirements for organic-labeled rooibos entering American retail channels. Stakeholders must monitor evolving geographic indication enforcement in new trade agreements and adapt sourcing strategies accordingly.
Market Dynamics
Geographic indication enforcement by South Africa's Department of Agriculture, Land Reform and Rural Development is tightening supply-side control, while functional beverage startups in the United States accelerate demand for caffeine-free polyphenol extracts. This regulatory-commercial tension is redistributing margin capture toward upstream processors with certified cultivation access.
Growth Catalysts
- EU F-Gas Regulation:Packaging material standards for imported tea products are accelerating sustainable material adoption among European distributors sourcing rooibos extracts.
- Specialty beverage retailers:German retail channels are expanding shelf space allocation for rooibos SKUs as consumer migration toward caffeine-free alternatives strengthens.
- Aspalathin extraction technologies:Novel processing methods are unlocking antioxidant concentrate applications for nutraceutical formulators targeting functional drink markets.
Market Restraints
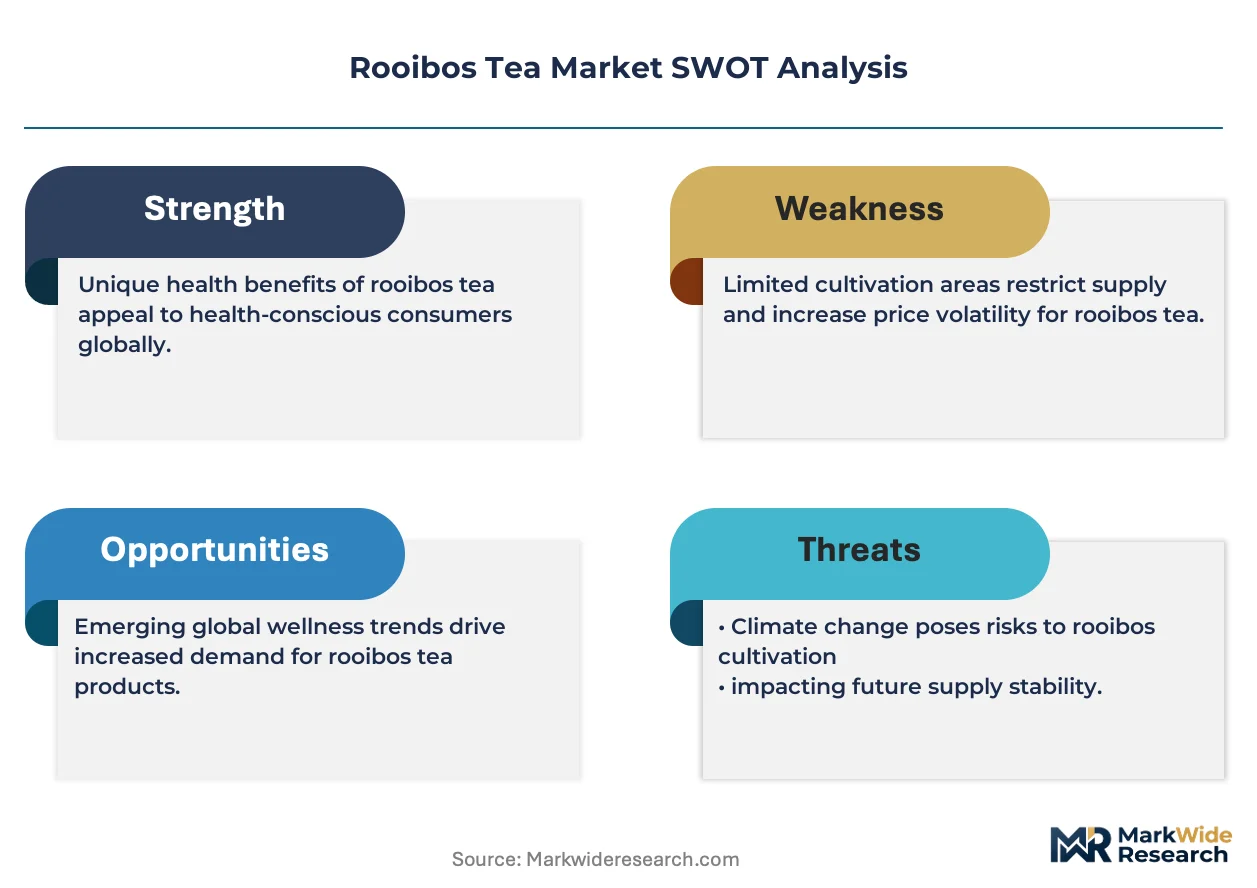
- Cederberg cultivation concentration:The endemic range of Aspalathus linearis to South Africa's sandstone-derived acidic soils creates inherent supply constraints with no viable alternative geography.
- Climate volatility exposure:Mediterranean climate dependency in the Western Cape region generates yield uncertainty from drought and temperature fluctuation cycles.
- Herbal tea substitution:Chamomile, peppermint, and hibiscus alternatives compete for shelf space and consumer trial in caffeine-free beverage categories.
Strategic Opportunities
- Ready-to-drink formulations:United States functional beverage startups are incorporating rooibos into canned and bottled products, bypassing traditional loose-leaf and tea-bag channels.
- USDA National Organic Program certification:Organic-labeled rooibos commands price premiums in North American health food retail, creating margin expansion for certified South African cooperatives.
- Direct-trade relationships:Specialty importers are bypassing conventional auction structures through farmer-direct contracts, capturing traceability premiums and quality tier separation.
Industry Challenges
- Processing-capability gaps:Vertically integrated South African growers maintain upstream control while Western brands dependent on outsourced packaging struggle to defend margin position.
- Geographic indication compliance timelines:New trade agreement negotiations require continuous monitoring of evolving enforcement protocols for unauthorized cultivation claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rooibos Tea Market |
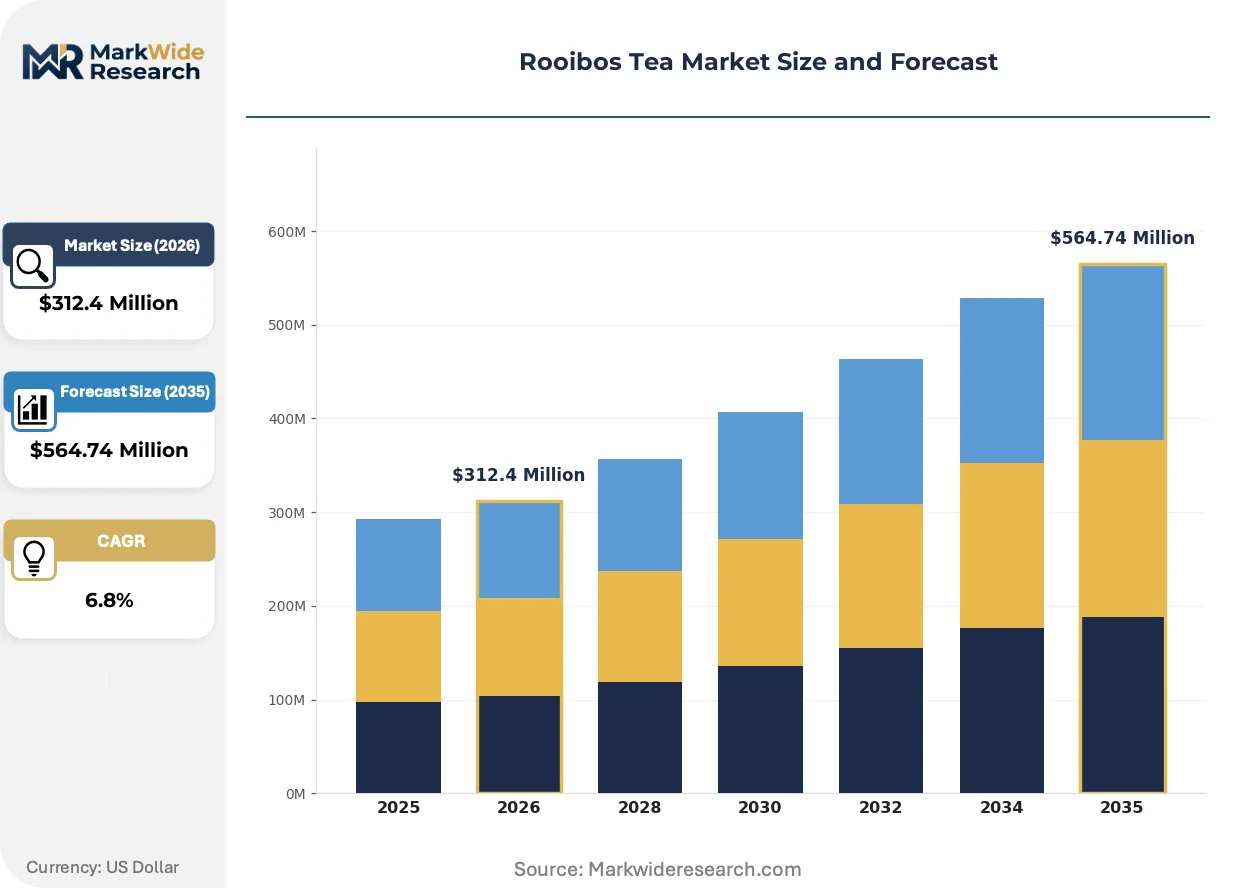
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Leaf, Tea Bags, Instant, Powdered Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Stores End User: Households, Cafes, Restaurants, Health Enthusiasts Form: Herbal Blend, Flavored, Unflavored, Organic |
| Companies Covered | Rooibos Ltd., Joekels Tea Packers Ltd, Carmién Tea, Cape Natural Tea Products, Twinings, The Republic of Tea, Harney & Sons Fine Teas, Numi Organic Tea, Tick Tock Tea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rooibos Tea Market Strategic Shifts
Processing technology and regulatory frameworks are converging to reshape how rooibos moves from Cederberg cultivation to finished consumer products. Three distinct shifts are reconfiguring competitive advantage across the value chain.
Micro-encapsulation of aspalathin and nothofagin extracts is displacing conventional dried-leaf exports as the primary value-capture mechanism for South African processors. Nutraceutical manufacturers in Germany and the United States are adopting these concentrates for functional beverage and supplement formulations. This technology shift compresses reliance on bulk commodity tea auctions while enabling premium pricing for standardized polyphenol content.
REACH and the EU F-Gas Regulation are mandating sustainable packaging material transitions for imported tea products entering European retail channels. Distributors sourcing rooibos for German and Dutch supermarket chains must now certify compostable or recyclable packaging compliance. Specialty beverage retailers are responding by consolidating supplier relationships with processors demonstrating full chain-of-custody documentation.
Certification-driven procurement preferences are fragmenting traditional auction-based purchasing patterns among North American importers. Health food store buyers in the United States now prioritize USDA National Organic Program and Fair Trade certified rooibos, displacing conventional unflavored bulk tonnage. This behavioral shift concentrates volume with South African cooperatives maintaining dual certification, particularly those in the Clanwilliam processing catchment.
Rooibos Tea Market Segmentation
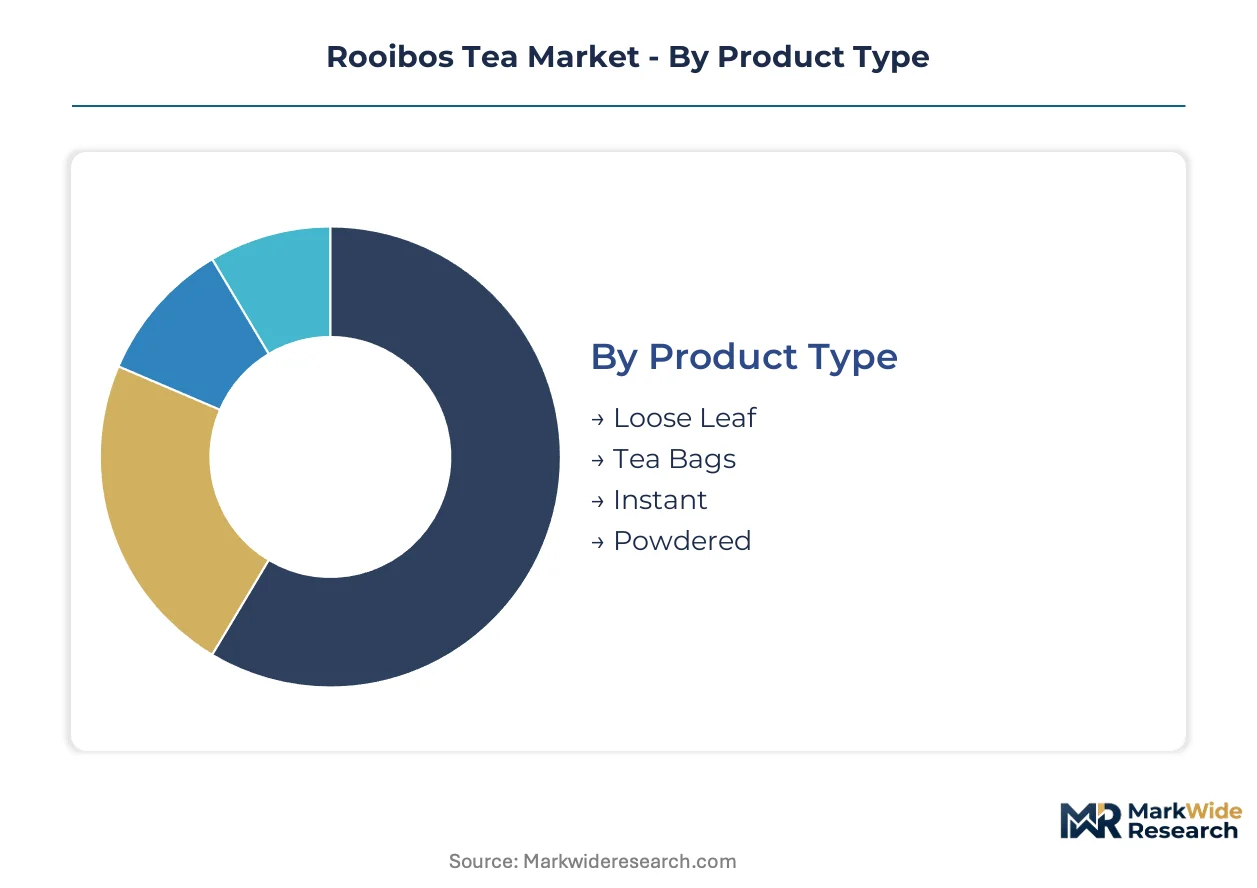
Rooibos tea segmentation reflects divergent margin capture between commodity bulk exports and certified specialty formats. Product form and distribution channel choices determine whether South African processors or Western brand owners retain value.
Product Type:
Margin pools concentrate in formats requiring minimal downstream processing by importers.
- Loose Leaf:Unprocessed oxidized needle-like leaves retain the highest polyphenol integrity. Specialty retailers in Germany and health food stores across the United States drive demand for this format as consumers prioritize brewing control and flavor intensity.
- Tea Bags:Standardized cut-leaf portions dominate household volume through supermarket channels in Europe and North America. Convenience positioning limits per-unit margins but secures recurring purchase frequency among caffeine-free beverage seekers.
- Instant:Spray-dried soluble extracts serve foodservice operators requiring rapid preparation. South African processors with spray-drying capacity capture upstream value before export.
- Powdered:Micronized leaf material targets nutraceutical formulators and functional beverage manufacturers. REACH compliance requirements for EU import packaging add certification costs that filter smaller traders from this segment.
Loose Leaf holds installed capacity. Tea Bags is rotating up the share rankings.
Distribution Channel:
Channel selection determines exposure to certification premiums and geographic indication enforcement scrutiny.
- Online Retail:Direct-to-consumer platforms enable specialty importers to bypass conventional auction structures and capture traceability premiums through farmer-direct storytelling.
- Supermarkets:Volume concentration in German and Dutch retail chains drives packaging standardization requirements under EU F-Gas Regulation mandates for sustainable materials.
- Specialty Stores:Curated assortments in Berlin and Hamburg beverage retailers emphasize origin documentation and Clanwilliam processing provenance. Staff education investments justify price premiums over mass-market alternatives.
- Health Food Stores:USDA National Organic Program certification serves as table stakes for shelf placement in United States natural products channels. Dual-certified Fair Trade and organic SKUs command the steepest price multiples.
Supermarkets anchor volume throughput. Online Retail is climbing fastest on margin per unit.
End User:
User categories split between price-sensitive institutional buyers and premium-paying individual consumers.
- Households:Repeat purchases of conventional tea bags sustain export tonnage from South Africa's Western Cape cultivation belt. Climate volatility in this Mediterranean zone introduces yield uncertainty that transmits to household shelf prices.
- Cafes:Beverage menu differentiation drives loose leaf procurement for manual brewing rituals. Berlin specialty coffee operators increasingly feature rooibos latte preparations alongside espresso-based alternatives.
- Restaurants:Foodservice distributors supply bulk formats for table service and kitchen applications. Cost pressure from chamomile and peppermint substitutes limits rooibos penetration in mid-tier dining.
- Health Enthusiasts:Aspalathin-aware consumers seek micro-encapsulated extracts and standardized polyphenol concentrates. Functional beverage startups in the United States formulate ready-to-drink products targeting this segment's antioxidant preferences.
Households represent the deepest volume base. Health Enthusiasts is expanding most quickly on per-capita spend.
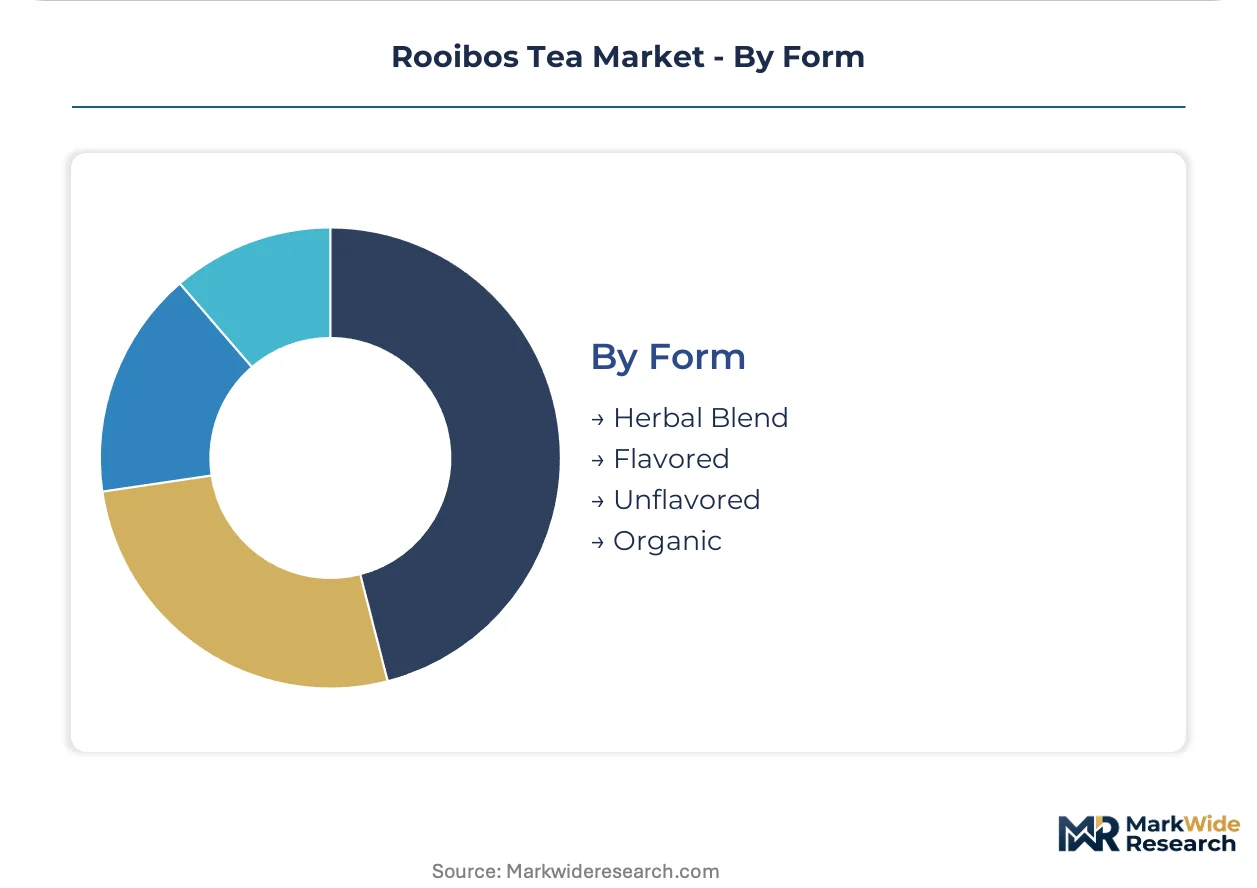
Form:
Certification status and flavor positioning create tiered price architecture across otherwise homogeneous leaf material.
- Herbal Blend:Rooibos combined with complementary botanicals such as vanilla or citrus peel expands addressable occasions. Twinings and similar European blenders leverage established grocery distribution for these SKUs.
- Flavored:Natural and artificial flavoring agents mask batch-to-batch oxidation variation. German retailers allocate dedicated shelf space for caramel and berry variants targeting younger caffeine-free converts.
- Unflavored:Conventional oxidized red rooibos and unoxidized green rooibos sustain bulk export economics. South Africa's Department of Agriculture geographic indication protections constrain unauthorized cultivation claims for this foundational category.
- Organic:Certified cultivation excluding synthetic inputs commands price premiums in North American health food retail. Clanwilliam catchment cooperatives with dual Fair Trade and organic credentials concentrate procurement attention from United States importers.
Unflavored carries the volume foundation. Organic is gaining share fastest on certification-driven procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household buyers in Germany accept steep premiums for certified organic rooibos, while price-sensitive foodservice operators in the United States gravitate toward conventional bulk formats. This elasticity divide shapes procurement patterns across major consumption centers.
United States
Functional beverage startups in California and New York formulate ready-to-drink rooibos products, bypassing traditional tea-bag channels. The USDA's National Organic Program governs certification requirements for shelf placement in health food retail. Los Angeles and San Francisco specialty grocers concentrate demand for dual-certified Fair Trade and organic SKUs.
Germany
Berlin and Hamburg beverage retailers expand shelf space for rooibos as caffeine-free migration accelerates among younger consumers. The EU's F-Gas Regulation and REACH frameworks mandate sustainable packaging standards for imported tea products. Specialty stores in Munich emphasize Clanwilliam processing provenance through staff education investments.
South Africa
The Western Cape's Cederberg cultivation belt supplies virtually all legal rooibos production under geographic indication protections. The Department of Agriculture, Land Reform and Rural Development enforces these protections against unauthorized foreign cultivation claims. Clanwilliam processing facilities anchor upstream value capture through farmer cooperative networks.
United Kingdom
London-based premium tea blenders source rooibos for vanilla and caramel variant formulations targeting supermarket channels. The UK Food Standards Agency aligns with EU packaging material standards for imported herbal products. Health food retailers in Brighton and Bristol concentrate procurement attention on certified organic tonnage.
Netherlands
Rotterdam and Amsterdam distribution hubs consolidate re-export flows to broader European retail chains. Dutch supermarket buyers enforce EU F-Gas Regulation compliance documentation from South African processors. The Randstad cluster concentrates specialty importer activity for direct-trade relationship development.
Rooibos Tea Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the rooibos value chain. Vertically integrated South African processors control upstream cultivation and primary processing, while Western brand owners dominate downstream packaging and retail distribution. The market structures around three archetypes: origin-anchored processors, established blenders with grocery scale, and specialty organic traders with certification depth. Dominant competitive moves include geographic indication compliance investments and direct-trade relationship formation that bypasses conventional auction structures.
Among South African origin-anchored processors, Rooibos Ltd. and Cape Natural Tea Products occupy positions controlling Clanwilliam catchment supply. Twinings and Numi Organic Tea represent contrasting Western archetypes—Twinings exemplifies established European grocery distribution leverage, while Numi Organic Tea sits within the certified organic direct-trade tier. Joekels Tea Packers Ltd. anchors mid-market South African processing capacity. These players illustrate how margin capture splits between upstream origin control and downstream brand equity.
| Leading Market Players |
|---|
| Rooibos Ltd. |
| Joekels Tea Packers Ltd |
| Carmién Tea |
| Cape Natural Tea Products |
| Twinings |
| The Republic of Tea |
| Harney & Sons Fine Teas |
| Numi Organic Tea |
| Tick Tock Tea |
| Others |
Value Chain & Pricing Dynamics
South Africa's geographic indication protections gate both supply qualification and price differentiation simultaneously, restricting legal rooibos cultivation to the Cederberg belt while enabling certified-origin premiums in European and North American retail channels. This regulatory architecture concentrates upstream margin capture with Clanwilliam-based processors who control farmer cooperative networks and primary oxidation facilities.
Pricing Analysis
After-sales revenue from extended supply contracts and traceability documentation drives lifetime value for South African processors serving specialty importers. Three-tier pricing structure across organic-certified premium, conventional bulk standard, and private-label economy levels stratifies the market. Cost compression in conventional unflavored tonnage is intensifying because German supermarket buyers consolidate volume with fewer suppliers. Foodservice operators in mid-tier United States restaurants exhibit highest price sensitivity, while health food retailers in Los Angeles and San Francisco accept steep organic premiums.
Supply Chain Analysis
South Africa supplies virtually all legal rooibos production, with the Western Cape's Cederberg cultivation belt anchoring global raw material flows. Primary processing draws from sandstone-derived acidic soils, Mediterranean climate-dependent growing cycles, and Clanwilliam oxidation facilities. Single-source vulnerability from climate volatility in the Western Cape generates yield uncertainty that transmits through contract structures. Distribution runs through Rotterdam and Amsterdam re-export hubs for European supermarket chains, with direct-trade channels bypassing conventional auction structures for North American specialty retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified organic cultivation acreage within the protected Cederberg geographic indication zone constrains supply expansion and amplifies returns for incumbent processors with farmer network control.
For Market Incumbents: Shield Clanwilliam processing capacity investments against climate volatility exposure by diversifying cultivation contracts across multiple Western Cape microclimates. Secure dual USDA National Organic Program and Fair Trade certification depth to defend margin position against emerging South African cooperatives. Prioritize micro-encapsulation technology licensing to capture nutraceutical extract premiums before commodity leaf exports erode. For New Entrants and Emerging Players: Differentiate on direct-trade relationship formation with Clanwilliam catchment cooperatives bypassing conventional auction structures. Target United States functional beverage startups in California seeking ready-to-drink formulation partners with traceable aspalathin content. Penetrate online retail channels through farmer-direct storytelling that commands price premiums unavailable to mass-market blenders. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across micro-encapsulation and spray-drying processing capacity as extract demand displaces bulk leaf exports. Long-term viability favors acquisition targets with dual organic-Fair Trade certification and captive farmer cooperative relationships rather than pure trading operations. Watch for inflection signals in EU F-Gas Regulation enforcement tightening that filters smaller processors from sustainable packaging compliance.| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Indication Compliance Investment | South Africa's Department of Agriculture enforcement protects authorized cultivation claims against unauthorized foreign competitors. |
| Micro-Encapsulation Capacity Expansion | Clanwilliam processors capture nutraceutical extract premiums from German and United States functional beverage formulators. |
| Direct-Trade Relationship Formation | Specialty importers bypass conventional auction structures to secure traceability premiums and quality tier separation. |
| Dual Certification Procurement | USDA National Organic Program and Fair Trade credentials command shelf placement in United States health food retail channels. |
| Sustainable Packaging Transition | EU F-Gas Regulation compliance filters supplier relationships toward processors with full chain-of-custody documentation. |
Study Parameters
A standing panel of rooibos cooperative managers, Clanwilliam processing facility operators, German specialty beverage retail buyers, and United States health food store procurement directors provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with these stakeholder roles alongside secondary validation from South African Department of Agriculture geographic indication filings, EU REACH compliance documentation, USDA National Organic Program certification records, and customs trade data tracking Western Cape export flows. Bottom-up volume modeling from farmer cooperative tonnage reports was triangulated against top-down demand estimates from European and North American retail channel audits.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented the market by product form, distribution channel, end user category, and certification status. CAGRs were derived from regression analysis of historical trade flows and elasticity-adjusted demand projections. Key forecast inputs included climate volatility scenarios for the Western Cape cultivation belt and aspalathin extraction technology adoption curves in nutraceutical applications.
Material uncertainties — drought frequency cycles in the Cederberg region, EU packaging regulation enforcement intensity, and functional beverage formulation trends — sit outside the modeled envelope. Forecasts reflect assumptions about sustained geographic indication protection and stable certification premium structures. Recalibration cycles align with material shifts in Western Cape rainfall patterns and EU F-Gas Regulation implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Asia-Pacific Tea Market
Tea
Global Tea Bag Market
Tea
Herbal Tea Market
Tea
Camellia Sinensis Leaf Extract Market
Tea
Moringa Tea Market
Tea
Butterfly Pea Flower Tea Market
Tea
Slimming Tea Market
Tea
Green Tea Leaves Market
Tea
Detox Tea Market
Tea
Tea Infuser Market
Tea
Asia-Pacific Green Tea Market
Tea
APAC RTD Tea Market
Tea
Out of Home Tea Market
Tea
North America Ready-To-Drink Tea Market
Tea
Black Tea Market
Tea
Asia-Pacific Ready to Drink Tea Market