
 Beauty Drinks Market | 2026-2036
Beauty Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Beauty Drinks Market Analysis
Nutraceutical formulation expertise is bifurcating the competitive landscape between pharmaceutical-grade manufacturers and lifestyle-brand entrants. AmorePacific Corp leverages decades of fermented-ingredient R&D to anchor its premium positioning across Asian markets. Shiseido Co. Ltd competes through integrated beauty ecosystems that merge topical and ingestible product lines. Nestlé SA sustains global manufacturing scale while navigating divergent regulatory thresholds across its operating regions.
Beauty drinks constitute ingestible liquid formulations containing bioactive compounds—collagen peptides, hyaluronic acid, ceramides, or botanical extracts—typically delivered in single-serve bottles or powder sachets reconstituted with water, designed to improve skin elasticity, hydration, or hair and nail integrity from within. Collagen-based products dominate current revenue pools due to established clinical backing and consumer familiarity, while activated charcoal formulations occupy a smaller, novelty-driven niche with narrower repeat-purchase rates. Skin hydration applications lead absolute volume, though anti-aging positioning commands premium pricing and stronger margin retention across specialty retail channels.
FDA oversight of dietary supplement labeling under DSHEA, EFSA health-claim authorization requirements in Europe, and Japan's FOSHU (Foods for Specified Health Uses) framework collectively determine which functional claims reach shelf-stable packaging and which require reformulation or regional adaptation. Stakeholders must monitor evolving substantiation standards for collagen bioavailability claims, as regulatory divergence between Japan's Ministry of Health, Labour and Welfare and EFSA's evolving guidance on beauty-related health claims will increasingly dictate where R&D investment flows and which formulations achieve cross-border commercialization.
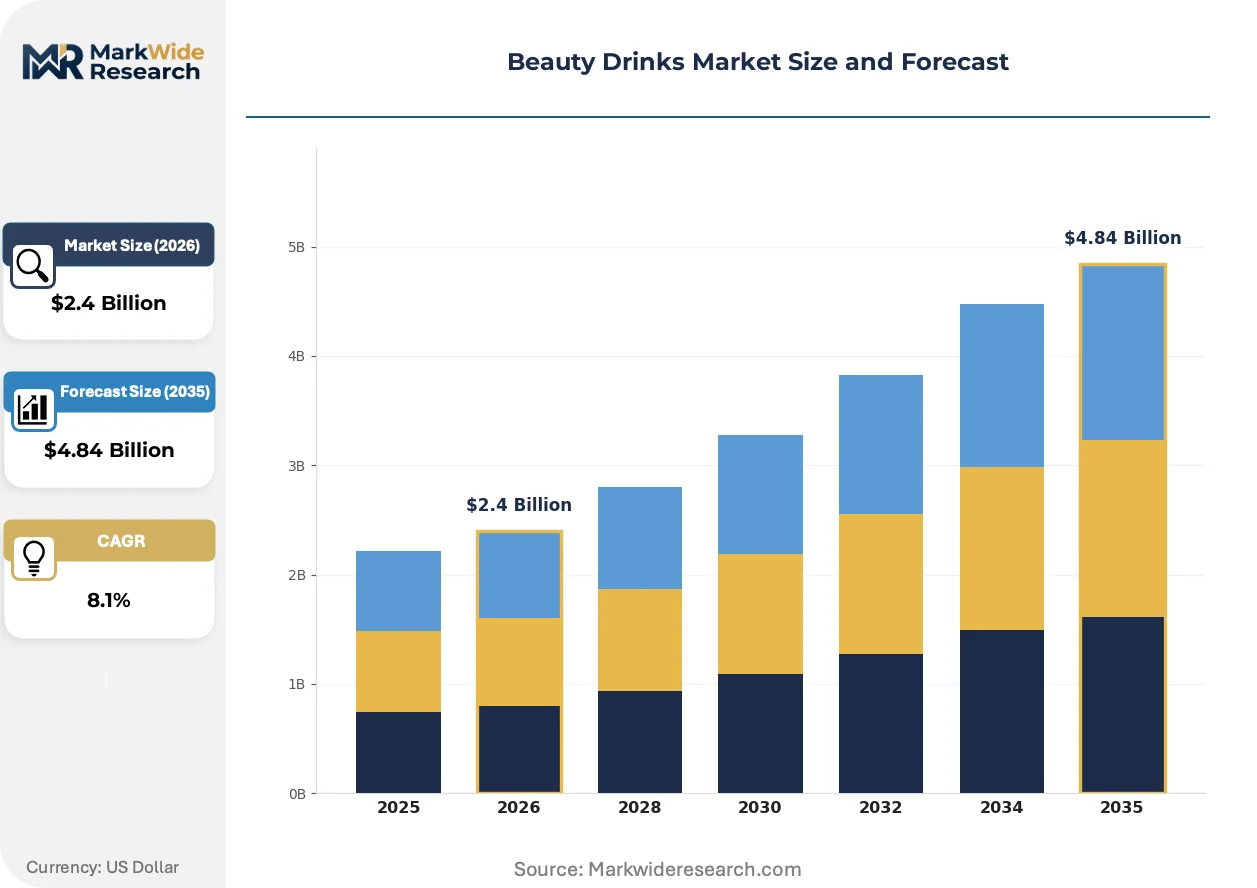
Market Dynamics
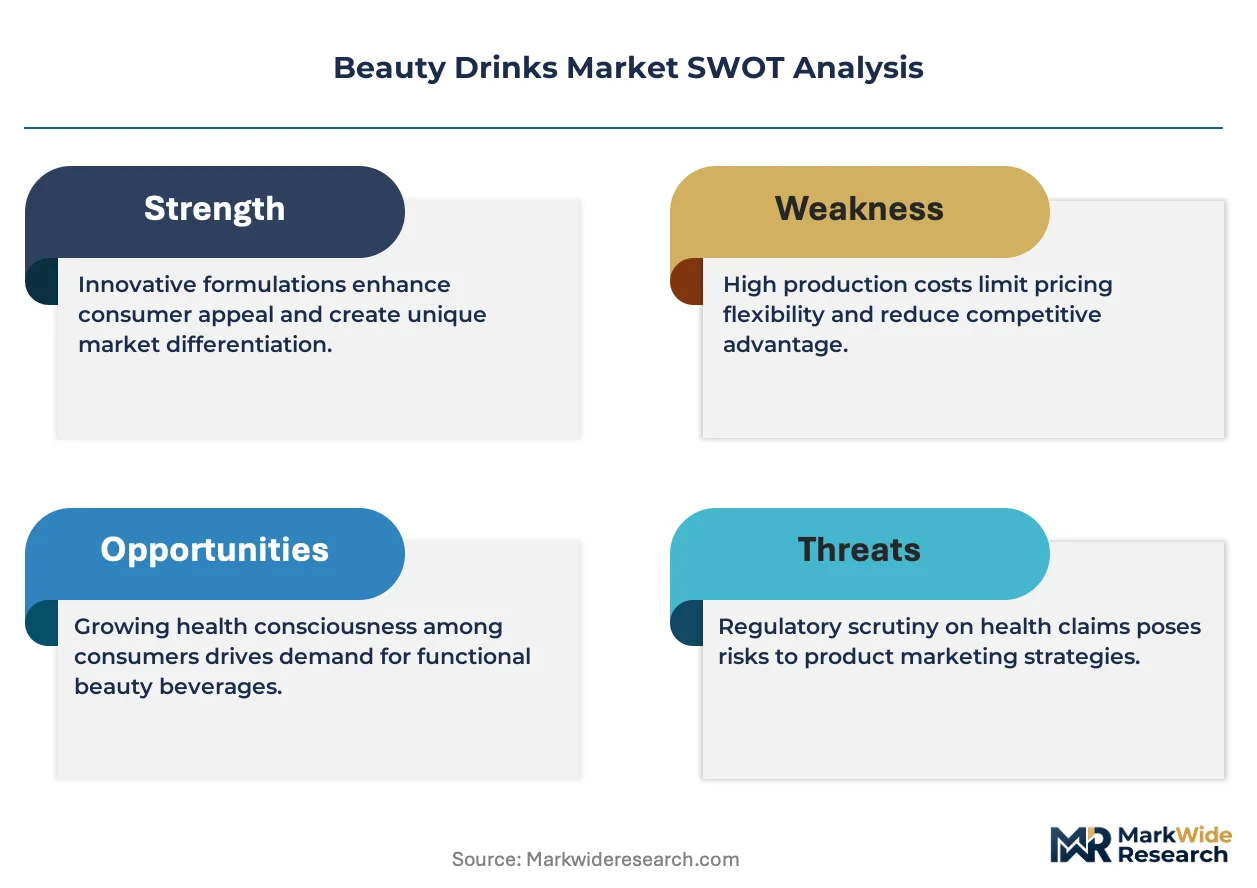
Regulatory divergence between Japan's FOSHU framework and EFSA's evolving health-claim substantiation standards is fragmenting formulation strategies and forcing manufacturers to maintain parallel R&D streams for cross-border commercialization.
Growth Catalysts
- Japan's FOSHU authorization pathway:The Ministry of Health, Labour and Welfare's structured approval process for ingestible skincare claims provides regulatory clarity that accelerates premium product launches in Tokyo and Osaka wellness corridors.
- Collagen peptide bioavailability advances:Hydrolyzed marine collagen processing improvements are expanding the addressable consumer base beyond traditional demographies into men's grooming and prenatal wellness segments.
- Professional channel penetration:South Korean med-spa networks and dermatology clinic chains are integrating beauty beverages into post-treatment protocols, creating institutional demand pull.
Market Restraints
- Marine collagen supply concentration:Wild-caught fish skin and scale sourcing clusters heavily in Southeast Asian coastal processing zones, exposing margins to climate-induced catch volatility.
- EFSA health-claim friction:The European regulator's stringent substantiation requirements for beauty-related claims block direct skin-hydration messaging on shelf-stable packaging, forcing vague positioning.
- Hyaluronic acid cost structure:Fermentation-derived sodium hyaluronate input costs fluctuate with pharmaceutical-grade demand competition from dermal filler manufacturers.
Strategic Opportunities
- Men's ingestible grooming:Underpenetrated male demographics in Germany and the UK present whitespace for collagen-plus-botanical formulations targeting hair density and stress-related skin fatigue.
- Direct-to-clinic distribution:Bypassing traditional retail through aesthetic practitioner networks captures higher margins and enables personalized regimen bundling with topical protocols.
- EU Green Deal alignment:Circular packaging mandates and carbon-labeling incentives favor brands investing in algae-derived collagen alternatives and refillable glass bottle systems.
Industry Challenges
- Cross-border formulation complexity:Divergent permissible ingredient lists between FDA DSHEA oversight, EFSA additive restrictions, and Japan's positive-list system force SKU proliferation and inventory segmentation.
- Clinical substantiation talent scarcity:The shallow pool of dermatology-trained formulation scientists capable of designing publishable bioavailability studies constrains credible claim development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beauty Drinks Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.84 Billion |
| CAGR (2026 – 2036) | 8.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagen, Herbal, Vitamin, Activated Charcoal Application: Skin Hydration, Anti-Aging, Weight Management, Beauty Enhancement Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Shops Target Demographic: Millennials, Gen Z, Adults, Seniors |
| Companies Covered | Kinohimitsu, AmorePacific Corp, Nestlé SA, Hangzhou Nutrition Biotechnology Co. Ltd, Vital Proteins LLC, Shiseido Co. Ltd, Lacka Foods Ltd, Big Quark, Sappe Public Company Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beauty Drinks Market Emerging Trajectories
Active ingredient delivery systems and regulatory positioning strategies are bifurcating competitive approaches between pharmaceutical-grade efficacy claims and lifestyle-brand accessibility.
Liposomal encapsulation technology for hyaluronic acid and ceramide compounds is miniaturizing molecular structures to enhance intestinal absorption rates. Premium beauty drink manufacturers in Japan and South Korea are adopting these systems fastest, compressing the efficacy gap between topical serums and ingestible formats. The technology is miniaturizing dosage requirements while maintaining bioactive concentration, enabling smaller serving sizes that reduce packaging costs and shipping weights.
EFSA's ongoing revision of beauty-related health-claim guidance is forcing European manufacturers to pivot from direct skin-benefit messaging toward broader wellness positioning. The industrial consequence is a wave of reformulation toward multi-functional blends combining adaptogens with collagen rather than single-ingredient SKUs. Anti-aging positioned products face the steepest compliance burden, with several brands withdrawing specific elasticity claims pending new substantiation protocols.
Subscription-based replenishment models are displacing traditional retail discovery for repeat-purchase consumers. Direct-to-consumer channels in urban Japan and South Korea now capture significant volume from convenience store incumbents, with personalization algorithms driving flavor and ingredient customization. This channel rotation is most visible among millennial and Generation Z demographics in Seoul and Tokyo, where mobile-first purchasing and influencer-curated regimen bundling dominate acquisition.
Beauty Drinks Market Segmentation
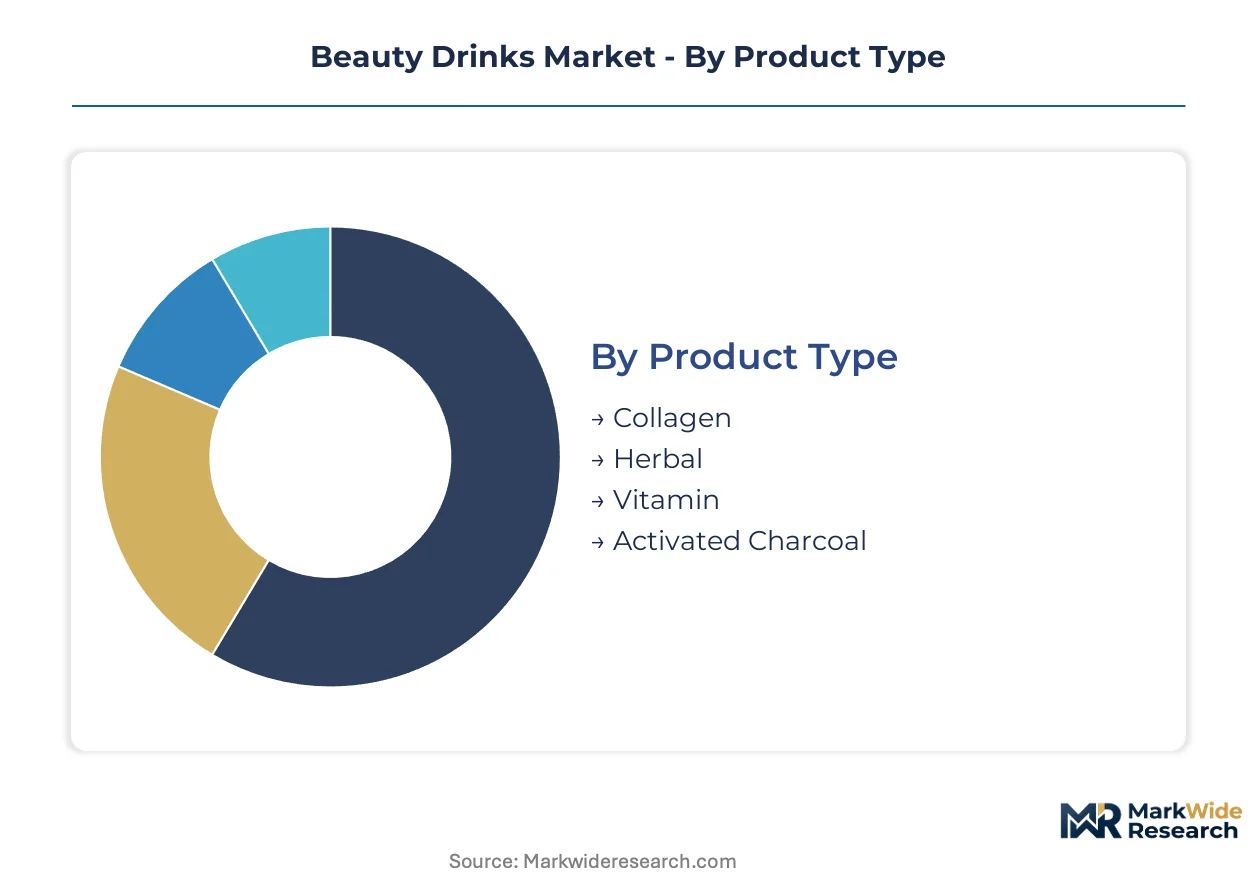
Segmentation in beauty drinks reveals where formulation investment concentrates and which channels capture repeat-purchase loyalty. Distinct regulatory tolerances across geographies force parallel SKU strategies even for single brands.
Product Type:
Collagen-based formulations face the most intense substitution pressure from emerging ceramide and postbiotic alternatives, while herbal and vitamin blends compete with established supplement categories outside beauty-specific positioning.
- Collagen:Hydrolyzed marine and bovine peptide concentrates deliver the clinical substantiation base that supports premium pricing in Japanese FOSHU-authorized products. Demand clusters in South Korean med-spa networks and Tokyo's urban wellness corridors where post-treatment protocols institutionalize ingestible skincare routines.
- Herbal:Fermented botanical extracts and adaptogenic root formulations leverage traditional medicine credibility, particularly in markets with established TCM or Ayurveda consumer familiarity. EFSA's restrictive stance on botanical health claims forces European herbal SKUs toward vague wellness positioning rather than specific beauty outcomes.
- Vitamin:Biotin and vitamin C complexes target nail integrity and collagen synthesis support with lower price points and broader retail accessibility.
- Activated Charcoal:Detox-positioned formulations occupy a novelty-driven niche with narrower repeat-purchase rates and limited clinical backing for beauty-specific claims.
Collagen anchors the volume base while herbal formulations gain share at the steepest rate as consumers seek multi-functional adaptogenic benefits beyond single-ingredient positioning.
Application:
Cost tier stratification separates premium anti-aging SKUs from mass-market hydration products, with weight management applications competing against established functional beverage categories.
- Skin Hydration:Hyaluronic acid and ceramide blends lead absolute volume through daily-consumption positioning and accessible price points. Japanese consumers in Osaka and Tokyo wellness corridors drive institutional demand for clinically substantiated moisture-retention claims.
- Anti-Aging:Elasticity and wrinkle-reduction formulations command premium pricing and stronger margin retention across specialty retail channels. EFSA's evolving substantiation requirements force European anti-aging brands to reformulate toward multi-functional adaptogen blends or withdraw specific claims pending new protocols.
- Weight Management:Meal-replacement and appetite-suppression positioning competes with established protein beverage and diet drink categories with limited beauty-specific differentiation.
- Beauty Enhancement:Hair density and nail integrity formulations target underpenetrated male demographics in Germany and the UK with collagen-plus-botanical combinations.
Skin hydration captures the broadest consumer base while anti-aging commands the highest per-unit margins despite regulatory compliance burdens.
Distribution Channel:
Channel concentration determines margin structure and claim permissibility, with professional networks enabling personalized regimen bundling that mass retail cannot replicate.
- Online Retail:Subscription-based replenishment models displace traditional discovery for repeat-purchase consumers, with personalization algorithms driving flavor and ingredient customization. Mobile-first purchasing dominates acquisition among millennial and Generation Z demographics in Seoul and Tokyo.
- Supermarkets:Mass-market hydration products achieve scale through convenience store incumbents in Japan, though shelf-space competition from established beverage categories constrains beauty-specific SKU expansion.
- Specialty Stores:Premium positioning and educated staff enable complex ingredient storytelling for anti-aging and herbal formulations.
- Health Shops:Pharmacist-adjacent credibility supports higher price points for clinically positioned collagen and vitamin blends.
Online retail expands most quickly through direct-to-consumer personalization while specialty stores defend the highest margin tiers.
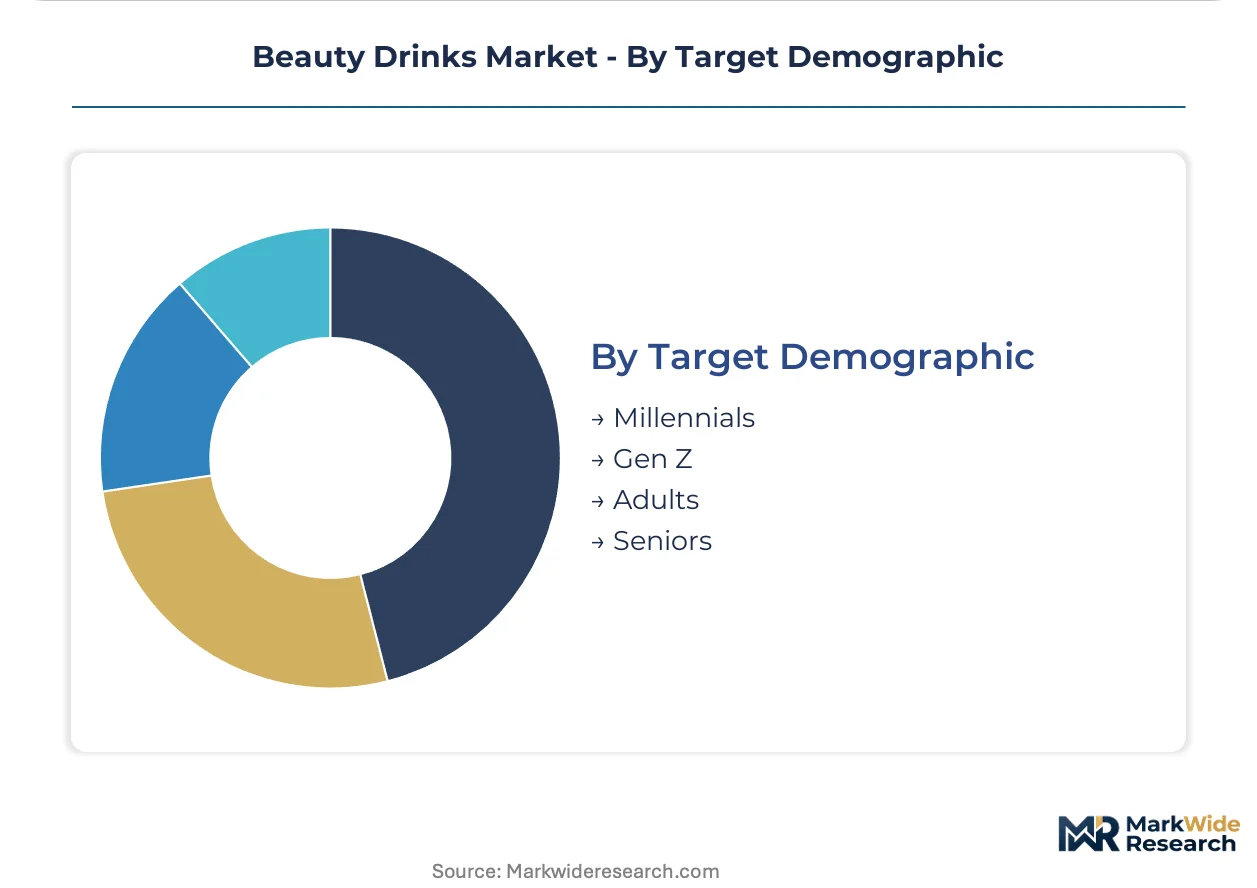
Target Demographic:
Maturity gradients separate established senior consumers from emerging Generation Z entrants, with each cohort demanding distinct formulation formats and channel experiences.
- Millennials:Regimen-conscious consumers prioritize ingestible-topical integration and influencer-curated bundling, driving volume in Seoul and Tokyo direct-to-consumer channels.
- Gen Z:Sustainability-aligned packaging preferences and TikTok-discovered novelty formats favor smaller brands with authentic ingredient sourcing narratives.
- Adults:Broad mid-market positioning captures routine-driven consumption with moderate price sensitivity and established channel loyalty.
- Seniors:Japan's aging population in urban wellness corridors prioritizes FOSHU-authorized claims and pharmacist-recommended formulations with clinical substantiation.
Seniors anchor premium pricing power while Gen Z drives packaging innovation and channel rotation toward mobile-first discovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Japanese urban wellness corridors while mass-market volume expansion accelerates in Southeast Asian processing hubs. This asymmetry reflects divergent regulatory clarity and channel maturity across geographies.
Japan
Tokyo and Osaka wellness corridors institutionalize ingestible skincare through pharmacist-recommended FOSHU-authorized formulations. The Ministry of Health, Labour and Welfare's structured approval pathway provides regulatory certainty that accelerates premium product launches. Aging consumers in Kanto and Kansai regions prioritize clinically substantiated collagen bioavailability claims with established repeat-purchase loyalty.
South Korea
Seoul's med-spa networks and dermatology clinic chains integrate beauty beverages into post-treatment protocols, creating institutional demand pull. The MFDS maintains positive-list oversight of functional food additives while allowing direct skin-benefit messaging for substantiated claims. Busan-Ulsan coastal processing zones concentrate marine collagen extraction facilities serving domestic brands and export markets.
United States
Men's grooming segments and prenatal wellness demographics expand collagen peptide adoption beyond traditional female consumer bases. FDA DSHEA oversight permits structure-function claims while blocking disease-prevention messaging, forcing nuanced positioning. California and New York Metro areas anchor direct-to-consumer subscription growth with influencer-curated regimen bundling.
Germany
Underpenetrated male demographics present whitespace for collagen-plus-botanical formulations targeting hair density and stress-related skin fatigue. EFSA's stringent health-claim substantiation requirements block direct skin-hydration messaging, forcing vague wellness positioning. Bavaria and North Rhine-Westphalia concentrate specialty retail channels where educated staff enable complex ingredient storytelling.
Thailand
Bangkok and coastal processing zones cluster wild-caught fish skin and scale sourcing for marine collagen extraction. Climate-induced catch volatility exposes margins to supply disruption while domestic consumption grows through convenience store channels. The Thai FDA's evolving functional food framework lags Japanese regulatory clarity, constraining premium claim development.
Beauty Drinks Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with pharmaceutical-grade manufacturers commanding premium pricing and lifestyle-brand entrants capturing volume through accessible positioning. The market structures around three tiers: fermented-ingredient specialists with decades of R&D depth, integrated beauty ecosystems merging topical and ingestible lines, and global manufacturing scale operators navigating divergent regulatory thresholds. Dominant competitive moves include direct-to-clinic distribution partnerships and algae-derived collagen alternative development aligned with EU Green Deal circular packaging mandates.
Within the fermented-specialist tier, AmorePacific Corp and Shiseido Co. Ltd exemplify integrated beauty ecosystem strategies that merge topical and ingestible product lines. Nestlé SA occupies a position as the global manufacturing scale anchor navigating divergent regulatory thresholds across operating regions. Kinohimitsu represents the direct-to-consumer replenishment model with subscription-based personalization algorithms.
| Leading Market Players |
|---|
| Kinohimitsu |
| AmorePacific Corp |
| Nestlé SA |
| Hangzhou Nutrition Biotechnology Co. Ltd |
| Vital Proteins LLC |
| Shiseido Co. Ltd |
| Lacka Foods Ltd |
| Big Quark |
| Sappe Public Company Ltd |
| Others |
Supply Flow & Price Mechanics
Japan's FOSHU authorization pathway gates both supplier qualification and price differentiation simultaneously, as only Ministry of Health, Labour and Welfare-certified manufacturers command premium positioning in Tokyo and Osaka wellness corridors while uncertified competitors remain trapped in commodity tiers.
Pricing Analysis
Configured-to-order pricing through direct-to-clinic distribution commands substantial premiums over standard retail SKUs. Three-tier pricing structure across premium, standard, and economy levels separates FOSHU-authorized formulations from mass-market hydration products and novelty-positioned activated charcoal entries. Price differentiation stems from certification grade and vertical integration into marine collagen extraction. Cost compression in economy tiers is intensifying because wild-caught sourcing volatility transfers downstream. Male grooming segments in Germany and the UK exhibit lowest price sensitivity, while convenience store channels in Thailand face highest elasticity.
Supply Chain Analysis
Thailand and Vietnam anchor wild-caught fish skin and scale processing for marine collagen peptide extraction. Indonesia and the Philippines supplement coastal processing capacity with scale finishing operations. Raw material dependencies center on tropical catch volumes, hydrolysis enzyme inputs, and pharmaceutical-grade sodium hyaluronate from fermentation facilities. Single-source vulnerability concentrates in Bangkok-Ulsan shipping lanes exposed to climate disruption. Distribution runs through professional channel networks in Seoul and direct-to-consumer platforms in Tokyo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's FOSHU framework revision constitutes a high-growth disruption, as streamlined approval pathways for bioavailability claims will accelerate premium product launches and compress competitive response windows.
For Market Incumbents: Fortify regulatory compliance infrastructure ahead of evolving EFSA substantiation protocols that threaten existing anti-aging claims. Deepen backward integration into algae-derived collagen alternatives to deflect marine sourcing volatility. Capture institutional channel control through exclusive med-spa distribution partnerships in South Korea. For New Entrants and Emerging Players: MFDS fast-track authorization for substantiated skin-benefit claims unlocks whitespace in Seoul's dermatology clinic networks. Target underpenetrated male demographics in Germany with collagen-plus-botanical formulations for hair density. Deploy influencer-curated regimen bundling as the primary go-to-market angle. For Investors and Strategic Acquirers: EFSA's evolving health-claim guidance reshapes the acquisition landscape toward multi-functional adaptogen blend capabilities. Long-term viability favors vertically integrated specialists with captive fermentation capacity and cross-border regulatory expertise. Monitor FOSHU approval velocity as the signal indicating premium pricing power concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Algae-Derived Collateral Development | EU Green Deal alignment secures circular packaging credentials for premium positioning. |
| Direct-to-Clinic Distribution Expansion | Seoul med-spa networks capture higher margins through personalized regimen bundling. |
| Liposomal Encapsulation Scale-Up | Japanese manufacturers compress efficacy gaps between topical and ingestible formats. |
| Men's Grooming Line Extension | German and UK male demographics present whitespace for hair-density formulations. |
| Subscription Personalization Investment | Tokyo and Seoul mobile-first channels displace convenience store incumbents. |
Methodological Framework
Operator-level perspectives from brand managers at fermented-ingredient specialists, category buyers at Japanese pharmacy chains, regulatory affairs leads navigating EFSA protocols, and procurement directors at marine collagen processors anchored the qualitative base. Secondary validation drew from Ministry of Health, Labour and Welfare FOSHU filings, MFDS functional food registrations, EFSA health-claim opinions, and customs trade data on hydrolyzed peptide imports. Bottom-up volume modeling and top-down value reconciliation ensured triangulation integrity.
Sensitivity analysis tested input assumptions across the projection horizon. Segmentation dimensions spanned product type, application, distribution channel, and target demographic with regional regulatory cluster overlays. CAGRs derived from fitted growth curves applied to base-year estimates, incorporating collagen peptide bioavailability advances and professional channel penetration rates as industry-specific demand drivers.
Underlying assumptions cover sustained FOSHU authorization velocity and stable marine catch volumes, with deviation risk concentrated in climate-induced supply disruption and EFSA claim substantiation stringency. Recalibration cycles align with material shifts in regulatory guidance and coastal processing capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Soluble Beta Glucan Market
Functional Food and Beverage
Europe Health Drinks Market
Functional Food and Beverage
Vitamin Functional Water Market
Functional Food and Beverage
Natural Functional Food Market
Functional Food and Beverage
South America Functional Beverages Market
Functional Food and Beverage
Marine Functional Ingredients Market
Functional Food and Beverage
Functional Dairy Products Market
Functional Food and Beverage
Mediterranean Healthy-Aging Beverage Ingredients Market
Functional Food and Beverage
Global Functional Drinks Market
Functional Food and Beverage
Grape Skin–Carob Synergy Antioxidant Systems Market
Functional Food and Beverage
Global Low Calorie Food Market
Functional Food and Beverage
Europe Prebiotics Market
Functional Food and Beverage
Low Fat Protein Market
Functional Food and Beverage
Low-Fat and Low Cholesterol Diet Market
Functional Food and Beverage
Health and Wellness Foods Market
Functional Food and Beverage
Flavored and Functional Water Market