
 Hibiscus Extract Market | 2026-2036
Hibiscus Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Hibiscus Extract Market Outlook
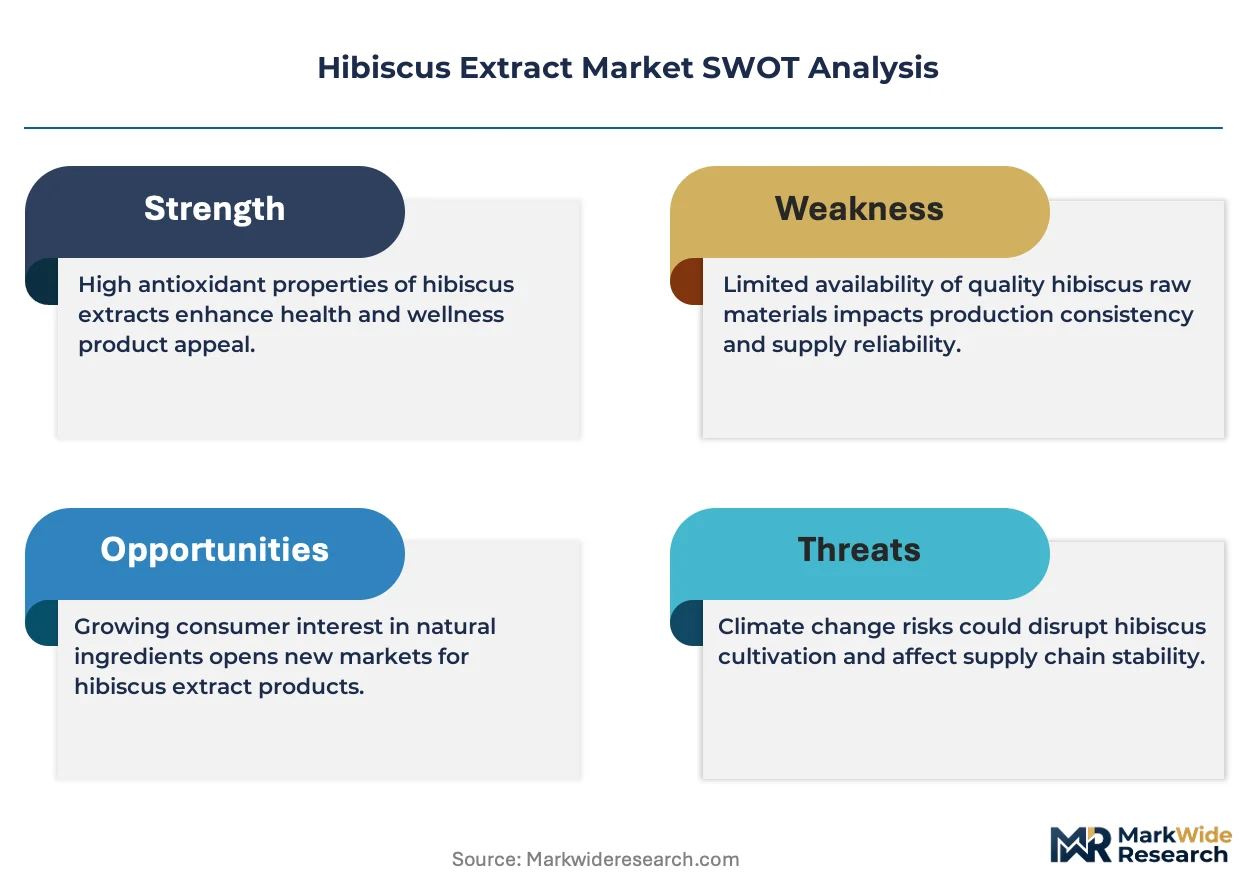
Functional beverage formulators are gaining share over traditional tea and juice processors as the demand pool is bifurcating toward clinically positioned drinkable wellness products. Givaudan SA leverages its flavor science infrastructure to supply standardized hibiscus extracts for beverage fortification. Wild Hibiscus Flower Co. anchors its position through backward integration into Australian and Pacific Island cultivation networks. Indena S.p.A. differentiates via phyto-complex extraction technologies that preserve anthocyanin stability.
Hibiscus extract comprises dried calyces of Hibiscus sabdariffa L. subjected to aqueous or hydroalcoholic extraction, yielding anthocyanins (primarily delphinidin-3-sambubioside and cyanidin-3-sambubioside), organic acids, and flavonoids at standardized concentrations for industrial use. Powder formats dominate volume throughput due to superior shelf stability and ease of incorporation into dry beverage premixes and supplement tablets. Pharmaceutical-grade extracts command premium positioning as cardioprotective and antihypertensive clinical validation accumulates in peer-reviewed literature, while cosmetic-grade variants gain traction in dermocosmetic formulations targeting antioxidant protection.
ISO 22000 and HACCP frameworks govern food-grade extract safety protocols, while FDA GRAS self-affirmation and EFSA Novel Food assessments determine market access for new hibiscus-derived ingredients in the United States and European Union respectively. India's FSSAI and CDSCO are tightening botanical extract purity standards, affecting export eligibility for suppliers targeting South Asian pharmaceutical and nutraceutical channels. Stakeholders must monitor evolving pharmacopeial monograph harmonization between USP, EP, and IP standards to preempt formulation reformulation costs and registration delays.
Market Dynamics
Functional beverage formulators are pulling hibiscus extract procurement away from traditional tea processors, creating a bifurcated demand structure where clinical positioning and standardized anthocyanin content determine supplier selection.
Growth Catalysts
- EFSA Novel Food assessments:Clarified safety pathways for hibiscus-derived ingredients accelerate new entrant market access across European Union member states.
- Cardioprotective supplement applications:Accumulating peer-reviewed clinical validation for antihypertensive properties drives pharmaceutical-grade extract procurement from German formulators.
- Aqueous extraction standardization:Advances in hydroalcoholic processing yield higher delphinidin-3-sambubioside retention, improving color stability for natural beverage fortification.
Market Restraints
- Raw material concentration:Australian and Pacific Island cultivation networks dominate calyx supply, creating geographic single-source vulnerability for backward-integrated processors.
- Input cost volatility:Climate-sensitive Hibiscus sabdariffa yields fluctuate with monsoon patterns, compressing margin predictability for aqueous extraction operators.
- Regulatory friction:FDA GRAS self-affirmation requirements impose documentation burdens on novel extract variants targeting US food and beverage channels.
Strategic Opportunities
- Dermocosmetic antioxidant protection:Cosmetic-grade extract variants targeting topical formulations remain underpenetrated relative to ingestible applications.
- India FSSAI tightening:Stricter botanical extract purity standards create first-mover advantage for suppliers achieving CDSCO pharmaceutical-grade certification ahead of competitors.
- ISO 22000 harmonization:Convergence between USP, EP, and IP pharmacopeial monographs reduces reformulation costs for multi-territory product registrations.
Industry Challenges
- Anthocyanin stability expertise:Shortage of phytochemistry specialists capable of preserving cyanidin-3-sambubioside through shelf-stable powder processing constrains quality-scaled output.
- HACCP certification timelines:Extended food-grade safety protocol audits delay commercial launch schedules for new extraction facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hibiscus Extract Market |
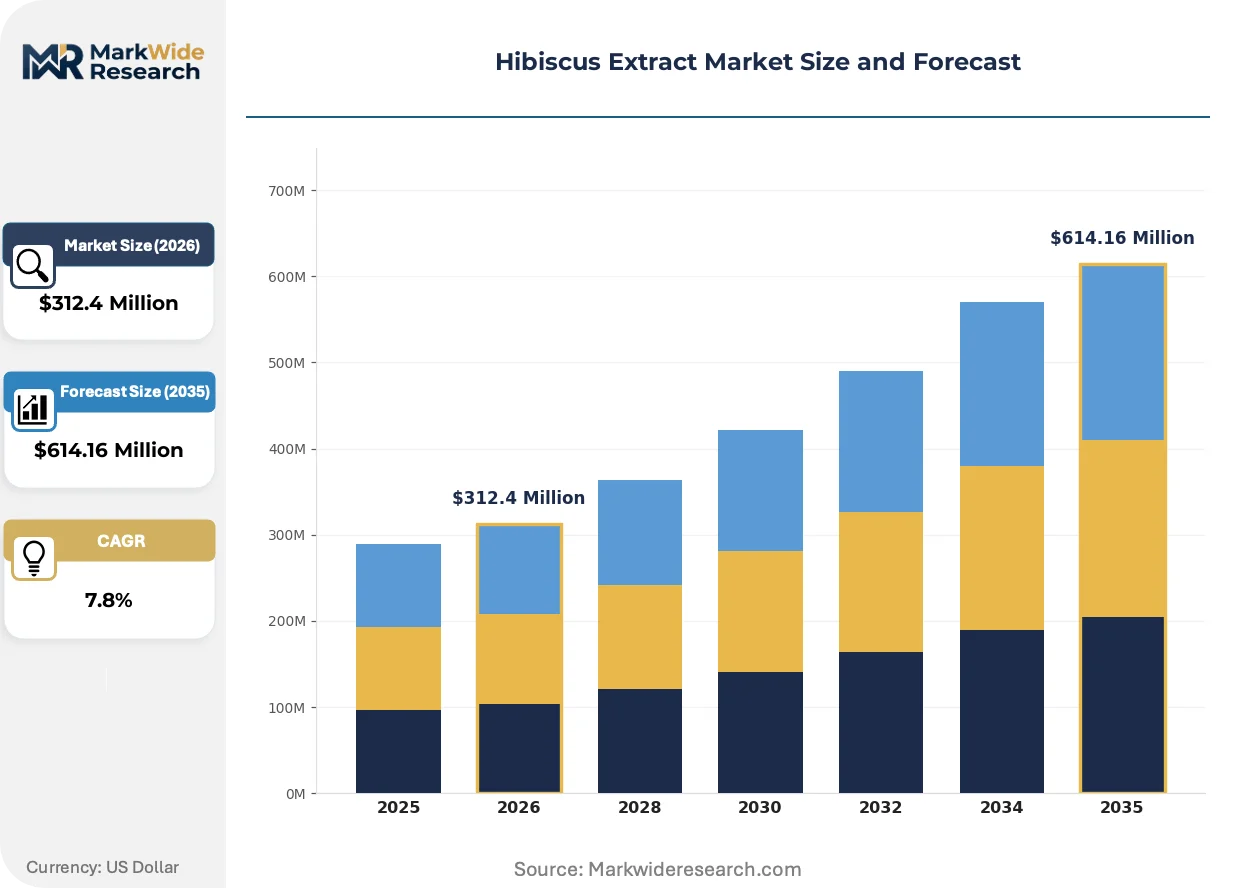
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $614.16 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Extract Application: Food & Beverage, Cosmetics, Pharmaceuticals, Supplements Grade: Food Grade, Cosmetic Grade, Pharmaceutical Grade, Industrial Grade Distribution Channel: Online, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | Givaudan SA, Wild Hibiscus Flower Co., Merck Group, OBG Pharmaceuticals Ltd, Fengchen Group, Hibiscus Bio-Extracts Pvt Ltd, Naturex, Indena S.p.A, Sabinsa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hibiscus Extract Market Strategic Shifts
Extraction technology convergence with precision fermentation and synthetic biology is compressing traditional botanical supply chains while regulatory science advances redefine permissible health claims.
Phyto-complex extraction technology is miniaturizing. Indena S.p.A. and comparable specialists deploy membrane filtration and low-temperature concentration systems that preserve anthocyanin molecular integrity. Pharmaceutical and nutraceutical formulators in Germany and Switzerland accelerate adoption of these standardized extracts for cardioprotective applications. The technology is miniaturizing batch-scale operations, enabling regional processing hubs to challenge centralized extraction facilities.
REACH registration requirements for novel botanical substances are tightening substance characterization obligations. ECHA mandates push extract suppliers toward comprehensive constituent profiling beyond marker compound quantification. Cosmetic and food-grade hibiscus extract importers into the European Union face accelerated compliance timelines, driving investment in analytical chemistry capabilities.
Buyers are consolidating procurement around certified-sustainable supply chains. Beverage manufacturers in Nordic markets now require organic cultivation documentation and carbon footprint disclosure from Australian and Thai calyx suppliers. This certification-driven preference shift displaces spot-market purchasing, locking in multi-year offtake agreements with backward-integrated processors.
Hibiscus Extract Market Segmentation
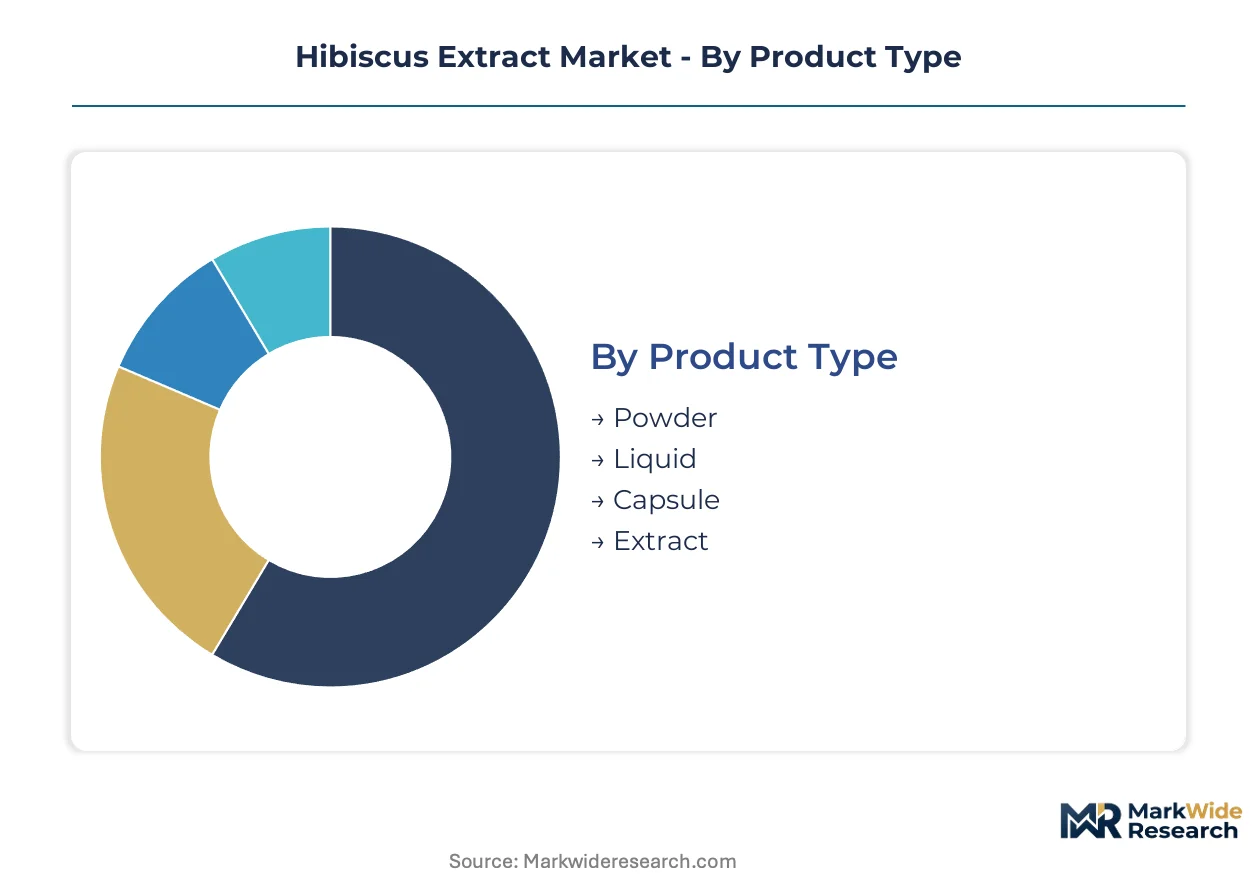
Procurement patterns in the hibiscus extract market bifurcate sharply between standardized industrial inputs and certified-grade variants for regulated applications. Supplier selection hinges on pharmacopeial alignment and end-use compliance requirements rather than commodity pricing alone.
Product Type:
Regulatory differentiation separates shelf-stable formats from temperature-sensitive alternatives, with powder and liquid variants subject to divergent HACCP and ISO 22000 validation protocols.
- Powder:Spray-dried or freeze-dried calyx derivatives with standardized anthocyanin concentrations between 5-25%. Dry beverage premix manufacturers in Germany and supplement tablet producers prioritize this format for logistical efficiency and 24-month stability windows.
- Liquid:Aqueous or hydroalcoholic concentrates requiring cold-chain integrity. Functional beverage formulators in Nordic markets source liquid extracts for direct fortification, though EFSA Novel Food assessments impose stricter documentation burdens on aqueous variants.
- Capsule:Encapsulated powder or oil-based formulations targeting direct-to-consumer nutraceutical channels.
- Extract:Unstandardized bulk preparations for downstream processing by ingredient houses.
Powder handles the majority of throughput; liquid is the fastest mover on share.
Application:
Cost tier stratification concentrates investment in clinical validation, with pharmaceutical and supplement applications commanding fivefold extraction precision over commodity food uses.
- Food & Beverage:Natural colorant and flavor fortification in ready-to-drink wellness products. EFSA and FDA GRAS pathways determine market access for novel hibiscus-derived ingredients in this segment.
- Pharmaceuticals:Cardioprotective and antihypertensive formulations requiring USP or EP monograph compliance. German formulators drive procurement of pharmaceutical-grade extracts with validated delphinidin-3-sambubioside content.
- Supplements:Standardized anthocyanin capsules and tablets for cardiovascular wellness positioning.
- Cosmetics:Dermocosmetic antioxidant applications with REACH-registered substance characterization.
Food & Beverage anchors volume demand; pharmaceuticals is climbing the fastest on margin contribution.
Grade:
Customer type segmentation separates institutional procurement from retail-facing channels, with pharmaceutical-grade extracts requiring CDSCO, FDA, or EMA-aligned manufacturing audits.
- Pharmaceutical Grade:GMP-certified extraction with full constituent profiling and heavy metal testing. Indian CDSCO and USP standards govern export eligibility for suppliers targeting South Asian and North American pharmaceutical channels.
- Food Grade:ISO 22000 and HACCP-compliant processing for beverage and ingredient applications. This grade captures the widest geographic supplier base.
- Cosmetic Grade:REACH-registered variants with dermal safety documentation for EU cosmetic regulation compliance.
- Industrial Grade:Unstandardized bulk material for non-ingestible processing.
Food Grade maintains the broadest supplier participation; pharmaceutical Grade is expanding most quickly on certification premiums.
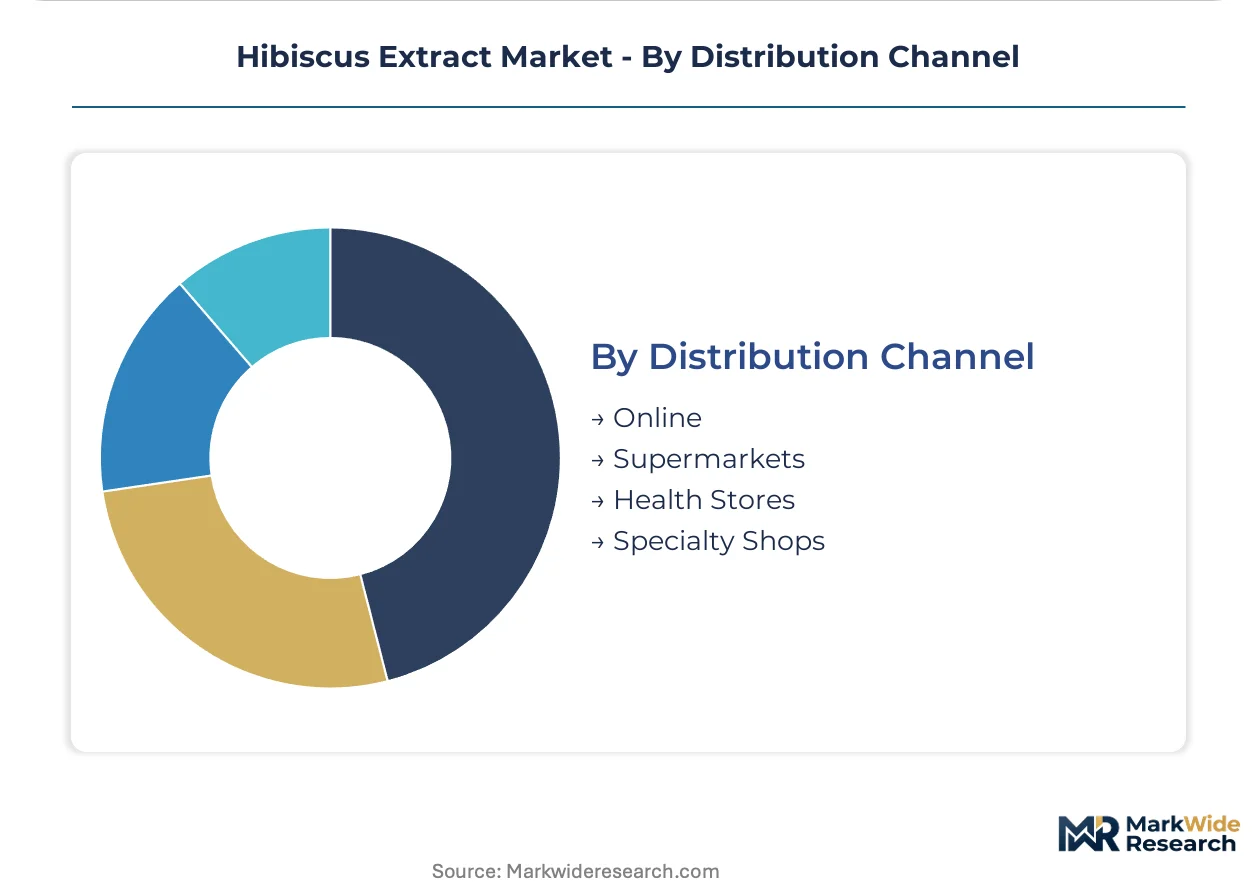
Distribution Channel:
Supply concentration in Australian and Thai cultivation networks shapes channel accessibility, with backward-integrated processors locking multi-year offtake agreements that displace spot-market purchasing.
- Online:Direct-to-consumer and B2B ingredient platforms. Supplement brands and small-batch beverage startups source standardized extracts through certified-sustainable digital procurement channels.
- Health Stores:Branded capsule and powder retail for wellness-positioned consumers.
- Supermarkets:Mass-market beverage and functional food placement.
- Specialty Shops:Premium organic and single-origin positioning for culinary and cosmetic applications.
Online channels are gaining procurement share fastest; health stores retain the highest margin extraction for finished goods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian calyx cultivation networks export standardized extracts to German pharmaceutical formulators and Nordic beverage manufacturers, establishing a transhemispheric trade corridor that concentrates procurement around certified-sustainable supply chains.
Germany
Pharmaceutical-grade extract procurement dominates regional demand as cardioprotective supplement formulators in Frankfurt and Mannheim validate antihypertensive applications through clinical trials. EFSA Novel Food assessments govern ingredient market access for novel hibiscus-derived substances. Bavarian extraction facilities specialize in hydroalcoholic processing with membrane filtration systems that preserve delphinidin-3-sambubioside stability.
United States
Functional beverage manufacturers in California and Colorado accelerate procurement of natural colorants and flavor fortification agents for wellness-positioned drinkable products. FDA GRAS self-affirmation requirements impose documentation burdens on extract variants targeting food and beverage channels. Pacific Northwest ingredient houses concentrate on spray-dried powder formats for dry premix applications.
India
Domestic nutraceutical formulators in Maharashtra and Karnataka source pharmaceutical-grade extracts for cardiovascular wellness capsules targeting export markets. FSSAI tightening of botanical extract purity standards affects export eligibility, while CDSCO pharmaceutical-grade certification creates competitive advantage for compliant suppliers. Andhra Pradesh cultivation clusters supply raw calyces to extraction facilities in Hyderabad.
Thailand
Organic cultivation networks in Chiang Mai and Nakhon Ratchasima supply certified-sustainable raw material to European and Japanese buyers demanding carbon footprint disclosure. The country's national food safety regulator enforces HACCP-aligned protocols for extract export eligibility. Bangkok-based processors specialize in aqueous extraction for direct-to-beverage liquid concentrate formats.
Switzerland
Precision nutraceutical formulators in Basel and Geneva procure standardized phyto-complex extracts for dermocosmetic and ingestible antioxidant applications. Swissmedic pharmaceutical-grade manufacturing audits govern extract certification for clinical positioning. Zurich-region analytical chemistry providers support REACH-registered substance characterization for EU cosmetic regulation compliance.
Hibiscus Extract Market Competitive Environment
Listed leaders compete with private specialists across extraction technology and supply chain control dimensions, producing a tiered structure where scale-driven ingredient houses and backward-integrated cultivators occupy distinct competitive positions. Three archetypes dominate: multinational flavor science conglomerates with beverage fortification infrastructure; regional specialists with captive cultivation networks; and phyto-complex extraction technology providers serving pharmaceutical channels. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers lock multi-year offtake agreements with certified-sustainable procurement requirements.
Within the flavor science tier, Givaudan SA exemplifies multinational infrastructure deployment for standardized extract supply. Among cultivation-integrated specialists, Wild Hibiscus Flower Co. occupies a position anchored to Australian and Pacific Island raw material control. On the pharmaceutical-grade extraction vector, Indena S.p.A. represents phyto-complex technology specialization serving cardioprotective formulators in Germany and Switzerland.
| Leading Market Players |
|---|
| Givaudan SA |
| Wild Hibiscus Flower Co. |
| Merck Group |
| OBG Pharmaceuticals Ltd |
| Fengchen Group |
| Hibiscus Bio-Extracts Pvt Ltd |
| Naturex |
| Indena S.p.A |
| Sabinsa Corporation |
| Others |
Value Chain & Pricing Dynamics
REACH registration requirements for novel botanical substances gate both supplier qualification and price differentiation simultaneously, forcing extract houses to absorb analytical chemistry investments that stratify procurement tiers between registered and unregistered material.
Pricing Analysis
Current-generation phyto-complex extraction technology commands 40-60% premiums over conventional aqueous processing, while next-generation precision fermentation alternatives remain pre-commercial. Three-tier pricing structure across pharmaceutical-grade, food-grade, and cosmetic-grade certification levels dominates procurement contracts. Price differentiation hinges on EFSA Novel Food completion status and USP monograph alignment. Cost compression in food-grade tiers is intensifying because Australian calyx suppliers are consolidating offtake agreements. Small-batch beverage startups exhibit highest price sensitivity; German pharmaceutical formulators show lowest.
Supply Chain Analysis
Strategic stockpiling of dried calyces dominates procurement behavior among backward-integrated processors, displacing just-in-time purchasing that proved vulnerable to monsoon-driven yield fluctuations. Raw material supply concentrates in Australia, Thailand, and select Pacific Island cultivation networks. Downstream extraction draws from hydroalcoholic solvents, membrane filtration systems, and spray-drying equipment. Single-source vulnerability in Australian calyx production creates structural risk for European and North American formulators. Distribution runs through certified-sustainable ingredient houses that lock multi-year contracts with cultivation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hibiscus extract demand is recovering from cyclical lows as functional beverage formulators restock inventories following pandemic-era destocking, with clinical validation cycles for cardioprotective applications driving replacement demand.
For Market Incumbents: Secure multi-year offtake agreements with Thai and Australian cultivation networks before certification requirements tighten. Invest in membrane filtration capacity expansion to defend against synthetic biology substitutes entering pre-commercial trials. Lock pharmaceutical-grade certification ahead of CDSCO harmonization with USP standards.
For New Entrants and Emerging Players: Differentiate on dermocosmetic antioxidant positioning where REACH-registered substance characterization remains sparse. Target Nordic beverage manufacturers demanding carbon footprint disclosure that incumbent suppliers struggle to provide. Pursue direct digital procurement channels that bypass established ingredient house markups.
For Investors and Strategic Acquirers: EFSA Novel Food assessment completion reshapes the acquisition landscape toward suppliers with validated safety dossiers. Five-to-ten-year viability favors backward-integrated specialists with captive cultivation and extraction technology IP. Watch for FDA GRAS self-affirmation submission volumes as inflection signal for US market access timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive calyx supply from Australian networks insulates margin from climate-driven input volatility. |
| Pharmaceutical-Grade Certification Investment | CDSCO-aligned GMP audits unlock premium positioning in Indian export and domestic channels. |
| Membrane Filtration Technology Deployment | Low-temperature concentration preserves delphinidin-3-sambubioside stability for beverage applications. |
| REACH-Registered Substance Characterization | Comprehensive constituent profiling satisfies ECHA mandates for EU cosmetic and novel food access. |
| Direct-to-Beverage Digital Procurement Channel | B2B platforms bypass traditional ingredient house markups for small-batch functional drink formulators. |
Study Parameters
Operator-level perspectives from extraction facility managers, beverage formulation scientists, pharmaceutical procurement leads, and regulatory affairs specialists anchored the qualitative base. Secondary validation drew from EFSA Novel Food assessment databases, FDA GRAS notification filings, USP and EP pharmacopeial monographs, and customs trade records for dried calyces and standardized extracts. Bottom-up volume modeling triangulated against top-down market sizing across grade tiers and application segments.
Sensitivity analysis tested forecast robustness against monsoon yield variability, regulatory assessment timeline delays, and synthetic biology substitution curves. Segmentation dimensions modeled include product format, application vertical, certification grade, and regional regulatory cluster. CAGRs derived from regression analysis of historical procurement volumes correlated with clinical publication velocity and novel food approval trajectories. Extract standardization technology adoption curves and backward integration rates served as industry-specific forecast inputs.
Material uncertainties — EFSA assessment outcome reversals, FDA GRAS enforcement shifts, and climate-driven Australian yield collapses — sit outside the modeled envelope. Forecasts reflect assumptions regarding pharmacopeial harmonization timelines and sustained clinical validation funding. Revision becomes warranted when synthetic biology-derived anthocyanin alternatives achieve cost parity with botanical extraction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Dairy Ingredients Market
Ingredients
Sesame Seed Extract Market
Ingredients
Gluten-Free Flour Market
Ingredients
Yeast Derivatives Market
Ingredients
US Ingredients Market
Ingredients
Textural Food Ingredients Market
Ingredients
Asia Pacific Feed Yeast Market
Ingredients
North America Brewing Enzymes Market
Ingredients
Hydrolyzed Pork Protein Market
Ingredients
Potato Starch Market
Ingredients
Barley Malt Extract Market
Ingredients
Yeast Peptide Market
Ingredients
Sunflower Meal Market
Ingredients
Organic Edible Oil Market
Ingredients
Vegetable Extract Market
Ingredients
Oyster Shell Powder Market