
 Functional Foods and Natural Health Products Market | 2026-2036
Functional Foods and Natural Health Products Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Foods and Natural Health Products Market Foresight
Plant-based protein isolates is hardening cost structures across dairy-alternative functional lines. Oatly Group AB leverages Nordic sourcing infrastructure to sustain oat-milk yogurt margins in European retail. Nestlé S.A. anchors its position through R&D intensity in microbiome-targeted formulations. Danone S.A. specializes in fermented functional beverages, competing on strain-specific clinical validation rather than commodity probiotic counts.
Functional foods and natural health products comprise edible formulations engineered with bioactive compounds—probiotics, prebiotics, omega fatty acids, or herbal extracts—at concentrations sufficient to deliver physiological benefits beyond basic nutrition, typically manufactured via controlled fermentation, cold-press extraction, or microencapsulation to preserve activity through shelf life and digestion. Their primary commercial purpose centers on disease-risk reduction and performance optimization in consumer wellness routines. Probiotics and prebiotics occupy the largest margin pools due to established clinical pipelines and premium pricing power, while omega fatty acids and nutraceutical supplements represent the fastest-expanding categories as cardiovascular and cognitive health claims gain regulatory traction in major economies. Digestive health applications remain mature, whereas immune support and cognitive function segments are deepening their growth curves post-pandemic.
The FDA oversees structure-function claim compliance in the United States, while EFSA enforces health claim authorization under EU Regulation 1924/2006, and China's SAMR administers blue-hat registration for functional food and health product labeling. These frameworks shape demand by determining which bioactive ingredients qualify for premium positioning versus commodity classification. Stakeholders must monitor evolving strain-level approval pathways and adapt substantiation portfolios before regulatory windows narrow for novel ingredient categories.
Market Dynamics
EU Regulation 1924/2006 is hardening health claim substantiation requirements, forcing manufacturers to rebuild clinical validation pipelines or retreat to generic positioning. This regulatory compression is redrawing competitive boundaries between strain-specific probiotic developers and commodity ingredient suppliers.
Growth Catalysts
- Microbiome-targeted R&D intensity:Nestlé S.A. and Danone S.A. are expanding strain-specific clinical pipelines, validating proprietary bacterial combinations for immune and cognitive endpoints beyond basic digestive claims.
- China's blue-hat registration pathway:SAMR's functional food labeling framework is accelerating traditional medicine integration, enabling ginseng, goji, and reishi extracts to carry approved health claims in domestic retail.
- Sports nutrition buyer concentration:Athlete and fitness consumer segments are adopting personalized wellness programs with bioactive dosing protocols, creating premium price acceptance for clinically validated formulations.
Market Restraints
- Oat protein isolate input volatility:Nordic sourcing infrastructure constraints and crop yield fluctuations are hardening cost structures across dairy-alternative functional yogurt lines.
- Strain-level approval concentration:EFSA's centralized health claim authorization creates bottlenecks for novel probiotic submissions, advantaging incumbents with existing approved strain portfolios.
- Plant-based omega-3 substitution limits:Algal DHA extraction yields remain below fish oil concentration thresholds, restricting cardiovascular claim substantiation for vegan-positioned products.
Strategic Opportunities
- Cognitive function white space:Post-pandemic immune support maturation is redirecting R&D toward nootropic botanicals and phosphatidylserine formulations for aging populations in Japan and Germany.
- Cold-chain direct-to-consumer channels:Refrigerated probiotic subscription models are bypassing conventional retail slotting fees, capturing lifetime value through personalized microbiome testing integration.
- US structure-function claim flexibility:FDA's less stringent substantiation threshold versus EFSA enables faster market entry for novel bioactives, provided manufacturers avoid disease treatment language.
Industry Challenges
- Clinical trialist scarcity:Strain-specific probiotic studies require gastroenterology and immunology specialists with nutritional intervention experience, creating recruitment bottlenecks and protocol delays.
- Microencapsulation capex intensity:Shelf-stable probiotic viability demands spray-drying and fluid-bed coating equipment investments that strain mid-cap manufacturer balance sheets.
- Cross-jurisdiction claim harmonization:Divergent EFSA, FDA, and SAMR evidence standards force parallel clinical programs, multiplying substantiation costs for global product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Foods and Natural Health Products Market |
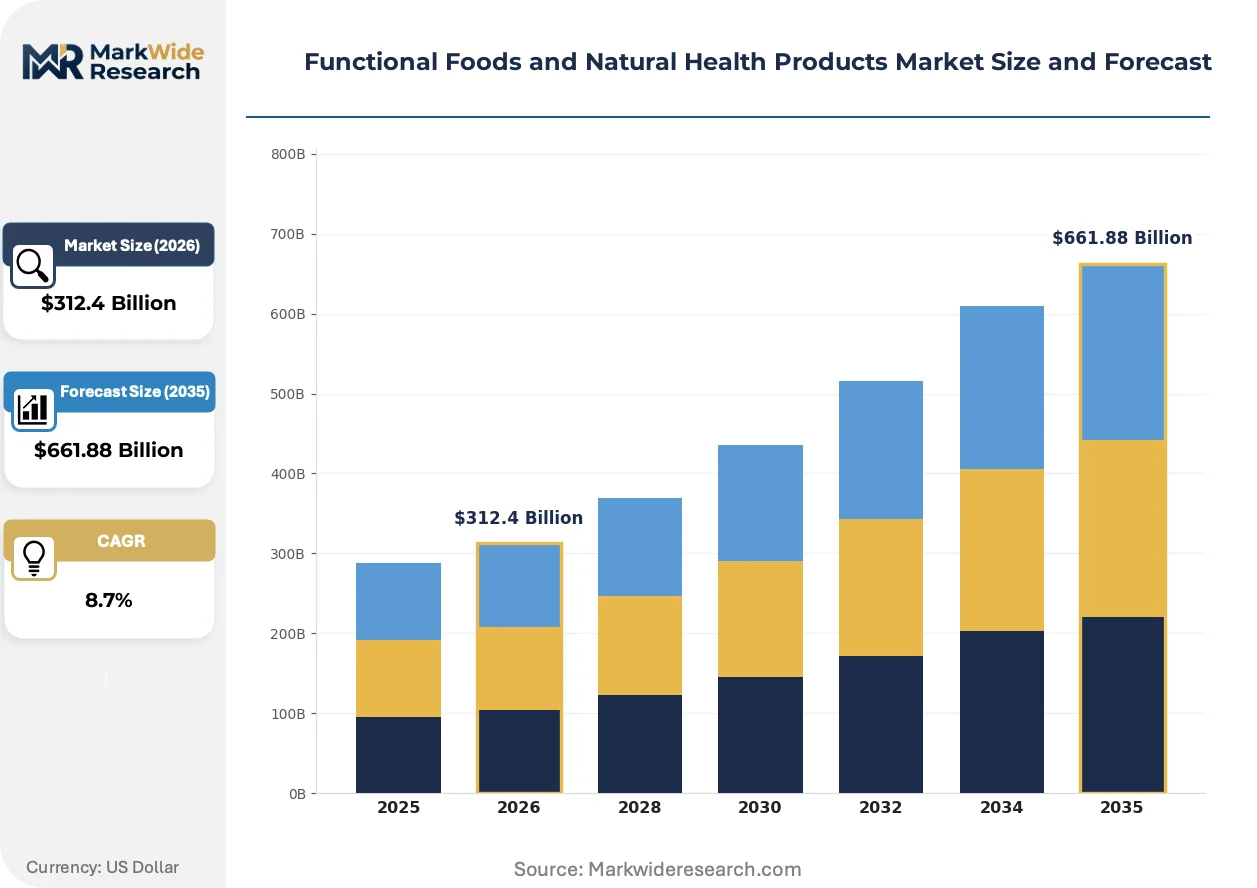
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $661.88 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Nutraceutical Supplements, Herbal Extracts, Omega Fatty Acids, Dietary Fibers Application: Digestive Health, Weight Management, Immune Support, Cognitive Function, Cardiovascular Wellness, Anti-Aging End User: Pharmacies, Wellness Centers, Specialty Retailers, Fitness Clubs, Natural Product Stores, E-commerce Platforms Packaging Type: Bottles, Blister Packs, Sachets, Jars, Tubes, Cartons |
| Companies Covered | Abbott Laboratories, General Mills, Nestlé S.A., Oatly Group AB, Yakult Honsha Co., Ltd., Danone S.A., Kellogg’s, Amway (Nutrilite), PepsiCo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Foods and Natural Health Products Market Shifts & Advancements
Fermentation process control and bioactive preservation technologies are compressing development cycles for functional formulations. These advances are enabling manufacturers to move from commodity positioning toward clinically differentiated premium tiers.
Precision fermentation of novel microbial strains is electrifying probiotic manufacturing economics. Sports nutrition and personalized wellness program adopters are integrating these bioactives at accelerating velocities. This technology is electrifying margin expansion opportunities for manufacturers that achieve strain-specific patent protection and clinical validation.
EFSA's 2023 updated guidance on beneficial physiological effect characterization is narrowing acceptable study designs for gut health claims. Manufacturers must now demonstrate sustained microbiome modulation rather than transient bacterial presence. Fermented functional beverage specialists in France and the Netherlands are responding by extending intervention study durations and adding metabolomic endpoints.
Consumer verification behavior is fragmenting trust mechanisms across purchase channels. Third-party certification programs including NSF International and Informed Sport are displacing unverified brand promises in athlete and clinical nutrition segments. This shift is most visible in Germany and Australia, where pharmacy and practitioner channels dominate high-concentration omega fatty acid distribution.
Functional Foods and Natural Health Products Market Segmentation
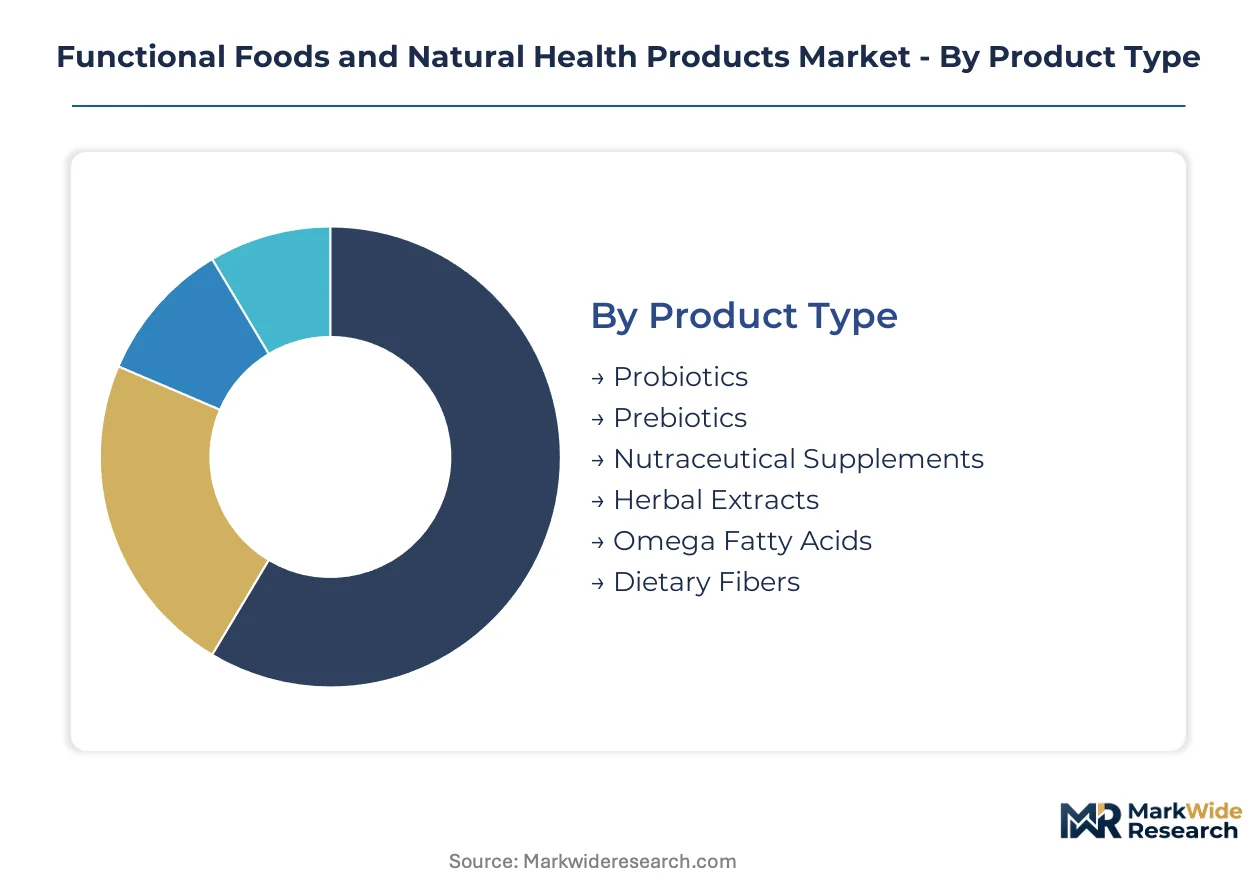
Segmentation in functional foods and natural health products determines which regulatory pathways manufacturers must navigate and which margin tiers they can access. Strain-specific probiotic approvals, herbal extract blue-hat registrations, and omega-3 cardiovascular claims each demand distinct substantiation investments that reshape competitive boundaries across product categories.
Product Type:
EFSA health claim authorization under EU Regulation 1924/2006 applies differentially across these segments, with probiotics and prebiotics facing the most stringent strain-level substantiation requirements while omega fatty acids navigate cardiovascular endpoint validation.
- Probiotics:Live microbial formulations delivering measurable physiological benefits through gut colonization, typically requiring controlled fermentation and microencapsulation for shelf stability. Demand concentrates in Germany and Japan where aging populations seek immune and cognitive endpoints beyond basic digestive support, constrained by EFSA's 2023 guidance demanding sustained microbiome modulation evidence rather than transient bacterial presence.
- Prebiotics:Non-digestible substrates that selectively feed beneficial gut microbiota, including inulin, fructooligosaccharides, and galactooligosaccharides. Sports nutrition adopters in Australia and the United States are integrating these into personalized wellness protocols, driving premium pricing for clinically validated dosing regimens that demonstrate bifidogenic effects.
- Nutraceutical Supplements:Concentrated bioactive compounds including vitamins, minerals, and specialty ingredients manufactured via extraction or synthesis.
- Herbal Extracts:Standardized botanical preparations from ginseng, ashwagandha, turmeric, and traditional medicine sources.
- Omega Fatty Acids:EPA and DHA concentrates from marine or algal sources targeting cardiovascular and cognitive health applications.
- Dietary Fibers:Soluble and insoluble fractions from oats, psyllium, and resistant starch supporting digestive regularity and glycemic control.
Probiotics sit at the top of the volume ranking, with omega fatty acids climbing the fastest as cardiovascular claim substantiation gains regulatory traction in major economies.
Application:
Cost tier differentiation separates premium clinically validated formulations from commodity-positioned products, with immune support and cognitive function commanding the highest substantiation investments per claim.
- Digestive Health:Mature application segment encompassing irritable bowel syndrome management, regularity support, and gut barrier function. Pharmacy channels in France and the Netherlands dominate distribution, with fermented functional beverage specialists extending intervention study durations to meet EFSA's updated beneficial physiological effect characterization standards.
- Immune Support:Post-pandemic growth curve deepening for formulations demonstrating measurable immunomodulatory effects through cytokine profiling or infection resistance endpoints. Japanese and German aging populations are driving demand for clinically validated combinations, though trialist scarcity in gastroenterology and immunology specialists creates recruitment bottlenecks.
- Weight Management:Satiety-enhancing fibers, thermogenic botanicals, and microbiome-modulating interventions.
- Cognitive Function:Nootropic botanicals, phosphatidylserine, and omega-3 formulations targeting memory and focus.
- Cardiovascular Wellness:Cholesterol management, blood pressure modulation, and vascular health applications.
- Anti-Aging:Collagen peptides, antioxidant complexes, and cellular health formulations.
Digestive health retains the largest volume position, while cognitive function is expanding most quickly as post-pandemic immune support maturation redirects R&D toward aging population needs.
End User:
Customer type determines trust mechanism requirements, with athlete and clinical segments demanding third-party certification while mass retail tolerates brand promises.
- Pharmacies:Professional channel requiring pharmacist recommendation or prescription alignment for high-concentration formulations. Germany and Australia exhibit the strongest pharmacy dominance for omega fatty acid distribution, where NSF International and Informed Sport certifications displace unverified claims.
- E-commerce Platforms:Direct-to-consumer channel enabling refrigerated probiotic subscription models that bypass conventional retail slotting fees. Cold-chain infrastructure investments and personalized microbiome testing integration are capturing lifetime value in the United States and China.
- Wellness Centers:Practitioner-guided protocols with customized bioactive dosing.
- Specialty Retailers:Curated assortments targeting health-conscious consumers with education-heavy purchase environments.
- Fitness Clubs:Sports nutrition integration with training protocols and recovery programs.
- Natural Product Stores:Traditional medicine alignment and clean-label positioning for botanical and whole-food formulations.
Pharmacies sit at the top of the volume ranking, with e-commerce platforms climbing the fastest as cold-chain logistics and subscription mechanics reshape distribution economics.
Packaging Type:
Supply concentration in barrier material technologies determines which formats can achieve the shelf stability and moisture protection required for viable probiotic delivery.
- Blister Packs:Individual-dose aluminum-plastic laminates providing superior moisture and oxygen barrier for hygroscopic nutraceuticals. High-concentration omega fatty acid and probiotic formats in Japan and Germany rely on this protection, though material cost volatility affects mid-cap manufacturer margins.
- Sachets:Flexible single-serve pouches enabling powder and liquid probiotic delivery with modified atmosphere options. China's SAMR blue-hat registration pathway favors this format for traditional medicine extracts like ginseng and goji, where portability aligns with domestic retail consumption patterns.
- Bottles:Rigid containers for tablet and capsule counts with desiccant integration.
- Jars:Wide-mouth containers for powder formulations and bulk probiotic servings.
- Tubes:Collapsible formats for gel, paste, and semi-solid functional food applications.
- Cartons:Paperboard-based secondary packaging with primary barrier integration for beverage and liquid formats.
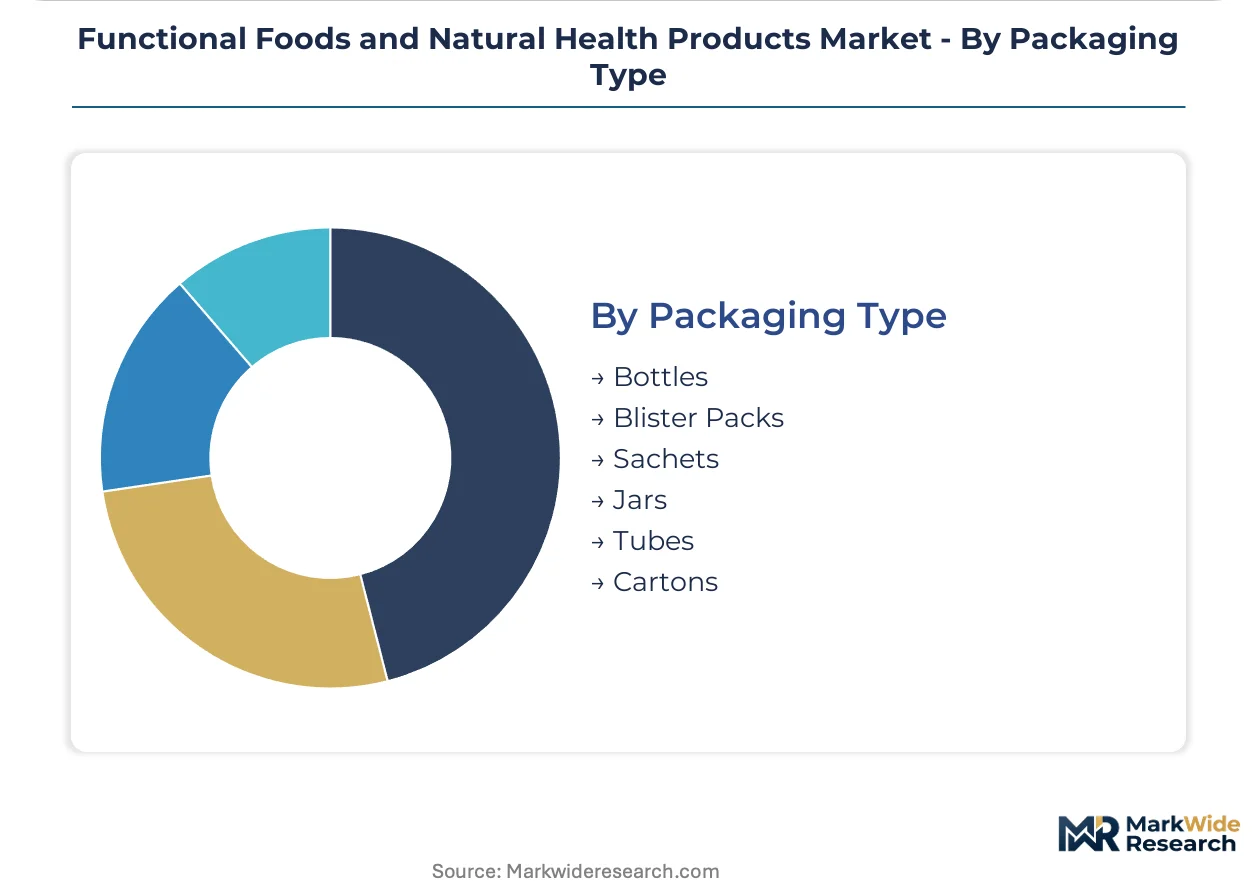
Blister packs sit at the top of the volume ranking, with sachets climbing the fastest as single-serve convenience and traditional medicine format alignment accelerate adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Baden-Württemberg region anchors European functional food manufacturing, hosting precision fermentation clusters that supply strain-specific probiotics across the continent. Demand concentrates in aging population centers seeking immune and cognitive endpoints beyond basic digestive support.
United States
Sports nutrition adopters in California and Texas are integrating personalized wellness protocols with bioactive dosing regimens. FDA structure-function claim flexibility enables faster market entry for novel bioactives compared to European frameworks. Chicago and Minneapolis host cold-chain logistics hubs supporting refrigerated probiotic subscription models that bypass conventional retail slotting fees.
Germany
Pharmacy channels in Bavaria and North Rhine-Westphalia dominate high-concentration omega fatty acid distribution, where NSF International certifications displace unverified brand promises. EFSA's 2023 updated guidance on beneficial physiological effect characterization is forcing manufacturers to demonstrate sustained microbiome modulation. Heidelberg and Munich clusters specialize in fermented functional beverages with extended intervention study durations.
China
SAMR's blue-hat registration pathway is accelerating traditional medicine integration in Shanghai and Guangzhou, enabling ginseng and reishi extracts to carry approved health claims. Yangtze River Delta manufacturers are scaling precision fermentation of novel microbial strains. Beijing's regulatory cluster is streamlining functional food labeling frameworks for domestic retail expansion.
Japan
Aging populations in Tokyo and Osaka are driving demand for clinically validated immune support combinations with measurable cytokine profiling endpoints. METI oversight shapes functional claim substantiation requirements for fermented beverages. Kansai region specialists are deepening R&D toward nootropic botanicals and phosphatidylserine formulations.
Australia
TGA-regulated pharmacy and practitioner channels dominate omega-3 distribution in Sydney and Melbourne, where Informed Sport certifications command premium positioning. Sports nutrition segments are adopting personalized microbiome testing integration. Queensland's algal DHA extraction facilities are addressing plant-based omega-3 concentration thresholds for vegan-positioned cardiovascular claims.
Functional Foods and Natural Health Products Market Competitive Landscape
Global majors compete with regional champions across regulatory substantiation capabilities, with strain-specific clinical validation separating premium-tier players from commodity ingredient suppliers. The market structure reflects consolidation around microbiome-targeted R&D pipelines and fermentation process control technologies. Three archetypes dominate: multinational nutrition conglomerates with proprietary bacterial strain portfolios, regional fermented beverage specialists competing on clinical study duration, and plant-based dairy-alternative operators leveraging Nordic sourcing infrastructure. Competitive moves center on M&A for strain patent acquisition and cold-chain direct-to-consumer channel expansion.
Within the multinational tier, Nestlé S.A. and Danone S.A. exemplify divergent strategic positioning in microbiome science, with the former anchoring R&D intensity in bacterial combinations and the latter specializing in fermented functional beverages with strain-specific clinical validation. Yakult Honsha Co., Ltd. occupies a distinct position as a Japanese precision fermentation specialist with decades-long consumer education in probiotic daily consumption habits. Oatly Group AB represents the plant-based infrastructure archetype, with its Nordic sourcing model sustaining margins across dairy-alternative functional lines. Abbott Laboratories sits within the clinical nutrition segment, bridging pharmaceutical-grade substantiation with consumer wellness applications.
| Leading Market Players |
|---|
| Abbott Laboratories |
| General Mills |
| Nestlé S.A. |
| Oatly Group AB |
| Yakult Honsha Co., Ltd. |
| Danone S.A. |
| Kellogg's |
| Amway (Nutrilite) |
| PepsiCo Inc. |
| Others |
Supply & Pricing Matrix
Sports nutrition adopters and personalized wellness program buyers concentrate demand for clinically validated formulations, anchoring a subscription-based pricing model that captures lifetime value through recurring bioactive dosing protocols rather than transactional commodity purchases.
Pricing Analysis
Input-cost pass-through from oat protein isolate and algal DHA extraction yields hardens cost structures across dairy-alternative functional lines and vegan-positioned omega-3 products. Pricing stratifies across premium, standard, and economy tiers based on EFSA strain-level approval status and third-party NSF International or Informed Sport certification. Cost compression in plant-based omega-3 categories is intensifying because algal extraction yields remain below fish oil concentration thresholds. Mass retail channels exhibit highest price sensitivity, while athlete and clinical segments accept premium positioning for validated formulations.
Supply Chain Analysis
Dual-sourcing requirements for live microbial strains and standardized herbal extracts mandate multi-supplier qualification across Nordic oat cultivation zones, Yangtze River Delta precision fermentation clusters, and German Baden-Württemberg manufacturing hubs. Raw material dependencies center on bacterial strain libraries, cold-press extraction equipment, and barrier-grade aluminum-plastic laminates for moisture-sensitive formats. Single-source vulnerability concentrates in EFSA-approved probiotic strain portfolios, where incumbent patent protection limits supplier alternatives. Distribution runs through pharmacy channels in Germany and Australia, refrigerated direct-to-consumer subscription models in the United States, and SAMR-regulated retail in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between FDA structure-function claim flexibility in the United States and EFSA's stringent health claim authorization in Europe, with manufacturers capturing faster market entry timelines and lower substantiation costs in North American jurisdictions.
For Market Incumbents: Lock in strain-specific patent protection and extend clinical validation pipelines before regulatory windows narrow for novel probiotic categories. Nestlé S.A. and Danone S.A. demonstrate the defensive value of proprietary bacterial combinations with immune and cognitive endpoints. Backward integration into precision fermentation capacity secures supply continuity against Nordic oat yield volatility.
For New Entrants and Emerging Players: Practitioner-guided wellness centers represent an underserved buyer archetype with customized bioactive dosing protocols and lower competitive density than mass retail. Cold-chain direct-to-consumer channels bypass conventional slotting fees and capture lifetime value through personalized microbiome testing integration. Japan's aging population demand for nootropic botanicals offers a penetrable geography with METI oversight familiarity.
For Investors and Strategic Acquirers: Multinational nutrition conglomerates are the most active acquirer in this space, seeking strain-specific clinical validation capabilities and fermentation process control technologies. Over a multi-year horizon, acquisition targets with EFSA-approved strain portfolios and extended intervention study durations command defensive positioning. The signal to watch is SAMR blue-hat registration acceleration for traditional medicine extracts, indicating regulatory pathway maturation for domestic Chinese market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Strain-Specific Clinical Pipeline Expansion | EFSA's 2023 guidance demands sustained microbiome modulation evidence rather than transient bacterial presence. |
| Cold-Chain Direct-to-Consumer Launch | Refrigerated probiotic subscriptions bypass retail slotting fees in Chicago and Minneapolis logistics hubs. |
| Precision Fermentation Capacity Buildout | Yangtze River Delta manufacturers scale novel microbial strain production for margin expansion. |
| Traditional Medicine Blue-Hat Registration | SAMR's pathway enables ginseng and reishi extracts to carry approved health claims in Shanghai retail. |
| Third-Party Certification Investment | NSF International and Informed Sport displace unverified claims in German pharmacy channels. |
Research Methodology
Multiple input streams — executive interviews with functional food R&D directors and regulatory affairs leads, procurement discussions with pharmacy chain category managers, and validation sessions with precision fermentation plant managers — were reconciled against secondary sources including EFSA health claim submission databases, SAMR blue-hat registration filings, and Nielsen retail audit data. Bottom-up segment sizing triangulated with top-down macroeconomic anchoring across the analysis window.
Data-stream reconciliation applied a multi-dimensional analytical framework spanning product type, application endpoint, end-user channel, and regional regulatory cluster throughout the forecast period. CAGRs derived from segment-level growth trajectory modeling incorporating bioactive ingredient approval timelines, cold-chain infrastructure penetration rates, and aging population demographic shifts in Japan and Germany.
Underlying measurement precision varies by segment; probiotics and prebiotics with established EFSA approvals carry tighter precision than novel nootropic botanical categories awaiting regulatory substantiation. Forecasts reflect assumptions regarding strain-level approval pathway efficiency, algal DHA extraction yield improvements, and traditional medicine integration velocity. Deviation in EFSA guidance enforcement or SAMR registration processing timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Adaptogen Drink Market
Functional Food and Beverage
Europe Medical Foods Market
Functional Food and Beverage
Functional Beverage Market
Functional Food and Beverage
Low-Fat and Low Protein Diet Market
Functional Food and Beverage
Global CBD Beverages Market
Functional Food and Beverage
Functional Chewing Gums Market
Functional Food and Beverage
RTD Protein Beverages Market
Functional Food and Beverage
Asia-Pacific Functional Water Market
Functional Food and Beverage
Europe Functional Beverages Market
Functional Food and Beverage
North America Functional Beverage Market
Functional Food and Beverage
Beauty Drinks Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
GCC Functional Food & Beverage Market
Functional Food and Beverage
Functional Soda Market
Functional Food and Beverage
Vegan Brain Food Market
Functional Food and Beverage
Asia-Pacific Functional Mushroom Market