
 Natural Functional Food Market | 2026-2036
Natural Functional Food Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Functional Food Market Outlook
Plant-based proteins are expanding their share of functional food formulations as manufacturers reformulate away from soy isolates toward pea and fava bean concentrates. Nestlé leverages its dairy heritage to build hybrid fermentation platforms that blend traditional cultures with novel substrates. Danone anchors its competitive position through dedicated R&D facilities in specialized probiotic strain development. General Mills competes by controlling grain supply chains that feed its fiber-supplement bar portfolio.
Natural functional food denotes consumable products derived from minimally processed biological sources that deliver measurable physiological benefits beyond basic nutrition, typically containing standardized bioactive compounds such as live microbial cultures, omega-3 fatty acids, or soluble fibers at concentrations proven to modulate gut microbiota, lipid metabolism, or immune response. Probiotics and prebiotics dominate current revenue pools due to established clinical validation and broad consumer recognition, while omega fatty acids represent the fastest-growing category as aquaculture-sourced algae oils displace fish-derived alternatives in clean-label positioning. Beverages capture expanding shelf space across distribution channels as ready-to-drink formats overcome the convenience deficit of powders and pills.
FDA nutrition labeling rules and EFSA health claims procedures jointly determine which functional benefit statements reach packaging in the United States and European Union, while China's SAMR imposes additional registration requirements on probiotic strains not listed in national food ingredient catalogs. The divergence between these frameworks forces multinational manufacturers to maintain parallel formulation portfolios and dossier systems. Stakeholders must monitor evolving strain-specific approvals and adapt certification pipelines before regulatory windows narrow for novel bioactive introductions.
Market Dynamics
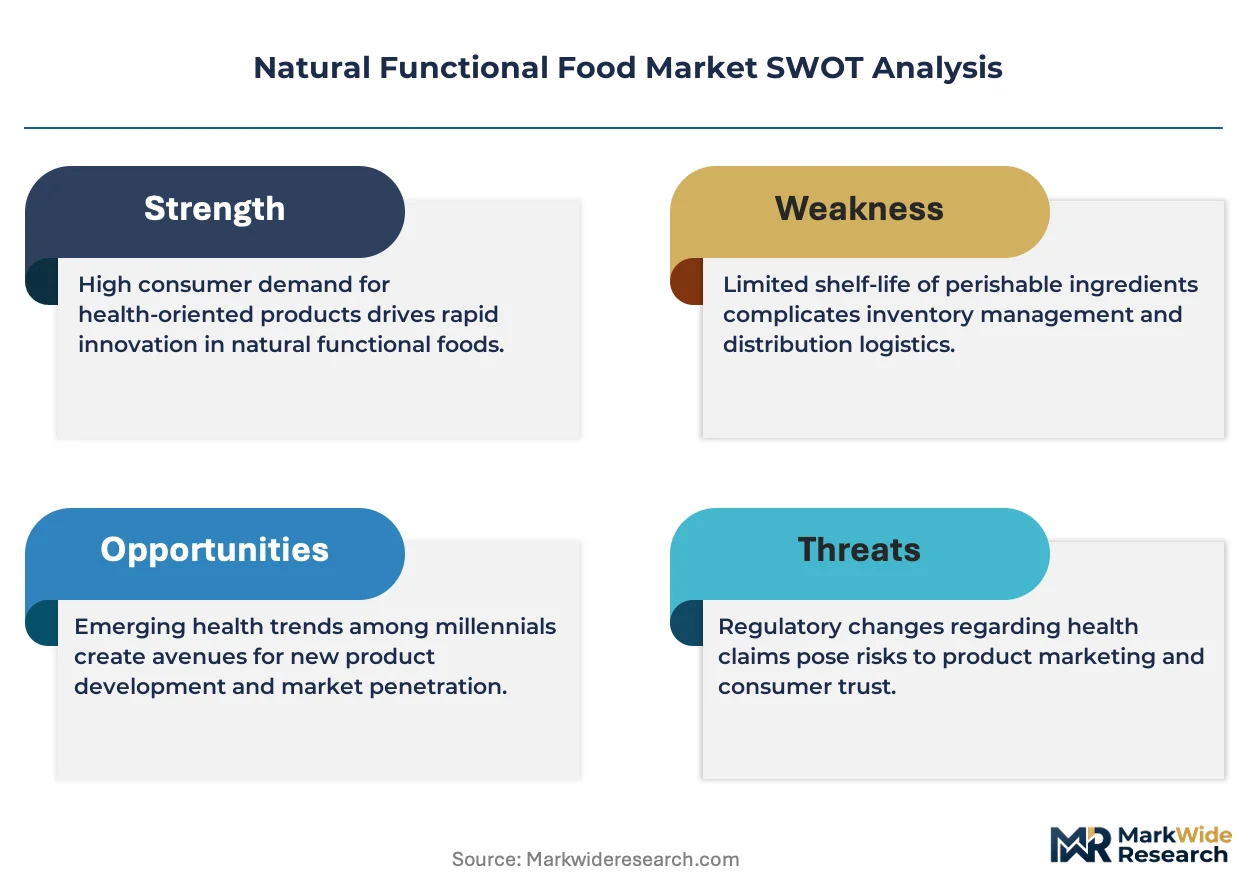
Ingredient traceability mandates under the EU Green Deal are forcing manufacturers to rebuild supply chain documentation systems while simultaneously opening premium positioning for verified-clean products in conventional retail channels.
Growth Catalysts
- Fermentation platform advancement:Hybrid culture systems that blend traditional dairy substrates with novel plant bases enable cleaner-label positioning without sacrificing probiotic viability. Health enthusiasts in Germany and France drive adoption through personalized nutrition platforms.
- EFSA health claims harmonization:Streamlined approval procedures for gut microbiota modulation claims reduce time-to-market for clinically validated strains. This regulatory clarity particularly benefits prebiotic fiber formulations seeking shelf space in EU conventional retail.
- Algae oil substitution:Aquaculture-sourced omega fatty acids displace fish-derived alternatives, resolving clean-label positioning conflicts for vegan-positioned functional beverages. Production concentrates in controlled-environment facilities near major formulation hubs.
Market Restraints
- Pea protein input volatility:Weather-dependent harvests in Canada and France create price instability for concentrate suppliers, compressing margins for bar and beverage manufacturers dependent on soy-free positioning.
- Strain registration bottlenecks:China's SAMR maintains closed catalogs for probiotic approvals, forcing parallel formulation portfolios and duplicative dossier investments for brands seeking Asia-Pacific access.
- Technical shelf-life limitations:Live culture viability degrades rapidly in ambient distribution, constraining ready-to-drink expansion into convenience retail without cold-chain infrastructure.
Strategic Opportunities
- Underpenetrated Polish retail:Conventional supermarket channels in Warsaw and Krakow lack dedicated functional beverage sets, creating first-mover advantage for fermented drink brands with local language labeling.
- Personalized nutrition convergence:Microbiome testing platforms integrate with subscription delivery models, enabling strain-matched probiotic recommendations based on individual gut composition analysis.
- Farm to Fork traceability premiums:EU Green Deal verification systems allow ingredient-origin storytelling that commands shelf positioning and price separation from uncertified competitors.
Industry Challenges
- Clinical trial capacity constraints:Strain-specific health claims require expensive human intervention studies, and CRO backlog extends validation timelines beyond product development cycles.
- Legacy ERP integration friction:Batch-level traceability systems demanded by EU regulations conflict with existing manufacturing software, requiring middleware investments that delay facility certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Functional Food Market |
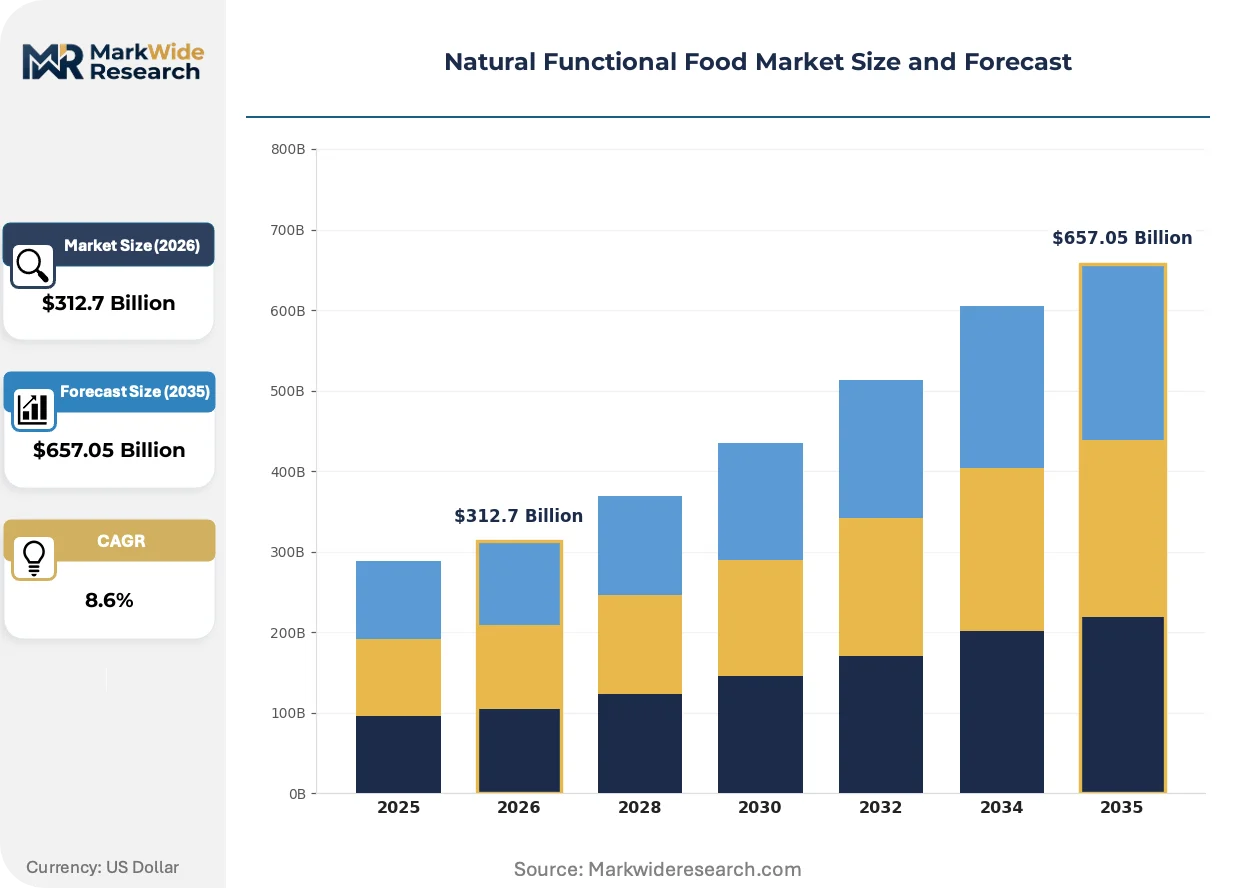
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $657.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prebiotics, Probiotics, Omega Fatty Acids, Fiber Supplements End User: Individuals, Health Enthusiasts, Athletes, Seniors Distribution Channel: Supermarkets, Online Retailers, Health Stores, Pharmacies Form: Pills, Powders, Bars, Beverages |
| Companies Covered | Nestlé, Danone, General Mills, Kellogg Company, PepsiCo, Abbott Laboratories, Mars, Glanbia, Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Functional Food Market Strategic Shifts
Fermentation infrastructure is fragmenting into distributed, smaller-scale systems that co-locate with formulation facilities, collapsing the traditional separation between culture production and finished goods manufacturing.
Precision fermentation is modularizing the production of bioactive compounds previously extracted from agricultural commodities. Specialty chemical buyers in the nutraceutical sector are adopting these systems at pilot scale to secure supply independence from marine and crop harvest volatility. This distributed manufacturing model is compressing minimum viable scale thresholds and enabling regional production clusters near major demand centers.
EFSA's evolving guidance on gut health claims is tightening evidentiary standards for prebiotic classifications, forcing manufacturers to redesign human studies or reformulate with better-characterized substrates. The industrial consequence is a bifurcation between legacy fiber ingredients and next-generation candidates with published microbiome data. Functional bar producers in Germany and the Netherlands are most affected, accelerating partnerships with academic research centers to secure compliant dossiers.
Subscription direct-to-consumer models are displacing conventional pharmacy and health food store distribution for personalized probiotic regimens. Millennial buyers in urban UK and Scandinavian markets favor microbiome-matched products delivered on 30-day cycles over shelf-selection of generic strains. This channel shift concentrates customer data ownership with platform operators and erodes brand loyalty for legacy supplement houses dependent on retail placement.
Natural Functional Food Market Segmentation
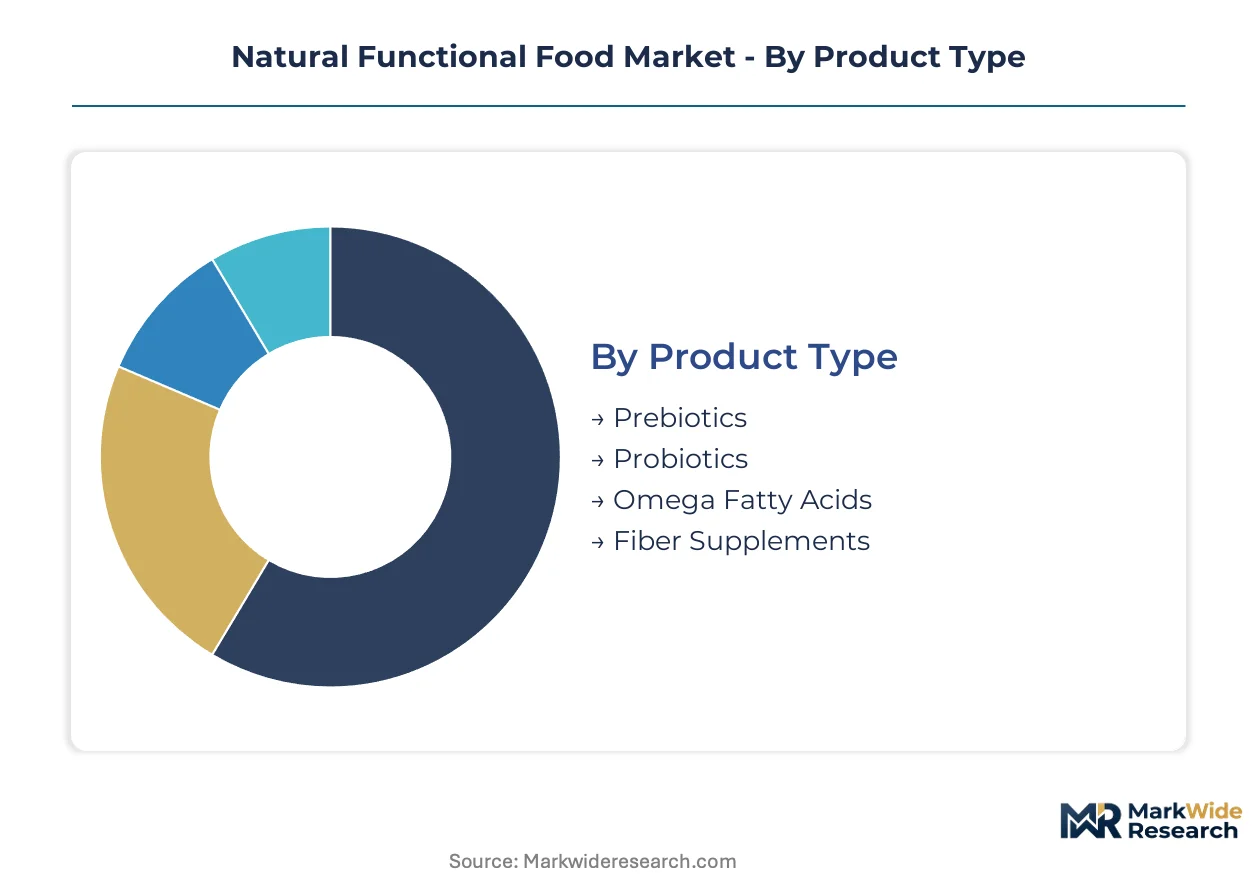
Natural functional food manufacturers must align formulation portfolios with distinct consumption occasions and physiological targets. Each segmentation dimension reveals divergent margin structures and channel access requirements that shape competitive positioning.
Product Type:
Upgrade cycles in functional ingredients accelerate as clinical validation standards tighten and clean-label expectations reshape formulation roadmaps.
- Prebiotics:Non-digestible fibers that selectively nourish beneficial gut microbiota, typically delivered as inulin, FOS, or GOS at standardized concentrations. German and Dutch bar manufacturers drive demand as EFSA tightens evidentiary standards for gut health claims, forcing reformulation toward better-characterized substrates with published microbiome data.
- Probiotics:Live microbial cultures maintained at colony-forming unit thresholds sufficient to survive gastric transit and colonize intestinal epithelium. Health enthusiasts in Germany and France adopt strain-specific products through personalized nutrition platforms, while China's SAMR catalog restrictions force parallel formulation portfolios for Asia-Pacific market access.
- Omega Fatty Acids:Long-chain polyunsaturated lipids sourced increasingly from aquaculture algae rather than marine fish. Controlled-environment production facilities near major formulation hubs resolve vegan positioning conflicts for beverage applications.
- Fiber Supplements:Concentrated soluble and insoluble fractions isolated from grains, legumes, or fruits. General Mills controls captive grain supply chains feeding bar portfolio expansion in North American conventional retail.
Probiotics sit at the top of the volume ranking, with omega fatty acids climbing the fastest as algae oil substitution resolves clean-label positioning constraints.
End User:
Customer lifetime value varies dramatically across physiological life stages and performance optimization goals, driving divergent subscription and retail strategies.
- Individuals:General wellness seekers purchasing sporadically through conventional retail without sustained regimen adherence. Price sensitivity limits premium positioning unless clinical endpoints are clearly communicated on packaging.
- Health Enthusiasts:The fastest-expanding cohort redirecting purchasing behavior through personalized nutrition platforms and microbiome testing integration. German consumers in this segment command premium shelf positioning for fermented functional beverages in conventional retail channels.
- Athletes:Performance-optimized consumers seeking recovery and gut integrity benefits under training stress. Powder formats dominate due to dosing precision and portability requirements.
- Seniors:Demographic concentrated in pharmacy and healthcare practitioner channels with reimbursement sensitivity and pill-format preferences. EFSA health claims harmonization particularly benefits this segment's prebiotic fiber formulations.
Individuals generate baseline volume across all channels, though health enthusiasts are expanding most quickly through platform-mediated subscription models.
Distribution Channel:
Channel selection determines cold-chain requirements, label claim permissibility, and consumer education burden for live culture products.
- Supermarkets:Conventional retail commanding expanding shelf space for ready-to-drink formats as ambient distribution technical limitations constrain probiotic viability without infrastructure investment. EU Green Deal traceability verification enables premium positioning separation from uncertified competitors.
- Online Retailers:Direct-to-consumer platforms displacing pharmacy and health food store distribution for personalized probiotic regimens. Millennial buyers in urban UK and Scandinavian markets favor microbiome-matched products delivered on 30-day cycles.
- Health Stores:Specialty retail with educated staff capable of communicating strain-specific benefits and substrate sourcing stories. Farm to Fork verification systems allow ingredient-origin storytelling that commands price separation.
- Pharmacies:Regulated channel with healthcare practitioner influence over senior and clinical nutrition segments. China's SAMR registration requirements particularly shape product availability in this channel for Asia-Pacific access.
Supermarkets anchor volume through mass-market penetration, while online retailers gain share fastest as subscription models concentrate customer data ownership with platform operators.
Form:
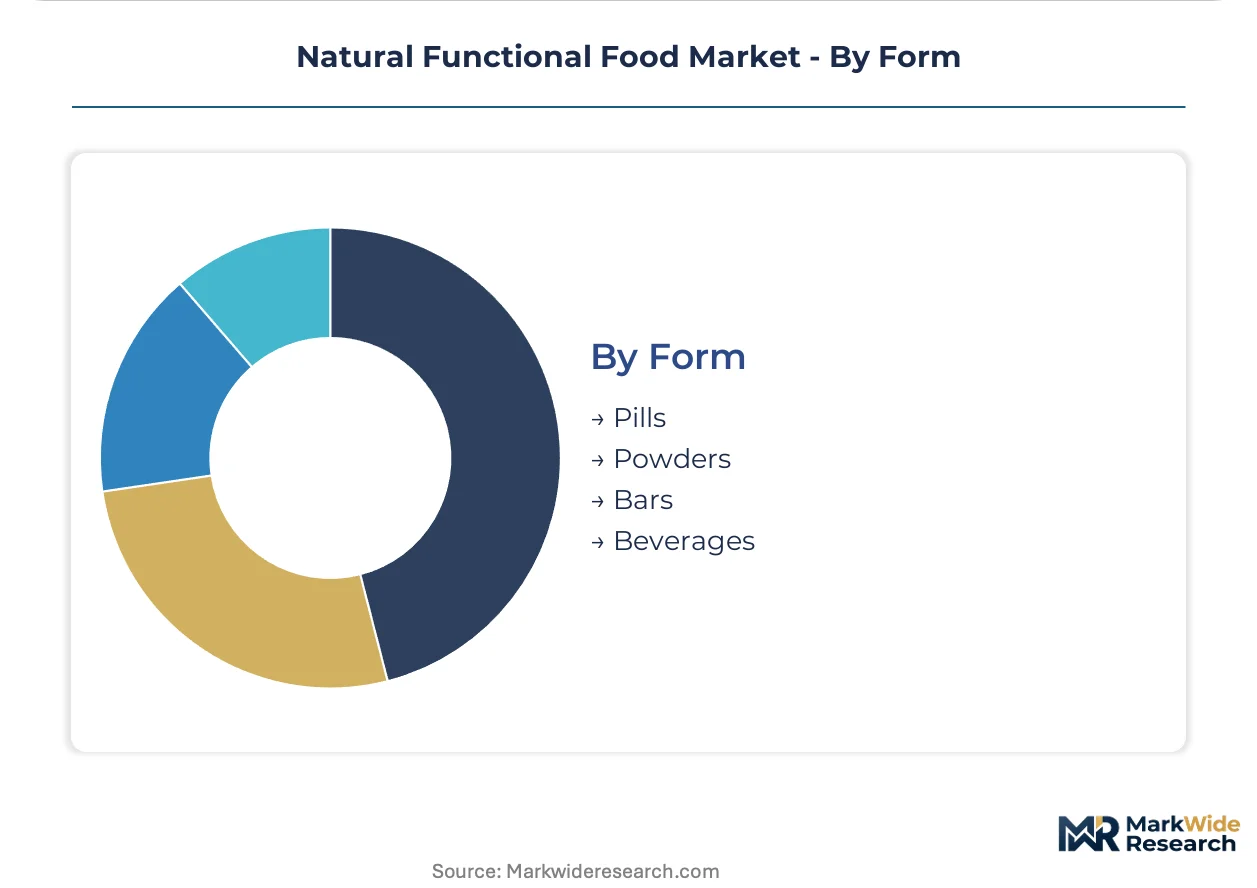
Format selection involves trade-offs between bioactive stability, dosing precision, and consumption convenience that vary by active ingredient category.
- Pills:Encapsulated formats with extended shelf life and precise unit dosing, preferred by senior end users and pharmacy channel distribution. Strain-specific probiotic claims require expensive human intervention studies that extend validation timelines beyond product development cycles.
- Powders:Bulk formats enabling flexible dosing and beverage integration, dominant among athlete end users. Convenience deficit relative to ready-to-drink alternatives limits expansion in convenience retail without cold-chain infrastructure.
- Bars:Solid food matrices combining fiber supplements with protein and lipid macronutrients. Pea protein input volatility from weather-dependent harvests in Canada and France creates price instability for soy-free positioning.
- Beverages:Ready-to-drink formats overcoming the convenience deficit of powders and pills, capturing expanding shelf space across distribution channels. Hybrid fermentation platforms blending traditional dairy substrates with novel plant bases enable cleaner-label positioning without sacrificing probiotic viability.
Beverages are gaining share fastest as format innovation resolves technical shelf-life limitations, though pills retain volume leadership in pharmacy and senior segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fermentation infrastructure anchors functional beverage production across Europe, with hybrid culture platforms supplying reformulated plant-dairy blends to conventional retail channels.
Germany
Health enthusiasts in Berlin and Munich drive demand for fermented functional beverages through personalized nutrition platforms. The EU Green Deal's Farm to Fork Strategy mandates batch-level ingredient traceability for shelf positioning in conventional retail. The Baden-Württemberg cluster concentrates precision fermentation R&D facilities developing next-generation probiotic strains.
United States
FDA nutrition labeling rules determine which functional benefit statements reach packaging, shaping formulation decisions for mass-market penetration. Subscription direct-to-consumer models displace pharmacy distribution for personalized probiotic regimens in urban coastal markets. The Pacific Northwest hosts controlled-environment algae oil production facilities supplying omega fatty acid formulations.
China
SAMR maintains closed catalogs for probiotic strain approvals, forcing parallel formulation portfolios for brands seeking domestic market access. Urban middle-class consumers in Shanghai and Beijing adopt ready-to-drink functional beverages despite cold-chain infrastructure gaps. The Yangtze River Delta concentrates contract manufacturing capacity for multinational brands navigating registration bottlenecks.
France
EFSA health claims harmonization streamlines gut microbiota modulation approvals, reducing time-to-market for clinically validated prebiotic fibers. Paris and Lyon retail channels command premium positioning for verified-clean products under EU Green Deal verification systems. The Auvergne-Rhône-Alpes region hosts academic research partnerships accelerating compliant dossier development.
United Kingdom
Millennial buyers in London and Manchester favor microbiome-matched subscription products delivered on 30-day cycles over generic retail selection. Post-Brexit regulatory divergence from EFSA frameworks creates parallel certification requirements for EU market access. The Southeast England corridor concentrates platform operators consolidating customer data ownership from legacy supplement houses.
Natural Functional Food Market Competitive Environment
Global majors compete with regional champions across fermentation platform development and strain-specific R&D investment. Market structure tilts toward consolidated control at the ingredient supply tier, with fragmented competition among finished goods formulators. Three archetypes dominate: dairy heritage conglomerates leveraging hybrid culture systems, specialized probiotic developers with captive strain libraries, and grain supply chain integrators feeding fiber-supplement portfolios. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with cold-chain infrastructure partnerships enabling ambient distribution trials.
Within the dairy heritage tier, Nestlé and Danone exemplify platform strategies blending traditional fermentation expertise with novel substrate development. General Mills anchors the supply chain integration archetype through captive grain sourcing. These three companies occupy positions spanning multiple format categories and geographic markets, with each representing distinct strategic approaches to clean-label positioning and clinical validation investment.
| Leading Market Players |
|---|
| Nestlé |
| Danone |
| General Mills |
| Kellogg Company |
| PepsiCo |
| Abbott Laboratories |
| Mars |
| Glanbia |
| Kraft Heinz Company |
| Others |
Value Chain & Pricing Dynamics
Pea protein concentrate spot prices in Canada and France cascade through formulation tiers, compressing margins for soy-free positioned bars while enabling premium capture for algae-sourced omega formulations with verified clean-label credentials.
Pricing Analysis
Input-cost pass-through from weather-dependent legume harvests intensifies margin pressure across mid-tier functional bar manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-validated strains from generic probiotic offerings, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from cold-chain infrastructure requirements constraining ambient-ready beverage expansion. Health enthusiasts show least price sensitivity through personalized platform subscriptions, while sporadic retail purchasers in conventional channels exhibit highest elasticity.
Supply Chain Analysis
EU Green Deal local-content mandates for Farm to Fork traceability documentation are forcing ingredient-origin verification systems that reshape sourcing from Canada, France, and Germany toward certified-origin suppliers. Raw material flows draw from aquaculture algae facilities, precision fermentation R&D clusters, and controlled-environment grain operations. Single-source vulnerability concentrates in Canadian pea protein harvests exposed to climate variability. Distribution runs through hybrid direct-to-consumer platforms and conventional retail with divergent cold-chain requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The natural functional food market reads as a late-cycle quality story where health enthusiast demand shifts toward EFSA-validated, traceability-certified premium specifications that reward clinical investment over commodity positioning.
For Market Incumbents: Deploy hybrid fermentation platform expansion to defend against specialized probiotic developers with captive strain libraries. Deepen backward integration into algae oil production facilities near major formulation hubs to secure supply independence from marine harvest volatility. Accelerate EU Green Deal batch-level traceability certification ahead of regulatory window narrowing.
For New Entrants and Emerging Players: Precision fermentation infrastructure as a service offers white-space entry into contract manufacturing for mid-tier brands lacking in-house culture development. Target underpenetrated Polish conventional retail channels in Warsaw and Krakow with local-language labeled fermented beverages. Pursue microbiome testing platform partnerships as the primary go-to-market angle for subscription customer acquisition.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized probiotic developers possessing published strain-specific dossiers and academic research center partnerships. Long-term viability over the coming decade hinges on regulatory navigation capabilities across FDA, EFSA, and SAMR frameworks. Watch EFSA gut health claim evidentiary standard tightening as the inflection signal separating compliant from legacy fiber ingredient portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Fermentation Platform Expansion | Enables plant-dairy culture blending that satisfies German health enthusiast clean-label preferences without viability loss. |
| EFSA Health Claims Dossier Investment | Secures gut microbiota modulation approvals that unlock conventional retail shelf positioning in France and Netherlands. |
| Cold-Chain Infrastructure Partnership | Resolves ambient distribution constraints blocking ready-to-drink probiotic expansion into convenience retail channels. |
| Algae Oil Supply Agreement | Locks controlled-environment omega production capacity near Pacific Northwest formulation hubs for vegan positioning. |
| Microbiome Testing Platform Integration | Concentrates customer data ownership with subscription operators, eroding legacy supplement house retail loyalty. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation platform engineers, regulatory affairs leads at multinational manufacturers, category buyers at German conventional retail chains, and supply planners at grain procurement operations with secondary validation from FDA GRAS notifications, EFSA health claims registers, SAMR probiotic catalogs, and customs trade data on pea protein concentrate flows. Bottom-up strain-level demand modeling and top-down macro consumption pattern analysis provided triangulation.
Segment-weighting across product type, end user cohort, distribution channel, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory approval timelines and cold-chain infrastructure buildout rates. Forecast inputs incorporated EFSA guidance evolution on gut health evidentiary standards and algae oil production capacity expansion near major beverage formulation hubs.
The model holds under stable regulatory approval pathways and intact cold-chain investment cycles; deviation in SAMR catalog expansion timing or Canadian harvest volatility would shift volume and value trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Asia-Pacific Functional Mushroom Market
Functional Food and Beverage
APAC Functional Food Ingredients Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
Xanthohumol Market
Functional Food and Beverage
Spain Probiotic Drinks Market
Functional Food and Beverage
Tobacco Alternative Gum Market
Functional Food and Beverage
Functional Beverage Market
Functional Food and Beverage
Asia-Pacific Functional Water Market
Functional Food and Beverage
RTD Protein Beverages Market
Functional Food and Beverage
Grape Skin–Carob Synergy Antioxidant Systems Market
Functional Food and Beverage
Functional Water Market
Functional Food and Beverage
Global Functional Proteins Market
Functional Food and Beverage
Marine Functional Ingredients Market
Functional Food and Beverage
Functional Dairy Products Market
Functional Food and Beverage
Low Fat Product Market
Functional Food and Beverage
Beauty Drinks Market