
 Low Fat Product Market | 2026-2036
Low Fat Product Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Product Market Foresight
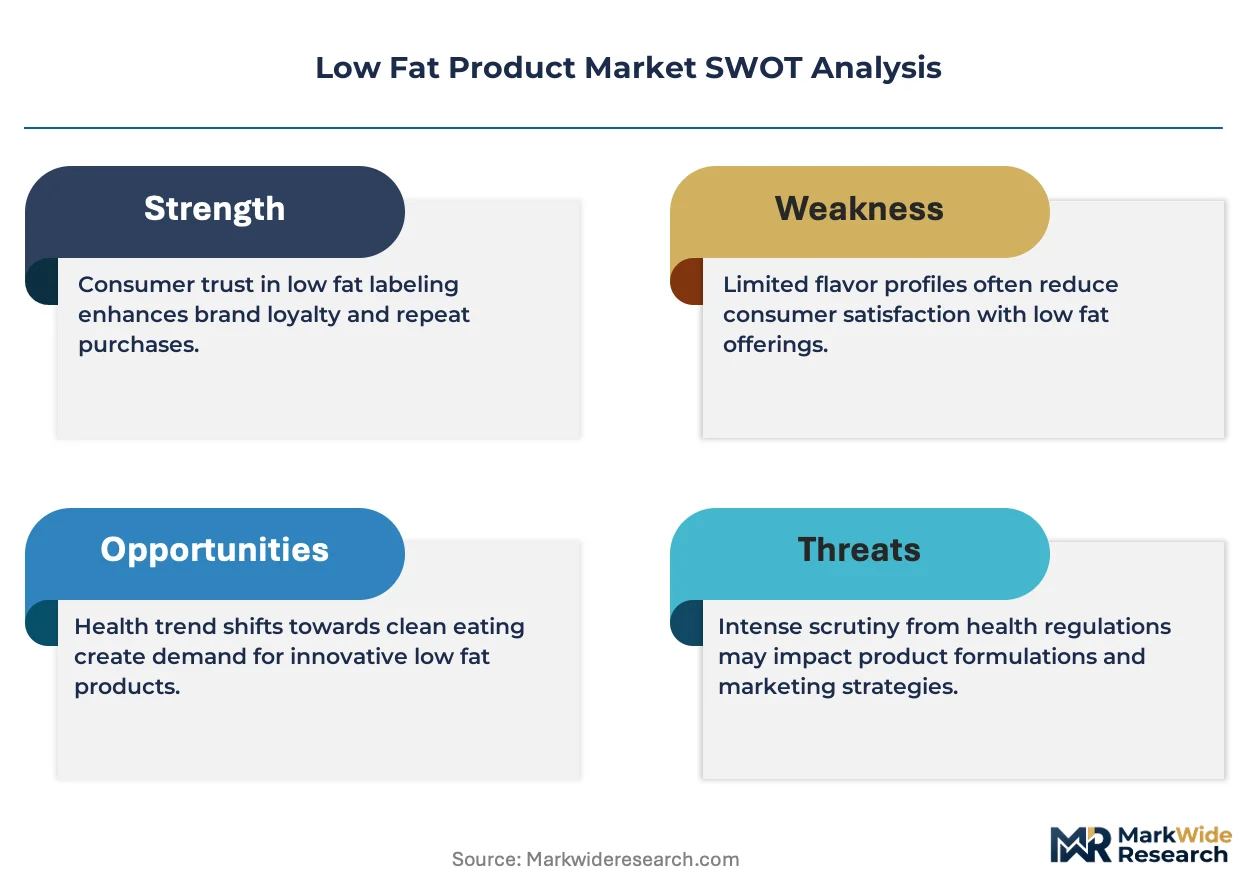
Supermarket buyer concentration is consolidating as Walmart, Kroger, and Tesco-style banners in North America and Europe reduce supplier rosters and demand exclusive low-fat product lines. Nestlé S.A. leverages its dairy R&D infrastructure to sustain formulation pipelines across European and Asian markets. Danone S.A. anchors its competitive position through plant-based yogurt specialization, while Unilever Plc competes on dressing and spread portfolios reformulated for reduced-fat claims.
Low fat products contain no more than three grams of fat per serving under FDA labeling guidelines, achieved through mechanical separation, enzymatic fat reduction, or fat-mimetic hydrocolloid substitution in dairy and plant-based matrices. These formulations serve commercial purposes ranging from calorie-controlled retail positioning to institutional healthcare catering and fitness-channel nutrition programming. Yogurt and snack bars occupy the largest margin pools as health-conscious consumers accept premium pricing for portable, portion-controlled formats. Plant-based ingredient sources represent the fastest-expanding segment as oat, almond, and pea protein bases displace traditional dairy in refrigerated cases.
FDA nutritional labeling standards, EU Health Claims Regulation under EFSA oversight, and FSSAI fat-content thresholds for processed foods collectively shape permissible marketing claims and reformulation targets across major supply jurisdictions. Compliance with these frameworks determines market access for imported low-fat products and influences domestic manufacturer R&D allocation. Stakeholders must monitor evolving front-of-pack warning label regimes and sugar-replacement ingredient approvals as regulators tighten the boundary between permissible low-fat positioning and prohibited health assertions.
Market Dynamics
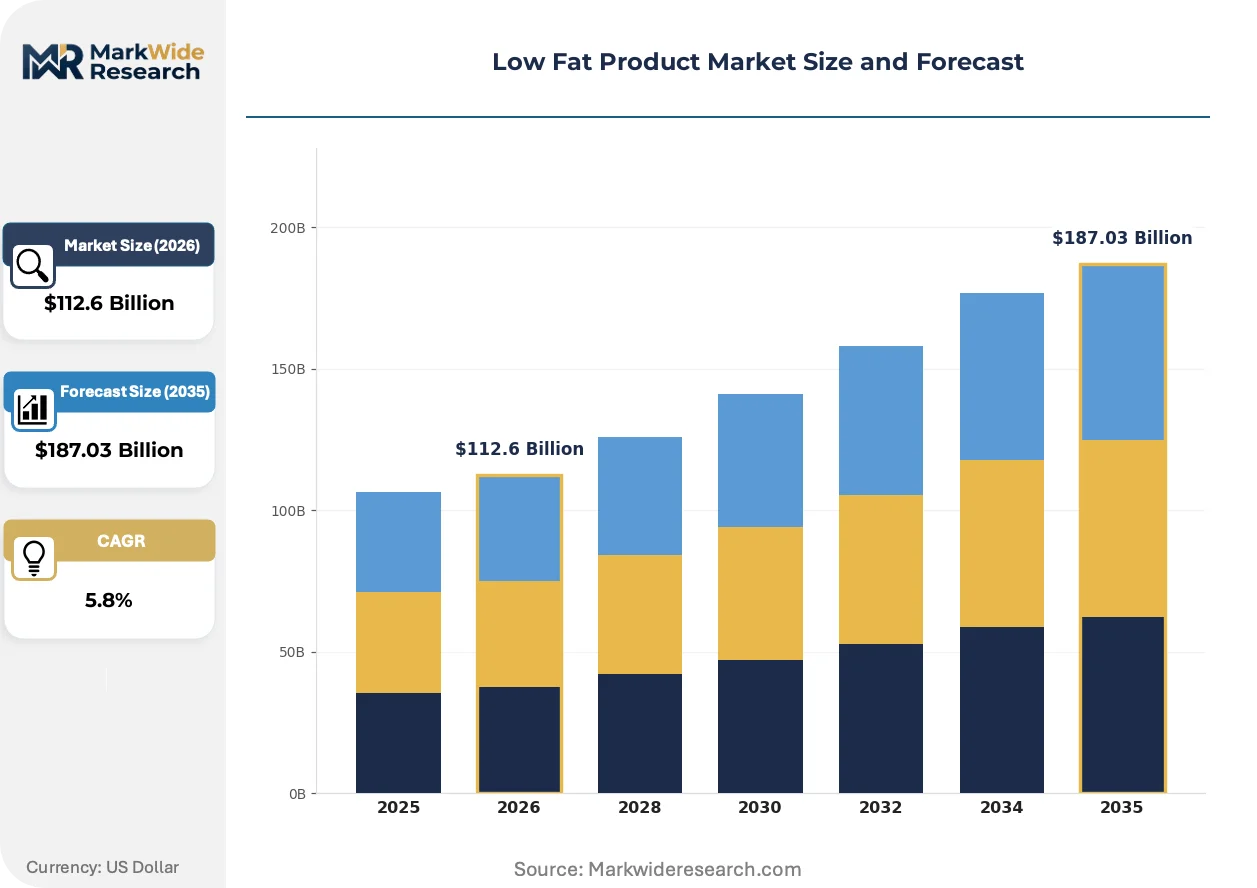
Supermarket buyer consolidation and FDA front-of-pack calorie disclosure mandates are compressing supplier margins while forcing simultaneous fat reduction and taste preservation investments across dairy and plant-based portfolios.
Growth Catalysts
- FDA Nutritional Labeling Requirements:Front-of-pack calorie disclosure rules pressure manufacturers to reformulate for reduced-fat claims to maintain retail shelf access in United States supermarket chains.
- Plant-Based Ingredient Technology:Oat, almond, and pea protein fat-mimetic hydrocolloids enable dairy-free low-fat formulations that capture health-conscious flexitarian demand in refrigerated cases.
- Urban Health Consciousness:Metropolitan consumers in United States, United Kingdom, and German retail environments prioritize certified low-fat SKUs in portable yogurt and snack bar formats.
Market Restraints
- Input Cost Volatility:Specialized hydrocolloid and protein isolate prices fluctuate with agricultural commodity cycles, compressing margins on reformulated low-fat dairy alternatives.
- Technical Taste Ceiling:Mechanical fat separation and enzymatic reduction methods face sensory limits where further fat removal degrades mouthfeel below consumer acceptance thresholds.
- Regulatory Fragmentation:Divergent EFSA health claim validation requirements versus FDA labeling standards force dual formulation tracks for European and United States market access.
Strategic Opportunities
- Institutional Healthcare Catering:Calorie-controlled hospital and senior living facility contracts seek reliable low-fat dairy and spread suppliers with consistent portion-controlled delivery.
- Fitness-Channel Nutrition Programming:Gym chains and wellness apps create private-label low-fat snack bar and yogurt partnerships with direct-to-consumer subscription models.
- EU Green Deal Alignment:Sustainable packaging mandates and carbon footprint labeling incentivize plant-based low-fat lines that qualify for preferential retail placement in French and Dutch supermarkets.
Industry Challenges
- Formulation Talent Scarcity:Food scientists skilled in enzymatic fat reduction and hydrocolloid stabilization command premium compensation, constraining R&D pipeline velocity at mid-tier manufacturers.
- Certification Timeline Compression:EFSA novel food approvals and FDA GRAS self-determinations for new fat-mimetic ingredients extend product launch cycles beyond retailer exclusive-line deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Product Market |
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $187.03 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yogurt, Cheese, Dressing, Snack Bars Ingredient Source: Plant-Based, Dairy, Animal, Others End User: Health Conscious Consumers, Fitness Enthusiasts, Dieters, Families Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Convenience Stores |
| Companies Covered | Nestlé S.A., Danone S.A., Unilever Plc, General Mills, Inc., Mondelez International, Kellogg's, Arla Foods, Kraft Heinz Company, Fonterra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Product Market Shifts & Advancements
Reformulation science and regulatory disclosure mandates are rewriting competitive rules. Manufacturers now race to preserve taste profiles while hitting strict fat-content thresholds, with technology and channel innovation determining who captures shelf space.
Precision fermentation-derived dairy proteins are converging with traditional enzymatic fat reduction systems to create hybrid low-fat matrices that replicate full-fat mouthfeel. Specialty cheese and yogurt manufacturers in the Netherlands and California adopt these combined approaches to maintain premium positioning. The convergence is compressing the performance gap between plant-based and dairy low-fat alternatives, forcing ingredient suppliers to defend their category boundaries.
EFSA's tightened health claim substantiation requirements under the EU Health Claims Regulation now demand clinical evidence for low-fat cardiovascular benefit assertions. This policy shift disqualifies marketing language that previously sufficed with generic nutritional references. Dairy processors targeting German and French retail banners must either fund expensive trials or retreat to factual compositional claims only.
Direct-to-fitness-channel procurement is displacing traditional broker-mediated supermarket negotiations for low-fat snack bar and ready-to-drink categories. Boutique wellness brands and gym chains now specify macronutrient profiles and exclusive flavor formulations directly with contract manufacturers. This pattern is most visible in United States coastal metropolitan markets where subscription nutrition boxes and app-integrated meal planning consolidate consumer loyalty outside conventional retail.
Low Fat Product Market Segmentation
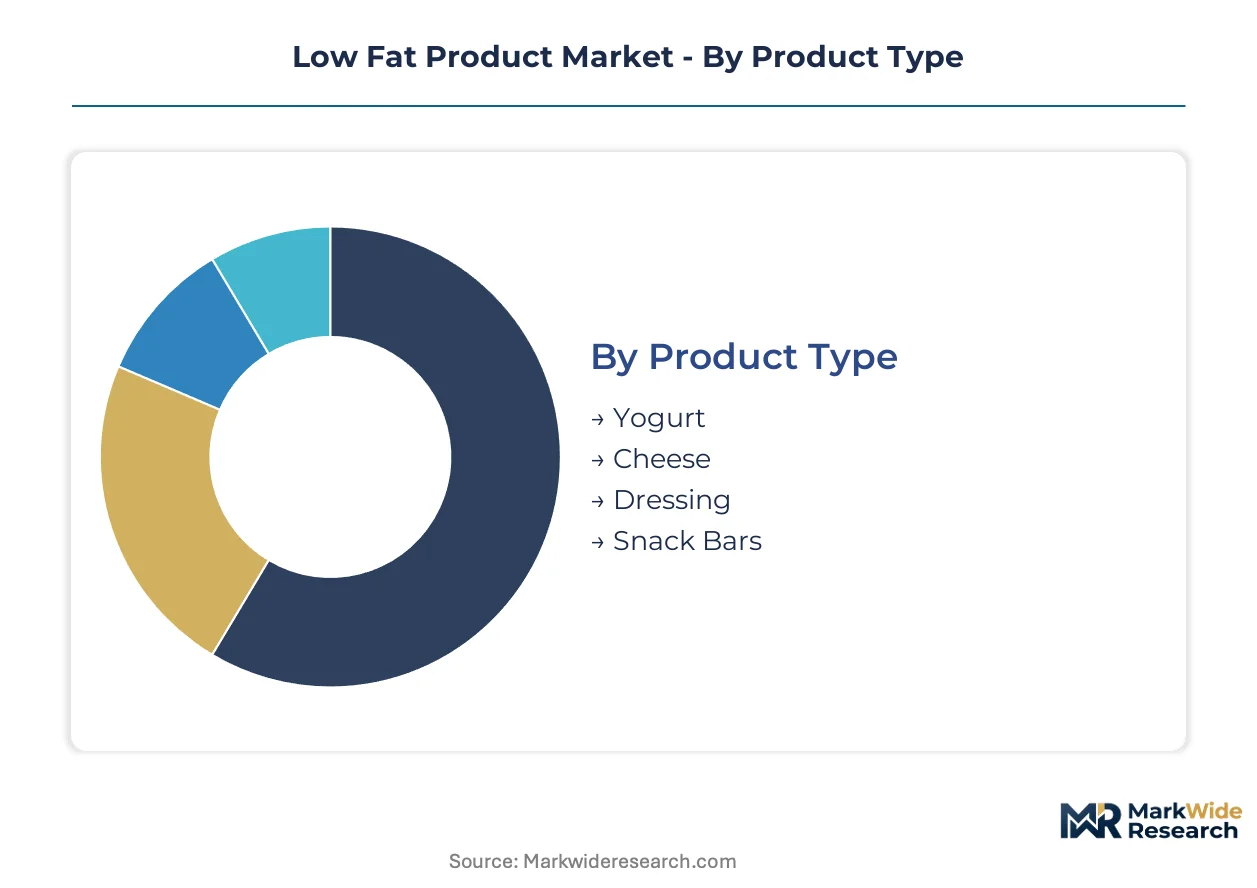
Low fat product manufacturers face divergent formulation requirements across consumer segments, with ingredient sourcing and channel access determining margin capture. Understanding where health-conscious buyers cluster versus where price-sensitive families shop shapes portfolio prioritization decisions.
Product Type:
Buyers in this category separate by consumption occasion and portability needs, with refrigerated formats commanding different shelf-space negotiations than ambient-stable alternatives.
- Yogurt:Fermented dairy or plant-based matrices with live cultures achieve fat reduction through mechanical separation or fat-mimetic hydrocolloids. Demand concentrates in United States urban supermarkets where portion-controlled cups and drinkable formats capture breakfast and on-the-go occasions.
- Snack Bars:Compressed cereal, protein, and fruit matrices bind with reduced-fat emulsifiers for shelf-stable portability. Fitness enthusiasts in United States coastal metropolitan markets drive direct-to-consumer subscription procurement for macronutrient-specified formulations.
- Cheese:Enzymatic fat reduction and modified milk protein concentrates create sliceable and spreadable formats for retail deli cases.
- Dressing:Emulsion-stabilized pourable and spoonable formats replace oil phases with hydrocolloid-thickened aqueous bases for salad and sandwich applications.
Yogurt leads volumes today; snack bars are gaining share fastest.
Ingredient Source:
Cost tier and sustainability positioning differentiate buyers, with premium flexitarians paying ingredient-story premiums while conventional shoppers prioritize price per serving.
- Plant-Based:Oat, almond, and pea protein bases displace dairy matrices through fat-mimetic hydrocolloid stabilization. German and French retail banners under EU Green Deal sustainability mandates grant preferential placement to carbon-labeled plant-based SKUs.
- Dairy:Traditional cow's milk fractions undergo mechanical separation and enzymatic modification to hit three-grams-per-serving thresholds. United States supermarket chains demand reformulated dairy lines to satisfy FDA front-of-pack calorie disclosure compliance and maintain shelf access.
- Animal:Reduced-fat meat, poultry, and egg derivatives serve institutional healthcare and specialized athletic nutrition contracts.
- Others:Precision fermentation-derived proteins and hybrid matrices blend dairy and non-dairy components for taste-optimized positioning.
Dairy leads volumes today; plant-based is expanding most quickly.
End User:
Application intensity and nutritional literacy separate buyers, with performance-driven users specifying macronutrient targets while general wellness seekers respond to front-of-pack claims.
- Health Conscious Consumers:Urban United States and United Kingdom shoppers prioritize certified low-fat labels and clean ingredient decks across yogurt and dressing categories.
- Fitness Enthusiasts:Gym-affiliated buyers in United States metropolitan markets specify protein-to-fat ratios through direct-to-consumer channels and subscription box partnerships.
- Dieters:Calorie-controlled program participants seek portion-controlled snack bars and single-serve dairy formats for compliance tracking.
- Families:Multi-person households balance child-acceptable taste profiles with parental health preferences in bulk-format supermarket purchases.
Health conscious consumers anchor volume today; fitness enthusiasts show the steepest expansion trajectory.
Distribution Channel:
Volume scale and margin structure differentiate buyers, with mass retail commanding exclusive line negotiations while specialty channels tolerate higher per-unit prices for curation.
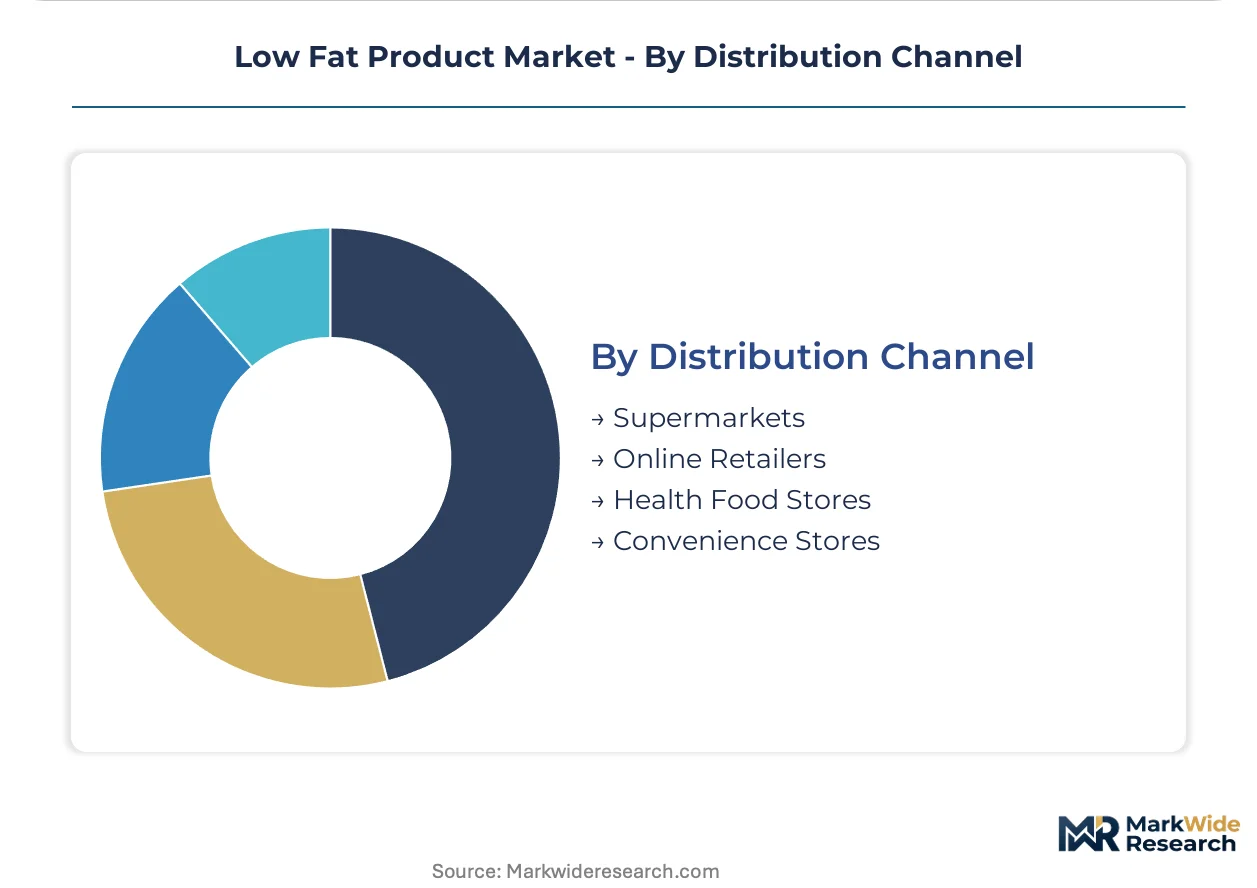
- Supermarkets:Walmart, Kroger, and Tesco-style banners consolidate supplier rosters and demand exclusive low-fat product lines with guaranteed fat-content compliance.
- Online Retailers:Amazon and direct-to-brand platforms enable subscription replenishment and personalized nutrition bundling for repeat-purchase yogurt and snack bar categories.
- Health Food Stores:Independent and chain specialty retailers curate plant-based and organic-certified low-fat assortments for ingredient-story-sensitive shoppers.
- Convenience Stores:Grab-and-go refrigerated cases in urban United States locations stock single-serve low-fat dairy and protein bars for immediate consumption.
Supermarkets dominate volume today; online retailers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States supermarket chains enforce stricter fat-content thresholds than German retailers, yet both markets now demand identical enzymatic reformulation capabilities from suppliers seeking shelf access.
United States
FDA front-of-pack calorie disclosure rules and Walmart-Kroger supplier roster consolidation drive reformulation investments. The agency mandates clear fat-content labeling for retail placement. California's precision fermentation cluster in South San Francisco supplies hybrid dairy proteins to yogurt manufacturers.
Germany
EFSA health claim substantiation requirements and EU Green Deal carbon labeling reshape permissible marketing language. The Federal Office of Consumer Protection and Food Safety enforces strict compositional standards. Bavaria's dairy processing corridor around Munich hosts enzymatic fat reduction R&D facilities.
France
Retail banner sustainability mandates and flexitarian demand expansion favor plant-based low-fat lines. ANSM oversees novel ingredient safety assessments for reformulated products. The Île-de-France region concentrates dairy alternative formulation labs serving Carrefour and Auchan.
United Kingdom
Tesco and Sainsbury's exclusive line negotiations and post-Brexit labeling divergence create compliance complexity. The Food Standards Agency maintains distinct thresholds from EU counterparts. London's food-tech cluster develops oat and pea protein fat mimetics for snack bar applications.
Netherlands
Green Deal preferential placement incentives and FrieslandCampina's R&D infrastructure attract plant-based investment. The Dutch Food and Consumer Product Safety Authority enforces strict novel food timelines. Wageningen's food innovation campus anchors European hydrocolloid stabilization research.
Low Fat Product Market Competitive Landscape
Swiss and French producers anchor one tier; Anglo-Dutch specialists hold formulation-driven positions. The market exhibits moderate consolidation with three distinct competitive layers: multinational dairy conglomerates with captive R&D, plant-based pure-plays leveraging sustainability positioning, and private-label contract manufacturers serving fitness-channel procurement. Strategic moves center on enzymatic technology licensing and exclusive retail line negotiations.
Within the multinational tier, Nestlé S.A. and Danone S.A. exemplify divergent archetypes—one leveraging integrated dairy infrastructure, the other anchoring plant-based specialization. Unilever Plc occupies a position spanning dressing and spread reformulation. These three represent the dominant competitive anchors against which mid-tier manufacturers and contract specialists benchmark portfolio decisions.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Danone S.A. |
| Unilever Plc |
| General Mills, Inc. |
| Mondelez International |
| Kellogg's |
| Arla Foods |
| Kraft Heinz Company |
| Fonterra |
| Others |
Supply & Pricing Matrix
EU Green Deal carbon labeling mandates gate qualified supply access and premium-tier pricing power for reformulated low-fat portfolios. Manufacturers lacking verified sustainability credentials face exclusion from preferential retail placement in French and Dutch supermarkets while certified competitors command ingredient-story premiums.
Pricing Analysis
Capacity additions in precision fermentation clusters are reshaping price floors for hybrid dairy proteins. Three-tier pricing structure across premium, standard, and economy levels separates precision fermentation-enhanced formulations from conventional enzymatic reduction and basic mechanical separation tiers. Cost compression in mid-tier dairy alternatives is intensifying because oat and pea protein isolate prices fluctuate with agricultural commodity cycles. Families purchasing bulk-format supermarket SKUs exhibit highest price sensitivity; fitness enthusiasts specifying macronutrient profiles through direct-to-consumer channels tolerate premium positioning.
Supply Chain Analysis
Direct-to-fitness-channel procurement displaces traditional broker-mediated supermarket negotiations for snack bar and ready-to-drink categories. Supply concentration centers on the Netherlands for hydrocolloid stabilization R&D, the United States for precision fermentation-derived proteins, and Germany for enzymatic fat reduction equipment. Formulation pipelines draw from specialized hydrocolloids, protein isolates, and modified milk protein concentrates. Single-source vulnerability in precision fermentation capacity creates bottleneck risk for hybrid matrix launches. Distribution runs through mass retail banners, direct-to-brand platforms, and institutional healthcare contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity into structural advantage. FDA front-of-pack calorie disclosure rules and EFSA health claim substantiation requirements create compliance moats that favor scaled incumbents with dedicated regulatory affairs infrastructure.
For Market Incumbents: Anchor defensive positioning through captive enzymatic technology licensing and exclusive retail line negotiations with Walmart-Kroger-Tesco banners. Consolidate formulation talent scarcity by acquiring mid-tier contract manufacturers in Bavaria's dairy processing corridor. Vertical integration into precision fermentation capacity insulates against hybrid protein supply bottlenecks.
For New Entrants and Emerging Players: Precision fermentation-derived fat mimetics offer technology-first wedge positioning against established hydrocolloid suppliers. Target direct-to-fitness-channel procurement in United States coastal metropolitan markets where subscription nutrition boxes consolidate consumer loyalty outside conventional retail. Pursue white-space in institutional healthcare catering contracts for calorie-controlled hospital and senior living facility supply.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier contract manufacturers with FDA and EFSA compliance capabilities because certification timeline compression extends product launch cycles beyond retailer exclusive-line deadlines. Long-term viability hinges on formulation talent access and regulatory infrastructure depth. Watch EFSA novel food approval velocity as inflection indicator for European market entry feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Hybrid dairy proteins from South San Francisco clusters replicate full-fat mouthfeel for premium yogurt positioning. |
| EFSA Health Claim Clinical Investment | Cardiovascular benefit substantiation trials enable permissible marketing language in German and French retail. |
| Exclusive Retail Line Negotiation | Walmart-Kroger supplier roster consolidation demands guaranteed fat-content compliance for shelf access. |
| Direct-to-Fitness-Channel Partnership | Gym chain and wellness app procurement displaces traditional broker-mediated supermarket negotiations. |
| Sustainability Certification Program | EU Green Deal carbon labeling qualifies plant-based SKUs for preferential placement in Dutch supermarkets. |
Research Methodology
Coverage spans the United States, Germany, France, the United Kingdom, and the Netherlands, with primary inputs from each. The analysis combines structured interviews with food formulation scientists, supermarket category buyers, regulatory affairs specialists, and contract manufacturing executives with secondary validation from FDA GRAS notifications, EFSA novel food approvals, EU Green Deal implementation documents, and retail audit data. Bottom-up SKU-level demand modeling triangulates against top-down macroeconomic consumption trends.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions include product type, ingredient source, end user archetype, and distribution channel, with regulatory jurisdiction clusters treated as orthogonal forecast modifiers. CAGRs derive from iterative convergence of demand-side adoption curves and supply-side capacity expansion schedules. Precision fermentation capacity buildout timelines and EFSA approval velocity serve as key industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory fragmentation between FDA and EFSA standards, agricultural commodity price volatility, and taste-profile acceptance thresholds for enzymatic fat reduction. Forecasts reflect documented assumptions about health-conscious consumer willingness to pay premium pricing and supermarket buyer consolidation trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Japan Functional Drinks Market
Functional Food and Beverage
Keto Diet Market
Functional Food and Beverage
Saudi Arabia Protein Bar Market
Functional Food and Beverage
Functional Food and Beverage Market
Functional Food and Beverage
Functional Tea Market
Functional Food and Beverage
Fermented Protein Market
Functional Food and Beverage
Mediterranean Lemon Bioflavonoid Shot Bases Market
Functional Food and Beverage
Hydrogen Water Market
Functional Food and Beverage
Oat Beta-Glucan Market
Functional Food and Beverage
Non-GMO Verified Sports Drink Market
Functional Food and Beverage
Very Low Calorie Desserts Market
Functional Food and Beverage
Zero-Fat Protein Market
Functional Food and Beverage
Probiotic Drink Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Asia-Pacific Beauty Drinks Market
Functional Food and Beverage
Asia-Pacific Functional Water Market