
 Reduced Sugar Food and Beverages Market | 2026-2036
Reduced Sugar Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Reduced Sugar Food and Beverages Market Intelligence
The shift toward asset-light business models, where brands outsource capital-intensive production, is narrowing the competitive field to entities with strong supply chain control and R&D capabilities. Nestlé S.A. leverages its extensive R&D infrastructure to pioneer novel sweetener formulations. Danone S.A. specializes in dairy and plant-based alternatives with reduced sugar content, aligning its portfolio with wellness-focused consumers. Cargill Inc. operates as a key ingredient supplier, providing a range of sugar alternatives to major food and beverage manufacturers.
Reduced sugar food and beverages are products reformulated to contain significantly less sucrose than their traditional counterparts. This is typically achieved by substituting sugar with high-intensity sweeteners like stevia or sugar alcohols, which necessitates careful formulation to replicate the texture and mouthfeel of the original product. Its primary purpose is to lower the caloric content and glycemic impact for consumers. Within product types, Soft Drinks command the largest share, while Dairy Alternatives are expanding most rapidly, especially among Health-Conscious Consumers.
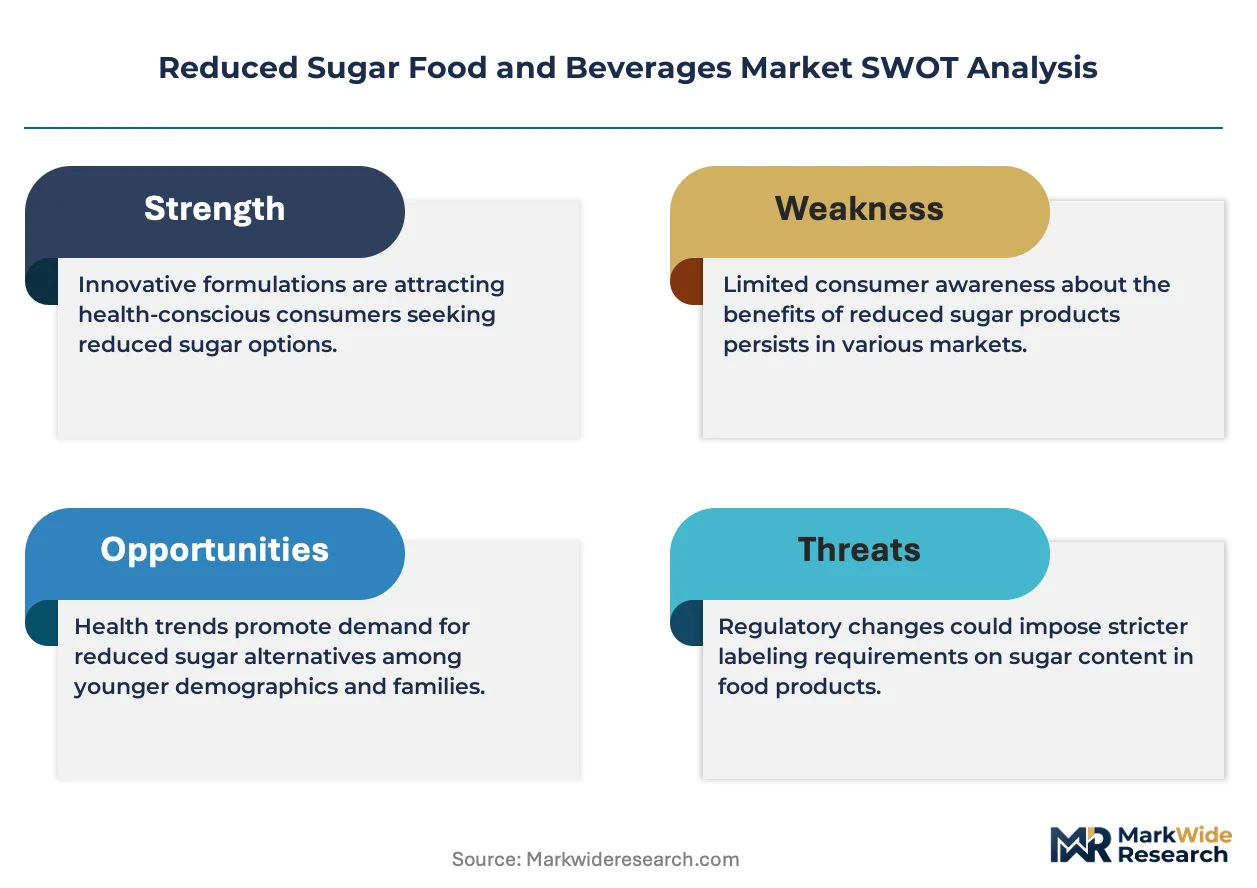
Product formulation and marketing are shaped by a complex web of international regulations. The US FDA's updated Nutrition Facts label mandates disclosure of added sugars, while the European Food Safety Authority (EFSA) governs health claims on reduced-sugar products. Concurrently, agencies like India's FSSAI define permissible sweetener use and labeling standards. Stakeholder success depends on navigating these disparate regulatory landscapes while maintaining consumer trust in alternative sweetener safety.
Market Dynamics
Regulatory pressure from public health bodies and fiscal policies like sugar taxes is the central force compelling food and beverage manufacturers to accelerate reformulation, shifting R&D priorities and supply chain sourcing toward sugar alternatives.
Growth Catalysts
- Public Health Policy:Fiscal measures, including the UK's Soft Drinks Industry Levy and similar taxes in Mexico, create a direct financial incentive for manufacturers to reduce sugar content in beverages to avoid penalties and maintain price competitiveness.
- Diabetic and Pre-diabetic Populations:Expanding consumer bases with specific dietary needs, particularly diabetics, actively seek products with a low glycemic impact, creating a dedicated demand channel for reduced sugar foods and beverages.
- Advances in Sweetener Technology:The commercialization of novel high-intensity sweeteners and sugar alcohols provides formulators with more tools to mimic the sensory properties of sucrose, enabling the development of more palatable reduced-sugar products.
Market Restraints
- Ingredient Cost Disparity:Many sugar alternatives, such as erythritol or certain stevia extracts, carry a higher unit cost than sucrose, creating margin pressure for manufacturers, especially in price-sensitive product categories.
- Formulation Complexity:Replicating the functional properties of sugar, including its role in texture, browning, and preservation, is a significant technical hurdle that requires extensive R&D investment and expertise in food science.
- Inconsistent Regulatory Approvals:A lack of global harmonization in sweetener regulations, with bodies like the FDA and EFSA having different approval lists and usage levels, complicates product development for multinational brands.
Strategic Opportunities
- Emerging Market Penetration:Rising health consciousness and disposable incomes in markets across Southeast Asia and Latin America present significant white space for reduced sugar products, particularly in the beverage and dairy categories.
- Clean Label Formulations:An opportunity exists to develop products using natural, recognizable sweeteners like monk fruit or allulose, catering to consumer demand for "clean label" ingredient lists that avoid artificial-sounding names.
- Functional Food Integration:Incorporating reduced sugar formulations into functional foods, such as protein bars or fortified yogurts, allows brands to stack health benefits and appeal to wellness-focused consumer segments.
Industry Challenges
- Managing Consumer Perception:Manufacturers face the ongoing challenge of building and maintaining consumer trust regarding the safety and taste of alternative sweeteners, often combating misinformation and negative media coverage.
- Supply Chain Stability:The supply of plant-derived sweeteners like stevia is subject to agricultural variables such as crop yield and quality, introducing potential volatility in both price and availability for ingredient procurement.
- Talent Scarcity:A shortage of experienced food scientists who can effectively work with complex sweetener systems can act as a bottleneck for new product development and innovation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reduced Sugar Food and Beverages Market |
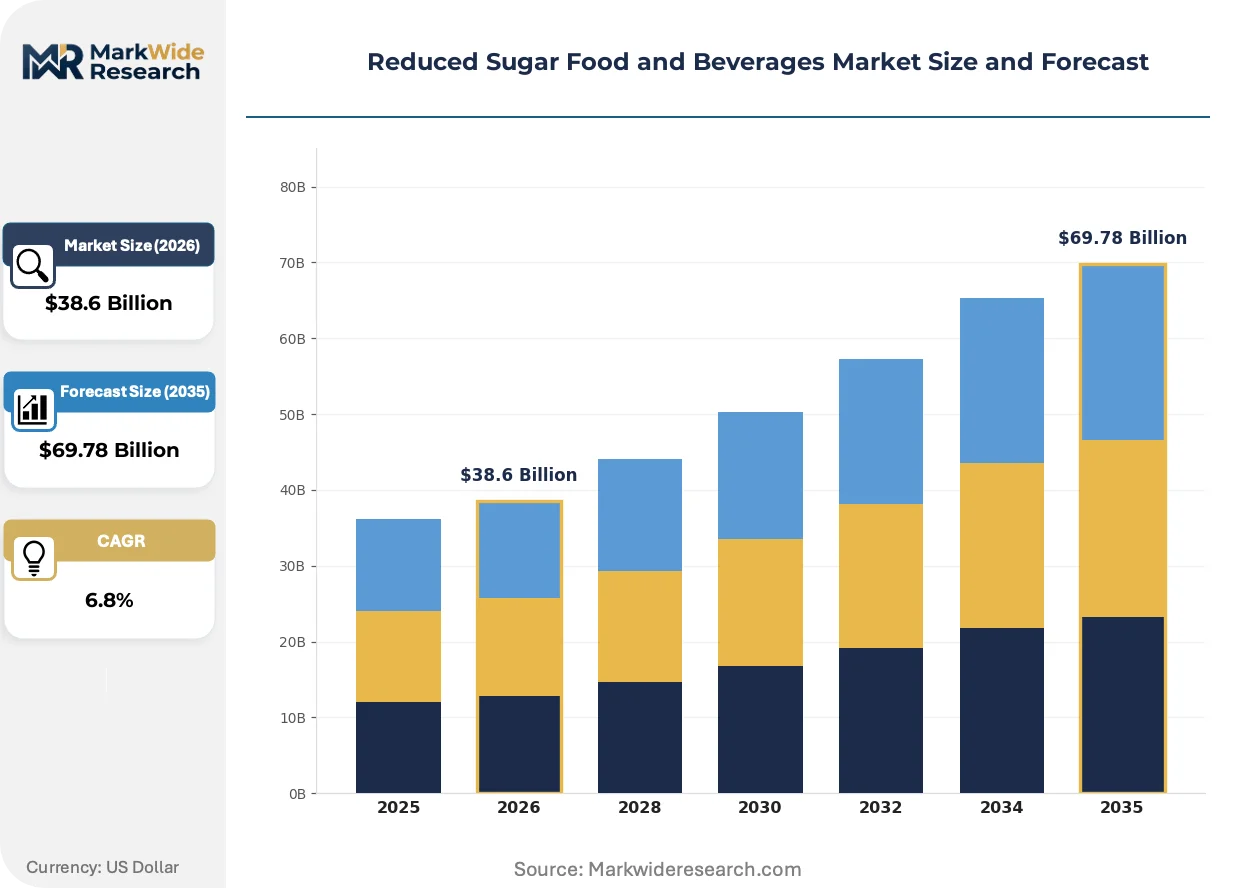
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Drinks, Snacks, Dairy Alternatives, Sauces End User: Health-Conscious Consumers, Families, Diabetics, Athletes Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales Packaging Type: Bottles, Boxes, Cartons, Pouches |
| Companies Covered | The Coca-Cola Company, PepsiCo, Nestlé S.A., Mondelēz International, Unilever, The J. M. Smucker Company, Danone S.A., Cargill Inc., Kraft Heinz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reduced Sugar Food and Beverages Market Strategic Shifts & Innovations
Advanced formulation science is intersecting with evolving consumer expectations for transparency and naturalness. This dynamic is pushing the industry beyond simple sugar reduction toward a more holistic approach to product health profiles and ingredient sourcing.
Precision fermentation is a key enabling technology for producing rare sugars like allulose and specific steviol glycosides at scale. Major food and beverage conglomerates are adopting this method to secure a stable supply of high-purity, non-caloric sweeteners. This biomanufacturing process is rendering obsolete traditional, less efficient agricultural extraction methods for many plant-based sweeteners.
India’s FSSAI is tightening its regulations on permissible sweeteners and is advancing proposals for mandatory front-of-pack labeling. This policy shift forces both domestic and multinational companies operating in India to reformulate products to meet new health-oriented standards. The traditional sweets and mass-market beverage segments are most affected, spurring investment in compliant, locally acceptable formulations.
A consumer pivot from "low sugar" claims to a preference for "clean label" and naturally sweetened products is reshaping purchasing criteria. This shift disrupts the market for items using traditional artificial sweeteners, as consumers now scrutinize ingredient lists for recognizable names like monk fruit or fruit extracts. This behavior is most prominent in the dairy alternatives and children's food categories in North America.
Reduced Sugar Food and Beverages Market Segmentation
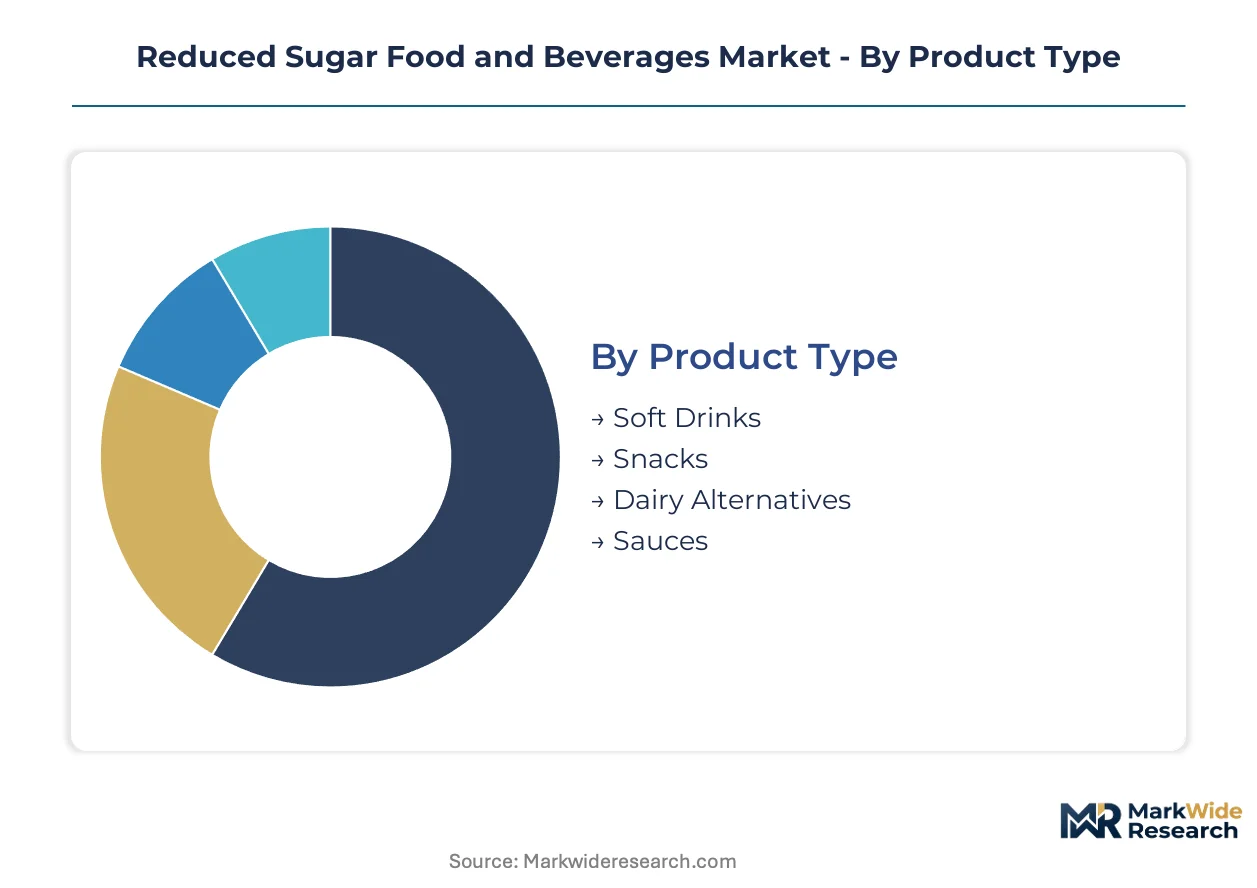
The reduced sugar food and beverages market exhibits diverse characteristics across various categories, reflecting complex consumer preferences and evolving industry dynamics. Understanding these segmentations provides clarity on where product innovation, marketing efforts, and supply chain investments yield the most significant returns for market participants.
Product Type:
The after-sales service intensity for reduced sugar food and beverages varies significantly across product types, influencing consumer loyalty and repeat purchases.
- Soft Drinks:These beverages are reformulated to contain significantly less sucrose than traditional carbonated or still options, often utilizing high-intensity sweeteners like aspartame or sucralose. Demand concentrates heavily in the United States due to strong consumer health trends and widespread retail availability.
- Dairy Alternatives:Products in this segment, such as almond, oat, or soy milks, offer reduced sugar content while maintaining nutritional profiles, catering to lactose-intolerant or vegan consumers. This category is expanding most rapidly, particularly among health-conscious consumers seeking plant-based options.
- Snacks:This category includes reduced sugar cookies, bars, and confectionery, formulated to offer indulgence with lower caloric impact.
- Sauces:Reformulated condiments like ketchup, dressings, and marinades provide reduced sugar options for consumers managing dietary intake.
By volume, Soft Drinks lead. By growth pace, Dairy Alternatives are expanding most quickly.
End User:
Understanding the specific dietary needs and purchasing behaviors of different end-user segments is crucial for tailoring product development and marketing strategies.
- Diabetics:This segment comprises individuals managing blood sugar levels, actively seeking products with a low glycemic impact to support their health regimen. Product adoption among diabetics is a key demand driver for the overall market.
- Health-Conscious Consumers:These individuals prioritize wellness and actively scrutinize ingredient lists, opting for products with natural sweeteners and clean label formulations. This group significantly influences product innovation in North America.
- Families:This segment often seeks healthier options for children, driving demand for reduced sugar products that balance taste with nutritional considerations.
- Athletes:Athletes require products that support energy levels and recovery without excessive sugar, often preferring functional reduced sugar options like protein drinks or bars.
Each end-user group presents distinct demand drivers, with health outcomes and lifestyle choices significantly shaping consumption patterns.
Distribution Channel:
Supply concentration within distribution channels determines product accessibility and pricing power for reduced sugar options.
- Supermarkets:These large-format retail stores represent a primary channel for reduced sugar products, offering broad consumer reach and diverse product assortments across various brands. They benefit from high foot traffic and established supply chains.
- Online Retail:E-commerce platforms provide convenience and a wider selection of niche reduced sugar products, catering to consumers who prefer home delivery or specialized dietary options. This channel facilitates market entry for smaller brands.
- Health Stores:Specialty health food stores cater to consumers specifically seeking organic, natural, or diet-specific reduced sugar items.
- Direct Sales:This channel includes direct-to-consumer models or brand-owned stores, offering a controlled brand experience and direct feedback loop.
Channel effectiveness hinges on consumer convenience and product visibility, with digital platforms increasingly complementing traditional retail footprints.
Packaging Type:
Packaging type often correlates with cost tiers and consumer perception of value, impacting the overall market positioning of reduced sugar products.
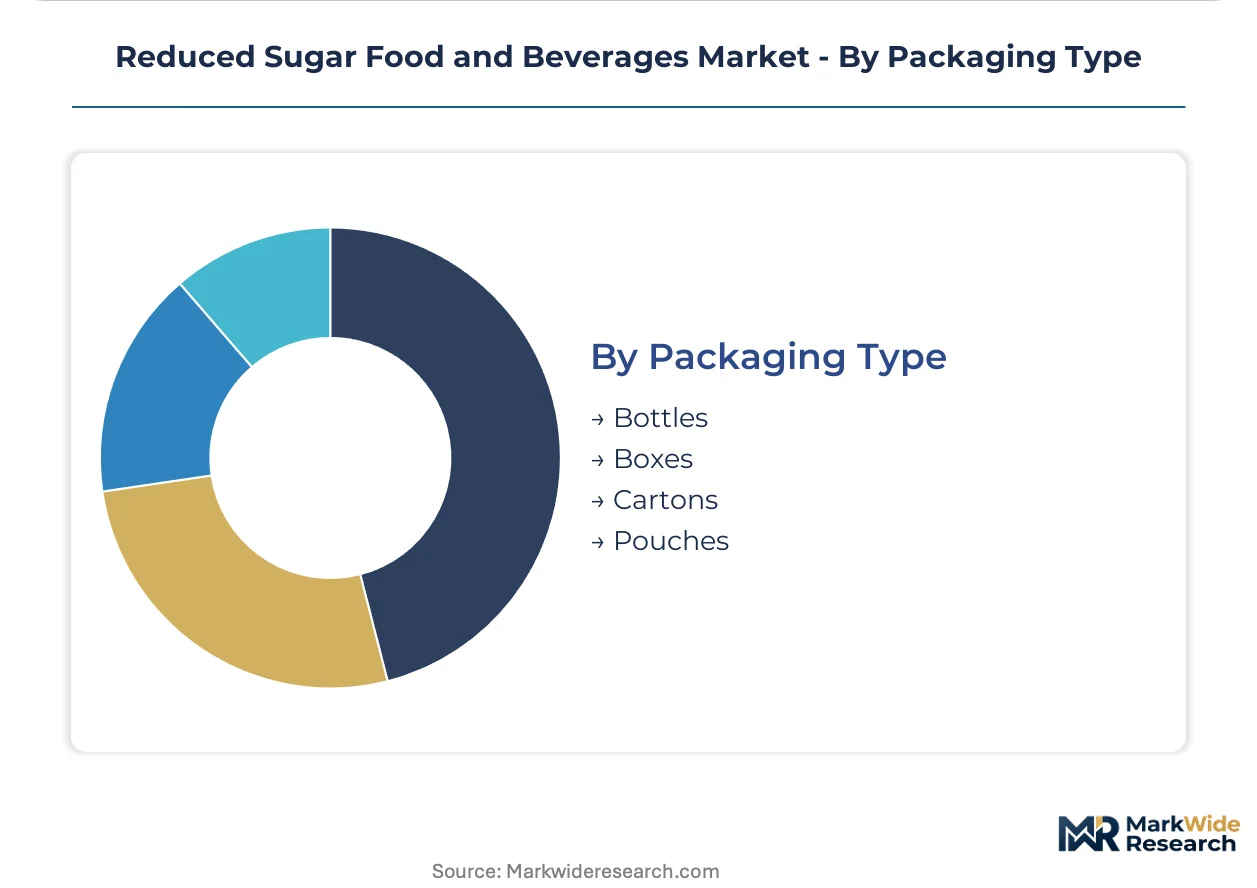
- Bottles:Primarily used for soft drinks and other beverages, bottles offer resealability and portability, with materials ranging from PET plastic to glass. This format commands a significant share in the beverage segment.
- Cartons:Common for dairy and plant-based alternatives, cartons provide extended shelf life and often feature sustainable material options. Their use is expanding with the growth of dairy alternatives.
- Boxes:This format is typically used for reduced sugar snacks, cereals, or dry mixes, offering protection and space for branding.
- Pouches:Flexible pouches are gaining traction for portion-controlled snacks, purees, and beverages, valued for their convenience and reduced material use.
Beyond containment, packaging innovation focuses on sustainability and extended shelf life, influencing material choices and design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious consumers and diabetic populations drive significant demand for reduced sugar food and beverages. These buyer archetypes actively seek products with lower caloric content and glycemic impact. Their purchasing patterns influence product innovation and market growth across key geographies.
United States
Health-conscious consumers significantly influence product innovation in the United States. The US FDA's updated Nutrition Facts label mandates disclosure of added sugars, prompting reformulation efforts. Major food and beverage manufacturers in California and New York are investing heavily in new sweetener technologies.
United Kingdom
Fiscal policies like the UK's Soft Drinks Industry Levy create strong incentives for manufacturers to reduce sugar content. This policy directly impacts beverage producers, pushing them towards sugar alternatives. London-based food and beverage companies are leading in developing new compliant product lines.
India
Rising health consciousness and evolving dietary preferences drive demand for reduced sugar options in India. India’s FSSAI is tightening its regulations on permissible sweeteners and advancing proposals for mandatory front-of-pack labeling. Major food manufacturers in Mumbai and Delhi are adapting their portfolios to meet these new health-oriented standards.
Mexico
Regulatory measures, including sugar taxes, compel reformulation efforts among beverage manufacturers in Mexico. These fiscal policies create a direct financial incentive to reduce sugar content and avoid penalties. Mexico City-based companies are focusing on developing affordable, reduced-sugar alternatives for mass-market consumption.
Germany
European consumers increasingly seek reduced sugar products, particularly in the dairy and plant-based alternative categories. The European Food Safety Authority (EFSA) governs health claims on reduced-sugar products, ensuring consumer trust. Food research centers in Bavaria are pioneering novel sweetener formulations for the European market.
Reduced Sugar Food and Beverages Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered market structure. Large food and beverage conglomerates leverage extensive R&D capabilities and robust supply chain control. Smaller, agile brands often focus on niche segments like clean label or functional foods, emphasizing specific dietary needs. Portfolio diversification into plant-based or natural sweetener categories is a common strategic move, alongside strategic partnerships for ingredient sourcing.
Among the diversified conglomerates, Nestlé S.A. exemplifies extensive R&D infrastructure, supporting novel sweetener formulations. Danone S.A., a France-based public limited company, occupies a strong position in dairy and plant-based alternatives with reduced sugar content. Cargill Inc., a global corporation, represents a critical ingredient supplier, providing a range of sugar alternatives to major food and beverage manufacturers worldwide. These entities collectively anchor different facets of the reduced sugar market, from end-product manufacturing to foundational ingredient supply.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo |
| Nestlé S.A. |
| Mondelēz International |
| Unilever |
| The J. M. Smucker Company |
| Danone S.A. |
| Cargill Inc. |
| Kraft Heinz |
| Others |
Cost & Logistics Intelligence
Underutilized precision fermentation capacity in North America for rare sugars drives both supplier behavior and pricing posture for novel sweeteners. This dynamic influences ingredient availability and the cost structure for advanced reduced-sugar formulations across the industry.
Pricing Analysis
Quality grade of sweetener formulations creates the primary spread in ingredient pricing. Transactional pricing dominates for bulk sugar alternatives, while value-based pricing applies to specialized, clean-label blends. Price differentiation stems from R&D intensity required for complex texture replication. Pricing pressure stems from the higher unit cost of many sugar alternatives compared to sucrose. Mass-market consumers exhibit high price sensitivity for finished goods, while health-conscious buyers accept premiums for natural sweeteners.
Supply Chain Analysis
Contract manufacturing of novel sweeteners concentrates in specialized facilities in the United States and Europe, particularly for precision-fermented ingredients. The supply chain draws from raw materials such as stevia leaf extracts from Southeast Asia and monk fruit from China. Regulatory approval inconsistencies across regions represent a structural supply chain risk. Distribution runs through established supermarket networks and increasingly via online retail platforms, ensuring broad product accessibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reduced sugar food and beverages market is an early-cycle expansion story, driven by a significant tailwind in health-conscious consumer adoption and proactive regulatory measures.
For Market Incumbents: Harden intellectual property around novel sweetener blends to counter emerging ingredient suppliers. Focus R&D infrastructure on replicating sugar's functional properties beyond sweetness, addressing formulation complexity. This defensive strategy mitigates margin pressure from ingredient cost disparity. Deepen supply chain control for key alternative sweeteners to ensure stability against agricultural variables.
For New Entrants and Emerging Players: Build out product lines targeting clean label formulations in underpenetrated segments like children's food and dairy alternatives. Southeast Asia presents significant white space for market penetration due to rising health consciousness. A direct-to-consumer go-to-market angle emphasizing ingredient transparency can capture wellness-focused consumer segments efficiently.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among ingredient suppliers specializing in proprietary sweetener technologies. Long-term viability for the market is underpinned by sustained public health focus and continuous innovation in taste and texture. Acquisition target archetypes include niche brands with strong clean label positioning or technology firms advancing precision fermentation. Global harmonization of sweetener regulations is a signal to watch for accelerated market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Sweetener R&D | Secures unique formulations for taste and texture replication, differentiating products from competitors. |
| Precision Fermentation Investment | Ensures stable, high-purity supply of rare sugars like allulose for consistent product quality. |
| Clean Label Brand Acquisition | Expands portfolio into consumer-preferred natural segments, aligning with evolving purchasing criteria. |
| Emerging Market Distribution Expansion | Captures new demand from rising health consciousness in regions like Southeast Asia. |
| Functional Food Integration | Stacks health benefits appealing to wellness-focused consumers, enhancing product value proposition. |
Research Approach
A spread of perspectives from food scientists, R&D directors, regulatory affairs specialists, and procurement leads converged on the working assumptions for this study. Primary interviews with industry stakeholders were validated against secondary data from FDA filings, EFSA reports, FSSAI regulations, and industry association reports. This approach facilitated bottom-up and top-down triangulation.
Demand-supply balance analysis informed the analytical framework across the analysis window. Segmentation dimensions modeled included product type, end-user, distribution channel, packaging type, and specific sweetener types. Compound annual growth rates were derived through regression analysis, incorporating expert consensus. Public health policy changes and sweetener technology advancements served as key forecast inputs.
Practitioners should monitor regulatory shifts and consumer perception changes for early signals impacting market trajectory. Forecasts reflect assumptions documented through extensive research. Quarterly review of regulatory updates and consumer sentiment indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Marine Functional Ingredients Market
Functional Food and Beverage
Europe Functional Beverages Market
Functional Food and Beverage
Functional Coffee Market
Functional Food and Beverage
Low Fat and Low Cholesterol Diet Foods Market
Functional Food and Beverage
Global CBD Beverages Market
Functional Food and Beverage
North America Functional Beverage Market
Functional Food and Beverage
Probiotic Drink Market
Functional Food and Beverage
Functional Soda Market
Functional Food and Beverage
Asia-Pacific Beauty Drinks Market
Functional Food and Beverage
Vitamin Functional Water Market
Functional Food and Beverage
Mediterranean Healthy-Aging Beverage Ingredients Market
Functional Food and Beverage
RTD Protein Beverages Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
Hydrogen Water Market
Functional Food and Beverage
Yeast Beta Glucan Market