
 Global L-Arginine Market | 2026-2036
Global L-Arginine Market Size, Share, and Industry Trends Forecast 2026-2036
Global L-Arginine Market Outlook
A capital-intensity divergence between fermentation-based and synthetic-route producers is collapsing as Chinese manufacturers achieve comparable batch yields at lower fixed-asset thresholds. Ajinomoto leverages its proprietary Corynebacterium fermentation platform to sustain premium pricing in pharmaceutical-grade supply chains. Kyowa Hakko Bio anchors Japanese domestic demand through kosher and halal-certified production lines. Evonik competes in Europe with microbial strain optimization that reduces downstream purification costs.
L-arginine is a conditionally essential amino acid with the molecular formula C6H14N4O2, typically manufactured through microbial fermentation of glucose or hydrolysis of protein-rich substrates, and functions as a nitric oxide precursor in vascular endothelium and protein synthesis pathways. Powder formulations dominate bulk pharmaceutical procurement due to blending flexibility and lower unit logistics costs, while liquid formats occupy pediatric and geriatric delivery niches where swallowing difficulties limit solid-dose uptake. Sports nutrition end users concentrate margin pools in branded pre-workout blends, whereas cardiovascular health applications in clinical settings require USP-grade certification that restricts supplier pools.
FDA cGMP enforcement for dietary supplements and EFSA novel food assessments shape ingredient qualification timelines on opposite sides of the Atlantic, while China's NMPA and GB standards govern import registration for finished dosage forms containing L-arginine. REACH registration requirements in Europe further constrain non-EU raw material entrants lacking toxicological dossiers. Stakeholders must monitor evolving pharmacopeial monograph harmonization between USP, EP, and ChP standards to anticipate qualification cost shifts that could reroute procurement toward multi-compendial certified suppliers.
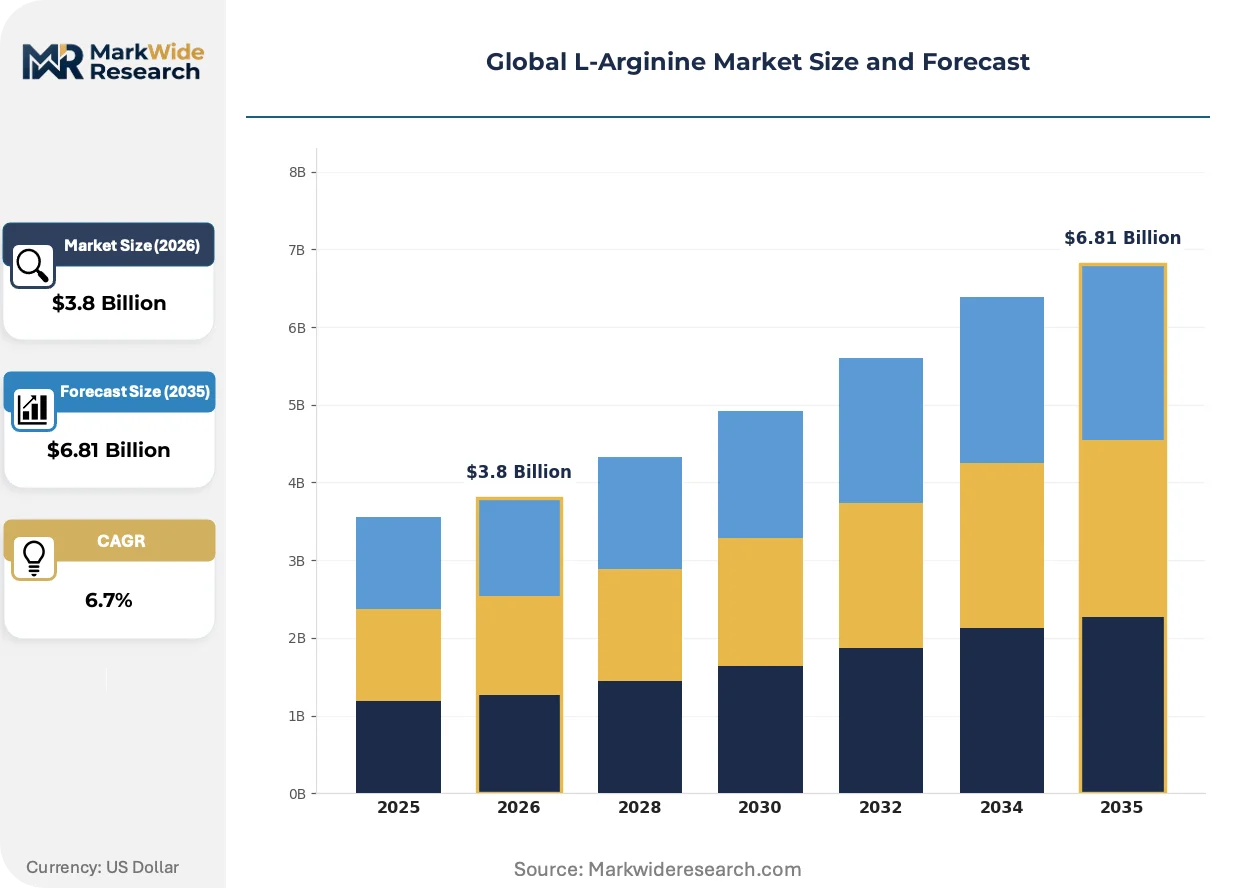
Market Dynamics
Fermentation-based manufacturing is consolidating cost advantages over synthetic chemical routes as Chinese producers achieve pharmaceutical-grade yields at reduced fixed-asset intensity, compressing margin structures for incumbent suppliers.
Growth Catalysts
- Sports nutrition formulation expansion:Pre-workout supplement brands in the United States are elevating L-arginine dosing in nitric-oxide-boosting blends, pulling volume through direct-to-consumer channels.
- Cardiovascular clinical protocols:USP-grade certification requirements for hospital and clinic procurement are tightening supplier qualification standards, favoring established multi-compendial manufacturers.
- REACH registration completion:European toxicological dossier submissions by Asian raw material suppliers are unlocking EU pharmaceutical and dietary supplement market access previously blocked by regulatory barriers.
Market Restraints
- Glucose feedstock volatility:Corn and sugar-derived carbohydrate prices fluctuate with agricultural commodity cycles, squeezing fermentation batch economics for non-integrated producers.
- Chinese supply concentration:Bulk pharmaceutical-grade output clusters in Shandong and Jiangsu provinces, creating geographic single-point vulnerability for global procurement networks.
- Citrulline substitution threat:L-citrulline offers superior oral bioavailability as a nitric oxide precursor, pressuring L-arginine positioning in sports nutrition formulations.
Strategic Opportunities
- Pediatric liquid delivery formats:Swallowing-difficulty populations in aged-care and pediatric segments remain underserved by powder-dominant supply, opening formulation differentiation.
- Kosher and halal certification premiums:Religious dietary compliance production lines command 15-25% price premiums in Middle Eastern and North American markets with underserved Muslim and Jewish consumer bases.
- EFSA novel food pathway:Synthetic biology-derived L-arginine strains await European safety assessments, creating first-mover positioning for fermentation innovators submitting toxicological packages.
Industry Challenges
- Pharmacopeial harmonization complexity:Divergent USP, EP, and ChP monograph specifications force redundant analytical method validation, extending qualification timelines for multi-regional suppliers.
- Downstream purification capex:Chromatographic separation and crystallization equipment for pharmaceutical-grade output demands substantial fixed investment, elevating break-even scale thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global L-Arginine Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powder, Liquid, Granules End User: Pharmaceuticals, Dietary Supplements, Sports Nutrition, Cosmetics Application: Cardiovascular Health, Muscle Recovery, Immune Support, Weight Management Distribution Channel: Online Retail, Pharmacies, Health Stores, Direct Sales |
| Companies Covered | Ajinomoto, Kyowa Hakko Bio, Evonik, Daesang, Jingjing Pharmaceutical, Jinghai Amino Acid, Jiahe Biotech, Shine Star, Longteng Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global L-Arginine Market Strategic Shifts
Continuous processing technologies and strain engineering advances are compressing batch cycle times while regulatory frameworks on both sides of the Atlantic tighten purity verification requirements.
Precision genome-edited Corynebacterium strains with enhanced arginine biosynthetic pathway flux are supplanting traditional mutagenesis-derived production organisms. Pharmaceutical-grade manufacturers in Japan and Germany are adopting these platforms to reduce fermentation duration from 72 to 48 hours. The technology is compressing unit production costs and enabling smaller-scale facilities to achieve pharmaceutical-grade certification.
China's NMPA has implemented revised GB standards for dietary supplement raw material purity, elevating heavy metal and microbial contamination testing protocols for imported L-arginine. The regulation is forcing non-Chinese suppliers to establish domestic analytical laboratories or partner with local testing houses. European and North American exporters are responding by pre-certifying shipments against dual USP-ChP specifications.
Direct-to-consumer supplement brands are consolidating procurement through vertically integrated contract manufacturers rather than trading houses. This disintermediation concentrates volume with facilities offering in-house formulation, encapsulation, and fulfillment. The shift is most visible in United States sports nutrition, where branded pre-workout companies now specify arginine particle size and flow characteristics directly with fermentation producers.
Global L-Arginine Market Segmentation
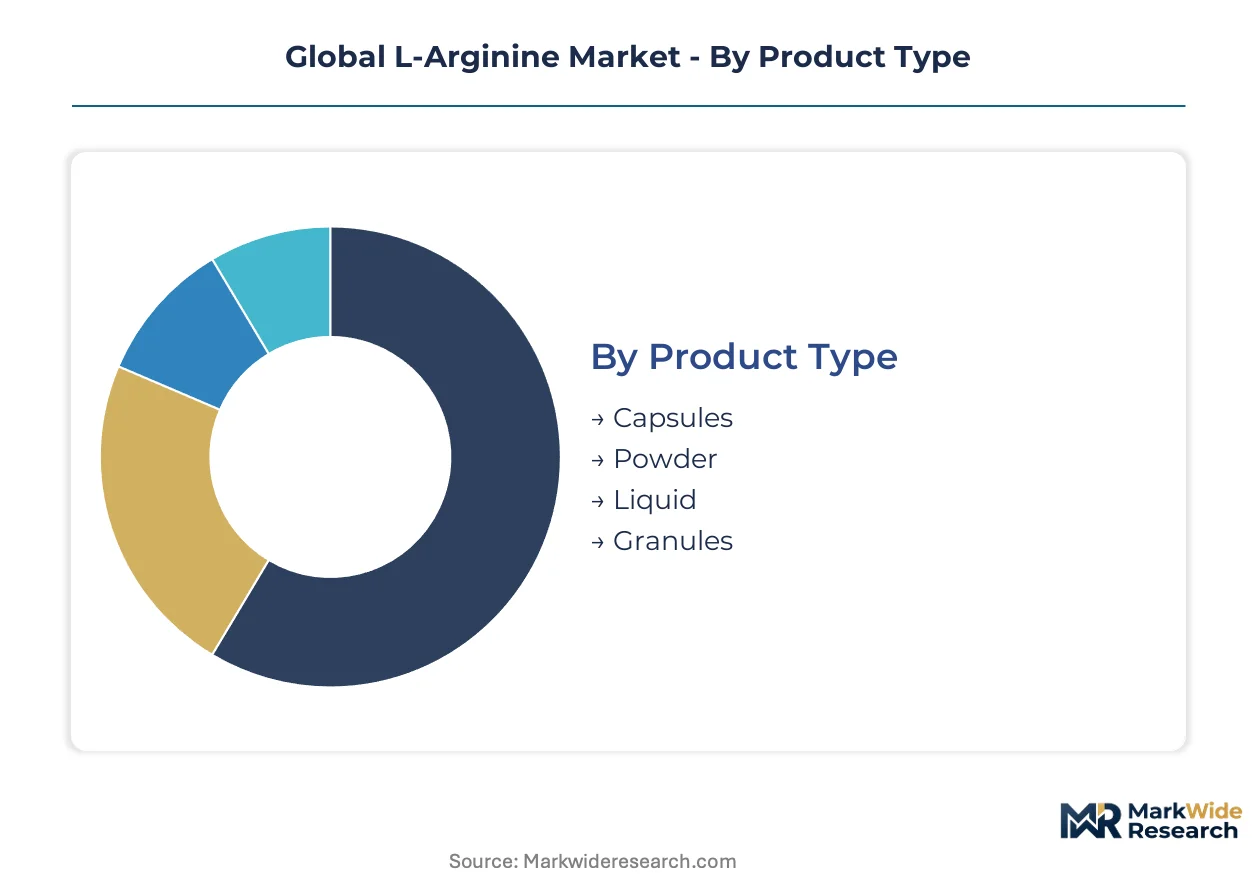
L-arginine market segmentation reveals divergent supply chain configurations across delivery formats and end-use verticals. Pharmaceutical-grade specifications command multi-compendial certification, while sports nutrition channels prioritize formulation flexibility and particle engineering.
Product Type:
Powder formulations dominate export-led procurement from Chinese fermentation clusters, whereas liquid and capsule formats concentrate in domestic North American and European contract manufacturing.
- Powder:Free-flowing crystalline material with standardized mesh distribution enables bulk pharmaceutical blending and direct-to-consumer scoop dosing. Demand concentrates in United States sports nutrition contract manufacturers seeking customizable particle size for instantized pre-workout matrices.
- Capsules:Hard-shell gelatin or HPMC encapsulation protects hygroscopic arginine from moisture degradation during shelf life. European pharmacies and North American health food retailers specify capsule formats for cardiovascular patient compliance programs.
- Liquid:Aqueous solutions with pH buffering and preservative systems serve pediatric and geriatric populations with swallowing difficulties. Japanese and German aged-care facilities specify liquid arginine for enteral nutrition protocols.
- Granules:Agglomerated particles with enhanced flow properties and reduced dust generation suit high-speed tablet compression lines. Indian pharmaceutical manufacturers import granules for effervescent formulation production.
Powder holds the largest share; momentum sits with liquid formats expanding in clinical nutrition applications.
End User:
Cost tier stratification separates pharmaceutical-grade USP certification from commodity sports nutrition supply, with dietary supplements occupying a contested middle ground requiring dual-quality documentation.
- Pharmaceuticals:Injectable and oral dosage forms demand endotoxin-controlled, multi-compendial certified material with validated stability data. Hospital procurement in the United States, Germany, and Japan restricts supplier pools to established fermentation houses with FDA, EMA, and PMDA facility inspections.
- Dietary Supplements:Capsule, tablet, and powder products require FDA cGMP compliance for US distribution and NMPA GB standard adherence for China import. Direct-to-consumer brands in California and New York specify arginine from vertically integrated contract manufacturers offering in-house analytical testing.
- Sports Nutrition:Pre-workout and recovery formulations prioritize nitric-oxide-boosting claims with flexible dosing protocols. Branded supplement companies in Florida and Texas source directly from Shandong fermentation facilities, bypassing traditional trading houses.
- Cosmetics:Topical applications leverage arginine's humectant and skin-conditioning properties in anti-aging serums and hair care. South Korean and French cosmetic formulators specify cosmetic-grade material with heavy metal certification below pharmaceutical thresholds.
Pharmaceuticals command premium pricing; sports nutrition is expanding most quickly through disintermediated procurement channels.
Application:
Volume concentration in cardiovascular protocols contrasts with emerging demand in metabolic health, where clinical evidence development lags commercial formulation activity.
- Cardiovascular Health:Nitric oxide pathway modulation supports endothelial function in hypertension and peripheral artery disease management. Mayo Clinic and Cleveland Clinic protocols specify USP-grade arginine for inpatient parenteral nutrition.
- Muscle Recovery:Post-exercise protein synthesis enhancement drives inclusion in branched-chain amino acid blends. CrossFit and bodybuilding communities in Texas and California purchase high-dose arginine through subscription direct-to-consumer channels.
- Immune Support:Lymphocyte proliferation and cytokine modulation applications remain investigational with limited clinical endpoint validation. Wellness brands in Germany and Switzerland market arginine for seasonal immune maintenance.
- Weight Management:Satiety signaling and growth hormone stimulation claims face EFSA and FTC scrutiny for substantiation. Meal replacement formulators in the United Kingdom and Netherlands trial arginine-glucomannan combinations.
Cardiovascular health anchors volume; muscle recovery is gaining share fastest in North American sports nutrition.
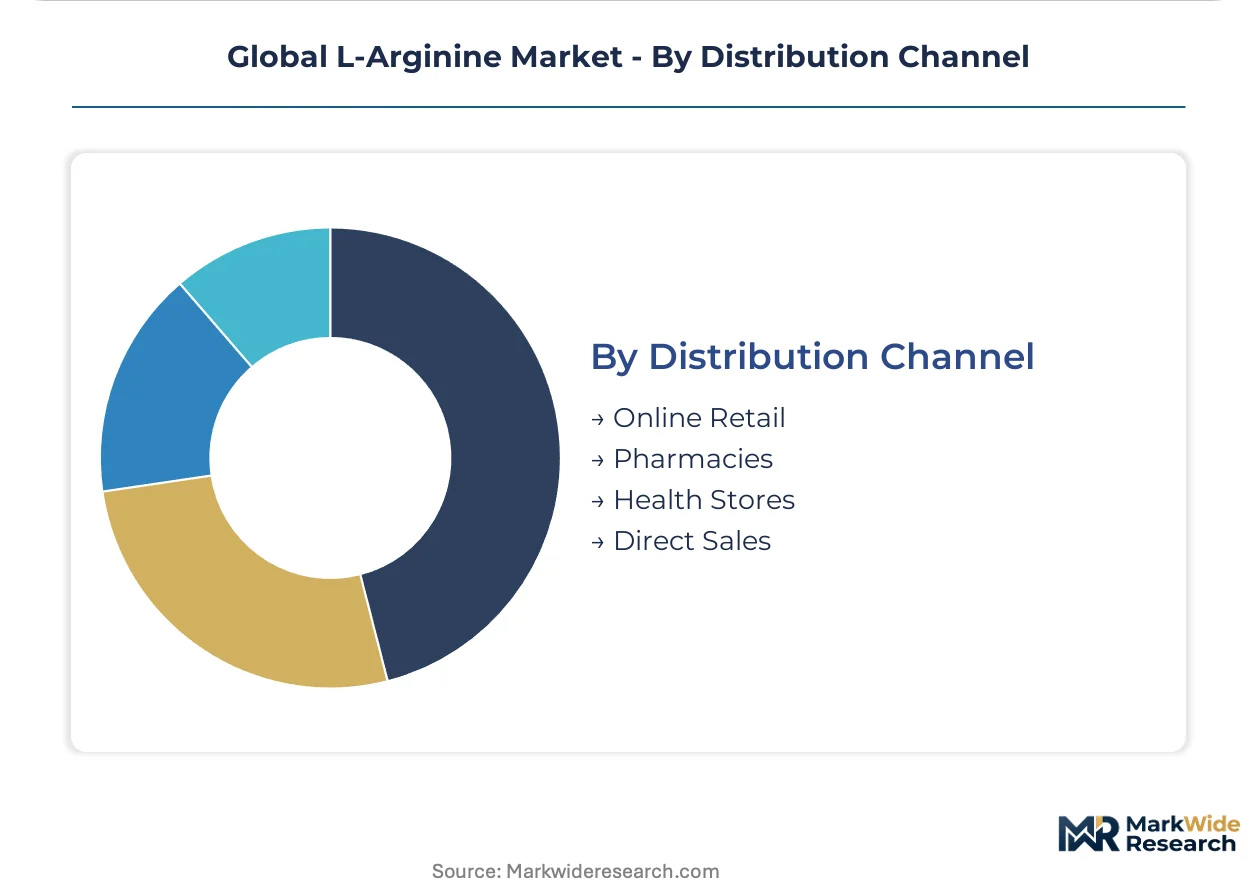
Distribution Channel:
Customer type fragmentation separates institutional procurement through pharmacies from consumer-direct acquisition, with channel strategy determining margin capture and brand control.
- Online Retail:Amazon, iHerb, and direct-brand storefronts enable subscription replenishment and review-driven discovery. California-based sports nutrition brands capture 40-60% gross margins through owned-channel sales versus wholesale distribution.
- Pharmacies:CVS, Walgreens, and independent drugstores stock cardiovascular and wound-healing arginine products behind-the-counter or in supplement aisles. Pharmacist recommendation drives trial in German and Japanese markets with established clinical acceptance.
- Health Stores:GNC, Vitamin Shoppe, and regional cooperatives emphasize staff education and sampling for pre-workout positioning. Texas and Florida retail footprints concentrate in metropolitan fitness corridors.
- Direct Sales:Multi-level marketing organizations and medical practitioner networks distribute clinical-grade material with personalized dosing guidance. Japanese and South Korean door-to-door channels maintain residual strength in aged-care segments.
Online retail holds the largest share; pharmacies show steepest expansion trajectory as clinical acceptance broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers absorb premium pricing for USP-grade certification without volume elasticity, while Chinese procurement networks extract cost efficiencies from concentrated Shandong fermentation capacity.
United States
Direct-to-consumer sports nutrition brands in Florida and Texas drive arginine volume through disintermediated procurement channels. FDA cGMP enforcement for dietary supplements elevates compliance documentation requirements for imported raw material. California-based contract manufacturers now specify particle size and flow characteristics directly with fermentation producers, bypassing traditional trading houses.
China
Shandong and Jiangsu provinces host the bulk of global pharmaceutical-grade fermentation output. NMPA revised GB standards for dietary supplement raw material purity, forcing foreign suppliers to establish domestic analytical laboratories or partner with local testing houses. Qingdao and Yantai fermentation clusters achieve comparable batch yields to Japanese counterparts at lower fixed-asset thresholds.
Germany
Evonik anchors European supply through microbial strain optimization that reduces downstream purification costs. REACH registration requirements constrain non-EU raw material entrants lacking toxicological dossiers. Frankfurt and Ludwigshafen chemical processing hubs concentrate pharmaceutical-grade formulation and multi-compendial certification capacity.
Japan
Kyowa Hakko Bio anchors domestic demand through kosher and halal-certified production lines. PMDA facility inspections restrict hospital and clinic procurement to established fermentation houses with validated stability data. Tokyo and Osaka metropolitan areas concentrate aged-care liquid arginine demand for enteral nutrition protocols.
South Korea
Cosmetic formulators in Seoul leverage arginine's humectant properties for anti-aging serums and hair care applications. MFDS regulates cosmetic-grade material with heavy metal certification thresholds below pharmaceutical requirements. Busan-Ulsan industrial corridors host contract manufacturing for topical delivery formats.
Global L-Arginine Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with fermentation-based manufacturers commanding premium positioning in pharmaceutical-grade supply chains while synthetic-route producers compete on commodity sports nutrition volume. The competitive terrain stratifies across three archetypes: multi-compendial certified fermentation houses, vertically integrated amino acid specialists, and regional trading intermediaries. Capacity expansion and backward integration into glucose feedstock sourcing represent the dominant competitive moves as margin compression intensifies.
Among Japanese fermentation houses, Ajinomoto and Kyowa Hakko Bio exemplify the premium-tier archetype through proprietary Corynebacterium platforms and religious certification production lines. Evonik occupies a position within the European microbial optimization tier. Chinese specialists including Jingjing Pharmaceutical, Jinghai Amino Acid, and Jiahe Biotech represent the scale-driven fermentation cluster achieving pharmaceutical-grade yields at reduced fixed-asset intensity.
| Leading Market Players |
|---|
| Ajinomoto |
| Kyowa Hakko Bio |
| Evonik |
| Daesang |
| Jingjing Pharmaceutical |
| Jinghai Amino Acid |
| Jiahe Biotech |
| Shine Star |
| Longteng Biotech |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Shandong fermentation clusters and United States sports nutrition brands lock in multi-year supply access while capping price volatility exposure for both parties. These arrangements concentrate procurement power with vertically integrated contract manufacturers who can commit to volume floors, leaving spot-market buyers exposed to glucose feedstock swings and NMPA compliance cost pass-throughs.
Pricing Analysis
After-sales certification documentation and technical service packages drive lifetime value for pharmaceutical-grade suppliers commanding sustained premiums over commodity tiers. Three-tier pricing structure across USP-certified pharmaceutical, dual-standard dietary supplement, and unbranded sports nutrition grades separates Ajinomoto and Kyowa Hakko Bio from Chinese fermentation houses. Cost compression in the sports nutrition tier is intensifying as Shandong producers achieve comparable batch yields at lower fixed-asset thresholds. Direct-to-consumer brands exhibit the highest price sensitivity, while hospital procurement committees prioritize validated stability data over unit cost.
Supply Chain Analysis
Strategic stockpiling of pharmaceutical-grade inventory dominates Japanese and German procurement patterns, whereas United States sports nutrition buyers favor just-in-time replenishment through vertically integrated contract manufacturers. Global output concentrates in China, Japan, and Germany, with Shandong and Jiangsu provinces anchoring bulk fermentation capacity. Corn and sugar-derived glucose feedstocks, Corynebacterium seed strains, and chromatographic purification resins constitute critical input dependencies. Single-source vulnerability from Chinese geographic clustering exposes procurement networks to NMPA regulatory disruption. Distribution runs through direct manufacturer-to-brand relationships that disintermediate traditional trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as sports nutrition formulation activity outpaces clinical evidence development, creating penetration headroom in condition-specific applications before therapeutic protocols mature.
For Market Incumbents: Secure multi-compendial certification pipelines against pharmacopeial harmonization complexity that threatens to obsolete single-standard suppliers. Deepen backward integration into glucose feedstock sourcing to buffer agricultural commodity volatility squeezing fermentation economics. Lock in long-term offtake agreements with direct-to-consumer brands before Chinese producers complete REACH registration and unlock European market access.
For New Entrants and Emerging Players: Differentiate on pediatric liquid delivery formats where swallowing-difficulty populations remain underserved by powder-dominant incumbents. Target kosher and halal certification premiums in Middle Eastern and North American markets with compliant production lines commanding sustained price premiums. Enter through EFSA novel food pathway submissions for precision genome-edited strains awaiting European safety assessments.
For Investors and Strategic Acquirers: Capital is best deployed toward fermentation houses with demonstrated pharmaceutical-grade yields and existing multi-compendial certifications that serve as durable competitive moats. Favor targets with captive strain engineering capabilities compressing batch cycle times from traditional mutagenesis-derived platforms. Watch L-citrulline substitution rates in sports nutrition formulations as the inflection signal for arginine demand elasticity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glucose Feedstock | Corn and sugar sourcing captive supply buffers agricultural commodity cycle exposure for fermentation economics. |
| Multi-Compendial Certification Investment | Dual USP-ChP validation extends supplier qualification timelines but secures hospital procurement preference. |
| Precision Strain Engineering Platform | Genome-edited Corynebacterium reduces fermentation duration and enables smaller-scale pharmaceutical-grade facilities. |
| Pediatric Liquid Format Development | pH-buffered aqueous solutions address swallowing-difficulty populations in aged-care and pediatric segments. |
| Religious Certification Production Lines | Kosher and halal compliance unlocks 15-25% price premiums in Middle Eastern and North American markets. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA cGMP enforcement records, NMPA GB standard revisions, and USP-EP-ChP pharmacopeial harmonization documents. Plant managers at Shandong fermentation facilities, procurement leads at United States sports nutrition contract manufacturers, regulatory affairs specialists navigating REACH registration, and hospital pharmacy directors specifying parenteral nutrition protocols contributed qualitative inputs. Bottom-up volume estimates from fermentation capacity utilization and top-down demand segmentation from end-use application analysis were cross-validated.
Segmentation dimensions modeled include product format tier, end-user quality grade, application indication, and distribution channel structure across the analysis window. CAGRs were derived from regression analysis against fermentation batch yield improvements, regulatory compliance cost trajectories, and substitution elasticity parameters. Strain engineering adoption curves and direct-to-consumer channel penetration rates served as industry-specific forecast inputs.
Material uncertainties — glucose feedstock price volatility, NMPA enforcement intensity, and L-citrulline formulation substitution — sit outside the modeled envelope. Forecasts reflect assumptions about pharmacopeial harmonization timelines and REACH registration completion rates. Revision becomes warranted when citrulline substitution in nitric-oxide-boosting blends crosses thresholds that trigger sports nutrition formulation reformulation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Asia-Pacific Amino Acids Market
Functional Chemicals
Furan Dicarboxylic Methyl Ester (FDME) Market
Functional Chemicals
Global Sodium Lignosulfonate Market
Functional Chemicals
Trimer Acid Market
Functional Chemicals
Paraben Market
Functional Chemicals
Lauric Acid Market
Functional Chemicals
Sodium Lauroyl Glutamate Market
Functional Chemicals
Paraformaldehyde Market
Functional Chemicals
Adipamide Market
Functional Chemicals
Urea Formaldehyde Market
Functional Chemicals
Lauric Arginate Market
Functional Chemicals
Fumaric Acid Market
Functional Chemicals
Europe Fumaric Acid Market
Functional Chemicals
L-Cysteine Market
Functional Chemicals
Isophthaloyl Chloride Market
Functional Chemicals
Acrylamide Monomer Market