
 L-Citrulline Market | 2026-2036
L-Citrulline Market Size, Share, and Industry Trends Forecast 2026-2036
L-Citrulline Market Outlook
Buyer concentration is shifting from niche bodybuilding channels toward mainstream fitness consumers and institutional sports programs. Kyowa Hakko Bio Co., Ltd. leverages its fermentation technology leadership to dominate pharmaceutical-grade supply chains. NOW Foods sustains broad retail penetration across health stores and e-commerce platforms. Glanbia plc anchors premium sports nutrition partnerships with global ingredient sourcing networks.
L-citrulline is a non-proteinogenic alpha-amino acid synthesized through ornithine transcarbamylase pathways or industrial fermentation, functioning primarily as a nitric oxide precursor to enhance vasodilation and ammonia detoxification. Powder formulations lead volume shipments due to cost-efficient bulk manufacturing and flexible dosing protocols, while capsules capture margin concentration through convenience positioning in direct-to-consumer channels. Sports nutrition applications drive fastest-growing demand as endurance athletes and CrossFit participants prioritize pump-enhancing and fatigue-delaying supplements.
The US FDA enforces Current Good Manufacturing Practice regulations for dietary supplements, compelling batch testing and adverse event reporting that elevates compliance costs for new entrants. Japan's MHLW and PMDA maintain strict health claim substantiation requirements, limiting functional marketing but reinforcing quality premiums for verified suppliers. Stakeholders must monitor evolving amino acid import tariffs and purity testing standards across destination markets to preserve supply chain continuity and pricing power.
Market Dynamics
Fermentation technology maturation and pharmaceutical-grade purity standards are compressing supply tiers while elevating compliance barriers for commodity-grade entrants.
Growth Catalysts
- DSHEA-compliant formulation expansion:The US FDA's dietary supplement framework enables structure-function claims for vasodilation benefits, accelerating pre-workout product pipelines.
- CrossFit and endurance athletics:Amateur and professional endurance communities prioritize ammonia-buffering supplementation for high-intensity training blocks.
- Ornithine transcarbamylase pathway optimization:Industrial biotechnology advances reduce unit production costs for pharmaceutical-grade material.
Market Restraints
- Arginine substitute availability:Lower-cost L-arginine formulations compete for nitric-oxide precursor positioning in budget supplement tiers.
- Fermentation input volatility:Corn-derived glucose and nitrogen source pricing fluctuates with agricultural commodity cycles.
- Japan MHLW health claim restrictions:Functional marketing limitations constrain premium pricing power in East Asian pharmaceutical channels.
Strategic Opportunities
- Clinical nutrition institutional contracts:Hospital and long-term care facilities seek urea cycle disorder management alternatives to synthetic interventions.
- Direct-to-consumer capsule formats:Convenience-positioned unit-dose products bypass traditional bulk powder distribution markups.
- EU EFSA novel food authorization pathways:Regulatory clarity for non-traditional delivery systems opens functional food integration.
Industry Challenges
- cGMP batch testing capacity:Third-party laboratory bottlenecks extend certification timelines for new manufacturing facilities.
- Pharmaceutical-grade specification drift:Maintaining USP and EP monograph compliance across multi-source raw material inputs demands continuous analytical investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | L-Citrulline Market |
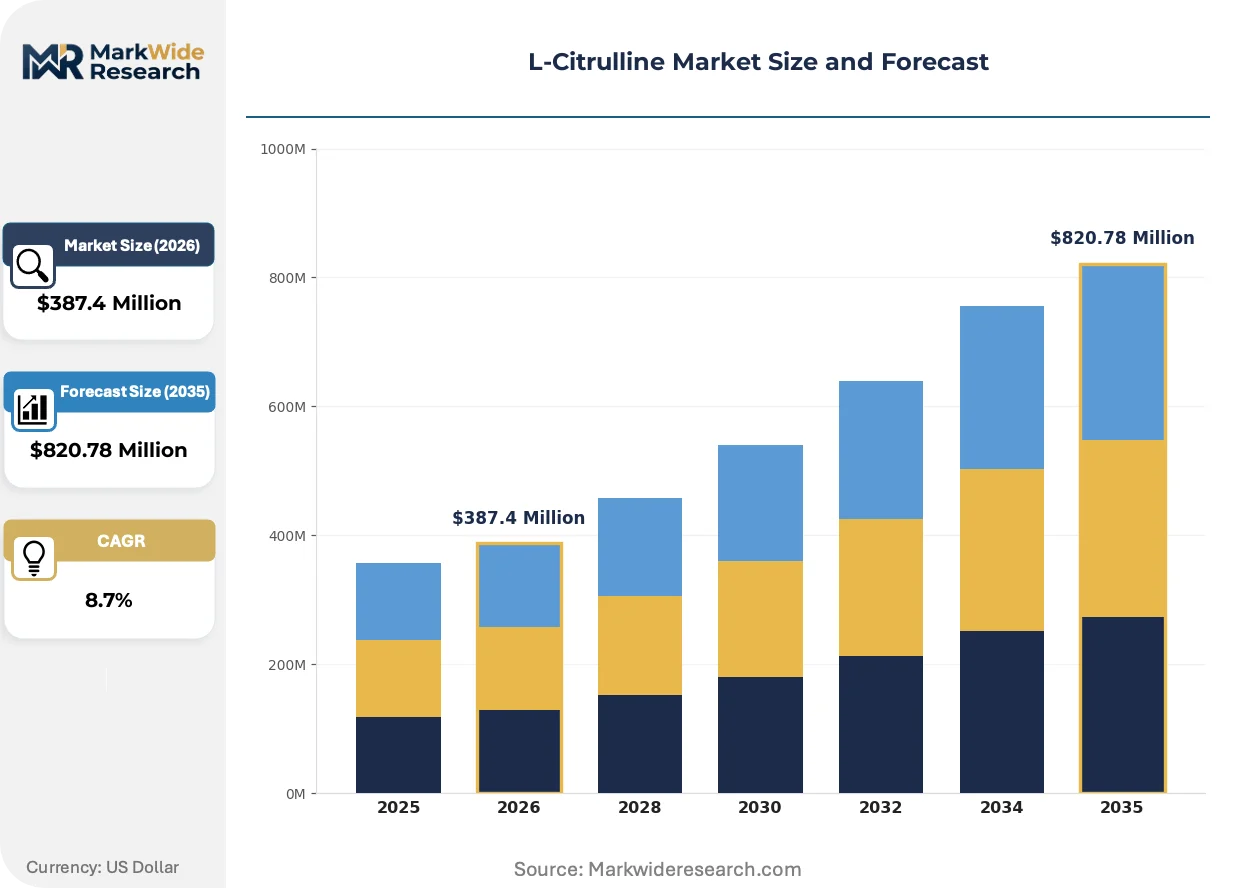
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $820.78 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsules, Tablets, Liquid End User: Athletes, Fitness Enthusiasts, Health Supplements, Medical Patients Distribution Channel: Online Retail, Health Stores, Pharmacies, Wholesale Application: Sports Nutrition, Dietary Supplements, Cardiovascular Health, Muscle Recovery |
| Companies Covered | NOW Foods, Kyowa Hakko Bio Co., Ltd., GNC Holdings, LLC, BulkSupplements, Primaforce, Pure Encapsulations, Jarrow Formulas, Glanbia plc, NutraBio Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
L-Citrulline Market Strategic Shifts
Sustained-release delivery technologies and clean-label positioning are reconfiguring formulation priorities while regulatory divergence between jurisdictions complicates unified product strategies.
Microencapsulation of L-citrulline with lipid matrices is unifying bioavailability enhancement with taste-masking functionality. Sports nutrition formulators adopt these systems for ready-to-drink applications where solubility and stability previously limited inclusion rates. The technology is compressing differentiation timelines between pharmaceutical and consumer-grade suppliers.
EU REACH registration requirements for amino acid imports are elevating documentation burdens for non-European manufacturers. The regulation forces batch-level traceability systems that smaller fermentation houses struggle to implement. Pharmaceutical-grade suppliers with pre-existing ISO 17025 laboratory infrastructure capture accelerated market access.
Subscription-based replenishment models are displacing traditional retail replenishment cycles in direct-to-consumer channels. Endurance athletes and CrossFit practitioners favor automated delivery schedules aligned with training periodization. This behavioral shift concentrates most visibly in North American metropolitan fitness corridors where digital-native brands dominate customer acquisition.
L-Citrulline Market Segmentation
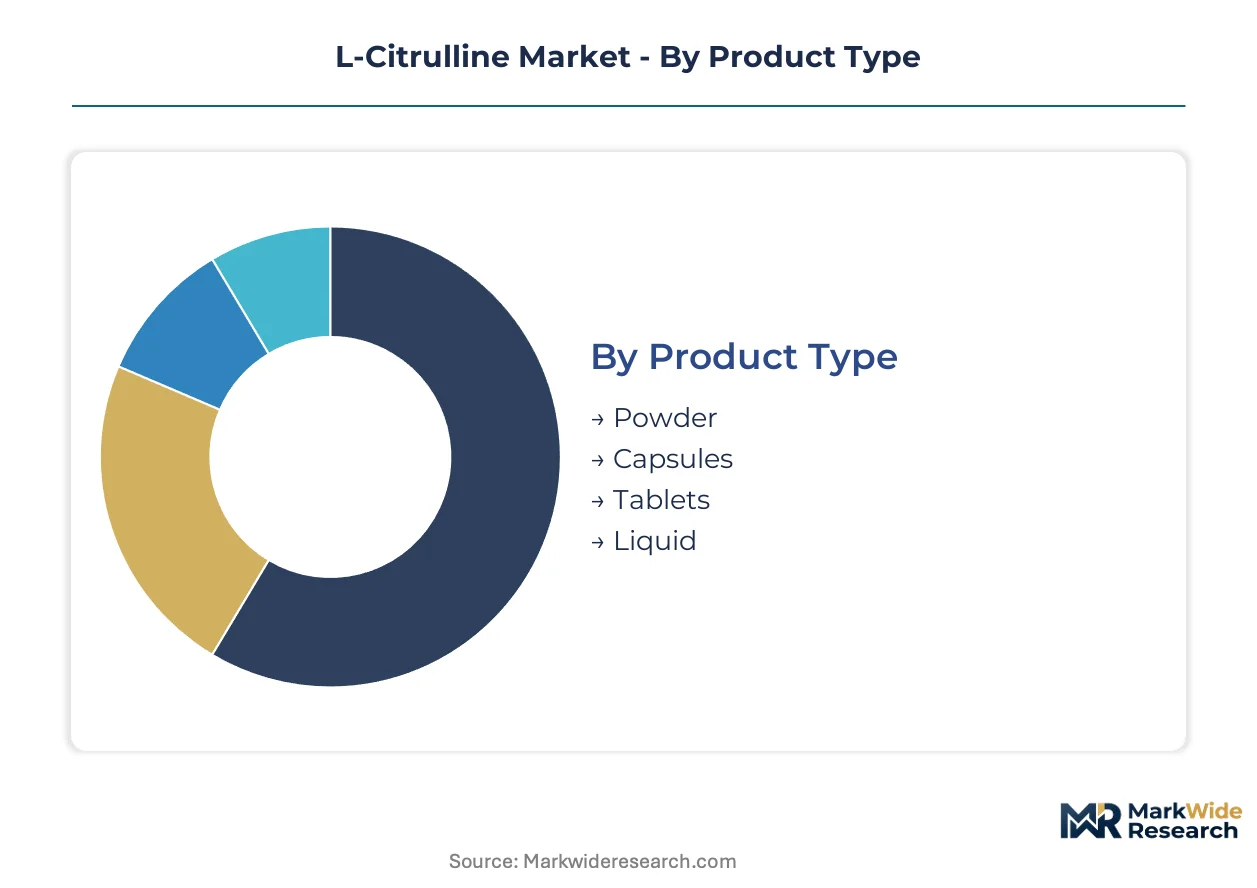
L-citrulline segmentation reveals distinct performance requirements across consumer tiers, with pharmaceutical-grade specifications diverging sharply from convenience-oriented formats. Understanding these divides enables targeted positioning against compliance costs and channel economics.
Product Type:
Cost tier separates bulk industrial buyers from premium direct-to-consumer purchasers, with purity certification levels driving margin stratification.
- Powder:Unformulated crystalline material with USP-grade purity specifications serves institutional sports programs and compounding pharmacies. Bulk procurement by CrossFit affiliates and endurance coaching networks prioritizes cost-per-gram efficiency over convenience. Fermentation-derived powder from Kyowa Hakko Bio dominates pharmaceutical supply chains.
- Capsules:Pre-measured gelatin or vegetable cellulose shells deliver unit-dose precision for traveling athletes and time-constrained professionals. Direct-to-consumer brands capture premium positioning through subscription replenishment models. NOW Foods anchors retail distribution across North American health store networks.
- Tablets:Compressed formulations with binding agents suit mass-market retail shelves where shelf stability and child safety packaging matter. Glanbia plc supplies excipient-compatible grades for co-manufacturing partnerships.
- Liquid:Ready-to-drink suspensions with flavor masking target fitness newcomers averse to powder mixing protocols. Microencapsulation advances are compressing taste-barrier limitations for this format.
Powder leads volumes today; capsules are gaining share fastest through digital-native brand expansion.
End User:
Application maturity distinguishes established clinical protocols from emerging recreational adoption patterns.
- Athletes:Professional and Olympic competitors utilize ammonia-buffering supplementation under sports dietitian supervision. USADA-permitted status drives institutional procurement through collegiate athletic departments. Pre-workout stacking with creatine monohydrate is standard practice.
- Fitness Enthusiasts:Amateur CrossFit participants and recreational endurance runners prioritize pump-enhancing effects for training motivation. Social media influencer recommendations accelerate trial rates in metropolitan fitness corridors.
- Health Supplements:General wellness consumers seek cardiovascular support claims within DSHEA structure-function boundaries. Aging demographics drive interest in endothelial function maintenance.
- Medical Patients:Urea cycle disorder management represents the sole FDA-recognized indication, requiring prescription-grade material and specialist oversight. Hospital pharmacy formularies stock L-citrulline as arginine precursor therapy.
Athletes anchor current demand; fitness enthusiasts are expanding most quickly through mainstream channel penetration.
Distribution Channel:
Customer acquisition economics favor automated replenishment over traditional retail markup structures.
- Online Retail:Amazon and direct-to-consumer platforms capture subscription-based endurance athlete segments. Digital-native brands leverage training periodization data for personalized dosing recommendations. cGMP certification badges reduce purchase friction.
- Health Stores:GNC and Vitamin Shoppe locations serve impulse purchasers seeking immediate product access. Staff consultation drives first-time buyer conversion for unfamiliar ingredients.
- Pharmacies:CVS and Walgreens chains stock limited SKUs targeting heart health positioning. Pharmacist counseling requirements elevate trust perceptions among skeptical consumers.
- Wholesale:Bulk supply to sports nutrition contract manufacturers and institutional food service operations. Minimum order quantities exclude smaller formulation houses.
Online retail commands volume leadership; health stores face share erosion from digital migration.
Application:
Regulatory claim boundaries separate permissible marketing language across consumer and clinical contexts.
- Sports Nutrition:Pre-workout and intra-workout formulations dominate finished product innovation. DSHEA-compliant vasodilation claims accelerate pipeline development without FDA pre-approval requirements.
- Dietary Supplements:Stand-alone amino acid products compete for shelf space with combination formulations. Clean-label positioning demands fermentation-derived rather than synthetic sourcing disclosure.
- Cardiovascular Health:Endothelial function support attracts aging consumer interest, though EFSA health claim restrictions limit European marketing specificity. Blood pressure maintenance framing requires careful jurisdictional adaptation.
- Muscle Recovery:Post-exercise ammonia clearance positioning targets high-volume training blocks. Delayed-onset muscle soreness reduction claims face varying substantiation standards.
Sports nutrition leads current consumption; cardiovascular health is climbing the fastest through demographic aging trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands higher per-capita sports nutrition expenditure than Germany, yet Japanese pharmaceutical-grade demand sustains tighter purity premiums across East Asian supply chains.
United States
CrossFit affiliate networks and endurance coaching programs drive institutional powder procurement. The FDA enforces Current Good Manufacturing Practice regulations that elevate batch testing costs for new entrants. Miami and Austin metropolitan fitness corridors concentrate digital-native brand headquarters and subscription fulfillment operations.
Germany
Aging demographics prioritize endothelial function supplements within cardiovascular health applications. EFSA novel food authorization pathways create regulatory clarity for functional food integration. The Rhine-Ruhr industrial cluster hosts fermentation technology suppliers serving pharmaceutical-grade specifications.
Japan
Hospital pharmacy formularies stock L-citrulline for urea cycle disorder management under specialist oversight. The MHLW and PMDA maintain strict health claim substantiation requirements that limit functional marketing specificity. The Kanto region around Tokyo anchors premium ingredient import and distribution infrastructure.
China
Domestic fermentation capacity expansion targets both pharmaceutical and sports nutrition export markets. The NMPA regulates amino acid purity standards for clinical nutrition applications. The Yangtze River Delta industrial corridor concentrates contract manufacturing facilities serving global supplement brands.
Australia
Endurance athletics communities prioritize ammonia-buffering supplementation for triathlon and ultramarathon training blocks. The TGA oversees therapeutic goods manufacturing standards that align with USP monograph requirements. Sydney and Melbourne metropolitan areas concentrate specialty health retail and direct-to-consumer distribution channels.
L-Citrulline Market Competitive Environment
Japanese producers anchor the pharmaceutical-grade tier; North American specialists hold dominant positions in direct-to-consumer capsule and powder formats. The vendor base splits between fermentation technology leaders and formulation-focused brands, creating a bifurcated structure where purity certification separates premium from commodity supply tiers. Strategic archetypes include fermentation-derived API suppliers, sports nutrition contract manufacturers, and clean-label direct-to-consumer marketers. Capacity expansion and subscription-based customer acquisition represent the dominant competitive moves across both tiers.
Within the fermentation-technology tier, Kyowa Hakko Bio Co., Ltd. exemplifies pharmaceutical-grade supply chain dominance through its Japanese industrial base. NOW Foods occupies a central position in North American retail and e-commerce distribution, representing the broad-access archetype. Glanbia plc anchors premium sports nutrition partnerships, exemplifying the global ingredient sourcing and co-manufacturing specialist model.
| Leading Market Players |
|---|
| NOW Foods |
| Kyowa Hakko Bio Co., Ltd. |
| GNC Holdings, LLC |
| BulkSupplements |
| Primaforce |
| Pure Encapsulations |
| Jarrow Formulas |
| Glanbia plc |
| NutraBio Labs |
| Others |
Value Chain & Pricing Dynamics
Institutional sports program procurement of USP-grade powder is forcing fermentation houses to upgrade analytical infrastructure, compressing margins for commodity-grade suppliers while concentrating pricing power with Japanese and North American pharmaceutical-certified producers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard-grade material. Three-tier pricing structure across pharmaceutical-certified, food-grade, and feed-grade levels separates Kyowa Hakko Bio's premium positioning from bulk commodity suppliers. Cost compression in the standard tier stems from domestic Chinese fermentation scale-up. Fitness enthusiasts purchasing direct-to-consumer capsules show lowest price sensitivity; institutional CrossFit affiliates buying bulk powder exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with Japanese pharmaceutical-grade fermentation capacity for urea cycle disorder therapeutic supply. Raw material sourcing draws from corn-derived glucose in the US Midwest and nitrogen substrates from German chemical processors. Tariff exposure on amino acid imports into the EU elevates landed costs for non-European manufacturers. Distribution runs through direct-to-consumer subscription platforms and health store retail networks in North American metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Japan's premium pharmaceutical-grade pricing and China's scaling fermentation cost base, with regulatory compliance differentials creating 40-60% landed cost spreads across destination markets.
For Market Incumbents: To counter Chinese capacity expansion in standard-grade supply, Kyowa Hakko Bio and NOW Foods should deepen backward integration into proprietary strain development and secure cGMP-certified co-manufacturing partnerships in North American fitness corridors. Certification investment in EU REACH registration and USP monograph compliance preserves margin separation from commodity entrants. For New Entrants and Emerging Players: Enter via clinical nutrition institutional contracts for urea cycle disorder management, where hospital pharmacy formulary inclusion creates sticky demand with limited incumbent penetration. Australia's endurance athletics community and Germany's aging cardiovascular wellness segments represent the most penetrable white-space targets. Go-to-market leverage should center on sports dietitian education programs and automated replenishment subscription mechanics. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier fermentation houses possessing ISO 17025 infrastructure but lacking branded distribution, as regulatory documentation burdens force consolidation toward vertically integrated players. Five-to-ten-year viability hinges on pharmaceutical-grade certification maintenance and direct-to-consumer channel control. Watch for FDA adverse event reporting thresholds tightening as the inflection signal for compliance-cost driven M&A acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Chinese domestic scale-up targets pharmaceutical export qualification under NMPA oversight. |
| Backward Integration into Strain Development | Kyowa Hakko Bio's proprietary ornithine transcarbamylase optimization reduces unit input costs. |
| Direct-to-Consumer Subscription Launch | Digital-native brands capture endurance athlete replenishment cycles in Austin and Miami corridors. |
| EU REACH Registration Completion | Batch-level traceability systems unlock functional food integration under EFSA novel food pathways. |
| Clinical Nutrition Institutional Partnership | Hospital pharmacy formulary inclusion creates urea cycle disorder management revenue stability. |
Study Parameters
Multiple input streams — fermentation technology suppliers, sports nutrition formulators, clinical nutrition procurement officers, and regulatory affairs specialists — were reconciled against customs trade data, FDA cGMP inspection records, and EFSA novel food submission databases. Primary interviews with plant managers at Japanese fermentation houses, category buyers at North American health store chains, and hospital pharmacy directors in Germany and Japan were cross-validated with secondary sources including USP monograph documentation and MHLW pharmaceutical-grade specifications. Bottom-up volume estimates from end-use application sizing and top-down value reconstructions from trade flow analysis were triangulated for convergence.
Historical volume trajectories were cross-referenced against expert panel inputs on regulatory timeline shifts and raw material cost movements across the projection horizon. Segmentation modeling captured product type differentiation by purity certification level, end-user distinction between clinical and recreational applications, distribution channel economics comparing subscription versus retail replenishment, and geographic regulatory cluster effects. CAGRs were derived from fitted growth curves adjusted for patent expiration impacts and import tariff regime changes. Forecast inputs incorporated CrossFit affiliate network expansion rates and endurance athletics participation trends.
Inputs from hospital pharmacy procurement databases and direct-to-consumer subscription platform disclosures were available through the study window; gaps in real-time fermentation capacity utilization data introduce uncertainty bands around Chinese supply expansion timing. Forecasts reflect documented assumptions regarding regulatory stability and raw material input cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Potassium Methylate Market
Functional Chemicals
Asia-Pacific Amino Acids Market
Functional Chemicals
Fumaric Acid Market
Functional Chemicals
Serine Market
Functional Chemicals
Sodium Malate Market
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
Functional Polymer Market
Functional Chemicals
Ortho Phthalic Aldehyde Market
Functional Chemicals
L-Alanyl-L-Glutamine Market
Functional Chemicals
Adipamide Market
Functional Chemicals
Glutamine Market
Functional Chemicals
Acrylamide Monomer Market
Functional Chemicals
Global Functional Fluids Market
Functional Chemicals
Furan Dicarboxylic Methyl Ester (FDME) Market
Functional Chemicals
Global Methylal Market
Functional Chemicals
Carbomer Market