
 L-Alanyl-L-Glutamine Market | 2026-2036
L-Alanyl-L-Glutamine Market Size, Share, and Industry Trends Forecast 2026-2036
L-Alanyl-L-Glutamine Market Analytics
The EU Green Deal is restructuring procurement criteria for clinical nutrition across European hospital networks. Ajinomoto leverages its amino acid fermentation heritage to sustain supply security for pharmaceutical-grade dipeptides. Kyowa Hakko Bio anchors Japanese production capacity while competing in European sports nutrition channels. Evonik dominates specialty excipient integration, extending its reach into parenteral formulation partnerships.
L-Alanyl-L-glutamine is a dipeptide composed of L-alanine and L-glutamine joined by a peptide bond, manufactured through enzymatic synthesis or chemical condensation, with a molecular weight of 217.22 g/mol and high water solubility that enables stable intravenous solutions. Powder formulations lead hospital procurement due to compounding flexibility and extended shelf life, while liquid formats occupy growing home-infusion segments where pre-mixed convenience reduces clinical preparation time. Medical nutrition applications concentrate margin pools around parenteral formulations for ICU and oncology patients, whereas sports nutrition channels differentiate through third-party certification and dosage precision.
FDA oversight of parenteral drug products shapes manufacturing standards and facility inspection protocols for U.S. market access, while EMA's Good Manufacturing Practice guidelines and REACH chemical registration requirements govern European production and import compliance. Japan's PMDA maintains distinct pharmacopeial standards for dipeptide injectables that influence formulation development priorities for METI-registered manufacturers. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP monographs to anticipate qualification burdens and sourcing flexibility.
Market Dynamics
The EU Green Deal is restructuring procurement criteria for clinical nutrition across European hospital networks, forcing manufacturers to requalify supply chains around carbon-accounted dipeptide production and renewable energy inputs.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of fluorinated greenhouse gases is accelerating investment in enzymatic synthesis methods that eliminate solvent-intensive purification steps for pharmaceutical-grade dipeptides.
- Home-infusion segments:Oncology and post-surgical patients are transitioning from inpatient to ambulatory parenteral nutrition, expanding demand for pre-mixed liquid formulations with extended stability profiles.
- Enzymatic synthesis:Fermentation-derived peptide bond formation is displacing chemical condensation in Japanese and European manufacturing, reducing impurity burdens and simplifying pharmacopeial qualification.
Market Restraints
- Pharmaceutical-grade L-glutamine supply:Fermentation capacity constraints in amino acid production create input cost volatility that compresses margins for dipeptide manufacturers without backward integration into amino acid supply.
- German manufacturing concentration:Integrated production networks around Frankfurt and Darmstadt create geographic supply risk for hospital procurement managers dependent on single-source parenteral formulations.
- Substitution by free amino acids:Unformulated L-glutamine remains clinically accepted in oral nutrition protocols, limiting dipeptide penetration in cost-sensitive institutional purchasing.
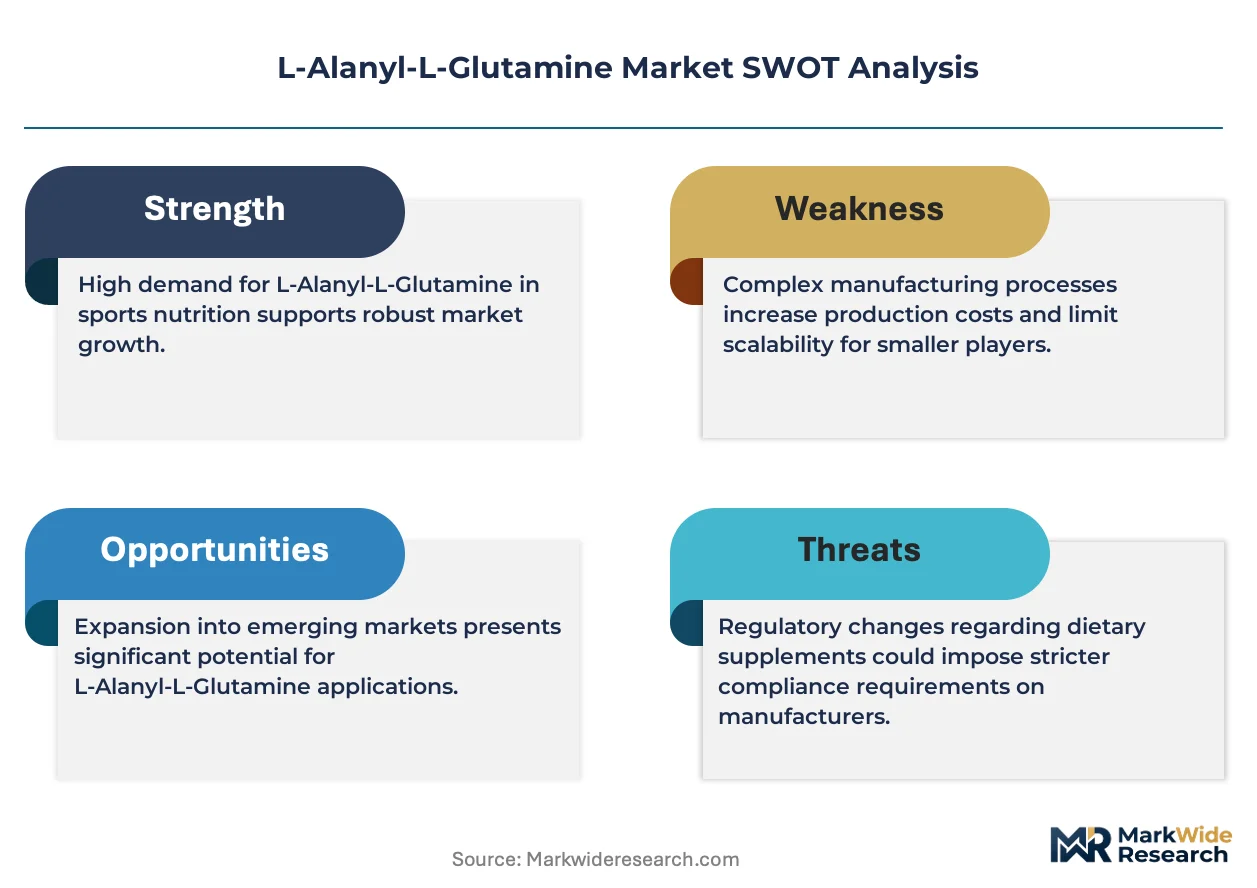
Strategic Opportunities
- Indian hospital networks:Tertiary care expansion under the PLI scheme for pharmaceuticals is creating first-mover openings for dipeptide parenteral registration with CDSCO.
- Sports nutrition certification:Informed Sport and NSF Certified for Sport programs are enabling premium positioning for dipeptide supplements in North American collegiate and professional athletic channels.
- Continuous manufacturing:Integration of real-time release testing with peptide synthesis is collapsing batch release timelines and enabling just-in-time compounding for hospital pharmacy operations.
Industry Challenges
- Pharmacopeial harmonization:Divergent USP, EP, and JP monograph specifications for dipeptide purity and endotoxin limits force manufacturers to maintain parallel analytical methods and reference standards.
- Specialized fermentation expertise:Scarcity of process engineers with combined amino acid fermentation and peptide chemistry experience constrains capacity expansion timelines for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | L-Alanyl-L-Glutamine Market |
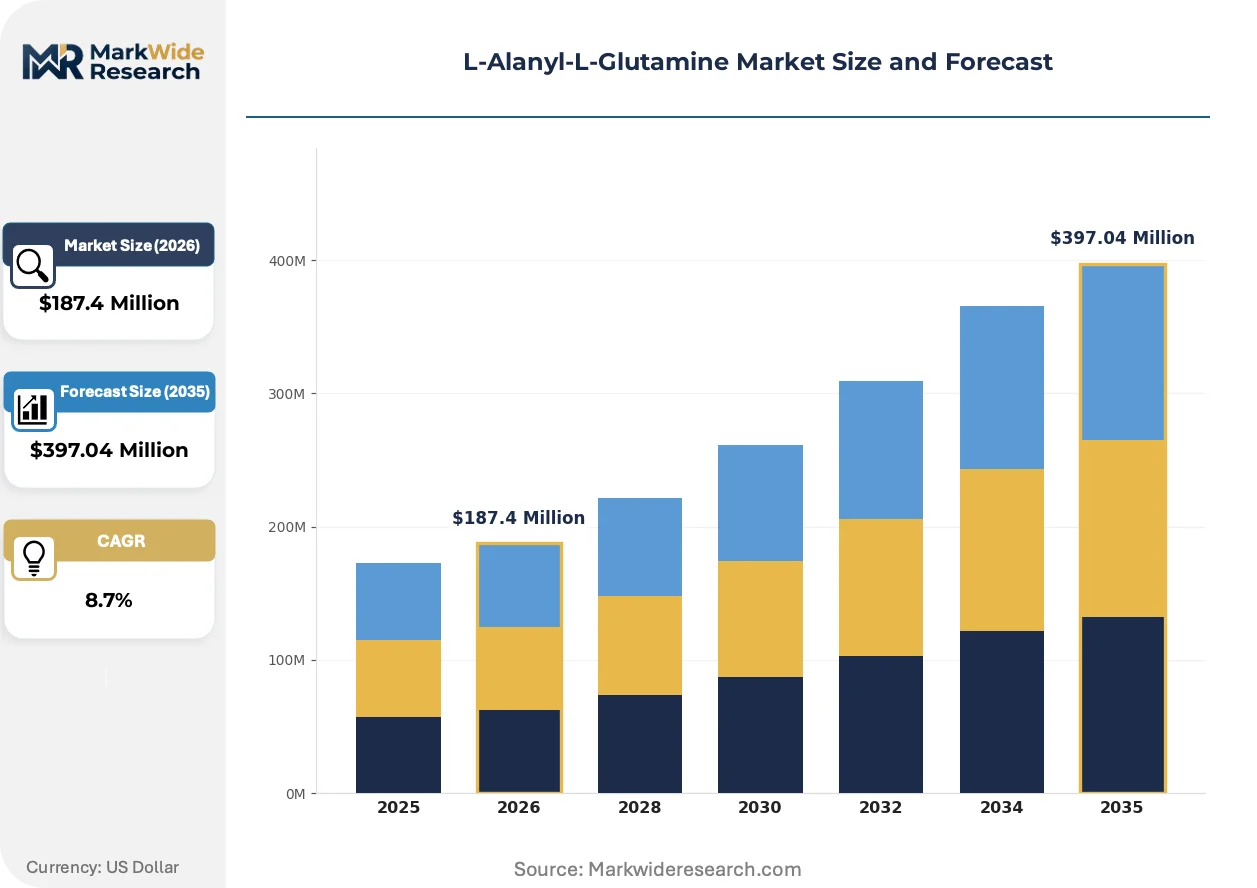
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Liquid, Granule Application: Nutritional Supplements, Sports Nutrition, Medical Nutrition, Pharmaceutical End User: Athletes, Bodybuilders, Patients, Health-Conscious Consumers Distribution Channel: Online Retail, Drug Stores, Supermarkets, Specialty Stores |
| Companies Covered | Ajinomoto, Kyowa Hakko Bio, Evonik, Jinan Chenghui-Shuangda Chemical, Wuhan Microsen Technology, Jiangsu Chengxin Pharmaceutical, Xi’an Lyphar Biotech, Fresenius Kabi, Nanjing Shineking Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
L-Alanyl-L-Glutamine Market Evolving Landscape
Enzymatic synthesis platforms are absorbing capital and technical talent from traditional chemical condensation, reshaping competitive positioning around biological rather than synthetic process expertise.
Continuous flow enzymatic reactors are absorbing fixed investment from batch peptide synthesis facilities. ICU pharmacy directors in German and Japanese tertiary hospitals are specifying these platforms for in-house compounding of patient-specific parenteral bags. The technology is absorbing regulatory scrutiny around process analytical technology validation, compressing approval timelines for manufacturers demonstrating real-time quality assurance.
The EU Medical Device Regulation is reclassifying certain parenteral nutrition delivery systems as Class III devices, extending quality management system requirements to dipeptide formulation partners. Manufacturers supplying hospital networks must now maintain dual compliance with GMP and ISO 13485 standards. German clinical nutrition departments are responding by consolidating supplier panels to partners with pre-validated device-drug combination capabilities.
Hospital procurement managers are consolidating annual contracts around single-source dipeptide suppliers with integrated device compatibility testing. Group purchasing organizations in France and Italy are displacing fragmented multi-vendor purchasing with framework agreements bundling powder formulations, pre-mixed liquids, and infusion pump compatibility validation. The shift is most visible in oncology nutrition protocols where treatment continuity requirements favor supply security over price competition.
L-Alanyl-L-Glutamine Market Segmentation
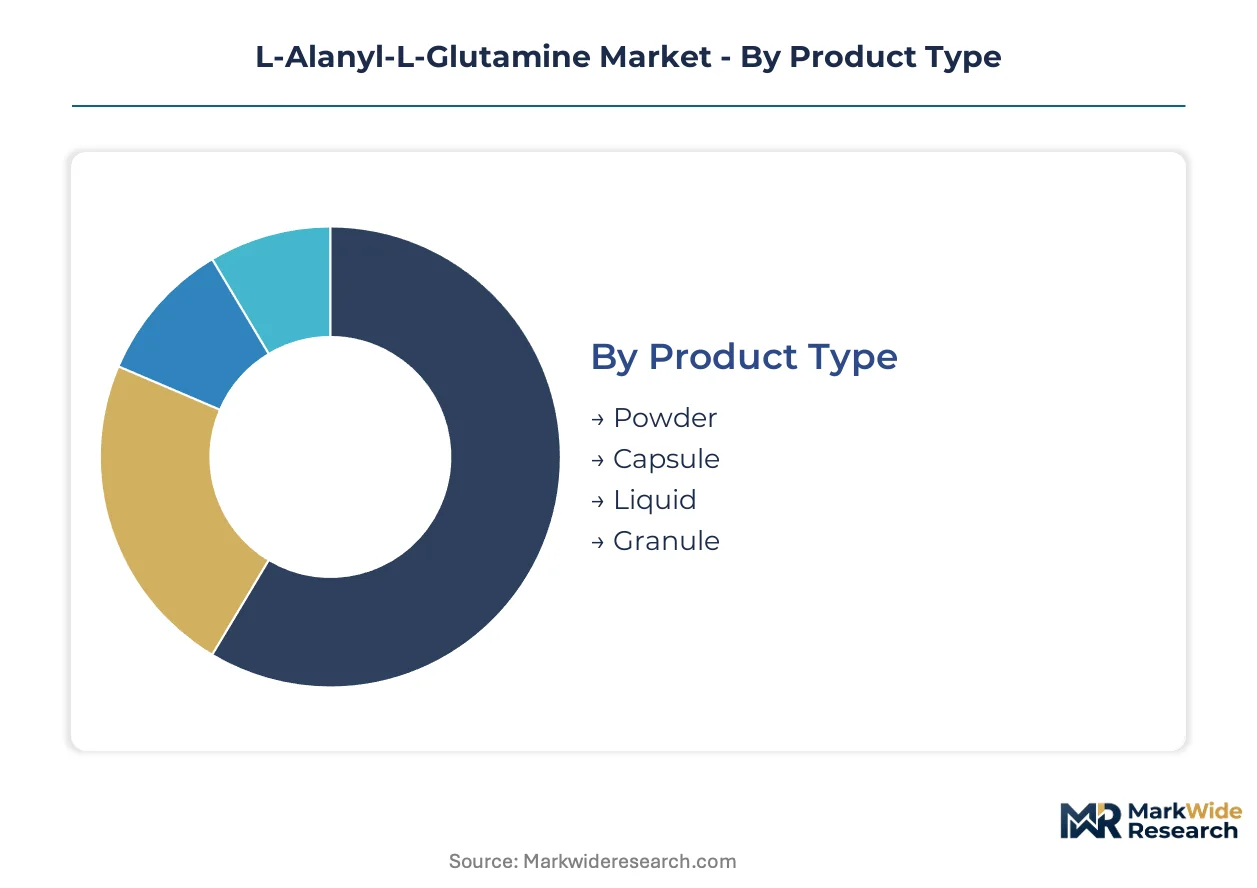
L-Alanyl-L-glutamine's dual identity as a clinical therapeutic and performance supplement creates distinct manufacturing and distribution requirements across segment boundaries. Capital allocation decisions hinge on whether producers target hospital pharmacy compounding or direct-to-consumer channels.
Product Type:
Capital intensity peaks with liquid formulation infrastructure, where aseptic filling lines and stability testing laboratories demand the heaviest upfront investment.
- Powder:Lyophilized or crystalline dipeptide with extended shelf stability enables hospital pharmacy compounding flexibility. German tertiary hospitals concentrate procurement around bulk powder for patient-specific parenteral bag preparation, driven by ICU nutrition protocol standardization.
- Liquid:Pre-mixed sterile solutions require blow-fill-seal equipment and accelerated stability chambers. Home-infusion demand in Japan and North America is climbing fastest as oncology patients transition to ambulatory care settings.
- Capsule:Encapsulation lines with powder dosing precision serve sports nutrition and oral medical nutrition segments. FSSAI-registered Indian manufacturers are expanding hard-shell capacity for export markets.
- Granule:Sachet-format instantized powder offers convenience for outpatient oral supplementation. European pharmacy chains favor this format for patient compliance programs.
Powder absorbs the bulk of installed capacity; liquid is expanding most quickly.
Application:
Margin structure varies sharply across the therapeutic-nutritional boundary, with pharmaceutical applications commanding premium pricing tied to pharmacopeial compliance burdens.
- Medical Nutrition:Parenteral dipeptide formulations for ICU, oncology, and post-surgical patients require endotoxin-controlled manufacturing and batch release testing. Japanese PMDA pharmacopeial standards and EMA GMP inspections govern supply to hospital networks in Tokyo and Osaka clusters.
- Sports Nutrition:Powder and capsule formats for muscle recovery and endurance support differentiate through third-party certification. North American collegiate athletic programs and professional team nutritionists are specifying Informed Sport-tested products.
- Nutritional Supplements:General wellness positioning targets health-conscious consumers through retail and e-commerce. FSSAI registration requirements shape Indian market entry strategies for oral dipeptide products.
- Pharmaceutical:Active pharmaceutical ingredient supply for drug manufacturers and compounding pharmacies demands USP, EP, and JP monograph compliance. REACH registration governs European import and production.
Medical Nutrition commands the highest per-kilogram pricing; Sports Nutrition shows the steepest expansion trajectory.
End User:
Customer acquisition economics diverge between institutional procurement committees and individual purchase behavior.
- Patients:Hospital discharge and home-infusion prescriptions drive recurring demand for parenteral formulations. German statutory health insurance reimbursement codes influence prescribing patterns for dipeptide-containing nutrition.
- Athletes:Collegiate, professional, and amateur competitors seeking recovery optimization generate volume in certified sports nutrition channels. NSF Certified for Sport and Informed Sport programs filter supplier eligibility.
- Bodybuilders:Strength-training enthusiasts prioritize dosage precision and amino acid ratio transparency. Specialty retail and direct-to-consumer e-commerce capture this segment.
- Health-Conscious Consumers:Preventive wellness positioning attracts buyers through pharmacy and supermarket channels. Japanese functional food regulations shape product claims and labeling.
Patients generate the most predictable recurring revenue; Athletes are gaining share fastest.
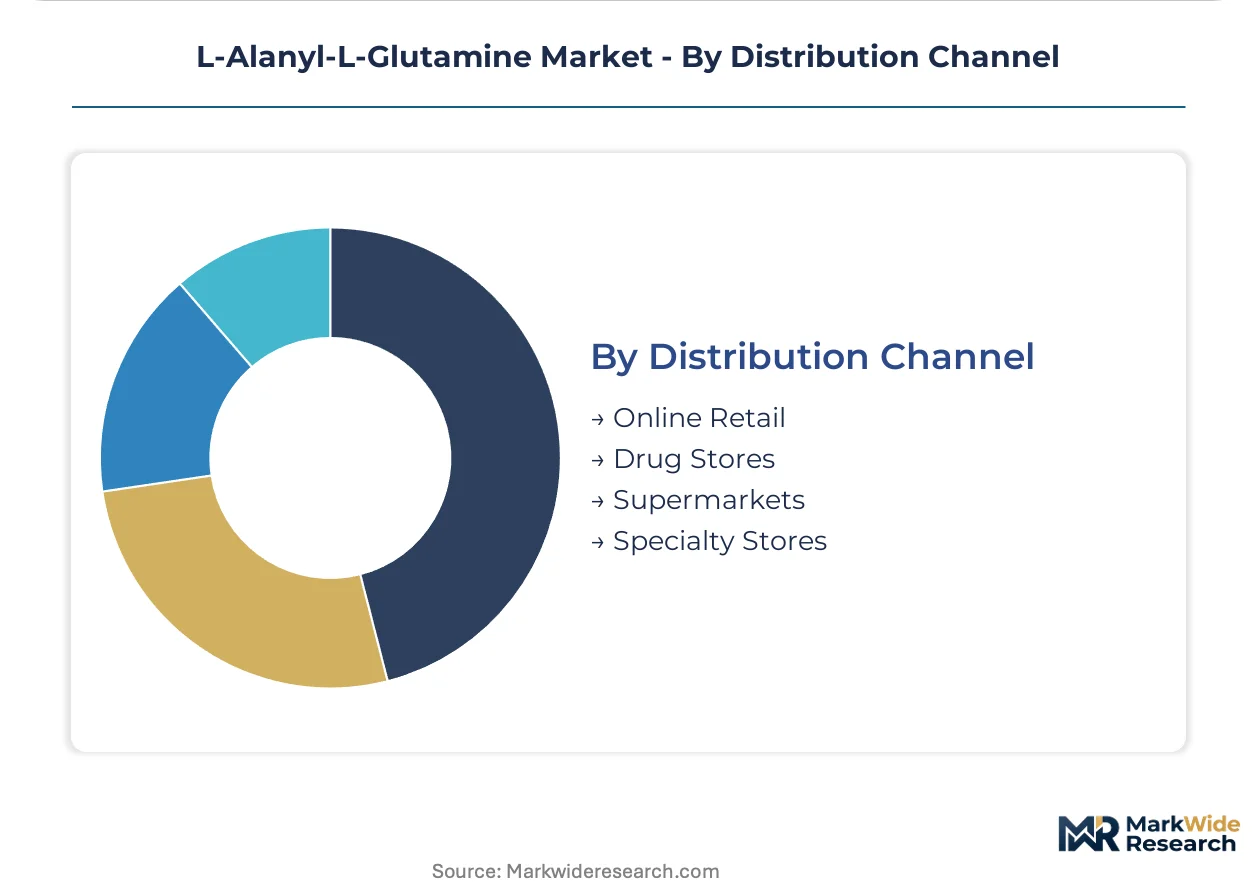
Distribution Channel:
Channel selection determines regulatory exposure and working capital requirements, with hospital supply chains imposing the longest payment cycles.
- Online Retail:Direct-to-consumer and marketplace platforms enable sports nutrition and supplement brands to bypass wholesale markups. Amazon and specialized fitness e-commerce dominate North American and European volume.
- Drug Stores:Pharmacy chains and hospital outpatient dispensaries handle prescription medical nutrition and OTC supplements. Japanese drugstore consolidation is reshaping supplier negotiations.
- Supermarkets:Mass retail placement for consumer wellness products requires slotting fees and promotional investment. European supermarket private-label programs are testing dipeptide inclusion.
- Specialty Stores:Fitness centers, sports nutrition boutiques, and clinical nutrition consultants provide education-intensive purchase environments. German specialty retail maintains strength in personalized medical nutrition counseling.
Online Retail captures the highest volume growth; Drug Stores retain the most pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt and Darmstadt anchor European production networks for pharmaceutical-grade dipeptide manufacturing, with integrated fermentation and formulation facilities supplying hospital networks across the continent.
Germany
ICU nutrition protocol standardization drives hospital procurement of bulk powder formulations for patient-specific compounding. The EU F-Gas Regulation accelerates enzymatic synthesis investment to eliminate solvent-intensive purification. Fresenius Kabi maintains integrated manufacturing and distribution networks across the Frankfurt-Rhine-Main cluster.
Japan
Home-infusion demand climbs as oncology patients transition to ambulatory parenteral nutrition settings. METI-registered manufacturers navigate PMDA pharmacopeial standards for dipeptide injectables that shape formulation priorities. Tokyo and Osaka hospital clusters concentrate procurement for endotoxin-controlled medical nutrition supply.
United States
FDA oversight of parenteral drug products shapes manufacturing standards and facility inspection protocols for market access. Home-infusion segments expand pre-mixed liquid demand with extended stability profiles. Greater Boston and San Diego biopharma corridors host formulation development partnerships.
India
Tertiary care expansion under the PLI scheme for pharmaceuticals creates registration openings for CDSCO-compliant dipeptide parenterals. FSSAI registration requirements shape oral product market entry strategies. Maharashtra and Gujarat pharmaceutical manufacturing zones attract fermentation capacity investment.
China
Jinan and Wuhan chemical manufacturing bases supply crystalline dipeptide for export markets and domestic clinical nutrition. NMPA oversight of injectable drug products governs facility qualification and batch release protocols. Yangtze River Delta clusters concentrate enzymatic synthesis technology adoption.
L-Alanyl-L-Glutamine Market Competitive Landscape
The competitive structure tilts toward integrated fermentation specialists with backward amino acid supply control. Market concentration reflects high barriers in pharmaceutical-grade manufacturing, where pharmacopeial compliance and endotoxin testing capabilities filter participation. Two archetypes dominate: diversified chemical conglomerates with peptide chemistry divisions, and pure-play amino acid specialists leveraging fermentation heritage. Capacity expansion and strategic partnerships represent the dominant competitive moves, as manufacturers secure hospital network contracts through integrated device compatibility validation.
Among Japanese fermentation specialists, Ajinomoto and Kyowa Hakko Bio exemplify archetypes rooted in amino acid heritage, with the former representing supply security positioning and the latter anchoring production capacity for both domestic and European sports nutrition channels. Evonik occupies a position exemplifying specialty excipient integration, extending reach into parenteral formulation partnerships. Within Chinese chemical manufacturing, Jinan Chenghui-Shuangda Chemical and Wuhan Microsen Technology represent regional production base archetypes supplying crystalline dipeptide for export and domestic clinical nutrition markets.
| Leading Market Players |
|---|
| Ajinomoto |
| Kyowa Hakko Bio |
| Evonik |
| Jinan Chenghui-Shuangda Chemical |
| Wuhan Microsen Technology |
| Jiangsu Chengxin Pharmaceutical |
| Xi'an Lyphar Biotech |
| Fresenius Kabi |
| Nanjing Shineking Biotech |
| Others |
Value Network & Pricing Analysis
Process engineers with combined amino acid fermentation and peptide chemistry expertise concentrate in the Frankfurt-Rhine-Main and Tokyo-Osaka corridors, creating labor-cost differentials that widen pricing spreads between pharmaceutical-grade and sports nutrition tiers.
Pricing Analysis
Yield-based pricing anchors pharmaceutical-grade dipeptide contracts, with manufacturers capturing premiums tied to endotoxin compliance and batch consistency in ICU applications. Three-tier pricing structure across premium, standard, and economy levels separates USP/EP/JP-certified injectables from Informed Sport-certified sports nutrition and unbranded oral supplements. Cost compression in standard-tier powder formulations is intensifying because fermentation capacity constraints in L-glutamine supply create input volatility. Hospital procurement committees exhibit lowest price sensitivity due to reimbursement code coverage, while health-conscious consumers in retail channels drive hardest bargain.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Tokyo, and Boston anchor hub-and-spoke patterns for temperature-controlled parenteral formulations. Manufacturing concentrates in Germany, Japan, and China, with enzymatic synthesis capacity expanding fastest in the Yangtze River Delta. Raw material flows draw from pharmaceutical-grade L-glutamine fermentation in Japan, L-alanine supply from Chinese amino acid producers, and specialty excipient production in Germany. Single-source vulnerability around Fresenius Kabi's integrated Frankfurt-Darmstadt network creates concentration risk for European hospital networks. Distribution runs through direct hospital contracts for medical nutrition and specialized fitness e-commerce for sports nutrition channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation's Class III reclassification of parenteral nutrition delivery systems erects a compliance moat that rewards manufacturers with pre-validated device-drug combination capabilities and dual GMP-ISO 13485 certification.
For Market Incumbents: Lock in hospital network contracts through integrated device compatibility validation and real-time release testing partnerships with ICU pharmacy directors. Fresenius Kabi and Evonik should extend backward integration into amino acid fermentation to buffer L-glutamine supply volatility. Consolidate supplier panels before group purchasing organizations in France and Italy complete their framework agreement centralization. For New Entrants and Emerging Players: Specialty stores in German clinical nutrition counseling channels represent the most penetrable entry point for certified sports nutrition positioning. Indian tertiary care expansion under the PLI scheme offers CDSCO registration white space for parenteral formulations. Target home-infusion segments with pre-mixed liquid stability profiles as oncology patients transition to ambulatory settings. For Investors and Strategic Acquirers: Re-rating potential sits with enzymatic synthesis specialists given the EU F-Gas Regulation's phase-down of fluorinated greenhouse gases accelerating biological process adoption. Long-term viability over a multi-year horizon favors manufacturers with captive amino acid supply and pharmacopeial harmonization capabilities. Watch for PMDA-EMA monograph convergence as an inflection signal for qualification burden relief.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Synthesis Scale-Up | Eliminates solvent-intensive purification steps under EU F-Gas Regulation compliance deadlines. |
| Backward Integration into Amino Acid Fermentation | Captive L-glutamine supply buffers margin compression from fermentation capacity constraints. |
| Device-Drug Combination Validation | Dual GMP-ISO 13485 certification secures hospital procurement consolidation under EU MDR. |
| Home-Infusion Liquid Formulation Development | Extended stability profiles capture ambulatory parenteral nutrition demand from oncology transitions. |
| Third-Party Sports Certification Investment | Informed Sport and NSF Certified for Sport programs unlock North American collegiate athletic channels. |
Research Methodology
Document review covered FDA parenteral drug product filings, EMA GMP inspection reports, PMDA pharmacopeial submissions, and METI manufacturing registrations, complemented by interviews with ICU pharmacy directors, hospital procurement managers, clinical nutrition consultants, and fermentation process engineers. Secondary validation drew from customs trade data for dipeptide imports, CDSCO registration databases, FSSAI product approvals, and SEC filings of listed amino acid manufacturers. Bottom-up volume estimates from hospital network purchasing data were cross-referenced against top-down market sizing from pharmaceutical-grade production capacity disclosures.
Historical shipment patterns from Japanese and German manufacturers were cross-referenced against panel input from group purchasing organization contract managers. The analytical framework modeled segmentation across product type, application, end user, and distribution channel throughout the forecast period. CAGRs were derived from trend extrapolation of enzymatic synthesis adoption curves and home-infusion segment penetration rates. Forecast inputs included ICU nutrition protocol standardization timelines and PLI scheme pharmaceutical capacity buildout schedules in India.
Caveats apply where pharmacopeial harmonization delays, fermentation input cost spikes, or EU Green Deal procurement restructuring could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Lauric Acid Market
Functional Chemicals
Transfluthrin Market
Functional Chemicals
Para-Aminophenol Market
Functional Chemicals
Urea Formaldehyde Market
Functional Chemicals
Ortho Phthalic Aldehyde Market
Functional Chemicals
Global Tert-Amylbenzene Market
Functional Chemicals
Imidazole Market
Functional Chemicals
Europe Formic Acid Market
Functional Chemicals
L-Citrulline Market
Functional Chemicals
Global Potassium Citrate Market
Functional Chemicals
Global Adiponitrile Market
Functional Chemicals
Adipamide Market
Functional Chemicals
Citrate Market
Functional Chemicals
Sodium Lauroyl Glutamate Market
Functional Chemicals
Propylparaben Market
Functional Chemicals
Trimer Acid Market